
 Air Humidifier and Dehumidifier Market | 2026-2036
Air Humidifier and Dehumidifier Market Size, Share, and Industry Trends Forecast 2026-2036
Air Humidifier and Dehumidifier Market Outlook
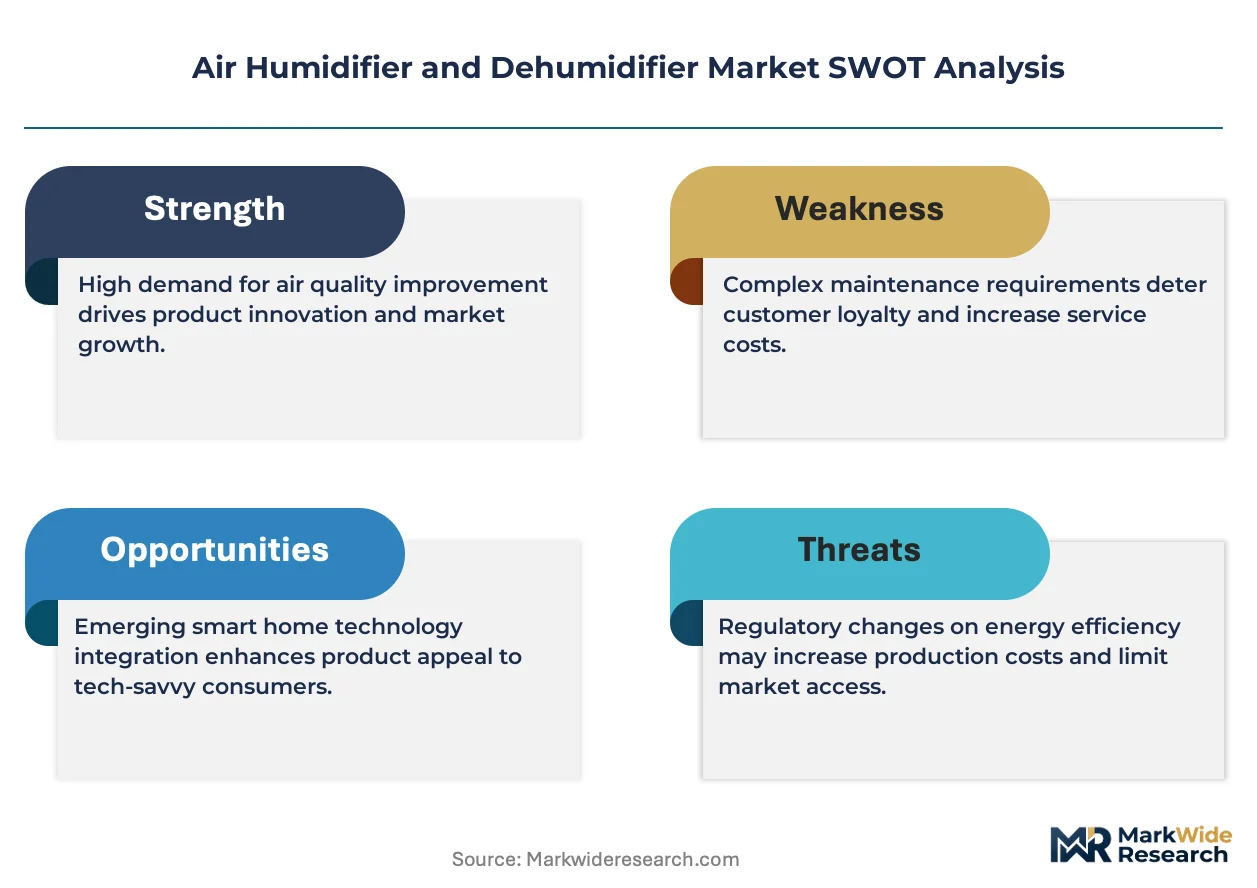
EPA appliance efficiency standards is recalibrating the cost-of-entry calculus for manufacturers targeting the North American market. Honeywell leverages its building automation ecosystem to sustain premium positioning across commercial installations. Munters anchors its portfolio in industrial desiccant systems where moisture removal rates exceed conventional refrigerant thresholds. Aprilaire competes through specialized whole-home integration with HVAC distribution networks.
Air humidifiers and dehumidifiers are electromechanical devices that regulate ambient relative humidity through vapor injection or moisture extraction, typically operating across 30-60% RH setpoints for human comfort and material preservation. The equipment serves critical functions in preventing mold proliferation, protecting electronics manufacturing cleanrooms, and maintaining pharmaceutical stability during storage. Ultrasonic and refrigerant product types dominate volume shipments, with ultrasonic systems capturing residential preference due to silent operation below 35 decibels while refrigerant architectures command industrial margins through higher moisture removal capacities. Healthcare and industrial applications represent the fastest-expanding demand pools, driven by Joint Commission accreditation requirements for surgical suites and semiconductor fabrication protocols mandating tight humidity tolerances.
DOE efficiency mandates, EPA Energy Star certification thresholds, and ASHRAE ventilation standards collectively shape product development roadmaps and procurement specifications across institutional buyers. The EU Ecodesign Directive and F-Gas Regulation are simultaneously restricting refrigerant selections for dehumidifier units sold in European markets, forcing compressor redesigns and alternative working fluid adoption. Stakeholders must monitor evolving efficiency tier transitions and refrigerant phase-down schedules to align R&D pipelines with compliance deadlines.
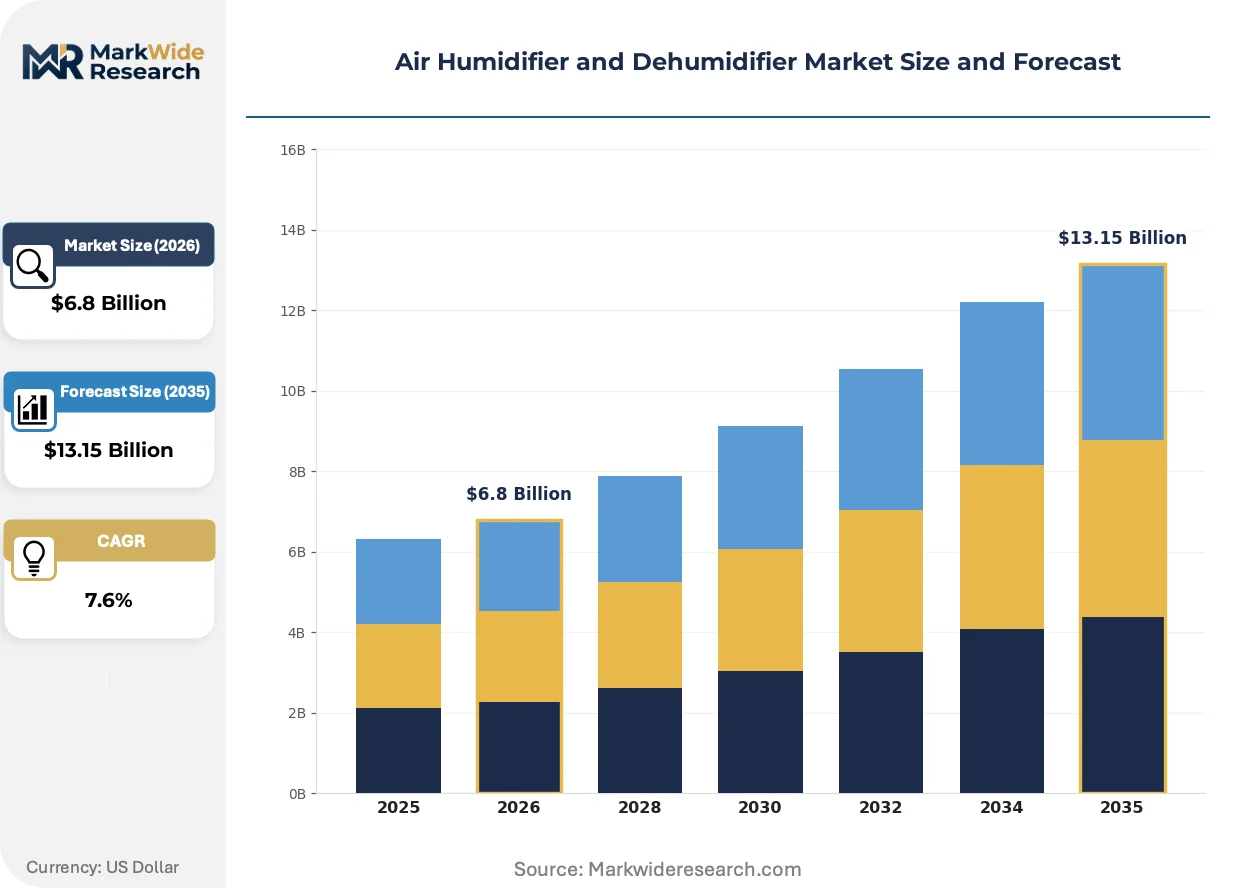
Market Dynamics
The U.S. Department of Energy's appliance efficiency standards are compressing product development cycles and forcing compressor redesigns across residential and commercial portfolios. Manufacturers must recalibrate thermal engineering specifications to maintain market access while preserving moisture removal performance.
Growth Catalysts
- Healthcare Accreditation Mandates:Joint Commission requirements for surgical suite humidity control are expanding precision system installations across U.S. hospital networks. These mandates specify 45-55% RH tolerances for infection prevention.
- Semiconductor Fabrication Protocols:Cleanroom humidity specifications in chip manufacturing are tightening to ±3% RH variance, driving demand for desiccant-based industrial dehumidifiers with redundant sensor arrays.
- China's Coastal Industrialization:Jiangsu and Guangdong provinces are intensifying moisture control investments for electronics assembly and pharmaceutical storage facilities exposed to monsoon climate patterns.
Market Restraints
- Refrigerant Input Volatility:EU F-Gas Regulation phase-down schedules are constraining R-410A and R-134a availability, forcing costly working fluid transitions in compressor-based dehumidifier architectures.
- Component Supply Concentration:Precision humidity sensors and variable-speed compressor motors concentrate among Japanese and German suppliers, creating vulnerability to regional logistics disruptions.
- Ultrasonic Scaling Limitations:Residential ultrasonic humidifiers face mineral deposit accumulation in hard water regions, degrading performance and requiring frequent maintenance cycles that deter repeat purchases.
Strategic Opportunities
- Data Center Humidity Management:Hyperscale facilities in Singapore and Ireland are adopting precision humidification for static electricity control, creating demand for adiabatic systems with low energy footprints.
- Smart Home Integration:Wi-Fi-enabled humidifiers with API connectivity to Nest and Ecobee ecosystems are penetrating North American residential markets through HVAC contractor channels.
- EU Ecodesign Incentive Alignment:Manufacturers achieving A+++ efficiency ratings under the directive gain preferential positioning in public procurement frameworks across Germany, France, and the Netherlands.
Industry Challenges
- Multi-Standard Certification Complexity:Products must simultaneously satisfy EPA Energy Star, EU Ecodesign, and ASHRAE 62.1 ventilation standards, extending testing timelines by 8-14 months for global portfolios.
- Cross-Functional Engineering Talent Scarcity:The intersection of thermodynamics, IoT firmware, and regulatory compliance requires specialists rarely available outside Munich, Boston, and Shenzhen talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Humidifier and Dehumidifier Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Evaporative, Steam, Refrigerant Technology: Microfiber, Activated Carbon, Ion Exchange, Thermoelectric Application: Residential, Commercial, Industrial, Healthcare End User: Consumers, Businesses, Hospitals, Schools |
| Companies Covered | Therma-Stor, Trane, Aprilaire, GE Appliances, Honeywell, Munters, DCA, General Filters, Dri-Eaz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Humidifier and Dehumidifier Market Strategic Shifts
Electromechanical humidity control is absorbing digital sensing, connected diagnostics, and refrigerant chemistry advances that alter competitive positioning. These developments compress traditional equipment lifecycles while opening service-based revenue streams.
Desiccant rotor technology is converging with heat pump thermal recovery systems in industrial dehumidifier architectures. Pharmaceutical warehouses and lithium battery dry rooms are adopting these hybrid systems to cut regeneration energy by 30-40%. The convergence is displacing conventional refrigerant-only designs in moisture removal applications above 12 liters per hour.
EPA's updated Energy Star 4.0 certification thresholds took effect for residential dehumidifiers, mandating integrated energy factor improvements of 15-20% over prior tiers. Manufacturers serving the U.S. market are redesigning heat exchanger geometries and migrating to brushless DC fan motors. The standard most compresses margins for economy-tier producers lacking thermal engineering depth.
Building automation procurement is unbundling humidity control from bundled HVAC maintenance contracts. Facility managers in U.S. commercial real estate are specifying separate service agreements with remote monitoring and predictive filter replacement. This pattern concentrates in Class A office properties managed by institutional investors with sustainability reporting obligations.
Air Humidifier and Dehumidifier Market Segmentation
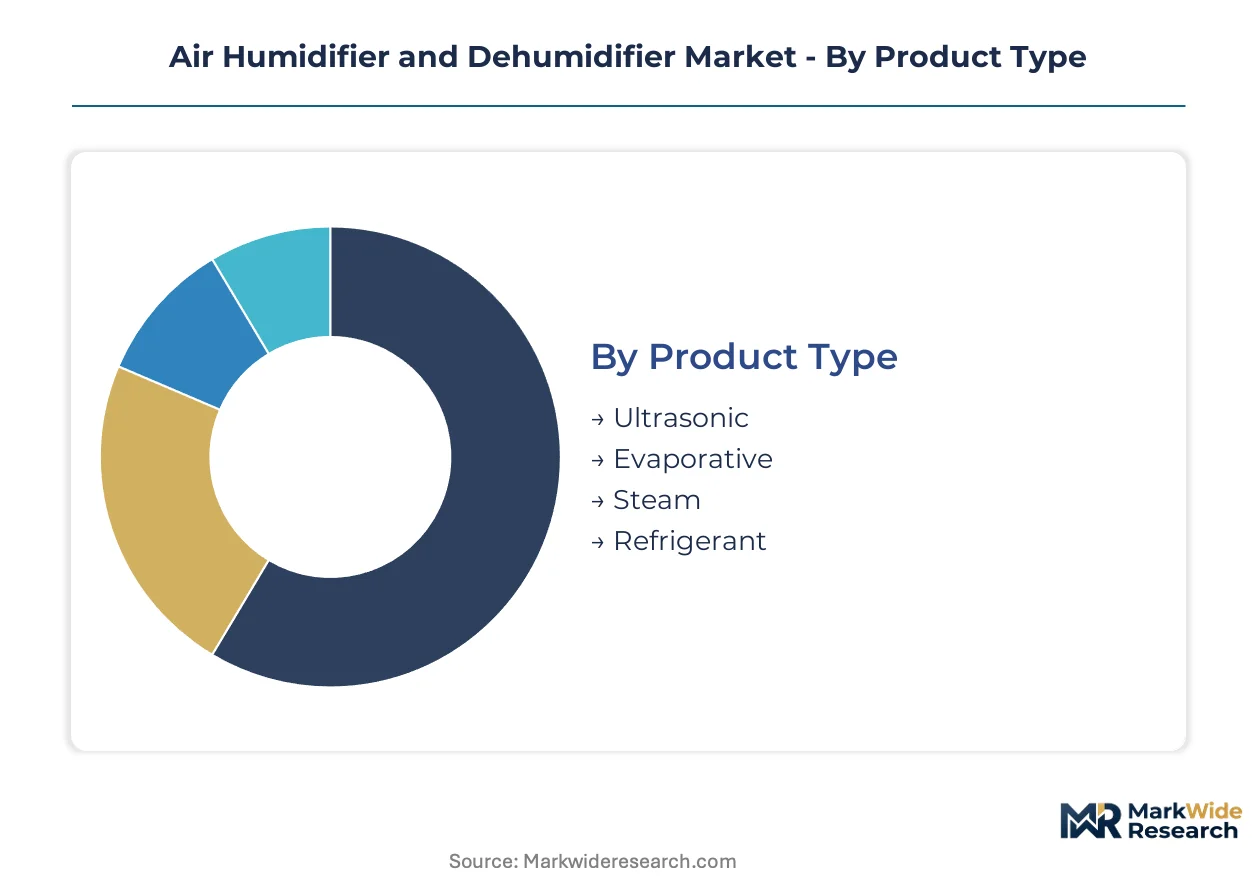
Humidity control equipment segments diverge sharply in certification burdens, with industrial and healthcare applications demanding ISO 14644 cleanroom compliance and FDA 510(k) clearance for surgical suite installations. Residential and commercial segments face lighter EPA Energy Star thresholds but must still navigate ASHRAE ventilation standards. Understanding these tiered approval pathways illuminates where margin concentration and competitive moats actually form.
Product Type:
EPA Energy Star 4.0 certification thresholds apply differentially across these architectures, with refrigerant-based dehumidifiers facing the steepest efficiency recalibration while ultrasonic humidifiers navigate decibel and mineral emission standards.
- Ultrasonic:Piezoelectric transducers generate high-frequency mechanical vibrations that atomize water into sub-5-micron droplets without thermal energy. Residential demand clusters in Japan and South Korea where silent operation below 35 decibels commands premium positioning, though hard water mineral scaling remains a recurring maintenance burden that deters repeat purchases in limestone belt regions.
- Refrigerant:Vapor-compression cycles condense atmospheric moisture on cooled evaporator coils, achieving moisture removal rates exceeding 50 liters per day in industrial configurations. China's Jiangsu province electronics assembly corridors are intensifying procurement of these systems for monsoon season humidity spikes, even as EU F-Gas Regulation phase-downs force costly R-410A to R-32 transitions.
- Evaporative:Wick-based natural evaporation with fan-assisted air distribution, common in arid climate residential applications.
- Steam:Electrode or resistive heating elements boil water to produce sterile vapor, preferred in hospital respiratory therapy departments.
Refrigerant systems sit at the top of the volume ranking, with ultrasonic units climbing the fastest on smart home integration momentum.
Technology:
Cost tier stratification separates premium filtration-integrated systems from economy-grade basic humidity control, with activated carbon and ion exchange commanding 40-60% price premiums over microfiber baseline configurations.
- Activated Carbon:Porous carbon matrices adsorb volatile organic compounds alongside moisture regulation, serving pharmaceutical storage facilities requiring simultaneous humidity and contaminant control. German industrial warehouse operators specify these dual-function systems to satisfy both EU Ecodesign efficiency mandates and ECHA REACH chemical safety protocols.
- Thermoelectric:Solid-state Peltier modules enable compressor-free dehumidification with no moving parts, achieving whisper-quiet operation essential for bedroom and nursery deployments. Singapore's compact residential market favors these units for space-constrained high-rise apartments, though energy efficiency lags refrigerant alternatives by 30-40%.
- Microfiber:Synthetic fiber wicks with antimicrobial coatings, dominant in entry-level evaporative humidifier segments.
- Ion Exchange:Resin-based water softening cartridges that reduce mineral scaling in ultrasonic systems, extending maintenance intervals.
Activated carbon leads revenue concentration on filtration integration premiums, with thermoelectric gaining share fastest in noise-sensitive residential niches.
Application:
Customer procurement patterns bifurcate between institutional buyers with 5-7 year total cost of ownership models and residential consumers prioritizing upfront purchase price and aesthetic integration.
- Healthcare:Surgical suites, pharmaceutical compounding cleanrooms, and respiratory therapy departments require Joint Commission-mandated 45-55% RH tolerances with ±2% variance alarms. U.S. hospital networks in Texas and Florida are expanding precision humidification investments for infection control, with redundant sensor arrays and BACnet building automation integration now standard specifications.
- Industrial:Semiconductor fabrication, lithium battery dry rooms, and electronics assembly demand desiccant-based systems achieving -40°C dew points. Ireland's hyperscale data center corridor is adopting adiabatic humidification for static electricity suppression, with adiabatic cooling delivering 60-70% energy reduction versus traditional steam injection.
- Residential:Single-family and multi-family dwelling humidity comfort, dominated by portable and whole-home HVAC-integrated units.
- Commercial:Office buildings, retail environments, and hospitality properties with ASHRAE 62.1 ventilation compliance requirements.
Industrial applications command the highest average selling prices, with healthcare expanding most quickly on accreditation mandate tightening.
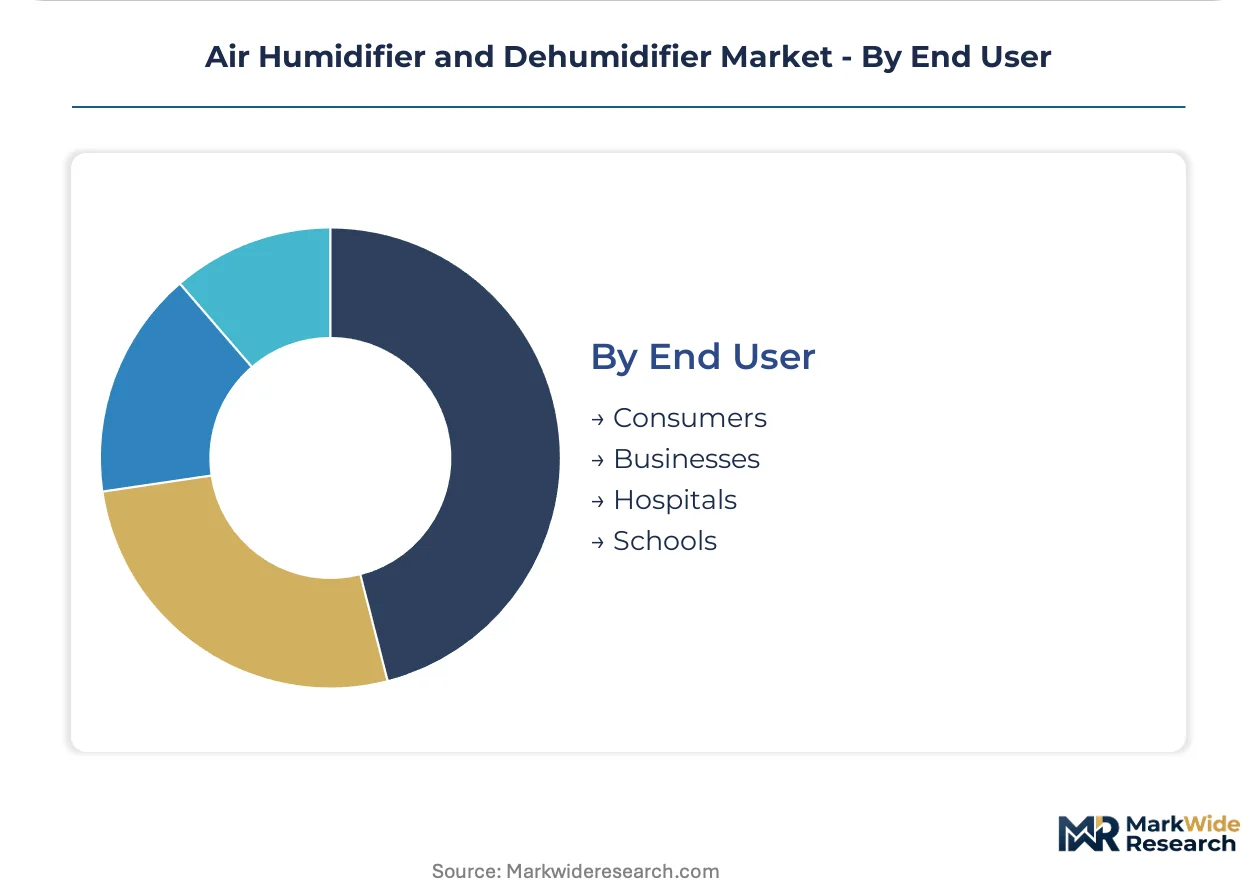
End User:
Supply channel configuration varies dramatically across these buyer types, with hospitals purchasing through group purchasing organizations and specialized medical equipment distributors while consumers buy through Amazon, Home Depot, and HVAC contractor networks.
- Hospitals:Acute care facilities, ambulatory surgery centers, and long-term care institutions with Joint Commission accreditation cycles driving replacement demand. The U.S. Southeast hospital construction boom—concentrated in Nashville, Atlanta, and Dallas-Fort Worth corridors—is expanding centralized humidity control infrastructure with 15-20 year service life specifications.
- Businesses:Corporate real estate portfolios, manufacturing facilities, and logistics warehouses with sustainability reporting obligations driving efficiency upgrades. Netherlands-based institutional investors with EU CSRD disclosure requirements are specifying A+++ Ecodesign-rated equipment for Class A office properties.
- Consumers:Individual households purchasing portable or console units through retail and e-commerce channels.
- Schools:K-12 and higher education facilities with deferred maintenance backlogs and varying indoor air quality awareness across districts.
Businesses represent the largest installed base, with hospitals demonstrating the steepest expansion trajectory on construction and accreditation investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal engineering talent clusters in Boston, Munich, and Shenzhen anchor product development pipelines for precision humidity control systems. These concentrations feed directly into regional manufacturing footprints and regulatory compliance capabilities.
United States
Hospital construction booms in Nashville, Atlanta, and Dallas-Fort Worth corridors are expanding centralized humidity control infrastructure with 15-20 year service life specifications. EPA Energy Star 4.0 certification thresholds mandate integrated energy factor improvements of 15-20% over prior tiers, forcing heat exchanger redesigns. The Joint Commission's 45-55% RH mandates for surgical suites are driving precision system installations across Texas and Florida hospital networks.
China
Jiangsu and Guangdong provinces are intensifying moisture control investments for electronics assembly and pharmaceutical storage facilities exposed to monsoon climate patterns. The country's dual carbon goals are recalibrating industrial dehumidifier efficiency specifications. Shanghai and Shenzhen electronics corridors are adopting desiccant-based systems for semiconductor fabrication cleanrooms requiring ±3% RH variance control.
Germany
Industrial warehouse operators specify dual-function humidity and contaminant control systems to satisfy both EU Ecodesign efficiency mandates and ECHA REACH chemical safety protocols. The EU F-Gas Regulation phase-down schedules are constraining R-410A availability, forcing costly working fluid transitions. Bavaria and Baden-Württemberg manufacturing clusters are pioneering heat pump thermal recovery integrations that cut regeneration energy by 30-40%.
Japan
Residential demand clusters in Japan and South Korea where silent operation below 35 decibels commands premium positioning for ultrasonic systems. METI efficiency standards and JIS certification requirements shape product development roadmaps. Tokyo and Osaka metropolitan markets favor compact thermoelectric units for space-constrained high-rise apartments, despite 30-40% energy efficiency lag versus refrigerant alternatives.
Singapore
Hyperscale data center facilities are adopting adiabatic humidification for static electricity control, with adiabatic cooling delivering 60-70% energy reduction versus traditional steam injection. The tropical climate drives year-round dehumidification demand for electronics manufacturing and residential comfort. The compact residential market favors thermoelectric units with no moving parts for bedroom and nursery deployments.
Air Humidifier and Dehumidifier Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between building automation integrators, industrial desiccant system fabricators, and residential comfort equipment manufacturers. Three archetypes dominate: diversified technology conglomerates with HVAC ecosystem leverage, industrial moisture control specialists with deep desiccant engineering capabilities, and residential-focused brands with distribution network density. Competitive moves concentrate on smart home API integrations and compressor redesigns for refrigerant phase-down compliance.
Among diversified technology conglomerates, Honeywell and GE Appliances occupy positions leveraging building automation ecosystem integration for commercial and residential market access. Munters anchors the industrial desiccant specialist tier with expertise in high-capacity moisture removal architectures. Aprilaire exemplifies the residential-focused archetype through HVAC contractor channel relationships and whole-home system integration. Therma-Stor, Trane, and DCA represent mid-tier fabricators with regional manufacturing footprints and specialized application expertise.
| Leading Market Players |
|---|
| Therma-Stor |
| Trane |
| Aprilaire |
| GE Appliances |
| Honeywell |
| Munters |
| DCA |
| General Filters |
| Dri-Eaz |
| Others |
Value Chain & Pricing Dynamics
Backward integration into compressor manufacturing anchors both supply resilience and pricing power for dehumidifier producers navigating refrigerant transition costs. Captive production of variable-speed motors and heat exchanger coils insulates tier-one manufacturers from Japanese and German supplier concentration while supporting premium positioning against import-dependent competitors.
Pricing Analysis
Bundled service contracts with predictive maintenance and remote monitoring command 25-40% lifetime value premiums over transactional equipment sales in U.S. commercial real estate. Certification grade under EPA Energy Star 4.0 and EU Ecodesign A+++ ratings drives price differentiation between efficiency tiers. Cost compression in economy ultrasonic segments intensifies as mineral scaling issues erode brand loyalty and trigger replacement cycles. Residential consumers through Amazon and Home Depot channels exhibit highest price sensitivity, while hospital GPO procurement prioritizes total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Japanese suppliers of precision humidity sensors and German manufacturers of variable-speed compressor motors, creating chokepoints for industrial system fabricators. Component sourcing concentrates in China, Japan, and Germany, with Shenzhen electronics corridors feeding residential ultrasonic assembly and Bavaria anchoring thermoelectric module production. Raw material dependencies span rare earth elements for piezoelectric transducers, copper for refrigerant coils, and activated carbon matrices for filtration-integrated systems. Tariff exposure on Chinese-manufactured electronic components threatens margin stability for North American residential brands. Distribution runs through HVAC contractor networks for whole-home integration, medical equipment distributors for hospital sales, and e-commerce platforms for portable consumer units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with Joint Commission surgical suite mandates and semiconductor cleanroom specifications shifting procurement toward premium precision systems with 15-20 year service life requirements.
For Market Incumbents: Extend building automation ecosystem integration to capture facility management unbundling trends in Class A office properties. Deepen captive supply of variable-speed compressor motors to offset Japanese supplier concentration risks. Accelerate R-32 refrigerant transition pipelines ahead of EU F-Gas phase-down deadlines to defend margin position against retrofit-dependent competitors. For New Entrants and Emerging Players: Capture thermoelectric niche penetration in Singapore and Japan residential markets where noise sensitivity commands premium positioning despite energy efficiency tradeoffs. Target data center adiabatic humidification in Ireland and Singapore corridors with low-energy footprint specifications. Pursue API-first smart home integration through Nest and Ecobee ecosystem partnerships as primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for industrial desiccant specialists because pharmaceutical and lithium battery dry room demand concentrates procurement among engineering-capable fabricators with ISO 14644 compliance track records. Five-to-ten year viability hinges on refrigerant chemistry transition execution and heat pump thermal recovery integration depth. Watch EU F-Gas Regulation enforcement acceleration as signal for compressor redesign investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Investment | R-410A to R-32 migration preserves EU market access under F-Gas phase-down schedules. |
| Building Automation Integration | BACnet protocol compatibility captures facility management unbundling in U.S. commercial real estate. |
| Desiccant Heat Pump Hybridization | Thermal recovery integration cuts pharmaceutical warehouse regeneration energy by 30-40%. |
| Smart Home API Development | Wi-Fi-enabled connectivity with Nest and Ecobee ecosystems penetrates North American residential channels. |
| Precision Sensor Array Deployment | Redundant humidity monitoring achieves ±2% variance alarms for Joint Commission surgical suite compliance. |
Study Parameters
Coverage spans the United States, China, Germany, Japan, and Singapore, with primary inputs from each market cluster combining executive interviews with HVAC contractor network managers, hospital biomedical engineering directors, pharmaceutical facility managers, semiconductor cleanroom operators, and industrial procurement leads. Secondary validation draws from EPA Energy Star certification databases, EU Ecodesign compliance registries, ASHRAE standard documentation, and customs trade flow records. Bottom-up equipment shipment analysis triangulates against top-down construction spending and accreditation mandate timelines.
Granularity-level modeling operates at product type, technology tier, application segment, and end-user archetype dimensions, with refrigerant chemistry transition and smart home connectivity adoption tracked as cross-cutting variables. CAGRs derive from logistic curve fitting to historical efficiency standard implementation patterns and healthcare construction cycle phasing. Forecast inputs include Joint Commission accreditation audit schedules, EU F-Gas Regulation phase-down milestones, and semiconductor fabrication capacity expansion announcements.
Refrigerant chemistry transition delays, healthcare construction cycle interruptions, and sensor supply chain disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding standard implementation timelines and substitution elasticity parameters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
France HVAC Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
Wall Fan Coil Market