
 Global Portable Evaporative Air Cooler Market | 2026-2036
Global Portable Evaporative Air Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Evaporative Air Cooler Market Foresight
Market Context
Modular add-on configurations—filter upgrades, ionizer attachments, and smart controller bundles—is rebalancing buyer choice toward customizable systems over fixed-feature units. Symphony Ltd. leverages its India-centric manufacturing scale to dominate price-sensitive segments across South Asia and the Middle East. Honeywell International Inc. sustains brand strength in North American retail channels through broad distribution partnerships with home improvement chains. Portacool LLC specializes in industrial-grade portability, anchoring its position in warehouse and outdoor event applications where airflow volume determines purchasing decisions.
Technical Definition and Segment Structure
A portable evaporative air cooler is a self-contained cooling device that draws ambient air through water-saturated cooling pads, typically cellulose or aspen fiber media with thickness ranging from 50 to 200 millimeters, to produce cooled air through the latent heat of vaporization without refrigerant compression cycles; its primary commercial purpose is to deliver energy-efficient spot cooling in dry climates where wet-bulb depression exceeds 10 degrees Celsius. Tower coolers occupy the premium residential tier due to aesthetic integration and space efficiency, while personal coolers compete on portability metrics for individual workstation deployment. Hybrid evaporative technology, combining direct and indirect stages, captures the fastest-growing technology segment as commercial buyers prioritize humidity control alongside temperature reduction in corporate offices and hospitality units.
Regulatory Framework and Outlook
The EPA Energy Star program and California Energy Commission appliance standards shape minimum efficiency thresholds for units sold in the United States, while the EU Ecodesign Directive and REACH chemical safety protocols govern material composition and energy labeling across European markets. India's Bureau of Energy Efficiency star ratings and BIS electrical safety certifications create compliance layers that favor established manufacturers with testing infrastructure over import-dependent entrants. Stakeholders must monitor evolving water-use restrictions in drought-prone jurisdictions, as municipal conservation ordinances increasingly scrutinize evaporative cooling systems during peak summer demand periods.
Market Dynamics
Modular component architectures are fragmenting buyer preferences across the portable evaporative air cooler supply base, as purchasers in water-scarce climates increasingly assemble cooling systems from discrete subsystems rather than accepting fixed-feature factory configurations.
Growth Catalysts
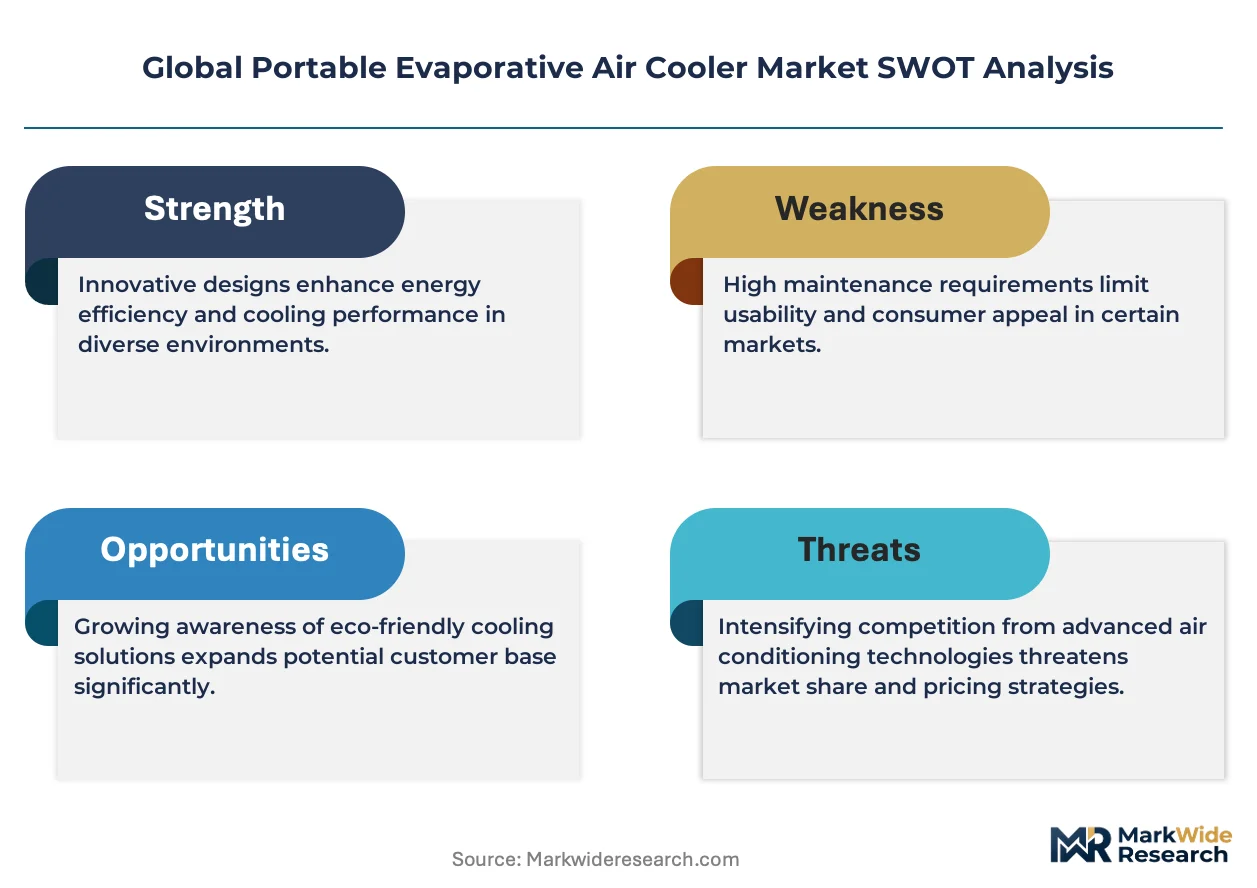
- EPA Energy Star certification thresholds:Stricter efficiency benchmarks in the United States are filtering out low-performance imports and elevating certified manufacturers into retail channel priority positions.
- Apartment cooling retrofit cycles:Multi-unit residential buildings in India and Australia are replacing fixed HVAC with portable spot-cooling units to avoid infrastructure modification costs.
- Cellulose cooling pad density advances:Thicker 150-200mm media formulations are extending effective cooling ranges by 15-20% in dry-climate deployment zones.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger and motor housing materials face commodity price swings that compress margin predictability for mid-tier manufacturers.
- Water-use ordinance proliferation:Municipal conservation mandates in drought-prone southwestern US jurisdictions impose operational curtailments during peak summer demand periods.
- Refrigerant-based mini-split substitution:Falling costs of variable-speed compressor units in 1-2 ton capacities erode evaporative cooling's historical price advantage in semi-arid transition zones.
Strategic Opportunities
- Indonesia and Philippines penetration gaps:Island archipelago markets with high humidity but seasonal dry periods remain unserved by established distribution networks focused on continental dry zones.
- Outdoor event and warehouse rental channels:Short-term cooling-as-a-service models for construction sites and festival infrastructure bypass residential purchase cycle constraints.
- EU Ecodesign Directive material compliance:REACH-aligned component sourcing creates first-mover certification advantages for European market entry ahead of 2027 enforcement milestones.
Industry Challenges
- Thermofluid engineering talent scarcity:Wet-bulb optimization and psychrometric system design expertise concentrates in legacy HVAC firms, constraining cooler-specialist R&D pipelines.
- Multi-jurisdiction certification sequencing:Simultaneous BIS, EPA, and CE marking requirements extend product launch timelines by 8-14 months for cross-border portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Evaporative Air Cooler Market |
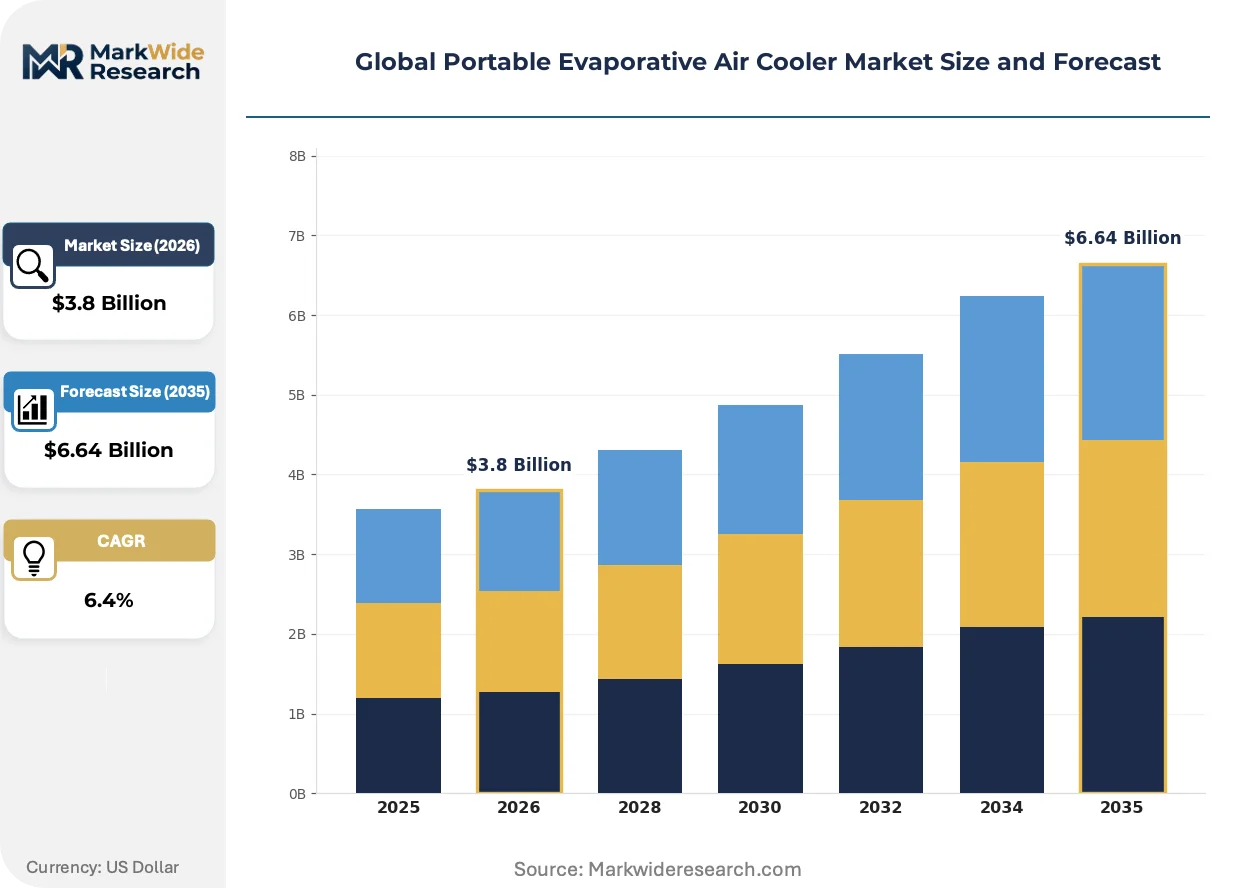
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Coolers, Tower Coolers, Desk Coolers, Window Coolers Technology: Direct Evaporative, Indirect Evaporative, Hybrid Evaporative, Swamp Cooling Application: Residential Cooling, Commercial Spaces, Outdoor Events, Warehousing End User: Retail Outlets, Corporate Offices, Educational Institutions, Hospitality Units |
| Companies Covered | Honeywell International Inc., Symphony Ltd., Bajaj Electricals Ltd., Hessaire Products Inc., Portacool LLC, NewAir, Aolan Industry Co Ltd., Shenzhen Lianchuang Technology Group Co. Ltd., Seeley International Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Evaporative Air Cooler Market Shifts & Advancements
Product architectures are decomposing into interoperable subsystems, enabling buyers to configure cooling performance through aftermarket attachments rather than factory-locked specifications. This shift is compressing product lifecycles while expanding addressable use cases.
Smart controller ecosystems are modularizing around Bluetooth mesh and Wi-Fi-enabled hub platforms, allowing residential users in Phoenix, Arizona and Jaipur, Rajasthan to integrate evaporative coolers with home automation networks. Commercial buyers in Australian mining camps are adopting these configurations for centralized facility management. The technology is modularizing supplier relationships as electronics specialists displace traditional HVAC controls vendors.
REACH chemical safety protocols in Europe are mandating phased elimination of certain biocidal treatments in cooling pad materials, forcing reformulation of cellulose media toward salt-resistant natural fiber alternatives. Manufacturers serving German and French retail channels are accelerating compliance timelines to capture shelf space ahead of 2026 material disclosure deadlines. Industrial-grade units with stainless steel reservoirs face accelerated testing cycles to verify corrosion resistance under new chloride exposure standards.
Rental and subscription-based acquisition models are displacing outright purchase in commercial segments, particularly among event management firms and temporary construction site operators. Channel intermediaries in Dubai and Riyadh are building captive fleets of industrial portable units for seasonal deployment. This pattern is most visible in Middle Eastern hospitality and infrastructure development verticals where project-based cooling needs resist capital equipment commitments.
Global Portable Evaporative Air Cooler Market Segmentation
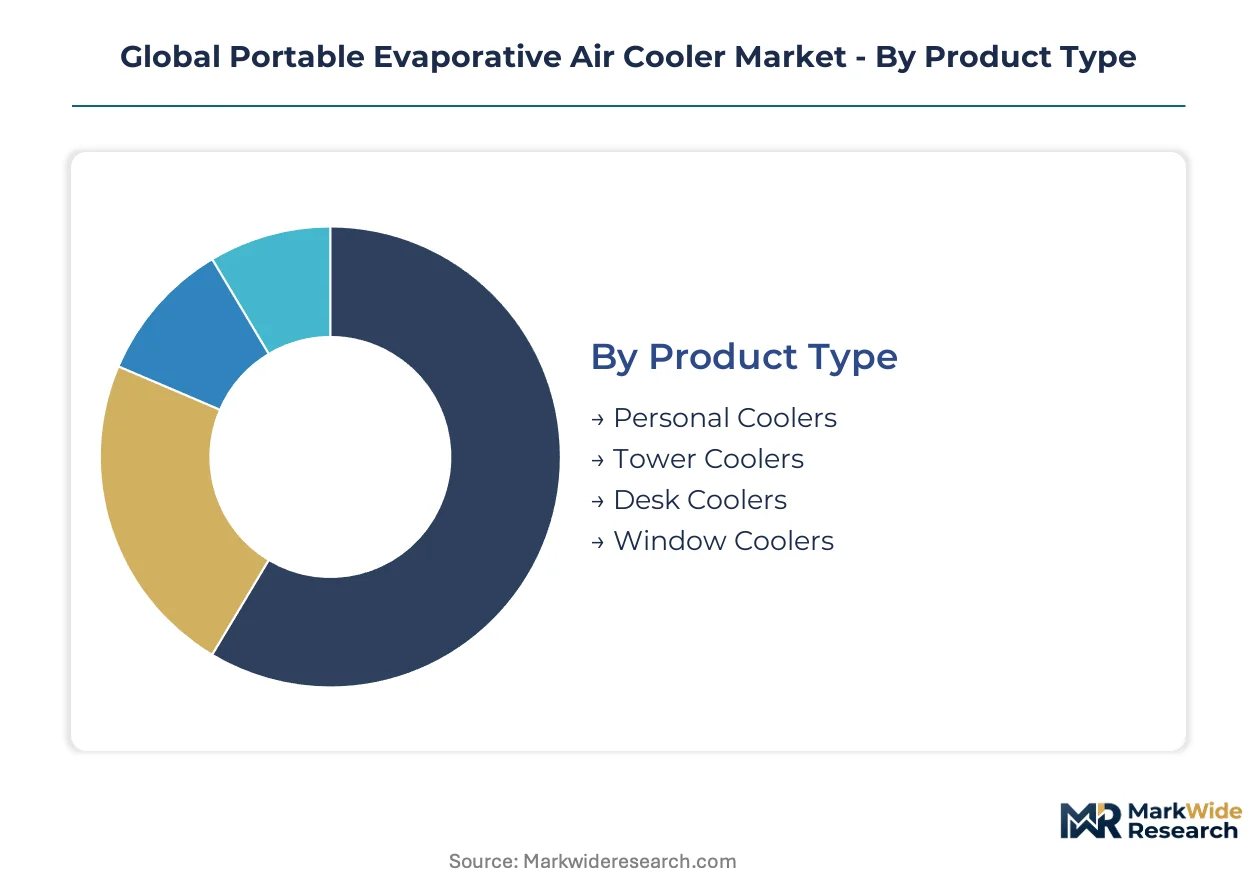
Product differentiation in portable evaporative air coolers follows climate-specific performance requirements and installation constraints rather than brand positioning. Buyers select configurations based on wet-bulb depression thresholds, water availability, and mobility needs across residential and commercial deployment scenarios.
Product Type:
Supply concentration tilts toward manufacturers with dedicated tooling for high-volume tower and personal cooler platforms, while window and desk variants rely on shared component ecosystems.
- Tower Coolers:Vertical form factors integrate 150-200mm cellulose cooling pads within space-efficient enclosures designed for residential living areas. Demand concentrates in Indian urban apartments and Australian suburban homes where floor-space constraints intersect with dry-climate cooling needs. Premium pricing reflects aesthetic engineering and smart controller compatibility.
- Personal Coolers:Compact units below 10 liters capacity target individual workstation cooling with USB or low-voltage DC power options. Corporate offices in Phoenix and Denver deploy these for hot-desk environments where central HVAC proves insufficient. Portability metrics dominate purchasing decisions over absolute cooling output.
- Desk Coolers:Ultra-portable designs with sub-5 liter reservoirs occupy immediate personal space cooling niches in educational institutions and home offices.
- Window Coolers:Semi-permanent installation units bridge portable and fixed-system categories, finding demand in rental properties across southwestern United States jurisdictions.
Tower coolers absorb the bulk of installed capacity; personal coolers are expanding most quickly.
Technology:
Cost tier stratification separates premium hybrid systems from commodity direct evaporative platforms, with indirect configurations occupying a narrowing mid-market position.
- Hybrid Evaporative:Combined direct and indirect stages achieve wet-bulb effectiveness above 90% through counterflow heat exchanger integration. Corporate offices and hospitality units in Dubai and Riyadh prioritize these for humidity-controlled cooling where guest comfort standards override energy cost considerations. REACH-compliant material sourcing adds certification complexity for European market entry.
- Direct Evaporative:Single-stage water-saturated pad systems deliver the simplest thermodynamic pathway with lowest capital cost. Residential cooling in Jaipur, Lucknow, and other North Indian cities depends on these units for pre-monsoon heat management. BIS electrical safety certification requirements filter import competition.
- Indirect Evaporative:Separated air streams prevent humidity addition, suiting semi-arid transition zones in Spain and Portugal where moderate cooling without moisture loading is preferred.
- Swamp Cooling:Colloquial category encompassing basic aspen-fiber pad designs dominates rural and industrial price-sensitive segments in Mexico and Central Asian markets.
Direct evaporative platforms retain volume leadership; hybrid configurations gain share fastest in commercial specifications.
Application:
Volume distribution tracks seasonal heat intensity and infrastructure retrofit cycles across building stock categories with varying HVAC penetration.
- Residential Cooling:Apartment dwellers in water-scarce regions deploy portable units to avoid strata approval for fixed system installation. Australian multi-unit residential buildings increasingly specify portable spot-cooling during HVAC replacement intervals.
- Commercial Spaces:Retail outlets and small offices in India's tier-2 cities adopt evaporative cooling for customer zones where compressor-based air conditioning costs prove prohibitive.
- Outdoor Events:Festival infrastructure and temporary hospitality in Saudi Arabia and UAE drives rental fleet investment for industrial-grade portable deployment.
- Warehousing:High-bay logistics facilities in Phoenix and Las Vegas combine evaporative pre-cooling with mechanical ventilation for worker comfort compliance.
Residential applications anchor production planning; outdoor event deployment shows the steepest expansion trajectory.
End User:
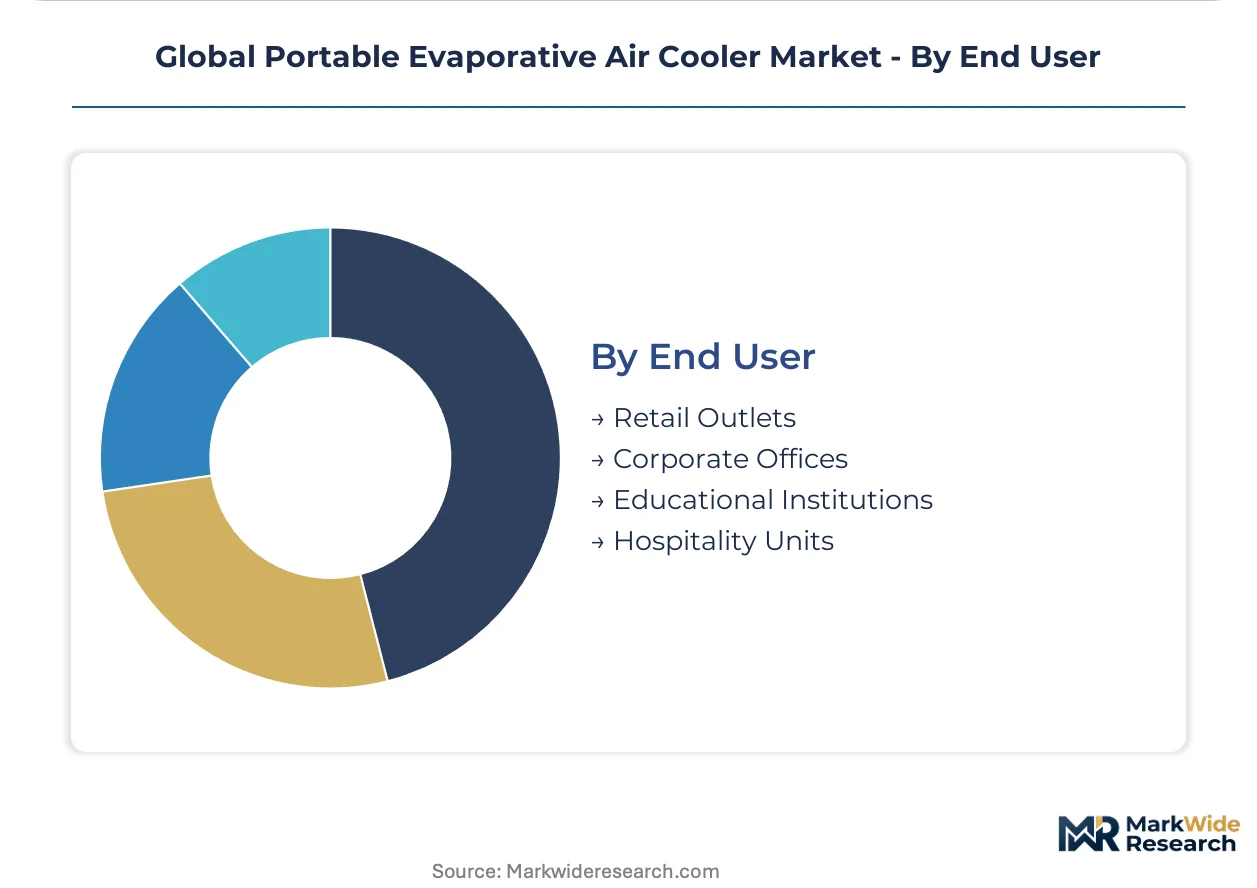
Customer type determines specification rigor, with corporate and hospitality buyers imposing certification burdens that commodity retail channels bypass.
- Corporate Offices:Facility managers in Bangalore and Hyderabad specify Energy Star-equivalent efficiency thresholds for procurement compliance. Smart controller integration and centralized monitoring capability drive specification premiums.
- Hospitality Units:Hotels and resorts in Rajasthan and Arizona balance guest-facing aesthetics with operational water-use accountability under municipal conservation ordinances.
- Retail Outlets:Electronics and appliance chains in India and Middle Eastern markets prioritize margin-friendly SKUs with established brand recognition over technical differentiation.
- Educational Institutions:Schools and universities in Australia's Northern Territory deploy personal and desk coolers for temporary classroom cooling during extreme heat events.
Corporate offices command the tightest specification standards; hospitality units are climbing fastest in absolute volume terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in India and China while consumption tilts toward arid climate zones across North America, the Middle East, and South Asia. This production-consumption divide shapes logistics networks and certification sequencing for cross-border portfolios.
United States
Apartment cooling retrofits in Phoenix, Las Vegas, and Tucson drive residential spot-cooling demand as multi-unit buildings avoid HVAC infrastructure modifications. EPA Energy Star certification thresholds filter low-performance imports from retail channels. California Energy Commission appliance standards impose efficiency minimums that elevate certified manufacturers into Home Depot and Lowe's priority positions.
India
Pre-monsoon heat waves in Jaipur, Lucknow, and Delhi-NCR sustain peak seasonal demand for direct evaporative units in residential and small commercial segments. Bureau of Energy Efficiency star ratings and BIS electrical safety certifications create compliance layers favoring established manufacturers with testing infrastructure. Symphony Ltd. leverages India-centric manufacturing scale to dominate price-sensitive South Asian and Middle Eastern distribution networks.
Australia
Multi-unit residential buildings in Sydney and Melbourne specify portable spot-cooling during HVAC replacement intervals to bypass strata approval requirements. The country's national energy efficiency regulator mandates minimum performance thresholds for cooling equipment sold through retail channels. Mining camps in Western Australia's Pilbara region deploy smart controller ecosystems for centralized facility management of evaporative cooling fleets.
Saudi Arabia
Hospitality and infrastructure development verticals in Riyadh and Jeddah drive project-based cooling needs that resist capital equipment commitments. The Saudi Food and Drug Authority and SASO quality mark requirements govern product safety and material composition for imported cooling equipment. Channel intermediaries in Dubai and Riyadh build captive rental fleets for seasonal deployment at outdoor events and construction sites.
Germany
REACH chemical safety protocols and EU Ecodesign Directive material compliance deadlines force reformulation of cellulose cooling pads toward salt-resistant natural fiber alternatives. Industrial clusters in Bavaria and North Rhine-Westphalia host HVAC component suppliers accelerating testing cycles for corrosion resistance under new chloride exposure standards. German retail channels prioritize shelf space for manufacturers ahead of 2026 material disclosure deadlines.
Global Portable Evaporative Air Cooler Market Competitive Landscape
The competitive structure tilts toward scale-driven manufacturers with dedicated tooling for high-volume platforms and modular component specialists serving aftermarket attachment demand. Three archetypes dominate: India-centric mass-market fabricators with captive distribution across South Asia, North American retail-channel brands leveraging home improvement chain partnerships, and industrial-grade portability specialists anchoring warehouse and outdoor event applications. M&A activity concentrates on electronics specialists acquiring traditional HVAC controls vendors, while capacity expansion targets REACH-aligned component sourcing for European market entry.
Among India-based manufacturers, Symphony Ltd. and Bajaj Electricals Ltd. exemplify the mass-market archetype with domestic manufacturing scale. Honeywell International Inc. represents the North American retail-channel position, while Portacool LLC occupies the industrial-grade specialization tier. These three anchors demonstrate how geographic origin and company structure correlate with strategic positioning across residential, commercial, and rental-channel segments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Symphony Ltd. |
| Bajaj Electricals Ltd. |
| Hessaire Products Inc. |
| Portacool LLC |
| NewAir |
| Aolan Industry Co Ltd. |
| Shenzhen Lianchuang Technology Group Co. Ltd. |
| Seeley International Pty Ltd. |
| Others |
Supply & Pricing Matrix
Industrial-grade rental fleet operators in Dubai and Riyadh anchor volume procurement for premium portable evaporative air coolers, locking in contract-based long-term offtake pricing that insulates certified manufacturers from spot-market volatility in residential channels. This buyer concentration tilts pricing power toward REACH-compliant suppliers with captive testing infrastructure, while mid-tier fabricators serving Indian retail face transactional spot pressure.
Pricing Analysis
Cost-down pressure on standard-tier residential units accelerates as copper and aluminum commodity swings compress margin predictability for mid-tier manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and smart controller compatibility. Price differentiation hinges on BIS electrical safety tier and cellulose cooling pad density specification. Corporate procurement teams in Bangalore and Hyderabad exhibit lowest price sensitivity due to Energy Star-equivalent compliance mandates, while rural Indian households drive economy-tier volume.
Supply Chain Analysis
Freight cost inflation on India-to-Middle East routes is reshaping regional distribution economics for tower cooler platforms. Manufacturing gravity centers on India and China, with component ecosystems for cellulose media and motor housings concentrated in Gujarat and Guangdong provinces. Raw material dependencies rest on copper windings, aluminum heat exchangers, and aspen fiber or cellulose cooling substrates. Single-source vulnerability in REACH-compliant biocide formulations for European-bound pads elevates compliance risk. Distribution runs through home improvement chains in North America, specialized HVAC distributors in Australia, and electronics retail networks across South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulose cooling pad density advances and REACH-aligned material reformulation are constraining qualified supplier capacity, propping pricing premiums for certified manufacturers across European and Middle Eastern channels.
For Market Incumbents: To counter falling variable-speed mini-split substitution in semi-arid transition zones, Symphony Ltd. and Honeywell International Inc. should deepen backward integration into cellulose media production and accelerate BIS-plus-EPA dual certification sequencing. Channel control through captive rental fleet partnerships in Saudi Arabia and UAE hospitality verticals defends margin position against price-commoditized imports. For New Entrants and Emerging Players: Launch via short-term cooling-as-a-service rental models in Indonesia and Philippines archipelago markets, where seasonal dry periods intersect with unserved distribution networks. Target corporate office specifications in Bangalore and Hyderabad for smart controller-integrated hybrid systems, exploiting thermofluid engineering talent scarcity among legacy HVAC specialists. For Investors and Strategic Acquirers: The window for entry favors electronics specialists with Bluetooth mesh and Wi-Fi-enabled hub platforms, as modular controller ecosystems displace traditional HVAC controls vendors. Watch for inflection when municipal water-use ordinances in southwestern US jurisdictions trigger operational curtailment thresholds during peak summer demand periods.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Aligned Material Reformulation | Positions cellulose pad suppliers ahead of 2026 EU disclosure deadlines. |
| Smart Controller Platform Integration | Enables centralized facility management for Australian mining camp deployments. |
| Captive Rental Fleet Buildout | Bypasses residential purchase cycle constraints in Saudi event infrastructure. |
| Dual Certification Sequencing Investment | Compresses BIS-plus-EPA launch timelines for cross-border portfolios. |
| Backward Integration into Cooling Media | Secures supply of 150-200mm cellulose formulations for premium tower platforms. |
Research Methodology
Document review covered customs and trade data, Bureau of Energy Efficiency star rating disclosures, and EPA Energy Star certification registries, complemented by interviews with HVAC procurement managers at Indian retail chains, facility directors at Australian mining operations, and thermofluid engineering leads at established cooler manufacturers. Primary fieldwork engaged rental fleet operators in Dubai and Riyadh, cellulose media suppliers in Gujarat, and electronics controls specialists displacing traditional HVAC vendors. Secondary validation drew from EU Ecodesign Directive implementation timelines, REACH chemical safety protocol amendments, and California Energy Commission appliance standard filings. Bottom-up unit shipment modeling triangulated against top-down market value reconstruction.
Segment-level projections across product type, technology tier, application vertical, and end-user category fed aggregate market sizing over the projection horizon. CAGRs derived from regression against historical efficiency mandate adoption curves and wet-bulb depression climate mapping. Psychrometric system performance data and cooling pad density specifications informed technology segment splits.
Water-use ordinance proliferation, copper and aluminum commodity volatility, and refrigerant-based mini-split cost trajectories are the dominant revision risks for evaporative cooling demand forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Heat Moisture Exchanger Market
HVAC Equipment
Air Conditioning Equipment Market