
 Electric Underfloor Heating Market | 2026-2036
Electric Underfloor Heating Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Underfloor Heating Market Analysis
Aftermarket service revenue is reconfiguring how manufacturers capture lifetime value in the electric underfloor heating sector. nVent Electric plc leverages its electrical infrastructure heritage to dominate commercial-grade cable systems across North America. Warmup plc sustains brand strength in the United Kingdom through specialized mat and foil products for residential renovation. Danfoss Group anchors its position via advanced control system integration, competing on energy management rather than heating element commodity supply.
Electric underfloor heating comprises resistive heating elements—typically copper or alloy conductors insulated within polymer sheaths—embedded beneath finished floor surfaces to deliver radiant heat at surface temperatures between 25°C and 29°C. Mats dominate new-build residential applications due to standardized spacing and rapid installation, while cables capture renovation margins through custom layout flexibility. Smart thermostats represent the fastest-expanding control system segment, displacing manual units as building energy codes tighten and homeowners prioritize programmable load management.
The EU Green Deal and F-Gas Regulation are reshaping product standards across Europe, phasing out gas boilers and elevating electric heating compliance requirements. In the United States, the IRA's home energy rebates are expanding addressable demand for retrofit electric heating systems. Building code officials in Germany and France are mandating lower primary energy factors that favor electric solutions paired with renewable generation. Stakeholders must monitor how national implementation timelines for heat pump coexistence rules affect pure electric underfloor positioning against hybrid systems.
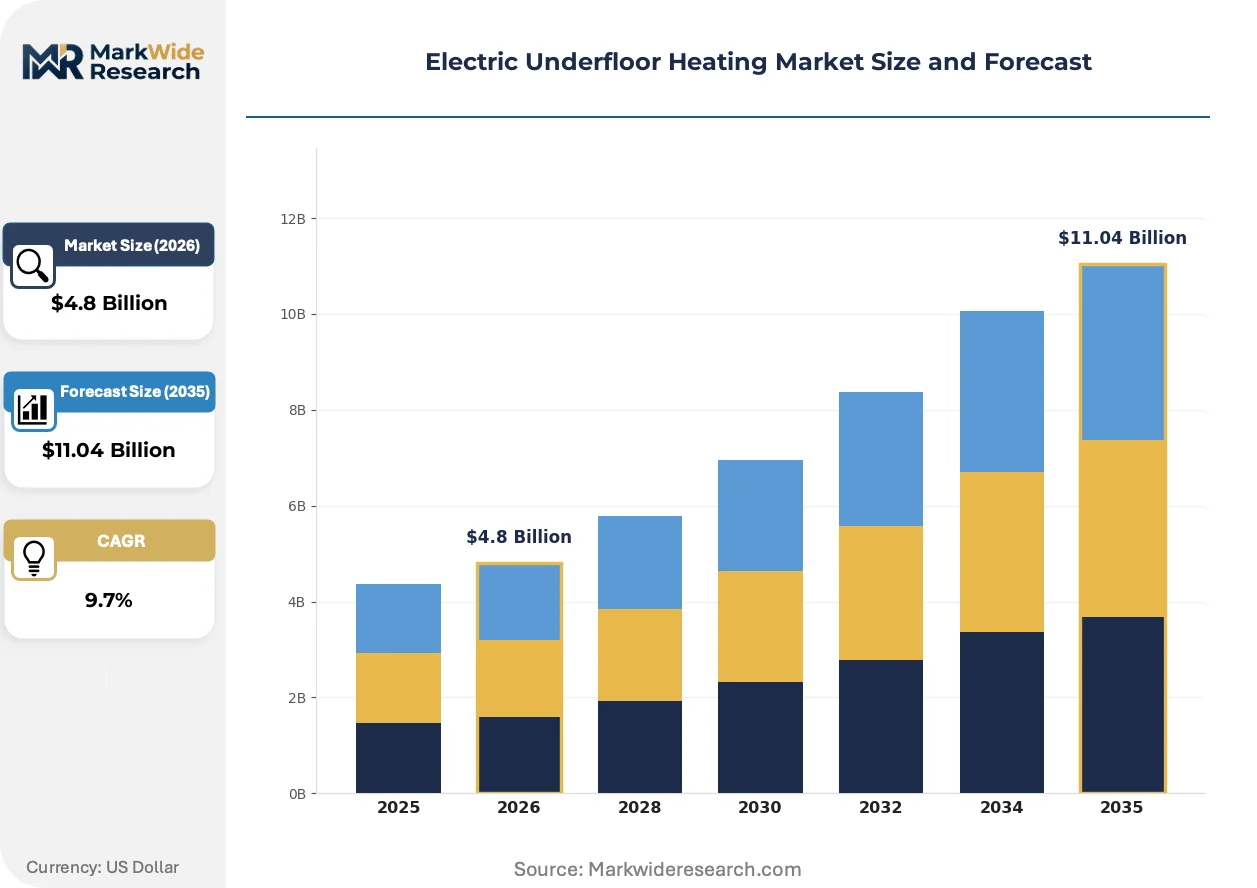
Market Dynamics
The EU Green Deal's building renovation mandates are compressing replacement cycles for fossil-fuel heating systems, while Germany's net-zero housing specifications and the United Kingdom's retrofit decarbonization programs create parallel demand channels for electric underfloor systems.
Growth Catalysts
- EU Green Deal building mandates:Member states must renovate residential stock to meet carbon targets, accelerating electric heating adoption in France, Italy, and Poland.
- Residential net-zero construction:German builders specify electric underfloor systems in Passivhaus-certified developments where heat pump integration proves technically challenging.
- Smart thermostat integration:Programmable load management capabilities align with time-of-use electricity tariffs, driving specification in high-renewable grid regions.
Market Restraints
- Copper conductor volatility:Resistive element manufacturers face margin compression from London Metal Exchange price swings in refined copper cathode.
- Heat pump substitution threat:Air-source and ground-source heat pumps capture whole-house heating projects where underfloor distribution already exists.
- Primary energy factor tightening:French and German building codes penalize pure electric heating without renewable pairing, creating compliance friction.
Strategic Opportunities
- United Kingdom retrofit channel:Aging Victorian and Edwardian housing stock requires decarbonization upgrades without structural floor replacement.
- Renewable generation pairing:Solar PV-to-underfloor direct coupling eliminates grid dependency for daytime heating loads in residential applications.
- Control system convergence:Integration with home energy management platforms opens specification through HVAC contractor channels previously closed to heating element suppliers.
Industry Challenges
- Electrical contractor certification gaps:Underfloor heating installation requires Part P competency in the United Kingdom, limiting qualified installer availability.
- Legacy wet system integration:Hybrid configurations combining electric mats with existing radiator circuits demand complex hydraulic and electrical coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Underfloor Heating Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foil, Mats, Cables, Film Installation Type: New Build, Renovation, Retrofit, Industrial End User: Residential, Commercial, Hospitality, Educational Control System: Smart Thermostats, Manual Thermostats, Programmable, Wireless |
| Companies Covered | nVent Electric plc, Warmup plc, Resideo Technologies Inc., Rehau Ltd, Danfoss Group, Schneider Electric SE, Mitsubishi Electric Corporation, Siemens AG, ThermoSoft International Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Underfloor Heating Market Emerging Trajectories
Digital control architectures and material science advances are redefining performance benchmarks across the electric underfloor heating sector. Specification decisions increasingly hinge on system-level energy management capabilities rather than heating element thermal output alone.
Self-regulating polymer composite heating cables adjust resistance with temperature fluctuations, eliminating overheating risk in complex floor geometries. Large-scale residential developers in Scandinavia specify these systems for timber-framed construction where thermal mass is minimal. Conventional fixed-resistance cable layouts are rendering obsolete in multi-zone applications where load variability demands adaptive response.
The F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants is elevating electric heating compliance pathways across EU member states. Heat pump manufacturers face supply constraints for low-global-warming-potential working fluids, creating specification windows for pure electric alternatives. Commercial refurbishment projects in France and Belgium are responding by prioritizing electric underfloor systems where refrigerant-based heat distribution poses regulatory uncertainty.
Specification authority is migrating from general contractors to specialized energy consultants who model lifetime operating costs. These advisors displace traditional merchant distributor recommendations with simulation-driven product selection. The United Kingdom's retrofit sector exhibits this shift most acutely, where PAS 2035 compliance requirements mandate whole-dwelling energy assessment before heating system replacement.
Electric Underfloor Heating Market Segmentation
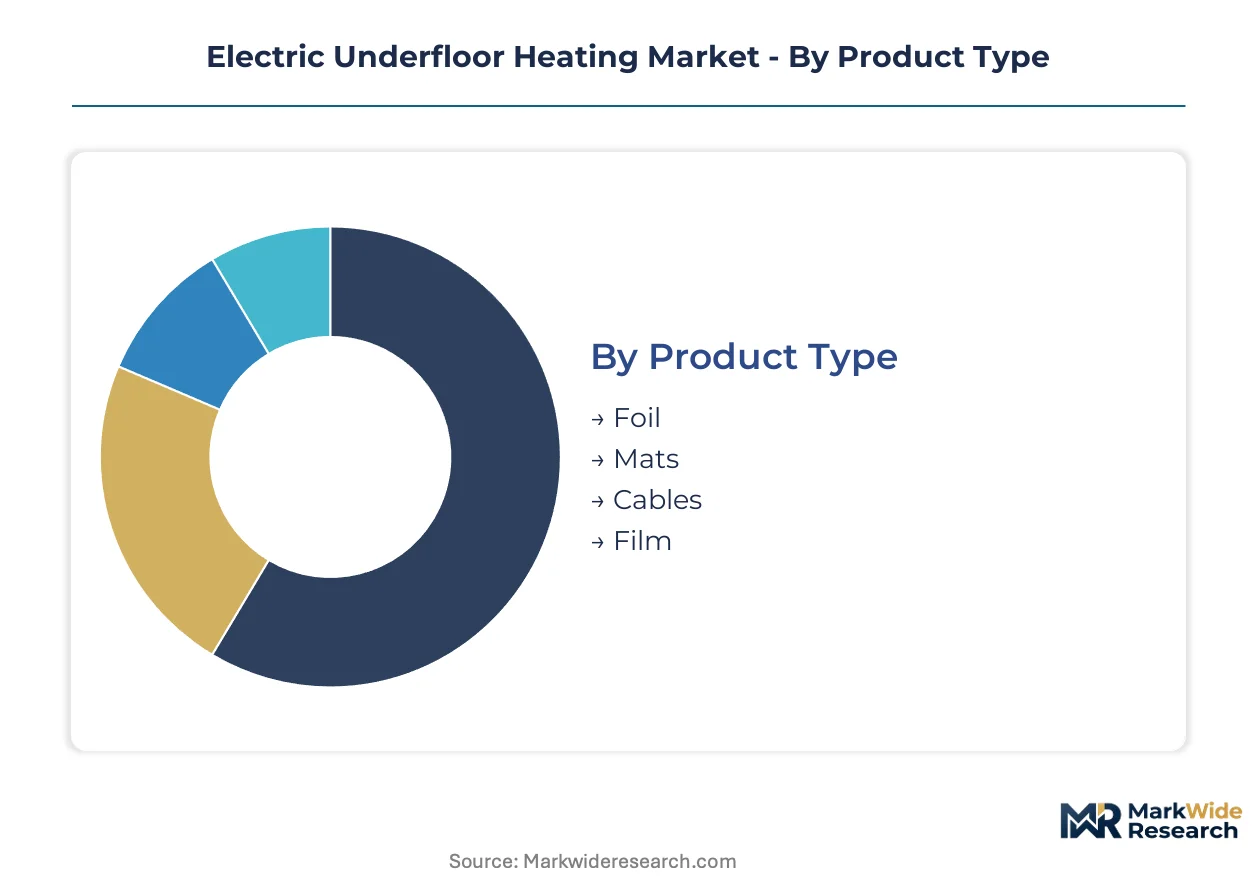
Segmentation in electric underfloor heating reveals divergent margin structures and specification pathways. Product type determines installation labor intensity, while control system selection increasingly drives total project value capture.
Product Type:
Replacement cycles vary dramatically: heating cables outlast foil systems by years, yet foil commands premium pricing in speed-sensitive renovation channels.
- Mats:Pre-spaced resistive elements bonded to mesh substrates deliver standardized thermal output across uniform floor plans. German Passivhaus-certified residential developments specify mats for predictable heat distribution where construction timelines compress installation windows.
- Cables:Loose conductor layouts enable custom spacing around architectural obstacles and varying thermal loads. United Kingdom Victorian terrace retrofits favor cables for navigating irregular floor geometries without structural modification.
- Foil:Ultra-thin aluminum laminate construction suits floating floor assemblies where build height constraints dominate specification. Scandinavian timber-frame housing applies foil systems where thermal mass is minimal and rapid response matters.
- Film:Polymer-based conductive layers integrate with laminate and engineered wood surfaces for surface-mount applications. Japanese residential refurbishment channels specify film where adhesive bonding eliminates screed requirements.
Mats anchor the volume base while smart thermostat-compatible cable systems gain share at the steepest rate.
Installation Type:
Customer acquisition costs stratify sharply: new build contractors negotiate bulk supply agreements while retrofit specialists capture margin through diagnostic and customization services.
- New Build:Large-scale residential developers specify electric underfloor heating during foundation phase, embedding mats within structural screeds before final floor finishes. France's tightening primary energy factors in new construction favor electric systems paired with solar PV.
- Renovation:Partial floor replacement scenarios demand low-profile systems that minimize height buildup. United Kingdom PAS 2035 compliance mandates drive whole-dwelling assessment before heating system replacement, elevating specification authority to energy consultants.
- Retrofit:Existing floor preservation requirements limit solution sets to ultra-thin foil and film technologies. Belgium's commercial refurbishment sector prioritizes electric underfloor where refrigerant-based heat distribution faces F-Gas Regulation uncertainty.
- Industrial:Heavy-duty cable systems withstand mechanical loading in warehouse and manufacturing environments where process heat maintenance is critical.
New Build generates the highest absolute volume while Retrofit climbs fastest as EU Green Deal renovation mandates compress replacement cycles.
End User:
Specification authority migrates differently across customer types: residential decisions consolidate with homeowners, commercial channels fragment across facilities managers and energy consultants.
- Residential:Single-family and multi-family housing dominates unit volume, with smart thermostat integration driving upgrade decisions in high-renewable grid regions like Denmark and Germany.
- Commercial:Office and retail specifications prioritize zonal control for unoccupied period setbacks, aligning with time-of-use electricity tariffs.
- Hospitality:Guest comfort requirements demand rapid thermal response and silent operation, favoring film and foil systems in boutique hotel renovations.
- Educational:Public procurement channels in France and Italy specify electric underfloor for new school construction where maintenance simplicity outweighs first-cost premiums.
Residential anchors the volume base while Commercial gains share through energy management platform integration.
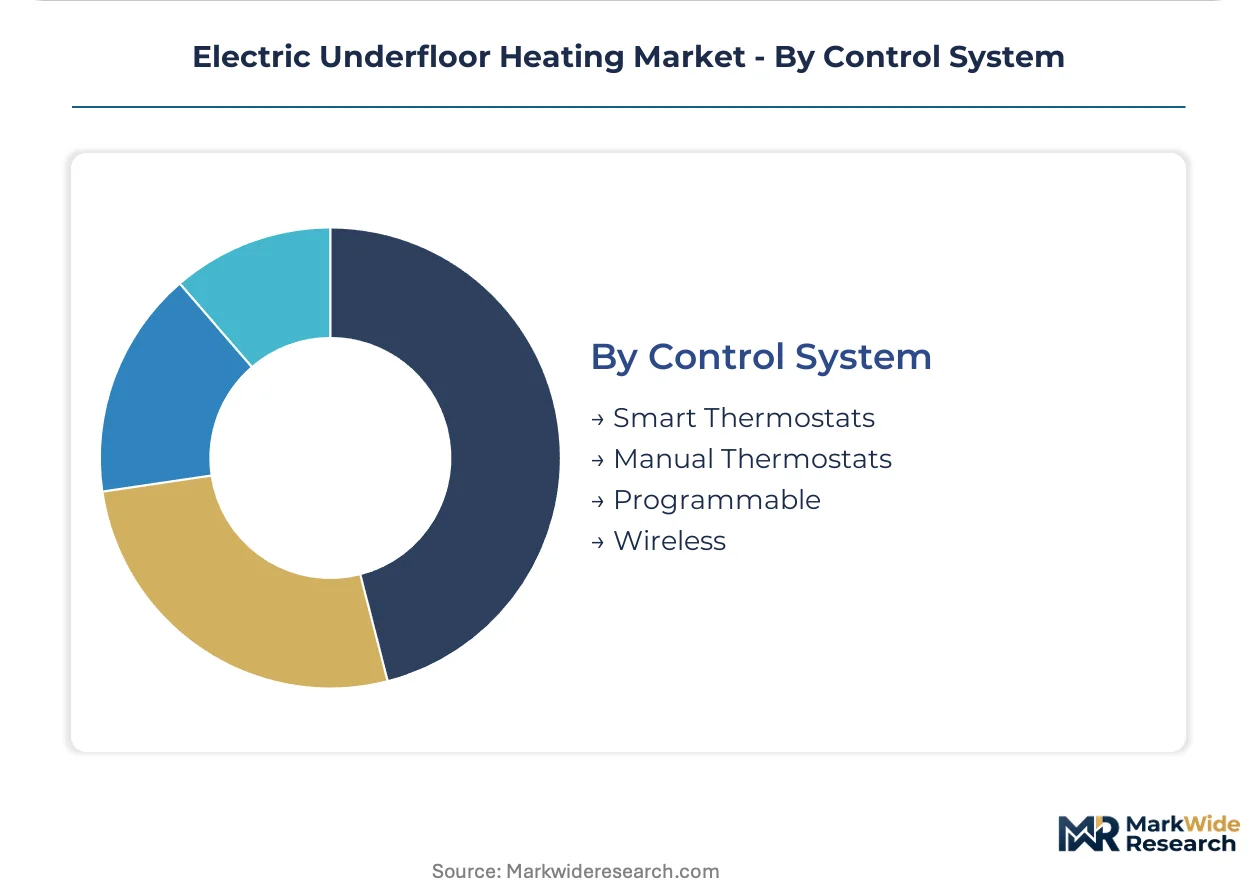
Control System:
Hardware margin pools are shifting toward software-enabled platforms as building energy codes tighten and time-of-use tariffs proliferate.
- Smart Thermostats:WiFi-enabled devices with machine learning occupancy prediction and remote scheduling displace manual units in new residential specifications. Germany's building code officials mandate programmable controls for electric heating compliance.
- Manual Thermostats:Basic dial or digital temperature setpoints persist in budget-conscious renovation segments and landlord-controlled rental housing where tenant control is restricted.
- Programmable:Time-based setback scheduling without connectivity serves commercial applications where facility management systems handle centralized optimization.
- Wireless:Battery-powered sensor networks eliminate wiring runs in solid floor constructions, gaining traction in United Kingdom solid-wall property retrofits where invasive routing is impractical.
Manual Thermostats retain residual volume in price-sensitive channels while Smart Thermostats expand most quickly through HVAC contractor specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Scandinavia accept substantial first-cost premiums for certified low-energy systems, while price sensitivity dominates specification decisions across Southern Europe and Eastern European retrofit channels.
Germany
Passivhaus-certified residential developments in Bavaria and Baden-Württemberg specify electric underfloor mats where heat pump integration proves technically challenging. The EU Green Deal's building renovation mandates accelerate fossil-fuel heating replacement under national implementation timelines. Berlin-Brandenburg housing associations are trialing solar PV-to-underfloor direct coupling for daytime heating load independence.
United Kingdom
Victorian and Edwardian terrace retrofits in Northern England and Scotland favor loose conductor cables for navigating irregular floor geometries without structural modification. PAS 2035 compliance mandates whole-dwelling energy assessment before heating system replacement, elevating specification authority to energy consultants. The Midlands retrofit corridor exhibits fastest channel growth as aging housing stock faces decarbonization deadlines.
France
Commercial refurbishment projects in Île-de-France prioritize electric underfloor systems where F-Gas Regulation uncertainty constrains refrigerant-based heat distribution. Tightening primary energy factors in new construction favor electric systems paired with rooftop solar PV. Auvergne-Rhône-Alpes educational procurement channels specify electric heating for maintenance simplicity in public school construction.
United States
The IRA's home energy rebates expand addressable demand for retrofit electric heating systems across Northeast and Pacific Coast states. Cold-climate regions with high renewable grid penetration drive smart thermostat specification for programmable load management. Texas and Florida residential builders specify mats in luxury new-build segments where construction timeline compression matters.
Belgium
Flemish commercial refurbishment channels respond to F-Gas Regulation phase-down by prioritizing electric underfloor where refrigerant-based distribution faces compliance friction. Brussels-capital renovation mandates accelerate replacement cycles for fossil-fuel systems in office and retail stock. Walloon industrial zones specify heavy-duty cable systems for warehouse process heat maintenance.
Electric Underfloor Heating Market Vendor Landscape
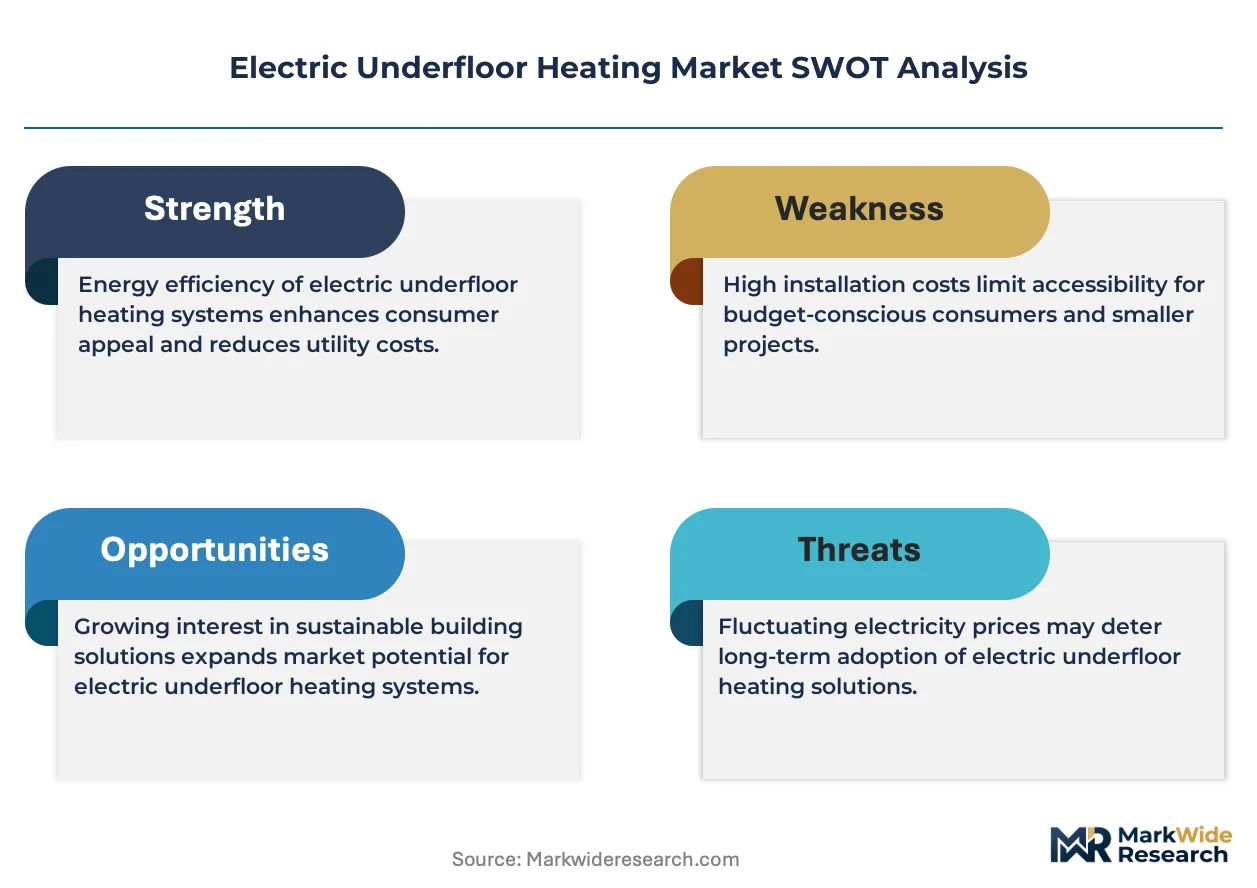
Capability concentration sits with specialized heating element designers; scale advantage sits with diversified electrical infrastructure conglomerates. The vendor base organizes around three strategic archetypes: cable and mat specialists, control system integrators, and broad-line electrical component suppliers. Dominant competitive moves include backward integration into polymer insulation compounding and geographic expansion through HVAC contractor channel partnerships.
Within the specialized heating element tier, nVent Electric plc and Warmup plc exemplify divergent geographic anchoring strategies. nVent occupies a position reflecting North American electrical infrastructure heritage, while Warmup sits within United Kingdom-centric residential renovation specialization. Danfoss Group represents the control system integration archetype, competing on energy management platform capabilities rather than heating element commodity supply. These three anchors illustrate how specification authority migration toward energy consultants favors players with software-enabled platform offerings over pure hardware fabricators.
| Leading Market Players |
|---|
| nVent Electric plc |
| Warmup plc |
| Resideo Technologies Inc. |
| Rehau Ltd |
| Danfoss Group |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Siemens AG |
| ThermoSoft International Corp. |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors concentrate polymer insulation compound shipments from German chemical producers to cable extrusion plants across the Benelux, with container rate volatility feeding directly into manufacturer margin structures and downstream tiered pricing for heating element distributors.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers now drive lifetime value capture for manufacturers competing beyond commodity heating element supply. Three-tier pricing structure across premium certified, standard compliance-grade, and economy unbranded levels separates nVent Electric's commercial-grade cable systems from Warmup's specialized mat offerings and unlabeled import alternatives. Cost compression in economy foil segments is intensifying because Chinese polymer film producers are expanding European distribution partnerships. Residential renovation contractors in the United Kingdom exhibit highest price sensitivity, while German Passivhaus developers accept substantial first-cost premiums for certified low-energy system integration.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates raw material cost planning for resistive element manufacturers sourcing polymer sheathing compounds. Supply concentration rests on Germany and Belgium for advanced insulation compounding, China for copper conductor drawing, and South Korea for self-regulating polymer composite formulations. Critical dependencies include London Metal Exchange copper cathode, fluoropolymer insulation resins, and aluminum laminate substrates for ultra-thin foil construction. Single-source vulnerability in specialized polymer formulations creates procurement risk for self-regulating cable producers. Distribution runs through electrical wholesale distributors serving HVAC contractor channels, with direct specification authority migrating toward energy consultants in retrofit-dominant markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric underfloor heating sits in early-cycle expansion as EU Green Deal renovation mandates compress replacement timelines for fossil-fuel systems and elevate specification of electric alternatives in residential decarbonization programs.
For Market Incumbents: Insulate core cable and mat franchises through backward integration into polymer insulation compounding, capturing margin from volatile resin supply chains. Prioritize certification investment for CE marking and Passivhaus compatibility to defend against emerging control system integrators like Danfoss Group that compete on energy management platforms rather than heating element commodity supply.
For New Entrants and Emerging Players: Build out wireless sensor network capabilities for solid-floor retrofit applications where invasive wiring runs prove impractical, targeting United Kingdom Victorian terrace channels where PAS 2035 compliance mandates elevate specification authority to energy consultants. Solar PV-to-underfloor direct coupling represents the most penetrable white-space application for daytime heating load independence.
For Investors and Strategic Acquirers: Control system specialists with home energy management platform capabilities offer the most attractive acquisition profile for capturing specification authority migration away from pure hardware fabricators. Long-term viability hinges on software-enabled recurring revenue models displacing transactional heating element sales. Watch for heat pump coexistence rule implementations across EU member states as the critical inflection signal for pure electric underfloor positioning against hybrid system alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captures margin from volatile resin supply chains serving German cable extrusion plants. |
| Smart Thermostat Platform Integration | Opens HVAC contractor specification channels previously closed to heating element suppliers. |
| Solar PV Direct Coupling Development | Eliminates grid dependency for daytime heating loads in German residential applications. |
| Wireless Sensor Network Expansion | Addresses United Kingdom solid-wall property retrofits where invasive routing is impractical. |
| Passivhaus Certification Investment | Secures specification in Bavarian net-zero housing developments where heat pump integration fails. |
Methodological Framework
Initial hypotheses were tested against primary input from electrical contractors, HVAC system integrators, energy consultants, and polymer compound procurement managers, then refined through secondary validation against EU Green Deal implementation timelines, F-Gas Regulation compliance databases, and London Metal Exchange copper price series. Bottom-up unit economics from installation project data combined with top-down construction spending forecasts to triangulate market sizing across product type, installation category, and control system segments.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation dimensions spanning product type (mats, cables, foil, film), installation category (new build, renovation, retrofit, industrial), end user (residential, commercial, hospitality, educational), and control system sophistication (manual, programmable, smart, wireless). CAGRs were derived from fitted growth curves incorporating EU building renovation mandate implementation schedules, IRA home energy rebate uptake trajectories, and copper price elasticity assumptions for resistive element demand.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese foil producers or accelerated heat pump subsidy programs would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Thermo Ventilators Market
HVAC Equipment
Kitchen Hood Market
HVAC Equipment
HVAC Air Handling Units Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
North America Industrial Air Chiller Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
United Kingdom Heat Pumps Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Global HVAC Linesets Market