
 Water Softener Equipment Market | 2026-2036
Water Softener Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Water Softener Equipment Market Insights
NSF/ANSI 44 certification tier is bifurcating the competitive landscape into specification-grade and basic-installation suppliers. Pentair PLC leverages its captive resin manufacturing to control input costs across North American distribution channels. Culligan International Company anchors its position through franchise-operated service networks that sustain recurring revenue from salt delivery and cartridge replacement cycles.
Water softener equipment comprises vessels, control valves, and ion-exchange resin media engineered to reduce calcium and magnesium ion concentrations below 60 mg/L as CaCO3 equivalent, primarily protecting plumbing infrastructure and improving detergent efficiency in commercial and residential settings. Salt-based softeners dominate installed base volumes while salt-free alternatives capture margin pools in environmentally restricted municipalities. Reverse osmosis technology segments compete alongside electrodialysis in process water applications where boiler feed specifications require near-zero hardness.
EPA secondary drinking water guidelines and NSF/ANSI 44 certification frameworks shape product design thresholds and market access conditions for equipment sold into US municipal and residential channels. The EU F-Gas Regulation and REACH chemical restrictions constrain resin chemistry choices and brine disposal protocols for European manufacturers. Stakeholders must monitor evolving state-level plumbing codes and resin disposal regulations to anticipate certification burden shifts and channel eligibility requirements.
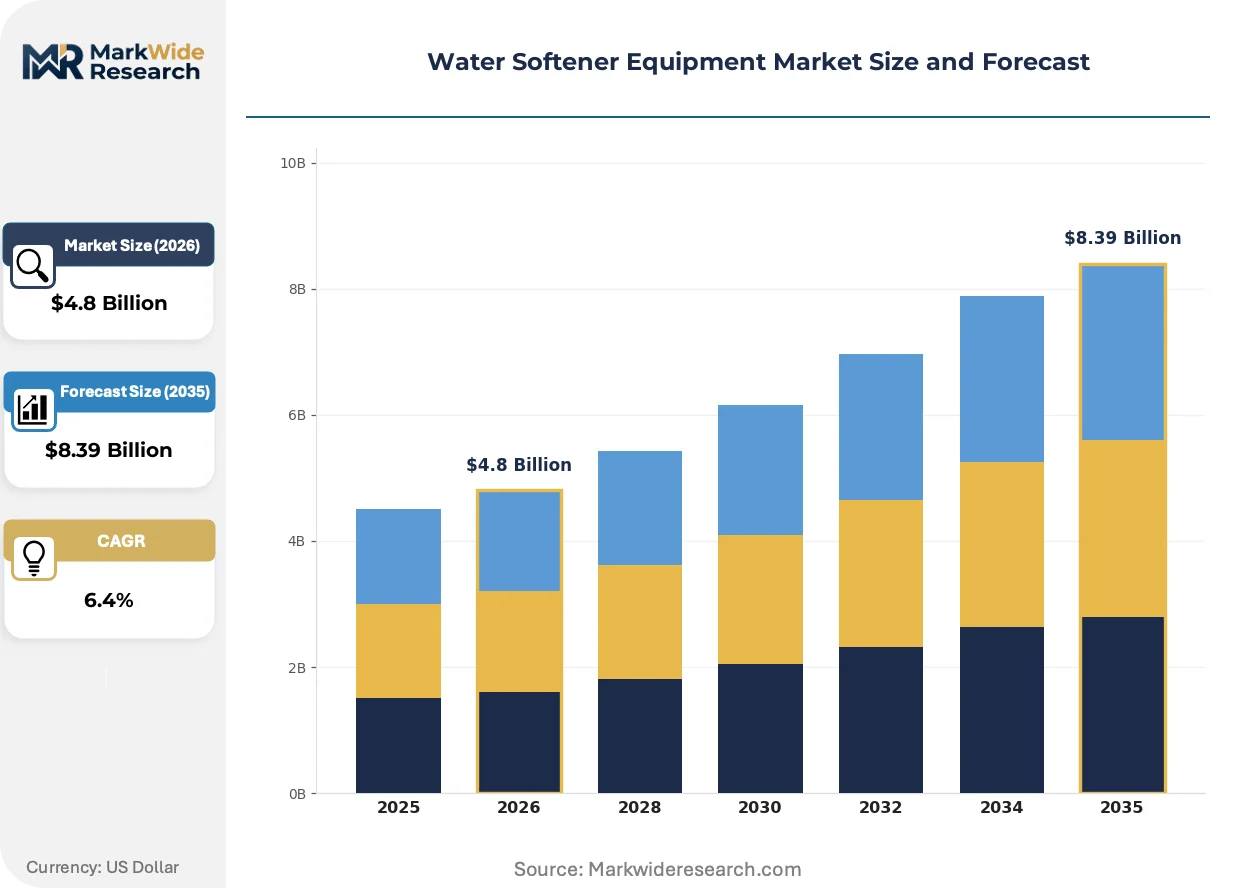
Market Dynamics
The water softener equipment sector is bifurcating around certification tier, with NSF/ANSI 44 specification-grade systems commanding premium positioning while basic-installation units compete on upfront cost. This structural tension between performance standards and price accessibility is reshaping manufacturer R&D allocation and channel strategy.
Growth Catalysts
- EPA Secondary Standards Compliance:Municipal water treatment authorities across the United States are expanding ionic exchange system procurement to meet federal hardness guidelines, creating specification-grade demand pull.
- ECHA Chemical Restrictions:Germany's regulatory environment favors salt-free softener adoption, converging with consumer preference for maintenance-free residential appliances.
- Boiler Feed Water Specifications:Industrial process water applications requiring near-zero hardness are expanding electrodialysis and reverse osmosis integration alongside conventional softening.
Market Restraints
- Resin Chemistry Constraints:EU REACH regulations and F-Gas Regulation limit formulation options for European manufacturers, compressing margin pools on salt-based systems.
- Brine Disposal Friction:Municipal wastewater authorities in water-stressed regions are restricting chloride discharge, raising operational costs for regeneration-based softeners.
- Input Cost Volatility:Specialty ion-exchange resin prices fluctuate with petrochemical feedstock cycles, exposing mid-tier suppliers to margin compression.
Strategic Opportunities
- Underpenetrated Rural Municipalities:Small-scale water districts in the United States lack centralized softening infrastructure, creating distributed system deployment potential.
- Smart Home Integration:IoT-enabled softeners with predictive maintenance alerts and automated salt reordering are capturing premium residential segments.
- Commercial Laundry Vertical:On-premise laundry operations in hospitality and healthcare are specifying high-capacity continuous-flow systems to reduce detergent consumption and linen replacement rates.
Industry Challenges
- NSF/ANSI 44 Certification Timelines:Third-party validation cycles for new resin formulations extend 18-24 months, delaying product launches and freezing development roadmaps.
- Service Network Density Requirements:Franchise-operated salt delivery and cartridge replacement models demand localized inventory positioning, constraining geographic expansion speed for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Softener Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt-based Softener, Salt-free Softener, Dual-tank Softener, Magnetic Softener Technology: Ionic Exchange, Reverse Osmosis, Electrodialysis, Nano-filtration End User: Residential, Commercial, Industrial, Agricultural Application: Water Treatment, Residential Use, Process Water, Boiler Feed Water |
| Companies Covered | A.O. Smith Corporation, Whirlpool Corporation, Culligan International Company, Leaf Home Water Solutions, Fleck Systems, Kinetico Incorporated, Pentair PLC, SpringWell Water Systems, EcoWater Systems LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Softener Equipment Market Trends and Innovations
Equipment miniaturization and digital connectivity are converging to redefine residential softener form factors and service models. These shifts are compressing installation footprints while expanding remote monitoring capabilities across both municipal and consumer channels.
Template-assisted crystallization technology is miniaturizing salt-free softener designs for point-of-entry residential installations. Single-family homeowners in German and Benelux markets are adopting these systems at accelerating rates. The technology is miniaturizing equipment footprints from cabinet-sized units to under-sink configurations, enabling penetration of space-constrained urban housing stock.
REACH chemical authorization procedures are forcing resin manufacturers to reformulate crosslinked polystyrene matrices ahead of sunset dates for legacy chemistries. Industrial softener OEMs face reformulation validation costs and supply continuity risks. Specification-grade equipment destined for European municipal tenders is most affected, with procurement specifications beginning to require pre-certified alternative resin sources.
Subscription-based salt delivery and maintenance bundling is displacing transactional equipment sales in North American residential channels. Big-box retailers and direct-to-consumer platforms are losing share to vertically integrated service networks. This pattern is most visible in suburban United States markets where franchise operators have achieved route density economies.
Water Softener Equipment Market Segmentation
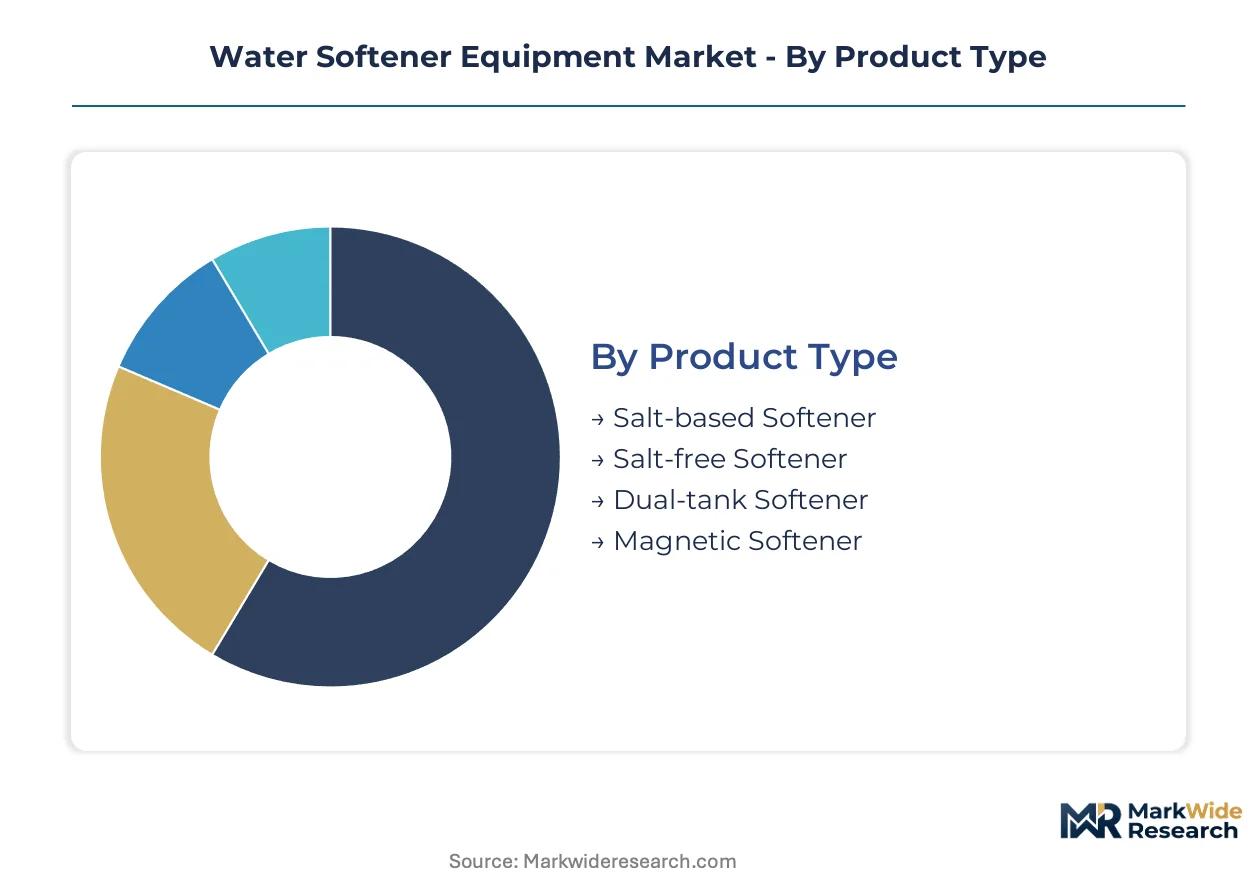
Equipment classification in water softening determines certification requirements, channel access, and service model economics. Segment boundaries increasingly blur as hybrid systems combine salt-free pretreatment with ionic exchange polishing for regulatory compliance.
Product Type:
Salt-based softeners dominate North American municipal procurement, while salt-free alternatives concentrate in European residential markets restricted by chemical discharge regulations.
- Salt-based Softener:Ion-exchange resin vessels regenerate with sodium chloride brine to remove calcium and magnesium ions below 60 mg/L as CaCO3 equivalent. Municipal water treatment authorities in the United States specify these systems for EPA secondary standard compliance, driving specification-grade procurement volumes.
- Salt-free Softener:Template-assisted crystallization and electromagnetic technologies condition water without chemical discharge. German homeowners under ECHA chemical restrictions favor these maintenance-free appliances for point-of-entry urban installations.
- Dual-tank Softener:Continuous-flow designs alternate regeneration cycles for commercial laundry and hospitality operations requiring uninterrupted soft water supply.
- Magnetic Softener:Coil-based electromagnetic field systems target scale prevention in agricultural irrigation and light commercial applications with lower hardness reduction requirements.
Salt-based softeners hold the largest share; momentum sits with salt-free alternatives gaining share fastest in restricted municipalities.
Technology:
Cost tier stratification separates capital-intensive membrane systems from lower-first-cost resin exchange, with application hardness specifications determining technology selection.
- Ionic Exchange:Crosslinked polystyrene resin beads capture hardness ions through reversible sodium exchange. Industrial boiler feed applications in process water facilities demand these systems for near-zero hardness specifications.
- Reverse Osmosis:Semi-permeable membranes reject dissolved solids including hardness ions alongside other contaminants. Semiconductor and pharmaceutical manufacturing facilities specify RO for ultrapure water production.
- Electrodialysis:Ion-selective membranes and electrical potential separate charged species. Food and beverage processing plants deploy electrodialysis for partial demineralization without full desalination.
- Nano-filtration:Porous membranes target divalent ion removal while preserving monovalent salts. Agricultural water reuse applications favor nano-filtration for selective hardness reduction without sodium addition.
Ionic exchange commands the dominant installed base; reverse osmosis is climbing the fastest in precision manufacturing verticals.
End User:
Customer type determines equipment scale, service intensity, and purchasing channel, with industrial buyers demanding continuous-flow designs and residential segments favoring compact cabinet units.
- Residential:Single-family and multi-family installations prioritize space efficiency and automated regeneration. Subscription salt delivery models are displacing transactional sales in suburban United States markets.
- Commercial:On-premise laundry, hospitality, and healthcare operations specify high-capacity systems to reduce detergent consumption and linen replacement rates.
- Industrial:Power generation and chemical processing facilities require continuous softening for boiler feed and cooling tower makeup water.
- Agricultural:Irrigation system protection drives demand for scale prevention in hard water regions without potable water treatment requirements.
Residential generates the highest unit volumes; industrial applications show the steepest expansion trajectory in process water specifications.
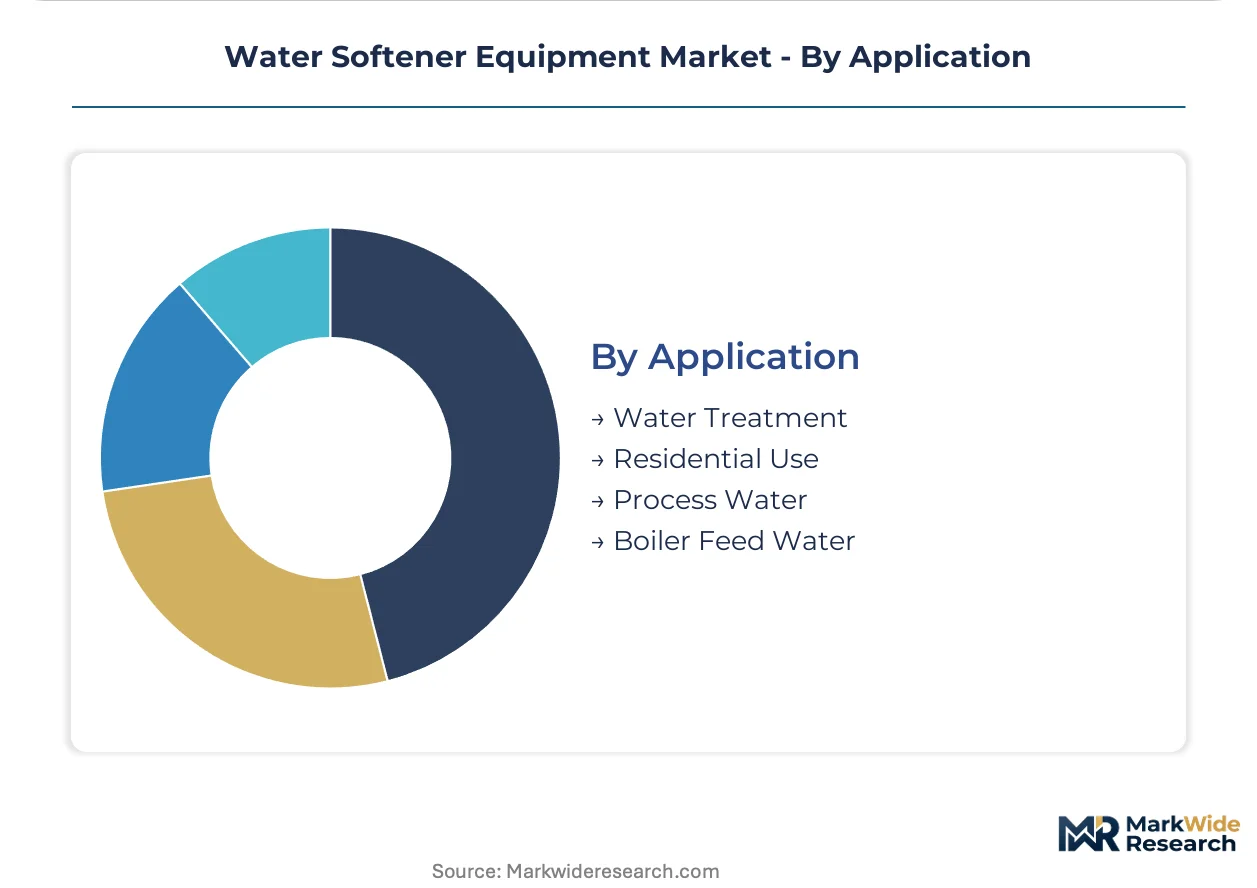
Application:
Application specificity determines performance certification tier, with municipal and boiler feed applications demanding NSF/ANSI 44 specification-grade validation.
- Water Treatment:Centralized municipal softening facilities serve distribution networks for entire communities. Small-scale water districts in underpenetrated rural United States municipalities represent distributed deployment potential.
- Residential Use:Point-of-entry whole-house systems protect plumbing infrastructure and improve appliance efficiency. German and Benelux urban housing stock drives miniaturization toward under-sink configurations.
- Process Water:Manufacturing facilities require consistent water chemistry for product quality and equipment protection. REACH chemical authorization procedures force resin reformulation ahead of sunset dates for European OEMs.
- Boiler Feed Water:Near-zero hardness specifications prevent scale formation and thermal efficiency losses in high-pressure steam systems. Electrodialysis and reverse osmosis integration competes alongside conventional softening in this specification tier.
Water treatment holds the largest installed base; process water applications are gaining share fastest in manufacturing reshoring initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in water softener equipment tilt toward net-importing industrial economies, with Germany and the United States absorbing the highest absolute volumes of ion-exchange resin vessels and control valve assemblies. Manufacturing concentration in lower-cost European and Asian supply bases feeds this import dependency.
United States
Municipal water districts in Texas and Arizona are expanding ionic exchange procurement to meet EPA secondary drinking water standards for hardness reduction. The EPA's non-mandatory guidelines nonetheless drive specification-grade tendering across southwestern states. Phoenix and Dallas-Fort Worth metropolitan clusters concentrate demand for high-capacity continuous-flow systems serving rapid suburban expansion.
Germany
Residential salt-free softener installations are accelerating in Berlin and Hamburg urban housing stock under ECHA chemical restrictions on brine discharge. REACH authorization procedures force resin manufacturers toward reformulated crosslinked polystyrene matrices. Bavaria's industrial corridor around Munich maintains demand for process-grade ion-exchange systems in precision manufacturing facilities.
China
Power generation and chemical processing facilities in the Yangtze River Delta specify continuous softening for boiler feed applications. MEE discharge standards tighten chloride emission limits, pressuring regeneration-based system operators. Shanghai and Jiangsu province industrial clusters drive specification-grade procurement volumes for near-zero hardness process water.
India
Commercial laundry operations in Mumbai and Delhi-NCR are specifying high-capacity softeners to reduce detergent consumption and linen replacement rates. BIS certification requirements for water treatment equipment create compliance thresholds for imported systems. Gujarat's textile processing belt generates concentrated demand for industrial-scale ion-exchange installations.
Japan
Semiconductor fabrication facilities in Kyushu and the Kanto region integrate reverse osmosis alongside conventional softening for ultrapure water production. METI efficiency standards for industrial water use push facilities toward combined membrane-resin systems. Osaka-Kobe manufacturing clusters anchor demand for precision process water equipment.
Water Softener Equipment Market Competitive Landscape
Listed leaders compete with private specialists across franchise-operated service networks, creating a bifurcated structure where specification-grade certification separates premium positioning from basic-installation price competition. The vendor base stratifies around captive resin manufacturing, vertically integrated salt delivery logistics, and digital subscription platforms. Three archetypes dominate: multinational diversified industrials with captive supply chains, franchise-network service operators with recurring revenue models, and direct-to-consumer specialists leveraging e-commerce channels. Consolidation pressure favors M&A activity around regional service density, while technology licensing agreements accelerate smart-connected feature deployment.
Among North American diversified industrials, A.O. Smith Corporation and Whirlpool Corporation exemplify the scale-driven archetype with appliance-channel leverage and captive distribution networks. Pentair PLC anchors the specification-grade tier through upstream control over resin manufacturing inputs. Culligan International Company occupies a distinct position within franchise-operated service models, its route-density economics in salt delivery and cartridge replacement cycles representing a recurring-revenue archetype that subscription bundling has reinforced.
| Leading Market Players |
|---|
| A.O. Smith Corporation |
| Whirlpool Corporation |
| Culligan International Company |
| Leaf Home Water Solutions |
| Fleck Systems |
| Kinetico Incorporated |
| Pentair PLC |
| SpringWell Water Systems |
| EcoWater Systems LLC |
| Others |
Pricing and Supply Chain Analysis
NSF/ANSI 44 certification gates both supply qualification and price differentiation simultaneously, separating specification-grade resin manufacturers from basic-installation assemblers while compressing margin pools for uncertified entrants. Municipal procurement officers in the United States pay premiums for validated systems, whereas residential channels fragment across subscription-bundled service models and transactional hardware sales.
Pricing Analysis
Industrial OEM buyers anchor pricing structure around three-tier certification grades across premium specification-grade, standard commercial, and economy residential tiers. Price differentiation rests on NSF/ANSI 44 validation status and captive resin manufacturing, with specification-grade systems commanding substantial premiums over basic-installation alternatives. Cost compression in economy tiers is intensifying because mid-tier suppliers face petrochemical feedstock volatility without backward integration into resin production. Residential subscribers show lowest price sensitivity due to bundled salt delivery convenience, while municipal procurement teams negotiate aggressively on volume tenders.
Supply Chain Analysis
Specialty ion-exchange resin production concentrates in Germany, China, and the United States as the primary manufacturing clusters for crosslinked polystyrene matrices. Raw material dependencies include styrene monomer, divinylbenzene crosslinkers, and sulfonation reagents sourced from petrochemical feedstocks. Supply chain risk centers on REACH chemical authorization timelines that force reformulation validation cycles extending eighteen to twenty-four months. Distribution runs through franchise-operated service networks for salt delivery logistics alongside direct OEM channels for municipal specification-grade tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water softener equipment functions fundamentally as a service-attach opportunity where subscription salt delivery and predictive maintenance layers expand faster than standalone hardware transactions. Recurring revenue from cartridge replacement cycles and automated reordering platforms now outpaces equipment margin capture in mature North American markets.
For Market Incumbents: Consolidate route density in suburban United States markets where franchise salt delivery networks achieve logistics economies that new entrants cannot replicate. Acquire regional service operators to deepen control over aftermarket parts flows. Salt-free template-assisted crystallization substitutes threaten ion-exchange incumbents in ECHA-restricted European municipalities.
For New Entrants and Emerging Players: Rural municipal water districts in the southwestern United States represent underserved specification-grade demand where incumbent service density remains thin. Target small-scale water authorities lacking centralized softening infrastructure with distributed ion-exchange system deployments. Pursue direct municipal tendering bypassing franchise network gatekeepers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across salt-free softener manufacturing as template-assisted crystallization miniaturization reduces resin chemistry dependencies. Long-term viability favors asset-light service platforms over captive resin production over the coming decade. Acquisition targets should exhibit dense route economics in salt logistics or IoT-enabled predictive maintenance capabilities. Watch NSF/ANSI 44 certification backlog durations as the inflection signal for specification-grade supply constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Manufacturing | Pentair PLC's captive polystyrene production shields input costs from petrochemical volatility across North American channels. |
| Smart Home Platform Integration | IoT-enabled predictive maintenance alerts capture premium residential segments through automated salt reordering interfaces. |
| Franchise Network Expansion | Culligan International Company's route-density economics in salt delivery sustain recurring revenue moats against transactional competitors. |
| REACH-Compliant Resin Reformulation | European OEMs face eighteen-to-twenty-four month validation cycles ahead of legacy chemistry sunset dates. |
| Municipal Tender Pre-qualification | EPA secondary standard compliance creates specification-grade procurement barriers for uncertified equipment suppliers. |
Research Methodology
Operator-level perspectives from municipal water treatment engineers, franchise service network operators, resin manufacturing plant managers, and commercial laundry facility maintenance directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EPA enforcement databases, NSF certification registries, ECHA authorization timelines, and customs trade flow records. Bottom-up equipment shipment tracking triangulated against top-down municipal procurement budget allocations across the analysis window.
Sensitivity analysis tested forecast robustness across resin price volatility scenarios and regulatory delay assumptions throughout the projection horizon. Segmentation dimensions modeled include product type, technology category, end-user vertical, application specificity, and geographic regulatory cluster. CAGRs derived from equipment unit economics and service revenue attach rates, with inputs calibrated to ion-exchange capacity utilization and salt consumption intensity metrics.
Forecasts assume regulatory continuity in EPA secondary standards and REACH chemical authorization procedures; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as ECHA sunset date enforcement and state-level brine discharge restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Commercial HVAC Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Europe Heating Radiator Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
High Pressure Heat Exchanger Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Europe Commercial HVAC Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
South America Screw Compressor Market
HVAC Equipment
Europe Bus HVAC Market