
 Equipment for HVAC Market | 2026-2036
Equipment for HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Equipment for HVAC Market Analysis
Aftermarket service revenue is rewriting profit allocation across the equipment value chain. Daikin Industries leverages its captive parts network to capture recurring maintenance streams. Carrier Global anchors North American service contracts through its digital monitoring platform. Trane Technologies differentiates via predictive analytics bundled with extended equipment warranties.
Equipment for HVAC encompasses mechanical systems designed to regulate indoor temperature, humidity, and air quality through vapor-compression refrigeration cycles, heat exchange coils, and forced-air distribution networks rated by Seasonal Energy Efficiency Ratio and Heating Seasonal Performance Factor metrics. These systems serve commercial, industrial, and residential buildings where thermal comfort, ventilation control, and energy compliance intersect. Smart HVAC technology is capturing premium pricing as building automation integration becomes standard specification. Variable Refrigerant Flow systems are expanding fastest in mid-rise commercial applications where zonal control reduces operational waste. Traditional HVAC remains the volume base across price-sensitive residential markets.
EPA refrigerant regulations under the AIM Act are mandating transition from hydrofluorocarbon-based systems to lower-global-warming-potential alternatives, forcing manufacturers to redesign compressor architectures and retool production lines. DOE appliance efficiency standards are tightening minimum performance thresholds for air conditioners and heat pumps sold in the United States. Stakeholders must monitor refrigerant supply chain readiness and certification capacity as compliance deadlines compress product development cycles.
Market Dynamics
EPA refrigerant phase-down mandates under the AIM Act are compressing product development cycles and forcing compressor architecture redesigns across manufacturer portfolios. Commercial building retrofits are simultaneously accelerating replacement demand as aging infrastructure faces dual pressure from efficiency standards and environmental compliance.
Growth Catalysts
- AIM Act Refrigerant Mandates:The EPA's hydrofluorocarbon phase-down is compelling building owners to replace end-of-life equipment ahead of schedule, pulling forward replacement demand into the current analysis window.
- Urbanization in China:Centralized climate infrastructure investment is concentrating equipment procurement as municipal governments prioritize district heating and cooling networks in rapidly densifying metropolitan corridors.
- Variable Refrigerant Flow Technology:Zonal control capabilities are capturing specification share in mid-rise commercial applications where energy waste reduction drives procurement decisions.
Market Restraints
- Copper and Aluminum Input Volatility:Heat exchange coil manufacturing faces margin pressure from base metal price swings that compress equipment pricing flexibility.
- Specialized Compressor Supply Concentration:Production of low-global-warming-potential refrigerant-compatible compressors clusters among a limited supplier base, creating bottleneck risk.
- Heat Pump Performance Limitations:Vapor-compression cycles experience efficiency degradation in sub-freezing ambient conditions, restricting deployment latitude in cold climate zones.
Strategic Opportunities
- India Building Stock Expansion:Commercial and residential construction growth is creating first-mover positioning for equipment vendors establishing local assembly and service infrastructure.
- Building Automation Convergence:Integration between HVAC controls and energy management platforms is opening specification channels through master system integrators rather than traditional mechanical contractors.
- DOE Efficiency Standard Escalation:Tightening Seasonal Energy Efficiency Ratio thresholds are advantaging manufacturers with advanced heat exchanger designs and variable-speed compressor portfolios.
Industry Challenges
- Refrigerant Handling Certification Bottlenecks:Technician training capacity for A2L and A3 refrigerant safety protocols is lagging equipment rollout schedules, constraining installation throughput.
- Legacy Control System Integration:Proprietary building automation protocols from incumbent vendors create interoperability friction for smart HVAC retrofits in existing commercial properties.
- Production Line Retooling Intensity:Manufacturer capital allocation for low-global-warming-potential product transitions is diverting resources from adjacent technology development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equipment for HVAC Market |
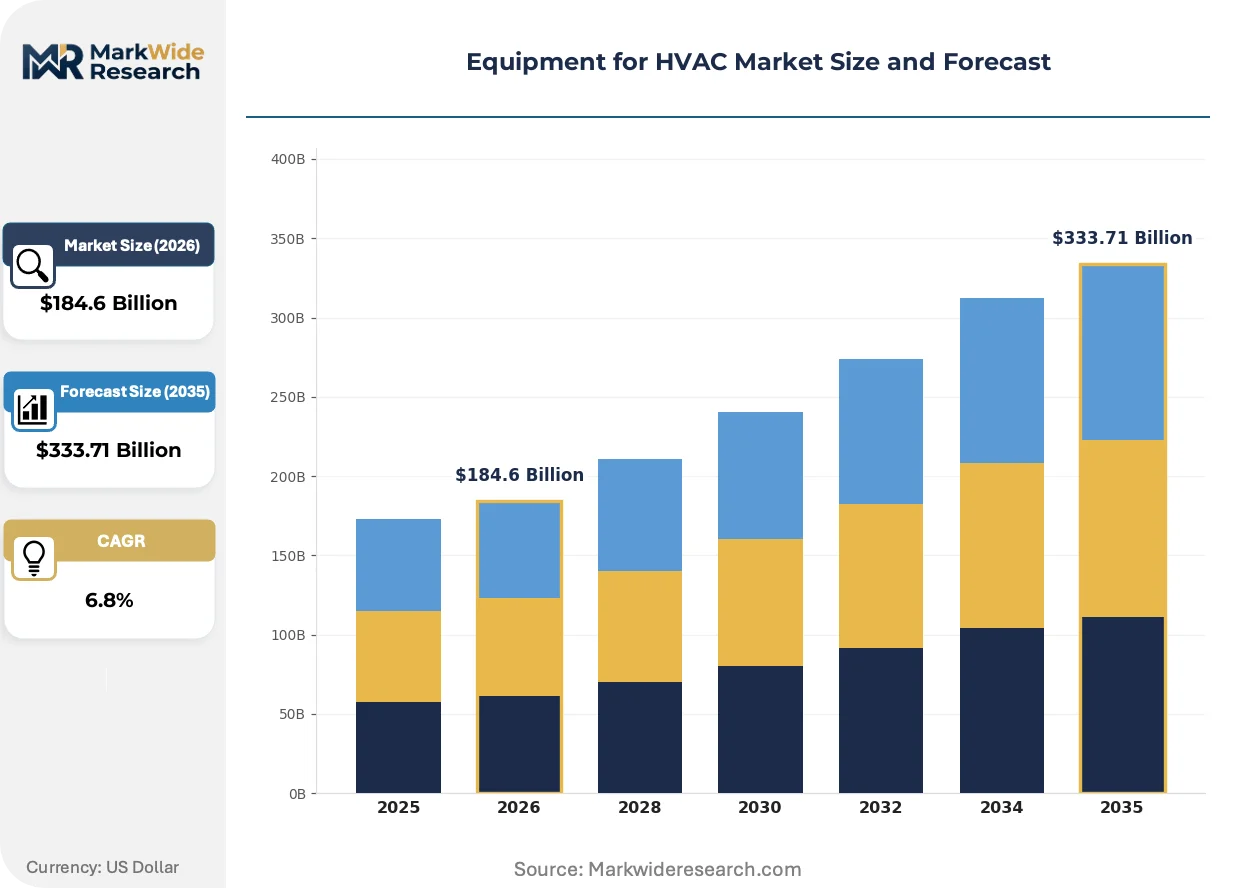
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $333.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioners, Heaters, Thermostats, Ventilation Systems Installation Type: Rooftop Units, Split Systems, Packaged Units, Ductless Systems Technology: Smart HVAC, Traditional HVAC, Energy Efficient, Variable Refrigerant Flow End User: Residential, Commercial, Industrial, Institutional |
| Companies Covered | Daikin Industries, Carrier Global, Trane Technologies, Johnson Controls, Gree Electric Appliances, Mitsubishi Electric, LG Electronics, Lennox International, Midea Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equipment for HVAC Market Emerging Trajectories
Equipment specification is pivoting from standalone thermal performance to integrated building system intelligence. Three concurrent developments are compressing traditional competitive advantages and opening new value capture mechanisms across the value chain.
Magnetic-bearing centrifugal chillers are collapsing maintenance cost structures in large commercial installations. Facility managers in healthcare and data center verticals are specifying oil-free compressor technology to eliminate bearing wear and extend service intervals. The technology is collapsing the traditional 20-year equipment replacement cycle by enabling predictive maintenance models that defer capital expenditure.
The EU F-Gas Regulation is accelerating refrigerant transition timelines beyond EPA mandates, creating asynchronous compliance requirements for multinational manufacturers. Equipment portfolios must now satisfy divergent hydrofluorocarbon phase-down schedules across Atlantic markets. European commercial refrigeration and commercial HVAC segments are responding by consolidating procurement specifications around natural refrigerant architectures that satisfy both regulatory regimes.
Performance contracting is displacing capital purchase models in municipal and institutional building portfolios. Energy service companies are capturing equipment specification authority by guaranteeing thermal output per square meter rather than selling hardware. This shift is most visible in German and French public sector retrofits where budget constraints favor operational expenditure treatment over balance-sheet equipment ownership.
Equipment for HVAC Market Segmentation
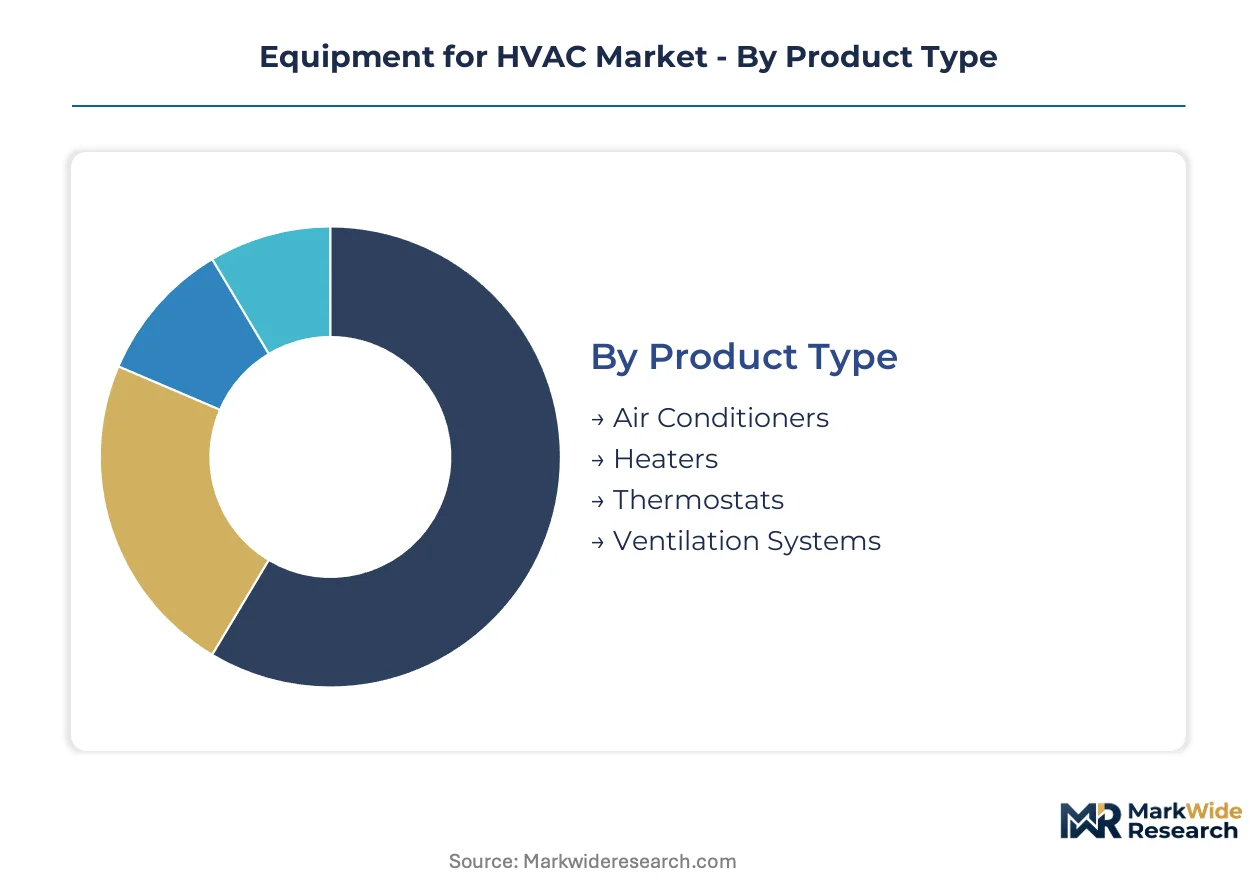
HVAC equipment segmentation reveals divergent maturity curves across product architectures and installation methods. Technology tiers and end-user requirements are compressing traditional category boundaries as efficiency mandates and building automation reshape procurement criteria.
Product Type:
Mature categories anchor volume while emerging configurations capture specification shifts driven by refrigerant transitions and zonal control demand.
- Air Conditioners:Vapor-compression systems rated by Seasonal Energy Efficiency Ratio dominate replacement cycles in residential and light commercial buildings. DOE efficiency standard escalations are pulling forward upgrade demand as legacy R-410A equipment faces obsolescence under AIM Act phase-down schedules.
- Heaters:Gas-fired furnaces and electric heat pumps serve distinct climate zones with diverging infrastructure dependencies. Cold-climate heat pump deployments are accelerating in US Northeast and Upper Midwest markets where utility rebate programs offset first-cost premiums.
- Thermostats:Programmable and connected climate controllers integrate with building automation platforms.
- Ventilation Systems:Energy recovery ventilators and dedicated outdoor air systems address indoor air quality compliance.
Air Conditioners retain volume leadership; Variable Refrigerant Flow holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates capital-intensive centralized systems from distributed architectures serving retrofit-constrained buildings.
- Rooftop Units:Packaged air handlers and condensing units consolidate heating, cooling, and ventilation in single curb-mounted enclosures. Big-box retail and suburban office verticals in the United States specify these systems for simplified maintenance access and minimized indoor mechanical room requirements.
- Split Systems:Separated evaporator and condenser coils connected by refrigerant lines enable flexible zoning without ductwork retrofit costs. Multi-family residential and small commercial installations in China and India favor this architecture for scalable capacity additions.
- Packaged Units:Self-contained systems integrate all components for rapid deployment.
- Ductless Systems:Mini-split and multi-head configurations serve buildings lacking central air distribution infrastructure.
Rooftop Units retain volume leadership; Ductless Systems are climbing the fastest.
Technology:
Application intensity varies across building automation integration levels and refrigerant compliance requirements.
- Smart HVAC:Sensor-networked systems with cloud-connected diagnostics and predictive maintenance algorithms command specification premiums. Healthcare and data center operators in Germany and Singapore prioritize these systems for uptime assurance and energy optimization.
- Variable Refrigerant Flow:Heat pump-based zonal systems modulate refrigerant flow to match real-time thermal loads. Mid-rise commercial buildings in Japan and South Korea specify VRF for simultaneous heating and cooling recovery between building zones.
- Traditional HVAC:Conventional fixed-speed compressors and electromechanical controls serve price-sensitive replacement markets.
- Energy Efficient:High-performance heat exchangers and variable-speed drives meet escalating minimum efficiency thresholds.
Traditional HVAC retains volume leadership; Smart HVAC is gaining share fastest.
End User:
Customer type determines specification authority, financing mechanisms, and service contract structures across the equipment lifecycle.
- Commercial:Office, retail, and hospitality facilities with professional facility management drive demand for predictive maintenance integration and extended warranty coverage. Property managers in France and the Netherlands are consolidating procurement around performance contracting models that transfer operational risk to equipment vendors.
- Residential:Single-family and multi-family dwellings with owner or landlord-driven purchase decisions prioritize first-cost minimization and installation speed. New construction markets in Texas and Florida specify builder-grade equipment with upgrade pathways to higher efficiency tiers.
- Industrial:Manufacturing and process facilities require specialized environmental control for equipment protection and product quality.
- Institutional:Government, education, and healthcare buildings with public funding cycles and extended ownership horizons.
Residential retains volume leadership; Commercial holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment deployment patterns diverge sharply by climate infrastructure maturity and regulatory enforcement intensity. China concentrates centralized district systems while the United States fragments across distributed rooftop architectures. European markets prioritize refrigerant compliance over capacity expansion.
China
Municipal governments in Shanghai and Beijing are procuring magnetic-bearing centrifugal chillers for healthcare and data center verticals. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate R-410A equipment phase-outs. The Yangtze River Delta manufacturing corridor supplies heat pump compressors for domestic retrofit programs and Southeast Asian export markets.
United States
Commercial building retrofits in Texas and Florida are pulling forward replacement demand ahead of EPA AIM Act deadlines. The Department of Energy tightens Seasonal Energy Efficiency Ratio thresholds for split-system air conditioners sold after 2025. Atlanta and Dallas anchor specification authority for packaged rooftop units serving big-box retail and suburban office developments.
Germany
Energy service companies capture equipment specification through performance contracting models in Frankfurt and Munich public sector buildings. The EU F-Gas Regulation mandates stricter hydrofluorocarbon phase-down schedules than EPA timelines. Bavarian industrial clusters manufacture natural refrigerant heat pumps for synchronized Atlantic market compliance.
India
Commercial construction growth in Maharashtra and Gujarat creates first-mover positioning for variable refrigerant flow systems in mid-rise developments. The Bureau of Indian Standards implements energy labeling requirements for room air conditioners. Tamil Nadu assembly plants scale production for price-sensitive residential markets across South Asia.
Japan
Mid-rise commercial buildings in Tokyo and Osaka specify simultaneous heating and cooling recovery through zonal heat pump networks. METI efficiency standards drive variable-speed compressor adoption in replacement cycles. Nagoya manufacturing bases export advanced heat exchanger technology to Australian and Southeast Asian climate zones.
Equipment for HVAC Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The equipment base consolidates around compressor architecture specialists and captive parts networks. Three archetypes dominate: integrated manufacturers controlling refrigerant-to-installation value chains, regional assemblers serving price-sensitive replacement markets, and controls specialists bundling predictive analytics with hardware. Competitive moves center on production line retooling for low-global-warming-potential transitions and backward integration into heat exchanger manufacturing.
Among Japanese- and American-anchored manufacturers, Daikin Industries, Carrier Global, and Trane Technologies occupy positions across the premium service-contract tier. These firms exemplify archetypes that capture recurring revenue through digital monitoring platforms and extended warranty structures. Their geographic distribution spans Osaka-based integrated manufacturing, Florida-anchored North American service networks, and Irish-domiciled European climate technology portfolios.
| Leading Market Players |
|---|
| Daikin Industries |
| Carrier Global |
| Trane Technologies |
| Johnson Controls |
| Gree Electric Appliances |
| Mitsubishi Electric |
| LG Electronics |
| Lennox International |
| Midea Group |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing corridor anchors global compressor production capacity, and its expansion dynamics directly determine pricing leverage for downstream equipment assemblers. Capacity additions in this cluster feed into tiered equipment pricing that separates premium magnetic-bearing chillers from standard fixed-speed units across procurement contracts.
Pricing Analysis
Long-term service contracts dominate commercial procurement, with subscription-tiered maintenance bundling commanding premiums over transactional equipment-only sales. Price differentiation rests on SEER certification tiers and captive parts network coverage, with standard-grade units facing compression from copper coil cost volatility. Institutional buyers in healthcare and data centers exhibit lowest price sensitivity due to uptime guarantee requirements, while residential replacement markets prioritize first-cost minimization above efficiency payback calculations.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for heat exchanger sourcing. Manufacturing concentrates in China, Japan, and Germany, with production drawing from copper cathode, aluminum coil, and rare-earth permanent magnet inputs. Single-source vulnerability clusters around low-global-warming-potential compressor architectures from limited qualified suppliers. Distribution runs through master system integrators and mechanical contractor networks rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat pump electrification sits as the primary substitution threat, with building electrification mandates pulling demand from gas-fired furnace incumbents who must now defend installed base through refrigerant transition readiness.
For Market Incumbents: Build captive service network moats by acquiring independent HVAC contractors in Texas and Florida metro corridors to lock in replacement cycle access. Compressor architecture backward integration into heat exchanger manufacturing reduces copper input margin exposure. Defend against emerging controls specialists by bundling predictive analytics with extended warranty coverage that ties customers to proprietary diagnostic platforms. For New Entrants and Emerging Players: Pursue white-space positioning in India's Tamil Nadu and Maharashtra commercial construction corridors where local assembly infrastructure gaps create first-mover advantage. Target mid-rise VRF specifications where incumbent coverage remains thin. Establish go-to-market partnerships with energy service companies capturing performance contracting authority in German and French public sector retrofits. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because refrigerant transition capital intensity will strand sub-scale manufacturers lacking retooling resources. Acquisition targets should display captive parts distribution networks and certified technician training capacity. Monitor A2L refrigerant handling certification throughput as the inflection signal for installation capacity constraints that advantage scaled service organizations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Manufacturing | Captive copper coil production insulates margins from LME price swings affecting competitor cost structures. |
| Certified Technician Training Program Expansion | A2L safety protocol capacity builds installation throughput moat ahead of EPA refrigerant mandate deadlines. |
| Energy Service Company Partnership | Performance contracting channel access transfers specification authority from mechanical contractors to equipment vendors. |
| Magnetic-Bearing Chiller Platform Launch | Oil-free compressor technology collapses maintenance costs for healthcare and data center verticals in Shanghai and Beijing. |
| Natural Refrigerant Architecture Development | Simultaneous EU F-Gas and EPA AIM Act compliance opens synchronized Atlantic market procurement specifications. |
Methodological Framework
The analysis maps air conditioning, heat pump, ventilation, and controls sub-sectors, each validated through facility managers, mechanical contractors, OEM procurement directors, and energy service company executives. Primary interview intelligence triangulates against EPA regulatory filings, DOE efficiency standard dockets, EU F-Gas Regulation implementation reports, and customs trade data for compressor and heat exchanger flows. Bottom-up equipment shipment tracking reconciles with top-down building construction permit analysis across the projection horizon.
Assumptions held fixed include AIM Act refrigerant phase-down schedules and DOE SEER threshold escalations, while variables tested encompass copper price trajectories and district heating policy intensity in China. Segmentation modeling spans product architecture, installation method, technology tier, and end-user type with regional regulatory cluster overlays. CAGRs derive from replacement cycle timing analysis and new construction equipment intensity ratios, with compressor supply capacity and technician certification throughput as HVAC-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in construction lending rates and municipal infrastructure bond issuance would shift the trajectory for commercial retrofit demand. Forecasts reflect assumptions about regulatory enforcement consistency and refrigerant supply chain readiness. Continuous validation against equipment shipment data and contractor backlog reports is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Canada HVAC Equipment Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
China HVAC Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Compressed Air Treatment Equipment Market
HVAC Equipment
South America Compressor Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
United States Heat Exchanger Market
HVAC Equipment
Residential Heat Pump Market