
 Industrial Dehumidifiers Market | 2026-2036
Industrial Dehumidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Dehumidifiers Market Analytics
Aftermarket service revenue is reshaping margin pools across the industrial dehumidifier value chain, pulling profitability away from pure equipment sales toward predictive maintenance contracts and remote monitoring subscriptions. Munters leverages its global service infrastructure to capture recurring revenue streams in pharmaceutical and food processing installations. Bry-Air anchors its competitive position through deep specialization in desiccant rotor technology and application engineering for lithium battery dry rooms. Dantherm Group extends its footprint across European warehousing and maritime climate control through modular product architectures.
Industrial dehumidifiers are electromechanical systems that extract moisture from process air or enclosed environments, typically achieving dew points between minus 40 degrees Celsius and plus 10 degrees Celsius depending on desiccant media or refrigeration cycle configuration; their primary purpose is to prevent corrosion, mold proliferation, and product degradation in moisture-sensitive operations. Desiccant systems dominate high-performance applications where ultra-low humidity is mandatory, while refrigerant units retain cost advantages in standard commercial and warehousing environments. Smart control technology represents the fastest-expanding segment as facilities integrate IoT-enabled humidity monitoring with building management systems to optimize energy consumption and reduce unplanned downtime.
EPA regulations on hydrofluorocarbon refrigerants and EU F-Gas phase-down schedules are forcing manufacturers to redesign cooling circuits and accelerate adoption of natural refrigerants and hybrid architectures. FDA current good manufacturing practice standards for pharmaceutical production and EMA Annex 15 guidelines on qualification and validation create compliance-driven demand for documented humidity control and calibration protocols. Stakeholders must monitor evolving refrigerant classifications and energy-efficiency benchmarking frameworks to anticipate product obsolescence risks and retrofit opportunities.
Market Dynamics
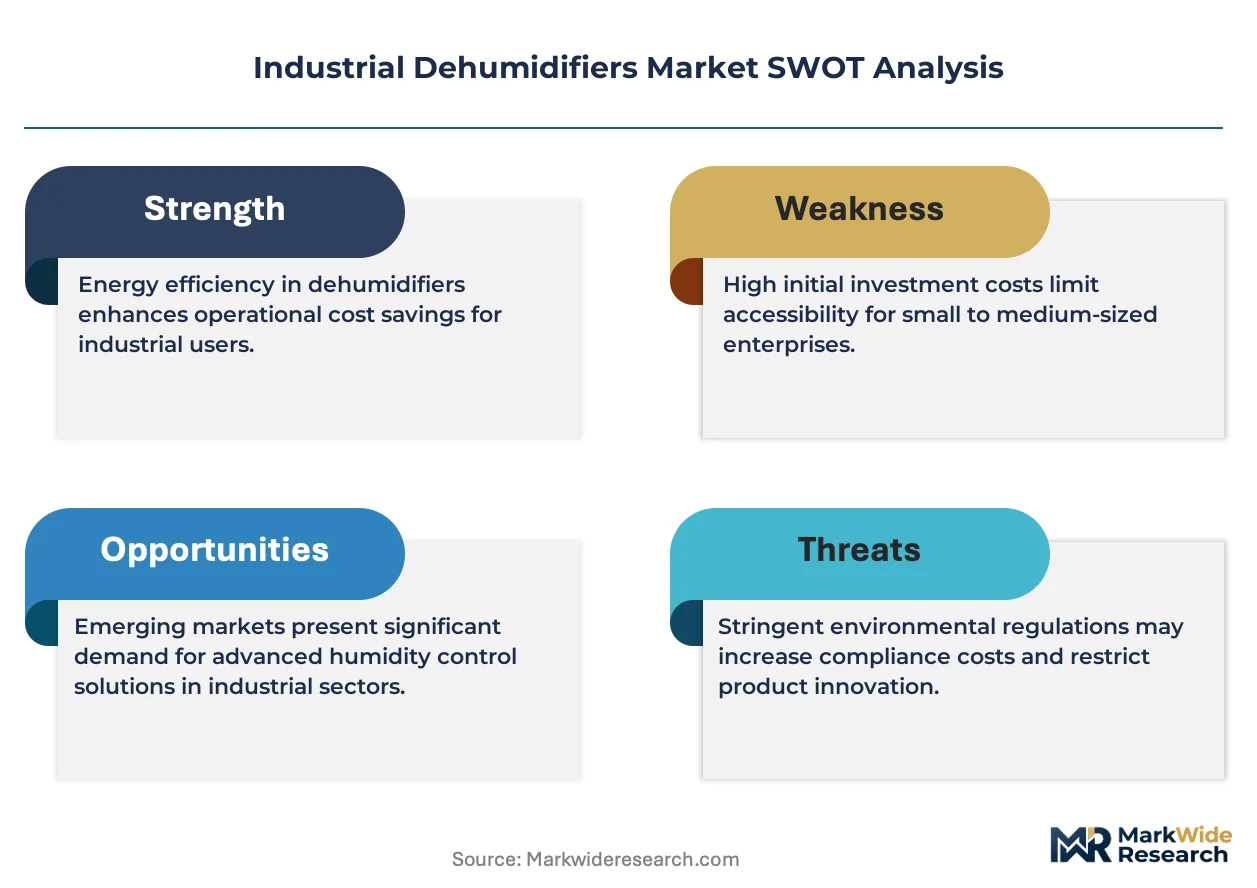
The industrial dehumidifier market pivots on refrigerant chemistry transitions mandated by environmental regulators, forcing manufacturers to reengineer cooling circuits and validate natural refrigerant performance under load conditions previously served by synthetic hydrofluorocarbons.
Growth Catalysts
- EMA Annex 15 compliance:Pharmaceutical manufacturers in Germany and Switzerland invest in validated desiccant systems to meet qualification protocols for sterile manufacturing environments.
- Lithium battery dry rooms:Gigafactory construction across Jiangsu province and Michigan drives specification of ultra-low dew point rotor systems for electrode coating operations.
- EU F-Gas Regulation phase-down:The 2024-2030 refrigerant quota system accelerates retrofit demand in European warehousing and cold chain logistics.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger fabrication costs swing with London Metal Exchange pricing, compressing margins on refrigerant-based units.
- Desiccant silica gel supply concentration:Three Japanese chemical conglomerates control specialty zeolite and silica gel production for high-performance rotors.
- Technical floor for refrigerant systems:Vapor compression cycles cannot achieve dew points below minus 15 degrees Celsius, ceding ultra-dry applications to desiccant competitors.
Strategic Opportunities
- India pharmaceutical corridors:CDSCO manufacturing standards for active pharmaceutical ingredient facilities create compliance-driven demand in Hyderabad and Ahmedabad clusters.
- Predictive maintenance integration:IoT sensor networks enable subscription-based remote monitoring contracts displacing traditional break-fix service models.
- Hybrid architecture development:Converged desiccant-refrigerant systems optimize energy consumption across variable load conditions in semiconductor cleanrooms.
Industry Challenges
- Refrigerant technician certification:EPA Section 608 credentialing requirements constrain installer capacity as natural refrigerant handling protocols diverge from legacy fluorocarbon training.
- Legacy building management integration:BACnet and Modbus protocol mismatches delay smart dehumidifier deployment in 1990s-era industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Dehumidifiers Market |
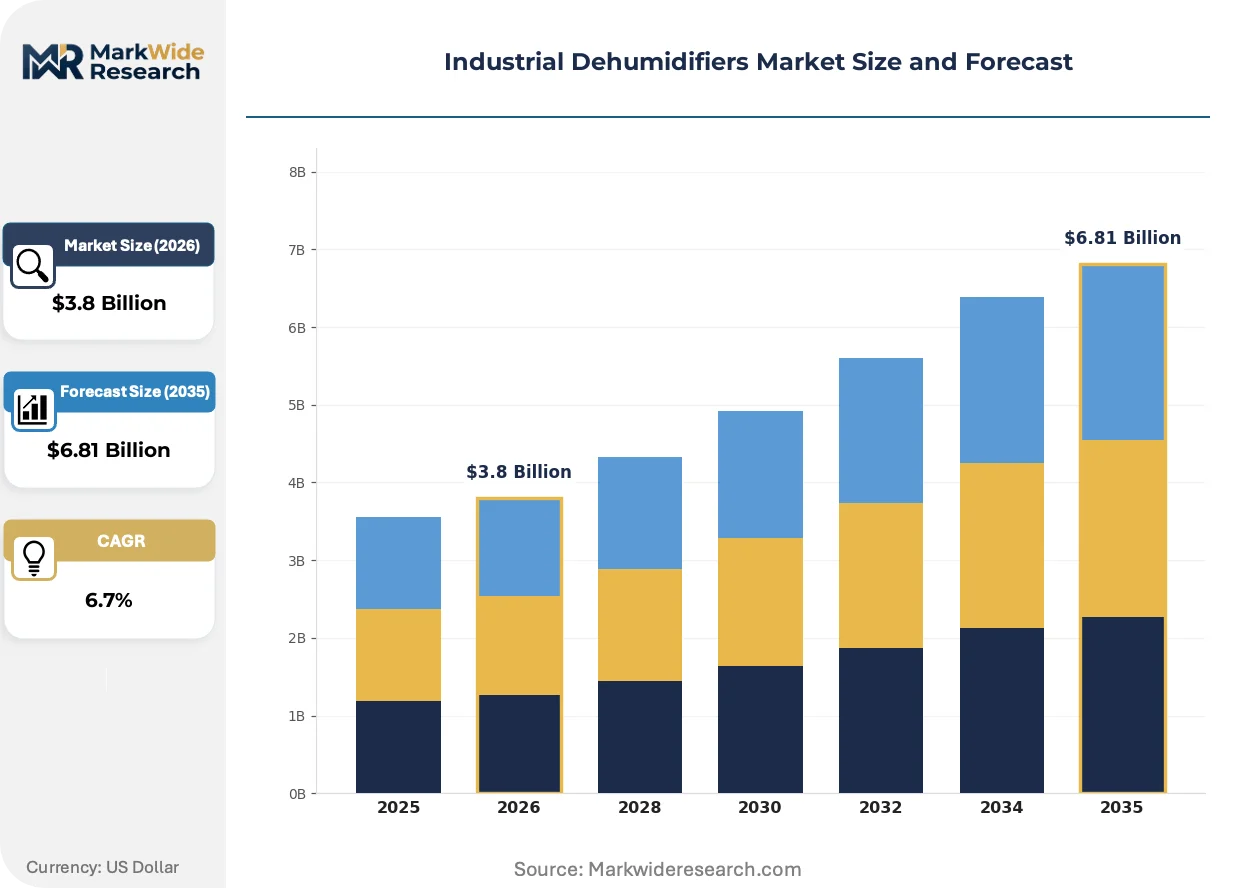
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desiccant, Refrigerant, Hybrid, Chemical End User: Manufacturing, Warehousing, Food Processing, Pharmaceuticals Technology: Smart Control, Manual Control, Portable Systems, Fixed Systems Application: Building Preservation, Mold Control, Humidity Regulation, Climate Control |
| Companies Covered | Munters, Bry-Air, Condair Group, Cotes, Seibu Giken DST, Trotec, DehuTech AB, Fisen Corporation, Dantherm Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Dehumidifiers Market Evolving Landscape
Digital twin technology and refrigerant chemistry innovation are compressing product development cycles while reshaping how humidity control integrates with broader facility energy management.
Smart rotor desiccant systems equipped with variable-speed drives and real-time moisture load sensing are virtualizing the traditional fixed-capacity dehumidifier architecture. Pharmaceutical manufacturers in Denmark and the Netherlands adopt these configurations to match energy draw to actual process requirements. The technology is virtualizing capital equipment procurement into subscription-based performance contracts where vendors retain ownership and optimize runtime algorithms remotely.
EPA hydrofluorocarbon phase-down rules under the AIM Act tighten allowable global warming potential thresholds for industrial refrigeration equipment through 2036. Original equipment manufacturers face accelerated redesign timelines to validate propane and carbon dioxide circuits in capacities above 100 kilowatts. Food processing facilities in California and Texas constitute the most affected segment, with several operators piloting ammonia-desiccant hybrid configurations to maintain compliance without sacrificing throughput.
Facility managers increasingly unbundle equipment procurement from lifecycle service obligations, separating capital budgets from operating expenditure streams. Original equipment manufacturers respond by establishing captive financing arms and performance-guarantee contracts in the electronics manufacturing vertical. This behavioral shift appears most pronounced in Japan's Kansai region, where precision component factories prioritize uptime commitments over upfront capital cost minimization.
Industrial Dehumidifiers Market Segmentation
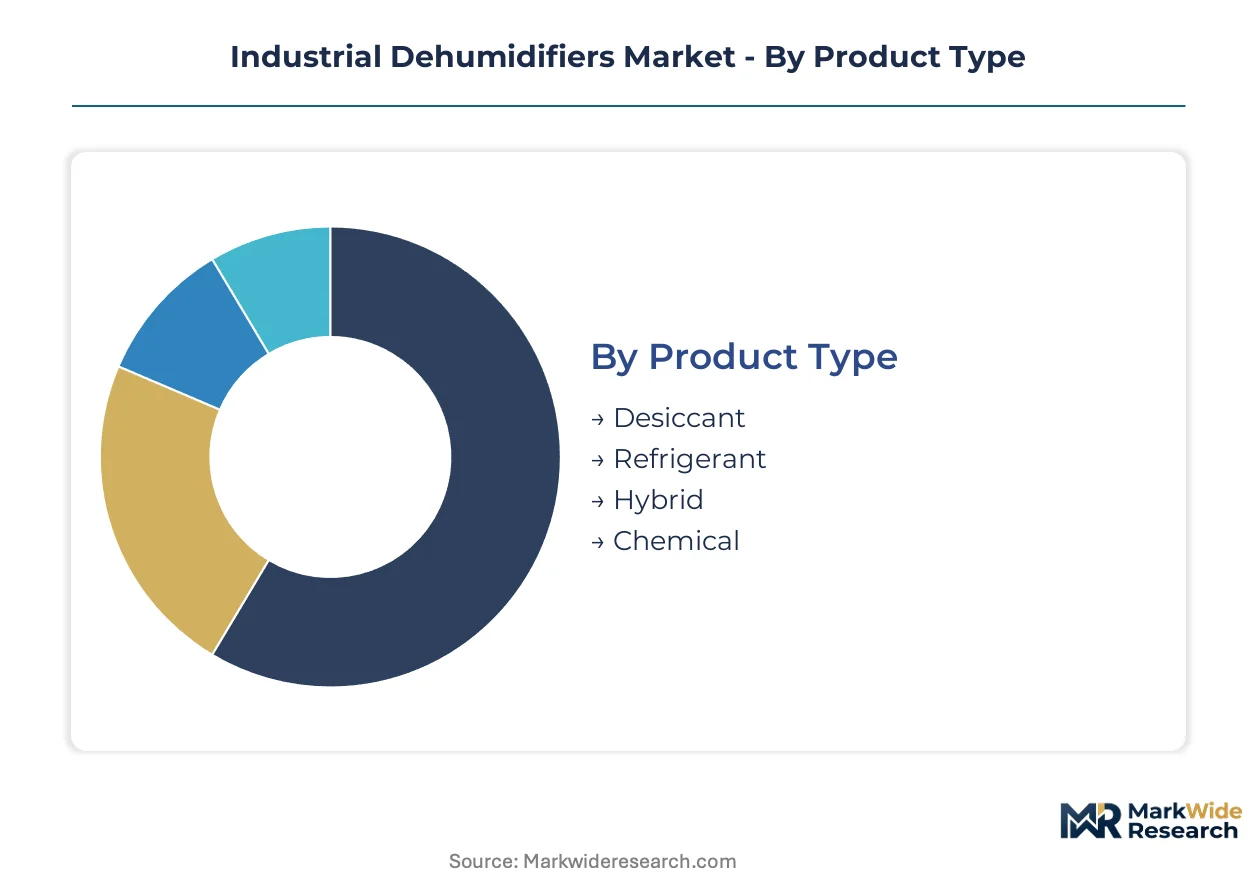
Segmentation in industrial dehumidifiers determines service contract structures and lifecycle revenue capture. Equipment complexity varies sharply across technology types, dictating whether vendors profit through upfront sales or long-term maintenance subscriptions.
Product Type:
After-sales-service intensity varies dramatically by dehumidification mechanism, with desiccant systems demanding rotor replacement schedules and refrigerant units requiring refrigerant handling certification.
- Desiccant:Silica gel or zeolite rotor systems achieve ultra-low dew points through adsorption processes. Pharmaceutical cleanrooms in Germany and Switzerland specify these for EMA Annex 15 compliance, driving premium service contracts for rotor media replacement and performance validation.
- Refrigerant:Vapor compression cycles condense moisture through cooled coils, capping performance at minus 15 degrees Celsius dew point. Food processing facilities in California and Texas face EPA AIM Act retrofit pressure as hydrofluorocarbon quotas tighten, accelerating technician certification bottlenecks.
- Hybrid:Converged architectures optimize energy across variable loads. Semiconductor fabs in Japan's Kansai region pilot these for cleanroom climate control.
- Chemical:Deliquescent media absorb moisture through exothermic reactions. Maritime shipping and remote warehousing deploy these where electricity access is limited.
Refrigerant systems hold the largest share; momentum sits with hybrid architectures.
End User:
Capital deployment patterns diverge sharply across operational environments, with continuous-process industries favoring performance contracts over equipment ownership.
- Manufacturing:Electronics and battery production lines require precision humidity control to prevent corrosion and ensure product consistency. Gigafactory construction across China's Jiangsu province and Michigan drives specification of ultra-low dew point systems for electrode coating operations.
- Pharmaceuticals:Sterile manufacturing demands validated systems with documented calibration protocols. FDA current good manufacturing practice standards and EMA qualification requirements create compliance-driven procurement with mandatory service agreements.
- Warehousing:Cold chain logistics operators face EU F-Gas Regulation retrofit timelines, shifting equipment decisions toward natural refrigerant compatibility.
- Food Processing:Moisture control prevents spoilage and maintains texture specifications. California and Texas facilities pilot ammonia-desiccant hybrids to maintain throughput under EPA phase-down rules.
Manufacturing commands the greatest installed base; pharmaceuticals are climbing the fastest on regulatory compliance spending.
Technology:
Control sophistication determines integration depth with facility energy management systems and the viability of subscription-based service models.
- Smart Control:IoT-enabled systems with real-time moisture sensing and variable-speed drives virtualize fixed-capacity architectures. Pharmaceutical manufacturers in Denmark and the Netherlands adopt performance contracts where vendors retain ownership and optimize algorithms remotely.
- Fixed Systems:Permanent installations dominate high-capacity industrial applications. Legacy BACnet protocol mismatches delay deployment in 1990s-era facilities.
- Manual Control:Basic humidity setpoint management persists in cost-constrained warehousing environments.
- Portable Systems:Mobile units serve temporary remediation and construction drying applications with minimal service attachment.
Fixed systems dominate current installations; smart control configurations are gaining share fastest through remote monitoring subscriptions.
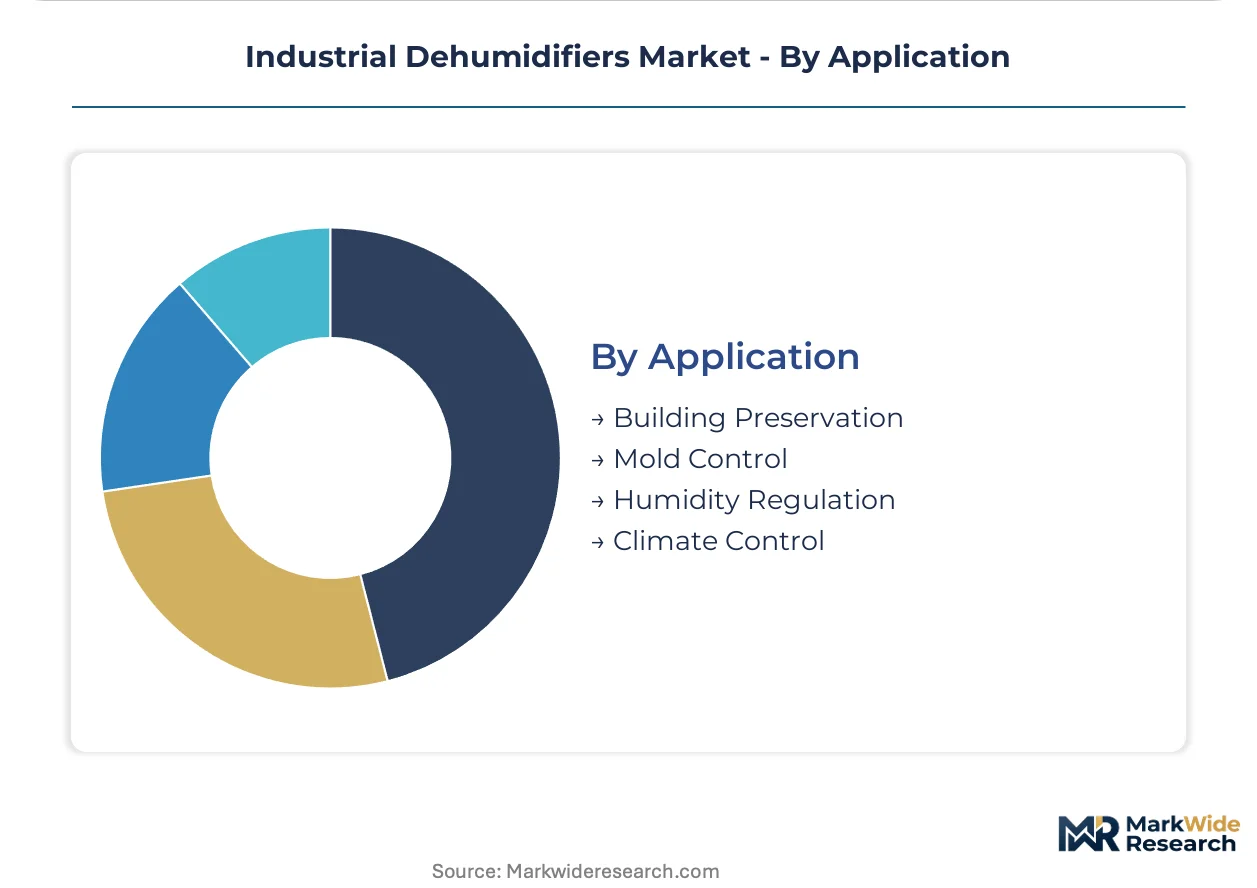
Application:
Humidity control objectives shape equipment specification, with preservation-focused applications tolerating wider performance bands than active manufacturing processes.
- Climate Control:Precision management of temperature and humidity together dominates semiconductor and pharmaceutical cleanrooms. Japan's precision component factories prioritize uptime commitments over capital cost minimization in this segment.
- Mold Control:Threshold-based moisture suppression prevents fungal proliferation in archives and heritage buildings. Building preservation authorities in Northern Europe specify desiccant systems for manuscript storage.
- Humidity Regulation:General industrial processes require stable moisture levels for material consistency. Chemical processing and powder handling operations fall within this scope.
- Building Preservation:Historic structure protection emphasizes gradual moisture reduction to prevent material stress. Museums and conservation facilities deploy these systems.
Climate control holds the largest share; mold control is expanding most quickly on heritage preservation spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Warehousing operators in India and Southeast Asia prioritize capital cost minimization, while pharmaceutical manufacturers in Germany and Switzerland absorb premium pricing for validated systems with documented calibration protocols.
United States
Food processing facilities in California and Texas pilot ammonia-desiccant hybrid configurations to maintain throughput under EPA AIM Act hydrofluorocarbon phase-down rules. The EPA Section 608 credentialing requirements constrain installer capacity as natural refrigerant handling protocols diverge from legacy fluorocarbon training. Michigan's battery manufacturing corridor drives specification of ultra-low dew point rotor systems for electrode coating operations in gigafactory construction.
Germany
Pharmaceutical manufacturers invest in validated desiccant systems to meet EMA Annex 15 qualification protocols for sterile manufacturing environments. The EU F-Gas Regulation 2024-2030 refrigerant quota system accelerates retrofit demand in warehousing and cold chain logistics. Industrial clusters in North Rhine-Westphalia anchor demand for hybrid architectures that optimize energy consumption across variable load conditions.
China
Electronics and precision manufacturing in Jiangsu province require stringent humidity management for semiconductor and battery production lines. The country's national environmental regulator enforces dual carbon goals that push industrial facilities toward energy-efficient climate control systems. Yangtze River Delta manufacturing hubs specify smart-controlled units with IoT-enabled humidity monitoring integrated into building management systems.
Japan
Precision component factories in the Kansai region prioritize uptime commitments over upfront capital cost minimization, favoring performance contracts with remote monitoring subscriptions. METI industrial standards emphasize energy benchmarking that accelerates adoption of variable-speed drive configurations. Nagoya-area automotive suppliers deploy desiccant rotor systems to prevent corrosion in moisture-sensitive assembly operations.
India
Active pharmaceutical ingredient facilities in Hyderabad and Ahmedabad clusters face CDSCO manufacturing standards that create compliance-driven demand for documented humidity control. The country's national pharmaceutical regulator mandates qualification protocols similar to EMA Annex 15 for sterile manufacturing environments. Western pharmaceutical corridors absorb higher equipment costs to meet export market certification requirements for European and North American buyers.
Industrial Dehumidifiers Market Competitive Landscape
Capability concentration sits with desiccant rotor specialists; scale advantage sits with diversified climate control conglomerates. The market structures around three tiers: premium validated-system vendors serving pharmaceutical compliance markets, mid-tier refrigerant-based suppliers competing on energy efficiency, and regional fabricators capturing cost-sensitive warehousing contracts. Dominant competitive moves include captive financing arms for performance-guarantee contracts and strategic partnerships for IoT platform integration.
Within the premium validated-system tier, Munters and Bry-Air exemplify archetypes built on application engineering depth and rotor media specialization. Seibu Giken DST occupies a position among Japanese precision manufacturers with strongholds in semiconductor and battery dry room specifications. These three anchors demonstrate how geographic origin and naming conventions signal strategic positioning: Swedish-American conglomerate structures versus Indian engineering specialists versus Japanese precision-industry suppliers.
| Leading Market Players |
|---|
| Munters |
| Bry-Air |
| Condair Group |
| Cotes |
| Seibu Giken DST |
| Trotec |
| DehuTech AB |
| Fisen Corporation |
| Dantherm Group |
| Others |
Value Network & Pricing Analysis
Japanese chemical conglomerates controlling specialty zeolite and silica gel production for high-performance desiccant rotors concentrate upstream margin capture, forcing downstream equipment vendors to compete through service bundling and captive financing arms rather than component cost leverage.
Pricing Analysis
Aftermarket service contracts and remote monitoring subscriptions now drive lifetime value more than equipment sales, with predictive maintenance tiers separating pharmaceutical cleanroom operators from cost-constrained warehousing buyers. Price differentiation rests on certification grade for EMA Annex 15 or FDA cGMP compliance and geographic delivery cost for remote maritime installations. Pricing pressure stems from copper and aluminum volatility on London Metal Exchange, compressing margins on refrigerant-based units. Food processing facilities in California and Texas show highest price sensitivity due to EPA retrofit timelines, while German pharmaceutical manufacturers absorb premium validated-system costs.
Supply Chain Analysis
Extended payment terms from Japanese rotor media suppliers and supply-chain finance facilities anchor working capital structures for desiccant system assemblers. Manufacturing concentrates in Japan for specialty zeolite, Germany for precision engineering components, and China for standard refrigeration assemblies. Raw material dependencies include silica gel, aluminum heat exchangers, and copper tubing. Single-source vulnerability in specialty desiccant media creates procurement risk. Distribution runs through OEM direct sales for pharmaceutical compliance markets and regional distributor networks for standard warehousing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized application engineering for ultra-low dew point environments represents a scarce capability, with qualified rotor system designers and validated calibration protocol expertise concentrated among a handful of vendors serving pharmaceutical and battery manufacturing verticals.
For Market Incumbents: Build switching-cost moats through embedded IoT sensor networks that virtualize equipment ownership into performance contracts. Deepen captive financing arms to capture subscription revenue streams. Expand rotor media replacement infrastructure in China's Jiangsu province to serve gigafactory construction timelines. Defend against emerging refrigerant-technology specialists by accelerating natural refrigerant certification programs ahead of EPA phase-down deadlines.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's pharmaceutical corridors, specifically CDSCO-compliant active pharmaceutical ingredient facilities in Hyderabad and Ahmedabad clusters. Target hybrid architecture development for semiconductor cleanrooms where converged desiccant-refrigerant optimization remains underdeveloped. Anchor go-to-market strategy through performance-guarantee contracts rather than capital equipment sales to match Japanese Kansai region procurement preferences.
For Investors and Strategic Acquirers: Capital is best deployed toward application-engineering specialists with validated EMA or FDA qualification track records and established service infrastructure. Long-term viability favors vendors with recurring revenue attachment rates above industry norms. Monitor refrigerant chemistry patent filings and EPA Section 608 technician certification expansion rates as inflection indicators for technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | IoT-enabled humidity monitoring displaces break-fix service models in pharmaceutical installations. |
| Natural Refrigerant Circuit Validation | Propane and carbon dioxide system certification secures EPA AIM Act compliance for food processing. |
| Rotor Media Backward Integration | In-house zeolite production reduces dependency on Japanese chemical conglomerate supply concentration. |
| Performance Contract Captive Financing | Vendor-retained ownership models match Japanese precision manufacturer uptime prioritization. |
| Hybrid Architecture Joint Development | Desiccant-refrigerant convergence addresses semiconductor cleanroom variable load optimization. |
Research Methodology
Desk research of customs trade databases, EU F-Gas Regulation implementation reports, and EPA refrigerant phase-down filings preceded structured interviews with pharmaceutical facility engineers, food processing plant managers, battery gigafactory construction directors, and aftermarket service heads. Primary fieldwork across Germany, China, Japan, and the United States validated secondary findings on technology adoption patterns. Bottom-up equipment shipment analysis triangulated against top-down industrial construction spending data.
Assumptions held fixed include current EU F-Gas and EPA AIM Act regulatory trajectories, while copper and aluminum price scenarios and lithium battery dry room construction timelines were stress-tested across sensitivity bands. Segmentation modeling incorporated product type, end-user vertical, control technology sophistication, and application environment. CAGRs derived from regression analysis against industrial output indices and regulatory compliance spending patterns. Forecast inputs included gigafactory construction permits and pharmaceutical manufacturing facility qualification timelines.
Sensitivities concentrate around refrigerant chemistry classification revisions and critical mineral supply disruptions affecting desiccant media availability. Forecasts reflect documented assumptions on regulatory implementation schedules and industrial capital expenditure cycles. Macroeconomic contraction, accelerated refrigerant phase-down schedules, or breakthrough solid-state dehumidification technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
GCC Portable Air Conditioners Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Electric Underfloor Heating Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Hot Water Circulator Pump Market
HVAC Equipment
Air Conditioning Equipment Market
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Centrifugal Chillers Market
HVAC Equipment
Hydro Chillers Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Residential Heat Pump Market