
 Construction Machinery Attachment Market | 2026-2036
Construction Machinery Attachment Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Machinery Attachment Market Analysis
Buyer concentration among rental services is consolidating as national chains expand their attachment inventories at the expense of independent dealers. Caterpillar Inc. leverages its dealer network to control aftermarket parts flows for hydraulic breakers and grapples. Komatsu Ltd. anchors its position through in-house production of quick-coupler systems that reduce fleet downtime. Epiroc Aktiebolag specializes in mining-focused attachments, competing on rock-tool durability in hard-rock extraction environments.
Construction machinery attachments are purpose-built implements that mount to host machines through standardized coupler interfaces, typically rated by breakout force, hydraulic flow capacity, and operating weight class to match specific carrier specifications. Excavator buckets dominate attachment type revenue due to universal deployment across excavation and grading workflows, while hydraulic breakers command premium positioning in demolition applications where tool steel composition determines wear life. Steel remains the baseline material for structural components, though alloy variants are gaining share in high-cycle mining attachments where fatigue resistance justifies material cost premiums.
OSHA workplace safety standards in the United States mandate load-capacity verification for material handling attachments, directly shaping product certification requirements and liability exposure for rental fleet operators. The EU Machinery Directive and CE marking framework enforce design safety protocols for grapples and pallet forks sold across European member states, creating compliance cost barriers for non-European suppliers. Stakeholders must monitor how emerging battery-electric construction equipment platforms redefine hydraulic interface specifications and attachment power-draw limits.
Market Dynamics
Electrified hydraulic architectures are forcing attachment manufacturers to redesign coupler interfaces and power-draw specifications for battery-electric host machines, compressing development cycles and recalibrating compatibility matrices across OEM portfolios.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating electrified hydraulic system adoption, creating replacement demand for low-emission attachment designs across European rental fleets.
- Autonomous haulage integration:Mining operators in Western Australia are expanding specialized attachment inventories to support automated truck loading workflows, driving precision-tool demand in hard-rock extraction.
- Quick-coupler standardization:ISO 13031 compliance is reducing fleet downtime through universal interface adoption, enabling rapid tool swapping across mixed-manufacturer equipment bases.
Market Restraints
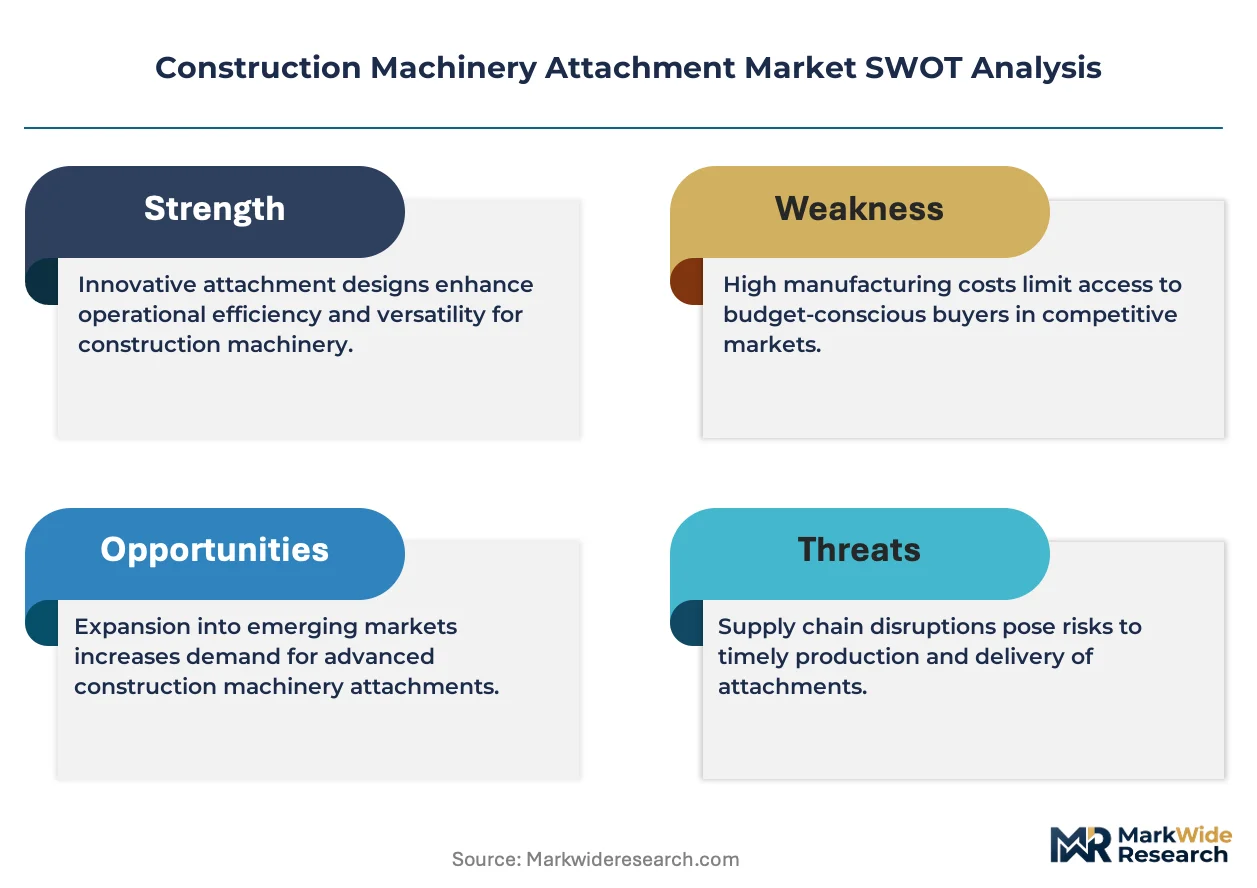
- Alloy steel input volatility:High-cycle mining attachments depend on fatigue-resistant alloy variants, exposing manufacturers to nickel and chromium price swings that compress margin buffers on long-delivery contracts.
- CE marking compliance costs:Non-European suppliers face elevated certification barriers under the EU Machinery Directive, limiting market access for unverified grapple and pallet fork producers.
- Hydraulic-electric interface incompatibility:Legacy attachment fleets lack standardized power electronics for battery-electric carriers, creating stranded asset risk for rental operators with mixed-age equipment.
Strategic Opportunities
- India infrastructure build-out:National highway and urban metro expansion is concentrating demand for excavator buckets and hydraulic breakers in the Delhi-Mumbai Industrial Corridor.
- Telematics-integrated attachments:Sensor-embedded tools enabling usage-based rental pricing are penetrating German construction markets ahead of Southern European adoption curves.
- US IRA clean construction incentives:Tax credits for electrified equipment procurement are stimulating early replacement cycles for diesel-dependent attachment fleets.
Industry Challenges
- Hydraulic systems engineering talent scarcity:Electrification is displacing conventional fluid power expertise, forcing manufacturers to retrain workforce competencies or compete for limited electromechanical design specialists.
- Multi-certification timeline compression:Simultaneous OSHA load-capacity verification and CE Machinery Directive compliance is extending product launch windows for cross-Atlantic suppliers.
- Legacy fleet integration complexity:Retrofit compatibility kits for older excavators require custom hydraulic mapping, fragmenting engineering resources across one-off customer configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Machinery Attachment Market |
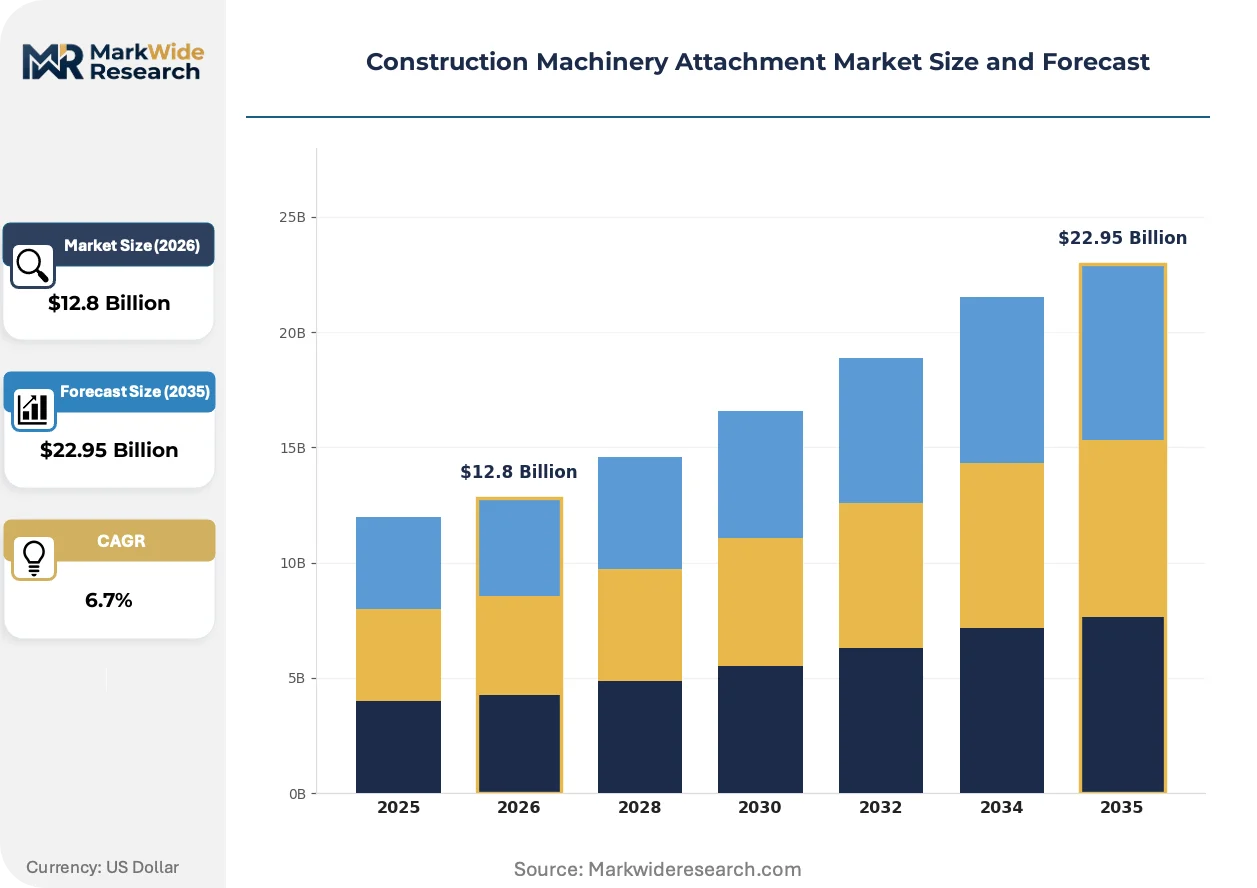
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Attachment Type: Excavator Buckets, Pallet Forks, Hydraulic Breakers, Grapples Material: Steel, Alloy, Composite, Rubber Application: Excavation, Demolition, Material Handling, Grading End User: Construction Firms, Rental Services, Municipals, Mining Operators |
| Companies Covered | Liebherr-International Deutschland GmbH, Hitachi Construction Machinery Co., Ltd., Caterpillar Inc., Doosan Bobcat Inc., J.C. Bamford Excavators Limited, Komatsu Ltd., Volvo Construction Equipment AB, Epiroc Aktiebolag, Deere & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Machinery Attachment Market Emerging Trajectories
Attachment intelligence is migrating from passive implements to active data-generating nodes, rewiring how rental operators manage utilization and how OEMs structure aftermarket revenue.
Telematics-embedded load sensors are rewriting fleet management economics by transmitting real-time stress data to cloud-based maintenance platforms. Large rental chains in Germany are deploying these instruments across breaker and grapple inventories to optimize replacement scheduling. The technology is compressing traditional time-based service intervals into condition-triggered interventions, reducing unplanned downtime in high-utilization environments.
The EU F-Gas Regulation is mandating sealed hydraulic systems with reduced refrigerant leakage potential, compelling attachment producers to redesign cylinder architectures and sealing technologies. Manufacturers serving Rhine-Ruhr industrial clusters are prioritizing electrified actuation to bypass hydraulic fluid compliance entirely. Mining-focused product lines face the steepest redesign burden due to extreme duty cycles that stress conventional sealing solutions.
Equipment-as-a-service contracting is displacing outright purchase for mid-size excavation attachments among German municipal utilities and infrastructure contractors. Rental service providers are unbundling maintenance and insurance from base equipment rates, capturing margin through usage-tiered pricing structures. This model concentrates most visibly in urban demolition verticals where project duration uncertainty favors operational expense treatment over capital commitment.
Construction Machinery Attachment Market Segmentation
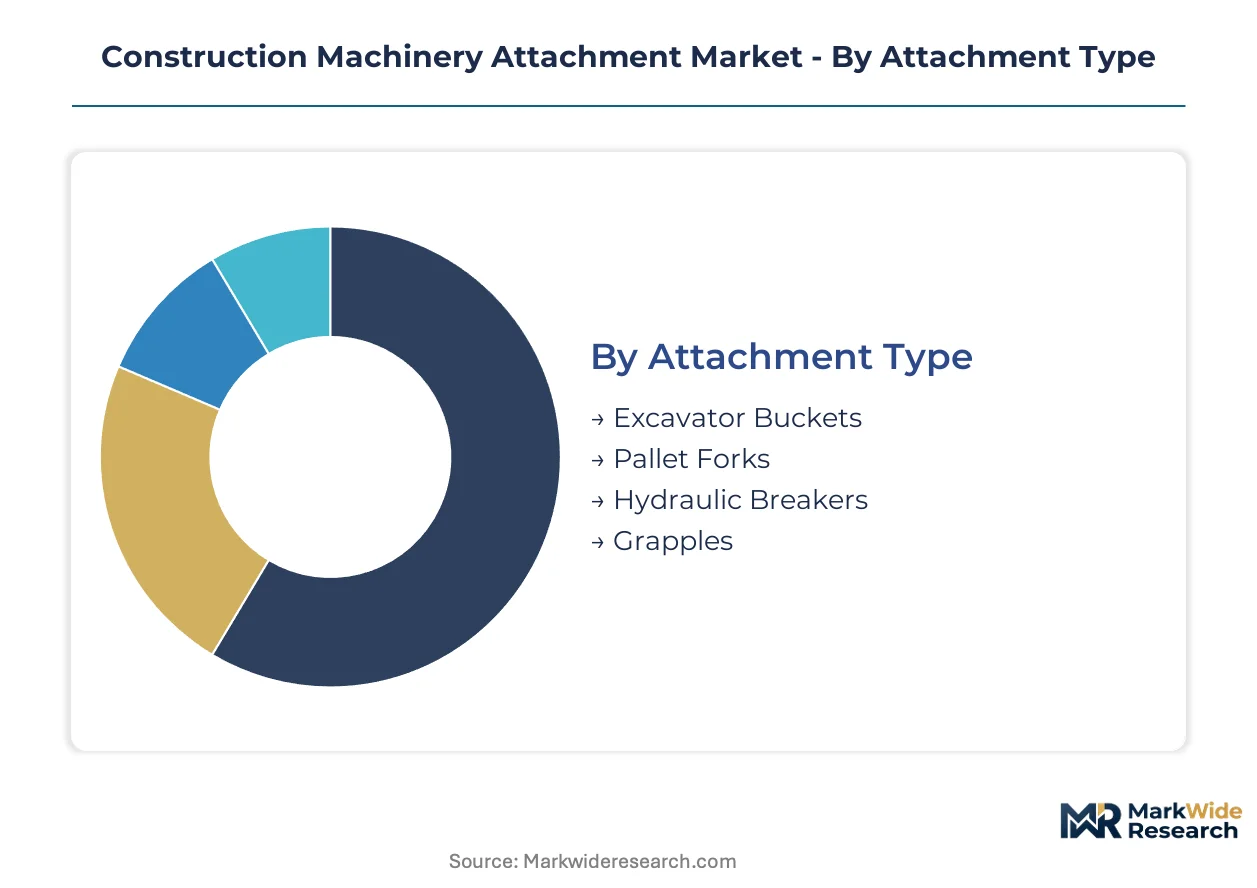
Attachment selection decisions cascade from carrier machine specifications through to duty-cycle intensity and regulatory exposure. Buyers weight hydraulic flow compatibility against wear-part availability and certification burden.
Attachment Type:
Buyers prioritize breakout force ratings and coupler interface standardization when specifying implements for mixed-fleet deployment.
- Excavator Buckets:Fabricated from high-tensile steel plate with reinforced cutting edges and wear strips. Demand concentrates in Germany's Rhine-Ruhr corridor where rapid equipment turnaround requirements favor universal bucket geometries. ISO 13031 coupler compatibility reduces fleet downtime for rental operators managing multi-manufacturer bases.
- Hydraulic Breakers:Percussion tools rated by impact energy class and blow frequency, with tool steel composition determining wear life in hard-rock environments. Mining operators in Western Australia are expanding breaker inventories to support autonomous haulage integration, driving demand for precision-matched hydraulic flow systems.
- Pallet Forks:Load-rated tine assemblies with carriage-mounted quick-attach interfaces. OSHA load-capacity verification mandates shape certification requirements for US rental fleet operators.
- Grapples:Hydraulic-actuated multi-tine implements for bulk material sorting. CE marking compliance under the EU Machinery Directive elevates design safety costs for non-European suppliers.
Excavator buckets lead on scale; hydraulic breakers lead on momentum.
Material:
Material selection hinges on fatigue-cycle requirements and alloy input cost volatility across long-delivery contracts.
- Steel:Baseline structural grade for general-purpose attachments with standard wear resistance. Construction firms in India's Delhi-Mumbai Industrial Corridor specify steel buckets for highway expansion projects where capital constraints limit alloy adoption.
- Alloy:Fatigue-resistant nickel-chromium variants for high-cycle mining attachments. Western Australian hard-rock extraction environments justify material cost premiums through extended service intervals.
- Composite:Reinforced polymer structures for weight-sensitive applications. Municipal utilities in Germany are testing composite components for reduced carrier fuel consumption.
- Rubber:Vibration-dampening elements and wear pads for noise-sensitive urban demolition. EU F-Gas Regulation compliance is pushing manufacturers toward sealed systems that reduce hydraulic fluid exposure to rubber seals.
Steel dominates current procurement volumes; alloy commands the steepest expansion trajectory.
Application:
Workflow specificity determines attachment durability specifications and replacement frequency.
- Excavation:Earthmoving and trenching operations requiring high breakout force and abrasion-resistant cutting edges. German infrastructure contractors are adopting telematics-embedded buckets for usage-based rental pricing.
- Demolition:Structure dismantling with emphasis on hydraulic breaker precision and grapple sorting efficiency. Urban demolition verticals in the US are shifting toward equipment-as-a-service contracting to manage project duration uncertainty.
- Material Handling:Load-lifting and transport with OSHA-mandated load-capacity verification. Rental services are consolidating national inventories of certified pallet forks.
- Grading:Surface finishing with precise depth control requirements. Municipal utilities favor quick-coupler systems for rapid tool swapping between excavation and grading tasks.
Excavation anchors volume demand; demolition is gaining share fastest.
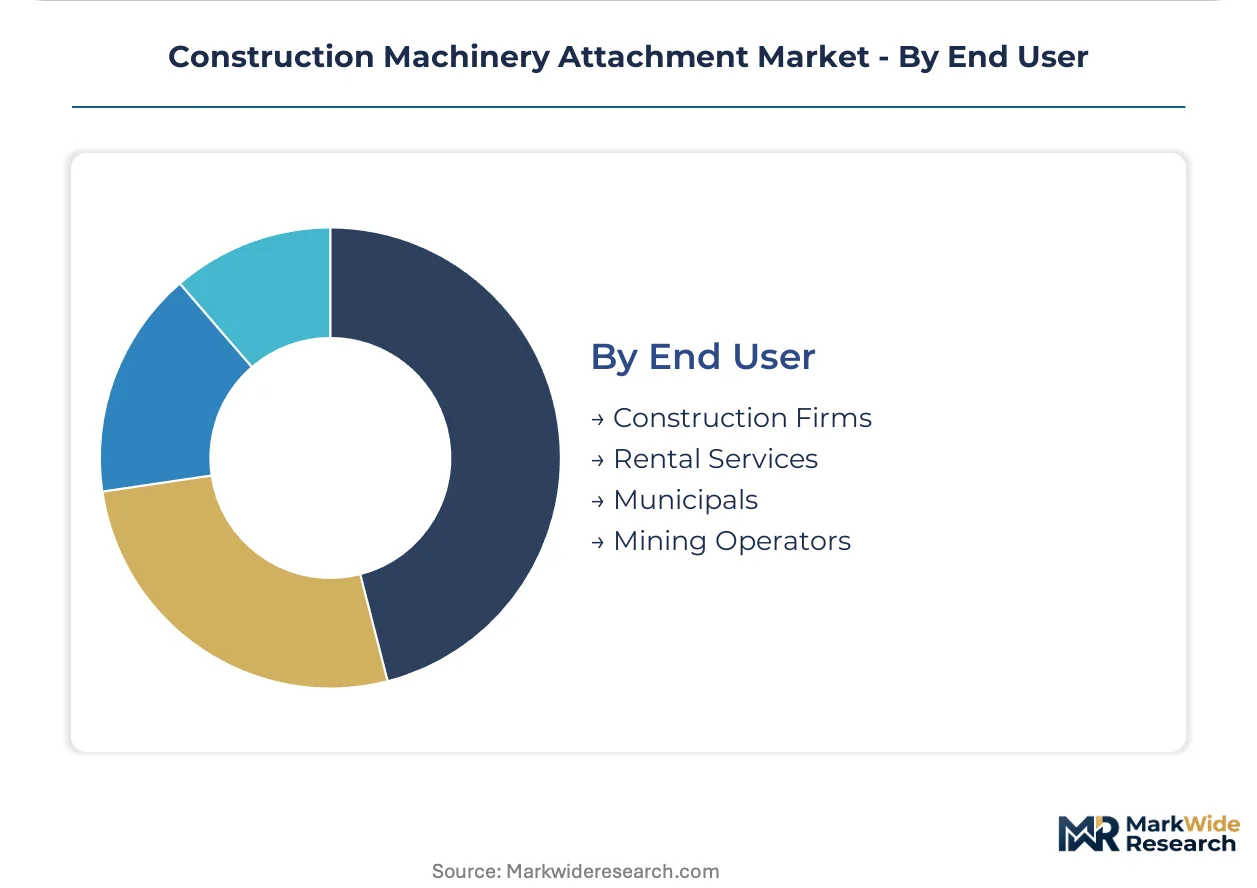
End User:
Procurement authority and maintenance capability shape attachment specification and ownership models.
- Construction Firms:Project-based buyers with mixed fleet ages requiring retrofit compatibility solutions. US IRA clean construction incentives are stimulating early replacement cycles for diesel-dependent attachment fleets.
- Rental Services:National chains expanding attachment inventories at the expense of independent dealers. German rental operators are deploying telematics-integrated breakers and grapples for condition-triggered maintenance interventions.
- Municipals:Public sector entities with operational expense preference and extended equipment holding periods. Equipment-as-a-service contracting is penetrating German municipal utilities for mid-size excavation attachments.
- Mining Operators:Hard-rock extraction specialists prioritizing rock-tool durability and autonomous haulage compatibility. Western Australian operators are expanding specialized attachment inventories to support automated truck loading workflows.
Rental services lead on procurement scale; mining operators lead on technology adoption momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia commands premium attachment demand through autonomous mining integration, while Germany drives regulatory-compliant electrification in hydraulic systems. China anchors manufacturing scale for standard buckets and breakers. India concentrates infrastructure-driven procurement in emerging industrial corridors.
United States
OSHA load-capacity verification mandates shape certification requirements for rental fleet operators managing material handling attachments. The Inflation Reduction Act clean construction incentives stimulate early replacement cycles for diesel-dependent attachment fleets. Equipment-as-a-service contracting penetrates urban demolition verticals where project duration uncertainty favors operational expense treatment.
Germany
The EU F-Gas Regulation accelerates electrified hydraulic system adoption across Rhine-Ruhr industrial clusters where OEMs and rental services co-locate. CE marking compliance under the EU Machinery Directive elevates design safety costs for grapple and pallet fork producers. Telematics-integrated attachments enabling usage-based rental pricing are penetrating German construction markets ahead of Southern European adoption curves.
Australia
Mining operators in Western Australia expand specialized attachment inventories to support autonomous haulage systems and automated truck loading workflows. The country's national workplace safety regulator enforces load-capacity verification standards for material handling equipment in hard-rock extraction environments. Perth-based equipment distributors concentrate rock-tool durability expertise for extreme duty cycle applications.
India
National highway and urban metro expansion concentrates demand for excavator buckets and hydraulic breakers in the Delhi-Mumbai Industrial Corridor. The Bureau of Indian Standards certification framework shapes product entry requirements for construction equipment attachments. Construction firms in Maharashtra and Gujarat specify steel buckets for infrastructure projects where capital constraints limit alloy adoption.
China
Domestic infrastructure maintenance and Belt-and-Road construction exports sustain volume demand for standard excavator buckets and quick-coupler systems. The Ministry of Industry and Information Technology oversees equipment quality standards that influence attachment interface specifications. Manufacturing clusters in Jiangsu and Shandong provinces supply cost-optimized fabrications for emerging market procurement.
Construction Machinery Attachment Market Vendor Landscape
German and Japanese producers anchor one tier; Australian mining specialists and American full-line manufacturers hold differentiated positions. The vendor structure concentrates around integrated construction equipment OEMs with captive attachment divisions, complemented by independent fabricators serving rental aftermarket channels. Three archetypes dominate: full-line machinery producers with in-house attachment portfolios, mining-focused rock-tool specialists, and regional fabrication houses supplying price-sensitive procurement. Competitive dynamics center on quick-coupler standardization races and electrified hydraulic interface development.
Among Germany-based manufacturers, Liebherr-International Deutschland GmbH exemplifies the integrated machinery producer archetype. Komatsu Ltd. and Caterpillar Inc. represent the full-line OEM tier with established aftermarket parts control. Epiroc Aktiebolag occupies a specialist position within mining-focused attachment supply. These three entities illustrate how geographic origin and corporate structure map to competitive positioning without requiring specific product or strategic claims.
| Leading Market Players |
|---|
| Liebherr-International Deutschland GmbH |
| Hitachi Construction Machinery Co., Ltd. |
| Caterpillar Inc. |
| Doosan Bobcat Inc. |
| J.C. Bamford Excavators Limited |
| Komatsu Ltd. |
| Volvo Construction Equipment AB |
| Epiroc Aktiebolag |
| Deere & Company |
| Others |
Supply Flow & Price Mechanics
A certification-performance divergence separates CE-marked grapples and pallet forks from uncertified commodity alternatives, with this bifurcation driving both margin capture in German Rhine-Ruhr clusters and sourcing concentration toward integrated OEMs with captive compliance capabilities.
Pricing Analysis
Capacity additions in China's Jiangsu and Shandong provinces are reshaping price floors for standard excavator buckets, compressing margins on undifferentiated fabrications while alloy-reinforced mining attachments in Western Australia command durability premiums. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13031 coupler compatibility and fatigue-cycle ratings. Price differentiation stems from certification grade and after-sales service bundling. Cost compression in steel-grade buckets intensifies because of import competition, while rental services show highest price sensitivity and mining operators demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with nickel-chromium alloy suppliers serving high-cycle mining attachment producers, exposing fabricators to raw material disruption. Manufacturing concentrates in China, Germany, and Australia, with component sourcing drawing from South Korean hydraulic systems and Swedish tool steel. Supply chain risk centers on tariff exposure for EU-bound grapples from non-CE-certified producers. Distribution runs through OEM captive dealer networks and independent rental aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation phase-down mandates are accelerating replacement cycles for electrified hydraulic attachments across European rental fleets.
For Market Incumbents: Deepen in-house production of quick-coupler systems to defend against emerging Chinese fabricators with cost-optimized bucket offerings. Anchor aftermarket parts control through dealer network exclusivity clauses for hydraulic breakers and grapples. CE marking compliance investment represents the priority defensive lever against non-European suppliers facing elevated certification barriers. For New Entrants and Emerging Players: Telematics-embedded load sensors offer a technology-first wedge into German rental service procurement specifications ahead of Southern European adoption curves. Target India's Delhi-Mumbai Industrial Corridor for excavator bucket penetration where capital-constrained highway contractors prioritize steel-grade procurement. Pursue equipment-as-a-service contracting models to bypass upfront purchase resistance among municipal utilities. For Investors and Strategic Acquirers: Consolidation pressure builds where independent fabrication houses lack capital to fund electrified hydraulic redesigns for battery-electric carrier compatibility. Long-term viability favors specialists with mining-focused rock-tool expertise and autonomous haulage integration capabilities. Watch for inflection when telematics-integrated attachment penetration crosses critical mass in German construction markets.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Hydraulic System Development | EU F-Gas Regulation compliance enables market access across Rhine-Ruhr industrial clusters. |
| Telematics Integration Partnership | German rental chains deploy sensor-embedded breakers for condition-triggered maintenance interventions. |
| Quick-Coupler Standardization Investment | ISO 13031 compatibility reduces fleet downtime for mixed-manufacturer equipment bases. |
| Mining Attachment Specialization | Western Australian autonomous haulage integration demands precision-matched rock-tool durability. |
| Alloy Steel Supply Agreement | Long-term nickel-chromium sourcing hedges margin compression from commodity price volatility. |
Methodological Framework
Multiple input streams — primary interviews with OEM procurement teams, rental fleet managers, and mining maintenance directors; secondary validation through SEC filings, customs trade data, and equipment registration databases; plus technical specification reviews — were reconciled through bottom-up and top-down triangulation to construct segment-level estimates.
Historical shipment patterns were cross-referenced against panel input from equipment distributors and aftermarket service heads across the analysis window. Segmentation modeling covered attachment type, material grade, application workflow, and end-user procurement authority. CAGRs were derived from fitted growth curves incorporating regulatory phase-in schedules and infrastructure investment pipelines.
The model holds under stable alloy input pricing and continued electrification subsidy programs; deviation in trade policy or battery-electric platform adoption rates would shift trajectory. Forecasts reflect documented assumptions about coupler standardization timelines and autonomous mining deployment curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market