
 Europe Bus HVAC Market | 2026-2036
Europe Bus HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bus HVAC Market Insights
Aftermarket software-defined thermal management is restructuring how European fleet operators procure bus climate systems. Webasto leverages its retrofit connectivity platform to capture recurring service revenue beyond hardware installation. Valeo sustains engineering intensity in low-GWP refrigerant architectures aligned with EU F-Gas phase-down schedules. Thermo King anchors its position through captive service networks spanning depot infrastructure across France and Benelux.
Bus HVAC systems regulate cabin temperature, air quality, and humidity through vapor-compression cycles, heat exchange circuits, and filtered ventilation delivering thermal outputs from 20 kW to 45 kW depending on vehicle class and climate zone. Rooftop units dominate urban single-deck deployments due to packaging efficiency and service accessibility, while integrated systems gain share in battery-electric platforms where thermal loads must coordinate with pack conditioning. Heat pump technology is displacing conventional refrigeration-heating combinations as operators confront total energy consumption targets under municipal procurement rules.
The EU F-Gas Regulation and Ecodesign Directive constrain refrigerant selection and minimum efficiency thresholds, compelling suppliers to revalidate component portfolios. Germany's KBA enforces type-approval protocols that extend certification timelines for novel thermal architectures. Stakeholders must monitor how national zero-emission fleet mandates synchronize with TCO-based procurement frameworks to anticipate replacement cycle timing and specification drift.
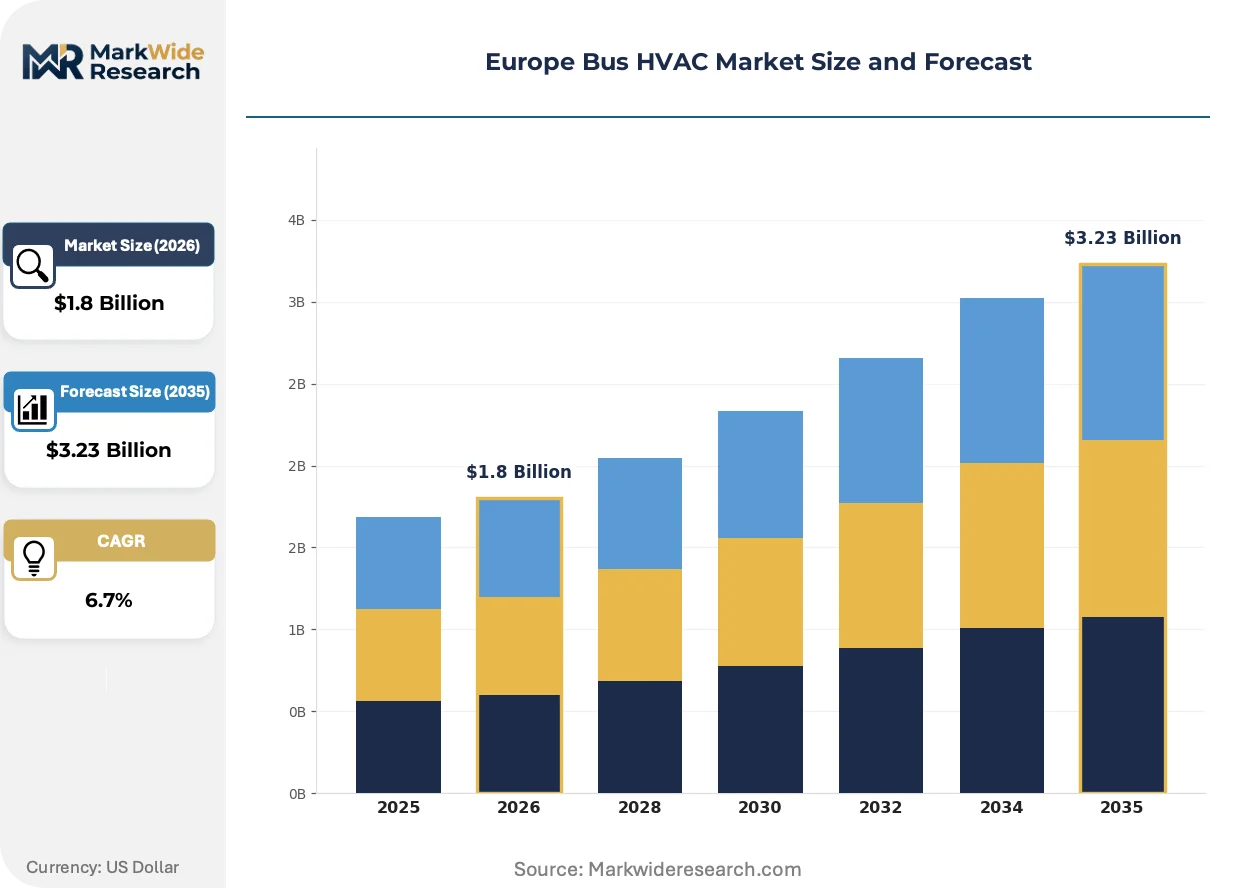
Market Dynamics
Fleet electrification across European municipal transit authorities is restructuring thermal system procurement, forcing suppliers to reengineer architectures around battery conditioning loads and heat pump efficiency targets mandated by EU F-Gas phase-down schedules.
Growth Catalysts
- EU Green Deal zero-emission mandates:National fleet electrification deadlines in Germany, France, and the Netherlands are accelerating replacement cycles for compatible HVAC systems in municipal bus depots.
- Heat pump technology maturation:Advances in low-GWP refrigerant architectures are enabling single-system heating and cooling that reduces energy draw from electric bus battery packs.
- Nordic corridor climate severity:Extended heating seasons in Norway, Sweden, and Finland are concentrating demand for high-capacity thermal outputs that validate next-generation heat pump performance.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger coil manufacturing faces margin compression from base metal commodity swings that suppliers cannot fully pass through under municipal tender pricing.
- Component supply concentration:Compressor and electronic expansion valve production clusters in Germany and Italy create single-source vulnerability for system integrators.
- KBA type-approval timelines:Germany's Federal Motor Transport Authority extends certification protocols for novel thermal architectures, delaying product launches by 12-18 months.
Strategic Opportunities
- Eastern European fleet modernization:Poland, Romania, and Czech Republic municipal operators are beginning zero-emission pilot programs that lack established HVAC supplier relationships.
- Depot infrastructure thermal integration:Battery conditioning and cabin climate systems are converging, creating bundled procurement opportunities for platform-level thermal management.
- Software-defined service contracts:Predictive maintenance algorithms and over-the-air calibration are enabling recurring revenue streams beyond hardware installation.
Industry Challenges
- Refrigerant handling certification gaps:Fleet maintenance technicians lack training in low-GWP refrigerant recovery protocols required by EU F-Gas Regulation amendments.
- Legacy depot electrical capacity:Aging grid connections in French and Italian municipal facilities cannot support simultaneous bus charging and high-draw heat pump operation without costly infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bus HVAC Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split System, Rooftop Unit, Underfloor System, Integrated System Technology: Refrigeration, Heat Pump, Radiant Heating, Ventilation End User: Public Transport, Private Coaches, School Buses, Tour Buses Installation: OEM, Retrofit, Aftermarket, Custom Installations |
| Companies Covered | Webasto, Valeo, Thermo King, Denso Corporation, MAHLE, Eberspächer, Carrier, Hanon Systems, Bosch, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bus HVAC Market Trends and Innovations
Electrification is collapsing the traditional separation between vehicle propulsion and cabin thermal management, forcing convergence in system architecture and procurement specifications.
Heat pump technology is consolidating its position as the dominant thermal architecture for battery-electric buses. These systems extract ambient heat for cabin warming rather than consuming battery energy through resistive elements. Municipal operators in Denmark and the Netherlands are specifying heat pump-only configurations in new tenders. This transition is consolidating supplier portfolios around refrigerant architectures that satisfy both heating performance and F-Gas compliance.
The EU F-Gas Regulation phase-down schedule is tightening refrigerant GWP limits through 2030. System manufacturers must revalidate component portfolios against declining threshold values while maintaining thermal output density. Rooftop unit suppliers serving German and French markets are accelerating R-454B and R-1234yf transitions ahead of regulatory deadlines.
Municipal procurement offices are unbundling hardware purchase from lifecycle service obligations. Tender structures now separate initial system supply from ten-year maintenance and refrigerant management contracts. This pattern is most visible in Swedish and Norwegian transit authorities, where total-cost-of-ownership calculations dominate award criteria over upfront capital expenditure.
Europe Bus HVAC Market Segmentation
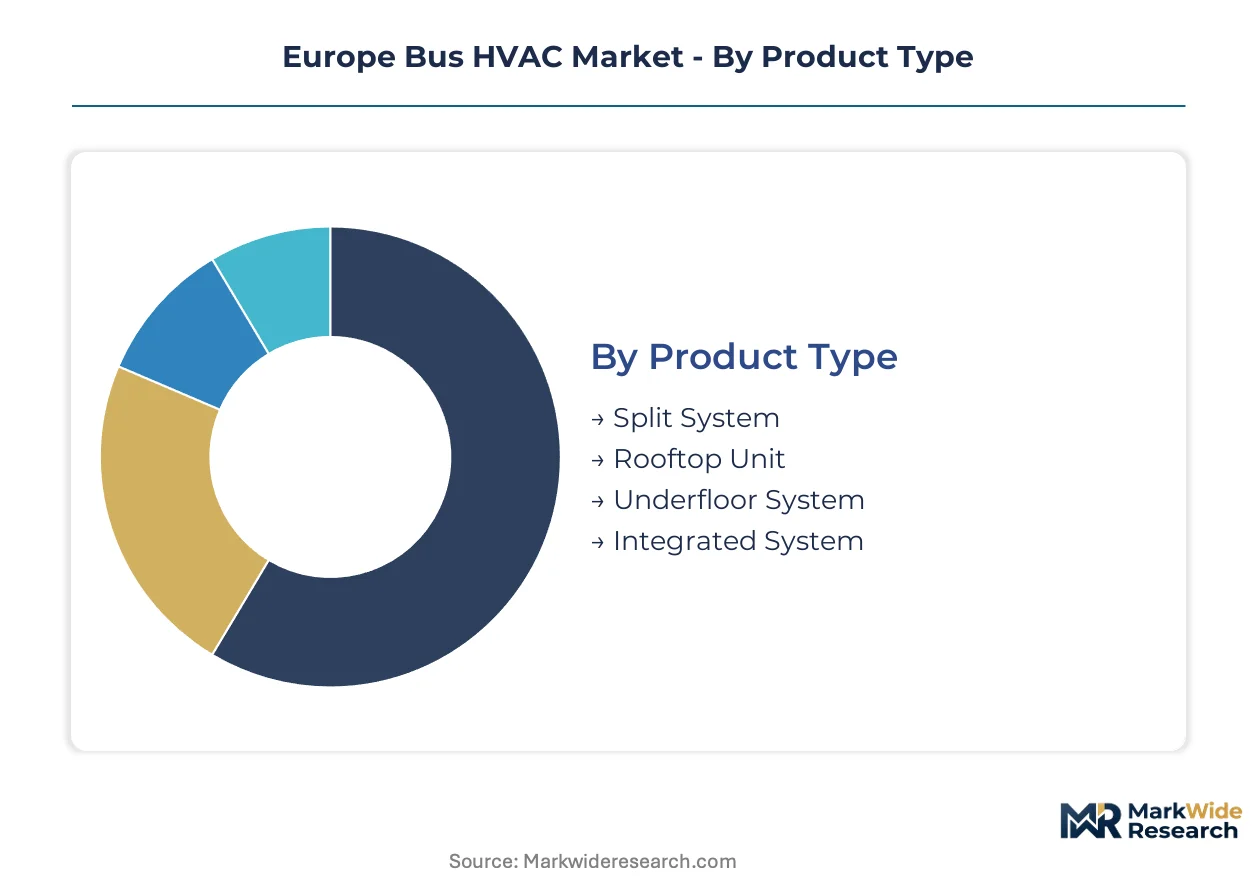
Bus HVAC procurement decisions in Europe hinge on thermal load coordination with electric drivetrains, refrigerant compliance deadlines, and depot infrastructure constraints. Fleet operators weigh upfront system cost against decade-long energy consumption and service obligations under municipal tender rules.
Product Type:
Packaging geometry and service accessibility dominate buyer selection as electric bus architectures constrain underhood space and rooftop load distribution.
- Rooftop Unit:Self-contained modules mount above passenger cabins, enabling rapid depot-level swap-out without bay downtime. Urban single-deck deployments across German and Dutch transit authorities concentrate here due to packaging efficiency and technician familiarity.
- Integrated System:Cabin climate and battery conditioning circuits share refrigerant loops and control electronics, reducing energy draw through unified thermal management. Battery-electric platforms from French and Nordic OEMs are standardizing this architecture to meet range targets under EU Green Deal procurement rules.
- Split System:Compressor and evaporator assemblies separate across vehicle zones, suiting double-deck configurations with constrained rooftop space.
- Underfloor System:Low-profile units fit beneath chassis rails in legacy diesel conversions where roof reinforcement is impractical.
Volume sits with Rooftop Unit; growth tilts toward Integrated System.
Technology:
Energy source for cabin heating determines total cost of ownership calculations as electricity displaces combustion-derived thermal energy.
- Heat Pump:Ambient heat extraction delivers three to four units of cabin warming per unit of electrical input versus resistive heating. Danish and Norwegian municipal tenders now mandate heat pump-only specifications, validating performance in sub-zero Nordic corridor conditions.
- Refrigeration:Vapor-compression cooling remains baseline for summer load management, though heating function is being stripped from these systems in favor of dedicated heat pump circuits.
- Radiant Heating:Electric panel and infrared emitters supplement perimeter zones in severe climate deployments where heat pump capacity fades at extreme ambient temperatures.
- Ventilation:Filtered air exchange without active thermal conditioning serves mild climate corridors and auxiliary passenger compartment isolation.
Refrigeration retains installed base dominance; heat pump architectures are climbing the fastest as fleet electrification mandates harden.
End User:
Route predictability and duty cycle intensity shape thermal system specification durability and redundancy requirements.
- Public Transport:High-frequency urban operations with stop-and-go thermal loads demand rapid cabin recovery and passenger door air curtains. German and French municipal authorities bundle HVAC specifications into ten-year service contracts with total-cost-of-ownership pricing.
- Private Coaches:Intercity operators prioritize lightweight rooftop units with modulated capacity for variable occupancy loads on long-haul routes.
- School Buses:Part-day duty cycles with extended idle periods suit simplified ventilation-dominant systems in Southern European climate zones.
- Tour Buses:Premium passenger expectations drive multi-zone climate control with rapid cool-down capability for summer alpine and Mediterranean deployments.
Public Transport commands procurement volume; Private Coaches show steepest specification upgrade intensity as coach electrification pilots expand.
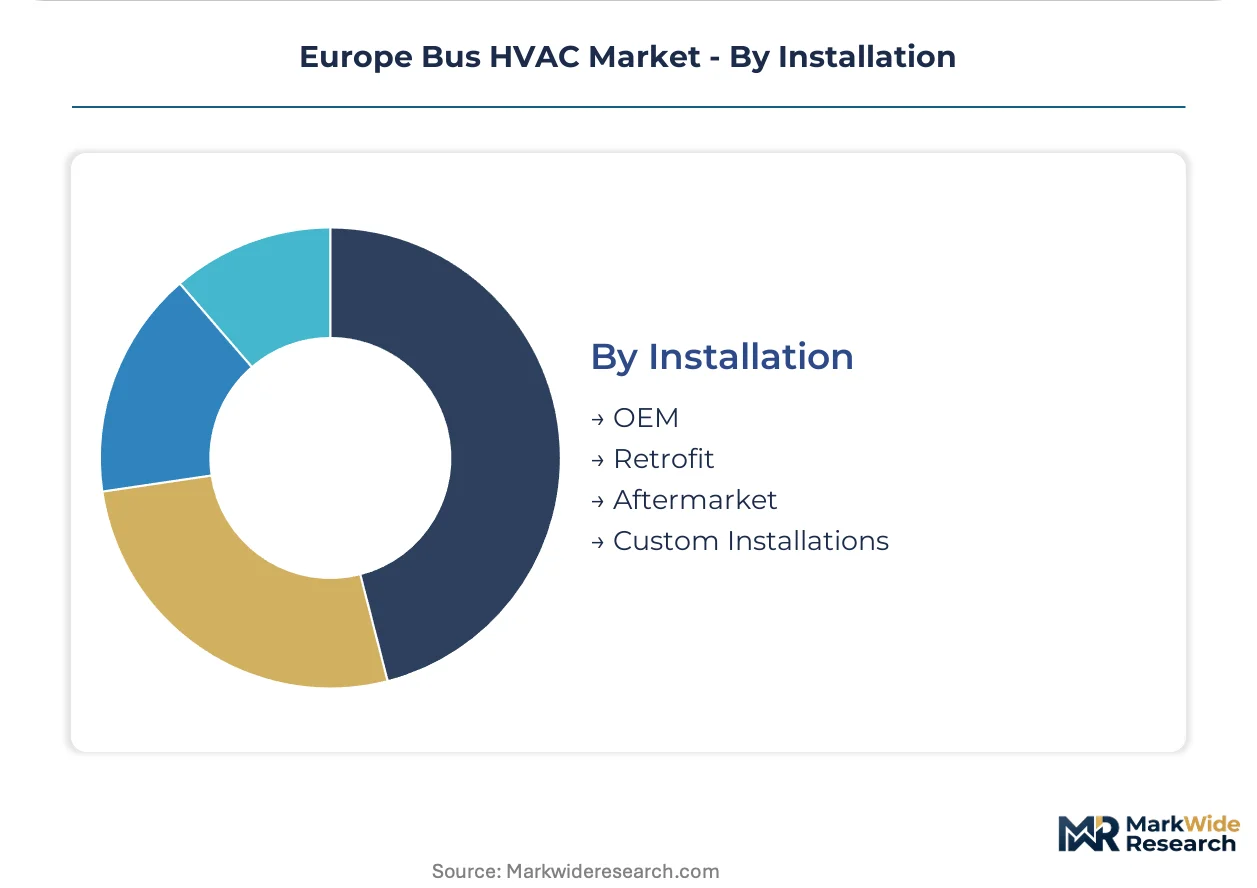
Installation:
Procurement channel structure determines margin capture between hardware manufacturers and service providers across fleet replacement cycles.
- OEM:Factory-integrated thermal systems ship with vehicle platform validation, locking refrigerant charge and control calibration to manufacturer specifications. Battery-electric bus platforms from Swedish and German OEMs are consolidating HVAC sourcing into platform-level thermal management contracts.
- Retrofit:Climate system replacement on mid-life diesel buses extends depot serviceability, though declining fleet sizes limit addressable market expansion.
- Aftermarket:Independent service networks handle refrigerant recovery, compressor replacement, and control module refurbishment outside OEM captive channels.
- Custom Installations:Specialized vehicle modifiers configure thermal systems for disability-accessible and premium-specification coaches outside standard product lines.
OEM integration captures value share; Aftermarket service contracts are gaining share fastest as municipal procurement unbundles hardware from lifecycle obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers concentrate heat pump component manufacturing, while Nordic transit authorities consume the highest per-unit thermal capacity. Eastern European depots import retrofit systems as electrification pilots expand. Southern European operators balance cooling loads against mild winter heating requirements.
Germany
KBA type-approval protocols extend certification timelines for novel thermal architectures, delaying product launches by 12-18 months. The EU F-Gas Regulation phase-down schedule tightens refrigerant GWP limits through 2030, compelling suppliers to revalidate component portfolios. Stuttgart and Munich host engineering clusters where Webasto and MAHLE refine low-GWP heat pump systems for battery-electric bus platforms.
France
Municipal procurement offices unbundle hardware purchase from lifecycle service obligations, separating initial supply from ten-year maintenance contracts. The EU Green Deal zero-emission mandates accelerate replacement cycles for compatible HVAC systems in Paris and Lyon depots. Thermo King anchors its position through captive service networks spanning depot infrastructure across France and Benelux.
Netherlands
Denmark and Dutch municipal tenders now mandate heat pump-only specifications, validating performance in variable climate conditions. The EU Ecodesign Directive constrains minimum efficiency thresholds for thermal systems deployed in Rotterdam and Amsterdam transit fleets. Valeo sustains engineering intensity in refrigerant architectures aligned with F-Gas compliance deadlines.
Sweden
Extended heating seasons in Nordic corridors concentrate demand for high-capacity thermal outputs exceeding 35 kW. Total-cost-of-ownership calculations dominate award criteria over upfront capital expenditure in Stockholm and Gothenburg procurement frameworks. Aftermarket software-defined thermal management enables predictive maintenance algorithms and recurring service revenue streams.
Poland
Municipal operators in Warsaw and Krakow launch zero-emission pilot programs lacking established HVAC supplier relationships. Fleet electrification creates bundled procurement opportunities for platform-level thermal management integrating battery conditioning with cabin climate. Eastern European fleet modernization attracts system integrators seeking to capture replacement demand ahead of regulatory mandate synchronization.
Europe Bus HVAC Market Competitive Landscape
Top-tier vendors anchor platform-level thermal management contracts, while mid-tier fabricators compete on retrofit connectivity and depot service reach. The supplier base organizes around three strategic archetypes: integrated system architects, rooftop module specialists, and aftermarket service platform operators. Consolidation pressure intensifies as municipal procurement unbundles hardware from decade-long maintenance obligations. Dominant competitive moves include captive service network expansion and refrigerant portfolio revalidation against declining GWP thresholds.
Among German-based engineering groups, Webasto, MAHLE, and Eberspächer exemplify the integrated system architect archetype, anchoring positions through in-house heat pump development and KBA certification expertise. Valeo represents the cross-border refrigerant specialist tier, while Thermo King occupies a position within the captive service platform category. Denso Corporation and Hanon Systems sit within the scale-driven Asian supplier segment, competing on component manufacturing efficiency for European OEM integration programs. Bosch exemplifies the diversified industrial conglomerate model, leveraging thermal management know-how across automotive and commercial vehicle applications.
| Leading Market Players |
|---|
| Webasto |
| Valeo |
| Thermo King |
| Denso Corporation |
| MAHLE |
| Eberspächer |
| Carrier |
| Hanon Systems |
| Bosch |
| Others |
Pricing and Supply Chain Analysis
Heat pump architecture transitions are simultaneously elevating R&D cost intensity and concentrating supplier leverage among refrigerant-certified manufacturers. Municipal tender unbundling is decoupling hardware margins from service revenue capture, forcing system integrators to restructure cost allocation across decade-long maintenance obligations.
Pricing Analysis
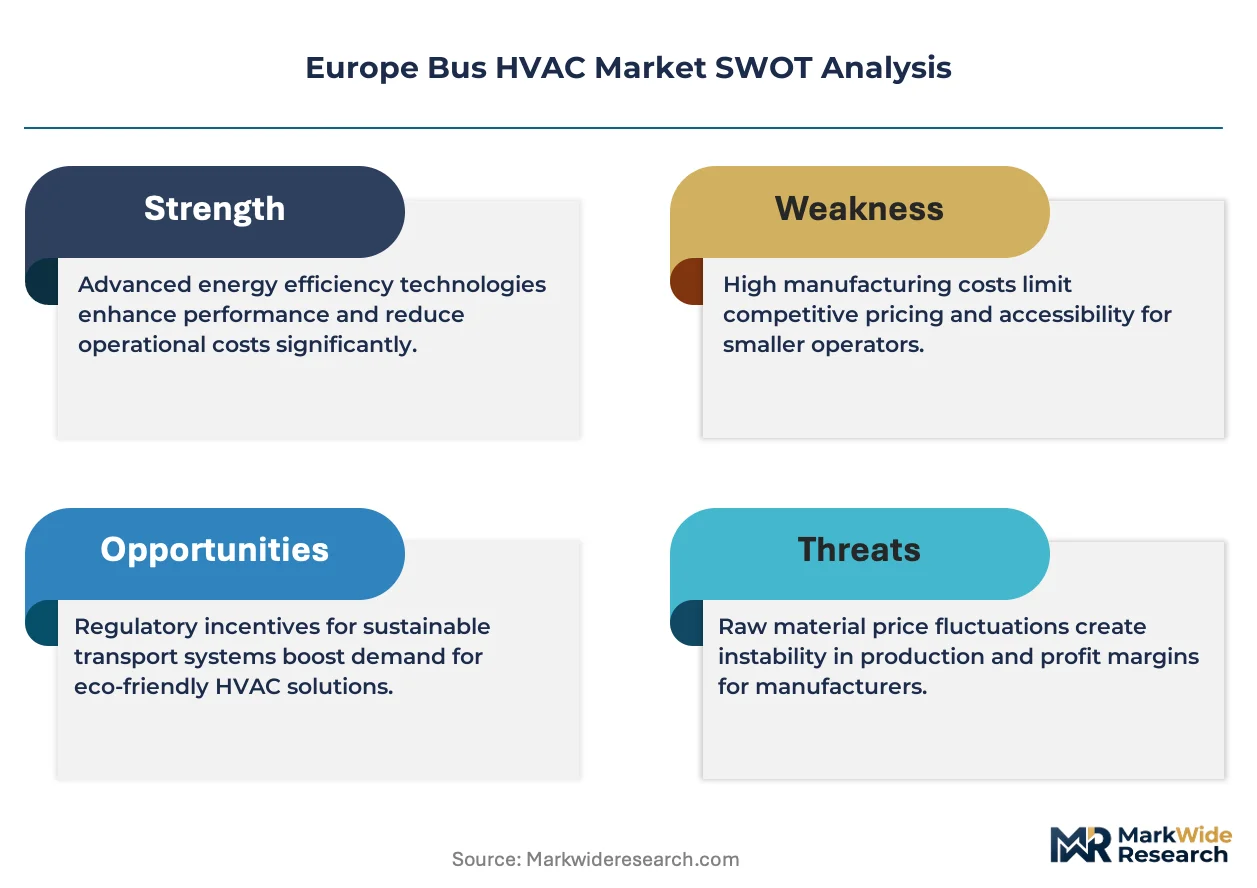
Margin tightening in integrated thermal systems reflects copper and aluminum commodity volatility that compresses heat exchanger fabrication economics. Three-tier pricing structure across premium, standard, and economy levels separates OEM-validated heat pump platforms from retrofit rooftop modules and basic ventilation units. Price differentiation hinges on F-Gas refrigerant certification tier and bundled depot service contract duration. Eastern European municipal operators exhibit highest price sensitivity; Nordic transit authorities prioritize thermal output density over upfront capital expenditure.
Supply Chain Analysis
Dual-sourcing mandates from German and French OEMs require compressor and electronic expansion valve qualification across multiple component suppliers. Manufacturing gravity centers on Germany, Italy, and Poland for heat pump assembly, with refrigerant charge operations concentrated near KBA certification facilities. Critical inputs span low-GWP refrigerant formulations, copper tubing, and power electronics for variable-speed compressor drives. Single-source vulnerability in German and Italian valve production creates tariff-exposed chokepoints. Distribution runs through captive depot service networks and independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Bus HVAC Market is executing a technology-transition phase as heat pump architectures displace conventional vapor-compression heating across battery-electric platforms.
For Market Incumbents: To counter margin compression from commodity-exposed heat exchanger manufacturing, anchor position through captive refrigerant handling certification programs and backward integration into compressor assembly. Prioritize KBA type-approval pipeline investment to compress 12-18 month certification timelines for novel thermal architectures. For New Entrants and Emerging Players: Eastern European municipal operators launching zero-emission pilot programs represent the most penetrable buyer archetype lacking established HVAC supplier relationships. Target Poland, Romania, and Czech Republic depot infrastructure projects with platform-level thermal management bundling battery conditioning and cabin climate. Lead with software-defined predictive maintenance contracts to capture recurring revenue ahead of hardware procurement decisions. For Investors and Strategic Acquirers: Re-rating potential sits with refrigerant-specialist component manufacturers given EU F-Gas phase-down acceleration and declining GWP threshold compliance requirements. Long-term viability favors suppliers with validated low-GWP portfolios and captive service network density. Monitor national zero-emission fleet mandate synchronization with TCO-based procurement frameworks as inflection signal for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Platform Standardization | Unifies battery conditioning and cabin climate circuits under single refrigerant architecture for range optimization. |
| Backward Integration into Compressor Manufacturing | Secures supply of variable-speed drives for low-GWP refrigerant systems amid German-Italian production concentration. |
| Depot Service Network Expansion | Thermo King's captive infrastructure model across France and Benelux locks in decade-long maintenance revenue streams. |
| Refrigerant Portfolio Revalidation | Webasto and MAHLE accelerate R-454B and R-1234yf transitions ahead of EU F-Gas 2030 thresholds. |
| Software-Defined Thermal Management | Enables predictive maintenance algorithms and over-the-air calibration for recurring service revenue beyond hardware. |
Research Methodology
Document review covered EU F-Gas Regulation amendments, KBA type-approval protocols, and municipal tender specifications from Germany, France, and the Netherlands, complemented by interviews with thermal system engineering directors, fleet procurement managers at transit authorities, refrigerant handling certification trainers, and depot infrastructure planners. Secondary validation drew from OEM platform engineering disclosures, component supplier SEC filings, and Nordic corridor climate performance test data. Bottom-up unit economics and top-down fleet replacement projections were triangulated against manufacturer capacity announcements.
Historical installation volumes were cross-referenced against panel input from municipal procurement officers to anchor baseline assumptions. The analytical framework modeled product type, technology architecture, and end-use application across the projection horizon, with vehicle class and regional regulatory cluster as additional segmentation dimensions. CAGRs were derived from replacement cycle timing under national zero-emission mandates and heat pump penetration curves validated by Danish and Norwegian tender specifications. Bus fleet electrification schedules and copper price trajectory sensitivity informed scenario boundaries.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas amendment timing and KBA certification backlog duration. Forecasts reflect assumptions around refrigerant transition compliance cost pass-through and municipal budget continuity. A model refresh is warranted upon material change in national zero-emission fleet mandate deadlines or heat pump performance validation failures in sub-zero Nordic corridor conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Blowers Market
HVAC Equipment
United States Air Conditioning Equipment Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Industrial Air Heaters Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
US Compressed Air Treatment Equipment Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Recirculating Chillers Market