
 United Kingdom HVAC Market | 2026-2036
United Kingdom HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom HVAC Market Insights
Market Context
F-Gas Regulation is shifting the cost-of-entry calculus for equipment suppliers serving the United Kingdom. Johnson Controls International plc leverages its chiller refurbishment network to capture retrofit workflows across NHS estates and university campuses. Daikin Industries Ltd anchors its position through captive heat pump manufacturing in Europe, insulating UK operations from tariff volatility. Mitsubishi Electric Corporation specializes in ductless VRF configurations that align with Part L conservation targets for commercial envelopes.
Technical Definition and Segment Structure
Heating, ventilation, and air conditioning encompasses electromechanical systems that regulate thermal comfort, air quality, and humidity within built environments, typically operating across refrigerant cycles with working pressures between 15 and 45 bar and temperature deltas of 5 to 12 Kelvin. The primary purpose spans occupant health protection, process climate control for manufacturing, and energy load management in conditioned spaces. Heat pump installations lead volume growth across the residential end user segment, while smart thermostat integration concentrates margin pools in the commercial technology tier. Chillers retain structural importance in the hospitality and industrial sectors despite longer replacement cycles. Retrofit installation types now outpace new construction flows as building regulations tighten operational carbon thresholds.
Regulatory Frame and Outlook
MEES, the UK Building Regulations Part L, and the F-Gas Regulation collectively shape equipment specifications, refrigerant selections, and compliance documentation burdens for market participants. The Boiler Upgrade Scheme channels subsidy flows toward air-source and ground-source heat pumps, while Part F ventilation mandates drive mechanical extraction upgrades in dense urban housing stock. Stakeholders must monitor the trajectory of hydrogen-ready boiler deliberations and their potential to bifurcate investment between electrification and blended fuel pathways.
Market Dynamics
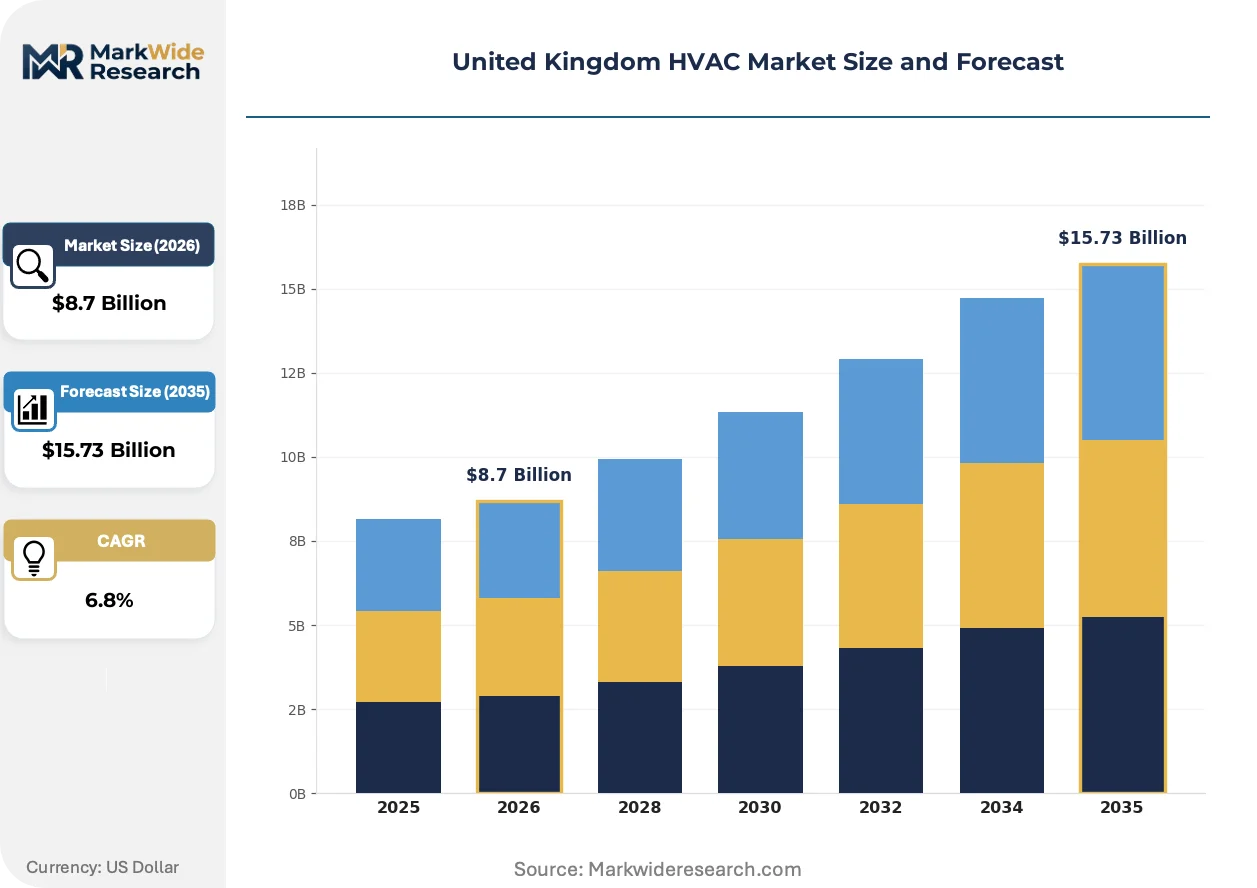
The UK HVAC sector is contending with a forced refrigerant transition as F-Gas Regulation tightens GWP thresholds, compressing equipment replacement cycles and elevating refurbishment economics against new unit sales.
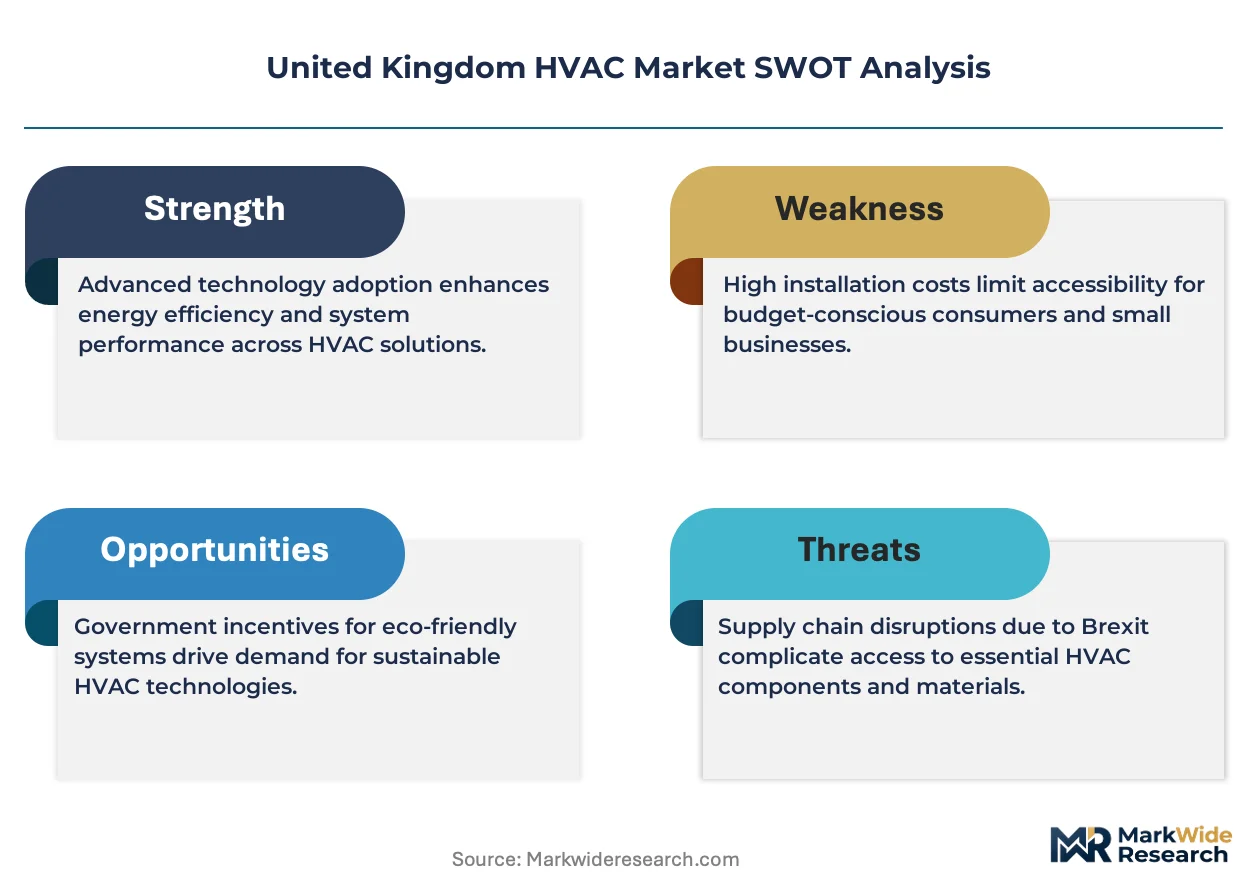
Growth Catalysts
- Boiler Upgrade Scheme:Subsidy flows for air-source and ground-source heat pumps are accelerating deployment in social housing retrofits across England and Wales.
- Part L conservation targets:Building regulations mandating operational carbon reductions are forcing commercial envelope upgrades that bundle HVAC replacement with fabric improvements.
- Midlands commercial stock:New-build office and logistics development in Birmingham and Manchester corridors is generating concentrated demand for VRF and chiller installations.
Market Restraints
- Copper and aluminum input volatility:Raw material price swings for heat exchanger metals are compressing fabrication margins and delaying contractor quoting cycles.
- Refrigerant supply concentration:Lower-GWP alternatives remain concentrated among limited European chemical suppliers, creating allocation risk during peak installation seasons.
- Hydrogen-ready boiler uncertainty:Pending deliberations on blended fuel pathways are freezing investment decisions in some residential gas-to-heat pump transitions.
Strategic Opportunities
- NHS estate refurbishment:Hospital backlog maintenance programs represent underpenetrated demand for chiller modernization and air handling unit replacement.
- Smart thermostat convergence:Integration of HVAC controls with building energy management systems opens margin pools in commercial technology tiers.
- Scottish social housing:Devolved administration efficiency targets are channeling capital toward heat pump rollout in Glasgow and Edinburgh municipal stock.
Industry Challenges
- F-Gas certification bottlenecks:Technician requalification timelines for lower-GWP refrigerant handling are constraining installation capacity during peak demand windows.
- Legacy BMS integration:Mechanical interoperability gaps between new heat pump units and existing building management infrastructure are extending project commissioning phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom HVAC Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioners, Heat Pumps, Furnaces, Chillers Technology: R32 Refrigerant, Variable Refrigerant Flow, Smart Thermostats, Ductless Systems End User: Residential, Commercial, Industrial, Hospitality Installation Type: Retrofit, New Construction, Modular, Centralized |
| Companies Covered | Daikin Industries Ltd, Johnson Controls International plc, Carrier Global Corporation, Mitsubishi Electric Corporation, Trane Technologies plc, Lennox International Inc, Bosch Thermotechnology, Systemair AB, Vaillant Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom HVAC Market Trends and Innovations
Electrification of thermal systems is intersecting with digital control layers to reshape equipment specifications, service models, and installer capabilities across UK building stock.
R32 and R454B refrigerant platforms are rewriting equipment replacement economics as manufacturers retool production lines ahead of GWP threshold reductions. Social landlords and housing associations are specifying these units in bulk procurement frameworks to lock in compliance. The shift is compressing residual value for R410A inventory and accelerating secondary market discounting.
MEES and Part L are tightening operational carbon thresholds for commercial leases and new construction. Property investors are bundling HVAC upgrades with fabric improvements to avoid rental voids from efficiency non-compliance. Retail and hospitality assets in London and Southeast England are experiencing the most concentrated compliance-driven replacement cycles.
Service unbundling is fragmenting traditional maintenance contracts as facility managers separate controls optimization from mechanical servicing. Third-party energy performance contractors are capturing monitoring and optimization work that incumbent installers previously bundled. University campuses and local authority portfolios are piloting this split most aggressively.
United Kingdom HVAC Market Segmentation
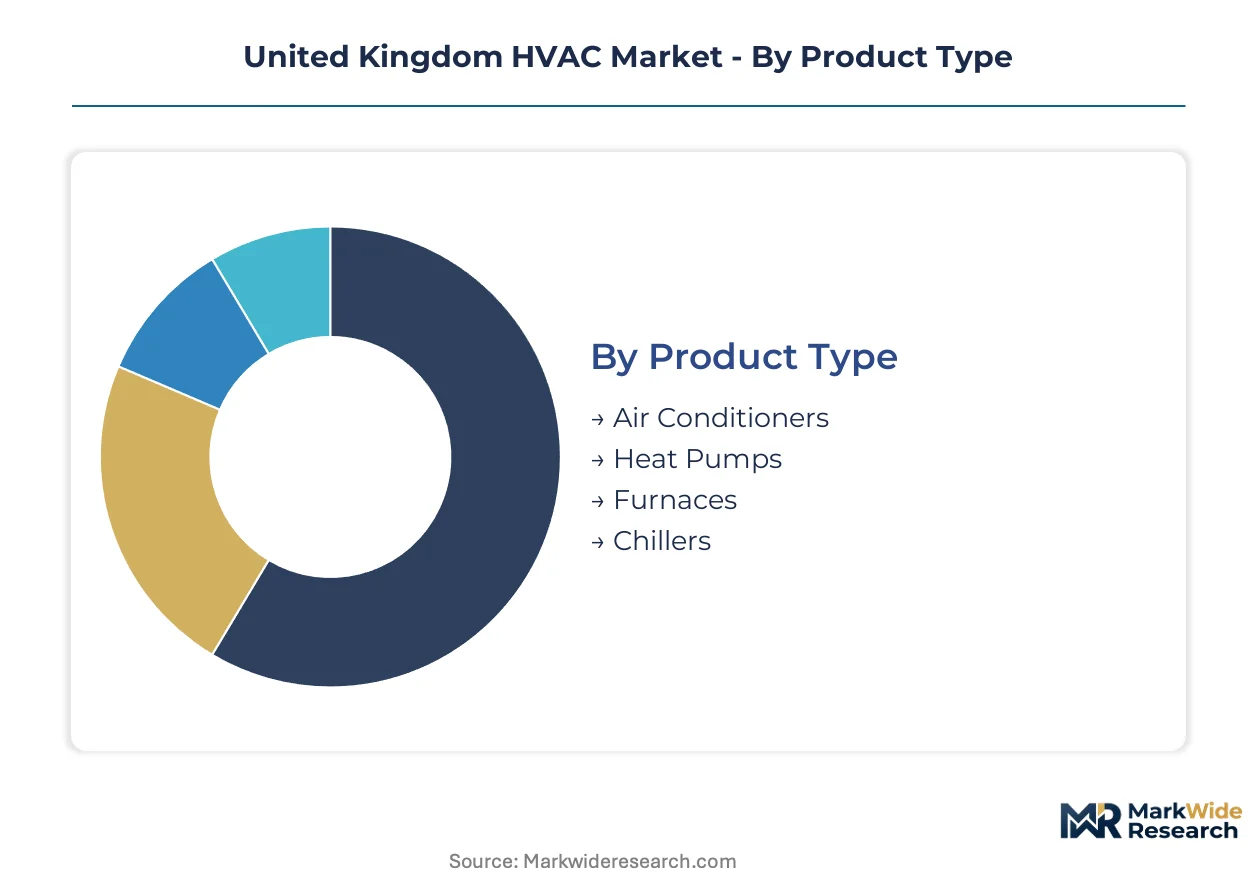
Segmentation in the UK HVAC market reveals distinct procurement patterns across product architectures and deployment contexts. Equipment specification diverges sharply between integrated new-build systems and standalone retrofit replacements, with regulatory compliance timelines driving category prioritization.
Product Type:
Integration depth varies substantially across product categories, with some systems designed for standalone deployment while others require embedded building infrastructure.
- Heat Pumps:Electromechanical systems that extract thermal energy from ambient air, ground, or water sources to deliver space heating and cooling through hydronic or forced-air distribution. Deployment concentrates in social housing retrofits across England and Wales as the Boiler Upgrade Scheme channels subsidy flows toward air-source and ground-source configurations.
- Air Conditioners:Vapor-compression cooling equipment ranging from residential split units to commercial rooftop packages, operating on refrigerant cycles with typical cooling capacities. Demand clusters in Southeast England commercial stock where Part L conservation targets are forcing envelope upgrades that bundle cooling replacement with fabric improvements.
- Chillers:Centralized refrigeration plants serving large commercial and institutional cooling loads through chilled water distribution networks.
- Furnaces:Fossil-fuel combustion heating equipment, predominantly natural gas-fired, facing phased obsolescence under decarbonization mandates.
Volume placements concentrate in heat pumps; the faster expansion belongs to air conditioners.
Technology:
Cost tier differentiation separates premium refrigerant platforms from legacy equipment, with compliance-driven obsolescence compressing residual value for non-compliant inventory.
- R32 Refrigerant:Lower-GWP hydrofluorocarbon working fluid with approximately one-third the global warming potential of R410A, requiring equipment redesign for higher operating pressures. Adoption accelerates in manufacturer production lines ahead of F-Gas Regulation threshold reductions, with social landlords specifying these units in bulk procurement frameworks to lock in compliance.
- Variable Refrigerant Flow:Multi-zone heat pump architecture enabling simultaneous heating and cooling across building zones with individual evaporator control. Deployment concentrates in Midlands commercial new-build corridors where Birmingham and Manchester office developments generate concentrated demand for flexible thermal zoning.
- Smart Thermostats:Networked control devices enabling remote scheduling, occupancy sensing, and integration with building energy management systems.
- Ductless Systems:Mini-split and multi-split configurations eliminating air distribution ductwork through direct refrigerant piping to wall-mounted or ceiling-cassette terminals.
Margin pools concentrate in variable refrigerant flow; smart thermostats are climbing the fastest.
End User:
Application context determines specification complexity, with industrial process loads demanding precision control that residential comfort applications do not require.
- Residential:Single-family and multi-family dwellings where thermal comfort drives specification, with electrification mandates accelerating heat pump substitution for gas boilers. Deployment concentrates in social housing retrofits across England and Wales as the Boiler Upgrade Scheme subsidizes air-source and ground-source installations.
- Commercial:Office, retail, and institutional buildings where operational carbon compliance drives bundled HVAC and fabric upgrades. Demand clusters in London and Southeast England assets where MEES efficiency thresholds threaten rental voids for non-compliant landlords.
- Industrial:Manufacturing and process facilities requiring precise temperature and humidity control for production quality.
- Hospitality:Hotels and restaurants where guest comfort expectations intersect with high ventilation requirements and intermittent occupancy patterns.
Capital deployment concentrates in commercial; residential is gaining share fastest.
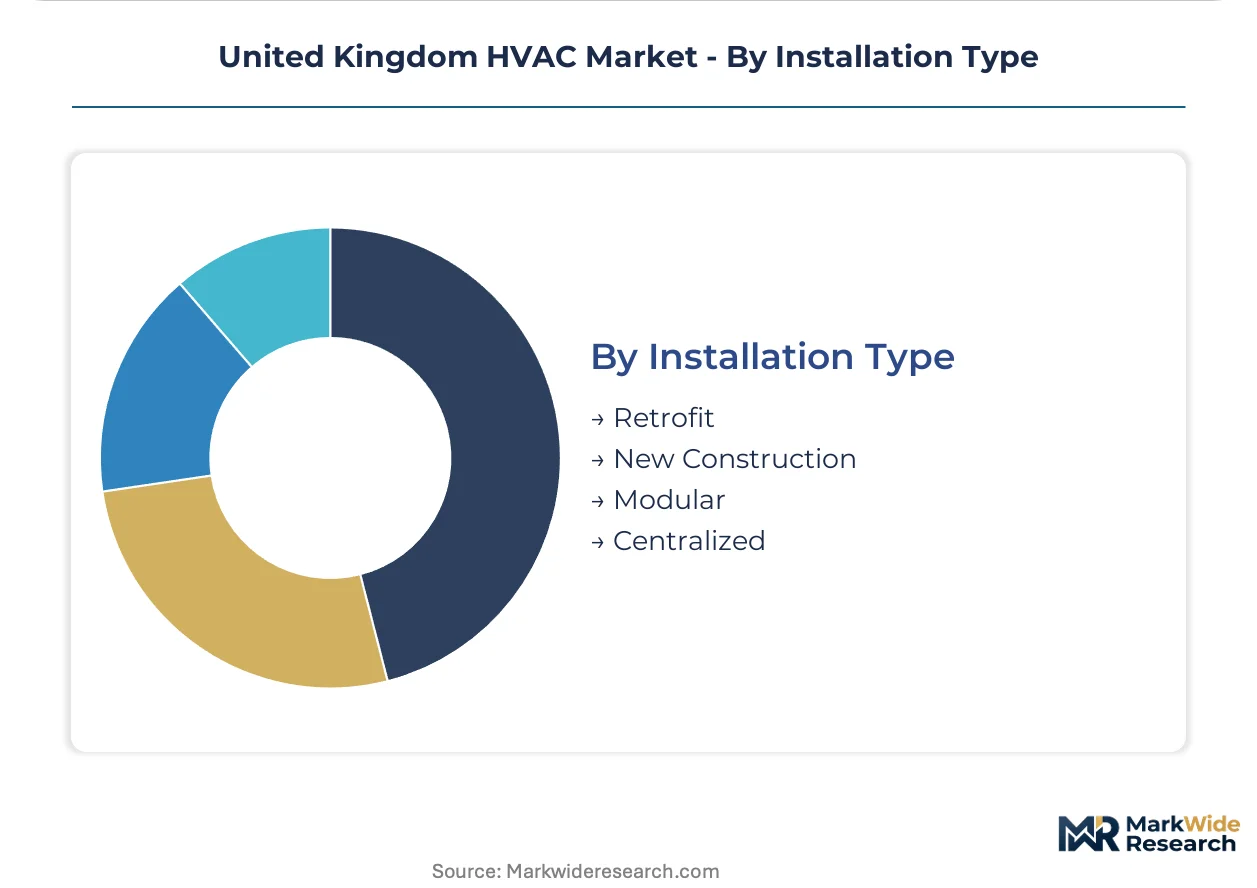
Installation Type:
Customer type segmentation separates owner-occupied decision-makers from tenant-facing landlords with different payback horizon requirements.
- Retrofit:Replacement of existing HVAC equipment within operational building envelopes, now outpacing new construction flows as building regulations tighten operational carbon thresholds. Deployment concentrates in NHS estate refurbishment programs where hospital backlog maintenance represents underpenetrated demand for chiller modernization and air handling unit replacement.
- New Construction:Integrated system design within buildings under development, enabling optimized equipment sizing and distribution architecture. Demand clusters in Midlands logistics and office developments where Birmingham corridor construction generates concentrated VRF and chiller procurement.
- Modular:Prefabricated plant room or rooftop units enabling rapid deployment with minimized on-site construction.
- Centralized:Single-source thermal generation serving multiple zones or buildings through district distribution networks.
Project pipelines concentrate in retrofit; modular configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freeport status and enterprise zone designations across England are concentrating HVAC procurement around tax-advantaged logistics corridors and social housing retrofit clusters.
London and Southeast England
Commercial lease compliance under MEES is forcing bundled HVAC and fabric upgrades in retail and hospitality assets. The Boiler Upgrade Scheme channels subsidy flows toward heat pump installations in Greater London social housing stock. Thames Freeport logistics developments generate concentrated demand for VRF and chiller systems in distribution facilities.
Midlands
Birmingham and Manchester corridor construction is driving new-build office and logistics development with integrated HVAC specifications. Part L conservation targets mandate operational carbon reductions that bundle mechanical upgrades with envelope improvements. East Midlands Freeport incentives are accelerating warehouse and manufacturing facility commissioning with centralized plant installations.
North England
Industrial heritage building conversions require specialized retrofit HVAC solutions for mixed-use redevelopment. Northern Powerhouse investment programs channel capital toward municipal building efficiency upgrades. Manchester and Leeds city centers exhibit concentrated demand for ductless VRF configurations in constrained envelope retrofits.
Scotland
Devolved administration efficiency targets are directing social housing capital toward heat pump rollout in Glasgow and Edinburgh municipal stock. Scottish Building Standards exceed UK baseline requirements for thermal performance and ventilation. Aberdeen's energy sector transition is repurposing engineering capabilities toward district heating and commercial HVAC servicing.
Wales
Social housing decarbonization programs prioritize heat pump deployment in Valleys communities with high fuel poverty indices. Welsh Government procurement frameworks specify lower-GWP refrigerant platforms for public sector buildings. Cardiff and Newport commercial development generates demand for modular plant room configurations in constrained urban sites.
United Kingdom HVAC Market Competitive Landscape
Japanese and European producers anchor the premium equipment tier; North American specialists hold positions in building automation and controls integration. The vendor base exhibits moderate concentration with five to seven firms capturing disproportionate share in heat pump and chiller categories. Two strategic archetypes dominate: diversified industrial conglomerates with captive refrigerant supply chains, and climate-control pure-plays with deep installer network relationships. Competitive moves center on refurbishment service bundling and smart control platform integration rather than capacity expansion.
Within the diversified conglomerate tier, Daikin Industries Ltd and Mitsubishi Electric Corporation exemplify Japanese manufacturers with European production footprints insulating UK operations from tariff exposure. Johnson Controls International plc anchors the building automation vector through chiller refurbishment networks serving NHS estates and university campuses. These three firms occupy positions spanning equipment supply through lifecycle service contracts, representing distinct responses to F-Gas Regulation compliance pressures and electrification mandates.
| Leading Market Players |
|---|
| Daikin Industries Ltd |
| Johnson Controls International plc |
| Carrier Global Corporation |
| Mitsubishi Electric Corporation |
| Trane Technologies plc |
| Lennox International Inc |
| Bosch Thermotechnology |
| Systemair AB |
| Vaillant Group |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange copper price volatility cascades through UK HVAC fabrication tiers, compressing margins for heat exchanger manufacturers while elevating refurbishment economics against new unit procurement. This input cost pressure stratifies pricing across installer networks serving social housing landlords, commercial property investors, and industrial facility managers with divergent payback horizons.
Pricing Analysis
Lead-time premiums dominate contractor quoting cycles, with spot inventory from R410A equipment liquidators trading at steep discounts against R32-compliant units with extended manufacturer backlogs. Three-tier pricing structure across premium, standard, and economy levels separates F-Gas-certified turnkey installations from basic equipment supply and secondary-market refurbished chillers. Price differentiation hinges on refrigerant platform compliance grade and after-sales service bundling. Cost compression in economy tiers is intensifying because raw material volatility forces fabricators to absorb margin erosion rather than pass through to price-sensitive social housing procurement frameworks. Social landlords exhibit highest price sensitivity; NHS estates and university campuses demonstrate lowest sensitivity due to capital availability and compliance-driven replacement mandates.
Supply Chain Analysis
Direct-to-contractor channels handle residential retrofit demand, while specification-influencer routes through M&E consultants dominate commercial new-build procurement. Manufacturing concentration rests on Germany, Japan, and China for compressor assemblies, heat exchanger coils, and electronic control modules. Raw material dependencies draw from Chilean copper cathode, Russian aluminum billet, and Chinese rare-earth magnet feedstock. Single-source vulnerability concentrates in lower-GWP refrigerant supply from limited European chemical producers. Distribution runs through national wholesaler networks with regional branch stockholding, supplemented by direct OEM relationships for large-scale commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK HVAC sector is consolidating around F-Gas compliance capabilities, with refrigerant transition timelines forcing smaller installers without technician requalification capacity toward acquisition or exit. Equipment suppliers lacking captive European manufacturing face tariff exposure and margin compression that favors scaled conglomerates.
For Market Incumbents: Anticipate technician certification bottlenecks constraining installation capacity during peak demand windows by accelerating in-house training academy investments ahead of R454B platform rollouts. Consolidate position through selective acquisition of regional service contractors with established NHS estate relationships, leveraging refurbishment workflows to defend against new equipment commoditization. F-Gas Regulation trajectory represents the primary threat; backward integration into refrigerant reclamation services offers margin protection. For New Entrants and Emerging Players: Smart thermostat integration with legacy BMS infrastructure offers a technology-first wedge into commercial building energy management, where incumbent mechanical installers lack software capabilities. Target Scottish social housing decarbonization programs as the most penetrable geography, where devolved administration efficiency targets channel capital toward heat pump rollout with less entrenched supplier relationships. Pursue energy-performance-contracting go-to-market models that separate controls optimization from mechanical servicing. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap HVAC service specialists with NHS estate contracts in England's North and Midlands, where hospital backlog maintenance programs represent underpenetrated demand. Long-term viability hinges on electrification mandate durability and hydrogen-ready boiler pathway abandonment. Monitor Boiler Upgrade Scheme subsidy trajectory as the critical inflection signal for residential heat pump deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Requalification Investment | F-Gas certification capacity separates compliant installers from regulatory exclusion. |
| Refrigerant Reclamation Infrastructure | Backward integration into refrigerant recovery services captures circular economy margins. |
| Smart Controls Platform Development | BMS interoperability gaps extend commissioning phases and create software attach opportunities. |
| NHS Estate Service Contracting | Hospital backlog maintenance programs concentrate demand for chiller modernization. |
| Scottish Social Housing Partnership | Devolved administration efficiency targets channel capital toward municipal stock electrification. |
Research Methodology
Trade association filings, customs import records, and building control approval databases formed the secondary backbone, supplemented by manufacturer production disclosures and refrigerant supplier allocation reports. Primary fieldwork encompassed interviews with M&E consultants, social housing procurement directors, NHS estates managers, HVAC contractor owner-operators, and F-Gas certification body administrators. Bottom-up equipment shipment analysis triangulated against top-down construction output metrics and regulatory compliance timelines.
Historical trendline analysis of heat pump deployment rates, chiller replacement cycles, and refrigerant platform transitions informed projection modeling across product type, technology tier, end-user segment, and installation context dimensions. CAGRs derived from segment-level volume trajectories weighted by regulatory compliance deadlines and subsidy program allocations. Forecast inputs incorporated F-Gas Regulation phase-down schedules, Boiler Upgrade Scheme budget trajectories, and MEES enforcement intensity assumptions.
Several conditions sit outside the modeled scope, including hydrogen-ready boiler commercialization timelines, potential refrigerant supply disruptions from geopolitical events, and unannounced revisions to Part L conservation targets. Forecasts reflect documented assumptions regarding subsidy continuity and technician training capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
China HVAC Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Global HVAC Linesets Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market
HVAC Equipment
Fabric Ducting Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Global Snow Making System Market