
 Africa Aluminum Door and Window Market | 2026-2036
Africa Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Aluminum Door and Window Market Analytics
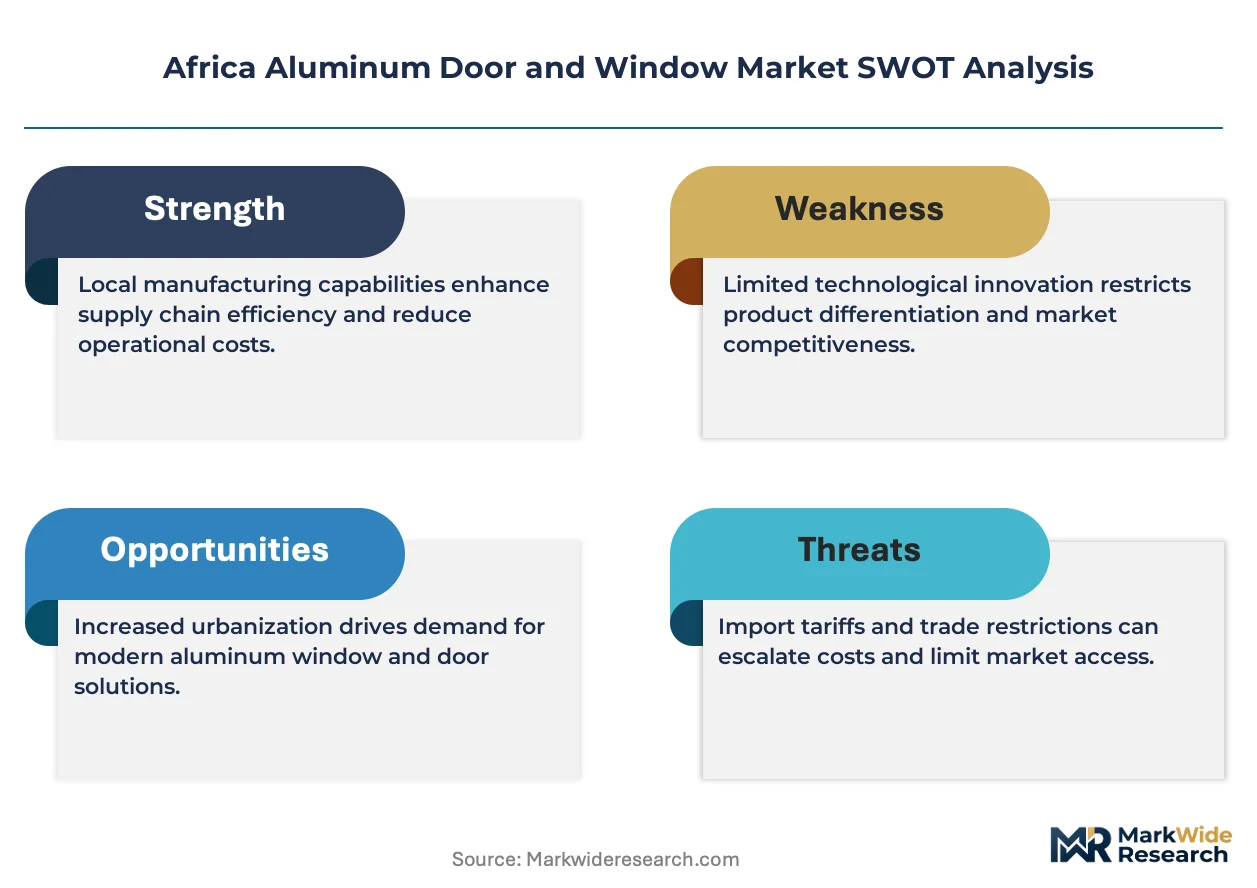
Egyptian manufacturing zones near Suez are tilting regional supply dynamics toward North African self-sufficiency. HBS Aluminium Systems leverages its extrusion capabilities to serve high-rise commercial towers across Cairo and Alexandria. Amdoor anchors East African distribution through fabrication facilities in Kenya and Tanzania. Reynaers Aluminium competes on thermal performance technology for green-certified buildings in Johannesburg and Cape Town.
Aluminum doors and windows are fabricated from extruded aluminum alloy profiles, typically 6063-T5 or 6061-T6 grade, assembled with polyamide thermal breaks and EPDM gaskets to achieve U-values below 2.0 W/m²K for commercial energy compliance. The primary purpose is to provide durable, corrosion-resistant fenestration that withstands coastal humidity and urban pollution while enabling natural daylighting and ventilation. Sliding doors dominate new construction volumes across African residential estates due to space efficiency and ease of installation. Casement doors command premium positioning in institutional and hospitality segments where acoustic and thermal performance carry specification weight. Retrofitting applications are gaining structural importance as existing commercial stock in South Africa and Nigeria faces energy compliance deadlines.
South Africa's National Regulator for Compulsory Specifications enforces SANS 10400-XA energy efficiency standards that directly shape aluminum window U-value requirements and thermal break specifications. Egypt's Housing and Building National Research Center maintains GB standards alignment for aluminum alloy grades used in public infrastructure projects. Kenya's National Construction Authority implements building code amendments that favor certified aluminum fabricators for government tenders. Stakeholders must monitor how divergent national certification regimes affect cross-border product acceptance and localized manufacturing investment decisions.
Market Dynamics
Thermal performance mandates across East and Southern Africa are compressing specification cycles for aluminum fabricators, forcing rapid retooling of extrusion lines and certification upgrades to meet divergent national energy codes.
Growth Catalysts
- SANS 10400-XA enforcement:South Africa's compulsory energy efficiency standard mandates U-values below 2.0 W/m²K for commercial fenestration, creating specification pull for thermally broken aluminum systems in Johannesburg and Cape Town office towers.
- Luxury residential estates:Nigeria's Lagos-Ibadan corridor concentrates demand from hospitality developments and high-end housing projects specifying powder-coated aluminum casement systems for acoustic performance.
- EPDM gasket innovation:Advanced polymer sealing technology enables fabricators to achieve coastal corrosion resistance required for Red Sea and Indian Ocean installations without stainless steel hardware premiums.
Market Restraints
- Aluminum ingot price volatility:LME price swings for 6063-T5 alloy billets directly compress fabrication margins across Egyptian and Nigerian extrusion plants with limited hedging infrastructure.
- Supply concentration in Suez Canal logistics:Egyptian manufacturing zones control regional billet supply, creating bottleneck risk for East African fabricators dependent on Alexandria-Cairo extrusion output.
- Steel window substitution:Galvanized steel framing retains cost advantage in Nigeria's mass housing segment, capping aluminum penetration below premium project tiers.
Strategic Opportunities
- Kenya's National Construction Authority certification:Government tender preferences for certified aluminum fabricators create structural advantage for accredited suppliers in Nairobi and Mombasa public infrastructure.
- Retrofit compliance deadlines:South Africa's existing commercial stock faces SANS 10400-XA retrofit requirements, opening replacement demand for thermally efficient sliding door systems in aging office parks.
- Polyamide thermal break + low-E glass convergence:Dual-technology integration enables fabricators to target green building certification premiums in Cape Town and Johannesburg sustainable developments.
Industry Challenges
- Thermal break insertion skill scarcity:Polyamide strip precision cutting and crimping requires specialized technician training unavailable across Tanzanian and Ugandan fabrication workshops.
- Multi-jurisdiction certification complexity:Fabricators serving Kenya, Tanzania, and Uganda simultaneously face divergent National Construction Authority, Tanzania Bureau of Standards, and Uganda National Bureau of Standards compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Aluminum Door and Window Market |
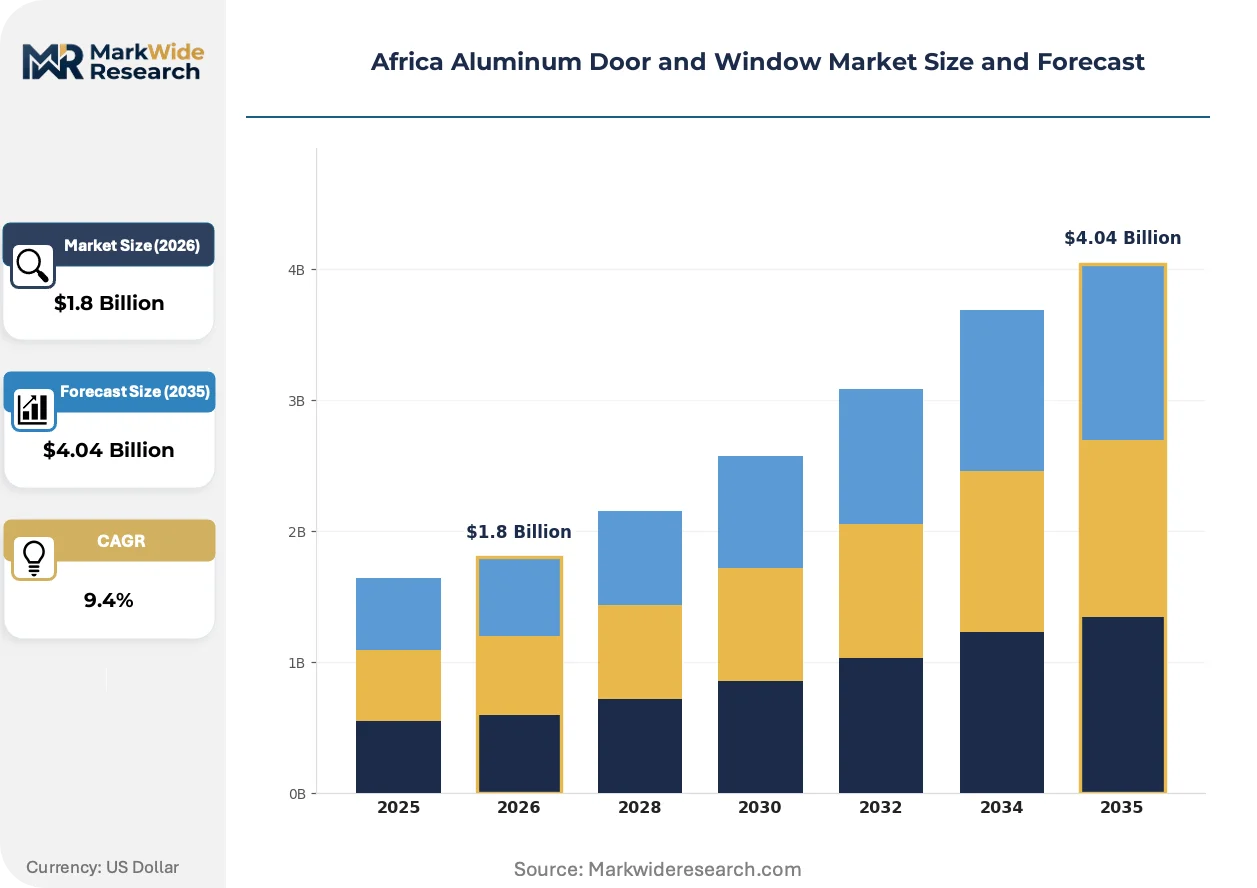
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Bi-fold Windows, Casement Doors, Fixed Windows End User: Residential, Commercial, Industrial, Institutional Design Style: Modern, Traditional, Minimalist, Contemporary Application: New Construction, Renovation, Retrofitting, Custom Builds |
| Companies Covered | HBS Aluminium Systems, Amdoor, Inso Aluminium, GGA Windows and Doors, Chamberlains, Architectural Glass and Aluminium, Reynaers Aluminium, AGA South Africa, Govaro, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Aluminum Door and Window Market Evolving Landscape
Digital specification tools and modular fabrication systems are compressing design-to-installation cycles across African aluminum fenestration, while regulatory fragmentation forces parallel compliance investments.
Building information modeling software is virtualizing the aluminum window specification process for Nairobi and Lagos architectural practices. Large commercial developers now require 3D thermal performance simulations before finalizing frame profiles. This technology is virtualizing traditional physical mock-up validation, compressing pre-construction timelines by eliminating site-built prototypes.
Kenya's National Construction Authority building code amendments favor certified aluminum fabricators for government tenders. The industrial consequence is tiered market access where uncertified suppliers face exclusion from public housing and infrastructure projects. East African fabricators are responding by accelerating ISO 9001 and product certification investments to maintain eligibility for state contracts.
Developer procurement teams now unbundle after-sales service from initial supply contracts, creating separate maintenance agreements with specialized glazing contractors. This pattern disrupts traditional fabricator-captured service revenue in South African commercial developments. The shift is most visible in Johannesburg's high-rise residential towers, where property management companies now directly contract acoustic seal replacement and hardware adjustment services.
Africa Aluminum Door and Window Market Segmentation
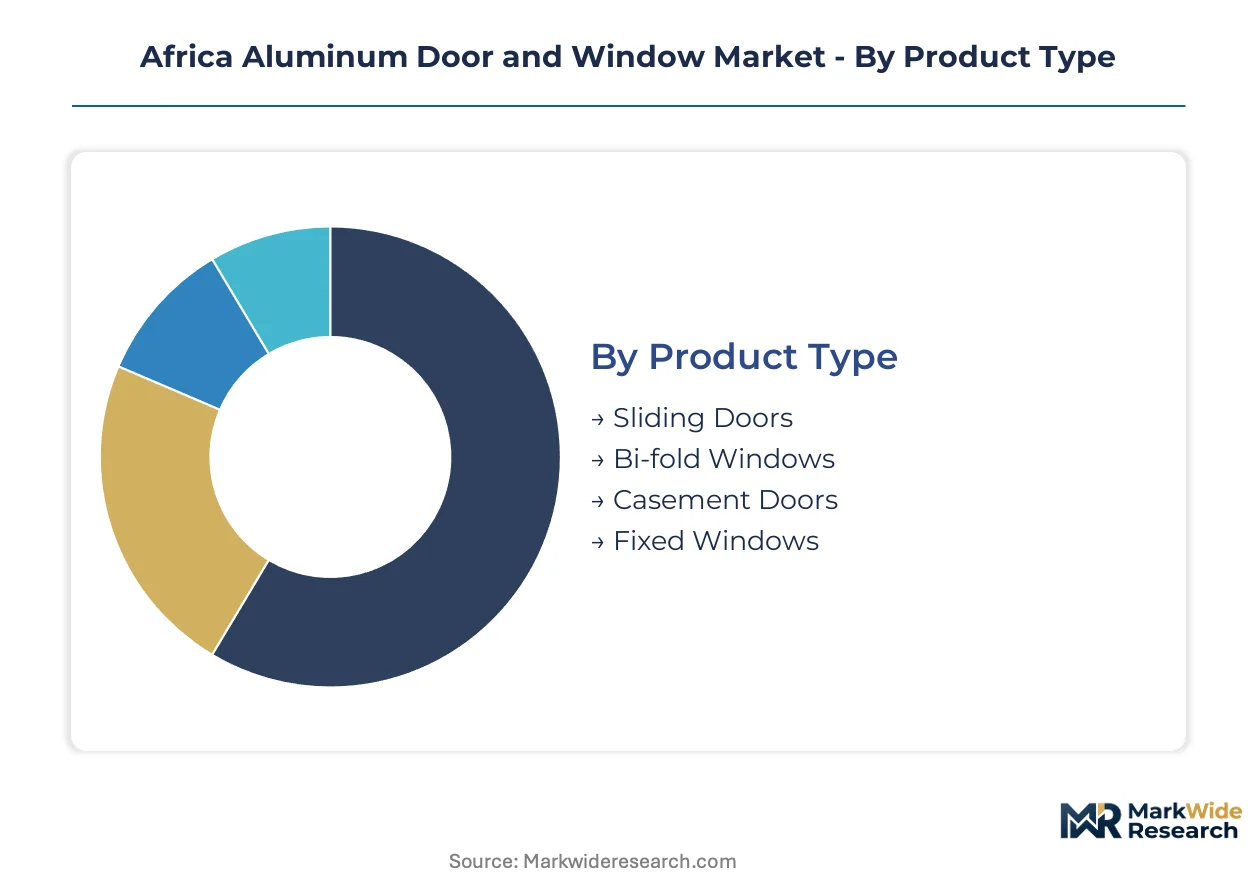
Segmentation in African aluminum fenestration reveals how specification requirements diverge across climate zones, building codes, and procurement channels. Each dimension shapes fabrication capabilities, thermal break investments, and distribution partnerships differently across the continent.
Product Type:
Architects and developers select aluminum fenestration products based on spatial constraints, thermal performance targets, and installation logistics across African construction sites.
- Sliding Doors:Horizontal rolling systems with tandem rollers and bottom-hung frames dominate space-constrained residential estates from Lagos to Nairobi. Kenyan developers specify these for balcony access in high-density apartment towers where swing clearance is unavailable.
- Casement Doors:Side-hinged frames with multi-point locking hardware deliver superior acoustic and thermal performance for hospitality and institutional projects. South Africa's green-certified commercial towers mandate these for SANS 10400-XA compliance in Cape Town and Johannesburg.
- Bi-fold Windows:Accordion-folding sash systems maximize ventilation aperture in coastal climates. Nigerian luxury residential projects along the Lekki corridor favor these for indoor-outdoor living transitions.
- Fixed Windows:Non-operable picture frames with structural glazing achieve cost minimization in industrial warehousing and stairwell applications. Egyptian manufacturing zones produce these at volume for Red Sea resort developments.
The dominant share belongs to Sliding Doors, while Casement Doors is closing the gap fastest.
End User:
Procurement sophistication varies sharply across customer categories, from individual homeowners to multinational property developers with dedicated specification teams.
- Residential:Individual homeowners and small-scale developers prioritize cost efficiency and local fabrication availability. East Africa's middle-class housing boom in Kampala and Dar es Salaam drives specification of powder-coated sliding systems with basic thermal breaks.
- Commercial:Corporate real estate and retail developers demand certified fabricators with BIM capability and performance warranties. South African REITs require SANS-compliant U-values and documented acoustic testing for Johannesburg office parks.
- Industrial:Manufacturing facilities and logistics warehouses specify fixed glazing and minimal-framing systems for natural daylighting. Egyptian Suez Canal Economic Zone projects source these from localized extrusion plants.
- Institutional:Government buildings, hospitals, and educational facilities mandate competitive tender compliance and extended maintenance contracts. Kenya's National Construction Authority certification requirements filter supplier eligibility for Nairobi public infrastructure.
Residential commands the volume base, though Commercial is expanding most quickly as energy codes tighten across Southern Africa.
Design Style:
Aesthetic preferences in aluminum fenestration track architectural movements and developer brand positioning across African urban centers.
- Modern:Clean sightlines, slim 60mm frame profiles, and concealed hardware align with international hotel brand standards. Lagos-Ibadan corridor hospitality projects specify these for guest room balconies.
- Contemporary:Mixed material integration with timber-look finishes and geometric grid patterns appeals to premium residential developers. Cape Town's Atlantic Seaboard estates favor these for architectural distinction.
- Minimalist:Ultra-slim 40mm frames with frameless corner joints maximize glass area for luxury apartments. Cairo's New Administrative Capital high-rises adopt these for skyline visibility.
- Traditional:Decorative mullions, heritage color palettes, and mechanically operated hardware serve conservation-area renovations. Stone Town Zanzibar restoration projects require these for UNESCO compliance.
Modern styling holds the specification lead, while Minimalist is gaining share fastest among high-end developers.
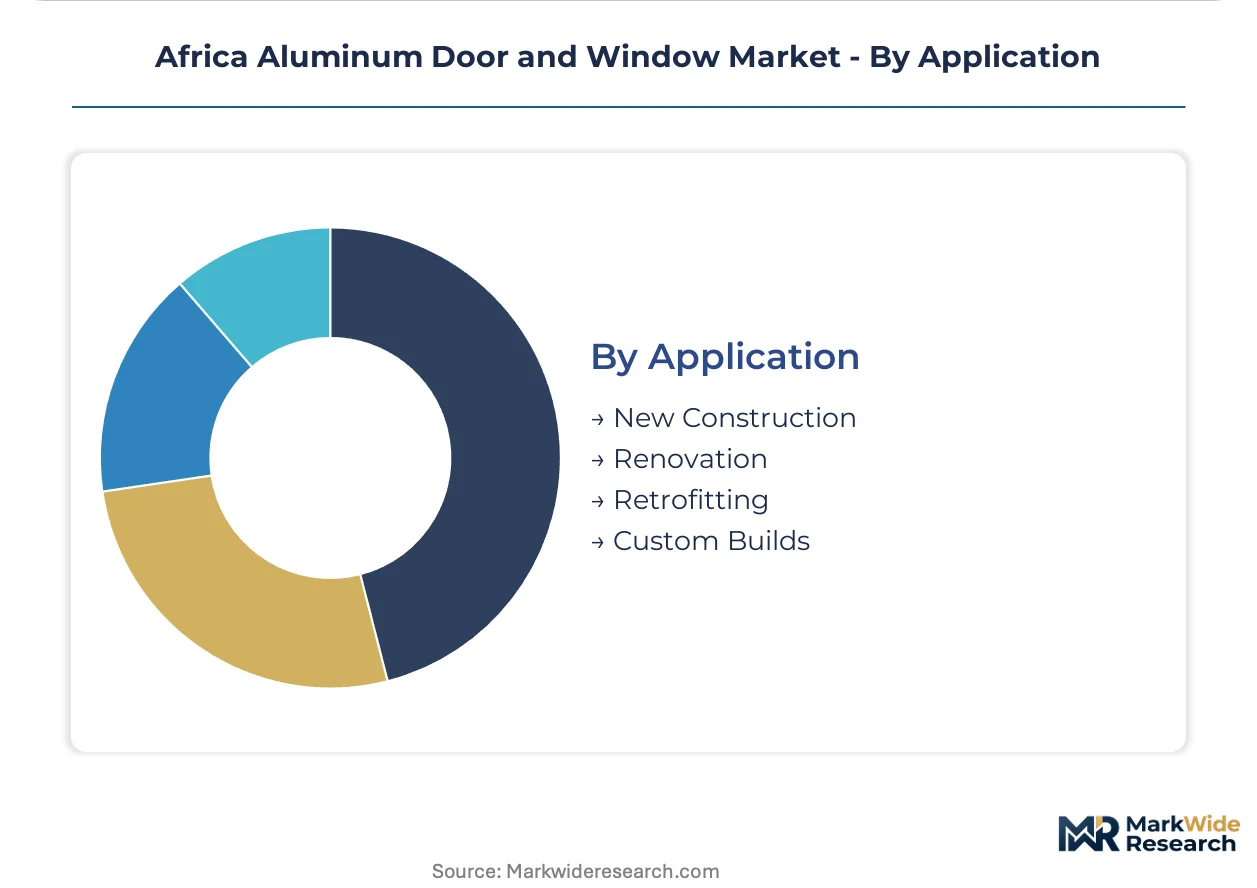
Application:
Project phase determines fabrication lead times, installation sequencing, and after-sales service bundling across African construction markets.
- New Construction:Greenfield developments enable integrated fenestration scheduling with curtain wall and cladding contractors. Nairobi's Konza Technopolis mandates certified aluminum fabricators for phase-one commercial buildings.
- Retrofitting:Energy compliance deadlines in existing commercial stock drive replacement demand for thermally efficient systems. South Africa's aging office parks face SANS 10400-XA retrofit requirements in Johannesburg and Pretoria.
- Renovation:Partial facade upgrades and single-unit replacements require flexible fabrication with minimal batch sizes. Nigerian residential estate management companies source these for villa refresh cycles.
- Custom Builds:Bespoke architectural specifications with non-standard dimensions and specialized hardware serve high-net-worth individual commissions. Cape Town's Clifton beachfront properties demand these for unique coastal exposure conditions.
New Construction retains the dominant project flow, though Retrofitting is climbing the fastest as regulatory deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's National Regulator for Compulsory Specifications anchors regulatory gravity across the continent through SANS 10400-XA enforcement. Fabricators in Johannesburg and Cape Town face mandatory U-value compliance that reshapes procurement patterns for commercial towers. Egyptian manufacturing zones near Suez tilt supply dynamics toward North African self-sufficiency.
South Africa
Johannesburg's commercial REITs drive specification pull for thermally broken systems in office park developments. SANS 10400-XA mandates U-values below 2.0 W/m²K for commercial fenestration. Cape Town's Atlantic Seaboard estates concentrate green-certified tower construction where acoustic and thermal performance carry specification weight.
Egypt
Cairo's high-rise residential towers and Alexandria's coastal hospitality projects generate demand for corrosion-resistant framing systems. The Housing and Building National Research Center maintains GB standards alignment for aluminum alloy grades in public infrastructure. Manufacturing zones near the Suez Canal Economic Zone supply extruded profiles across North African markets.
Nigeria
The Lagos-Ibadan corridor concentrates demand from luxury residential estates and hospitality developments specifying powder-coated casement systems. Mass housing segments retain galvanized steel framing cost advantages that cap aluminum penetration below premium tiers. Lekki corridor luxury projects favor bi-fold systems for indoor-outdoor living transitions.
Kenya
Nairobi's Konza Technopolis and high-density apartment towers drive specification of space-efficient sliding door systems. The National Construction Authority implements building code amendments favoring certified aluminum fabricators for government tenders. Mombasa's coastal exposure conditions require EPDM gasket innovation for corrosion resistance without stainless steel hardware premiums.
Tanzania
Dar es Salaam's middle-class housing boom specifies powder-coated sliding systems with basic thermal breaks. The Tanzania Bureau of Standards maintains divergent compliance timelines from neighboring jurisdictions. Fabrication workshops face skill scarcity in polyamide thermal break insertion precision cutting and crimping techniques.
Africa Aluminum Door and Window Market Competitive Landscape
Capability concentration sits with premium-tier fabricators possessing thermal break certification and BIM integration; scale advantage sits with regional extrusion plants serving mass residential segments. The market structures around three archetypes: certified premium fabricators targeting green building compliance, mid-tier regional suppliers serving government tenders, and localized workshops competing on installation speed. Dominant competitive moves include certification investments for National Construction Authority eligibility and geographic expansion through distribution partnerships across East African corridors.
Within the premium-tier vector, Reynaers Aluminium occupies a position exemplifying thermal performance technology specialization for green-certified buildings. HBS Aluminium Systems represents Egyptian manufacturing scale serving high-rise commercial towers across Cairo and Alexandria. Amdoor anchors East African distribution through fabrication facilities in Kenya and Tanzania, sitting within the regional expansion archetype.
| Leading Market Players |
|---|
| HBS Aluminium Systems |
| Amdoor |
| Inso Aluminium |
| GGA Windows and Doors |
| Chamberlains |
| Architectural Glass and Aluminium |
| Reynaers Aluminium |
| AGA South Africa |
| Govaro |
| Others |
Value Network & Pricing Analysis
Underutilization in Egyptian extrusion zones near Suez is forcing Alexandria-Cairo suppliers into aggressive volume discounting for East African fabricators, compressing margins across the Nile-to-Nairobi corridor while simultaneously incentivizing localized billet stockpiling by Kenyan distributors.
Pricing Analysis
Price spreads between Egyptian-manufactured thermal break profiles and Nigerian-fabricated standard frames exceed 40 percent on delivered-cost basis, with premium-mid-economy pricing differentiation anchored in SANS 10400-XA certification grade and polyamide thermal break specification. Project-based transactional pricing dominates commercial tower procurement in Johannesburg and Cape Town, while spot-market aluminum ingot exposure leaves Lagos fabricators vulnerable to LME volatility. Cost compression in East African standard-grade segments is intensifying because Kenyan National Construction Authority certification requirements filter supplier eligibility, concentrating tender access among accredited players. Mass housing developers in Nigeria exhibit highest price sensitivity, whereas South African REITs prioritize performance warranties over unit cost.
Supply Chain Analysis
Extended payment terms from Suez Canal Economic Zone extruders—typically 90-120 days for established East African distributors—are financing inventory float across the Alexandria-Mombasa logistics corridor, masking working capital strain among Tanzanian fabricators. Supply concentrates in Egypt, Kenya, and South Africa, with 6063-T5 alloy billets, polyamide thermal break strips, and EPDM gasket systems constituting critical input dependencies. Single-source vulnerability looms over Alexandria-Cairo billet supply for Nairobi and Dar es Salaam fabricators lacking alternative sourcing. Distribution runs through regional extrusion plants serving certified fabricators, with uncertified workshops competing on installation speed and localized service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Galvanized steel framing substitution in Nigeria's mass housing segment threatens aluminum penetration below premium tiers, requiring incumbent fabricators to articulate total-cost-of-ownership advantages against lower-first-cost alternatives.
For Market Incumbents: Harden thermal break certification moats by accelerating ISO 9001 and National Construction Authority accreditation investments ahead of Kenyan government tender expansions. Defend against Egyptian supply concentration risk by cultivating secondary billet sourcing relationships with South African extruders or captive scrap-recycling capabilities. Prioritize SANS 10400-XA compliance documentation for South African commercial retrofit pipelines. For New Entrants and Emerging Players: Build out fabrication capacity in Tanzania's undersupplied upcountry markets, where Bureau of Standards compliance timelines lag Kenyan and Ugandan requirements, creating temporary specification flexibility. Target Dar es Salaam's middle-class housing boom with powder-coated sliding systems featuring basic thermal breaks. Penetrate through direct contractor relationships bypassing established Nairobi distribution hierarchies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certified premium fabricators with maintenance contract capabilities in Johannesburg high-rise residential towers. Long-term viability over the next decade rests on thermal performance technology specialization and green building certification alignment. Acquisition focus should center on Egyptian extrusion assets with Suez Canal logistics access or East African fabricators with National Construction Authority eligibility. Watch for SANS 10400-XA retrofit deadline acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Break Certification Investment | Unlocks National Construction Authority eligibility for Nairobi government tenders. |
| Backward Integration into Billet Supply | Reduces LME price volatility exposure for Egyptian and Nigerian extrusion plants. |
| Retrofit Service Capability Buildout | Captures SANS 10400-XA compliance-driven replacement demand in Johannesburg office parks. |
| Coastal Corrosion-Resistant Product Line | Addresses Mombasa and Red Sea humidity requirements without stainless steel hardware premiums. |
| Distribution Partnership Expansion | Accelerates East African corridor penetration beyond Kenya into Tanzanian and Ugandan markets. |
Research Methodology
The analysis maps sliding door, casement door, bi-fold window, and fixed window sub-sectors, each validated through aluminum fabrication plant managers, architectural specification consultants, National Construction Authority certification officers, and commercial real estate procurement directors. Primary interviews with Egyptian extrusion operators, Kenyan distributor networks, and South African REIT asset managers combined with secondary validation from SANS 10400-XA regulatory filings, Kenya Bureau of Standards documentation, Tanzania Bureau of Standards compliance schedules, and LME aluminum price archives. Bottom-up unit economics from fabrication facilities triangulated against top-down construction spend estimates across the projection horizon.
Assumptions held fixed include current SANS 10400-XA U-value thresholds, Egyptian manufacturing zone capacity utilization rates, and National Construction Authority certification eligibility criteria; varied assumptions encompass LME aluminum price trajectory bands and Kenyan government tender award velocities. The forecast framework segments by product type, end user category, design style, and application phase, with CAGRs derived from installation volume growth rates and average selling price evolution across certified versus uncertified fabricator tiers. Industry-specific inputs include thermal break penetration rates by climate zone and green building certification adoption curves in Cape Town and Johannesburg.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Suez Canal Economic Zone extruders or accelerated SANS 10400-XA enforcement would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Bolt (Fastener) Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Canada Architectural Coatings Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Italy Facade Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Cement Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
India Cement Market
Building Materials
Drywall Joint Tape Market
Building Materials
Europe Cement Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Block Paving Market
Building Materials
Steel Products Market
Building Materials
Global Drywall and Building Plaster Market