
 Field-Erected Cooling Tower Market | 2026-2036
Field-Erected Cooling Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Field-Erected Cooling Tower Market Intelligence
ASHRAE 188 Legionella risk management compliance is collapsing the specification floor for field-erected cooling towers across healthcare and data center deployments. SPX Cooling Technologies, Inc. leverages its composite material expertise to occupy premium project tiers where thermal performance guarantees command pricing power. Evapco, Inc. specializes in modular mechanical draft configurations that anchor its position in petrochemical refinery expansions along the US Gulf Coast.
Field-erected cooling towers are site-constructed heat rejection structures engineered to circulating water flow rates exceeding thousands of gallons per minute, utilizing induced-draft or natural-draft configurations with fill media surface areas calibrated to specific wet-bulb temperature design conditions. Their primary purpose centers on dissipating waste thermal energy from power plant condensers, industrial process loops, and large-scale HVAC central plants where factory-assembled units lack sufficient capacity. Mechanical draft installations dominate current order books due to their siting flexibility and controlled plume dispersion characteristics, while natural draft concrete hyperbolic designs retain margin concentration in utility-scale power generation where lifecycle cost optimization overrides first-capital expenditure considerations. Chemical manufacturing applications represent the fastest-growing demand cluster as European producers retrofit cooling infrastructure to comply with tightened process safety directives.
The US EPA enforces Section 316(b) of the Clean Water Act governing cooling water intake structures, compelling power generators toward closed-cycle recirculating systems with field-erected towers rather than once-through cooling configurations. EMA's F-Gas Regulation and REACH chemical restrictions are reshaping material selection protocols for European installations, restricting certain biocide treatments and fill media compositions. China's MEE implements dual carbon goals through provincial emissions intensity targets that accelerate thermal efficiency investments in industrial cooling circuits. Stakeholders must monitor evolving regional carbon border adjustment mechanisms that threaten to reallocate cooling tower procurement decisions toward jurisdictions with embedded emissions certification requirements.
Market Dynamics
US EPA Section 316(b) enforcement is compressing once-through cooling configurations toward closed-cycle recirculating systems, while India's coal-fired retrofit wave and nuclear greenfield projects concentrate demand for large-scale concrete hyperbolic structures.
Growth Catalysts
- EPA Thermal Discharge Mandates:Section 316(b) of the Clean Water Act compels power generators to abandon once-through cooling for field-erected closed-cycle towers, accelerating replacement cycles across aging US fossil fleets.
- India's Power Capacity Expansion:Coal-fired plant retrofits and greenfield nuclear installations by NTPC and NPCIL concentrate procurement of natural-draft concrete hyperbolic towers exceeding 150-meter heights.
- Composite Material Advancement:Pultruded fiberglass structural components are extending service intervals in corrosive chemical process environments, opening specification pathways in European petrochemical retrofits.
Market Restraints
- Cement and Steel Input Volatility:Natural-draft hyperbolic construction requires 15,000+ cubic meters of reinforced concrete per unit, exposing project economics to commodity price swings in Portland cement and rebar.
- Fabrication Concentration Risk:Specialized hyperbolic shell formwork and climbing shutter systems concentrate among German and Italian engineering subcontractors, creating single-source vulnerability for utility-scale projects.
- REACH Biocide Restrictions:ECHA limitations on halogenated biocide treatments for fill media are eliminating proven Legionella control chemistries, forcing costly reformulation of water treatment protocols.
Strategic Opportunities
- Saudi Arabia's Giga-Project Pipeline:NEOM and Red Sea tourism developments require district cooling infrastructure at scales exceeding packaged unit capacity, creating specification openings for field-erected mechanical draft configurations.
- Data Center Liquid Cooling Convergence:Hybrid designs integrating field-erected towers with direct-to-chip liquid cooling loops are emerging at hyperscale facilities in Northern Virginia and Frankfurt.
- EU Carbon Border Adjustment Mechanism:Embedded emissions certification requirements are repositioning procurement decisions toward tower fabricators with verified low-carbon concrete supply chains.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section IX-qualified structural welders for stainless steel cold water basin fabrication face 18-month backlog periods, compressing project commissioning schedules.
- Legacy Control System Integration:Digital twin and predictive maintenance platforms must interface with 1980s-era SCADA architectures at existing power plants, multiplying commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field-Erected Cooling Tower Market |
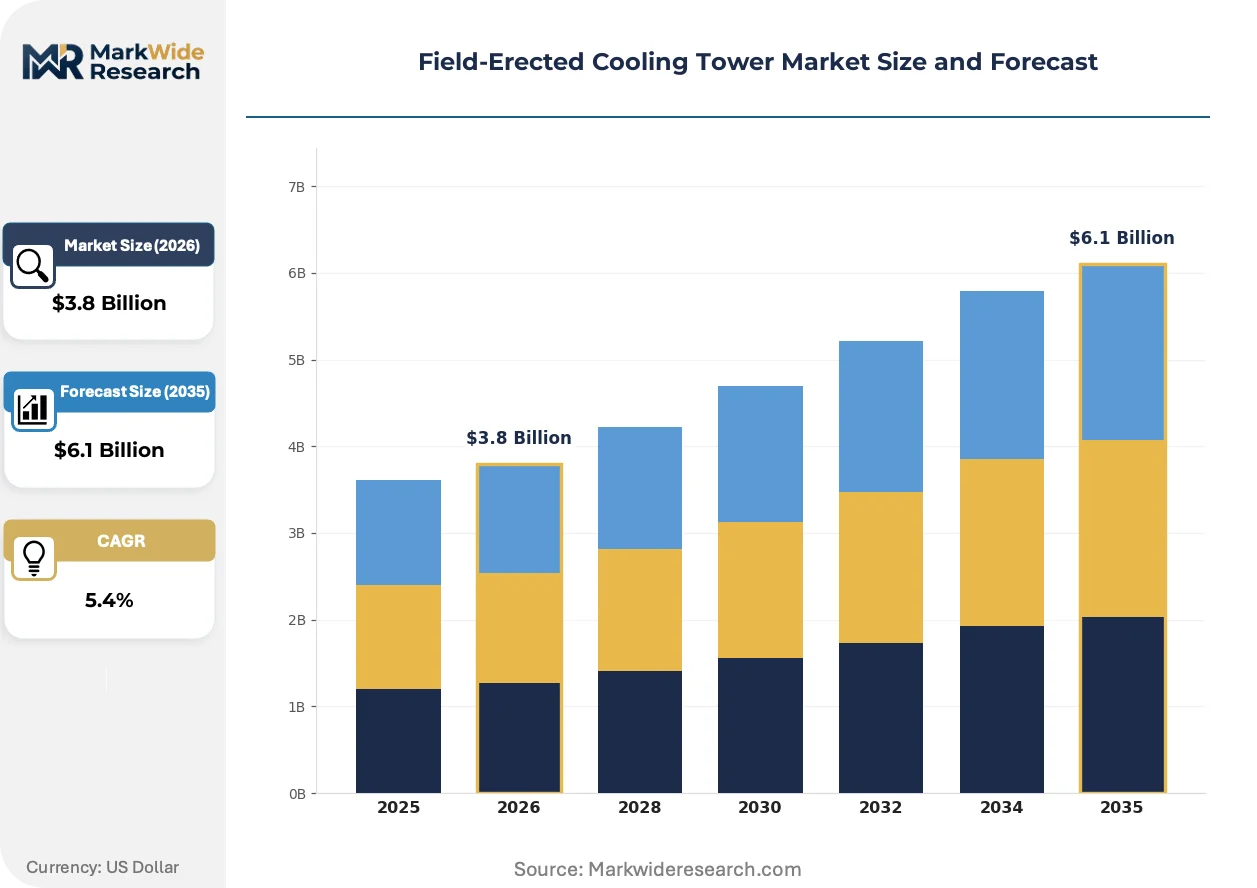
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Draft, Mechanical Draft, Hybrid, Crossflow Application: Power Generation, HVAC Systems, Industrial Processes, Chemical Manufacturing End User: Energy Providers, Manufacturing Facilities, Municipalities, Refineries Material: Fiberglass, Steel, Concrete, Aluminum |
| Companies Covered | SPX Cooling Technologies, Inc., ENEXIO Management GmbH, Hamon & Cie International SA, Baltimore Aircoil Company, Inc., Evapco, Inc., Paharpur Cooling Towers Ltd., Babcock & Wilcox Enterprises Inc., Delta Cooling Towers Inc., Brentwood Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field-Erected Cooling Tower Market Strategic Shifts & Innovations
Material substitution, regulatory chemistry restrictions, and procurement model fragmentation are simultaneously reshaping tower specification, fabrication, and lifecycle service architectures.
Advanced polymer concrete basins and pultruded fiberglass structural members are displacing traditional reinforced concrete and galvanized steel in corrosive-duty applications. Chemical processors along the US Gulf Coast and North Sea petrochemical clusters are specifying these materials for 40-year design life guarantees. The shift is compressing maintenance outage schedules from biennial to quadrennial intervals.
REACH F-Gas Regulation and ECHA biocide restrictions are eliminating halogenated treatment chemistries from European fill media specifications. Tower operators must deploy ozone-based or UV-C secondary disinfection systems to maintain ASHRAE 188 compliance. German and Dutch healthcare and data center deployments are absorbing 25-35% capital cost premiums for compliant water treatment packages.
Performance-based service contracting is fragmenting traditional EPC procurement at industrial installations. Owner-operators in Texas and Alberta are unbundling tower construction from 20-year thermal performance guarantees, shifting risk to specialized service integrators. The model concentrates margin capture among firms with predictive analytics capabilities and regional water chemistry databases.
Field-Erected Cooling Tower Market Segmentation
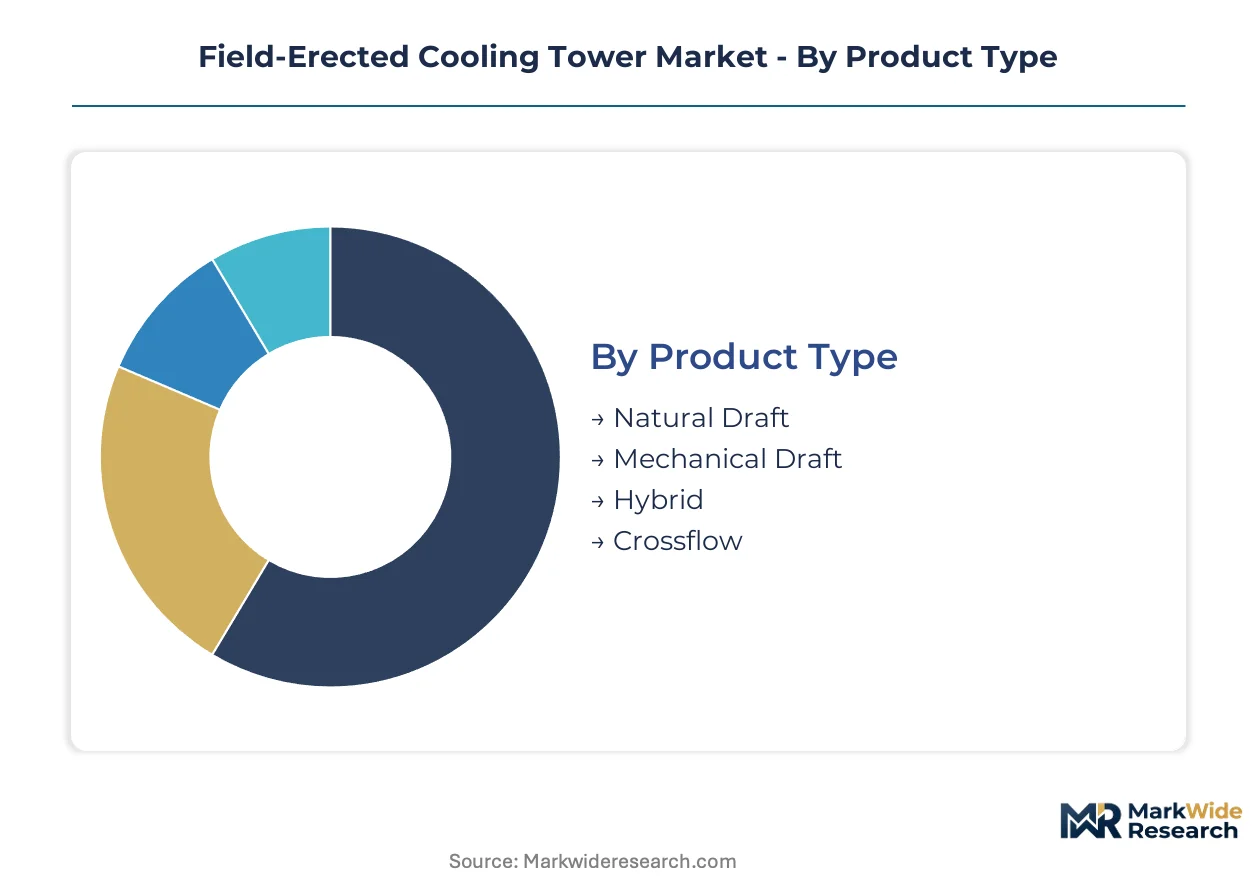
Field-erected cooling tower procurement splits along thermal capacity thresholds and regulatory compliance requirements. Specification decisions cascade from draft type selection through material chemistry to end-use operating conditions.
Product Type:
Mechanical draft configurations capture premium margin pools through siting flexibility and controlled plume dispersion, while natural draft concrete hyperbolic structures concentrate utility-scale lifecycle optimization value.
- Natural Draft:Concrete hyperbolic shells exceeding 150 meters in height utilize buoyancy-driven airflow without mechanical fans. India's coal-fired retrofits and NPCIL nuclear greenfield projects anchor procurement volumes for these structures.
- Mechanical Draft:Induced-draft and forced-draft configurations deploy axial or centrifugal fans for precise thermal control. Petrochemical refineries along the US Gulf Coast specify these for their footprint efficiency and rapid commissioning timelines.
- Hybrid:Combined natural and mechanical draft systems optimize for variable load conditions. These installations are gaining specification at combined-cycle power plants requiring operational flexibility.
- Crossflow:Horizontal airflow perpendicular to falling water maximizes fill media exposure. European chemical manufacturers specify crossflow designs for their compact basin geometry and reduced pumping head.
Natural Draft holds installed capacity. Mechanical Draft is rotating up the share rankings.
Application:
Power generation commands the largest project scale, though chemical manufacturing applications are climbing fastest on process safety retrofit mandates.
- Power Generation:Condenser heat rejection for fossil, nuclear, and combined-cycle plants requires towers handling thousands of gallons per minute. US EPA Section 316(b) enforcement is compressing once-through cooling toward closed-cycle recirculating systems.
- Chemical Manufacturing:Process cooling for reactors, distillation columns, and heat exchangers demands corrosion-resistant construction. REACH F-Gas Regulation and ECHA biocide restrictions are reshaping European fill media specifications.
- Industrial Processes:Steel, cement, and pulp production facilities require robust thermal rejection infrastructure. China's MEE provincial emissions intensity targets are accelerating efficiency investments in these cooling circuits.
- HVAC Systems:District cooling and large-scale central plants serve airports, hospitals, and university campuses. Saudi Arabia's NEOM and Red Sea tourism developments are creating specification openings for mechanical draft configurations at scales exceeding packaged unit capacity.
Power Generation retains project scale dominance. Chemical Manufacturing is climbing fastest on retrofit mandates.
End User:
Energy providers concentrate procurement volume through centralized capital planning, while refineries fragment purchasing across maintenance turnaround schedules.
- Energy Providers:NTPC, NPCIL, and US independent power producers deploy standardized tower specifications across fleet expansions. Their procurement leverages 20-year thermal performance guarantees and predictive maintenance service contracts.
- Refineries:Petrochemical complexes require corrosion-resistant materials for sour water and hydrocarbon exposure. US Gulf Coast and North Sea clusters are specifying pultruded fiberglass structural members for extended service intervals.
- Manufacturing Facilities:Discrete production plants specify modular mechanical draft towers for process cooling loops. Performance-based service contracting is fragmenting traditional EPC procurement at Texas and Alberta installations.
- Municipalities:District cooling authorities and water treatment plants deploy field-erected towers for public infrastructure. These procurements face extended approval cycles and bonded construction requirements.
Energy Providers anchor procurement volume. Refineries are rotating up the share rankings on petrochemical expansion cycles.
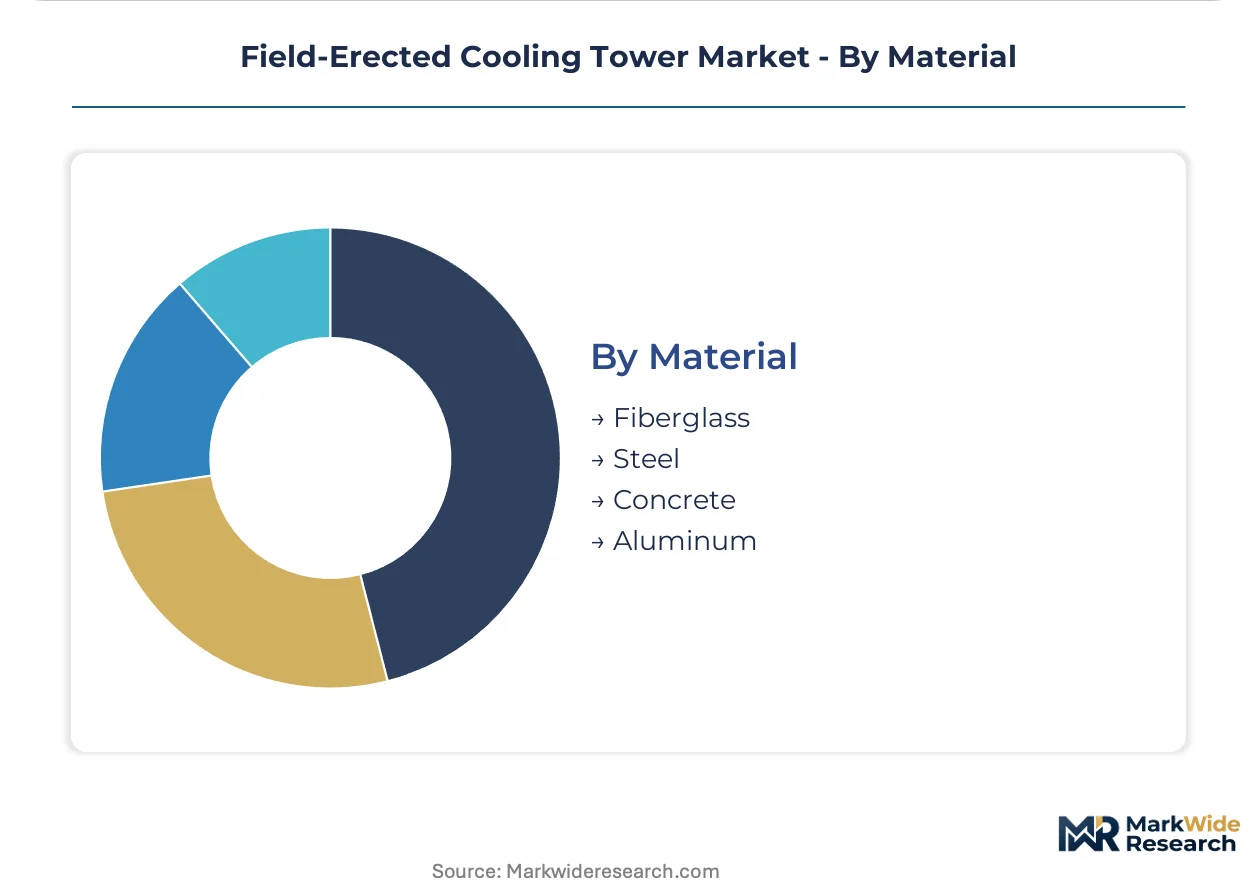
Material:
Concrete dominates natural-draft hyperbolic construction, while fiberglass is displacing steel in corrosive-duty specifications.
- Concrete:Reinforced Portland cement shells for natural-draft hyperbolic towers require 15,000+ cubic meters per unit. German and Italian engineering subcontractors concentrate specialized formwork and climbing shutter systems.
- Fiberglass:Pultruded structural components and polymer concrete basins extend design life in chemical process environments. European petrochemical retrofits are absorbing 25-35% capital cost premiums for these specifications.
- Steel:Galvanized and stainless steel cold water basins and framework dominate mechanical draft construction. ASME Section IX-qualified welders face 18-month backlogs, compressing project commissioning schedules.
- Aluminum:Lightweight structural members and louvers reduce foundation loads in seismic zones. These specifications concentrate in Japanese and Californian installations with strict weight constraints.
Concrete holds installed capacity. Fiberglass is rotating up the share rankings on corrosion resistance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hyperbolic shell formwork and climbing shutter systems concentrate among German and Italian engineering subcontractors, creating single-source vulnerability for utility-scale projects while cement and steel input volatility exposes project economics to commodity price swings.
United States
Power generators abandon once-through cooling configurations under EPA Section 316(b) enforcement, accelerating replacement cycles across aging fossil fleets. The Clean Water Act mandates closed-cycle recirculating systems with field-erected towers. Petrochemical refineries along the Texas and Louisiana Gulf Coast specify pultruded fiberglass structural members for sour water exposure.
India
NTPC coal-fired retrofits and NPCIL nuclear greenfield projects concentrate procurement of natural-draft concrete hyperbolic towers exceeding 150-meter heights. The Central Electricity Authority mandates thermal efficiency upgrades under national capacity expansion programs. Gujarat and Tamil Nadu industrial corridors anchor fabrication demand for reinforced concrete shells.
Germany
REACH F-Gas Regulation and ECHA biocide restrictions eliminate halogenated treatment chemistries from fill media specifications. Engineering subcontractors concentrate specialized hyperbolic formwork systems for export to utility-scale projects. The Rhine-Ruhr petrochemical cluster absorbs capital cost premiums for compliant water treatment packages.
China
Provincial emissions intensity targets under MEE dual carbon goals accelerate thermal efficiency investments in industrial cooling circuits. Yangtze River Delta steel and cement producers retrofit cooling infrastructure to meet tightening standards. Shandong Peninsula chemical manufacturers specify corrosion-resistant construction for process cooling loops.
Saudi Arabia
NEOM and Red Sea tourism developments require district cooling infrastructure at scales exceeding packaged unit capacity. The Ministry of Energy mandates efficiency standards for giga-project thermal infrastructure. Riyadh and the Eastern Province anchor specification openings for field-erected mechanical draft configurations.
Field-Erected Cooling Tower Market Key Industry Players
Concentration sits with full-service tower fabricators holding integrated design-construction capabilities and specialized subcontractors controlling hyperbolic shell formwork systems. The vendor base spans three tiers: global EPCs with thermal performance guarantee capacity, regional specialists in modular mechanical draft configurations, and niche providers of composite material components. Strategic moves center on performance-based service contracting unbundling and predictive maintenance platform integration.
Within the full-service tier, SPX Cooling Technologies, Inc. and Baltimore Aircoil Company, Inc. represent integrated design-build capabilities, while Evapco, Inc. occupies a position among modular mechanical draft specialists. ENEXIO Management GmbH and Hamon & Cie International SA exemplify European engineering heritage in natural-draft hyperbolic construction. Paharpur Cooling Towers Ltd. anchors Indian fabrication capacity for utility-scale concrete structures. These named entities illustrate archetype positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| SPX Cooling Technologies, Inc. |
| ENEXIO Management GmbH |
| Hamon & Cie International SA |
| Baltimore Aircoil Company, Inc. |
| Evapco, Inc. |
| Paharpur Cooling Towers Ltd. |
| Babcock & Wilcox Enterprises Inc. |
| Delta Cooling Towers Inc. |
| Brentwood Industries, Inc. |
| Others |
Cost & Logistics Intelligence
EPA Section 316(b) thermal discharge mandates and ASHRAE 188 Legionella certification simultaneously gate supplier qualification and stratify price tiers across field-erected cooling tower procurement. Compliance-grade fabricators command premium positioning while non-certified competitors face exclusion from healthcare and data center specifications.
Pricing Analysis
EPA Section 316(b) dictates the pricing tier structure across the US power generation segment, separating closed-cycle recirculating system specialists from once-through retrofit generalists. Three-tier pricing structure across premium, standard, and economy levels reflects thermal performance guarantee duration, with 20-year guaranteed output commanding substantial premiums over 5-year standard coverage. Cost compression in economy-tier mechanical draft configurations is intensifying because Chinese fabricators are expanding export capacity for modular induced-draft units. Municipal district cooling authorities exhibit highest price sensitivity due to bonded construction requirements and extended approval cycles, while nuclear utilities demonstrate lowest sensitivity given lifecycle cost optimization mandates.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam is elevating inbound logistics costs for German and Italian hyperbolic formwork systems destined for Indian utility-scale projects. Supply concentration rests on Germany, Italy, and India for specialized climbing shutter engineering, reinforced concrete shell fabrication, and composite material component manufacturing respectively. Pultruded fiberglass structural members, polymer concrete basin formulations, and ASME-certified stainless steel cold water basins constitute critical input dependencies. Single-source vulnerability concentrates among German engineering subcontractors controlling hyperbolic shell formwork intellectual property. Distribution runs through EPC-led turnkey contracting at utility scale, shifting to fragmented owner-operator direct procurement for industrial mechanical draft installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field-erected cooling tower demand sits in early-cycle expansion as EPA thermal discharge mandates and India's nuclear greenfield pipeline accelerate replacement and new-build procurement simultaneously.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance platforms and 20-year thermal performance guarantees that emerging competitors cannot replicate. Backward integration into pultruded fiberglass manufacturing secures margin control as REACH biocide restrictions reshape European material specifications. Capacity addition in Gujarat and Tamil Nadu industrial corridors defends share against Paharpur Cooling Towers' domestic fabrication advantages. For New Entrants and Emerging Players: Lead with modular mechanical draft configurations targeting Saudi Arabia's NEOM and Red Sea tourism giga-projects where district cooling scales exceed packaged unit capacity. Hybrid designs integrating field-erected towers with direct-to-chip liquid cooling loops represent the most penetrable white-space at Northern Virginia and Frankfurt hyperscale data centers. Performance-based service contracting unbundled from EPC delivery offers a differentiated go-to-market angle against integrated incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across natural-draft concrete hyperbolic construction as cement and steel input volatility exposes project economics to commodity price swings. Acquisition targets should concentrate on regional mechanical draft specialists with predictive analytics capabilities and established water chemistry databases. Monitor ASME Section IX welding certification backlog durations as an inflection indicator for commissioning schedule compression and margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contracting | Unbundles EPC risk and shifts 20-year thermal guarantees to specialized integrators with analytics platforms. |
| Composite Material Capacity Expansion | Pultruded fiberglass investments extend service intervals in corrosive Gulf Coast petrochemical environments. |
| Predictive Maintenance Platform Integration | Digital twin deployment must interface with 1980s-era SCADA at existing power plants, creating integration moats. |
| Regional Fabrication Footprint Expansion | Gujarat and Tamil Nadu capacity anchors Indian nuclear and coal retrofit procurement against German-Italian formwork dependence. |
| Low-Carbon Concrete Supply Chain Certification | EU Carbon Border Adjustment Mechanism repositioning procurement toward verified embedded emissions fabricators. |
Research Approach
Operator-level perspectives from power plant engineering directors, petrochemical maintenance managers, EPC procurement leads, and cooling tower aftermarket service heads anchored the qualitative base. Primary interview intelligence combined with secondary validation from EPA Section 316(b) enforcement records, ECHA biocide restriction filings, NTPC and NPCIL project development disclosures, and customs trade data for pultruded fiberglass and reinforced concrete inputs. Bottom-up project pipeline aggregation and top-down utility capital expenditure triangulation established market sizing boundaries.
Sensitivity analysis framed volume and value outputs across the projection horizon, modeling draft type selection, application end-use, material chemistry specifications, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from installed base replacement cycles, greenfield capacity addition announcements, and efficiency retrofit mandates. Forecast inputs incorporated wet-bulb temperature design condition distributions, fill media surface area specifications, and thermal discharge compliance deadlines.
Forecasts assume regulatory continuity in EPA Clean Water Act enforcement, EU REACH and F-Gas Regulation regimes, and India's Central Electricity Authority thermal efficiency mandates; material policy shifts would require re-modeling. Commodity price volatility in Portland cement and rebar, welding certification bottlenecks, and REACH biocide restriction expansion constitute specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Residential Heat Pump Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
United Kingdom Heating Equipment Market
HVAC Equipment
Asia-Pacific Compressor Market