
 Heat Transfer Fluids Market | 2026-2036
Heat Transfer Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Transfer Fluids Market Intelligence
Fluid lifecycle management services is expanding as a discrete revenue layer, with thermal monitoring subscriptions and predictive degradation analytics bundled into long-term supply contracts. Dow leverages its silicone oil expertise to anchor service relationships across North American data center operators. Clariant competes through specialized additive packages that extend drain intervals in chemical processing loops. Shell plc dominates maritime and remote power applications where on-site fluid analysis replaces routine changeouts.
Heat transfer fluids are thermally stable engineered liquids formulated from synthetic hydrocarbons, silicone polymers, or inhibited glycol-water blends, designed to convey thermal energy across temperature differentials typically spanning minus forty to four hundred degrees Celsius. Their primary purpose is to mediate heat exchange in closed-loop industrial systems where direct steam or water circulation proves thermally inefficient or chemically incompatible. Synthetic oil formulations command the deepest margin pools due to formulation complexity and replacement cost avoidance in high-temperature chemical processing. Silicone oil demand is accelerating fastest in electronics cooling and precision HVAC systems where thermal stability across wide temperature swings outweighs first-cost premiums. Mineral oil retains volume leadership in legacy power generation and paper mill applications where capital constraints resist fluid system upgrades.
EPA toxicity evaluations under the Toxic Substances Control Act and REACH substance restrictions administered by ECHA are jointly narrowing the aromatic hydrocarbon segment and elevating registration burdens for new chemistries. OSHA process safety management requirements and ISO 9001 quality system certifications further condition market access for suppliers serving regulated industries. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as precursor chemistries in some synthetic base stocks face heightened scrutiny in multiple jurisdictions.
Market Dynamics
Chemical processors are retiring mineral oil systems at scale, compelled by REACH substance restrictions and EPA toxicity protocols that disqualify high-aromatic formulations from new project specifications. This regulatory compression is redrawing supplier qualification criteria and accelerating reformulation cycles across the installed base.
Growth Catalysts
- REACH aromatic restrictions:ECHA's tightened substance evaluations are forcing European chemical plants to replace legacy mineral oils with synthetic alternatives, creating immediate demand for qualified low-toxicity formulations.
- Data center thermal loads:Hyperscale computing facilities in North America are adopting silicone-based coolants to manage chip-level heat flux densities that exceed water-glycol operational limits.
- German production clustering:BASF and Lanxess have concentrated formulation expertise around Ludwigshafen and Leverkusen, drawing regional process industries into their supply orbits through technical service bundling.
Market Restraints
- Silicone feedstock concentration:Four integrated chemical producers control over seventy percent of dimethylsiloxane monomer supply, exposing formulators to price volatility and allocation risk.
- High-temperature mineral oil persistence:Capital-constrained paper mills and legacy power plants in Eastern Europe resist fluid system upgrades despite synthetic performance advantages.
- ECHA registration burdens:New chemistry introductions face eighteen-to-thirty-six-month evaluation timelines and six-figure registration fees that deter mid-scale formulators from portfolio expansion.
Strategic Opportunities
- Indian chemical processing expansion:BIS standards adoption and PLI scheme incentives are attracting multinational formulators to establish local blending capacity for domestic specialty chemical producers.
- Predictive degradation analytics:IoT sensor integration with thermal monitoring platforms enables subscription-based fluid lifecycle management that locks in long-term supply relationships.
- Maritime waste heat recovery:IMO efficiency mandates are driving adoption of organic Rankine cycle systems aboard cargo vessels, opening a specialized high-margin application segment.
Industry Challenges
- Thermal fluid safety engineering expertise:OSHA process safety management compliance requires specialized personnel that smaller industrial facilities struggle to recruit and retain.
- Legacy system incompatibility:Synthetic oil conversions demand gasket replacement, metallurgical review, and cleaning protocols that extend project timelines and inflate total installation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Transfer Fluids Market |
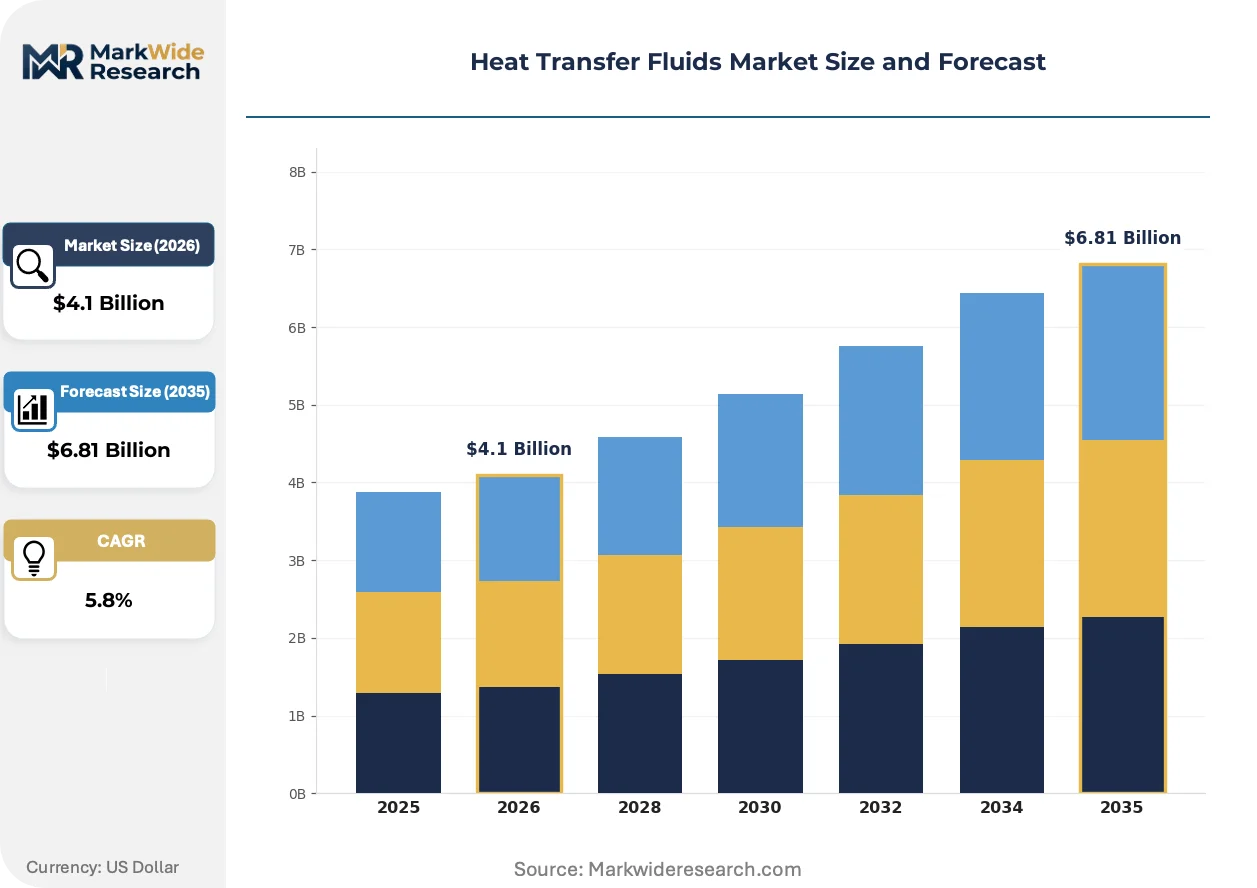
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Glycol, Silicone Oil, Aromatic Hydrocarbon, Mineral Oil, Synthetic Oil Technology: Direct Contact, Indirect Contact, Phase Change, Convection Application: Power Plants, Chemical Processing, Food Processing, HVAC Systems, Electronics Cooling End User Industry: Manufacturing Plants, Refineries, Data Centers, Thermal Energy Storage, Paper Mills |
| Companies Covered | ExxonMobil, Clariant, BASF SE, Lanxess, Huntsman Corporation, Dow, Shell plc, Chevron Corporation, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Transfer Fluids Market Strategic Shifts & Innovations
Digital fluid monitoring systems are compressing maintenance cycles and enabling predictive intervention models that reshape supplier-customer relationships. Three converging developments are restructuring competitive positioning.
AI-enabled thermal monitoring is automating degradation detection in closed-loop chemical processing systems. Dow and Clariant are deploying sensor networks across North American and European customer sites to capture real-time viscosity and acid number data. This capability is automating the transition from scheduled drain intervals to condition-based maintenance, collapsing traditional fluid consumption patterns.
EPA's updated Toxic Substances Control Act screening protocols are narrowing the aromatic hydrocarbon segment and elevating registration burdens for new synthetic base stocks. Chemical processors in regulated industries now require full material disclosure and third-party toxicity certification before fluid approval. The impact concentrates most severely on smaller formulators serving batch chemical producers in the US Gulf Coast region.
Service unbundling is fragmenting long-term supply contracts into discrete thermal monitoring subscriptions, fluid analysis packages, and predictive analytics modules. Data center operators and precision manufacturers are adopting this à-la-carte procurement model to match spending with actual thermal system performance. Germany and the Netherlands show the fastest adoption of unbundled service architectures among European process industries.
Heat Transfer Fluids Market Segmentation
Heat transfer fluid procurement decisions hinge on certification requirements that vary sharply across product chemistries and application temperatures. Regulatory alignment with EPA toxicity protocols, REACH substance restrictions, and OSHA process safety mandates determines supplier qualification and segment accessibility.
Product Type:
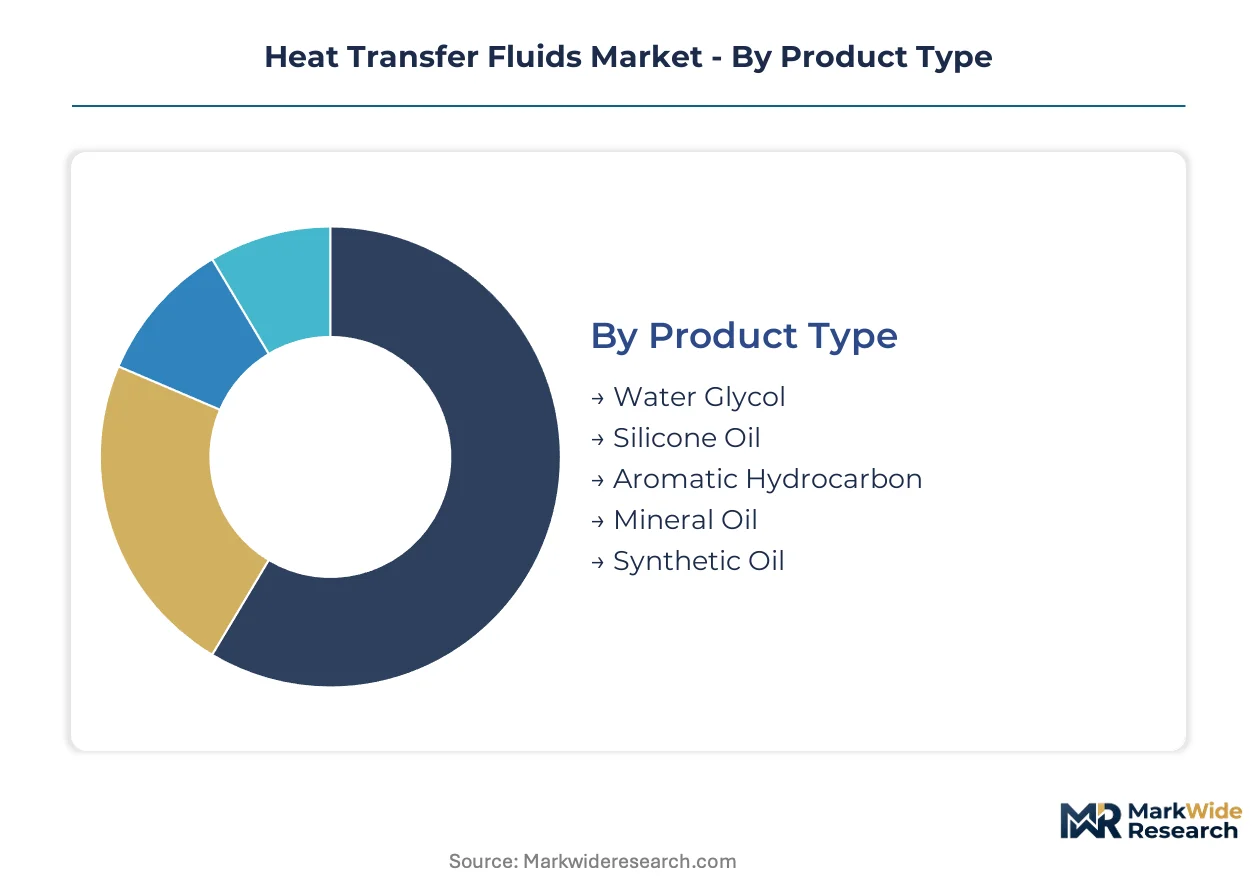
REACH substance restrictions and EPA toxicity evaluations under the Toxic Substances Control Act create divergent compliance burdens across base stock categories, with aromatic hydrocarbon formulations facing the steepest registration barriers.
- Synthetic Oil:Formulated from hydrogenated polyalphaolefins and alkylated aromatics engineered for thermal stability above three hundred degrees Celsius. Demand concentrates in German chemical processing clusters around Ludwigshafen, where BASF and Lanxess anchor production ecosystems serving European specialty chemical producers. REACH compliance costs and replacement cost avoidance in high-temperature loops sustain premium positioning.
- Silicone Oil:Dimethylsiloxane polymer formulations delivering thermal stability across minus forty to four hundred degree Celsius operating windows. North American data center operators in Virginia and Texas are adopting silicone-based coolants for chip-level heat flux densities exceeding water-glycol operational limits, with Dow leveraging formulation expertise to anchor long-term service contracts.
- Mineral Oil:Refined petroleum distillates with inhibited additive packages dominate legacy power generation and paper mill applications in Eastern Europe where capital constraints resist fluid system upgrades.
- Water Glycol:Inhibited aqueous solutions formulated for freeze protection and moderate temperature ranges serve HVAC systems and food processing equipment requiring non-toxic, biodegradable chemistries.
- Aromatic Hydrocarbon:High-aromatic mineral oil derivatives facing disqualification from new project specifications under tightened EPA toxicity screening protocols and ECHA substance evaluations.
Leading the category by volume: Mineral Oil. Growing fastest: Silicone Oil.
Technology:
Cost tier differentiation separates mature convection systems from premium direct contact implementations in precision thermal management applications.
- Direct Contact:Fluid immersion of heat-generating components eliminates thermal interface resistance, commanding premium positioning in electronics cooling for hyperscale computing facilities.
- Indirect Contact:Closed-loop heat exchanger configurations with physical separation between fluid and process streams dominate chemical processing and power generation where contamination risks mandate barrier protection.
- Phase Change:Latent heat absorption during liquid-to-vapor transition enables high heat flux management in specialized semiconductor manufacturing equipment.
- Convection:Forced or natural circulation without phase change serves baseline thermal loads in HVAC and legacy industrial applications with lowest capital requirements.
Highest installed base: Convection. Steepest expansion trajectory: Direct Contact.
Application:
Customer type fragmentation splits procurement between asset-intensive process industries and infrastructure operators with divergent technical service expectations.
- Chemical Processing:Continuous reactor heating and distillation column temperature control in German and US Gulf Coast facilities drives synthetic oil specification for thermal stability above three hundred degrees Celsius.
- Electronics Cooling:Hyperscale data centers in North America and precision manufacturing in the Netherlands are adopting silicone-based immersion cooling for chip-level thermal management.
- Power Plants:Legacy steam cycle facilities and emerging organic Rankine cycle installations in maritime applications specify mineral and synthetic formulations respectively.
- HVAC Systems:Commercial and industrial building thermal networks in urban centers deploy water-glycol and silicone solutions for freeze protection and wide-temperature operation.
- Food Processing:Edible oil heating and chocolate tempering applications require NSF-registered, non-toxic formulations with full material disclosure.
Deepest margin pool: Chemical Processing. Gaining share fastest: Electronics Cooling.
End User Industry:
Supply concentration around integrated chemical producers shapes regional availability and technical service bundling across end user categories.
- Data Centers:Hyperscale operators in Virginia, Texas, and Frankfurt specify silicone immersion coolants for artificial intelligence training clusters exceeding traditional air-cooling capacity.
- Refineries:Catalytic reforming and hydrocracker units in US Gulf Coast and Rotterdam-Antwerp corridor require synthetic formulations for high-temperature hydrogen-rich environments.
- Manufacturing Plants:General industrial thermal processes span the full product type spectrum based on temperature requirements and capital upgrade cycles.
- Thermal Energy Storage:Concentrated solar power and district heating systems in Spain and Denmark utilize specialized synthetic and silicone formulations for daily heat cycling.
- Paper Mills:Drying section steam systems in Eastern Europe and Southeast Asia retain mineral oil specifications due to extended capital replacement timelines.
Most procurement volume: Manufacturing Plants. Climbing the fastest: Data Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates synthetic oil formulation capacity while the United States drives silicone coolant adoption in hyperscale computing. India and China are expanding domestic blending infrastructure to serve chemical processing growth. Eastern European paper mills and Latin American refineries retain legacy mineral oil specifications due to capital constraints.
United States
Hyperscale data centers in Virginia and Texas specify silicone immersion coolants for artificial intelligence training clusters exceeding air-cooling limits. EPA toxicity screening protocols under the Toxic Substances Control Act disqualify high-aromatic formulations from federal project specifications. Dow leverages formulation expertise to anchor service relationships across North American data center operators through thermal monitoring subscriptions.
Germany
BASF and Lanxess anchor production clusters around Ludwigshafen and Leverkusen serving European specialty chemical producers. REACH substance restrictions administered by ECHA force replacement of legacy mineral oils with synthetic alternatives in continuous reactor systems. German process industries bundle technical service contracts with fluid supply agreements, locking in long-term supplier relationships.
China
Domestic chemical processing expansion drives demand for high-temperature synthetic formulations in hydrogen-rich catalytic reforming units. MIIT industrial standards and dual carbon goals accelerate retirement of inefficient mineral oil systems in coastal manufacturing zones. Yangtze River Delta chemical producers are upgrading fluid specifications to meet export market registration requirements.
India
BIS standards adoption and PLI scheme incentives attract multinational formulators to establish local blending capacity for domestic specialty chemical producers. Maharashtra and Gujarat chemical corridors specify synthetic oils for new continuous process installations requiring thermal stability above three hundred degrees Celsius. Indian formulators face eighteen-to-thirty-six-month ECHA-equivalent registration timelines for novel base stock chemistries.
Saudi Arabia
Refinery expansion in Jubail and Yanbu drives specification of synthetic formulations for high-temperature hydrocracker units in hydrogen-rich environments. The country's national industrial regulator mandates process safety management compliance for thermal fluid systems in petrochemical complexes. Eastern Province production clusters source formulated fluids through long-term supply contracts with integrated service bundling.
Heat Transfer Fluids Market Key Industry Players
Top-tier vendors anchor premium synthetic and silicone formulations, while mid-scale regional blenders compete on price in mineral oil segments. The vendor base spans integrated petrochemical majors, specialized additive houses, and regional distributors with formulation capabilities. Strategic archetypes include technology licensors with proprietary base stock patents, service-integrated suppliers bundling monitoring analytics, and commodity distributors with regional logistics networks. Dominant competitive moves encompass backward integration into dimethylsiloxane monomer supply and geographic expansion through local blending joint ventures.
Among integrated petrochemical majors, ExxonMobil and Shell plc exemplify scale-driven archetypes with captive base stock production and maritime service networks. Dow occupies a position representing silicone specialization, leveraging polymer expertise to anchor data center cooling relationships through predictive degradation analytics. Clariant sits within the additive-specialist tier, competing through formulated packages that extend drain intervals in chemical processing loops rather than base stock manufacturing.
| Leading Market Players |
|---|
| ExxonMobil |
| Clariant |
| BASF SE |
| Lanxess |
| Huntsman Corporation |
| Dow |
| Shell plc |
| Chevron Corporation |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
Silicone polymer production methods are shifting toward continuous flow chemistry, simultaneously compressing unit economics and concentrating dimethylsiloxane supply among four integrated producers. This dual effect tightens pricing power at the base stock tier while amplifying volatility exposure for downstream formulators serving data center and chemical processing customers.
Pricing Analysis
Margin tightening in synthetic oil formulations reflects REACH registration cost pass-through and specialized additive bundling. Three-tier pricing structure across premium, standard, and economy levels separates NSF-registered food-grade specifications from industrial mineral oil grades. Cost compression in aromatic hydrocarbon segments accelerates because EPA toxicity protocols disqualify high-aromatic formulations from federal project specifications. Price-sensitive paper mills in Eastern Europe resist synthetic upgrades despite performance advantages, while data center operators absorb silicone premiums for thermal stability.
Supply Chain Analysis
Dimethylsiloxane monomer supply rests on integrated chemical producers concentrated in Germany, the United States, and China. Formulators draw from hydrogenated polyalphaolefin base stocks, silicone polymer feedstocks, and corrosion inhibitor additive packages. Single-source vulnerability concentrates in dimethylsiloxane allocation, where four producers control over seventy percent of global supply. Distribution runs through regional blending facilities with technical service bundling, anchored by production clusters around Ludwigshafen, Leverkusen, and the US Gulf Coast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic oil formulations are displacing mineral oil systems in chemical processing, driven by REACH aromatic restrictions and EPA toxicity protocols that disqualify legacy formulations from new project specifications.
For Market Incumbents: Cement service-integrated supply relationships through predictive degradation analytics subscriptions that lock in long-term thermal monitoring contracts. Deepen backward integration into dimethylsiloxane monomer supply to defend against silicone feedstock concentration risk. Prioritize certification investment for NSF-registered food-grade formulations as specialty chemical producers demand full material disclosure. For New Entrants and Emerging Players: Capture Indian chemical processing expansion by establishing local blending capacity in Maharashtra and Gujarat corridors under BIS standards adoption. Target maritime waste heat recovery applications for organic Rankine cycle systems, where IMO efficiency mandates create specialized high-margin demand with limited incumbent presence. Lead with fluid lifecycle management services rather than commodity supply to differentiate from established formulators. For Investors and Strategic Acquirers: Exit pathways concentrate in additive-specialist acquisitions that extend drain intervals through formulated packages rather than base stock manufacturing. Long-term viability favors service-integrated suppliers with IoT-enabled thermal monitoring platforms and predictive analytics capabilities. Watch ECHA substance evaluation timelines as inflection indicators for accelerated mineral oil replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dimethylsiloxane | Captive monomer supply insulates formulators from allocation volatility in silicone feedstock markets. |
| Predictive Degradation Analytics Platform | IoT sensor integration enables subscription revenue streams that displace transactional fluid sales. |
| Local Blending Joint Venture | Indian PLI scheme incentives attract multinational capacity for domestic specialty chemical producers. |
| NSF Food-Grade Certification Investment | Full material disclosure requirements in food processing create defensible premium positioning. |
| Maritime Service Network Expansion | On-site fluid analysis capabilities replace routine changeouts in remote power applications. |
Research Approach
Independent corroboration across plant managers at chemical processing facilities, procurement leads at downstream OEMs, and technical R&D directors at formulation houses underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings of integrated petrochemical majors. Bottom-up segmentation modeling triangulates against top-down market sizing from production capacity and consumption pattern analysis.
Comparable-period anchoring to historical synthetic oil and silicone formulation adoption curves shapes the projection horizon across product type, application temperature tier, and regional regulatory cluster dimensions. CAGRs derive from segment-level growth trajectory analysis incorporating REACH compliance cost pass-through, data center thermal load expansion, and mineral oil replacement cycle timing. Forecast inputs include ECHA substance evaluation timelines and hyperscale computing facility deployment patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dimethylsiloxane supply allocation disruptions and per- and polyfluoroalkyl substance regulatory expansion. Assumptions reflect current EPA toxicity screening protocols and ECHA registration burdens, with revision triggers centered on evolving PFAS restrictions and maritime efficiency mandate acceleration. A small set of regulatory and feedstock triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Soil Treatment Chemicals Market