
 Corrosion Protection Polymer Coating Market | 2026-2036
Corrosion Protection Polymer Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Corrosion Protection Polymer Coating Market Analysis
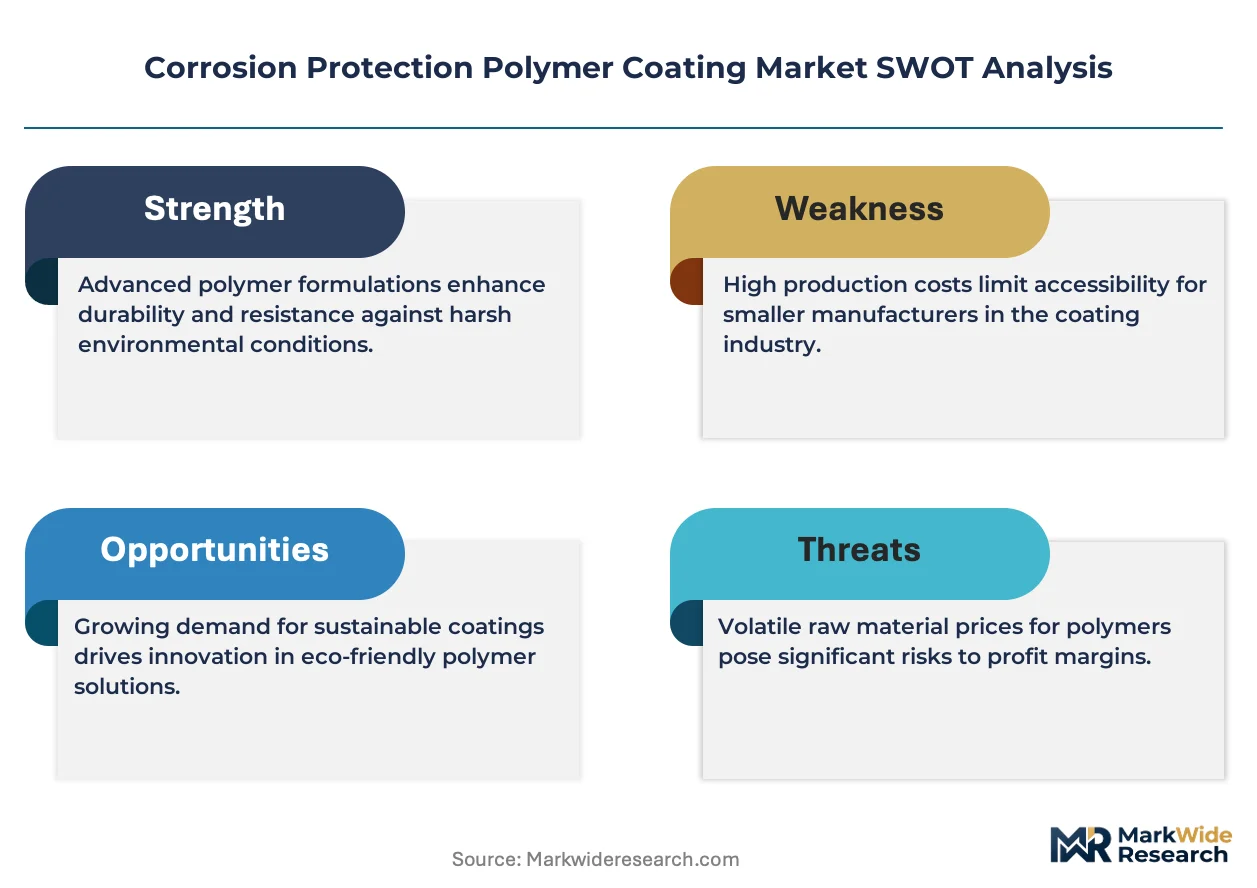
REACH compliance is pivoting the European corrosion protection polymer coating sector toward waterborne and high-solids formulations that slash volatile organic compound emissions. BASF leverages its integrated resin and additive portfolio to supply compliant binder chemistries at scale. Axalta Coating Systems anchors its position through dedicated R&D centers in Germany and the United States that focus on next-generation epoxy primers. PPG Industries, Inc. competes by controlling direct-to-fabricator channels across marine and energy end uses.
Corrosion protection polymer coatings are barrier-forming systems, typically comprising epoxy resins, polyurethane binders, or zinc-rich sacrificial pigments applied at dry-film thicknesses of 75–500 microns, designed to inhibit electrochemical degradation of steel and aluminum substrates in aggressive environments. Epoxy coatings dominate the product type landscape due to their adhesion strength and chemical resistance in submerged industrial settings. Polyurethane coatings represent the fastest-expanding category, driven by demand for UV-stable topcoats in marine structures and automotive components where aesthetic durability intersects with functional protection. Pipelines and marine structures command the deepest margin pools within the application dimension, reflecting the cost of failure in subsea and hydrocarbon transport infrastructure.
The EPA enforces stringent VOC limits under NESHAP standards that reshape formulation choices across U.S. manufacturing and energy facilities. ECHA administers REACH authorization and restriction processes that filter non-compliant chemistries from European supply chains. China's MEE implements dual carbon goals that tighten emissions scrutiny on solvent-based coating operations in Shandong and Jiangsu provinces. Stakeholders must monitor how regulatory divergence between these jurisdictions fragments formulation standards and reshapes regional sourcing strategies.
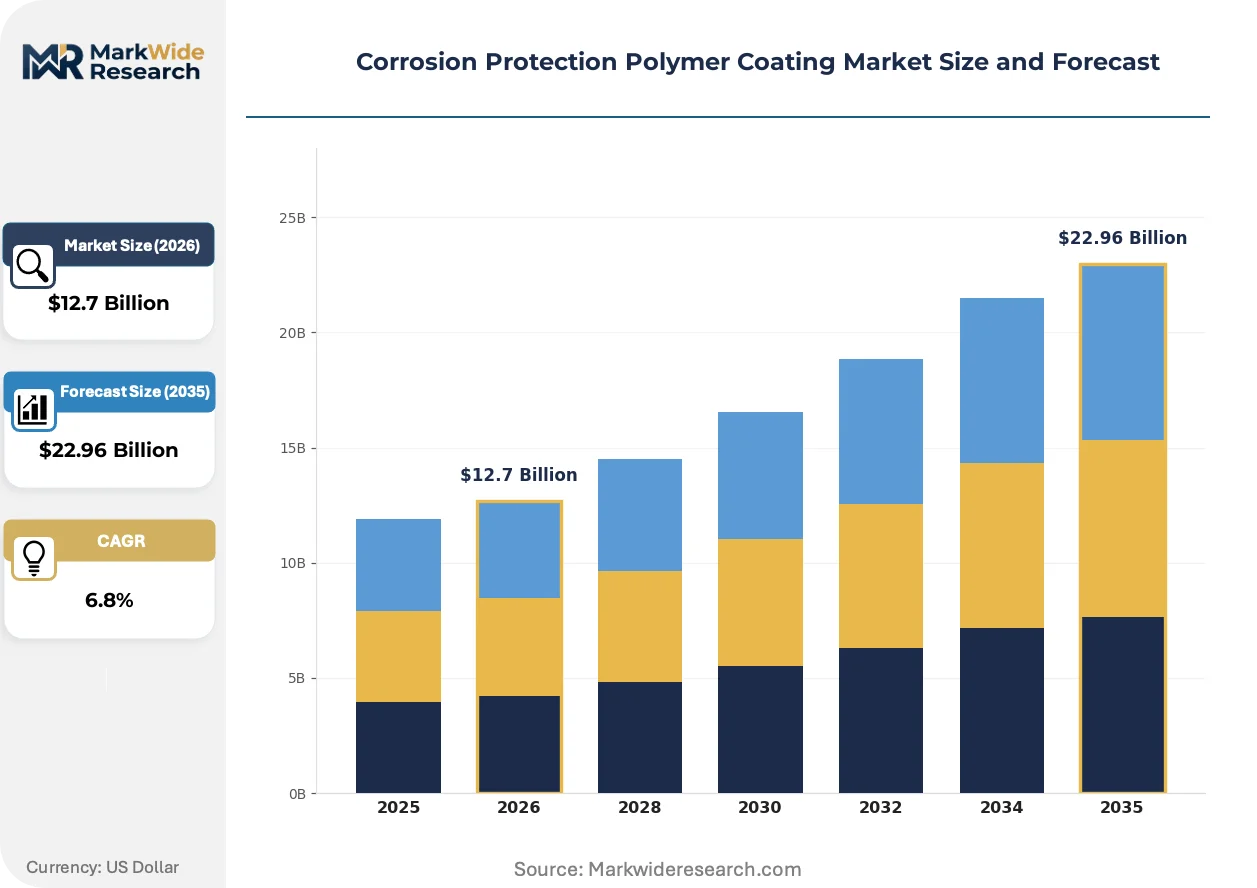
Market Dynamics
Offshore oil and gas infrastructure expansion is compressing specification cycles for corrosion protection systems, forcing coating suppliers to validate performance under deeper subsea pressures and longer asset lifespans than historical benchmarks required.
Growth Catalysts
- Port and refinery buildouts in China:Jiangsu and Shandong provinces are expanding hydrocarbon processing capacity and maritime logistics infrastructure, generating concentrated demand for high-performance epoxy and polyurethane coating systems.
- REACH authorization timelines:ECHA's phased restriction of chromium trioxide and other hazardous substances is accelerating qualified supplier status for coatings manufacturers with compliant waterborne formulations already in commercial production.
- Subsea tieback engineering:Deepwater field development in the Gulf of Mexico and West Africa is specifying 500-micron dry-film thickness systems with 25-year design lives, pulling advanced polymer chemistries into frontline deployment.
Market Restraints
- Zinc metal price volatility:Sacrificial zinc-rich primers depend on London Metal Exchange zinc pricing that has fluctuated within a 40% band, compressing margin predictability for applicators and specifiers.
- Epoxy resin supply concentration:Bisphenol A and epichlorohydrin production clusters in Northeast Asia create geographic concentration risk that disrupts coating formulation when regional logistics constrain feedstock movement.
- Cure temperature limitations:Ambient-cure epoxy systems face performance ceilings in sub-zero installation environments, restricting year-round application windows in North Sea and Arctic infrastructure projects.
Strategic Opportunities
- Floating offshore wind foundations:Monopile and semi-submersible platform fabrication in Scotland and Norway is creating specification pull for UV-stable polyurethane topcoats that resist splash-zone fatigue.
- Carbon border adjustment mechanism:EU CBAM phase-in creates compliance-driven preference for European-manufactured coatings with verified embodied carbon credentials, favoring local production scale-up.
- Drone-assisted inspection integration:Coating applicators partnering with unmanned aerial system providers can embed condition-monitoring data into warranty structures, creating differentiated service bundles.
Industry Challenges
- NACE/SSPC certification bottlenecks:Inspector qualification backlogs in coating specification review are extending project tender timelines and compressing contractor mobilization windows.
- Legacy solvent-based inventory stranding:Applicators with stocked high-VOC systems face write-down pressure as EPA NESHAP enforcement tightens and state-level air quality regulations advance compliance deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrosion Protection Polymer Coating Market |
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Coatings, Polyurethane Coatings, Acrylic Coatings, Zinc-Rich Coatings Application: Industrial Equipment, Marine Structures, Automotive Components, Pipelines End User: Construction, Oil & Gas, Automotive, Aerospace Delivery Mode: Spray Application, Brush Application, Roll Application, Electric Application |
| Companies Covered | BASF, Axalta Coating Systems, PPG Industries, Inc., Kansai Paint Co., Ltd., Hempel, AkzoNobel N.V., Jotun, Ashland Inc., The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrosion Protection Polymer Coating Market Emerging Trajectories
Polymer coating formulation is pivoting toward bio-based feedstocks and self-healing chemistries that extend maintenance intervals. Digital specification tools are compressing the distance between asset owner requirements and applicator compliance documentation.
Graphene-reinforced epoxy nanocomposites are rewriting durability benchmarks for immersed steel protection. Offshore platform operators in the North Sea are piloting these systems at 150-micron thicknesses that match 300-micron conventional coating performance. The technology is compressing material volume requirements and enabling lighter structural designs without sacrificing corrosion resistance.
EPA NESHAP Subpart HHHHHH enforcement is tightening volatile organic compound limits for surface coating of metal parts and products. Manufacturing facilities in Texas and Louisiana are retrofitting spray booths with thermal oxidizers or switching to waterborne alkyd and acrylic systems. The regulatory pressure is fragmenting formulation standards between US Gulf Coast operations and export-oriented production lines serving less restrictive jurisdictions.
Asset owners are unbundling coating specification from general construction contracts, creating direct procurement relationships with certified applicators. Oil majors in Brazil and Nigeria are issuing standalone coating work packages with performance warranties independent of EPC contractor liability. The channel shift is visible most acutely in pre-salt field development where coating failure costs exceed construction contingency budgets by an order of magnitude.
Corrosion Protection Polymer Coating Market Segmentation
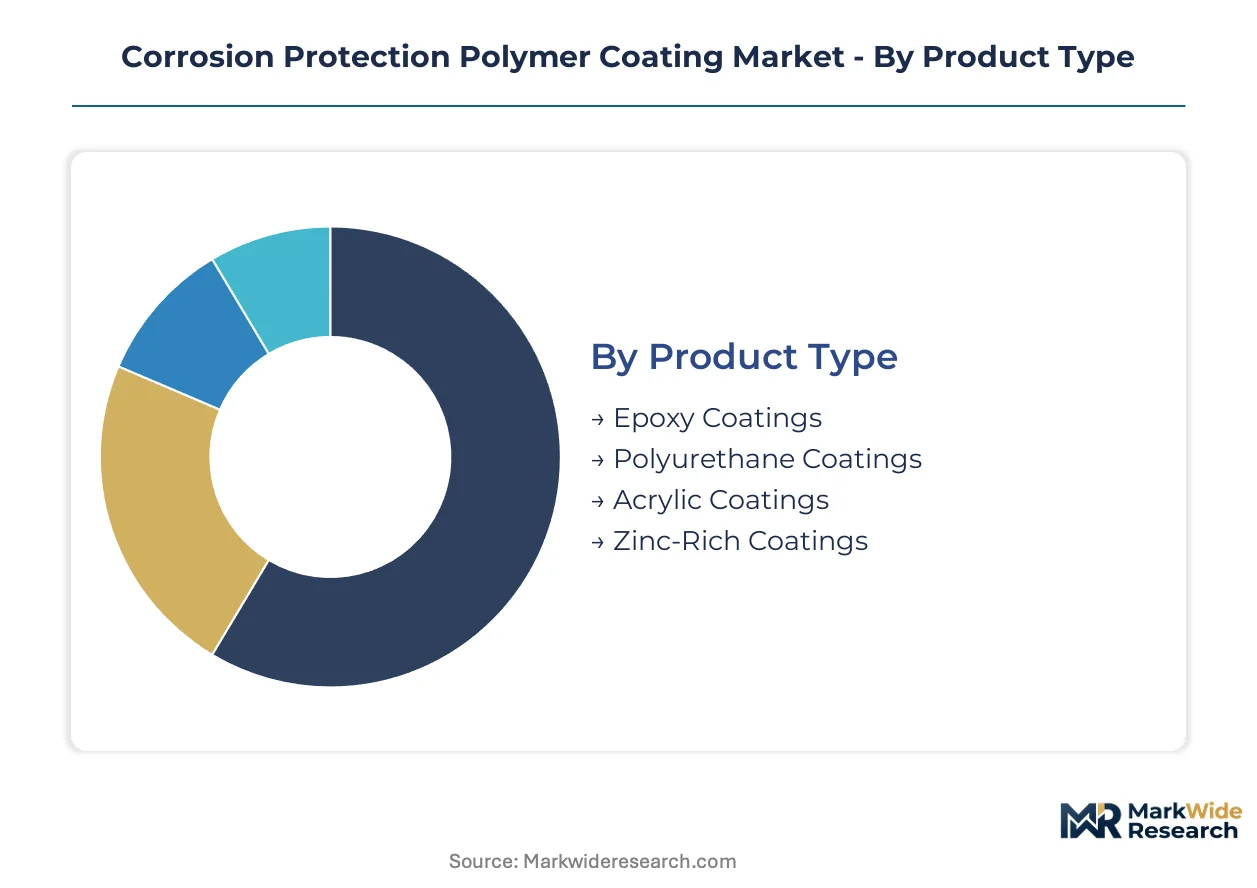
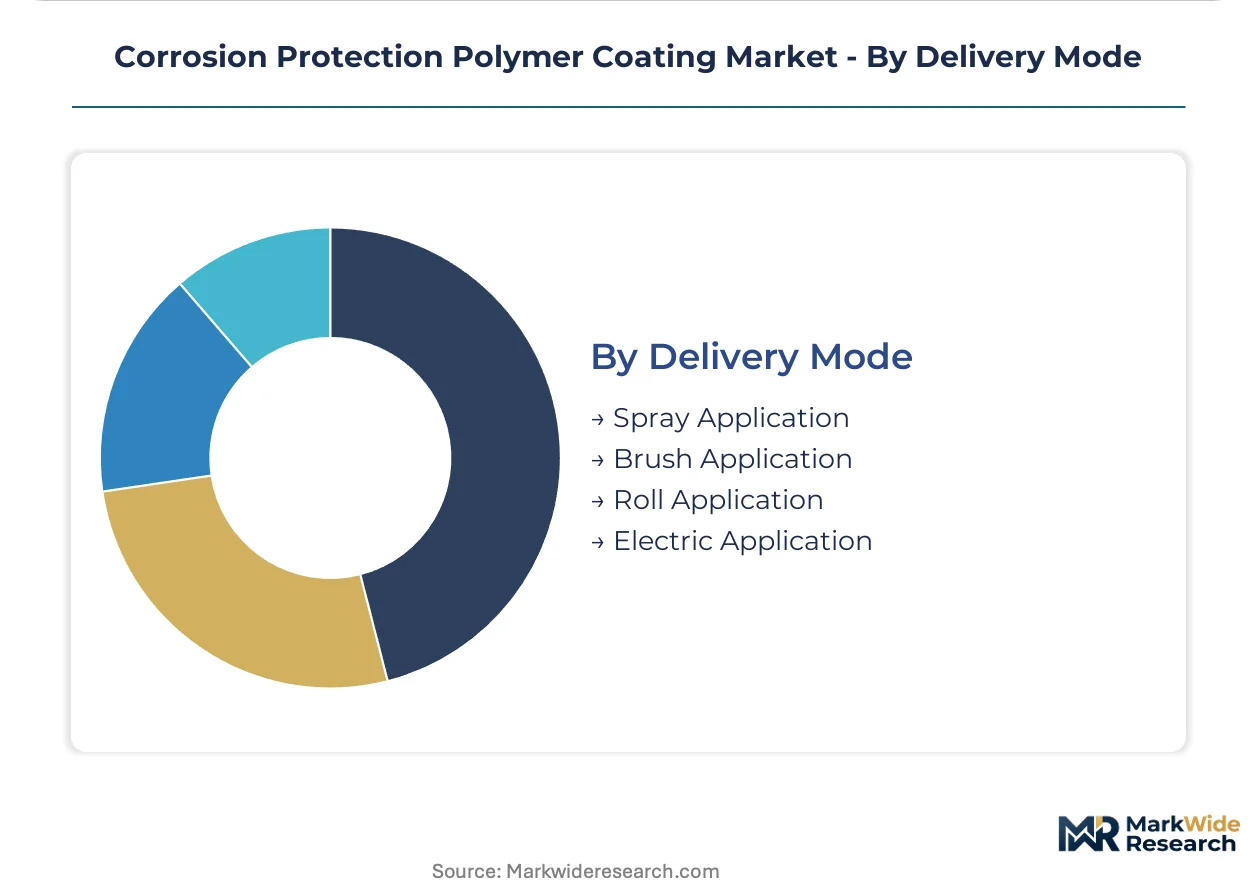
Corrosion protection polymer coatings segment across formulation chemistry, deployment environment, and application method. Specification cycles vary dramatically between submerged marine systems and atmospheric industrial service. Each axis carries distinct margin structures and regulatory compliance burdens.
Product Type:
Formulation chemistry determines barrier mechanism, cure kinetics, and environmental resistance profile.
- Epoxy Coatings:Two-component amine-cured systems deliver dense cross-linked films with exceptional adhesion to blast-cleaned steel. Demand concentrates in Gulf of Mexico offshore platforms where 500-micron systems must withstand cathodic disbondment at depths exceeding 1,500 meters. Subsea tieback engineering specifications favor epoxy primers for their chemical resistance against sour gas exposure.
- Polyurethane Coatings:Aliphatic isocyanate-cured topcoats provide UV stability and gloss retention for atmospheric service. Marine structures in the North Sea and floating offshore wind foundations in Scotland specify these for splash-zone fatigue resistance where aesthetic durability intersects functional protection. Polyurethane represents the steepest expansion trajectory among product types.
- Acrylic Coatings:Thermoplastic emulsion systems offer rapid dry-to-touch properties for maintenance painting in operational facilities.
- Zinc-Rich Coatings:Sacrificial primers with metallic zinc loading above 80% by weight provide galvanic protection to steel substrates.
Mature deployment sits with epoxy systems in offshore hydrocarbon infrastructure. Newer deployment is concentrated in polyurethane topcoats for renewable energy structures.
Application:
Environmental exposure severity dictates dry-film thickness requirements and re-coating intervals.
- Marine Structures:Immersed and splash-zone steel on platforms, jetties, and ship hulls demand high-build systems with cathodic protection compatibility. Specifications from oil majors in Brazil and Nigeria now require 25-year design lives with performance warranties decoupled from EPC contractor liability. The cost of coating failure in pre-salt fields drives premium specification tiers.
- Pipelines:External anti-corrosion coatings for buried and subsea hydrocarbon transport face fusion-bonded epoxy competition. Deepwater field development in West Africa pulls advanced polymer chemistries into frontline deployment where thermal insulation and mechanical protection layers integrate with corrosion barriers.
- Industrial Equipment:Atmospheric service coatings for processing vessels and storage tanks prioritize chemical resistance against acid and solvent exposure.
- Automotive Components:Underbody and chassis coatings balance stone-chip resistance with electrochemical protection in salt-laden environments.
Marine applications anchor margin pools through warranty-backed performance specifications. Pipeline coatings are gaining share fastest as subsea tieback engineering accelerates.
End User:
Asset ownership models determine procurement channel structure and specification authority.
- Oil & Gas:International oil companies and national oil companies drive the most demanding specification environments. Direct procurement relationships with certified applicators are unbundling coating work from general construction contracts. NACE/SSPC certification requirements create inspector qualification bottlenecks that extend project tender timelines.
- Construction:Infrastructure and commercial building owners specify coatings for structural steel in aggressive atmospheric environments.
- Automotive:OEM and tier supplier specifications emphasize process compatibility with electrocoating lines and robotic application.
- Aerospace:MRO and manufacturing specifications prioritize chromate-free pretreatments and low-VOC compliant systems.
Oil and gas end users concentrate the highest performance tier demand. Construction sector procurement is expanding most quickly as infrastructure buildouts accelerate in China.
Delivery Mode:
Application method constrains formulation viscosity, cure chemistry, and field productivity.
- Spray Application:Airless and plural-component spray dominates high-volume industrial and marine projects. EPA NESHAP Subpart HHHHHH enforcement is forcing retrofit of spray booths with thermal oxidizers or conversion to waterborne systems in Texas and Louisiana manufacturing facilities.
- Brush Application:Manual stripe coating and touch-up work persists in complex geometry and confined space access.
- Roll Application:Large flat surfaces in tank lining and marine deck systems achieve high transfer efficiency.
- Electric Application:Electrostatic spray and electrodeposition methods serve automotive and appliance manufacturing lines.
Spray application commands volume leadership in heavy industrial sectors. Electric application methods are climbing fastest as automotive OEMs expand coating line capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's free-trade zone status concentrates refinery construction and maritime logistics expansion, drawing coating specification toward high-build epoxy systems. Jiangsu's port infrastructure buildout generates parallel demand for subsea-grade formulations.
China
Jiangsu and Shandong provinces anchor hydrocarbon processing expansion and deepwater port construction, concentrating procurement for 500-micron epoxy systems. MEE dual carbon goals tighten emissions scrutiny on solvent-based operations, forcing reformulation toward waterborne chemistries. Ningbo-Zhoushan port cluster specifications now require 25-year design life warranties for immersed steel protection.
United States
Gulf of Mexico deepwater tieback engineering pulls advanced polymer chemistries into frontline deployment at depths exceeding 1,500 meters. EPA NESHAP Subpart HHHHHH enforcement tightens VOC limits across Texas and Louisiana manufacturing facilities, retrofitting spray booths with thermal oxidizers. Houston-Galveston corridor fabricators validate ambient-cure epoxies for sub-zero North Sea export specifications.
Germany
North Sea offshore wind foundation fabrication drives specification for UV-stable polyurethane topcoats resisting splash-zone fatigue. ECHA REACH authorization timelines for chromium trioxide accelerate qualified supplier status for waterborne formulation manufacturers. Hamburg-Bremen industrial cluster concentrates marine coating R&D and applicator certification capacity.
Norway
Floating offshore wind monopile and semi-submersible platform construction creates demand pull for UV-stable topcoat systems. Norwegian Petroleum Directorate regulations mandate extended asset integrity documentation for subsea infrastructure. Stavanger-Bergen corridor engineering offices unbundle coating procurement from EPC contracts with performance warranties.
Brazil
Pre-salt field development specifications decouple coating liability from construction contractor responsibility, creating direct procurement relationships. ANVISA chemical registration requirements filter non-compliant binder chemistries from supply chains. Rio de Janeiro-São Paulo industrial corridor hosts certified applicators qualified to NACE/SSPC standards for 25-year subsea system warranties.
Corrosion Protection Polymer Coating Market Vendor Landscape
German and Dutch producers anchor the premium formulation tier; Japanese specialists hold positions in marine-grade epoxy innovation. The vendor base concentrates around integrated resin manufacturers and dedicated coating formulators serving energy infrastructure. Three archetypes dominate: integrated chemical conglomerates controlling binder supply chains, pure-play coating specialists with applicator certification networks, and regional formulators serving maintenance markets. Competitive moves center on REACH-compliant waterborne portfolio expansion and direct-to-fabricator channel control.
Within the integrated chemical tier, BASF anchors positions through captive resin and additive supply. Axalta Coating Systems and PPG Industries, Inc. exemplify the specialist-formulator archetype with dedicated R&D infrastructure and direct channel relationships across marine and energy end uses. These three occupy positions where specification authority concentrates among international oil companies and national oil companies demanding performance-backed warranties.
| Leading Market Players |
|---|
| BASF |
| Axalta Coating Systems |
| PPG Industries, Inc. |
| Kansai Paint Co., Ltd. |
| Hempel |
| AkzoNobel N.V. |
| Jotun |
| Ashland Inc. |
| The Sherwin-Williams Company |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange zinc pricing cascades through corrosion protection polymer coating supply chains, compressing margin predictability for sacrificial primer manufacturers and forcing tiered pricing structures that separate qualified REACH-compliant suppliers from spot-market commodity formulators.
Pricing Analysis
Short lead-time premiums compress standard-tier margins as Gulf of Mexico offshore operators demand 48-hour mobilization for subsea repair campaigns. Three-tier pricing structure across premium, standard, and economy levels separates NACE/SSPC-certified applicators with performance warranties from uncertified maintenance contractors. Pricing pressure stems from zinc metal volatility and epoxy resin feedstock concentration in Northeast Asia. Maintenance contractors in operational facilities exhibit highest price sensitivity, while pre-salt field operators in Brazil prioritize failure-cost avoidance over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from international oil companies require qualified applicators to maintain approved relationships with at least two coating manufacturers for critical subsea systems. Bisphenol A and epichlorohydrin production clusters in China, South Korea, and Japan create geographic concentration risk that disrupts formulation when regional logistics constrain feedstock movement. Supply chain vulnerability centers on single-source dependency for specialized amine curing agents. Distribution runs through direct-to-fabricator channels that bypass traditional EPC contractor procurement layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance timelines and EPA NESHAP enforcement are consolidating the corrosion protection polymer coating vendor base, eliminating formulators unable to absorb waterborne reformulation costs or thermal oxidizer retrofit investments.
For Market Incumbents: Acquire captive resin production capacity to secure bisphenol A supply during Northeast Asian logistics disruptions. Lock in direct procurement relationships with Ningbo-Zhoushan port cluster fabricators before EPC contractors reassert channel control. Defend against graphene-reinforced nanocomposite substitutes by accelerating pilot program partnerships with North Sea platform operators. For New Entrants and Emerging Players: Certified applicator networks represent the most penetrable channel entry point for standalone coating work packages decoupled from construction liability. Target floating offshore wind foundation specifications in Scotland and Norway where UV-stable polyurethane demand outpaces established supply. Lead with drone-assisted inspection bundling to differentiate warranty offerings beyond commodity formulation. For Investors and Strategic Acquirers: Distressed-cycle entries favor waterborne formulation specialists with qualified supplier status under ECHA authorization timelines in Germany and the Netherlands. Five-to-ten-year viability hinges on carbon border adjustment mechanism compliance positioning. Monitor zinc price volatility band widening as inflection signal for sacrificial primer margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Captive bisphenol A supply insulates BASF and Axalta from Northeast Asian feedstock disruption during peak Gulf of Mexico project cycles. |
| REACH-Compliant Waterborne Portfolio Expansion | ECHA chromium trioxide restrictions accelerate qualified supplier status for PPG Industries and Hempel in Hamburg-Bremen industrial cluster. |
| Direct-to-Fabricator Channel Control | Oil majors in Brazil and Nigeria unbundle coating procurement from EPC contracts, favoring certified applicators with standalone warranties. |
| Drone-Assisted Inspection Partnership | Coating applicators embedding unmanned aerial system data into warranty structures create differentiated service bundles against commodity competitors. |
| Floating Offshore Wind Specification Capture | Monopile and semi-submersible platform construction in Scotland and Norway pulls UV-stable polyurethane demand from established marine suppliers. |
Methodological Framework
Trade databases, ECHA authorization registries, and SEC manufacturing filings formed the secondary backbone for supply chain mapping and regulatory timeline validation. Primary interviews with coating formulator R&D directors, certified applicator operations managers, and oil major procurement leads triangulated specification cycle compression and channel shift dynamics. Bottom-up volume estimates from port construction databases and refinery expansion permits reconciled against top-down market sizing from chemical industry associations.
Historical trendline analysis of epoxy resin pricing volatility and zinc metal exchange movements informed elasticity assumptions across the projection horizon. Segmentation modeling incorporated formulation chemistry, deployment environment severity, application method constraints, and end-user procurement authority dimensions. CAGR derivation rested on subsea tieback engineering specification rates and floating offshore wind foundation fabrication schedules as industry-specific demand drivers.
Caveats apply where ECHA REACH authorization timeline acceleration or EPA NESHAP enforcement escalation could materially shift the outlook toward waterborne formulation adoption curves. Forecasts embed assumptions regarding zinc price band stability and Northeast Asian feedstock logistics continuity. A model refresh is warranted upon material change in carbon border adjustment mechanism phase-in schedules or floating offshore wind capacity auction results.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Japan Marine Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Marine Deck Coatings Market
Coatings
Anti Fog Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Fillers and Coating Market
Coatings
Global Polyurea Coating Market
Coatings
South Africa Automotive OEM Coatings Market
Coatings
US Antifouling Yacht Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Textile Coatings Market
Coatings
Heavy Duty Glass Coating Market
Coatings
Global Surface Protection Films Market