
 Soil Treatment Chemicals Market | 2026-2036
Soil Treatment Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Treatment Chemicals Market Analysis
North American agrochemical manufacturers is rebalancing output toward lower-toxicity soil fumigants after EPA phasedowns on methyl bromide alternatives. BASF SE leverages its R&D pipeline to sustain dominance in nematicide formulations. Novozymes A/S anchors the biological segment through enzymatic soil conditioning platforms. Corteva Agriscience competes via integrated seed-and-soil treatment bundles across Midwest corn-soy rotations.
Soil treatment chemicals encompass synthetic and biological formulations applied to arable land to modify pH, suppress pathogens, enhance nutrient availability, or restore microbial biomass; active ingredients range from chloropicrin and 1,3-dichloropropene to Bacillus subtilis-based inoculants, with application rates typically calibrated to soil organic matter content and cation exchange capacity. Fertility enhancers occupy the largest value pool due to recurring micronutrient replenishment cycles on degraded soils, while biopesticides represent the fastest-expanding category as residue-tolerant export markets tighten maximum residue limits. Liquid formulations command premium positioning in precision agriculture systems, whereas granular products retain cost advantages in broadacre developing-market applications.
EPA soil fumigant buffer zone requirements and EU REACH restrictions on chlorpropham shape product registration pathways and reformulation investments. India's Central Insecticides Board mandates extended field trial data for new soil actives, lengthening commercialization timelines. Brazil's ANVISA alignment with OECD test guidelines accelerates parallel submission strategies for multinational registrants. Stakeholders must monitor regulatory divergence between residue-limit jurisdictions to prioritize portfolio rebalancing toward biological and reduced-risk chemistries.
Market Dynamics
EPA buffer zone mandates for soil fumigants are compressing synthetic chemistry margins while redirecting R&D budgets toward microbe-based platforms that bypass restricted-use classifications entirely.
Growth Catalysts
- California specialty crop demand:Strawberry and almond producers in the Central Valley face methyl bromide phaseout deadlines, accelerating adoption of chloropicrin-1,3-D blends and biological nematicides.
- EU REACH restrictions on chlorpropham:The ban on potato sprout inhibitors creates immediate replacement demand for maleic hydrazide and 3-decen-2-one soil treatments across Northwest European storage operations.
- Enzymatic soil conditioning:Novozymes' glucanase and chitinase platforms restore microbial biomass in degraded Brazilian cerrado soils, opening recurring subscription revenue streams tied to harvest cycles.
Market Restraints
- Petrochemical feedstock volatility:Chloropicrin and 1,3-dichloropropene production depends on ethylene and chlorine derivatives, exposing formulators to Gulf Coast refinery margin swings.
- Chinese active ingredient concentration:Over sixty percent of technical-grade organophosphates and pyrethroids originate from Jiangsu and Shandong provinces, creating single-source vulnerability for multinational blenders.
- Extended field trial timelines:India's Central Insecticides Board mandates three-season efficacy data for new soil actives, stretching registration cycles to seven years versus four in OECD-aligned jurisdictions.
Strategic Opportunities
- Brazilian government-backed soil health programs:The ABC+ Plan subsidizes biological inoculants and cover crop integration, creating procurement channels for microbe-based platform providers.
- Precision agriculture integration:Variable-rate liquid application systems in Midwest corn-soy rotations enable site-specific nematicide dosing, reducing per-hectare chemical load while preserving yield targets.
- Residue-tolerant export market access:Japan's MRL tightening on chlorothalonil and mancozeb residues redirects Chinese vegetable exporters toward biofungicide-treated soils to maintain supermarket shelf access.
Industry Challenges
- Microbiome formulation stability:Bacillus subtilis and Trichoderma harzianum spore viability degrades rapidly in non-refrigerated distribution chains, requiring cold-chain investments that granular synthetics avoid.
- Soil organic matter calibration complexity:Cation exchange capacity and pH variability across field zones demands agronomist-intensive prescription mapping, slowing biological product adoption among cost-sensitive broadacre operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Treatment Chemicals Market |
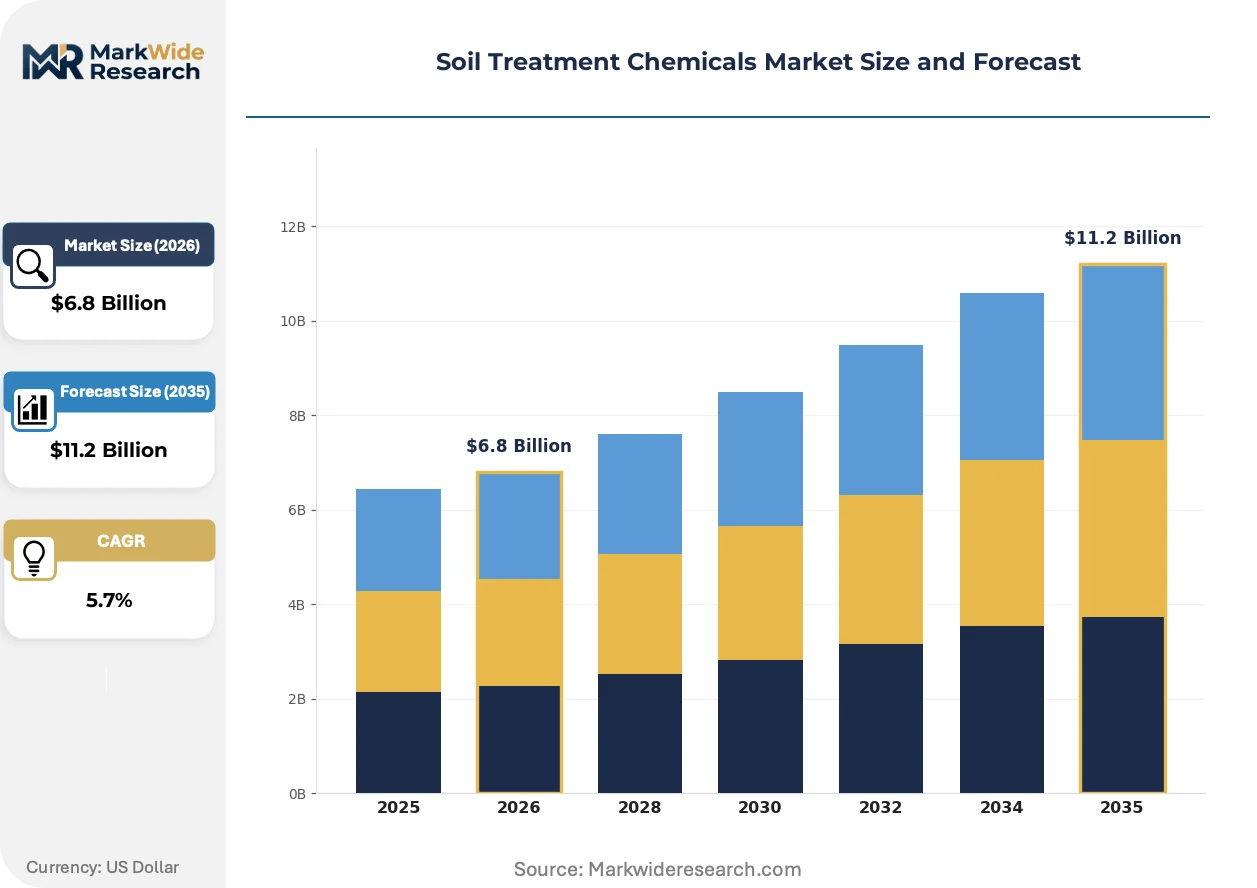
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fertility Enhancers, Soil Conditioners, Biopesticides, Growth Stimulators Application: Agricultural Land, Horticulture, Turf Management, Greenhouses Form: Granular, Liquid, Powder, Emulsion Distribution Channel: Direct Sales, Retail, Online Stores, Distributors |
| Companies Covered | Certis USA, Corteva Agriscience, BASF SE, Solvay SA, Bayer CropScience AG, Syngenta AG, AMVAC Chemical Corporation, UPL Limited, Novozymes A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Treatment Chemicals Market Emerging Trajectories
Biological soil treatment platforms are capturing functional territory once held by fumigants, driven by residue-limit enforcement and regenerative agriculture certification premiums.
RNA interference nematicides targeting root-knot and cyst nematode species are electrifying the crop protection pipeline. Specialty vegetable growers in Florida and California are piloting dsRNA formulations ahead of full commercialization. This technology is compressing the addressable market for traditional organophosphate nematicides by offering species-specific lethality without broad-spectrum soil sterilization.
EU F-Gas Regulation phase-down schedules are accelerating the search for non-ozone-depleting soil sterilization methods. Greenhouse operators in the Netherlands and Spain face 2030 reduction targets for sulfuryl fluoride use in substrate treatment. Containerized steam and hot water systems are displacing chemical fumigation in protected cultivation, with Dutch horticulture technology suppliers capturing equipment retrofit contracts.
Outcome-based biological performance contracts are restructuring buyer-supplier relationships in Midwest row-crop agriculture. Corteva and Bayer pilot programs tie microbe-based platform payments to documented yield preservation against untreated controls. This model is most visible in Illinois and Iowa corn operations, where growers defer upfront input costs in exchange for revenue-sharing arrangements tied to harvest results.
Soil Treatment Chemicals Market Segmentation
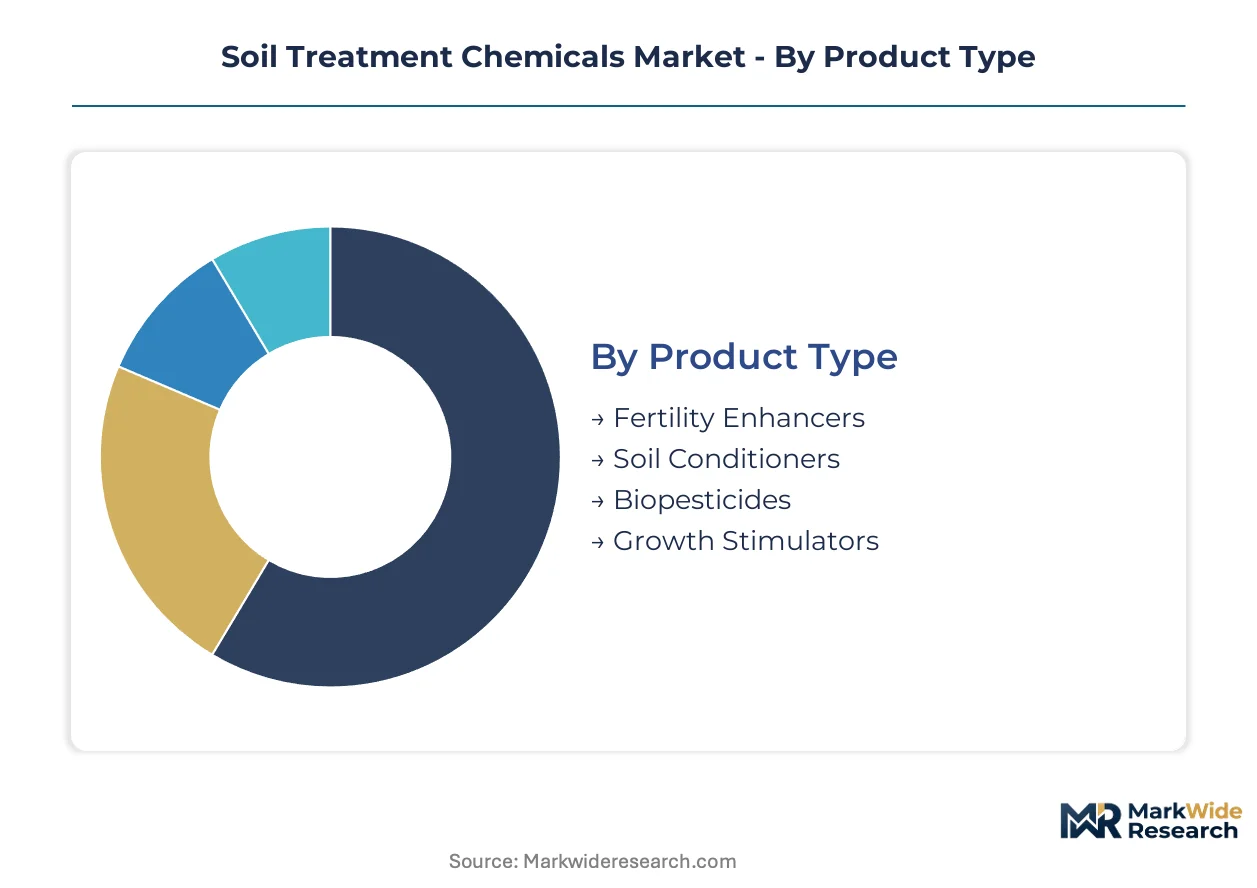
Soil treatment chemicals fragment across four intersecting dimensions that determine margin structure, regulatory exposure, and channel economics. Product type and application concentration dominate strategic positioning, while form and distribution channel shape working capital requirements and geographic reach.
Product Type:
Supply concentration in synthetic nitrogen and phosphate complexes favors established agrochemical conglomerates, whereas biological platforms attract venture-backed entrants with enzymatic IP.
- Fertility Enhancers:Micronutrient blends and chelated compounds replenish depleted soils through recurring seasonal applications. Demand clusters in India's Punjab wheat belt and Brazil's Mato Grosso soy frontier, where government soil health subsidies offset input costs for degraded cerrado plots.
- Soil Conditioners:Gypsum, lime, and organic matter amendments modify pH and structure for root penetration. California Central Valley almond orchards drive premium pricing as salinity management becomes critical under tightening groundwater sustainability mandates.
- Biopesticides:Bacillus thuringiensis and Trichoderma-based inoculants target nematodes and fungal pathogens without residue accumulation. EU MRL enforcement on synthetic residues accelerates substitution in Dutch greenhouse vegetable exports.
- Growth Stimulators:Auxin and cytokinin formulations enhance root establishment and stress tolerance. Southeast Asian rice intensification programs in Vietnam and Indonesia generate volume offtake for seedling-stage applications.
Today's leader: Fertility Enhancers. Tomorrow's challenger: Biopesticides.
Application:
Customer sophistication varies sharply across end-use contexts, with export-oriented operations demanding residue documentation that domestic broadacre growers often bypass.
- Agricultural Land:Row-crop corn, wheat, and soybean production consumes bulk formulated actives through dealer networks. Midwest US precision agriculture adoption enables variable-rate nematicide application, reducing per-acre chemical load while preserving yield targets.
- Horticulture:High-value fruit and vegetable operations prioritize residue-compliant inputs for supermarket chain certification. Spanish Almería greenhouse complexes deploy integrated steam-biological protocols to meet EU F-Gas phase-down deadlines for sulfuryl fluoride.
- Turf Management:Golf courses and municipal parks require aesthetic performance with minimal environmental runoff. Florida's St. Augustinegrass maintenance contracts specify slow-release formulations to comply with state watershed protection rules.
- Greenhouses:Substrate-based cultivation demands sterilization between crop cycles without ozone-depleting fumigants. Dutch horticulture technology suppliers capture equipment retrofit contracts for containerized hot water systems displacing chemical treatment.
Agricultural Land commands current volume. Horticulture offers the steepest expansion trajectory as export certification tightens.
Form:
Manufacturing asset intensity diverges between liquid blending facilities and granular compaction plants, with powder processing occupying intermediate capital requirements.
- Granular:Slow-release fertilizer matrices and soil-incorporated nematicides suit mechanized broadacre application. Brazilian soy producers favor granular phosphate coatings for cerrado acidity correction under ABC+ Plan subsidies.
- Liquid:Precision agriculture systems enable site-specific dosing through fertigation and spray equipment. California drip-irrigated almond orchards demand liquid micronutrient compatibility with existing infrastructure.
- Powder:Water-soluble concentrates and dry flowables reduce transport costs for distant markets. Chinese technical-grade exports to Southeast Asian rice systems predominantly ship in powder form for local dilution.
- Emulsion:Oil-based carriers improve adhesion and rainfastness for foliar-soil dual applications. Australian cotton growers specify emulsion formulations for residual herbicide compatibility in conservation tillage systems.
Liquid formulations dominate precision agriculture premiums. Granular products retain developing-market cost advantages.
Distribution Channel:
Channel selection determines technical service intensity, with direct sales supporting prescription agriculture and retail capturing price-sensitive commodity demand.
- Direct Sales:Agronomist-led soil testing and prescription mapping serve large-scale operations. Corteva and Bayer field teams in Illinois and Iowa corn belts bundle seed-treatment-soil platforms with outcome-based payment terms.
- Retail:Farm supply cooperatives and independent dealers stock standardized formulations for immediate pickup. India's Krishi Vigyan Kendra network channels subsidized micronutrients to smallholder wheat and rice cultivators.
- Online Stores:E-commerce platforms aggregate biological inoculant demand from specialty crop producers. Novozymes digital subscription models for enzymatic soil conditioning bypass traditional distributor markups in Brazilian cerrado regions.
- Distributors:Regional wholesalers manage inventory and credit for fragmented customer bases. ANVISA-aligned Brazilian distributors accelerate multinational product registration through established regulatory relationships.
Direct sales capture precision agriculture value. Online platforms are gaining share fastest in biological product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as formulators relocate blending capacity toward jurisdictions with streamlined biopesticide registration. Brazil's ANVISA alignment with OECD test guidelines now offers faster pathways than India's extended field trial mandates, drawing mid-scale manufacturers toward South American distribution hubs.
United States
California's Central Valley strawberry and almond producers drive chloropicrin-1,3-D blend consumption amid methyl bromide phaseout deadlines. EPA buffer zone requirements for soil fumigants compress synthetic chemistry margins while redirecting R&D toward microbe-based platforms. Midwest corn-soy rotations in Illinois and Iowa anchor precision agriculture adoption for variable-rate nematicide application.
Brazil
Government-backed ABC+ Plan subsidies for biological inoculants and cover crop integration concentrate demand in Mato Grosso soy frontier and degraded cerrado plots. ANVISA's OECD-aligned registration protocols accelerate parallel submission strategies for multinational registrants. São Paulo-based distributors leverage established regulatory relationships to compress product launch timelines versus Asian jurisdictions.
China
Jiangsu and Shandong provinces supply over sixty percent of technical-grade organophosphates and pyrethroids, creating single-source vulnerability for multinational blenders. The country's national agricultural regulator maintains stringent efficacy documentation requirements for new soil actives. Yangtze River Delta formulators are expanding biological production capacity to serve Southeast Asian rice intensification programs.
India
Punjab wheat belt and Haryana rice systems generate recurring micronutrient replenishment demand through government soil health subsidy schemes. The Central Insecticides Board mandates three-season efficacy data for new soil actives, stretching registration cycles to seven years. Krishi Vigyan Kendra networks channel subsidized inputs to smallholder cultivators across northern agricultural states.
Germany
EU REACH restrictions on chlorpropham and tightening F-Gas Regulation phase-down schedules accelerate replacement demand for biological alternatives. BASF SE leverages Ludwigshafen R&D infrastructure to sustain nematicide formulation leadership. Bavarian and North Rhine-Westphalia greenhouse operators pilot containerized steam systems displacing sulfuryl fluoride in substrate treatment.
Soil Treatment Chemicals Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue enzymatic conditioning and RNA interference platforms. The market structures around three distinct archetypes: integrated agrochemical conglomerates with seed-and-soil bundles, specialized biological platform providers with subscription revenue models, and regional formulators serving cost-sensitive broadacre markets. Competitive moves concentrate on portfolio diversification toward reduced-risk chemistries and strategic partnerships for microbiome formulation stability.
Among integrated agrochemical conglomerates, BASF SE and Bayer CropScience AG exemplify the R&D-intensive archetype with global registration capabilities. Novozymes A/S anchors the biological platform tier through enzymatic soil conditioning offerings. These three entities represent divergent strategic postures: chemical synthesis dominance, biological transition investment, and pure-play microbe-based specialization.
| Leading Market Players |
|---|
| Certis USA |
| Corteva Agriscience |
| BASF SE |
| Solvay SA |
| Bayer CropScience AG |
| Syngenta AG |
| AMVAC Chemical Corporation |
| UPL Limited |
| Novozymes A/S |
| Others |
Supply Flow & Price Mechanics
EU REACH restrictions on chlorpropham and EPA buffer zone mandates gate qualified supply for premium-tier soil fumigant formulations, concentrating margin capture among registrants with proven regulatory dossiers while channeling price-sensitive volume toward unregulated biological alternatives.
Pricing Analysis
Distributor margin compression in developing markets separates premium liquid micronutrient formulations from economy-grade granular phosphate coatings. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and cold-chain compliance, with biological inoculants commanding subscription premiums against per-ton commodity synthetics. Cost compression in economy synthetics is intensifying because Chinese technical-grade concentration exposes blenders to ethylene derivative volatility. Smallholder cooperatives in India's Punjab wheat belt exhibit highest price sensitivity, whereas California Central Valley almond operations prioritize residue documentation over unit cost.
Supply Chain Analysis
Freight cost escalation on refrigerated biological shipments from Copenhagen to São Paulo compresses spore-viability windows and forces regional blending investments. Technical-grade organophosphate and pyrethroid supply concentrates in Jiangsu and Shandong provinces, while enzymatic platform production centers on Danish and Brazilian facilities. Formulation draws from ethylene, chlorine derivatives, and microbial culture stocks. Single-source vulnerability in Chinese active ingredient concentration threatens multinational blenders during regulatory inspection cycles. Distribution runs through ANVISA-aligned Brazilian distributors and India's Krishi Vigyan Kendra cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soil treatment chemicals function as a stable compounder anchored by recurring micronutrient replenishment cycles on degraded agricultural soils.
For Market Incumbents: Hedge synthetic chemistry margin erosion by accelerating biological platform R&D and securing cold-chain distribution partnerships in Brazilian cerrado regions. RNA interference nematicide pipelines threaten traditional organophosphate formulations. Backward integration into microbial culture production reduces spore-viability degradation risks. For New Entrants and Emerging Players: Agronomist-led prescription service providers offer the most penetrable channel wedge for enzymatic soil conditioning platforms in Midwest corn-soy rotations. White-space targets include outcome-based yield preservation contracts in Illinois and Iowa, plus ANVISA-fast-tracked biological registrations for Mato Grosso soy frontiers. Digital subscription models bypass traditional distributor markups. For Investors and Strategic Acquirers: Roll-up economics work for regional biological formulators with established cold-chain infrastructure because microbiome formulation stability demands localized production that synthetic conglomerates cannot easily replicate. Five-to-ten year viability rests on regulatory divergence between residue-limit jurisdictions. Target specialists with validated spore-viability protocols. Watch EPA fumigant phase-down schedules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Platform Scale-Up | Novozymes expands glucanase production to capture ABC+ Plan subsidies in Brazilian cerrado. |
| Regulatory Parallel Submission | ANVISA-OECD alignment accelerates multinational product launches versus Indian seven-year cycles. |
| Cold-Chain Distribution Investment | Regional spore-viability preservation reduces degradation losses in non-refrigerated networks. |
| Outcome-Based Contract Piloting | Corteva ties microbe platform payments to documented yield preservation in Iowa corn operations. |
| Precision Agriculture Integration | Variable-rate liquid application reduces per-hectare chemical load while preserving yield targets. |
Methodological Framework
Bottom-up crop-specific modeling reconciled against top-down active ingredient production tracking forms the analytical core of this study. Primary interviews with formulation chemists at multinational agrochemicals, procurement leads at Brazilian agricultural cooperatives, regulatory affairs directors navigating ANVISA and EPA pathways, and precision agriculture agronomists in Illinois and Iowa supplied demand-side calibration. Secondary validation drew from EPA registration databases, EU REACH substance restrictions, Brazilian customs export records, and Central Insecticides Board field trial disclosures. Triangulation between farmer input cost surveys and technical-grade production volumes anchored regional demand estimates.
Historical trendline analysis across the analysis window established baseline growth trajectories segmented by product type, application context, formulation state, and distribution channel. Modeled dimensions included fertility enhancer versus biopesticide chemistry class, horticulture versus broadacre land use, liquid versus granular physical form, and direct sales versus retail channel economics. CAGRs derived from curve-fitting observed adoption rates against regulatory phase-out deadlines and subsidy program budgets. Forecast inputs incorporated EPA fumigant buffer zone expansion timelines and EU F-Gas Regulation phase-down schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, microbiome formulation stability breakthroughs, and regulatory divergence on maximum residue limits. Forecasts reflect assumptions documented across primary and secondary sources. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Potassium Acetate Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Global Aerosol Propellant Market