
 Mining Explosives Consumables Market | 2026-2036
Mining Explosives Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Explosives Consumables Market Foresight
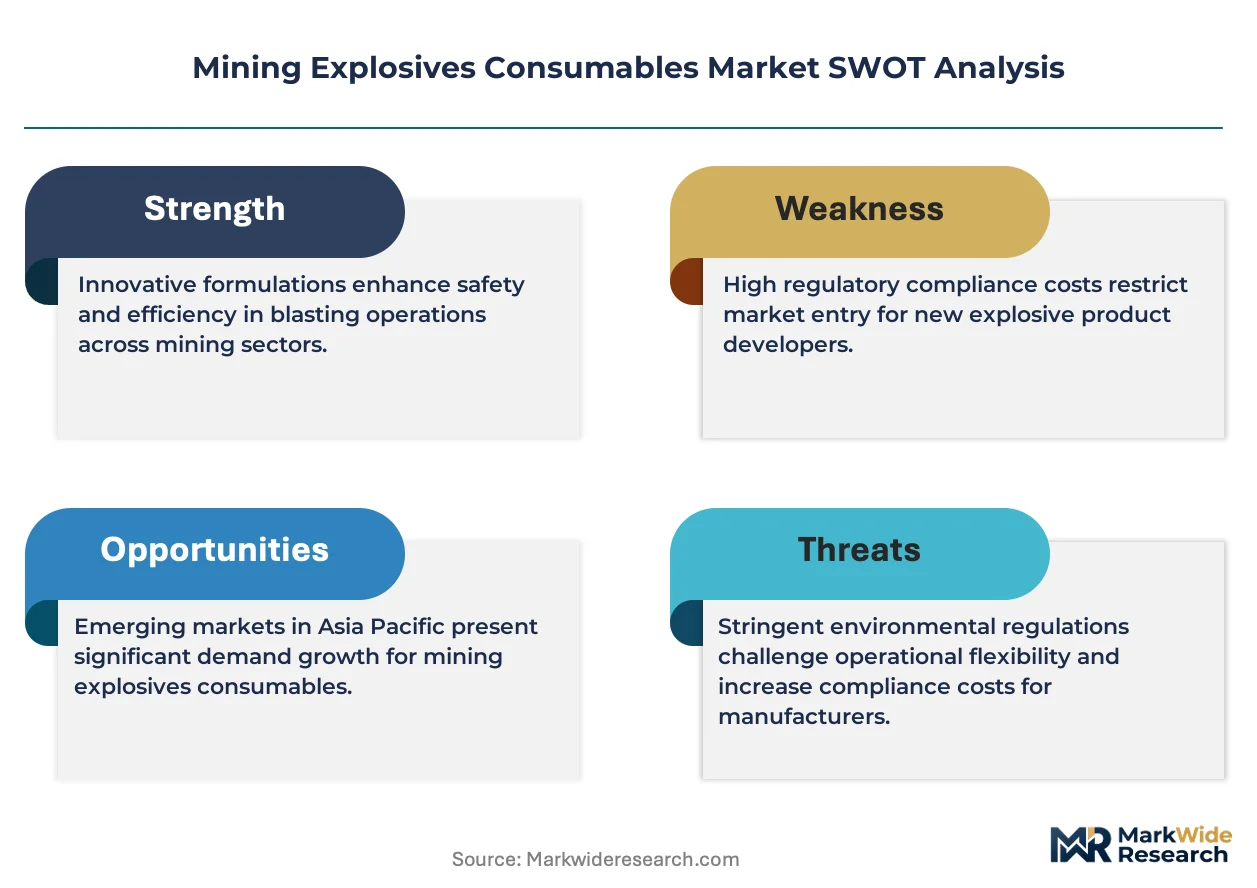
Blasting-as-a-service contracting is expanding what mining operators purchase, shifting capital expenditure into operational expenditure models. Dyno Nobel leverages its manufacturing scale across North American coal and metal operations. Orica Limited anchors its position through software-defined blast optimization platforms that integrate with customer mine planning systems.
Mining explosives consumables encompass formulated energetic materials—nitrate-based emulsions, ammonium nitrate fuel oil (ANFO) blends, and water gel compositions—manufactured through oxidizer-fuel sensitization processes and detonated via electronic initiation systems to fragment rock for mineral extraction. Emulsion products dominate value pools due to their water resistance and energy density advantages in wet-hole applications, while bulk delivery systems represent the fastest-growing delivery mode as large-scale surface miners shift from packaged products to on-site mixing trucks. Underground mining applications sustain premium pricing relative to quarrying segments because of stricter safety protocols and specialized product formulations.
OSHA and EPA frameworks govern storage, transport, and emissions standards for explosive precursors in the United States, while Australia's national resources regulator enforces ammonium nitrate security and handling mandates that shape procurement compliance costs. The EU REACH regulation and associated classification requirements restrict certain chemical sensitizers, redirecting formulation R&D toward alternative oxidizer blends. Stakeholders must monitor evolving electronic initiation mandates and precursor chemical tracking systems as regulatory digitization accelerates compliance complexity.
Market Dynamics
Bulk emulsion delivery systems are compressing procurement cycles as surface miners abandon packaged explosives for on-site mixing trucks, forcing suppliers to reconfigure logistics networks around mobile manufacturing units rather than fixed plant distribution.
Growth Catalysts
- Copper belt expansion:Chilean underground operations are scaling bulk emulsion procurement to access deeper ore bodies, pulling nitrate-based formulations into high-altitude, water-saturated drill patterns.
- Electronic initiation mandates:Australia's national resources regulator is tightening ammonium nitrate handling protocols, accelerating replacement of fuse-based systems with programmable detonators that reduce misfire rates.
- Coal seam gas drainage:Permian Basin operators are deploying specialized water gel compositions for pre-fracturing coal measures, opening incremental demand for energetic materials outside traditional metal mining.
Market Restraints
- Ammonium nitrate price volatility:Natural gas feedstock fluctuations directly compress emulsion manufacturing margins, exposing producers to input cost swings without immediate pass-through mechanisms.
- Western Australia supply concentration:Three bulk emulsion plants service the Pilbara iron ore district, creating single-point vulnerability for operators dependent on just-in-time delivery schedules.
- REACH chemical restrictions:ECHA classification requirements for certain sensitizer compounds are forcing European formulators toward alternative oxidizer blends with unproven field performance histories.
Strategic Opportunities
- Kazakhstan copper development:New underground projects in the Bozshakol district lack established explosives infrastructure, creating first-mover advantage for suppliers willing to deploy mobile mixing units.
- Blast optimization software integration:Convergence of electronic initiation systems with mine planning platforms enables precision timing that reduces overbreak and improves mill throughput.
- Indonesian nickel laterite expansion:Sulawesi operations are transitioning from manual to mechanized drilling, opening demand for packaged emulsion products in previously underserved surface mines.
Industry Challenges
- Shotfirer certification bottlenecks:Australia's state-level licensing requirements create 12-18 month qualification timelines that constrain workforce scaling during project ramp-ups.
- Legacy magazine integration:Underground operators running mixed electronic and pyrotechnic inventories face compatibility failures that delay blast sequences and compress production windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Explosives Consumables Market |
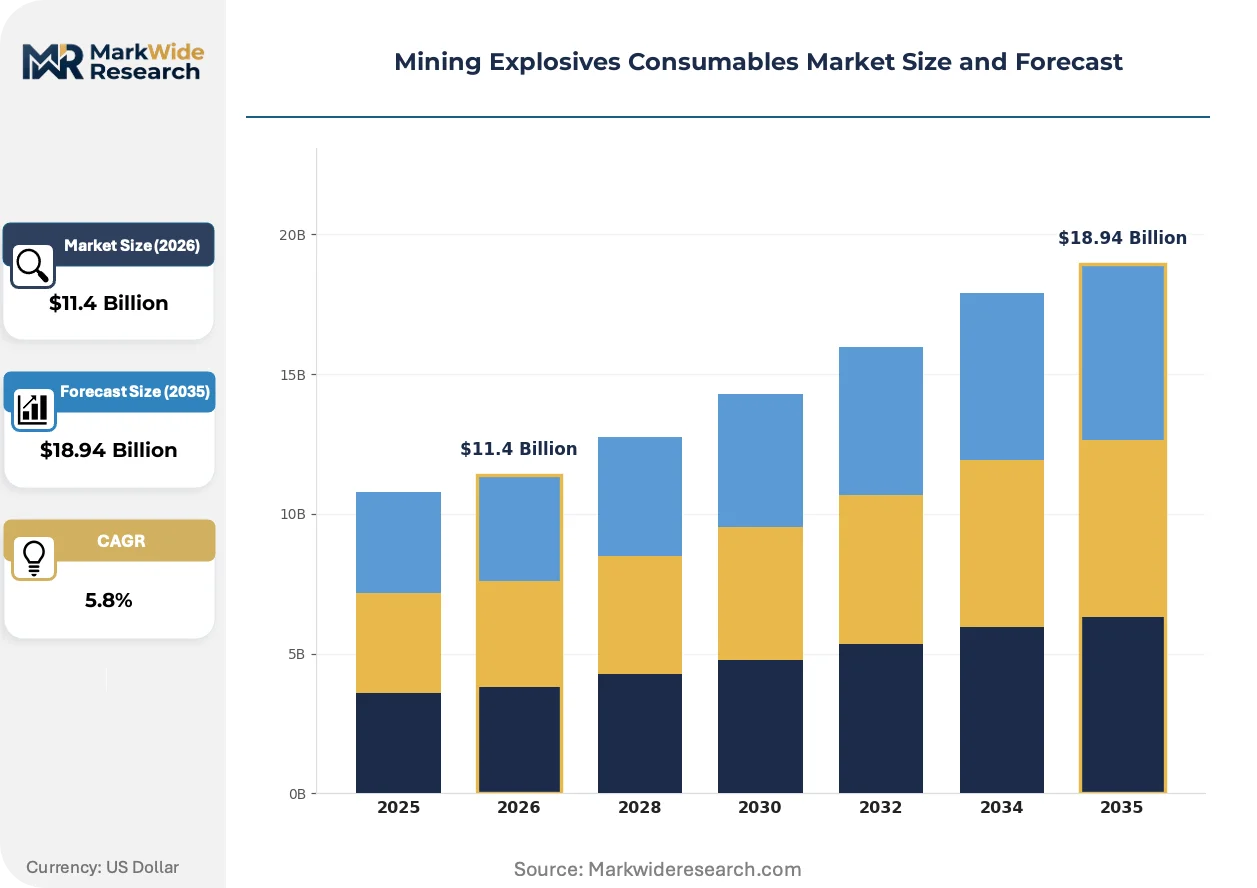
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, ANFO, Water Gels, Bulk Explosives Application: Quarrying, Underground Mining, Surface Mining, Construction Delivery Mode: Packaged, Bulk Delivery, Blasting Equipment, Initiation Systems End User: Mining Contractors, Construction Companies, Government Agencies, Industrial Operators |
| Companies Covered | ENAEX S.A., AECI Limited, Orica Limited, NOF Corporation, Sasol Limited, Dyno Nobel, Austin Powder Company, Solar Industries India Ltd, MAXAM Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Explosives Consumables Market Shifts & Advancements
Digital blast design platforms are compressing the feedback loop between drilling data and explosive loading decisions, enabling real-time pattern adjustments that were impossible under static paper-based planning workflows.
Electronic detonator networks are electrifying fragmentation control in hard-rock underground mines, replacing millisecond-delay fuse systems with microsecond-precision timing that operators in Chile's El Teniente complex are deploying across all production levels. The technology is electrifying competitive positioning by binding explosives suppliers to mine planning software ecosystems through API-level integration.
REACH regulation amendments are restricting nitrate ester sensitizers in European formulations, redirecting R&D investment toward perchlorate-based alternatives that meet ECHA hazard classification thresholds. Metal mining operations in Sweden and Finland are absorbing reformulation costs while quarrying segments face product discontinuation pressures that favor larger suppliers with diversified chemical portfolios.
Contracting structures are unbundling explosives supply from blast execution, with surface coal operators in Wyoming's Powder River Basin separating chemical procurement from drilling and firing services. This bifurcation is compressing supplier margins while expanding addressable market for specialized blasting contractors who assume liability for misfire events and fragmentation outcomes.
Mining Explosives Consumables Market Segmentation
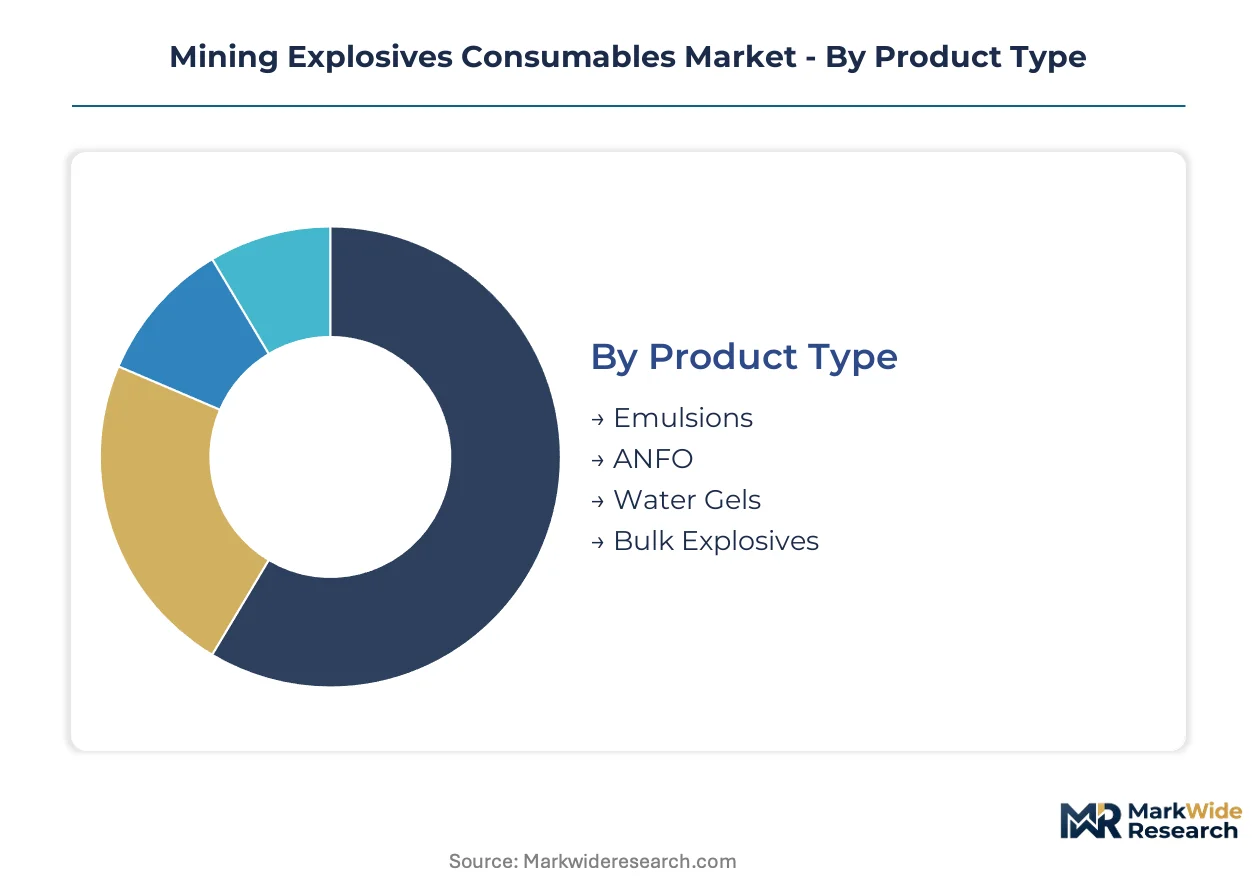
Explosives procurement patterns diverge sharply across product chemistry, deployment depth, and delivery logistics. Suppliers configure formulation plants and distribution networks around these fracture lines, not around undifferentiated commodity supply.
Product Type:
Cost tier separates premium water-resistant formulations from commodity blends in procurement decisions.
- Emulsions:Oxidizer-in-oil suspensions deliver superior water resistance and energy density for wet-hole applications. Chilean copper belt operators specify bulk emulsion systems exclusively for high-altitude, water-saturated drill patterns where ANFO fails.
- ANFO:Ammonium nitrate fuel oil blends remain the lowest-cost option for dry surface operations. Australian iron ore miners in the Pilbara deploy ANFO across vast open-cut pits where water ingress is minimal and blast volumes justify bulk delivery infrastructure.
- Water Gels:Cross-linked nitrate solutions bridge performance gaps with moderate water resistance and intermediate pricing. Permian Basin coal seam gas operators deploy specialized water gel compositions for pre-fracturing coal measures outside traditional metal mining.
- Bulk Explosives:Site-mixed formulations reduce transport costs and improve shelf-life economics for remote operations. Kazakhstan's Bozshakol copper district lacks fixed manufacturing infrastructure, creating first-mover openings for mobile mixing unit deployment.
Volume sits with ANFO; growth tilts toward emulsions.
Application:
Application determines safety protocol stringency and formulation specialization requirements.
- Quarrying:Standardized blast patterns and dry conditions favor commodity ANFO procurement with minimal technical support. European quarrying segments face product discontinuation pressures under REACH sensitizer restrictions that favor diversified chemical portfolios.
- Underground Mining:Confined-space operations demand specialized emulsion formulations with precise detonation control and fume characteristics. Australia's state-level shotfirer licensing creates 12-18 month qualification timelines that constrain workforce scaling during project ramp-ups.
- Surface Mining:Large-scale open-pit operations drive bulk delivery adoption with on-site mixing trucks replacing packaged products. Wyoming's Powder River Basin surface coal operators are unbundling explosives supply from blast execution, separating chemical procurement from drilling and firing services.
- Construction:Fragmented project-based demand favors packaged products with rapid mobilization capabilities. Urban tunneling projects in Sweden and Finland absorb reformulation costs under REACH amendments while maintaining electronic initiation mandates for vibration control.
Revenue concentrates in surface mining; margin expansion favors underground applications.
Delivery Mode:
Customer type dictates inventory risk allocation and technical service bundling.
- Packaged:Pre-manufactured cartridges and bags serve small-scale operators without bulk handling infrastructure. Indonesian nickel laterite operations in Sulawesi are transitioning from manual to mechanized drilling, opening demand for packaged emulsion products in previously underserved surface mines.
- Bulk Delivery:On-site mixing trucks compress procurement cycles and reduce transport cost structures for high-volume consumers. Western Australia's Pilbara iron ore district depends on three bulk emulsion plants, creating single-point vulnerability for just-in-time delivery schedules.
- Blasting Equipment:Mobile manufacturing units and pumping systems represent capital expenditure shifts into supplier-provided operational assets. Dyno Nobel leverages manufacturing scale across North American coal and metal operations through equipment-integrated supply contracts.
- Initiation Systems:Electronic detonator networks command premium positioning through software integration with mine planning platforms. Orica Limited anchors market position through API-level connectivity between programmable detonators and customer blast optimization systems.
Procurement volume flows through bulk delivery; technology differentiation clusters in initiation systems.
End User:
Volume scale and liability tolerance separate procurement behaviors across buyer categories.
- Mining Contractors:Specialized blasting firms assume misfire liability and fragmentation outcomes under unbundled contracting structures. Blasting-as-a-service models shift capital expenditure into operational expenditure for mining operators.
- Construction Companies:Project-based demand cycles favor flexible procurement with minimal long-term supply commitments. Urban infrastructure projects require vibration monitoring and electronic initiation compliance that packaged product suppliers struggle to meet.
- Government Agencies:Strategic stockpiling and defense applications sustain demand for stable, long-shelf-life formulations. Security protocols for ammonium nitrate handling impose procurement compliance costs that reshape supplier qualification requirements.
- Industrial Operators:Captive mining divisions of metal producers integrate explosives procurement into vertical cost control systems. Copper belt expansion in Chile pulls nitrate-based formulations into high-altitude operations with demanding technical specifications.
Contracting volume concentrates with mining contractors; procurement autonomy remains strongest among industrial operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore corridor in Western Australia anchors explosives procurement volume through three bulk emulsion plants servicing just-in-time delivery schedules for surface mining giants.
Australia
Western Australia's Pilbara district drives bulk emulsion consumption through iron ore surface operations with stringent ammonium nitrate handling protocols enforced by the national resources regulator. TGA-aligned state-level shotfirer licensing creates 12-18 month workforce qualification timelines that constrain rapid project scaling. Queensland's Bowen Basin coal operations are transitioning from packaged products to on-site mixing trucks.
Chile
Copper belt underground operations at El Teniente and Chuquicamata are scaling bulk emulsion procurement to access deeper ore bodies in high-altitude, water-saturated conditions. The national mining regulator enforces electronic initiation mandates that accelerate programmable detonator adoption. Antofagasta region concentrators specify nitrate-based formulations exclusively for wet-hole applications where ANFO fails.
United States
Permian Basin coal seam gas operators deploy specialized water gel compositions for pre-fracturing coal measures outside traditional metal mining. EPA and OSHA frameworks govern explosive precursor storage, transport, and emissions standards that shape procurement compliance costs. Wyoming's Powder River Basin surface coal operators are unbundling explosives supply from blast execution services.
Kazakhstan
Bozshakol copper district underground projects lack established explosives infrastructure, creating first-mover openings for mobile mixing unit deployment. The national mining authority is developing precursor chemical tracking systems as regulatory digitization accelerates. Karaganda region operations are absorbing reformulation costs while transitioning from fuse-based to electronic initiation systems.
Indonesia
Sulawesi nickel laterite operations are transitioning from manual to mechanized drilling, opening demand for packaged emulsion products in previously underserved surface mines. The national energy and mineral resources ministry is tightening handling protocols for ammonium nitrate imports. Morowali Industrial Park concentrators are specifying water-resistant formulations for tropical wet-season operations.
Mining Explosives Consumables Market Competitive Landscape
Capital-heavy producers compete with asset-light service integrators across fundamentally different return profiles. The supplier base consolidates around three to five integrated chemical manufacturers with captive nitrate supply and regional distribution networks, while specialized blasting contractors capture margin through execution risk assumption. Strategic archetypes separate bulk formulation specialists, electronic initiation technology vendors, and full-service blasting contractors. Dominant competitive moves include backward integration into ammonium nitrate manufacturing and API-level software integration with customer mine planning platforms.
Among Australia- and South Africa-based integrated suppliers, Orica Limited, AECI Limited, and Sasol Limited exemplify the capital-intensive archetype with manufacturing scale across multiple continents. These entities anchor market positioning through diversified chemical portfolios that absorb reformulation pressures from REACH-style regulations. Dyno Nobel represents the North American bulk emulsion specialist with equipment-integrated supply contracts across coal and metal operations. ENAEX S.A. occupies the Latin American regional champion position with concentrated exposure to Chilean copper belt procurement cycles.
| Leading Market Players |
|---|
| ENAEX S.A. |
| AECI Limited |
| Orica Limited |
| NOF Corporation |
| Sasol Limited |
| Dyno Nobel |
| Austin Powder Company |
| Solar Industries India Ltd |
| MAXAM Corp |
| Others |
Supply & Pricing Matrix
Bulk emulsion procurement mandates from Chilean copper belt operators are forcing suppliers to reconfigure logistics networks around mobile manufacturing units, compressing margin structures as fixed-plant economics give way to asset-heavy field deployment models.
Pricing Analysis
Cost-down pressure on packaged emulsion tiers accelerates because Australian iron ore miners in the Pilbara are abandoning cartridge products for on-site mixing trucks. Three-tier pricing structure across premium water-resistant formulations, standard bulk blends, and economy ANFO grades separates procurement tiers by water resistance certification and detonation control precision. Price differentiation hinges on electronic initiation bundling versus fuse-based alternatives. Quarrying segments exhibit highest price sensitivity due to commoditized blast patterns, while underground copper operations absorb premiums for specialized fume characteristics and microsecond timing precision.
Supply Chain Analysis
Dual-sourcing qualification requirements from Western Australian regulators mandate Pilbara operators maintain relationships with at least two of the three regional bulk emulsion plants, preventing single-source dependency despite geographic concentration. Manufacturing capacity clusters in Australia, Chile, and the United States, with nitrate supply anchored in captive ammonia-oxidizer facilities and natural gas feedstock corridors. Raw material dependencies span ammonium nitrate prills, fuel oil sensitizers, and specialized emulsifying agents. Single-source vulnerability concentrates around Western Australia's just-in-time delivery schedules for iron ore giants. Distribution runs through equipment-integrated supply contracts that bundle chemical procurement with mobile mixing unit deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over ammonium nitrate manufacturing and electronic initiation software ecosystems determines margin capture. Backward integration into oxidizer production and API-level mine planning connectivity represent the decisive levers.
For Market Incumbents: Anticipate margin compression from unbundled contracting structures by deepening captive nitrate supply and accelerating electronic detonator software integration. Lock in long-term offtake agreements with Chilean copper belt operators before mobile mixing unit competitors establish field presence. Prioritize TGA-aligned shotfirer certification programs to constrain workforce scaling by challengers.
For New Entrants and Emerging Players: Launch via mobile mixing unit deployment in Kazakhstan's Bozshakol district, where fixed infrastructure gaps create first-mover openings without incumbent plant competition. Target Indonesian nickel laterite operations in Sulawesi transitioning from manual to mechanized drilling, as packaged emulsion demand outpaces established supply networks. Pursue blasting-as-a-service contracting to shift capital barriers onto balance sheets while capturing execution risk premiums.
For Investors and Strategic Acquirers: The window for entry favors electronic initiation technology vendors with API-compatible detonator networks and established mine planning software partnerships. Long-term viability centers on suppliers controlling both formulation chemistry and precision timing hardware. Watch for REACH amendment enforcement accelerating European formulator consolidation as alternative oxidizer R&D costs strain mid-tier chemical portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonium Nitrate | Captive oxidizer supply insulates Dyno Nobel and Orica from natural gas feedstock volatility compressing emulsion margins. |
| Electronic Initiation Software Integration | API-level connectivity between programmable detonators and blast optimization platforms binds explosives suppliers to customer mine planning ecosystems. |
| Mobile Mixing Unit Deployment | On-site manufacturing trucks enable first-mover capture in Kazakhstan's Bozshakol district lacking fixed explosives infrastructure. |
| Blasting-as-a-Service Contracting | Unbundled execution models shift capital expenditure to operational expenditure for mining operators while transferring misfire liability to specialized contractors. |
| REACH-Compliant Formulation R&D | Perchlorate-based oxidizer alternatives redirect European R&D investment as ECHA restrictions eliminate nitrate ester sensitizers from established product lines. |
Research Methodology
Document review covered customs and trade data for ammonium nitrate movements, SEC filings from integrated chemical manufacturers, and national resources regulator enforcement notices, complemented by interviews with procurement leads at Australian iron ore operations, Chilean copper belt technical directors, explosives plant managers, and electronic initiation systems engineers. Secondary validation drew from EPA emissions disclosures, Australia's national resources regulator handling protocol amendments, and ECHA classification databases. Bottom-up volume estimates from mine-level consumption patterns triangulated against top-down formulation plant capacity assessments.
Segmentation outputs across product chemistry tiers, application depth classifications, delivery mode configurations, and end-user contracting structures informed the analytical framework over the projection horizon. CAGRs were derived from mine production expansion schedules, electronic initiation mandate implementation timelines, and bulk delivery infrastructure deployment rates. Industry-specific forecast inputs incorporated copper belt deepening project pipelines, coal seam gas drainage activity in the Permian Basin, and Indonesian nickel laterite mechanization transitions.
Natural gas price volatility, regulatory digitization of precursor chemical tracking systems, and workforce certification bottlenecks are the dominant revision risks for explosives consumables demand trajectories. Deviation in ammonium nitrate feedstock costs would shift manufacturing margin outlooks materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Regenerative Thermal Oxidizer Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Well Stimulation Materials Sales Market
Industrial Chemicals
Detergent Making Machinery Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Drag Reducing Agents Market