
 6-KT Mother Liquor Market | 2026-2036
6-KT Mother Liquor Market Size, Share, and Industry Trends Forecast 2026-2036
6-KT Mother Liquor Market Insights
China is reconfiguring regional supply dynamics through expanded fine-chemical fermentation capacity. Thermo Fisher Scientific leverages its analytical instrument ecosystem to anchor downstream demand for high-purity mother liquor inputs. Merck sustains European leadership through pharmaceutical-grade certification programs that filter subscale competitors.
6-KT mother liquor denotes the residual aqueous phase remaining after 6-keto-testosterone crystallization, typically containing dissolved steroids, organic solvents, and inorganic salts at controlled pH ranges between 6.8 and 7.4; pharmaceutical manufacturers recover this stream for secondary metabolite extraction or waste-to-value conversion. Concentrate-grade product dominates value capture due to downstream purification burden, while membrane filtration technology leads extraction method adoption as solvent recovery regulations tighten. Biochemical research applications represent the fastest-growing demand pool, though pharmaceutical synthesis retains the largest absolute volume.
FDA purity standards for steroid-derived active pharmaceutical ingredients shape North American product specifications, while REACH registration requirements in Europe constrain import eligibility for non-certified suppliers. China's NMPA aligns with ICH Q3D guidelines on elemental impurities, creating harmonized compliance thresholds for multinational pharma manufacturers. Stakeholders must monitor evolving pharmacopeial monographs for steroid-derived starting materials to anticipate qualification protocol changes.
Market Dynamics
Membrane filtration technology is compressing extraction economics for 6-KT mother liquor processors, forcing legacy solvent recovery operations to retool or exit as REACH compliance deadlines tighten purity verification protocols.
Growth Catalysts
- Peptide Manufacturing Scale-Up:Contract research organizations in Germany are expanding fermentation capacity to meet biopharma demand for steroid-derived intermediates, pulling concentrate-grade mother liquor volumes upward.
- REACH Registration Thresholds:ECHA mandates on research-grade chemical purity are disqualifying uncertified suppliers from European pharmaceutical supply chains, consolidating demand among qualified producers.
- Membrane Filtration Adoption:Nanofiltration systems are replacing thermal distillation for solvent recovery, cutting energy intensity and enabling smaller-batch pharmaceutical synthesis operations.
Market Restraints
- Input Cost Volatility:Organic solvent prices fluctuate with petrochemical feedstock indices, squeezing margin structures for processors dependent on n-hexane and ethyl acetate recovery.
- Supply Concentration Risk:Fine-chemical fermentation capacity clusters in China's coastal provinces, exposing downstream pharmaceutical manufacturers to logistics disruption and trade policy friction.
- Substitution Threat:Biosynthetic routes to 6-keto-testosterone starting materials are reducing reliance on extracted mother liquor streams for certain research applications.
Strategic Opportunities
- Underpenetrated Geography:India's CDMO sector is building steroid API capacity under PLI scheme incentives, creating first-mover advantage for mother liquor suppliers achieving CDSCO certification.
- Regulatory Tailwind:China's NMPA alignment with ICH Q3D elemental impurity guidelines is harmonizing import standards, easing multinational qualification protocols for certified producers.
- Technology Convergence:Integration of continuous chromatography with membrane filtration is enabling real-time purity monitoring, opening continuous-processing contracts with large-scale peptide manufacturers.
Industry Challenges
- Specialized Talent Scarcity:Steroid biochemistry expertise concentrates among aging cohorts in Basel and Shanghai, constraining scale-up of new extraction facilities.
- Qualification Timeline Compression:FDA pharmaceutical-grade certification cycles for starting materials now exceed eighteen months, freezing working capital and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 6-KT Mother Liquor Market |
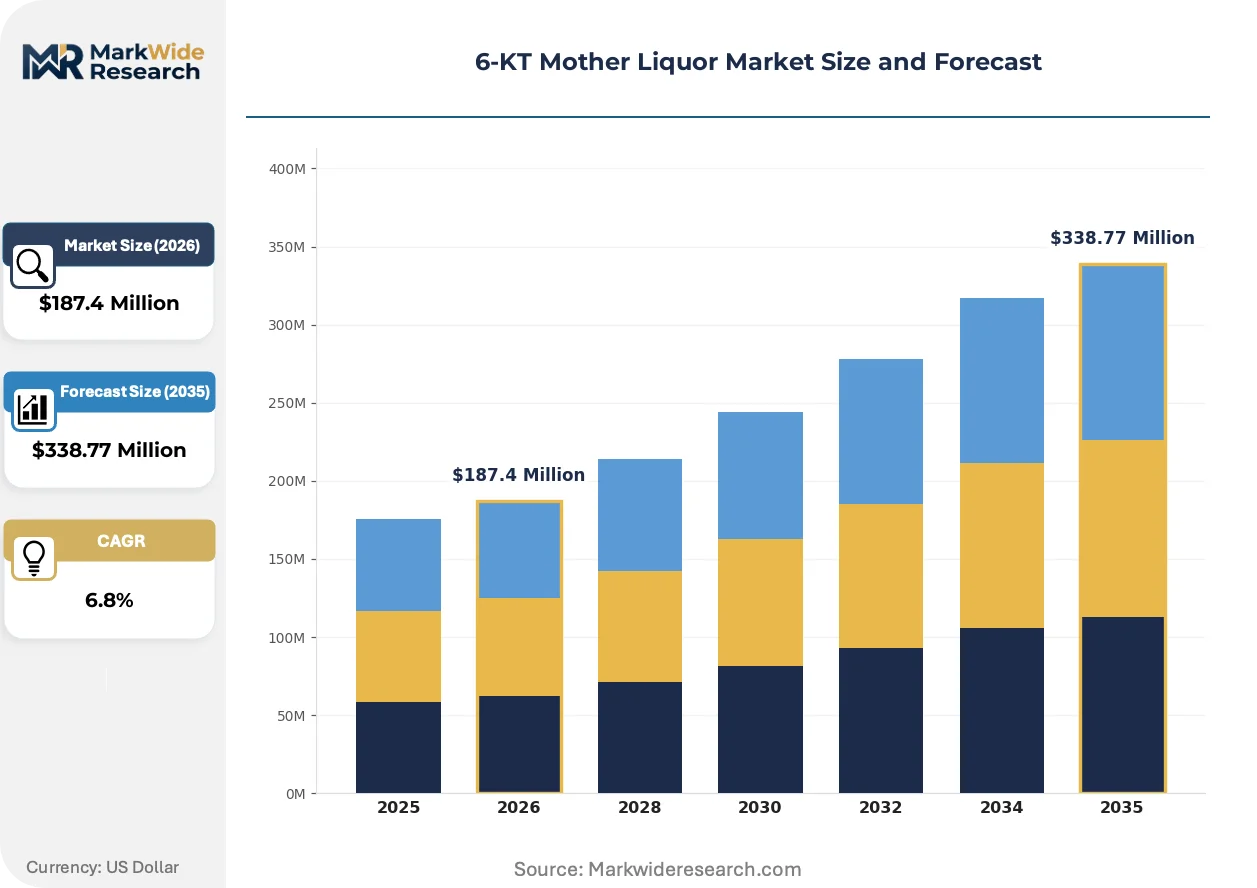
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Filtrate, Supernatant, Residual Solution Extraction Technology: Solvent Extraction, Membrane Filtration, Adsorption, Centrifugation Application: Pharmaceutical Synthesis, Cosmetic Production, Agricultural Formulation, Biochemical Research End User: Pharma Manufacturers, Cosmetic Makers, Agrochemical Firms, Research Laboratories |
| Companies Covered | Thermo Fisher Scientific, Merck, APExBIO Technology, Santa Cruz Biotechnology, Gold Biotechnology, Cayman Chemical, Carl Roth, Adooq Bioscience, TCI Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
6-KT Mother Liquor Market Trends and Innovations
Extraction technology and regulatory verification protocols are converging to redefine competitive advantage in 6-KT mother liquor supply, with purity assurance capabilities now outweighing volume scale as the primary vendor selection criterion.
Membrane filtration systems incorporating ceramic nanofiltration layers are hybridizing with traditional solvent recovery infrastructure, enabling simultaneous metabolite concentration and inorganic salt rejection. Mid-scale peptide manufacturers in Switzerland and Massachusetts are retrofitting batch operations with these hybrid units to meet contract specifications from top-ten pharmaceutical firms. The technology is hybridizing cost structures, compressing payback periods for processors serving high-purity research markets while marginalizing thermal-distillation-dependent competitors.
REACH registration requirements for steroid-derived intermediates are tightening documentary burdens on importers, with ECHA now requiring full supply chain substance volume tracking from crystallization through final formulation. European contract research organizations are responding by qualifying domestic mother liquor processors over Asian alternatives, even at measurable cost premiums. This regulatory pivot most affects concentrate-grade product lines destined for clinical-trial material production, where documentation gaps trigger automatic procurement suspensions.
Pharmaceutical procurement departments are consolidating qualified supplier lists to single-source or dual-source arrangements per intermediate, abandoning the fragmented multi-vendor strategies common five years prior. This concentration is compressing switching flexibility for mother liquor processors, who now face steeper revenue concentration risk and heightened customer negotiation leverage. The pattern is most pronounced in Germany and Switzerland, where large CDMOs have centralized intermediate purchasing under dedicated sourcing functions with mandate authority over site-level procurement decisions.
6-KT Mother Liquor Market Segmentation
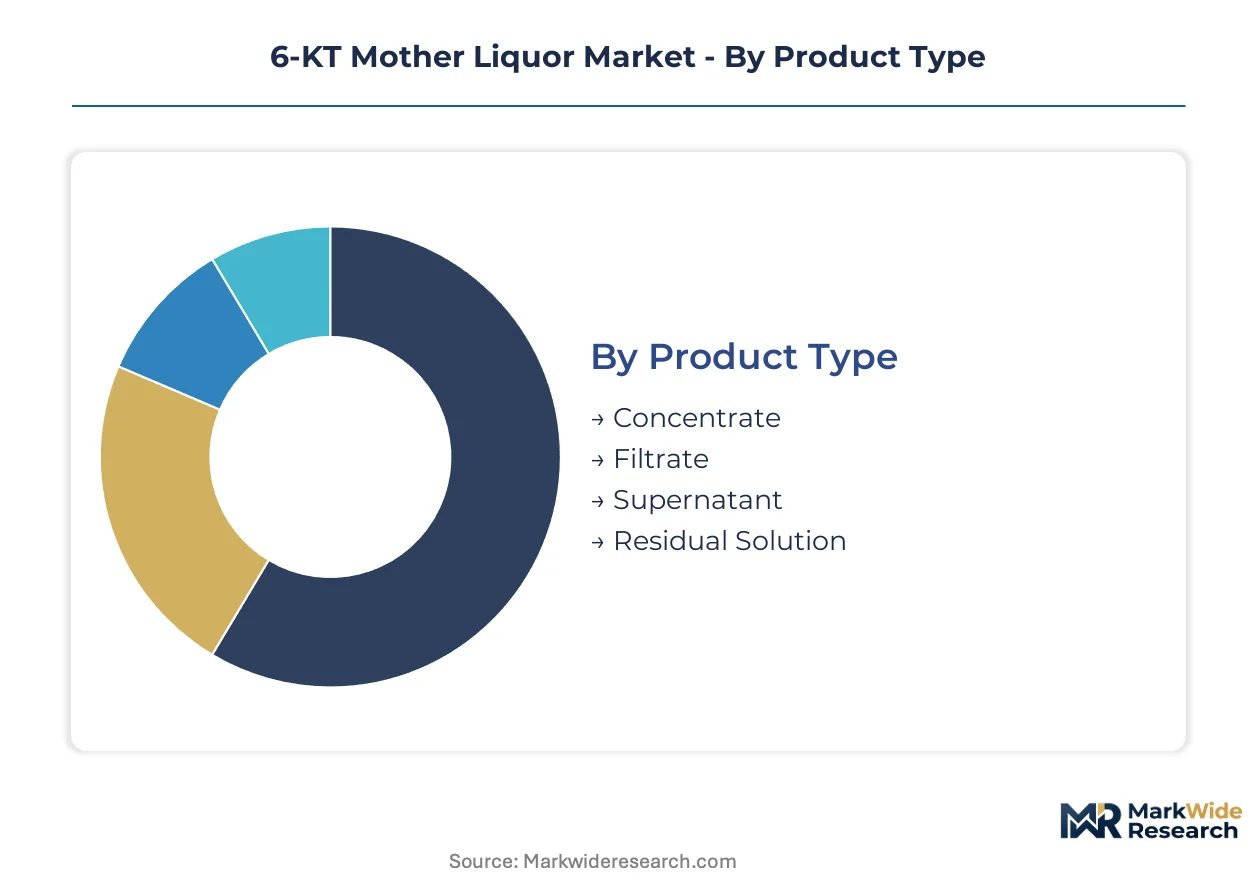
Segmentation in 6-KT mother liquor markets reflects divergent purity requirements and processing economics across downstream applications. Product type and extraction technology choices determine qualification pathways for pharmaceutical versus research-grade supply chains.
Product Type:
Cost tier differentiation separates commodity recovery streams from value-added concentrate products serving regulated pharmaceutical channels.
- Concentrate:High-solids aqueous phase containing dissolved steroids at 15-25% w/v concentration, requiring downstream chromatographic purification. German CDMOs and Swiss peptide manufacturers pull this grade for clinical-trial material production under ECHA documentary requirements.
- Filtrate:Clarified liquid fraction post-membrane separation with reduced inorganic salt burden. Massachusetts biotech clusters favor this grade for fermentation feedstock supplementation where elemental impurity specifications are less stringent than API starting material standards.
- Supernatant:Upper liquid layer following gravitational or centrifugal separation, typically 8-12% dissolved solids. Agricultural formulation producers in China's Shandong province absorb this stream for steroid-derived plant growth regulator synthesis.
- Residual Solution:Dilute aqueous phase remaining after primary metabolite recovery, often directed to waste-to-value conversion or solvent recovery loops. Research laboratories in Basel purchase small volumes for analytical method development.
Concentrate holds installed capacity. Filtrate is rotating up the share rankings.
Extraction Technology:
Application-specific purity thresholds drive technology selection, with membrane filtration displacing thermal methods in energy-sensitive pharmaceutical operations.
- Membrane Filtration:Ceramic nanofiltration and reverse osmosis systems enable simultaneous metabolite concentration and inorganic rejection at ambient temperature. Thermo Fisher Scientific's analytical ecosystem anchors demand for membrane-processed inputs in North American research markets.
- Solvent Extraction:Liquid-liquid partitioning using n-hexane or ethyl acetate remains prevalent for high-volume steroid recovery. REACH solvent recovery mandates are compressing margins for processors dependent on petrochemical-derived extraction media.
- Adsorption:Resin-based selective capture of target steroids from dilute streams. China's coastal fermentation facilities deploy this method for waste-to-value conversion where energy costs disadvantage thermal alternatives.
- Centrifugation:Density-gradient separation for rapid solid-liquid partitioning in batch pharmaceutical synthesis. Mid-scale European CROs retain this equipment for process development campaigns requiring fast turnaround.
Membrane filtration commands capital deployment. Adsorption is rotating up the share rankings.
Application:
Customer type maturity determines volume scale and qualification burden, with pharmaceutical synthesis imposing the steepest purity verification protocols.
- Pharmaceutical Synthesis:Steroid-derived active pharmaceutical ingredient and intermediate manufacturing requiring FDA or EMA starting material certification. Merck's pharmaceutical-grade certification programs filter subscale competitors from this channel.
- Biochemical Research:Academic and industrial R&D applications for metabolic pathway studies and analytical reference standard preparation. This application is expanding most quickly as CRISPR-enabled steroid biochemistry advances in Cambridge and Singapore research clusters.
- Cosmetic Production:Steroid-derived active ingredients for dermal formulations operating under less stringent purity tiers than pharmaceutical channels. South Korean cosmetic manufacturers source this grade under MFDS cosmetic ingredient guidelines.
- Agricultural Formulation:Plant growth regulators and veterinary steroid synthesis for crop and livestock applications. India's CDMO sector under PLI scheme incentives is building capacity to serve this application with CDSCO-certified inputs.
Pharmaceutical synthesis holds installed capacity. Biochemical research is rotating up the share rankings.
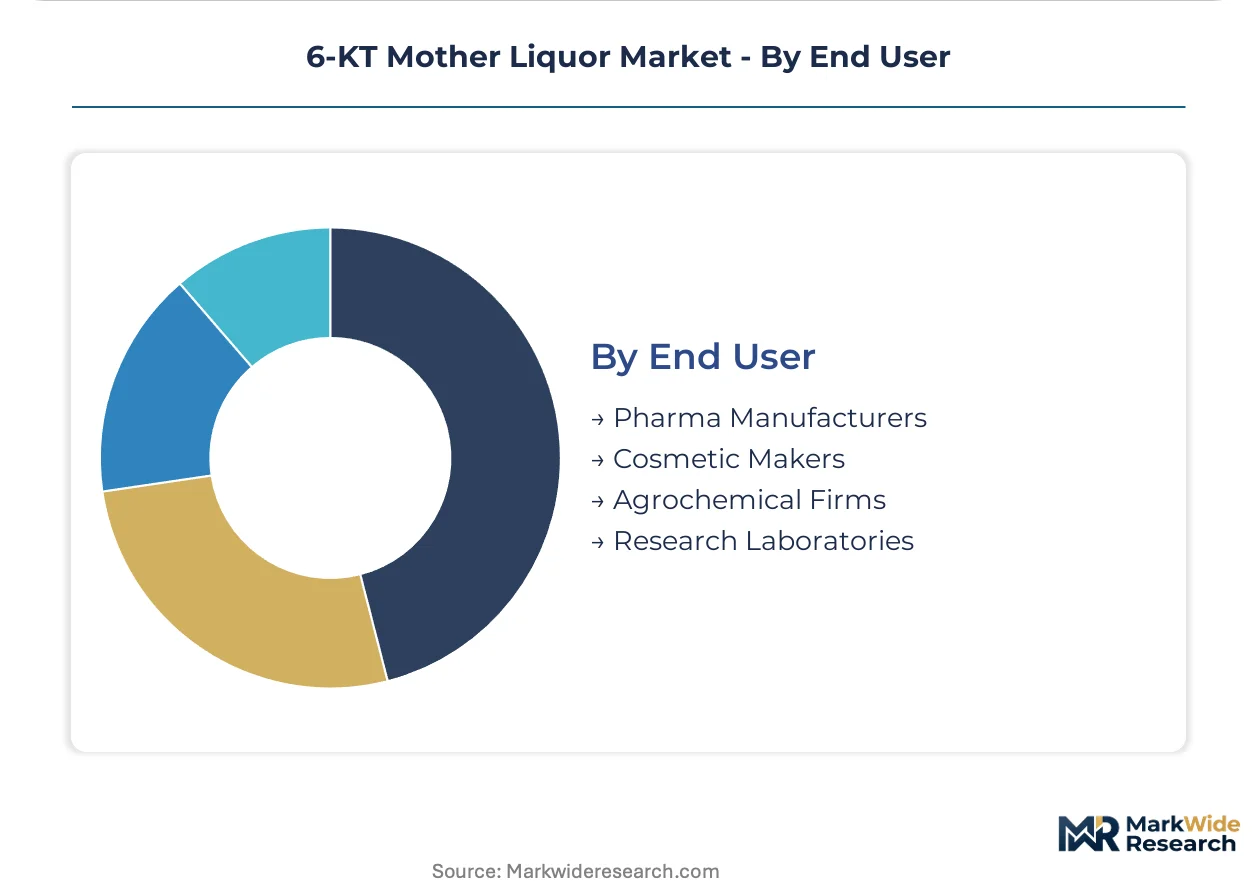
End User:
Geography and regulatory jurisdiction shape procurement patterns, with qualified supplier consolidation most pronounced in European pharmaceutical manufacturing.
- Pharma Manufacturers:Multinational firms and contract development manufacturing organizations requiring full supply chain documentation for regulatory submission. Procurement departments in Germany and Switzerland have centralized intermediate purchasing under dedicated sourcing functions with mandate authority.
- Research Laboratories:Academic institutions and biotech startups with fragmented purchasing and lower volume scale. China's NMPA alignment with ICH Q3D guidelines is easing multinational qualification protocols for certified producers serving this segment.
- Cosmetic Makers:Formulation houses and contract manufacturers for personal care products. These end users prioritize cost position over pharmaceutical-grade certification, sourcing from uncertified Asian suppliers where REACH registration thresholds do not apply.
- Agrochemical Firms:Producers of crop protection and animal health products with intermediate purity requirements between research and pharmaceutical grades. Brazil's ANVISA and Australia's TGA maintain distinct registration pathways for veterinary steroid applications.
Pharma manufacturers hold installed capacity. Research laboratories are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in China's coastal provinces concentrate bulk mother liquor supply, while European pharmaceutical demand pulls certified concentrate-grade volumes through REACH-regulated channels. Qualified supplier consolidation in Germany and Switzerland compresses procurement flexibility for downstream peptide manufacturers.
Germany
Contract research organizations in Baden-Württemberg and Bavaria scale peptide fermentation capacity for biopharma clients, driving concentrate-grade mother liquor procurement. ECHA REACH registration mandates disqualify uncertified Asian suppliers from clinical-trial material supply chains. The Rhine-Main cluster around Frankfurt anchors Merck's pharmaceutical-grade certification programs that filter subscale competitors.
China
Shandong province fermentation facilities expand fine-chemical capacity for steroid-derived intermediate export, absorbing regional mother liquor streams. NMPA alignment with ICH Q3D elemental impurity guidelines harmonizes import standards for multinational pharma manufacturers. Yangtze River Delta processors deploy membrane filtration systems to meet tightening solvent recovery regulations.
United States
Massachusetts biotech clusters favor filtrate-grade mother liquor for fermentation feedstock supplementation in CRISPR-enabled steroid biochemistry research. FDA purity standards for steroid-derived active pharmaceutical ingredients shape product specifications for domestic API starting material production. Greater Boston CROs retrofit batch operations with hybrid membrane-chromatography units to secure contracts from top-ten pharmaceutical firms.
Switzerland
Basel-area research laboratories purchase residual solution volumes for analytical method development in metabolic pathway studies. Swissmedic pharmaceutical-grade certification requirements sustain premium pricing for qualified mother liquor processors serving clinical-trial material channels. The Basel-Shanghai talent corridor constrains scale-up of new extraction facilities as specialized steroid biochemistry expertise concentrates among aging cohorts.
India
CDMOs in Maharashtra and Gujarat build steroid API capacity under PLI scheme incentives, creating first-mover opportunity for mother liquor suppliers achieving CDSCO certification. The country's national pharmaceutical regulator maintains distinct registration pathways for veterinary steroid applications that intermediate-grade mother liquor streams can serve. Hyderabad's fermentation corridor attracts contract manufacturing investment targeting agricultural formulation export markets.
6-KT Mother Liquor Market Competitive Landscape
Integrated analytical-instrument conglomerates and specialized biochemical suppliers split the market between ecosystem-anchored demand generation and purity-certification-led supply consolidation. Concentration is moderate at the top tier, with two global entities commanding downstream specification authority while mid-scale regional processors compete on CDSCO or REACH qualification speed. The dominant archetypes comprise laboratory-research ecosystem orchestrators, pharmaceutical-grade certification gatekeepers, and fermentation-capability-anchored regional suppliers. Competitive moves center on analytical instrument ecosystem integration and regulatory certification program expansion to filter subscale competitors.
Within the ecosystem-orchestrator tier, Thermo Fisher Scientific occupies a position leveraging analytical instrument penetration to anchor downstream demand for high-purity membrane-processed inputs. Merck exemplifies the certification-gatekeeper archetype through pharmaceutical-grade programs that consolidate European supply chain access. Among specialized biochemical suppliers, APExBIO Technology and Santa Cruz Biotechnology represent research-grade positioning archetypes serving fragmented academic and biotech procurement channels with lower qualification burdens than pharmaceutical synthesis applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck |
| APExBIO Technology |
| Santa Cruz Biotechnology |
| Gold Biotechnology |
| Cayman Chemical |
| Carl Roth |
| Adooq Bioscience |
| TCI Chemicals |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shandong province fermentation facilities is compressing spot pricing for filtrate-grade streams while tightening margins for membrane-equipped processors serving REACH-regulated channels. This utilization divergence rewards certified concentrate suppliers with pricing power over commodity recovery operations.
Pricing Analysis
REACH registration thresholds dictate the pricing tier structure across the 6-KT mother liquor market, separating pharmaceutical-grade concentrate from research-grade filtrate and agricultural supernatant streams. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with ECHA-documented product commanding 40-60% premiums over uncertified alternatives. Cost compression in standard-grade filtrate is intensifying because China's coastal capacity expansion outpaces German peptide manufacturing pull. Research laboratories exhibit highest price sensitivity due to fragmented procurement and grant-funded budgets, while Swiss CDMOs accept premium positioning for clinical-trial material security.
Supply Chain Analysis
Export control restrictions on ceramic nanofiltration membrane technology constrain equipment flows to Chinese processors, slowing Shandong facilities' upgrade timelines and preserving European purification advantages. Supply concentrates in China's coastal provinces, Germany's Rhine-Main corridor, and Switzerland's Basel cluster, with raw material dependencies on petrochemical-derived n-hexane, ethyl acetate, and specialized fermentation feedstocks. Single-source vulnerability runs through Yangtze River Delta logistics nodes, where port congestion or trade policy friction would disrupt filtrate-grade exports. Distribution runs through qualified supplier lists managed by centralized procurement functions at German and Swiss CDMOs, abandoning fragmented multi-vendor strategies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steroid biochemistry expertise concentrates among aging cohorts in Basel and Shanghai, creating a narrowing window for capability transfer as extraction facility scale-up demands outpace qualified personnel supply.
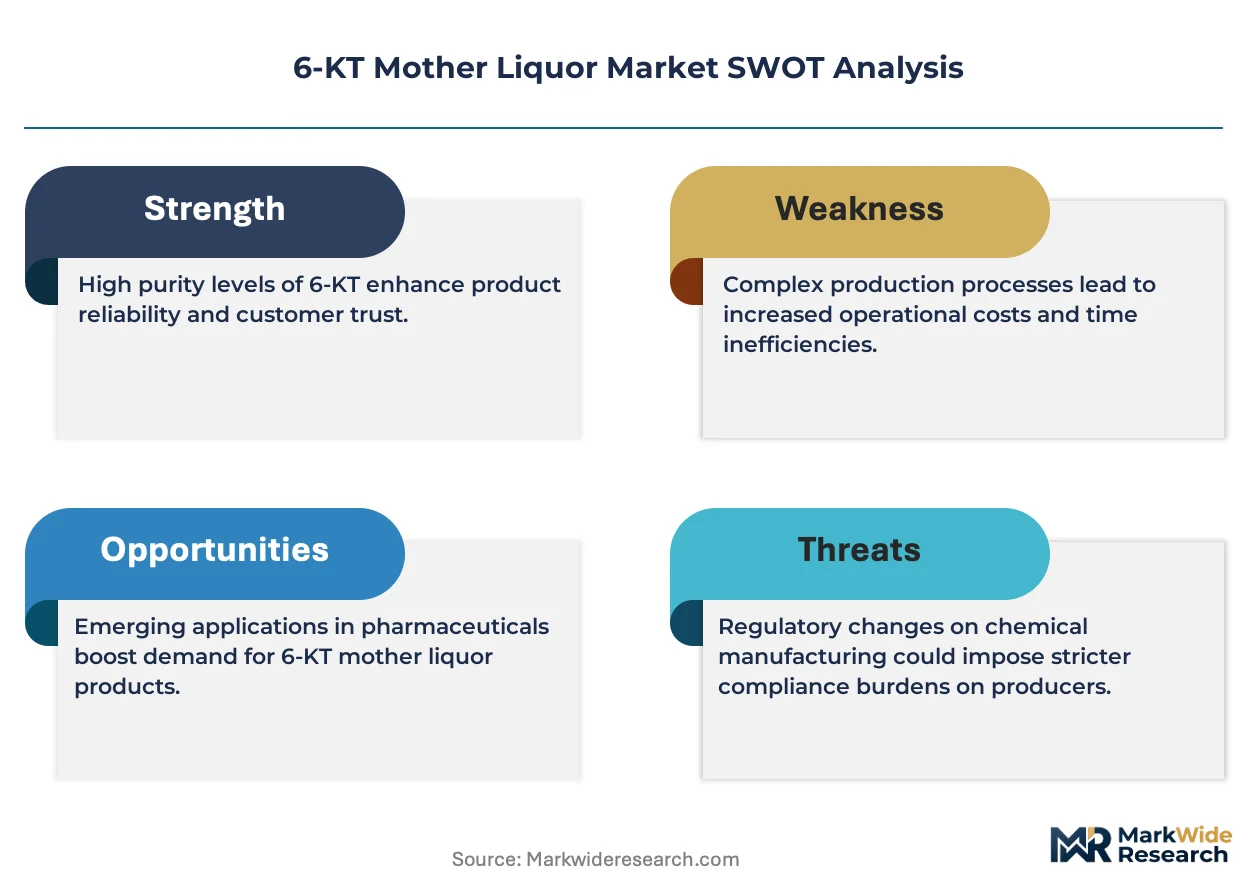
For Market Incumbents: Harden certification moats by accelerating REACH registration completion for concentrate-grade product lines before ECHA documentary requirements tighten further. Anchor membrane filtration capabilities through backward integration into ceramic nanofiltration equipment supply or exclusive service partnerships, defending against thermal-distillation-dependent competitors retooling for energy compliance. For New Entrants and Emerging Players: Pursue CDSCO certification for India's PLI-subsidized CDMO corridor, where steroid API capacity buildout creates first-mover procurement relationships before incumbent qualification timelines freeze supplier lists. Target agricultural formulation channels in Brazil and Australia under ANVISA and TGA veterinary steroid pathways, where purity requirements sit below pharmaceutical synthesis barriers and pricing pressure remains muted. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH and FDA certification timelines are extending faster than new qualified supply can enter, compressing revenue recognition for subscale processors and creating distressed acquisition opportunities. Watch for membrane filtration technology convergence with continuous chromatography as the inflection signal for process-intensification winners.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Acceleration | ECHA documentary requirements disqualify uncertified competitors from European clinical-trial material supply chains. |
| Membrane-Chromatography Integration | Hybrid systems enable real-time purity monitoring for continuous-processing contracts with top-ten pharmaceutical firms. |
| CDSCO Certification Investment | India's PLI scheme incentives create first-mover advantage for suppliers serving Maharashtra and Gujarat CDMO buildout. |
| Specialized Talent Acquisition | Basel-Shanghai expertise corridor constrains facility scale-up, rewarding early locking of steroid biochemistry cohorts. |
| Waste-to-Value Conversion Partnerships | Residual solution streams from crystallization operations open agricultural formulation channels under lower purity thresholds. |
Research Methodology
A standing panel of peptide manufacturing directors, regulatory affairs leads at German CDMOs, membrane filtration equipment specialists, and procurement managers at Swiss pharmaceutical firms provided ongoing calibration across the study period. Primary interview findings were cross-referenced with secondary sources including ECHA registration databases, FDA starting material guidance documents, NMPA ICH Q3D alignment notices, and customs trade flow records for steroid-derived intermediate categories. Bottom-up capacity assessments at Shandong fermentation facilities were triangulated against top-down demand modeling from German and Swiss contract research organization expansion plans.
Scenario bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product grade tier, extraction technology type, application purity requirement, and end-user regulatory jurisdiction. CAGRs were derived from installed capacity utilization rates, qualification timeline compression effects, and technology adoption curves for membrane filtration displacement of thermal distillation. Forecast inputs incorporated REACH registration queue lengths, NMPA harmonization implementation pacing, and PLI scheme disbursement timelines for Indian CDMO capacity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-supported fermentation conglomerates or rapid membrane technology export liberalization would shift outcomes. Material shifts in ECHA documentary burden intensity or FDA starting material certification cycle duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Global Chlorothalonil Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Global Substrate Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Butadiene Extraction Market