
 Global High Heat Foam Market | 2026-2036
Global High Heat Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Heat Foam Market Intelligence
Specialty polymer production in Europe is broadening the supply of precursors for advanced foam systems, enhancing material availability. BASF SE leverages its integrated chemical manufacturing to supply key melamine and polyimide foams for industrial insulation. Rogers Corporation specializes in high-performance silicone foams, targeting demanding applications within the electronics and transportation sectors. Evonik Industries positions its rigid foam products for critical aerospace components requiring superior thermal stability.
High heat foam refers to a family of cellular polymer or ceramic materials engineered to maintain structural integrity and insulating properties at continuous operating temperatures exceeding 150°C. Their primary function is to provide thermal management, fire resistance, and acoustic dampening in extreme environments. Polyimide and silicone product types command premium pricing in the aerospace and electronics end-user segments due to their superior performance. Phenolic foams represent a cost-effective solution for thermal insulation and fireproofing applications within the construction industry.
Product specifications are heavily influenced by regulatory frameworks governing fire safety and material toxicity across key end-user industries. Mandates from bodies like the US FAA on flammability, the European Union's REACH regulation on chemical substances, and China's GB standards for building materials dictate performance requirements. Navigating these diverse material qualification pathways and securing a resilient supply chain remain critical strategic decisions for manufacturers and their customers.
Market Dynamics
The convergence of stringent fire safety regulations and the aerospace industry's demand for lightweight thermal management materials is the central force shaping the high heat foam market. Mandates from bodies like the FAA and EU agencies compel material certification, driving innovation.
Growth Catalysts
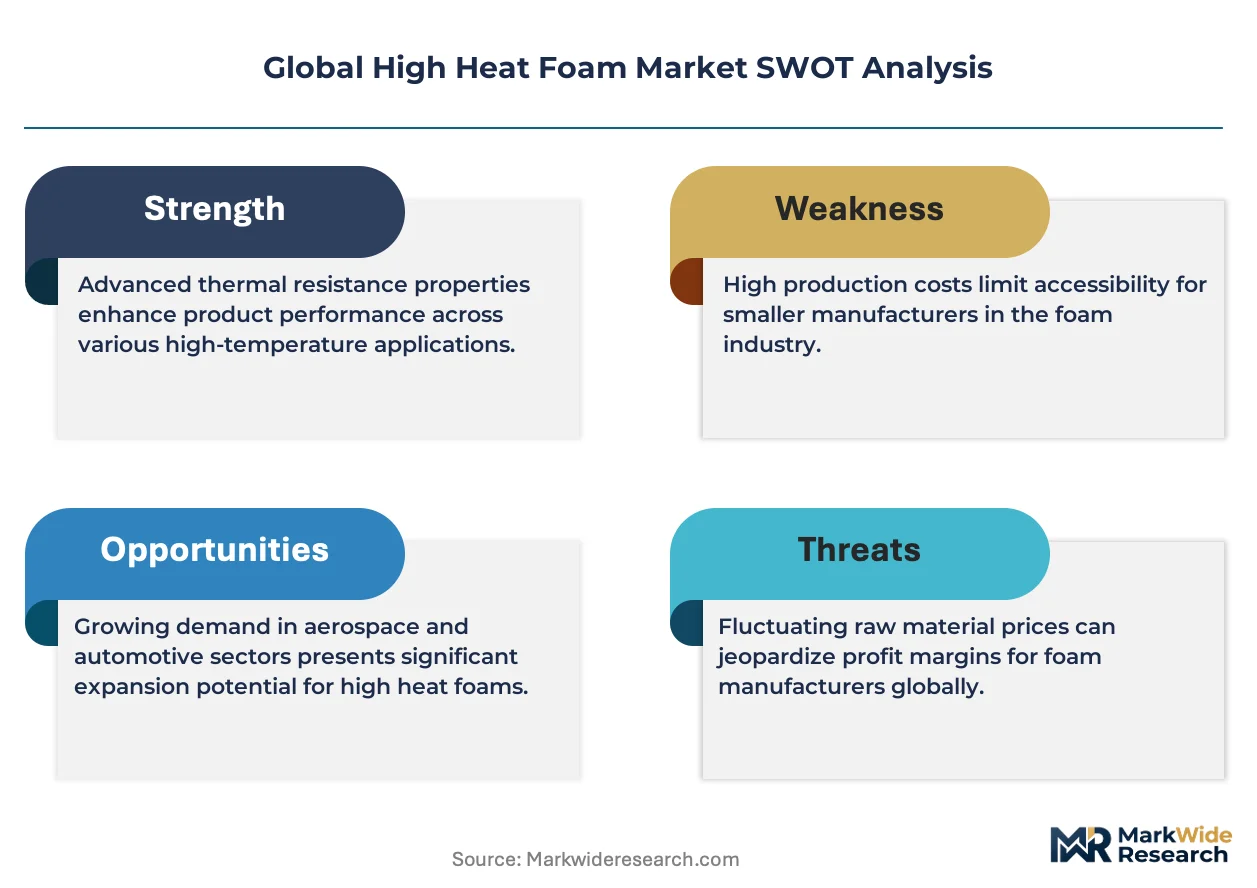
- Aerospace Lightweighting Initiatives:The push for fuel efficiency in commercial and military aircraft requires advanced, lightweight thermal and acoustic insulation, directly benefiting high-performance polyimide and silicone foams.
- Tightening Fire Safety Codes:Regulations such as the European Union's REACH and China's GB standards for building materials mandate the use of certified fire-resistant materials, expanding the addressable market for phenolic and melamine foams.
- Automotive Electrification:The transition to electric vehicles creates substantial demand for thermal management and fire protection solutions within battery packs and high-voltage electronics, opening a new, high-volume application segment.
Market Restraints
- High Precursor Costs:The manufacturing of high-performance foams like polyimide and silicone relies on expensive and specialized chemical precursors, which translates to premium product pricing that can limit adoption in cost-sensitive applications.
- Competition from Conventional Insulation:In applications with less extreme temperature requirements, traditional materials such as mineral wool and fiberglass offer a lower-cost alternative, posing a substitution threat to high heat foams.
- Complex Processing Requirements:The production of certain high heat foams, particularly rigid ceramic or polyimide types, involves complex and capital-intensive manufacturing processes, creating high barriers to entry for new competitors.
Strategic Opportunities
- Expansion in Medical Devices:Opportunities exist in sterilizable, high-temperature foam components for medical equipment and autoclave-safe instrument trays, where thermal stability and chemical inertness are critical performance criteria.
- Development of Bio-Based Foams:Innovating bio-derived precursors for high heat foam production can address sustainability demands and potentially mitigate volatility in petrochemical feedstock prices, appealing to environmentally conscious end-users.
- Growth in Industrial Processing:Applications in industrial furnace linings, pipe insulation, and thermal barriers for chemical processing plants represent a significant opportunity, especially in rapidly industrializing regions of Southeast Asia.
Industry Challenges
- Navigating Regulatory Fragmentation:Manufacturers face the operational challenge of qualifying products across disparate regulatory frameworks, including the FAA in the US, ECHA in Europe, and GB standards in China, which increases testing costs and time-to-market.
- Supply Chain Vulnerability:The supply of essential raw materials for specialty polymers is concentrated among a few key chemical producers, creating vulnerability to geopolitical events, trade policy shifts, and logistical disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Heat Foam Market |
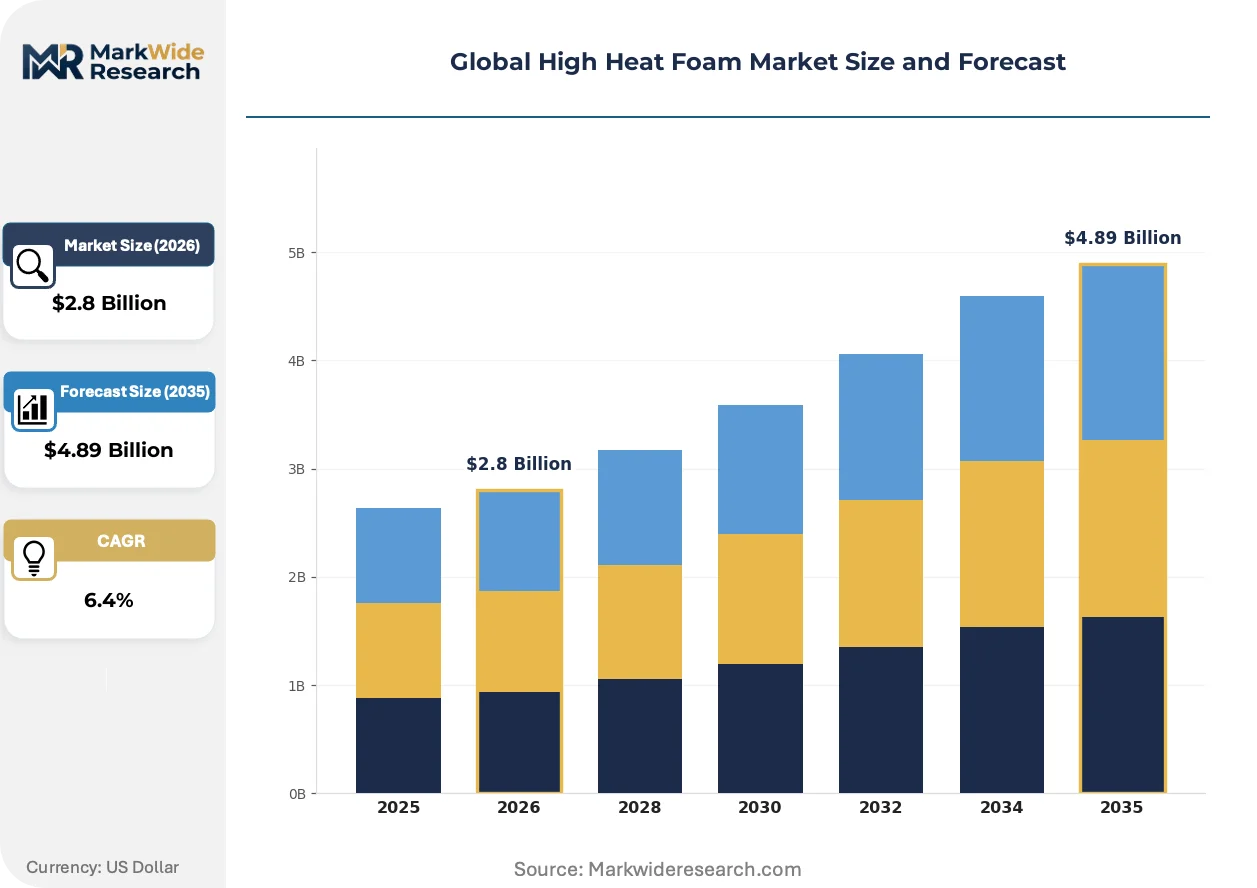
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenolic, Polyimide, Ceramic, Melamine, Silicone Application: Thermal Insulation, Fireproofing, Acoustics, Sealing, Cushioning End User: Aerospace, Electronics Manufacturers, Construction Firms, Transportation Sector, Marine Industry Form: Rigid Foam, Flexible Foam, Spray Foam, Board Foam |
| Companies Covered | Sabic, Sinoyqx, BASF SE, Rogers Corporation, Wacker Chemie AG, Armacell International S.A., UBE Industries Ltd., Intec Foams, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Heat Foam Market Strategic Shifts & Innovations
Product innovation is focused on creating hybrid material systems that balance performance, cost, and regulatory compliance. This drive is a direct response to end-user demands for tailored solutions that meet specific thermal, fire, and toxicity profiles without over-engineering.
Hybrid foam composites, which blend materials like silicone and polyimide, offer tunable properties for specific applications. The aerospace and defense sectors are early adopters, seeking materials with optimized thermal conductivity and mechanical strength for critical components. This development is modularizing thermal management design, enabling engineers to specify performance layer-by-layer instead of relying on a single, monolithic foam structure.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling manufacturers to provide detailed disclosures on material lifecycle impacts. This regulatory pressure accelerates the development of foams with higher recycled content or those derived from more sustainable, non-petrochemical feedstocks. The automotive and construction industries are most affected, as their procurement decisions are increasingly influenced by supply chain transparency and environmental performance metrics.
A clear behavioral change is the shift in purchasing criteria from initial price-per-kilogram to total cost of ownership, including installation, durability, and fire safety compliance. This trend disrupts commodity-based sales channels, favoring suppliers who can provide extensive technical support and certified performance data. This shift is most visible in high-stakes industries like oil and gas, marine, and aerospace, particularly in North America and Europe.
Global High Heat Foam Market Segmentation
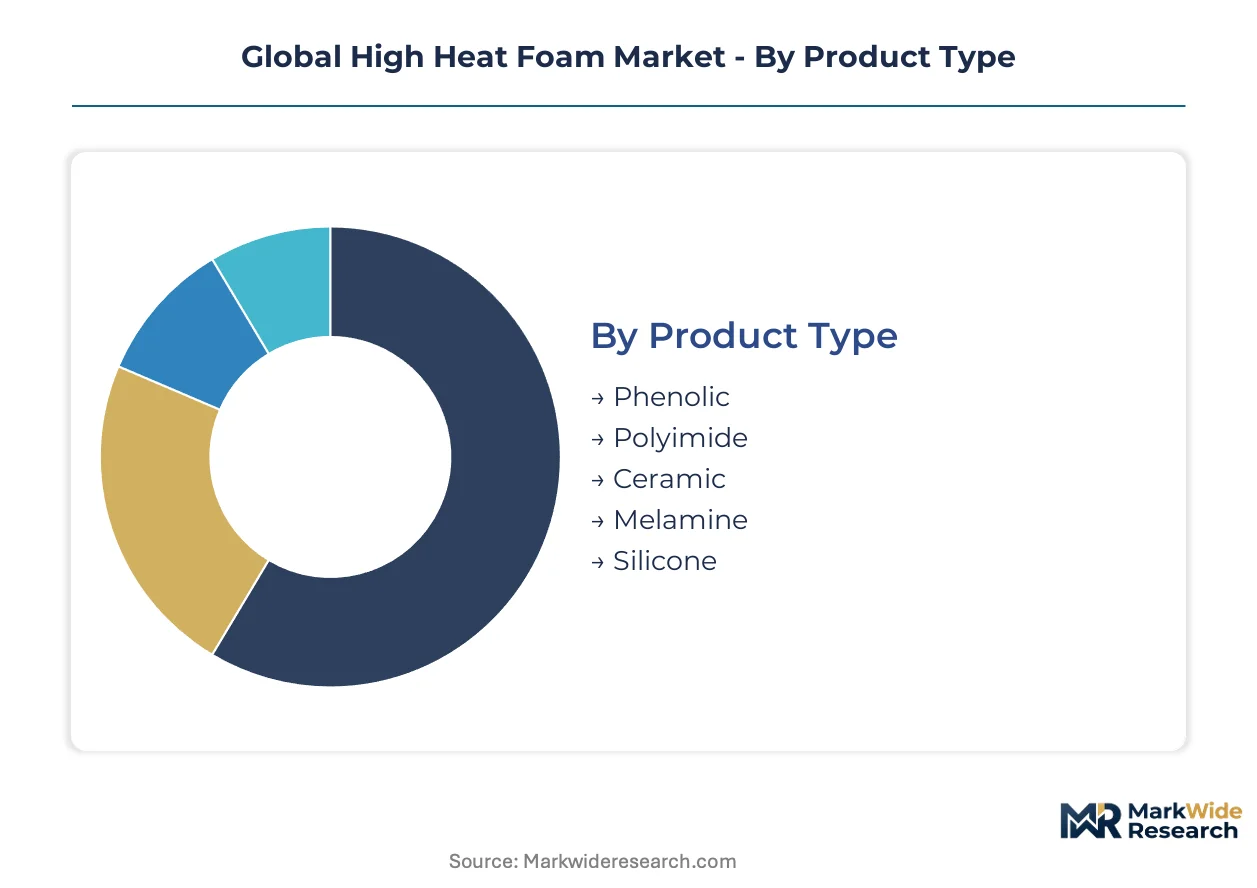
The high heat foam market exhibits diverse performance requirements and material specifications. Segmentation provides a granular understanding of product types, applications, and end-user demands influencing market dynamics. This analysis highlights the critical interplay between material science and regulatory compliance across various sectors.
Product Type:
Material selection within product types is heavily influenced by stringent regulatory certifications required for specific high-stakes applications, including FAA approvals for aerospace components and EU REACH compliance for chemical composition.
- Polyimide:These advanced polymer foams offer exceptional thermal stability and fire resistance, maintaining integrity at continuous operating temperatures exceeding 250°C. Demand concentrates in the aerospace sector for lightweight thermal insulation in aircraft engines and fuselage components, driven by fuel efficiency mandates.
- Silicone:Characterized by their flexibility, excellent thermal insulation, and resistance to extreme temperatures and chemicals, silicone foams are critical for sealing and gasketing. The electronics sector drives demand for high-performance silicone foams in battery packs and sensitive electronic enclosures, requiring superior thermal management.
- Phenolic:These thermoset polymer foams provide cost-effective thermal insulation and inherent fire resistance, often used in construction.
- Ceramic:Composed of inorganic materials, ceramic foams withstand extremely high temperatures, finding use in industrial furnace linings.
- Melamine:Known for their lightweight structure and acoustic dampening properties, melamine foams are utilized in building acoustics and transportation interiors.
Phenolic foam sits at the top of the volume ranking due to its widespread use in construction, with polyimide foam climbing the fastest driven by aerospace innovation.
Application:
The primary function of high heat foams varies significantly by application, ranging from passive fire protection to active thermal management in extreme environments.
- Thermal Insulation:High heat foams in thermal insulation reduce heat transfer, protecting sensitive components and maintaining operational temperatures in demanding environments. Aerospace lightweighting initiatives and industrial processing applications, particularly in chemical plants, drive demand for superior thermal barriers.
- Fireproofing:These applications focus on preventing flame spread and maintaining structural integrity during fire events, crucial for safety and regulatory compliance. Construction firms and the marine industry increasingly adopt fireproofing foams to meet strict fire safety codes, such as China's GB standards.
- Acoustics:High heat foams provide sound absorption and dampening, important for noise reduction in vehicles and industrial settings.
- Sealing:These materials create high-temperature resistant seals and gaskets, ensuring integrity in critical interfaces for electronics and automotive systems.
- Cushioning:High heat resistant cushioning protects sensitive components from vibration and impact in extreme temperature conditions.
Demand for thermal insulation applications is driven by energy efficiency mandates, while fireproofing sees critical adoption in safety-regulated industries.
End User:
End-user industries dictate both the performance requirements and the regulatory compliance pathways for high heat foam products, influencing material development.
- Aerospace:This sector demands ultra-lightweight, fire-resistant, and high-temperature stable foams for aircraft interiors, engine compartments, and thermal blankets. FAA flammability mandates and the continuous push for fuel efficiency compel the use of advanced polyimide and silicone foams in new aircraft designs.
- Transportation Sector:The automotive industry, particularly with the electrification trend, requires high heat foams for battery thermal management, fire protection, and acoustic insulation in electric vehicles. Stricter safety regulations for EV battery packs create substantial demand for specialized silicone and ceramic foams.
- Electronics Manufacturers:These companies utilize high heat foams for thermal management, electrical insulation, and vibration dampening in high-power electronic devices.
- Construction Firms:The construction industry employs high heat foams for insulation, fire barriers, and acoustic panels in commercial and residential buildings.
- Marine Industry:Marine applications require fire-resistant and thermally insulating foams for bulkheads, engine rooms, and accommodation areas on ships.
The aerospace sector represents a significant value pool for premium foams, with the transportation sector presenting new high-volume opportunities through electrification.
Form:
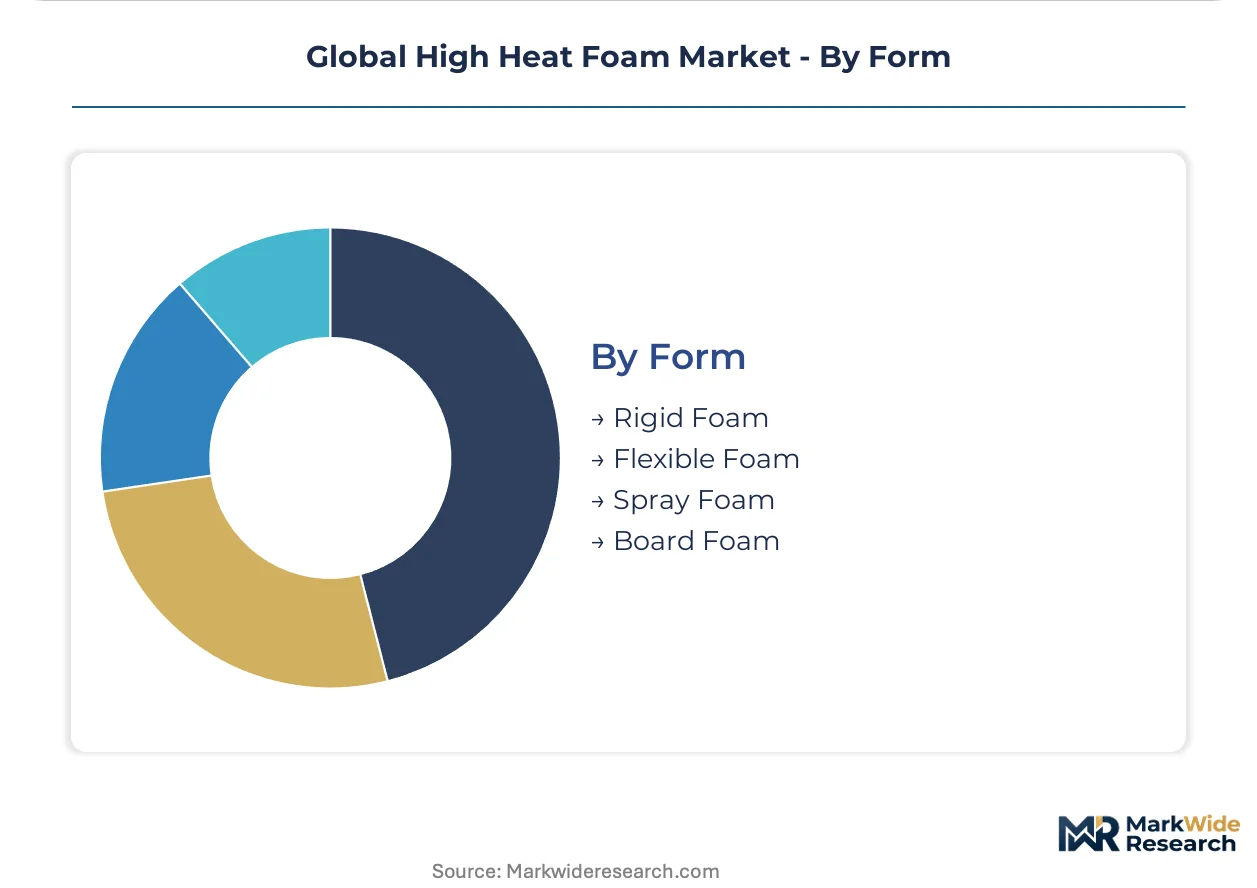
The physical form of high heat foam products determines their ease of installation, application versatility, and structural properties for various end-use cases.
- Rigid Foam:These foams offer structural integrity and high compressive strength, making them suitable for load-bearing thermal insulation and aerospace components. Evonik Industries positions its rigid foam products for critical aerospace applications requiring superior thermal stability.
- Flexible Foam:Characterized by their conformability and ability to absorb vibration, flexible foams are used for gasketing, sealing, and acoustic dampening in irregular spaces. Rogers Corporation specializes in high-performance silicone flexible foams for demanding electronics and transportation applications.
- Spray Foam:Applied as a liquid that expands and cures, spray foams conform to complex geometries, offering seamless insulation and air sealing.
- Board Foam:These pre-formed panels offer ease of installation and consistent thickness for large-area thermal insulation in construction and industrial settings.
The development of flexible foam forms is increasingly driven by specific installation requirements, complementing traditional rigid foam products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced manufacturing and automotive industries drive high heat foam demand, contrasting with the United States' significant aerospace sector. Both nations prioritize material innovation and regulatory compliance. This global market sees diverse regional adoption patterns.
Germany
Demand for high heat foams in Germany stems from its advanced automotive and industrial sectors. The KBA (Federal Motor Transport Authority) mandates stringent material standards for vehicle components. Munich's engineering clusters and Baden-Württemberg's automotive suppliers actively integrate specialized foams for thermal management.
United States
Aerospace lightweighting initiatives propel demand for high-performance foams across the United States. The FAA (Federal Aviation Administration) sets rigorous flammability and thermal stability requirements for aircraft materials. Seattle's aerospace manufacturing hub and Houston's energy sector drive innovation in polyimide and silicone foam applications.
China
Building materials and electric vehicle production fuel significant high heat foam adoption in China. GB standards (Guobiao standards) dictate fire safety and performance for construction and automotive applications. The Yangtze River Delta region, particularly Shanghai, sees extensive use in infrastructure projects and EV battery thermal management.
Japan
Electronics and automotive industries are key consumers of high heat foams in Japan. METI (Ministry of Economy, Trade and Industry) promotes advanced material development for energy efficiency and safety. Tokyo's electronics manufacturers and Nagoya's automotive giants integrate specialized silicone and polyimide foams.
India
Infrastructure development and a growing automotive industry increase the need for high heat foam solutions in India. BIS (Bureau of Indian Standards) regulations guide material specifications for fire resistance in construction. The National Capital Region (NCR) and Pune's industrial belt demonstrate rising adoption for thermal insulation and fireproofing.
Global High Heat Foam Market Key Industry Players
European chemical producers anchor one tier, while North American specialists hold distinct positions in high-performance foam development. The market exhibits a tiered structure, with established chemical giants and niche material innovators. Strategic archetypes include integrated chemical suppliers, specialized foam manufacturers, and application-focused material developers. Portfolio diversification and strategic partnerships represent dominant competitive moves.
On the premium-tier vector, BASF SE, a European chemical producer, exemplifies integrated chemical manufacturing, supplying key melamine and polyimide foam precursors. Rogers Corporation, a North American specialist, represents expertise in high-performance silicone foams for demanding applications within electronics and transportation. Evonik Industries, another European chemical giant, occupies a position in rigid foam products, particularly for critical aerospace components requiring superior thermal stability. These companies anchor different segments of the high heat foam market, reflecting diverse material science capabilities and targeted end-user solutions. Their strategic focus on specific product types and high-value segments shapes competitive dynamics.
| Leading Market Players |
|---|
| Sabic |
| Sinoyqx |
| BASF SE |
| Rogers Corporation |
| Wacker Chemie AG |
| Armacell International S.A. |
| UBE Industries Ltd. |
| Intec Foams |
| Evonik Industries |
| Others |
Cost & Logistics Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) gates both qualified supply and premium-tier pricing access for high heat foams, compelling manufacturers to disclose material lifecycle impacts. This regulatory pressure influences procurement decisions across automotive and construction industries.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade phenolic and melamine foams, driving a shift towards contract-based long-term offtake models. Price differentiation stems from certification level, particularly FAA approvals for aerospace, and customization levels for specialized electronics applications. Pricing pressure stems from the high cost of specialized chemical precursors like polyimide and silicone. Construction firms exhibit the highest price sensitivity, while the aerospace sector remains the least price-sensitive due prioritizing performance over cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream distribution for high heat foams, facilitating localized supply. Geographic supply concentration for key precursors remains significant in Germany, the United States, and China. The market relies heavily on specialized chemical inputs such as melamine, polyimide, and silicone polymers. Single-source vulnerability for these advanced precursors represents a critical structural risk. Distribution often runs through specialized material distributors and direct-to-OEM channels, particularly for high-performance applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA flammability mandates frame the high heat foam market as a regulatory compounder, continuously driving demand for certified, high-performance materials in critical applications like aerospace and transportation.
For Market Incumbents:
Extend product portfolios into hybrid material systems that balance performance and cost, addressing the threat of cost-sensitive alternatives. Deepen vertical integration into specialized precursor manufacturing to mitigate supply chain vulnerability and secure raw material access. Invest heavily in new material certifications across diverse regulatory bodies, including EU REACH and China's GB standards, to maintain market access. Prioritize R&D for advanced silicone and polyimide foams for high-value applications.
For New Entrants and Emerging Players:
Capture white-space opportunities in bio-based foam development, targeting sustainability demands from automotive and construction industries. Focus on niche applications within medical devices, where thermal stability and chemical inertness are critical performance criteria. The industrial processing sector in rapidly industrializing regions of Southeast Asia presents a penetrable segment for cost-effective phenolic foam solutions. A go-to-market angle emphasizing modular, application-specific foam solutions can differentiate offerings.
For Investors and Strategic Acquirers:
Valuations sit cheapest among regional manufacturers specializing in conventional high heat foams like phenolics, offering potential for consolidation. The long-term viability for this market over a 5-10 year window is anchored by persistent regulatory pressure for fire safety and energy efficiency. Acquisition targets should include niche technology specialists with proprietary bio-derived precursor chemistries or advanced processing capabilities. New EV battery pack safety standards represent a specific signal to watch for inflection in market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Specialty Precursors | Secures supply for high-performance foams and mitigates raw material price volatility for BASF SE. |
| R&D for Hybrid Foam Composites | Enables tailored thermal management solutions for aerospace and defense, optimizing performance. |
| Investment in Bio-Based Foam Development | Addresses sustainability mandates and diversifies feedstock sources for new material innovators. |
| Geographic Expansion in Southeast Asia | Captures rising demand from industrial processing and infrastructure development in emerging economies. |
| Certification for EV Battery Thermal Management | Unlocks high-volume opportunities in the automotive electrification trend for Rogers Corporation. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a comprehensive market view. This involved combining insights from R&D directors, procurement managers, regulatory specialists, and application engineers with data from industry association reports, patent databases, and government regulations. Bottom-up and top-down triangulation ensured data accuracy and consistency across all market segments.
Historical data was cross-referenced with expert panel input to develop the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, form, and regional regulatory frameworks. Compound annual growth rates were derived by assessing demand drivers, market restraints, and strategic opportunities. Aerospace production forecasts and electric vehicle adoption rates served as key industry-specific forecast inputs.
Raw material price volatility, new regulatory shifts, and disruptive material innovations are the dominant revision risks for future market projections. Forecasts reflect assumptions documented through iterative validation with industry stakeholders. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-K Dielectric Material Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
Hexafluoropropylene Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
High Molecular Weight Polyisobutylene Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
High Performance Mercury Sorbent Market