
 Pulp and Paper Enzymes Market | 2026-2036
Pulp and Paper Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp and Paper Enzymes Market Analysis
Food-grade enzyme purity standards is collapsing the barrier between pharmaceutical-grade suppliers and industrial paper chemical markets. Novonesis leverages its fermentation scale to occupy the premium cellulase tier for kraft pulp pre-treatment. AB Enzymes GmbH anchors European supply through specialized hemicellulase formulations tailored to hardwood feedstocks. BASF SE extends its position via backward integration into enzyme substrate production, reducing lot-to-lot variability for paper mill clients.
Pulp and paper enzymes comprise protein-based biocatalysts—typically operating at 40–65°C and pH 4.5–8.0—that selectively degrade lignocellulosic components to reduce chemical load in fiber processing. Their primary commercial purpose centers on improving pulp yield, reducing bleaching-stage effluent toxicity, and enabling closed-loop water systems. Xylanases now dominate bleaching-aid applications due to their compatibility with existing mill equipment and minimal capital retrofit requirements. Bio-deinking represents the fastest-growing application segment as recovered fiber quality standards tighten across European packaging supply chains. Liquid formulation technology leads volume shipments, though immobilized enzyme variants capture disproportionate margin pools in specialty tissue operations.
The EPA effluent limitation guidelines shape North American enzyme demand by penalizing adsorbable organic halogen discharge from chlorine-based bleaching. REACH registration requirements and the EU F-Gas Regulation redirect European mills toward enzymatic process alternatives that avoid hazardous chemical inventories. India's Central Pollution Control Board mandates zero liquid discharge for large pulp complexes, creating compliance-driven pull for waste-treatment enzyme suites. Stakeholders must monitor how evolving carbon border adjustment mechanisms recalibrate the cost advantage of enzymatic versus conventional chemical processing across integrated mill networks.
Market Dynamics
The pulp and paper enzymes sector pivots on regulatory displacement of chlorinated bleaching chemistry, with REACH chemical restrictions and EPA effluent guidelines forcing mill-level process re-engineering toward enzymatic alternatives.
Growth Catalysts
- EU Green Deal compliance deadlines:Nordic pulp corridors in Sweden and Finland accelerate xylanase adoption to eliminate adsorbable organic halogen discharge. Specialty paper producers retrofit bleaching sequences without capital-intensive equipment replacement.
- India's zero liquid discharge mandates:The Central Pollution Control Board mandates enzymatic waste-treatment suites for large integrated complexes, pulling cellulase and hemicellulase demand into South Asian supply chains.
- Bio-deinking technology maturation:Recovered fiber quality standards across European packaging supply chains tighten specification tolerances, positioning enzyme-based deinking as the preferred contaminant removal pathway for OCC furnish.
Market Restraints
- Fermentation substrate cost volatility:Corn steep liquor and wheat bran price swings compress enzyme producer margins and destabilize long-term supply contracts with paper mill clients.
- Single-source supplier concentration:Food-grade enzyme purity standards collapse market segmentation, concentrating premium cellulase supply among pharmaceutical-grade fermentation specialists with limited pulp industry technical service depth.
- Temperature-pH operational windows:Enzyme activity constraints at 40–65°C and pH 4.5–8.0 require mill-specific formulation customization, extending qualification timelines and locking out smaller regional producers lacking application engineering resources.
Strategic Opportunities
- Hardwood hemicellulase specialization:Eucalyptus and acacia pulp expansion in Brazil and Indonesia creates unmet demand for tailored xylanase-mannanase blends optimized for tropical hardwood lignin chemistry.
- Closed-loop water system integration:Immobilized enzyme variants capture disproportionate margin pools in specialty tissue operations where water recycling mandates intensify biocatalyst reuse economics.
- Carbon border adjustment mechanism positioning:EU CBAM implementation recalibrates cost structures for imported pulp, incentivizing enzymatic processing certification as a Scope 3 emissions reduction pathway for integrated European mills.
Industry Challenges
- Application biochemistry expertise scarcity:Mill operators lack trained enzymologists to optimize dosage protocols across varying furnish compositions, forcing reliance on supplier technical service that strains field engineering capacity.
- ISO 14001 environmental management integration:Enzyme procurement teams must document lifecycle carbon footprint data for certification audits, creating procurement friction where supplier ESG disclosure maturity remains uneven.
- Legacy DCS control system interfacing:Enzyme dosing automation requires middleware development to connect bioreactor monitoring with existing distributed control architectures, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp and Paper Enzymes Market |
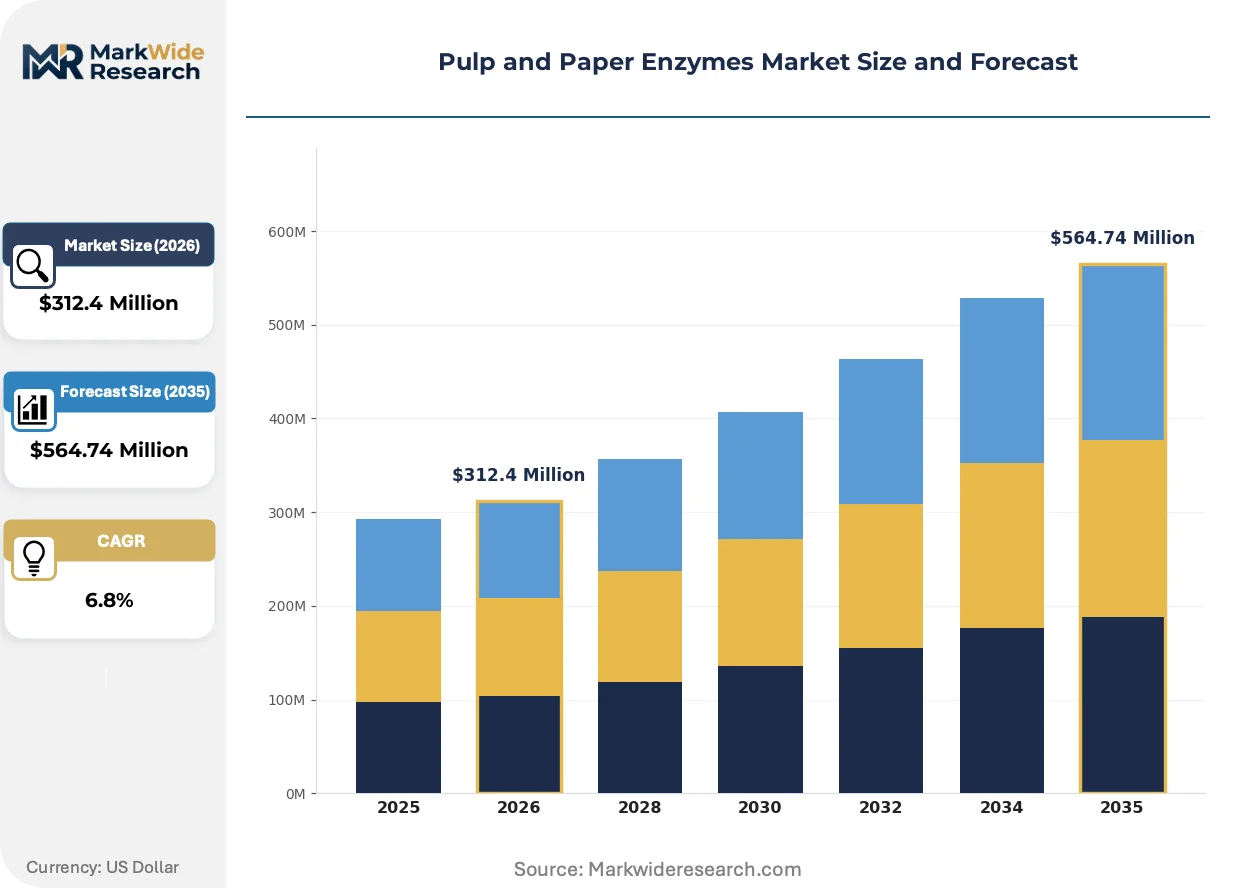
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulases, Hemicellulases, Xylanases, Laccases Application: Pulping, Bleaching, Waste Treatment, Bio-deinking End User: Paper Manufacturers, Packaging Industry, Tissue Producers, Specialty Paper Technology: Liquid Formulation, Solid Formulation, Enzyme Boards, Immobilized Enzymes |
| Companies Covered | AB Enzymes GmbH, Amano Enzyme Inc., Novonesis, Sunson Industry Group, Advanced Enzyme Technologies, DuPont Industrial Biosciences, Buckman, Metgen Oy, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp and Paper Enzymes Market Emerging Trajectories
Enzyme formulation technology is fragmenting along temperature stability and substrate specificity vectors, with liquid and immobilized variants diverging into distinct competitive arenas shaped by mill water system configuration.
Genetic engineering of thermostable cellulase variants is fragmenting the premium product tier. Kraft pulp pre-treatment operators in Finland and Sweden adopt these biocatalysts for reduced steam demand in fiberline operations. The technology is fragmenting historical supplier-customer relationships as food-grade fermentation specialists capture industrial paper chemical contracts previously held by commodity chemical distributors.
REACH registration requirements redirect European mills toward enzymatic alternatives that avoid hazardous chemical inventory reporting burdens. The regulation compresses chlorine dioxide consumption in bleaching sequences across German and French specialty paper producers. Nordic integrated mills respond with dedicated enzyme storage and dosing infrastructure investments to maintain TCF and ECF certification tiers.
Specification-driven procurement now dominates enzyme sourcing decisions as packaging converters demand chain-of-custody documentation for recycled content claims. Mill procurement teams unbundle enzyme supply from bundled chemical service contracts, forcing standalone price and performance benchmarking. This behavioral shift concentrates most visibly in German corrugated board supply chains where FSC and PEFC certification requirements cascade upstream to pulp processing inputs.
Pulp and Paper Enzymes Market Segmentation
Enzyme procurement in pulp and paper operations fragments along four intersecting dimensions: biocatalyst chemistry, process integration point, customer scale, and formulation technology. Each axis carries distinct margin profiles and regulatory exposure that reshape supplier-customer contracting terms.
Product Type:
REACH chemical restrictions and EPA effluent guidelines differentiate enzyme demand by biocatalyst class, with halogen-displacement mandates favoring specific lignin-modifying enzymes over others.
- Xylanases:These hemicellulose-selective enzymes cleave xylose backbones to liberate lignin fragments without fiber damage. Nordic integrated mills in Sweden and Finland deploy xylanases to achieve TCF bleaching certification while avoiding chlorine dioxide inventory reporting under REACH. The enzyme dominates bleaching-aid applications due to minimal capital retrofit requirements.
- Cellulases:Beta-glucan hydrolysis enzymes reduce refining energy demand in kraft pulp pre-treatment. Finnish specialty paper producers leverage thermostable variants to cut steam consumption; India's Central Pollution Control Board zero-liquid-discharge mandates pull cellulase demand into South Asian waste-treatment suites.
- Hemicellulases:Broad-spectrum carbohydrases target mannan and galactan side chains in hardwood pulps. Eucalyptus processors in Brazil specify customized formulations for tropical fiber chemistry.
- Laccases:Copper-containing oxidoreductases enable radical-mediated lignin degradation. Tissue operations with closed-loop water systems specify laccase for effluent color reduction.
Xylanases handle the majority of throughput; laccases are expanding most quickly on share as water recycling mandates intensify.
Application:
Process-stage economics determine enzyme selection, with bleaching and bio-deinking commanding premium pricing due to regulatory compliance value.
- Bleaching:Enzyme-aided sequences replace chlorine dioxide in ECF and TCF protocols. German specialty paper producers retrofit existing D-stage towers with xylanase dosing skids to meet EU Green Deal AOX discharge limits.
- Bio-deinking:Lipase-esterase blends detach toner and ink from recovered fiber surfaces. European packaging converters facing FSC chain-of-custody audits specify enzyme deinking for OCC furnish quality certification.
- Pulping:Pre-hydrolysis kraft operations use cellulase to enhance liquor penetration. Brazilian eucalyptus mills optimize enzyme dosage for reduced H-factor cooking.
- Waste Treatment:Sludge dewatering and effluent BOD reduction applications concentrate in Indian integrated complexes under zero-liquid-discharge enforcement.
Bleaching anchors volume demand; bio-deinking is climbing the fastest as recovered fiber specifications tighten.
End User:
Customer-scale differentiation separates commodity enzyme buyers from formulation-customization clients willing to pay technical-service premiums.
- Paper Manufacturers:Integrated kraft mills with captive pulping operations represent the largest enzyme volume purchasers. Swedish and Finnish producers negotiate multi-year supply agreements tied to TCF certification maintenance.
- Packaging Industry:Corrugated board and containerboard converters drive bio-deinking enzyme demand. German packaging supply chains cascade FSC and PEFC documentation requirements upstream to recovered fiber processing inputs.
- Tissue Producers:Premium towel and hygiene product manufacturers specify immobilized enzyme variants for closed-loop water system integration.
- Specialty Paper:Currency, filter, and technical paper producers require food-grade enzyme purity standards that collapse traditional market segmentation between industrial and pharmaceutical-grade suppliers.
Paper manufacturers absorb the bulk of shipments; specialty paper is gaining share fastest on purity-premium expansion.
Technology:
Formulation stability and dosing automation compatibility segment the supply base by mill infrastructure vintage.
- Liquid Formulation:Standard aqueous enzyme concentrates ship in bulk tote quantities for continuous dosing. Most European and North American mills specify liquid forms for compatibility with existing chemical handling infrastructure.
- Immobilized Enzymes:Carrier-bound biocatalysts enable multi-batch reuse in water-recycling tissue operations. The technology captures disproportionate margin pools where water reuse economics justify higher unit costs.
- Solid Formulation:Spray-dried powders serve regional mills with limited cold-chain logistics capabilities. Southeast Asian and Latin American installations favor solid forms for ambient-temperature storage.
- Enzyme Boards:Pre-impregnated carrier sheets deliver targeted biocatalyst release in specific process zones. Pilot installations in Finnish specialty paper mills test board-based dosing for precise retention-time control.
Liquid formulation moves the largest volumes; immobilized enzymes are expanding most rapidly on water-recycling mandate penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in pulp and paper enzymes tilt toward net-importing manufacturing hubs, with Nordic surplus production supplying deficit markets in Asia-Pacific and Southern Europe. Currency-adjusted freight costs and carbon border compliance now outweigh traditional price arbitrage in procurement decisions.
Sweden
Integrated kraft mills in Sundsvall and Örnsköldsvik drive xylanase demand for TCF bleaching certification. The Swedish Environmental Protection Agency enforces strict AOX discharge limits that eliminate chlorine dioxide alternatives. Stora Enso's Kvarnsveden complex anchors the Nordic pulp corridor's enzyme consumption cluster.
Finland
Thermostable cellulase adoption accelerates in Kotka and Kemi fiberlines to reduce steam intensity. Finnish chemical safety authority Tukes enforces REACH registration compliance for all bleaching-aid imports. Metsä Fibre's Joutseno mill exemplifies enzyme-based kraft pre-treatment scale deployment.
Germany
Specialty paper producers in Bavaria and North Rhine-Westphalia retrofit D-stage towers with enzyme dosing skids. The Federal Environment Agency implements EU Green Deal AOX reduction timelines. Haindl Paper's Augsburg operations demonstrate chlorine-free bleaching sequence conversion at commercial scale.
India
Large integrated complexes in Gujarat and Maharashtra deploy cellulase-hemicellulase suites for zero-liquid-discharge compliance. The Central Pollution Control Board mandates enzymatic waste-treatment for pulp mills exceeding discharge thresholds. Tamil Nadu Newsprint's Karur facility integrates biocatalyst systems for sludge dewatering operations.
Brazil
Eucalyptus pulp expansion in São Paulo and Minas Gerais states creates demand for hardwood-optimized hemicellulase blends. The National Environment Council enforces effluent color standards that favor laccase-based lignin modification. Fibria's Três Lagoas complex pilots customized xylanase-mannanase formulations for tropical fiber chemistry.
Pulp and Paper Enzymes Market Vendor Landscape
Listed leaders compete with private specialists across fermentation scale and application engineering depth. The supplier base concentrates around three archetypes: pharmaceutical-grade fermentation houses leveraging food-grade purity standards, industrial chemical distributors with backward integration into enzyme substrate production, and regional biotech specialists focused on tropical hardwood formulations. Consolidation pressure intensifies as REACH registration costs and technical service requirements lock out smaller regional players.
Within the premium-tier vector, Novonesis and BASF SE exemplify scale-driven archetypes with captive fermentation infrastructure. AB Enzymes GmbH occupies a distinct position among European specialists with application-specific formulation capabilities. Among Asia-Pacific-based suppliers, Sunson Industry Group and Advanced Enzyme Technologies represent regional scale players expanding beyond domestic market boundaries.
| Leading Market Players |
|---|
| AB Enzymes GmbH |
| Amano Enzyme Inc. |
| Novonesis |
| Sunson Industry Group |
| Advanced Enzyme Technologies |
| DuPont Industrial Biosciences |
| Buckman |
| Metgen Oy |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day enzyme formulation lead times concentrate pricing power among pharmaceutical-grade fermentation houses with captive substrate production, while paper mill procurement teams absorb volatility through annual contract structures indexed to corn steep liquor futures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on certification grade and customization level. Price differentiation hinges on food-grade purity standards and REACH registration documentation, with specialty paper producers least sensitive and regional packaging converters most sensitive to unit cost. Pricing pressure stems from fermentation substrate cost volatility, compressing margins for non-integrated suppliers unable to backward integrate into wheat bran or corn steep liquor production.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Indian and Brazilian mills sourcing Nordic-formulated enzyme concentrates. Supply concentrates in Denmark, Germany, and Finland, with raw material dependencies on agricultural fermentation feedstocks and specialized bioreactor components. Single-source vulnerability runs through pharmaceutical-grade cellulase suppliers lacking pulp industry technical service depth. Distribution runs through regional chemical distributors with application engineering capabilities, bypassing commodity traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application biochemistry expertise scarcity defines competitive advantage, as mill operators lack trained enzymologists to optimize dosage protocols across varying furnish compositions.
For Market Incumbents: Compound technical service capacity through dedicated field engineering teams in Nordic pulp corridors, defending against emerging regional biotech specialists in tropical hardwood formulations. Prioritize backward integration into enzyme substrate production to reduce lot-to-lot variability and lock in multi-year supply agreements with integrated kraft mills. For New Entrants and Emerging Players: Differentiate on hardwood-specific hemicellulase blends for eucalyptus and acacia pulp expansion in Brazil and Indonesia, the most penetrable geography given unmet demand for tropical fiber chemistry. Pursue direct technical partnerships with South Asian integrated complexes facing zero-liquid-discharge mandates, offering waste-treatment enzyme suites as the entry wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial chemical distributors with enzyme distribution rights but lacking captive fermentation infrastructure, particularly those serving German specialty paper producers. Long-term viability rests on positioning for carbon border adjustment mechanism compliance as Scope 3 emissions certification becomes a procurement gate. Watch EU CBAM implementation timelines as the inflection signal for enzymatic processing cost advantage recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive corn steep liquor supply secures margin stability for Novonesis and BASF against agricultural commodity swings. |
| Hardwood Formulation Specialization | Custom xylanase-mannanase blends capture Brazilian eucalyptus pulp expansion as Fibria scales tropical fiber output. |
| Closed-Loop Water System Integration | Immobilized enzyme variants command premium positioning in Finnish tissue operations under intensifying water reuse mandates. |
| REACH Registration Acceleration | Early compliance locks out smaller regional competitors from German specialty paper supply chains facing chemical inventory restrictions. |
| Technical Service Capacity Expansion | Dedicated field enzymologists address mill operator expertise gaps, extending qualification timelines and deepening supplier switching costs. |
Methodological Framework
A standing panel of fermentation process engineers, paper mill technical directors, procurement leads at Nordic integrated kraft complexes, and regulatory affairs specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against ECHA REACH registration databases, customs trade flows for enzyme concentrates, and SEC filings from listed fermentation houses. Bottom-up volume modeling triangulated against top-down market sizing from industry association capacity data.
Consistency checks validated volume and value outputs against external benchmarks including trade association production statistics and regional pulp capacity announcements. The analytical framework segments across biocatalyst chemistry, process integration point, customer scale, and formulation technology throughout the projection horizon. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory compliance deadlines and carbon border mechanism phasing. Industry-specific inputs include enzyme dosage rates per ton of pulp and steam reduction coefficients from thermostable cellulase deployment.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt fermentation feedstock price shocks would require recalibration. Forecasts reflect documented assumptions regarding REACH implementation timelines and zero-liquid-discharge mandate adherence in South Asia. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Electroelutor Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Mass Finishing Consumables Market