
 US Industrial Gas Regulator Market | 2026-2036
US Industrial Gas Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Gas Regulator Market Analytics
Equipment leasing and managed service contracts are reshaping competitive dynamics in the US industrial gas regulator space, lowering capital barriers for mid-sized chemical processors. Parker Hannifin Corporation leverages its distribution network to dominate aftermarket service contracts across the Gulf Coast. Emerson Electric Co. anchors its position through integrated digital monitoring capabilities embedded in pressure control systems. Swagelok Company specializes in high-purity applications where material traceability commands sustained pricing power.
Industrial gas regulators are precision mechanical devices that reduce high-pressure gas from cylinders or pipelines to safe, usable levels through spring-loaded diaphragm or piston mechanisms, typically constructed from brass, stainless steel, or aluminum alloys with elastomer or metal seals rated for specific temperature and corrosion environments. Their primary purpose is protecting personnel, equipment, and processes from pressure excursions while maintaining flow stability for welding, chemical synthesis, analytical instrumentation, and medical gas delivery. Pressure regulators occupy the largest revenue pool given their ubiquity across every end-use vertical, though safety relief valves capture disproportionate margin in hazardous service applications where API and ASME code compliance is mandatory. Flow regulators are gaining share in pharmaceutical manufacturing as continuous processing replaces batch methods, requiring tighter mass flow control.
The EPA enforces emissions standards that compel facility operators to replace leaking regulator bonnets and seals, while OSHA's Process Safety Management standard mandates documented inspection intervals for pressure-relief devices in covered chemical processes. DOT pipeline regulations administered by PHMSA govern transportable gas regulator certification, creating a dual compliance burden for suppliers serving both stationary and mobile applications. Stakeholders must monitor evolving hydrogen infrastructure codes, as repurposed natural gas regulator designs face material compatibility questions that will determine which manufacturers capture emerging clean energy demand.
Market Dynamics
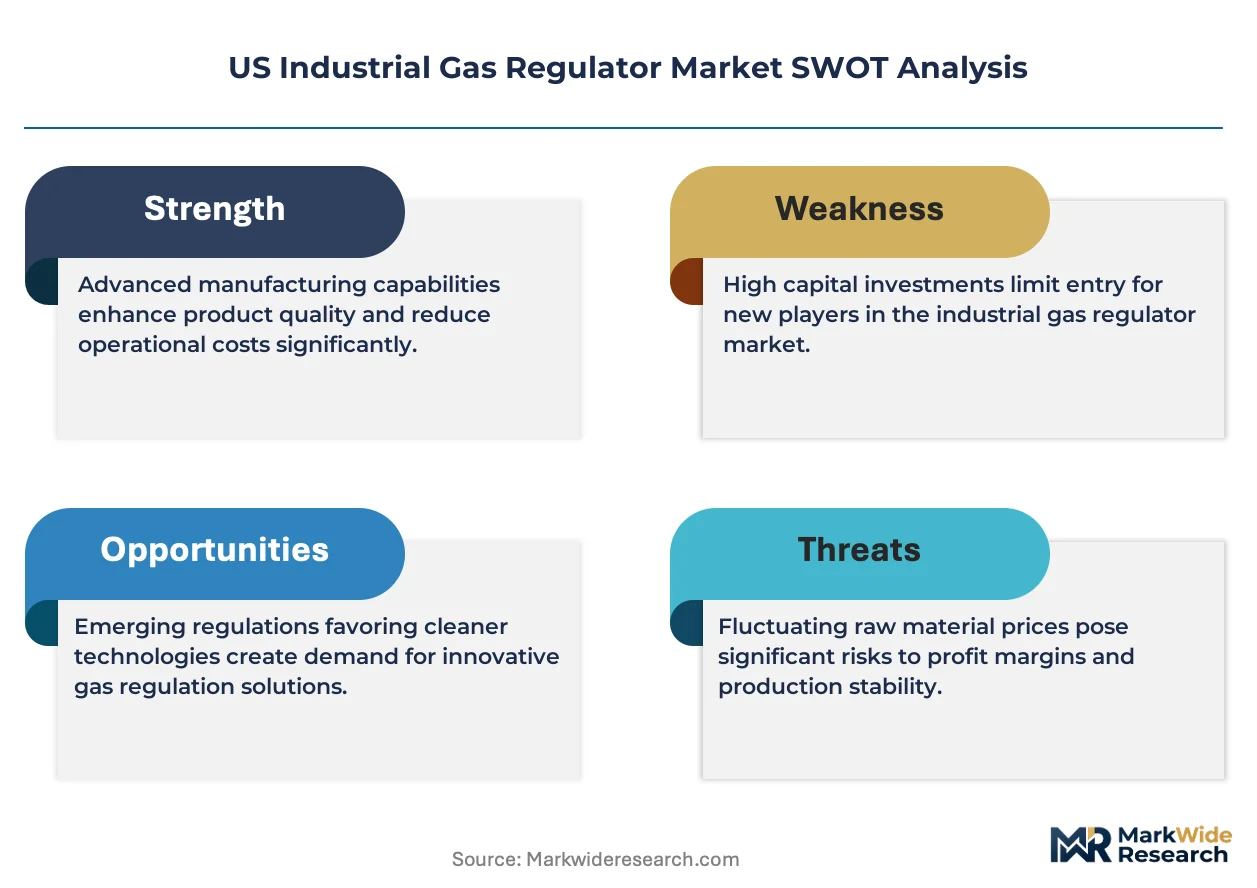
Equipment leasing and managed service contracts are compressing capital barriers for mid-sized chemical processors across the Gulf Coast petrochemical corridor, redirecting procurement toward recurring revenue relationships rather than discrete hardware purchases.
Growth Catalysts
- OSHA Process Safety Management:Mandatory documented inspection intervals for pressure-relief devices in covered chemical processes sustain replacement demand for certified regulator systems.
- Pharmaceutical manufacturing:Rising batch complexity and the shift toward continuous processing are tightening mass flow control requirements, expanding regulator specification intensity.
- Hydrogen infrastructure codes:Emerging clean energy deployment is creating material compatibility questions that favor manufacturers with advanced metallurgy capabilities.
Market Restraints
- Stainless steel price volatility:Raw material input swings compress margin predictability for brass and alloy-based regulator fabricators serving price-sensitive industrial segments.
- Gulf Coast supplier concentration:Refinery and chemical plant procurement clusters create geographic demand risk if regional petrochemical expansion cycles reverse.
- Repurposed natural gas designs:Existing regulator architectures face hydrogen embrittlement limitations that constrain rapid product line extension without fundamental redesign.
Strategic Opportunities
- Texas-Louisiana hydrogen hub development:DOE-funded regional clean hydrogen networks will require purpose-built pressure control systems with hydrogen-specific sealing technologies.
- Integrated digital monitoring:Convergence of mechanical regulators with IoT pressure sensors enables predictive maintenance contracts and recurring software revenue streams.
- Equipment-as-a-service models:Leasing structures with bundled calibration and inspection services capture mid-sized processors previously priced out of premium certified systems.
Industry Challenges
- ASME code certification timelines:Extended pressure vessel qualification periods delay product launches for safety relief valves in hazardous service applications.
- Legacy SCADA integration:New digital-enabled regulators face interoperability friction with existing plant control architectures, lengthening sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Gas Regulator Market |
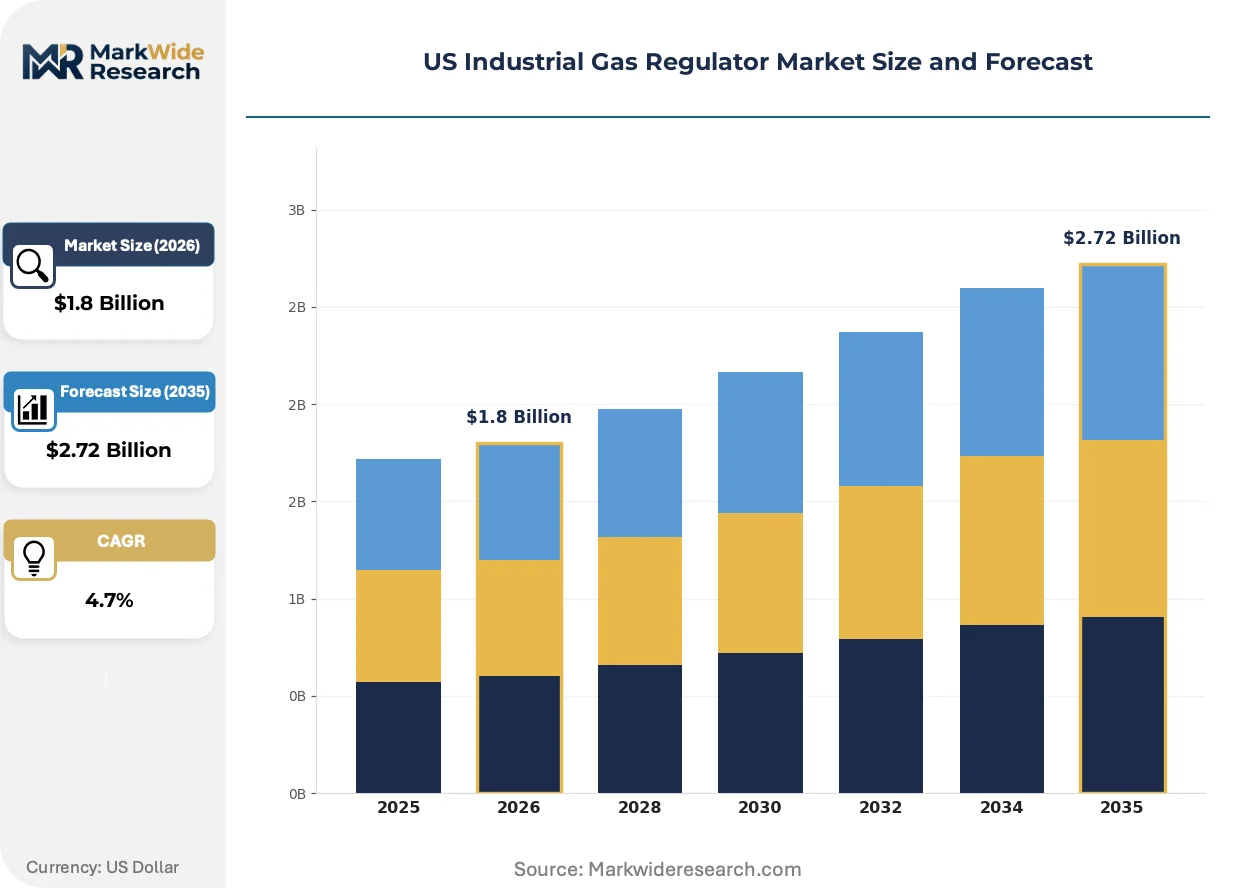
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Regulators, Flow Regulators, Vacuum Regulators, Safety Relief Valves End User: Manufacturing, Oil & Gas, Chemical, Pharmaceuticals Installation: On-Site, Off-Site, Centralized, Decentralized Service Type: Maintenance, Repair, Calibration, Testing |
| Companies Covered | Emerson Electric Co., Airgas Inc., Parker Hannifin Corporation, Swagelok Company, The Harris Products Group, Air Liquide, Linde Group, GCE Group, Honeywell International Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Gas Regulator Market Evolving Landscape
Digitalization of pressure control systems is reconfiguring how operators monitor gas flow, shifting value capture from hardware margins toward data-enabled service layers. Three developments are accelerating this transformation.
Sensor-embedded regulators with real-time pressure telemetry are virtualizing traditional mechanical-only architectures, enabling remote diagnostics and predictive seal replacement scheduling. Downstream chemical processors in Texas and Louisiana are piloting these systems at expanding hydrogen blending facilities. The technology is virtualizing aftermarket service relationships by converting episodic repair calls into continuous monitoring subscriptions.
EPA Clean Air Act amendments targeting fugitive emissions from valve bonnets and seals are compelling facility operators to accelerate replacement cycles for older regulator inventories. The industrial consequence is a compliance-driven hardware refresh wave across petrochemical complexes. Gulf Coast refineries are responding by specifying low-emission packing designs and documented leak detection protocols in procurement tenders.
Mid-sized processors are consolidating vendor relationships around integrated service providers capable of delivering calibration, inspection, and documentation compliance through single-source contracts. This concentration is displacing fragmented procurement across multiple specialty distributors. The shift is most visible in pharmaceutical manufacturing facilities where batch record integrity requirements favor suppliers with comprehensive quality management systems.
US Industrial Gas Regulator Market Segmentation
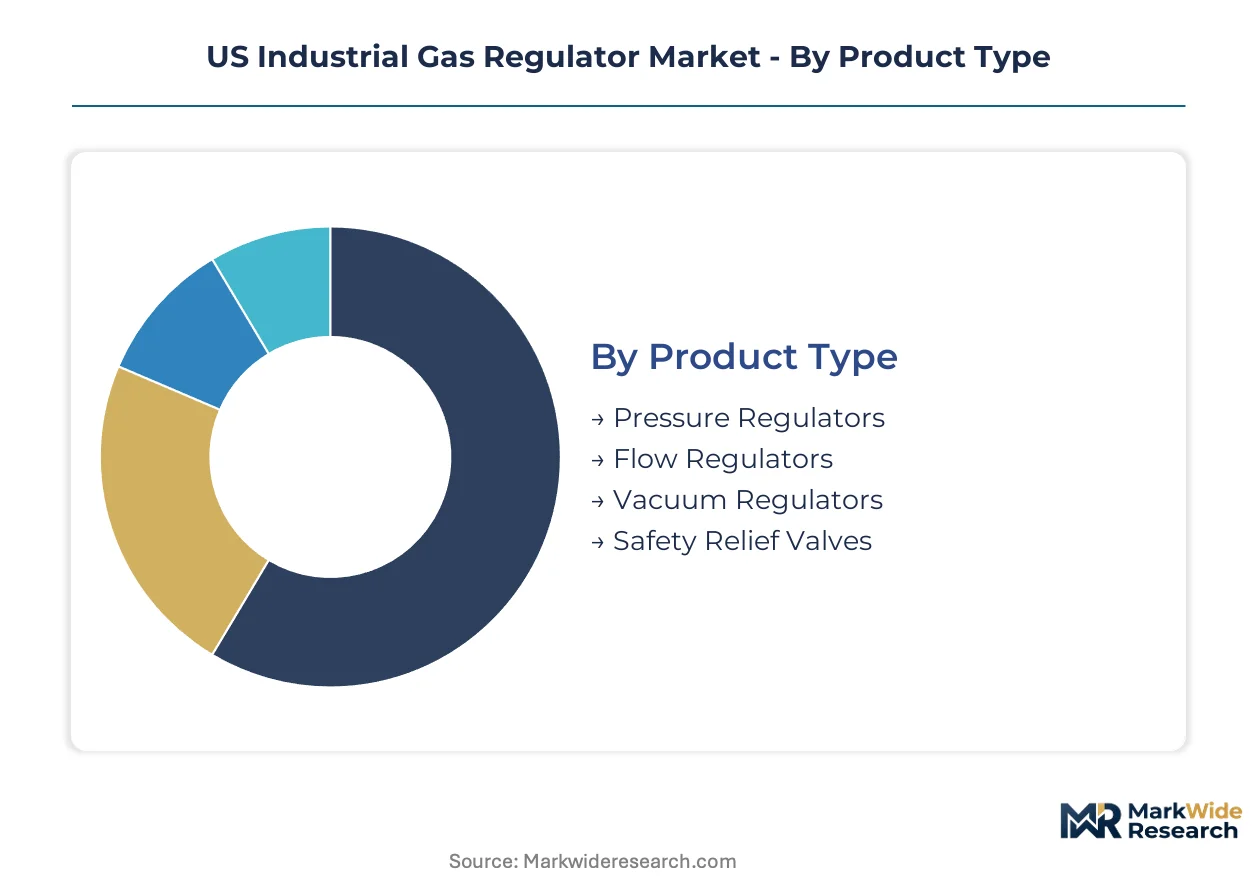
Industrial gas regulator procurement divides across four structural dimensions that shape vendor strategy and pricing architecture. Product type determines certification intensity and material specification. End-user verticals impose divergent purity and safety protocols. Installation topology influences capital deployment and service contract structures. Service type segmentation is reconfiguring revenue models toward recurring relationships.
Product Type:
Mature mechanical designs coexist with emerging digital-integrated architectures across this category.
- Pressure Regulators:Spring-loaded diaphragm or piston mechanisms constructed from brass, stainless steel, or aluminum alloys reduce cylinder or pipeline pressures to operational levels. Demand concentrates in Gulf Coast petrochemical complexes where OSHA Process Safety Management mandates documented inspection intervals for pressure-relief devices in covered chemical processes.
- Flow Regulators:Mass flow control devices with precision orifice configurations enable tighter process control in continuous manufacturing environments. Pharmaceutical manufacturing facilities in New Jersey and Massachusetts specify these systems as batch complexity rises and continuous processing displaces traditional batch methods.
- Vacuum Regulators:Sub-atmospheric pressure control systems maintain precise negative pressure environments for analytical instrumentation and semiconductor fabrication.
- Safety Relief Valves:ASME-code certified devices protect vessels and piping from overpressure events through automatic discharge mechanisms.
Pressure regulators retain volume leadership; flow regulators hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive process industries from specification-driven life sciences sectors.
- Manufacturing:Metal fabrication, automotive assembly, and general industrial operations deploy brass-bodied regulators for welding and cutting applications. Procurement clusters in Midwest industrial corridors where price sensitivity favors standardized catalog products over custom-engineered systems.
- Oil & Gas:Upstream production and midstream transmission operations require corrosion-resistant alloys for sour gas service. Texas and Louisiana shale plays drive specification of high-integrity regulator systems with hydrogen sulfide compatibility.
- Chemical:Process plants handling reactive or toxic media demand material traceability and documented leak-test protocols. EPA Clean Air Act amendments targeting fugitive emissions compel facility operators to replace older regulator inventories with low-emission packing designs.
- Pharmaceuticals:Aseptic manufacturing and bioprocessing applications mandate electropolished stainless steel with full material certification. FDA validation requirements favor suppliers with comprehensive quality management systems and batch record integrity capabilities.
Manufacturing commands installed base volume; pharmaceuticals generates premium pricing power.
Installation:
Volume concentration favors centralized architectures while decentralized deployments gain share in modular facility designs.
- On-Site:Regulators installed at point-of-use within production facilities enable localized pressure control with minimal distribution piping. Gulf Coast refineries favor this topology for maintenance accessibility.
- Off-Site:Bulk gas supply stations with remote regulation reduce facility footprint and consolidate hazardous material handling.
- Centralized:Single regulation point feeding multiple process areas through distribution manifolds optimizes capital efficiency in greenfield chemical plants.
- Decentralized:Multiple independent regulation points provide redundancy and zone isolation for critical processes in pharmaceutical facilities.
Centralized installation retains capital deployment dominance; decentralized configurations are climbing fastest in modular construction projects.
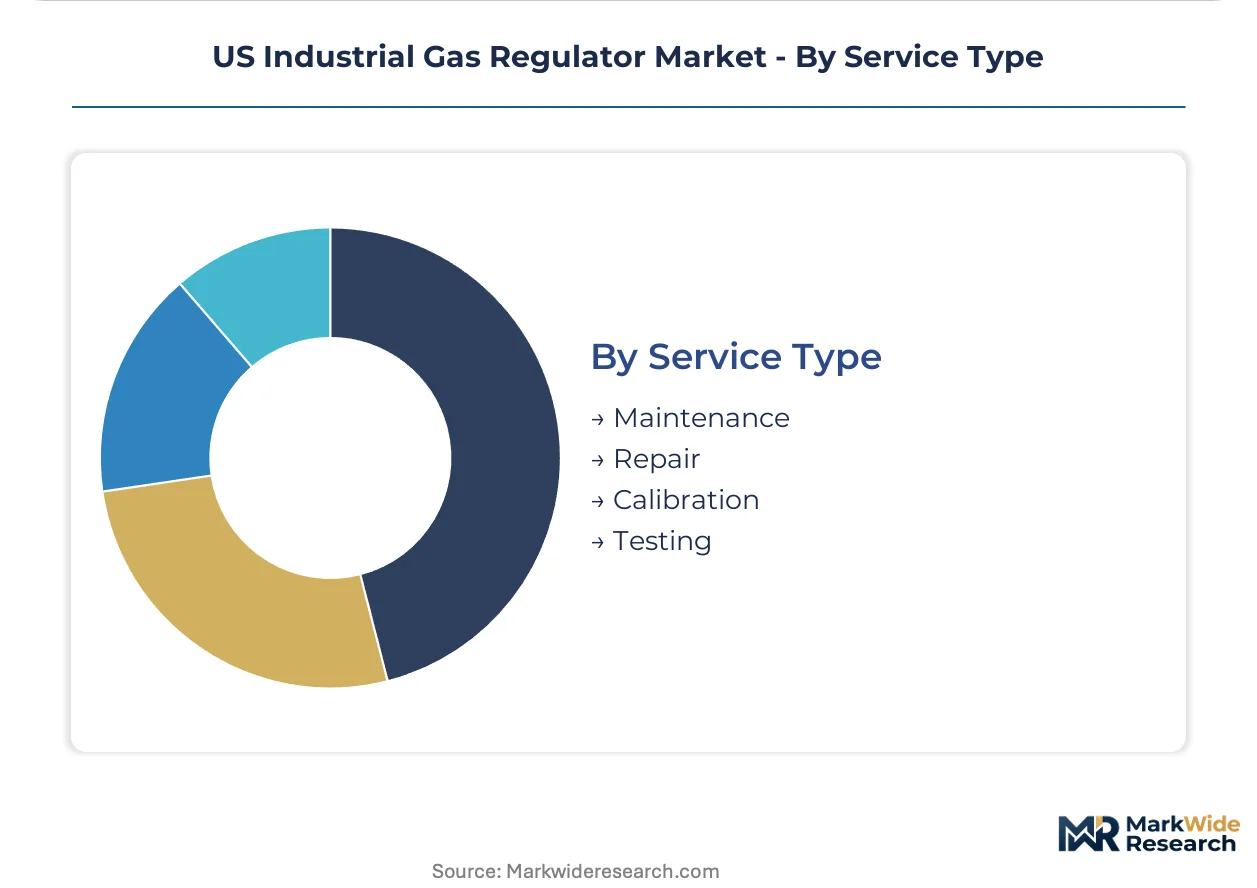
Service Type:
Customer type segmentation separates transactional parts replacement from integrated compliance management relationships.
- Maintenance:Scheduled inspection and preventive replacement programs ensure regulator performance integrity. OSHA-mandated intervals for pressure-relief devices sustain recurring demand.
- Repair:Emergency response and field refurbishment services address unplanned failures in continuous process operations.
- Calibration:Documented pressure accuracy verification against NIST-traceable standards supports regulatory audit requirements.
- Testing:Hydrostatic and pneumatic validation protocols confirm structural integrity for ASME code compliance.
Maintenance contracts anchor recurring revenue; calibration services are expanding most quickly as documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure funding and state-level clean energy incentives are redistributing industrial gas regulator procurement across US sub-regions, with hydrogen hub designations and petrochemical expansion cycles creating divergent demand profiles.
Texas Gulf Coast
Petrochemical complex expansions in Houston and Beaumont-Port Arthur sustain demand for high-integrity pressure control systems. OSHA Process Safety Management mandates documented inspection intervals for pressure-relief devices at covered chemical facilities. The Texas-Louisiana hydrogen hub designation is accelerating procurement of hydrogen-compatible regulator designs with advanced metallurgy specifications.
Louisiana Industrial Corridor
Refinery and chemical plant maintenance cycles sustain replacement demand for ASME-code certified safety relief valves. EPA Clean Air Act amendments targeting fugitive emissions compel facility operators to replace older regulator inventories with low-emission packing designs. Baton Rouge and Lake Charles processing complexes specify material traceability protocols for sour gas service applications.
California Manufacturing Belt
Semiconductor fabrication and biopharmaceutical manufacturing in the Bay Area and San Diego impose electropolished stainless steel requirements with full material certification. FDA validation requirements favor suppliers with comprehensive quality management systems. The state's hydrogen refueling network expansion is testing repurposed natural gas regulator designs for material compatibility limitations.
Midwest Industrial Heartland
Metal fabrication and automotive assembly operations in Michigan and Ohio deploy brass-bodied regulators for welding and cutting applications. Price-sensitive procurement favors standardized catalog products over custom-engineered systems. The region's hydrogen fuel cell vehicle pilot programs are creating nascent demand for specialized pressure control equipment.
Northeast Pharmaceutical Cluster
Aseptic manufacturing facilities in New Jersey and Massachusetts specify flow regulators as continuous processing displaces traditional batch methods. FDA batch record integrity requirements drive consolidation toward suppliers with integrated calibration and documentation services. The region's university research laboratories sustain demand for high-purity vacuum regulators in analytical instrumentation applications.
US Industrial Gas Regulator Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service providers capable of delivering hardware, calibration, and compliance documentation through single-source contracts. Three strategic archetypes dominate: diversified industrial conglomerates with distribution network scale, specialized high-purity fabricators with material traceability capabilities, and regional equipment lessors with managed service contract expertise. Competitive moves center on backward integration into sensor-embedded digital architectures and geographic expansion through hub-and-spoke service depot networks.
Among diversified industrial conglomerates, Emerson Electric Co. and Parker Hannifin Corporation exemplify archetypes pursuing integrated digital monitoring capabilities. Swagelok Company occupies a position within the specialized fabrication tier where material traceability commands sustained pricing power. These three entities anchor the competitive structure, with Emerson and Parker representing scale-driven service integration strategies while Swagelok exemplifies premium positioning through purity-grade specialization.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Airgas Inc. |
| Parker Hannifin Corporation |
| Swagelok Company |
| The Harris Products Group |
| Air Liquide |
| Linde Group |
| GCE Group |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
Chinese stainless steel and brass forging capacity anchors upstream supply for US industrial gas regulator fabricators, concentrating margin capture with domestic distributors and service integrators who bundle calibration and compliance documentation. EPA emissions mandates and OSHA inspection requirements compel facility operators toward premium-certified systems, widening spreads between commodity brass regulators and ASME-code safety relief valves.
Pricing Analysis
Certification grade creates the primary spread between economy brass catalog products and premium electropolished stainless steel systems with full material traceability. Three-tier pricing structure separates FDA-validated pharmaceutical-grade regulators from standard industrial brass units and commodity welding applications. Pricing pressure stems from raw material volatility in nickel and copper alloys, compressing margins for mid-tier fabricators serving price-sensitive Midwest metal fabrication shops. Pharmaceutical and semiconductor end-users exhibit lowest price sensitivity due to batch record integrity requirements, while general manufacturing procurement favors standardized catalog products.
Supply Chain Analysis
Extended payment terms from Gulf Coast petrochemical buyers strain working capital for smaller fabricators, favoring diversified industrial conglomerates with captive financing facilities. Component sourcing draws from Chinese brass forgings, German precision springs, and domestic stainless steel bar stock. Single-source vulnerability concentrates in specialized elastomer seals rated for hydrogen service. Distribution runs through authorized distributor networks with regional calibration depots, supplemented by direct OEM relationships for large chemical plant procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service substitution threatens traditional hardware margins, requiring incumbents to defend recurring revenue relationships against leasing entrants and digital monitoring platforms.
For Market Incumbents: Harden aftermarket service moats by embedding IoT pressure sensors in regulator architectures, converting episodic repair calls into continuous monitoring subscriptions. Backward integration into hydrogen-compatible sealing technologies defends position against material science specialists capturing DOE hub procurement. Consolidate calibration and documentation capabilities through hub-and-spoke depot networks across the Texas-Louisiana corridor. For New Entrants and Emerging Players: Establish a beachhead in mid-sized pharmaceutical processors previously priced out of premium certified systems through leased equipment with bundled compliance services. Target decentralized installation topologies in modular biopharmaceutical facilities where zone isolation requirements favor independent regulation points. Lead with integrated digital monitoring as a service differentiator against legacy mechanical-only competitors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional equipment lessors with managed service contract expertise and Gulf Coast customer concentration. Long-term viability hinges on hydrogen infrastructure deployment pace and regulatory enforcement intensity for fugitive emissions compliance. Watch EPA enforcement actions against petrochemical complexes as inflection indicator for compliance-driven replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Architecture | Captures predictive maintenance revenue streams from Gulf Coast hydrogen blending facilities. |
| Hydrogen-Compatible Sealing Technology Development | Positions fabricators for DOE-funded Texas-Louisiana hub procurement cycles. |
| Equipment-as-a-Service Model Launch | Lowers capital barriers for mid-sized New Jersey and Massachusetts pharmaceutical processors. |
| Regional Calibration Depot Expansion | Consolidates vendor relationships around single-source compliance documentation capabilities. |
| ASME Code Certification Acceleration | Shortens product launch timelines for safety relief valves in hazardous petrochemical service. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plant engineers, maintenance directors at Gulf Coast refineries, procurement leads at pharmaceutical manufacturers, and aftermarket service heads at authorized distributors. Secondary validation drew from EPA enforcement databases, OSHA Process Safety Management audit records, SEC 10-K filings of diversified industrial conglomerates, and DOT PHMSA pipeline safety incident reports. Bottom-up unit demand estimates triangulated against top-down industry value projections.
Calibration against historical replacement cycles and regulatory enforcement intensity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, installation topology, and service contract structure. CAGRs derived from regression analysis of capital expenditure patterns at petrochemical complexes and pharmaceutical facility expansion timelines. Hydrogen infrastructure deployment assumptions and EPA emissions rulemaking pace served as key industry-specific forecast inputs.
Sensitivities concentrate around stainless steel price volatility, hydrogen code adoption timing, and OSHA inspection enforcement intensity. Forecasts reflect documented assumptions regarding regional petrochemical expansion cycles and continuous processing adoption in pharmaceutical manufacturing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Industrial Nitrogen Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
3D Printing Gases Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Argon Gas Market
Industrial Gases
Xenon Gas Market
Industrial Gases
Global Industrial Denox Systems and Services Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Krypton-85 Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
Global Nitrogen Market