
 Trimethylolpropane (TMP) Market | 2026-2036
Trimethylolpropane (TMP) Market Size, Share, and Industry Trends Forecast 2026-2036
Trimethylolpropane (TMP) Market Outlook
The gap between pharmaceutical-grade and commodity-grade Trimethylolpropane is repositioning procurement strategies across buyer segments. OQ Chemicals leverages its European base to sustain REACH-certified supply chains for coatings customers. Perstorp anchors its competitiveness on backward integration into formaldehyde and n-butyraldehyde feedstocks. Wanhua Chemical Group dominates Asia-Pacific volume through integrated propylene oxide derivatives complexes.
Trimethylolpropane is a trifunctional alcohol with the molecular formula C6H14O3, synthesized via condensation of n-butyraldehyde with formaldehyde followed by catalytic hydrogenation, yielding a white crystalline solid with a melting point near 58°C and three primary hydroxyl groups that enable crosslinking in polymer systems. Its primary industrial purpose centers on polyurethane and alkyd resin modification, where the triol structure imparts hydrolytic stability, weather resistance, and controlled flexibility to cured films. Industrial-grade material leads volume consumption across polyester resins applications, where margin pools remain deepest due to long-term supply contracts with automotive OEM coatings divisions. Pharmaceutical-grade output registers the fastest structural expansion, driven by excipient qualification demands and tightening pharmacopeial monographs in regulated markets.
EPA oversight of formaldehyde emissions and REACH registration requirements for aldehyde-based intermediates are elevating compliance costs for non-integrated producers. China's SAMR enforces GB standards on industrial chemical purity that now approach pharmaceutical-grade thresholds for certain coating export categories. ISO 9001 and Responsible Care certifications function as de facto market access filters for European and North American procurement teams. Stakeholders must monitor feedstock aldehyde cost volatility and evolving biocidal product regulations that could reclassify TMP-containing formulations.
Market Dynamics
REACH-certified supply chains and EPA formaldehyde emission controls are restructuring competitive access for non-integrated producers, while China's SAMR purity mandates compress the gap between pharmaceutical and industrial grades.
Growth Catalysts
- Automotive refinish coatings:Low-VOC polyurethane formulations in vehicle repair networks absorb rising TMP volumes as OEMs phase out solvent-heavy systems.
- REACH registration:ECHA compliance requirements for aldehyde-based intermediates lock in European supply relationships for certified producers.
- Propylene oxide integration:Backward integration into PO derivatives complexes secures feedstock cost advantages for Asia-Pacific volume leaders.
Market Restraints
- n-Butyraldehyde cost volatility:Crude-linked feedstock pricing squeezes margin stability for non-captive producers without long-term supply agreements.
- Substitution pressure from pentaerythritol:Alternative polyols compete in alkyd resin applications where hydrolytic stability requirements are less stringent.
- REACH compliance friction:Registration costs and data requirements create barriers for commodity-grade entrants seeking European market access.
Strategic Opportunities
- Pharmaceutical-grade excipient qualification:USP and EP monograph expansion opens premium positioning for purified TMP in drug delivery systems.
- Biocidal product reclassification:Evolving BPR frameworks in Europe may recategorize certain TMP-containing formulations, creating reformulation service demand.
- Digital procurement platforms:Chemical marketplaces and direct manufacturer portals are compressing distributor layers in specialty polyol sourcing.
Industry Challenges
- Pharmacopeial certification timelines:Excipient qualification protocols require 18-36 month validation cycles that delay revenue recognition.
- Hydrogenation catalyst supply security:Specialized noble metal catalyst procurement faces lead time volatility from geopolitical concentration.
- Legacy alkyd resin customer integration:Long-term automotive OEM contracts resist rapid specification changes despite regulatory pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trimethylolpropane (TMP) Market |
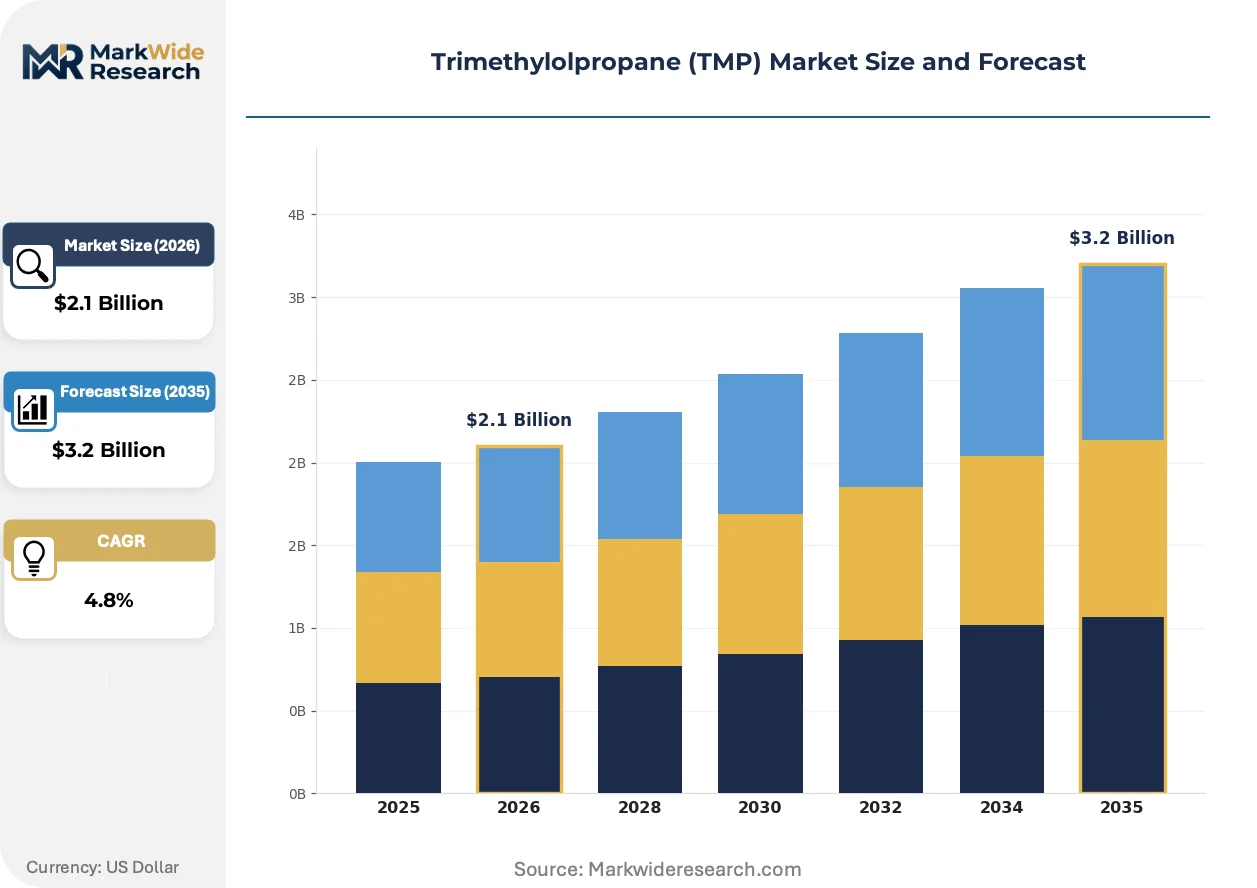
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Basic Grade, Industrial Grade, Pharmaceutical Grade, Food Grade End User: Chemical Industry, Coatings, Plastics, Adhesives Distribution Channel: Direct Sales, Wholesalers, Online Retailers, Distributors Application: Polyester Resins, Plasticizers, Lubricants, Synthetic Fibers |
| Companies Covered | OQ Chemicals, Baichuan High-tech New Materials, LANXESS, Mitsubishi Gas Chemical Company, Hubei Yihua Group, Perstorp, Wanhua Chemical Group, Chang Chun Group, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trimethylolpropane (TMP) Market Strategic Shifts
Continuous hydrogenation reactor designs and bio-based formaldehyde pathways are disrupting conventional batch production economics while regulatory purity thresholds climb across multiple jurisdictions.
Bio-based formaldehyde derived from biomass gasification is expanding into pilot-scale TMP production as European chemical clusters test carbon-intensity reduction pathways. Coatings formulators in Germany and the Netherlands are qualifying these outputs for automotive refinish segments where Scope 3 reporting pressures intensify. The technology is expanding into commercial viability as carbon border adjustment mechanisms approach implementation.
EPA formaldehyde emission standards under the Toxic Substances Control Act are tightening residual aldehyde specifications in imported resin intermediates. Industrial-grade TMP shipments to US coatings manufacturers now require third-party certification of hydrogenation completeness. The regulation most impacts Asian exporters serving North American automotive refinish supply chains, forcing additional purification investments.
Direct procurement relationships between alkyd resin compounders and integrated TMP producers are displacing traditional distributor intermediaries in volume segments. Long-term offtake agreements with fixed purity bands now govern 60-70% of automotive OEM coating supply. This concentration is most visible in China's Yangtze River Delta cluster where domestic resin production and TMP manufacturing co-locate.
Trimethylolpropane (TMP) Market Segmentation
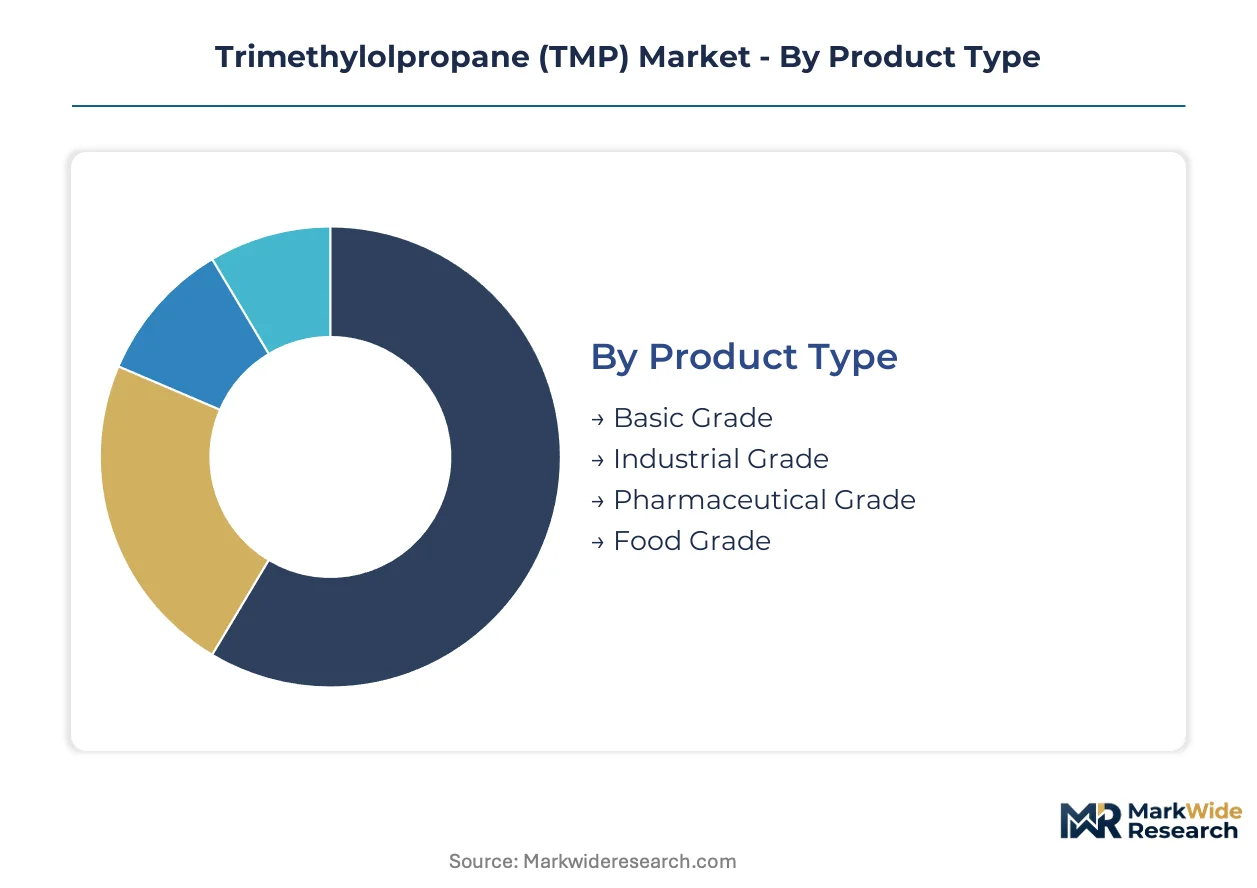
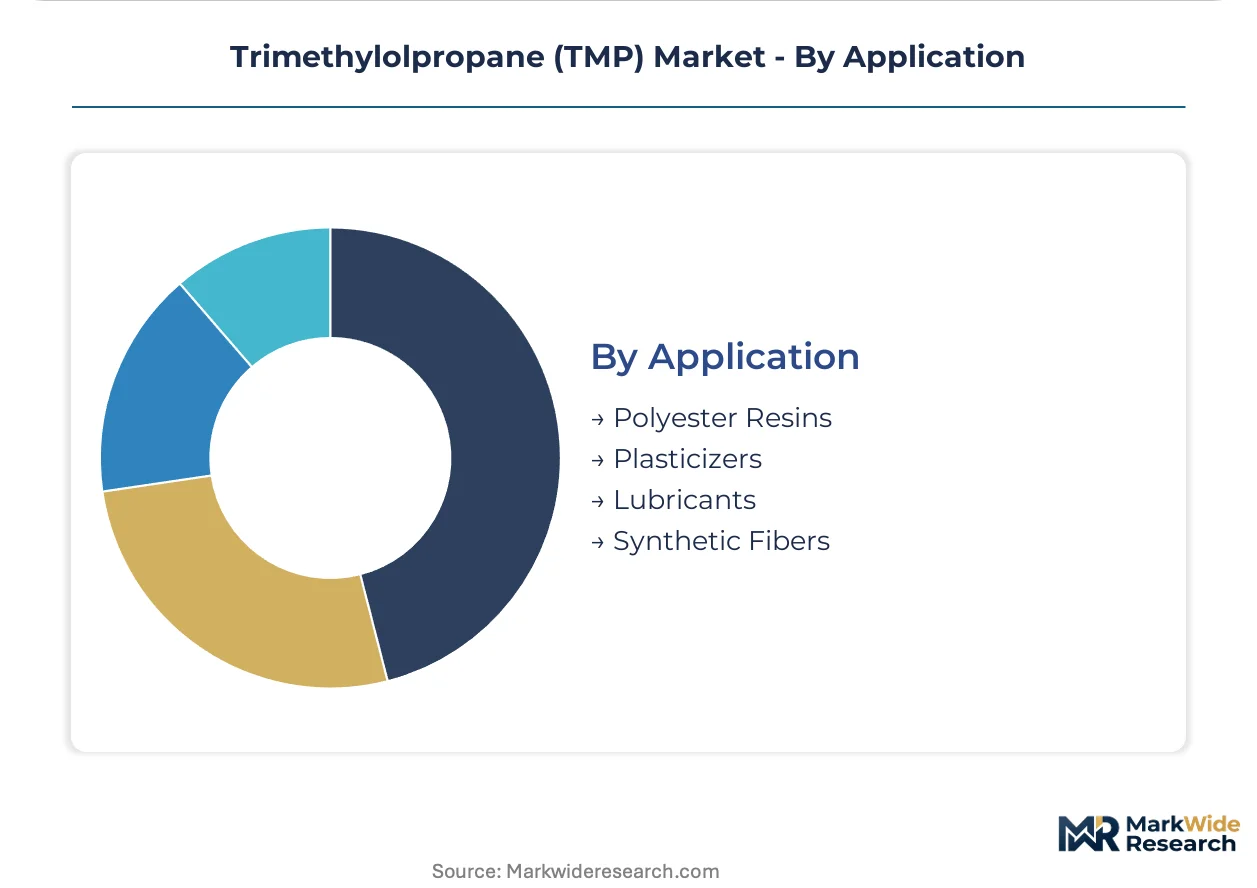
Grade purity specifications determine pricing architecture and regulatory pathway for Trimethylolpropane procurement. End-use concentration in automotive coatings and alkyd resin production shapes volume allocation across producer portfolios.
Product Type:
Purity thresholds separate commodity supply from certified pharmaceutical and food-grade streams, with hydrogenation completeness and residual aldehyde content defining each tier's market access.
- Basic Grade:Contains higher residual formaldehyde and n-butyraldehyde traces, suitable for general industrial applications where hydrolytic stability requirements remain moderate. Demand concentrates in China's domestic alkyd resin sector for construction coatings, constrained by tightening GB standards on export-bound material.
- Industrial Grade:Undergoes controlled hydrogenation to reduce aldehyde impurities below 500 ppm, meeting ISO 9001 specifications for polyurethane crosslinkers. Automotive OEM coatings divisions in Germany and the United States absorb rising volumes as low-VOC formulation mandates tighten.
- Pharmaceutical Grade:Purified to meet USP and EP monograph standards for excipient use in drug delivery systems.
- Food Grade:Complies with FDA and EFSA safety thresholds for indirect food contact applications in packaging coatings.
Industrial Grade leads on scale; Pharmaceutical Grade leads on momentum.
End User:
Customer concentration follows the downstream value chain for modified polyols, with specification power residing at the formulation stage.
- Chemical Industry:Intermediate producers of specialty polyols and alkyd resin modifiers drive bulk procurement through annual offtake agreements.
- Coatings:Polyurethane and alkyd formulators in automotive refinish networks command premium-grade supply, with REACH certification filtering European vendor pools.
- Plastics:Polyester resin compounders leverage TMP for hydrolytic stability in engineering thermoplastics, absorbing industrial-grade volumes through direct manufacturer relationships.
- Adhesives:Reactive hot-melt and structural adhesive producers utilize TMP crosslinkers for moisture-cure systems in construction and electronics assembly.
Chemical Industry leads on scale; Coatings leads on momentum.
Distribution Channel:
Channel selection correlates with volume scale and certification complexity, with certified grades bypassing traditional intermediaries.
- Direct Sales:Govern 60-70% of automotive OEM coating supply through long-term offtake agreements with fixed purity bands.
- Wholesalers:Handle commodity-grade material for small and mid-size alkyd resin producers without captive TMP sourcing.
- Online Retailers:Emerging platforms serve specialty chemical procurement for research quantities and rapid qualification samples.
- Distributors:Maintain regional inventory positions for just-in-time delivery to coatings compounders in fragmented European and North American markets.
Direct Sales leads on scale; Online Retailers leads on momentum.
Application:
Functional performance requirements in each end-use dictate grade selection and pricing realization.
- Polyester Resins:Saturated and unsaturated polyester modification for powder coatings and gel coats absorbs the deepest volume pools, with automotive OEM contracts locking in multi-year supply.
- Plasticizers:TMP esters serve as specialty plasticizers for PVC and cellulosic applications where low volatility and migration resistance command premium positioning.
- Lubricants:Synthetic ester base stocks for aviation and industrial lubricants leverage TMP's thermal stability and biodegradability profile.
- Synthetic Fibers:Polyester fiber modification for industrial textiles and tire cord applications utilizes industrial-grade material through integrated polymer producer supply chains.
Polyester Resins leads on scale; Lubricants leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs deeper TMP volumes than Germany despite both markets prioritizing low-VOC polyurethane formulations, while the United States and Japan concentrate demand in automotive refinish and pharmaceutical-grade excipient segments respectively.
China
Domestic alkyd resin production and automotive refinish sectors drive consumption across the Yangtze River Delta cluster. SAMR enforces GB standards on industrial chemical purity that approach pharmaceutical-grade thresholds for coating export categories. Wanhua Chemical Group anchors supply through integrated propylene oxide derivatives complexes in Ningbo and Yantai.
Germany
Automotive OEM coatings divisions command premium-grade supply for polyurethane crosslinkers in vehicle manufacturing and repair networks. ECHA REACH registration requirements for aldehyde-based intermediates lock in certified European supply relationships. The Cologne-Düsseldorf chemical corridor concentrates hydrogenation capacity serving coatings formulators across the Rhine-Ruhr industrial region.
United States
Low-VOC polyurethane formulation mandates in automotive refinish absorb rising industrial-grade volumes as solvent-heavy systems phase out. EPA formaldehyde emission standards under the Toxic Substances Control Act tighten residual aldehyde specifications in imported resin intermediates. Third-party certification requirements for hydrogenation completeness now govern shipments to coatings manufacturers in Michigan and Ohio.
Japan
Pharmaceutical-grade excipient qualification drives structural expansion for USP and EP monograph-compliant material in drug delivery systems. METI oversees chemical purity standards that align with international pharmacopeial protocols. Osaka-based resin compounders and pharmaceutical manufacturers concentrate procurement through direct manufacturer relationships bypassing traditional distributors.
South Korea
Polyester resin modification for powder coatings and industrial textiles absorbs industrial-grade volumes through integrated polymer producer supply chains. MFDS pharmaceutical regulations elevate purity benchmarks for excipient-grade material entering domestic and export markets. The Ulsan petrochemical complex anchors downstream TMP consumption serving automotive and electronics coatings sectors.
Trimethylolpropane (TMP) Market Competitive Environment
Top-tier vendors anchor integrated petrochemical and specialty chemical conglomerates, while mid-tier regional specialists compete on feedstock proximity and certification agility. The vendor base stratifies across three tiers: multinational chemical majors with backward integration into formaldehyde and n-butyraldehyde feedstocks, Asia-Pacific volume leaders operating integrated propylene oxide derivatives complexes, and regional specialists serving pharmaceutical-grade qualification demands. Strategic moves concentrate on capacity expansion in high-purity grades and geographic diversification to mitigate REACH compliance friction.
Within the multinational tier, BASF and LANXESS represent European-anchored REACH-certified supply chains, while Wanhua Chemical Group exemplifies Asia-Pacific scale through integrated PO derivatives positioning. Perstorp occupies a specialist position emphasizing feedstock integration. These named entities serve as archetype anchors for understanding competitive segmentation rather than definitive market share claims.
| Leading Market Players |
|---|
| OQ Chemicals |
| Baichuan High-tech New Materials |
| LANXESS |
| Mitsubishi Gas Chemical Company |
| Hubei Yihua Group |
| Perstorp |
| Wanhua Chemical Group |
| Chang Chun Group |
| BASF |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Germany and the Netherlands anchor premium-grade supply, translating certification investments into pricing discipline that resists commodity erosion. Their captive hydrogenation capacity and long-term automotive OEM contracts create margin buffers that non-integrated Chinese exporters cannot replicate under tightening EPA residual aldehyde specifications.
Pricing Analysis
Bundled certification-and-logistics services command 15-25% premiums over unbundled commodity transactions, particularly for REACH-registered material serving European coatings formulators. Three-tier pricing structure across pharmaceutical, industrial, and basic grades separates buyers by qualification burden and volume scale. Cost compression in basic-grade segments is intensifying because China's SAMR purity mandates now approach industrial-grade thresholds for export-bound material. Small and mid-size alkyd resin producers without captive sourcing exhibit the highest price sensitivity, while automotive OEM coatings divisions prioritize specification security over unit cost.
Supply Chain Analysis
Freight cost differentials between bulk liquid tankers and containerized solid shipments favor integrated producers co-located with downstream resin compounders. Supply concentrates in China, Germany, and the United States, with the Yangtze River Delta and Cologne-Düsseldorf corridor hosting the deepest hydrogenation capacity. Feedstock dependencies rest on n-butyraldehyde from propylene oxide derivatives complexes and formaldehyde from methanol oxidation units. Single-source vulnerability in noble metal hydrogenation catalysts—particularly palladium and ruthenium—creates procurement risk for non-integrated producers. Distribution runs through direct manufacturer relationships for 60-70% of automotive OEM volume, with regional distributors serving fragmented European and North American compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trimethylolpropane has matured into a late-cycle quality story where pharmaceutical-grade excipient qualification and REACH-certified supply chains capture expanding margin pools. Specification power has shifted decisively toward coatings formulators facing low-VOC mandates and automotive OEMs demanding hydrolytic stability guarantees.
For Market Incumbents: Cement backward integration into n-butyraldehyde and formaldehyde feedstocks to neutralize crude-linked cost volatility and lock in margin stability. Deepen hydrogenation capacity in the Cologne-Düsseldorf corridor to serve REACH-registered demand from German automotive OEM coatings divisions. Prioritize pharmacopeial certification investments to capture excipient-grade premiums before qualification timelines extend further.
For New Entrants and Emerging Players: Bio-based formaldehyde pathways from biomass gasification offer a technology-first wedge into European automotive refinish segments where Scope 3 reporting pressures intensify. Target South Korean and Japanese pharmaceutical-grade demand where METI and MFDS regulations elevate purity benchmarks above industrial-grade availability. Pursue direct procurement platform partnerships to bypass entrenched distributor layers in specialty polyol sourcing.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with captive hydrogenation capacity and incomplete pharmacopeial certification—assets that strategic buyers can complete. Five-to-ten-year viability hinges on feedstock integration depth and regulatory certification agility rather than scale alone. Watch for ECHA biocidal product reclassification decisions as an inflection signal that could force reformulation service demand and reshape competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive n-butyraldehyde supply from propylene oxide complexes neutralizes crude-linked margin volatility for Wanhua and Perstorp. |
| Pharmaceutical-Grade Capacity Expansion | USP and EP monograph qualification opens premium positioning in Japanese drug delivery systems and South Korean export markets. |
| Long-term Supply Agreement | Fixed-purity offtake contracts with German automotive OEM coatings divisions lock in 60-70% of volume and resist spot-price erosion. |
| Green Manufacturing Transition | Bio-based formaldehyde from biomass gasification qualifies for carbon border adjustment mechanisms in European automotive refinish. |
| Joint Venture | Co-location with alkyd resin compounders in China's Yangtze River Delta cluster compresses logistics costs and accelerates specification response. |
Study Parameters
Coverage spans China, Germany, the United States, Japan, and South Korea, with primary inputs from each market's coatings formulators and resin compounders. The analysis combines structured interviews with plant managers at integrated TMP producers, procurement leads at automotive OEM coatings divisions, technical R&D directors at alkyd resin specialists, and distribution channel partners in fragmented European markets. Secondary validation draws from customs and trade data, SEC and European stock exchange filings, ACC and Cefic industry reports, and ECHA REACH registration databases. Bottom-up volume estimates from grade-specific consumption patterns triangulate against top-down market sizing from feedstock capacity and downstream demand modeling.
Rate-of-change decomposition separates volume growth from pricing realization across the projection horizon, with segment-level CAGRs derived from regression analysis against automotive production indices, coatings formulation shift rates, and pharmacopeial qualification timelines. The forecast framework models grade tier, end-use industry, and regional production hub as primary segmentation dimensions, with hydrogenation capacity utilization and noble metal catalyst supply security as industry-specific sensitivity inputs.
The model holds under stable formaldehyde emission regulatory trajectories and continuous hydrogenation technology adoption; deviation in ECHA biocidal reclassification timing or palladium supply disruption would shift grade-specific growth rates. Forecasts reflect documented assumptions about feedstock cost pass-through elasticity and OEM specification stickiness. Stakeholders should weight assumptions against their own operating context and captive integration depth.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
HFO (Hydrofluoro-Olefin) Refrigerants Market
Industrial Chemicals
Nitrous Oxide Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Europe Biocides Market
Industrial Chemicals
Di (2-Ethylhexyl) Phthalate Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Process Fluid Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Asia Pacific Rotomoulding Powder Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Synthetic Gypsum Market
Industrial Chemicals
Global Metalworking Fluids Market