
 Quenching Fluids and Salts Market | 2026-2036
Quenching Fluids and Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Quenching Fluids and Salts Market Analysis
Asset-light leasing models for quenchant supply systems is fragmenting competitive dynamics across the heat treatment sector. Quaker Houghton leverages its fluid management service contracts to sustain long-term plant-level relationships. FUCHS Petrolub SE anchors European demand through specialized polymer-based formulations for automotive tier suppliers. Petrofer competes on regional formulation flexibility, while Chevron Corporation extends its base oil infrastructure into quenchant blending networks.
Quenching fluids and salts comprise engineered heat transfer media—typically mineral oils, aqueous polymers, or inorganic salt mixtures formulated with controlled cooling rates between 20°C and 100°C—designed to control metallurgical phase transformations during hardening of ferrous alloys. Their primary industrial purpose centers on achieving specified hardness profiles and minimizing distortion in precision-engineered components. Oil-based formulations still occupy the largest margin pool across mature aerospace supply chains, while polymer-based alternatives lead growth trajectories as metal fabrication shops confront wastewater treatment cost pressures. Salt mixtures dominate niche applications in alloy production where ultra-rapid cooling rates prove essential for specialty steel grades.
EPA enforcement of spent oil disposal rules under RCRA, alongside ECHA REACH restrictions on aromatic content in metalworking fluids, shapes product reformulation priorities across North American and European supply chains. China's MEE effluent standards for heat treatment operations further constrain salt mixture discharge practices, pushing adoption of closed-loop water-soluble systems. Stakeholders must weigh regulatory compliance timelines against capital requirements for quenchant recycling infrastructure when evaluating facility upgrade paths.
Market Dynamics
Polymer-based quenchants are displacing mineral oil formulations as heat treatment shops confront effluent discharge limits and closed-loop water system mandates across industrial jurisdictions.
Growth Catalysts
- ECHA REACH aromatic restrictions:German aerospace suppliers accelerate polymer quenchant qualification to eliminate hazardous substance reporting obligations in component finishing operations.
- Automotive forging scale-up:China's eastern industrial corridor expands salt mixture consumption for precision alloy hardening in crankshaft and camshaft production lines.
- Closed-loop water systems:Metal fabrication facilities adopt aqueous polymer formulations to eliminate spent oil disposal costs and achieve zero liquid discharge targets.
Market Restraints
- Base oil supply concentration:Mineral oil quenchant blenders depend on Group II/III base stock availability concentrated in Gulf Coast refining complexes, exposing margin pressure during feedstock allocation periods.
- Salt mixture handling infrastructure:Molten salt bath operations require specialized furnace construction and corrosion-resistant materials that constrain shop-floor retrofit economics.
- Aqueous polymer technical ceiling:Water-soluble formulations fail to achieve martensitic transformation rates required for high-carbon tool steel grades, preserving oil demand in cutting tool manufacturing.
Strategic Opportunities
- India heat treatment modernization:BIS certification requirements for automotive component suppliers create specification upgrade pathways for polymer quenchant penetration in Pune and Chennai manufacturing clusters.
- Additive manufacturing post-processing:Metal 3D printed part hardening requires controlled cooling rate fluids formulated for thin-wall geometries and residual stress management.
- Carbon border adjustment mechanisms:EU CBAM scope expansion incentivizes European heat treatment outsourcing to Turkish and North African facilities with lower-emission quenchant recycling infrastructure.
Industry Challenges
- Quenchant analyst skill scarcity:Formulation chemistry expertise for polymer bath concentration management and cooling curve interpretation remains concentrated among retiring technical specialists.
- Multi-standard certification timelines:Aerospace suppliers must synchronize AMS 2750 pyrometry compliance with Nadcap heat treatment accreditation and customer-specific fluid approval processes.
- Legacy oil system stranded assets:Shops with recently upgraded mineral oil infrastructure face write-down pressure when converting to aqueous systems requiring tank modifications and separator installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quenching Fluids and Salts Market |
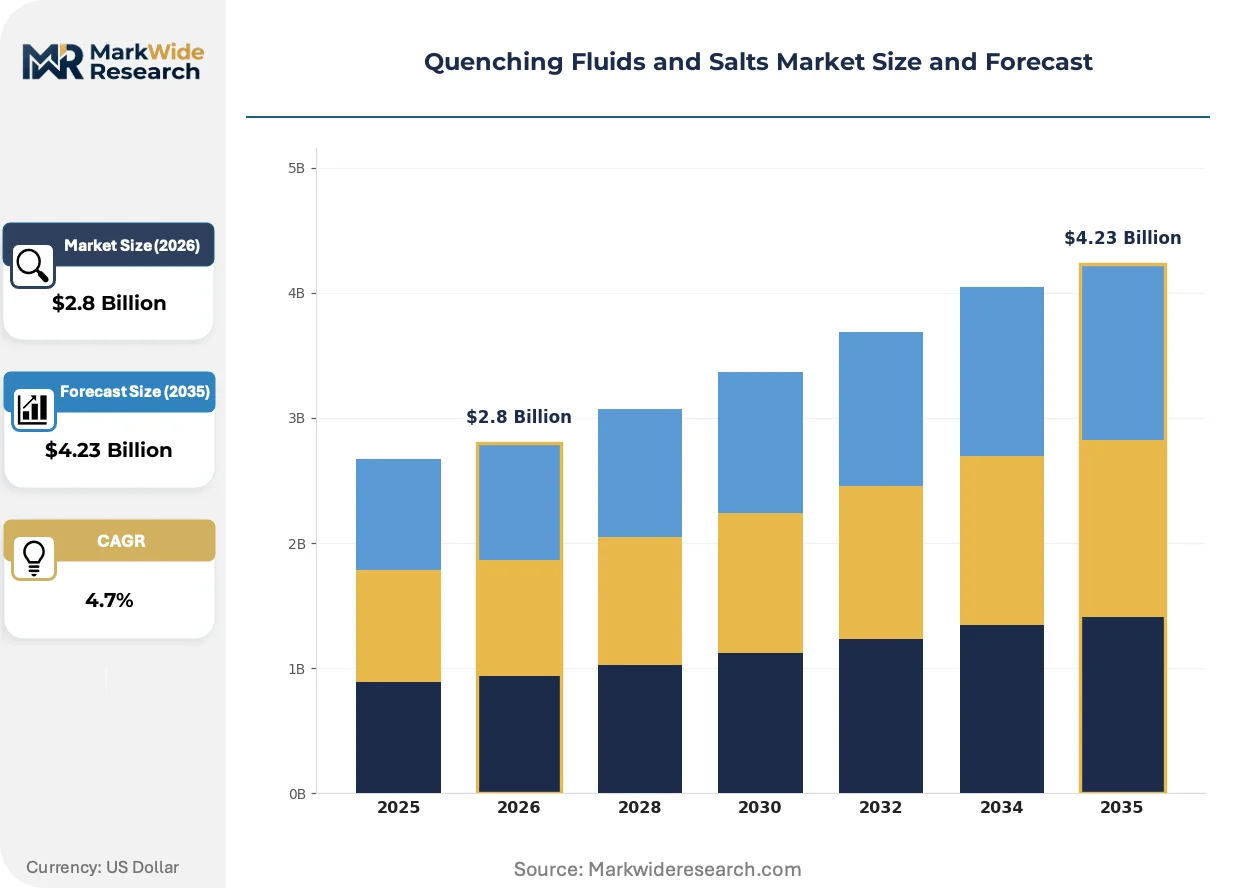
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Water-Based, Oil-Based, Salt Mixtures Application: Heat Treatment, Metal Hardening, Surface Finishing, Alloy Production Industry Vertical: Aerospace, Automotive, Metal Fabrication, Manufacturing Formulation: Water Soluble, Non-Aqueous, Concentrated, Pre-Mixed |
| Companies Covered | Chevron Corporation, Petrofer, Quaker Houghton, CONDAT, Chemtool Incorporated, FUCHS Petrolub SE, Exxon Mobil Corporation, Croda International Plc, TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quenching Fluids and Salts Market Emerging Trajectories
Formulation science is converging with digital process control to enable real-time quenching parameter adjustment, compressing qualification cycles and reducing distortion rejection rates in precision hardening operations.
Advanced polymer quenchants incorporating inverse solubility polymers are migrating from laboratory qualification to production floor deployment in European automotive transmission manufacturing. Tier suppliers in Stuttgart and Wolfsburg adopt these fluids to achieve reproducible martensite formation in thin-walled gear components. The technology is migrating from specialty aerospace applications to high-volume powertrain operations, compressing the premium pricing window for conventional accelerated oil formulations.
EPA RCRA enforcement on spent oil disposal is tightening manifest documentation and cradle-to-grave tracking requirements across US heat treatment networks. Metal finishing shops in Michigan and Ohio face inspection priority status for hazardous waste generator violations. Small and mid-size captive heat treatment departments absorb disproportionate compliance burden, accelerating third-party toll hardening consolidation.
Fluid management service contracts are displacing conventional bulk purchase arrangements as the dominant commercial structure in mature manufacturing regions. Quenchant suppliers assume inventory risk and bath monitoring responsibility while capturing multi-year revenue commitments. This model concentrates in German and Japanese automotive supply chains where OEMs demand supplier accountability for process parameter documentation.
Quenching Fluids and Salts Market Segmentation
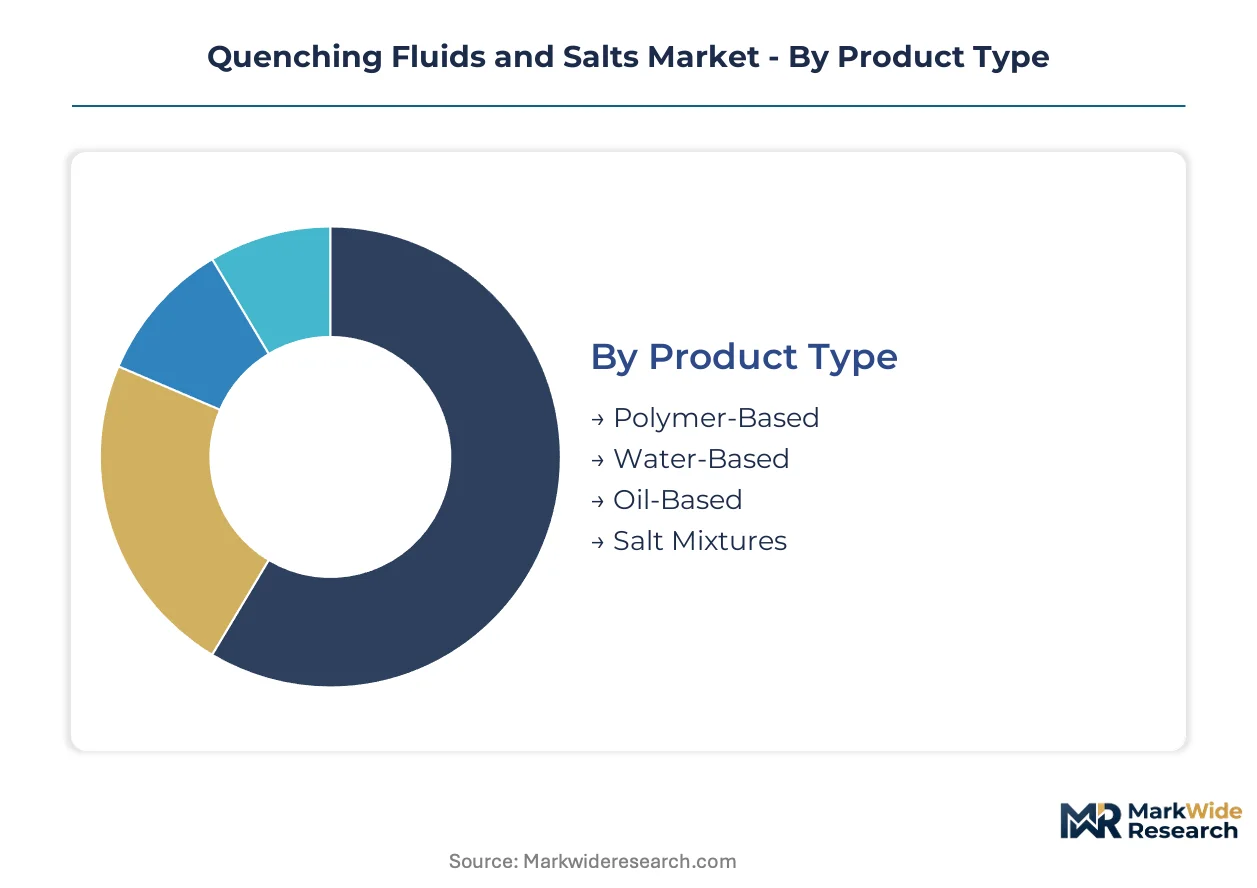
Quenching fluid selection hinges on cooling rate precision, regulatory compliance burdens, and metallurgical outcome requirements. Each segmentation axis reveals distinct procurement patterns across heat treatment operations.
Product Type:
Mature mineral oil formulations coexist with emerging aqueous alternatives as environmental regulations tighten discharge standards.
- Polymer-Based:Engineered aqueous solutions utilizing inverse solubility polymers to achieve controlled cooling curves. German aerospace suppliers in Stuttgart and Hamburg adopt these formulations to satisfy ECHA REACH aromatic restrictions while maintaining martensitic transformation precision in landing gear components.
- Oil-Based:Mineral oil formulations derived from Group II/III base stocks delivering maximum cooling rate control for high-carbon tool steels. Gulf Coast refining concentration creates feedstock allocation vulnerability during peak demand periods for automotive crankshaft hardening operations.
- Water-Based:Plain water or additive-enhanced aqueous systems for ultra-rapid quenching in specific alloy grades.
- Salt Mixtures:Inorganic salt baths providing extreme cooling rates for specialty steel production in China's eastern industrial corridor.
Oil-based formulations handle the majority of throughput; polymer-based quenchants are gaining share fastest as closed-loop water mandates expand.
Application:
Cost tier differentiation separates high-specification aerospace processes from volume-driven automotive operations.
- Heat Treatment:Controlled atmosphere furnace operations requiring precise quenchant temperature management and bath concentration monitoring. Nadcap-accredited facilities in Toulouse and Wichita prioritize polymer systems for pyrometry compliance documentation.
- Metal Hardening:Surface and through-hardening of ferrous components to specified Rockwell hardness profiles. Automotive forging lines in China's Jiangsu province scale salt mixture consumption for camshaft and crankshaft production.
- Surface Finishing:Final-stage quenching operations determining component cosmetic and functional surface properties.
- Alloy Production:Primary metallurgical processing of specialty steel grades requiring ultra-rapid cooling rates.
Heat treatment absorbs the largest volume allocation; metal hardening shows the steepest expansion trajectory as automotive lightweighting intensifies.
Industry Vertical:
Customer type fragmentation creates divergent specification requirements across OEM-direct and tier-supplier channels.
- Aerospace:Nadcap-accredited heat treatment operations demanding AMS 2750 pyrometry compliance and customer-specific fluid approvals. OEMs in Seattle and Toulouse mandate supplier accountability for process parameter documentation.
- Automotive:High-volume powertrain and transmission component hardening with intense cost pressure and zero-defect quality protocols. Stuttgart and Wolfsburg tier suppliers adopt inverse solubility polymers for thin-walled gear reproducibility.
- Metal Fabrication:Job-shop and captive heat treatment operations serving diversified industrial end-markets.
- Manufacturing:General industrial machinery and equipment component hardening with variable specification stringency.
Automotive represents the largest volume sink; aerospace commands the highest specification premiums and longest qualification cycles.
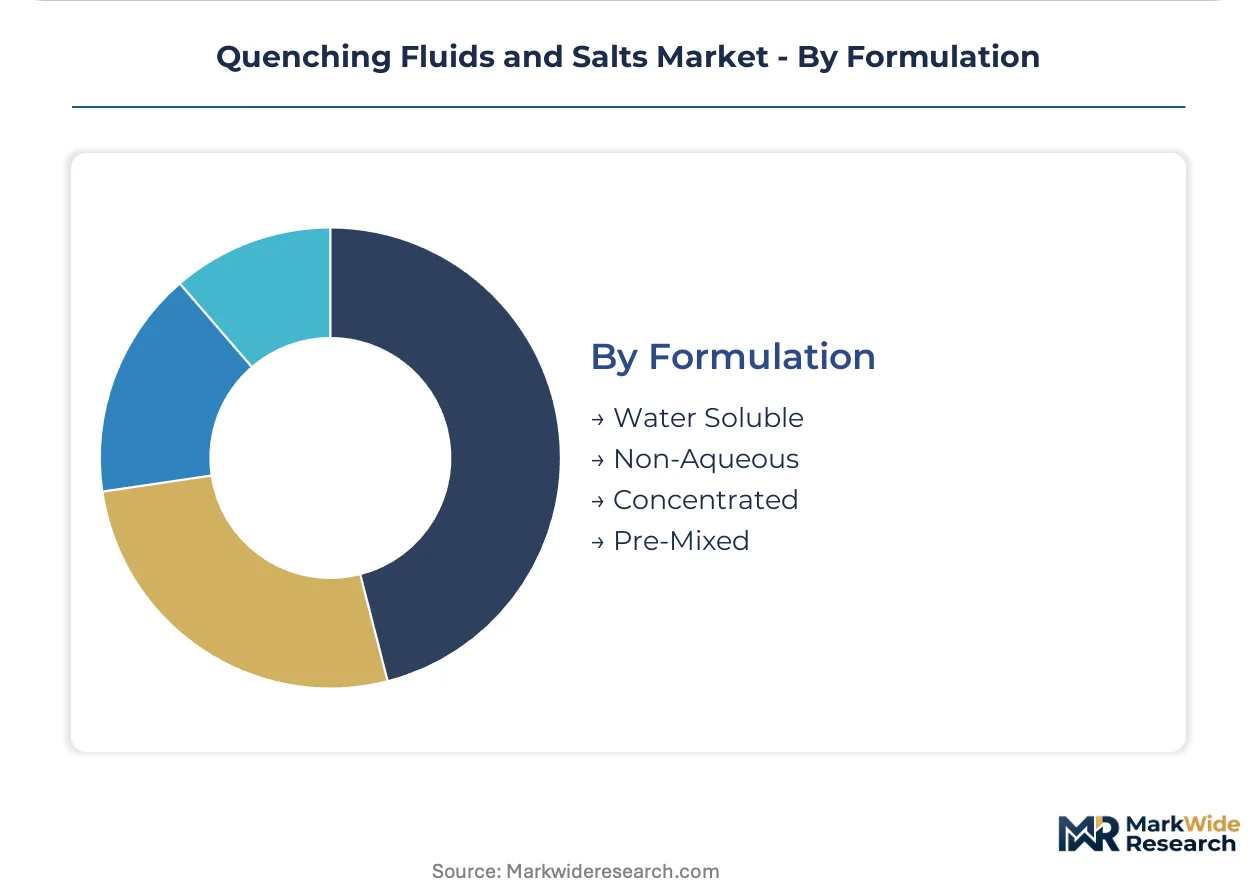
Formulation:
Supply concentration in blending infrastructure favors pre-mixed solutions for small and mid-size operations.
- Water Soluble:Polymer concentrates diluting to operational concentration for closed-loop system compatibility. EPA RCRA enforcement on spent oil disposal accelerates adoption in Michigan and Ohio metal finishing shops.
- Non-Aqueous:Oil-based formulations requiring hazardous waste manifest documentation and cradle-to-grave tracking.
- Concentrated:Undiluted polymer or salt products requiring on-site blending and bath concentration management.
- Pre-Mixed:Ready-to-use formulations eliminating blending infrastructure requirements for smaller heat treatment departments.
Water soluble formulations dominate new system installations; concentrated products retain share in large-volume captive operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of spent oil disposal rules and ECHA REACH aromatic restrictions are reshaping quenchant procurement patterns across major manufacturing jurisdictions. Heat treatment facilities in Germany, China, the United States, Japan, and India face divergent compliance timelines and capital requirements for system upgrades.
Germany
Stuttgart aerospace suppliers accelerate polymer quenchant qualification to eliminate hazardous substance reporting under ECHA REACH. The country's metalworking fluid regulations mandate aromatic content reductions in heat treatment operations. Hamburg and Wolfsburg manufacturing clusters adopt inverse solubility polymer systems for thin-walled gear hardening in automotive transmission lines.
China
Automotive forging operations in Jiangsu province scale salt mixture consumption for precision alloy hardening of crankshafts and camshafts. MEE effluent standards constrain discharge practices from heat treatment facilities. The Yangtze River Delta industrial corridor expands closed-loop water-soluble quenchant adoption to meet zero liquid discharge targets.
United States
Michigan and Ohio metal finishing shops face EPA RCRA inspection priority status for hazardous waste generator violations. The agency's cradle-to-grave tracking requirements tighten manifest documentation for spent mineral oil disposal. Wichita aerospace suppliers prioritize AMS 2750 pyrometry compliance documentation for Nadcap accreditation renewal.
Japan
Nagoya automotive tier suppliers integrate fluid management service contracts into long-term procurement arrangements. METI industrial efficiency guidelines encourage quenchant recycling infrastructure investment. The Kanto region around Tokyo hosts concentrated heat treatment operations serving precision machinery and electronics component manufacturers.
India
BIS certification requirements for automotive component suppliers create specification upgrade pathways in Pune and Chennai manufacturing clusters. The country's heat treatment modernization programs target closed-loop system adoption. Maharashtra and Tamil Nadu industrial zones absorb growing polymer quenchant volumes as OEMs enforce supplier accountability protocols.
Quenching Fluids and Salts Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented supply relationships in the quenching fluids sector. Integrated petrochemical groups leverage base oil infrastructure and distribution networks against independent formulators emphasizing technical service proximity. Three archetypes dominate: multinational lubricant conglomerates with captive quenchant blending, regional specialists offering formulation flexibility, and fluid management service providers assuming inventory risk. Competitive moves concentrate on M&A to secure regional formulation capabilities and strategic partnerships for recycling infrastructure deployment.
Among multinational lubricant conglomerates, Chevron Corporation and Exxon Mobil Corporation exemplify the scale-driven archetype leveraging Gulf Coast refining concentration. FUCHS Petrolub SE occupies a position representing European specialist leadership through polymer-based formulations. Quaker Houghton anchors the fluid management service tier with multi-year plant-level contracts. Petrofer exemplifies regional formulation flexibility competitors serving mid-size heat treatment operations.
| Leading Market Players |
|---|
| Chevron Corporation |
| Petrofer |
| Quaker Houghton |
| CONDAT |
| Chemtool Incorporated |
| FUCHS Petrolub SE |
| Exxon Mobil Corporation |
| Croda International Plc |
| TotalEnergies SE |
| Others |
Supply Flow & Price Mechanics
Base oil supply concentration in Gulf Coast refining complexes creates feedstock allocation vulnerability that compresses margin spreads between polymer-based and mineral oil formulations while forcing heat treatment shops toward long-term service contracts that externalize inventory risk.
Pricing Analysis
Certification level (Nadcap/AMS 2750 versus general industrial grade) creates the primary spread between aerospace-specified polymer quenchants and commodity mineral oil formulations. Three-tier pricing structure across premium, standard, and economy levels reflects qualification burden, with fluid management service contracts capturing multi-year commitments from automotive OEMs. Cost compression in standard-grade mineral oils is intensifying because of Group II/III base stock competition from lubricant blenders. Tier suppliers in automotive powertrain operations exhibit highest price sensitivity; Nadcap-accredited aerospace facilities accept premium positioning for process parameter documentation.
Supply Chain Analysis
Blending capacity concentrates with Quaker Houghton, FUCHS Petrolub SE, and Chevron Corporation across North American and European manufacturing corridors. Formulation chemistry draws from inverse solubility polymer supply anchored in German and Japanese specialty chemical sectors, while base oil feedstocks rest on Gulf Coast refinery output. Single-source vulnerability in polymer concentrate supply creates exposure when technical specialists retire. Distribution runs through fluid management service contracts in mature automotive supply chains and bulk purchase arrangements for mid-size captive operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer quenchant penetration sits at an early-cycle expansion phase as ECHA REACH aromatic restrictions and EPA RCRA enforcement simultaneously accelerate specification upgrades across German and US manufacturing bases.
For Market Incumbents: Build switching cost moats through fluid management service contracts that assume bath monitoring responsibility and capture multi-year plant-level relationships. Incumbents should deepen backward integration into inverse solubility polymer supply to defend margin position against base oil volatility. Investment in quenchant recycling infrastructure addresses emerging carbon border adjustment exposure.
For New Entrants and Emerging Players: Establish a beachhead in India's Pune and Chennai manufacturing clusters where BIS certification requirements create specification upgrade pathways without entrenched incumbent relationships. New entrants should target metal 3D printed part post-processing applications requiring controlled cooling rate fluids for thin-wall geometries. A technical service proximity model offering formulation flexibility for mid-size heat treatment operations provides viable go-to-market positioning.
For Investors and Strategic Acquirers: The market sits at a regulatory acceleration phase that favors acquisition of regional formulation specialists with established recycling infrastructure. Long-term viability centers on polymer-based technology platforms compatible with closed-loop water mandates. Target acquisition archetype: mid-size formulators with Nadcap-accredited customer relationships and proprietary inverse solubility polymer capabilities. Watch EU CBAM scope expansion as inflection signal for European heat treatment outsourcing patterns.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluid Management Service Contract Expansion | Quaker Houghton captures multi-year revenue commitments while externalizing inventory risk for automotive OEMs. |
| Backward Integration into Polymer Concentrate Supply | FUCHS Petrolub SE secures formulation flexibility for ECHA REACH-compliant aerospace specifications. |
| Quenchant Recycling Infrastructure Deployment | Petrofer addresses EU CBAM exposure for Turkish and North African toll hardening facilities. |
| Additive Manufacturing Post-Processing Qualification | Specialized fluid formulations capture thin-wall geometry hardening demand from metal 3D printing growth. |
| India Manufacturing Cluster Penetration | BIS certification pathways in Pune and Chennai unlock specification upgrade cycles without incumbent lock-in. |
Methodological Framework
Cross-validation between primary interviews with heat treatment plant managers, polymer formulation chemists, and automotive procurement leads and secondary sources including EPA RCRA enforcement records, ECHA REACH substance databases, and customs trade data anchors the qualitative findings. Bottom-up triangulation across product type, application, and industry vertical segmentation dimensions validates volume estimates against top-down manufacturing output correlations.
Calibration against historical adoption curves for aqueous polymer systems and mineral oil displacement patterns informs the projection framework across the analysis window. Segmentation modeling incorporates cooling rate precision requirements, regulatory compliance burden tiers, and metallurgical outcome specifications. CAGRs derive from facility-level capital expenditure tracking and quenchant consumption intensity per ton of hardened steel output.
Stress conditions across base oil price volatility, ECHA REACH enforcement timing, and China MEE effluent standard implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding polymer technical ceiling constraints and salt mixture handling infrastructure economics. Quarterly review of Nadcap accreditation renewal timelines and fluid management contract win rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Asia Pacific Rotomoulding Powder Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Urea Strippers Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Permeate Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Pelletized Activated Carbon Market