
 Fabric Starch Market | 2026-2036
Fabric Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Fabric Starch Market Foresight
REACH compliance in Europe is repositioning the cost structure for imported starch formulations by mandating full substance registration and toxicity documentation. Ingredion Inc. leverages its corn wet-milling infrastructure to control raw material quality from field to finished product. Cargill Inc. anchors its competitive stance through backward integration into North American grain supply chains.
Fabric starch comprises polysaccharide derivatives, primarily amylose and amylopectin extracted from corn, wheat, or tapioca, formulated into aqueous suspensions or dried powders that coat textile fibers to impart stiffness and wrinkle resistance. Spray starch dominates household channels due to convenience, while liquid starch sustains volume in industrial textile finishing where dip-tank application allows precise solids control. Organic starch variants compete on premium positioning through certified agricultural sourcing and reduced synthetic additive content.
The EPA regulates volatile organic compound limits in aerosol starch products, while the EU ECHA enforces biocidal product authorization for antimicrobial starch additives used in hospitality applications. India's BIS certification for textile auxiliaries shapes import eligibility and domestic manufacturing standards. Stakeholders must monitor how evolving chemical disclosure mandates in multiple jurisdictions will reshape formulation R&D priorities and regional sourcing strategies.
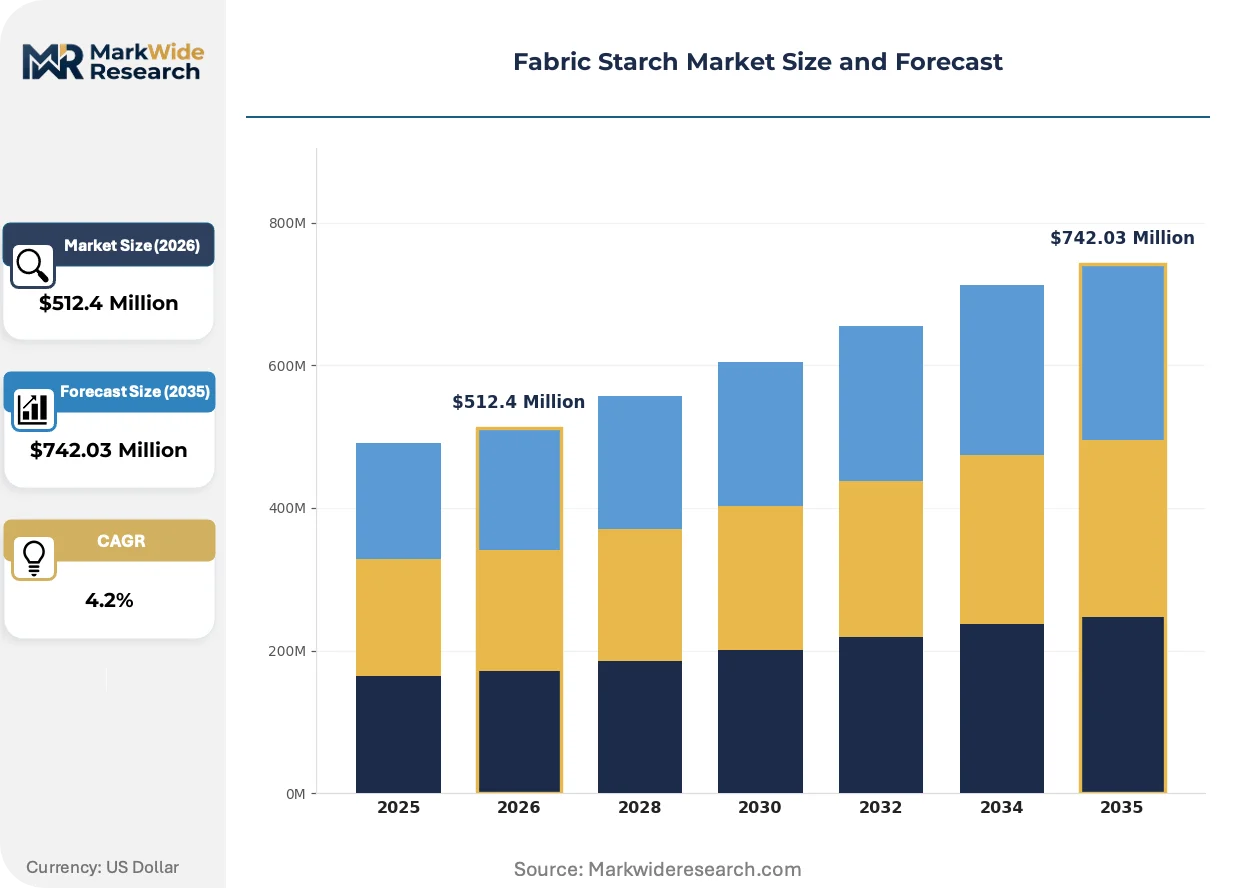
Market Dynamics
Professional textile finishing operations are consolidating procurement around concentrated liquid starch formulations, compressing margins for legacy aerosol manufacturers while redirecting R&D investment toward dip-tank compatible chemistries.
Growth Catalysts
- India's National Action Plan for Skill Development in Textiles:Formal garment finishing capacity expansion creates sustained demand for industrial-grade starch suspensions in Tiruppur and Surat clusters.
- Commercial laundry automation:Tunnel finishing systems in hotel and healthcare linen services require precisely metered liquid starch delivery, standardizing formulation specifications.
- Corn wet-milling infrastructure:North American grain processing networks supply consistent amylopectin ratios for high-performance textile coatings.
Market Restraints
- REACH registration costs:Full substance documentation requirements for EU import eligibility raise fixed compliance burdens disproportionately for small-batch starch blenders.
- Tapioca supply concentration:Southeast Asian cassava harvest volatility transmits directly to modified starch pricing for premium organic variants.
- Synthetic polymer substitution:Permanent-press resin finishes in fast-fashion applications displace reversible starch-based stiffening for certain garment categories.
Strategic Opportunities
- EPA Safer Choice certification:Ingredient disclosure mandates create first-mover advantage for transparent formulation portfolios in US household channels.
- Antimicrobial starch additives:Biocidal product authorization under EU ECHA opens hospitality linen treatment as a differentiated application segment.
- E-commerce direct fulfillment:Concentrated liquid concentrates shipped in refill formats bypass traditional retail shelf-space constraints for home laundry segments.
Industry Challenges
- Textile chemist talent pipeline:Specialized formulation expertise for industrial dip-tank optimization remains concentrated among legacy European and Japanese technical institutes.
- Legacy equipment retrofit costs:Commercial laundries face capital outlay for precision dosing systems compatible with next-generation concentrated starch suspensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fabric Starch Market |
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $742.03 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Starch, Powder Starch, Spray Starch, Organic Starch Application: Household Use, Industrial Use, Commercial Use, Textile Manufacturing Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Consumers, Garment Manufacturers, Dry Cleaners, Hotels |
| Companies Covered | Best Press, Bucko Ironing Spray, Faultless, Ingredion Inc., Cargill Inc., The Laundress, Quilter's Starch Savvy, Archer Daniels Midland Company, Purex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fabric Starch Market Shifts & Advancements
Formulation chemistry and application hardware are converging to displace standardized aerosol products with precision-dosed industrial systems and certified-sustainable household alternatives.
Enzymatic modification of starch polymers is integrating targeted molecular weight distribution control into textile finishing workflows. Industrial laundries serving hospital chains are adopting these precision-formulated suspensions at accelerating rates. This molecular engineering is integrating performance consistency previously unattainable with raw agricultural extracts.
REACH substance registration deadlines are compressing import eligibility windows for non-EU starch compounders. Full toxicity dossier requirements now gate market access regardless of volume thresholds. Professional textile finishers in Italy and Portugal are consolidating supplier relationships to ensure continuous formulation availability.
Certified organic sourcing is displacing conventional commodity purchasing in premium household segments. German and Dutch retail chains are removing uncertified starch products from shelf sets. This preference rotation is most visible in Benelux markets where environmental labeling carries disproportionate basket-share influence.
Fabric Starch Market Segmentation
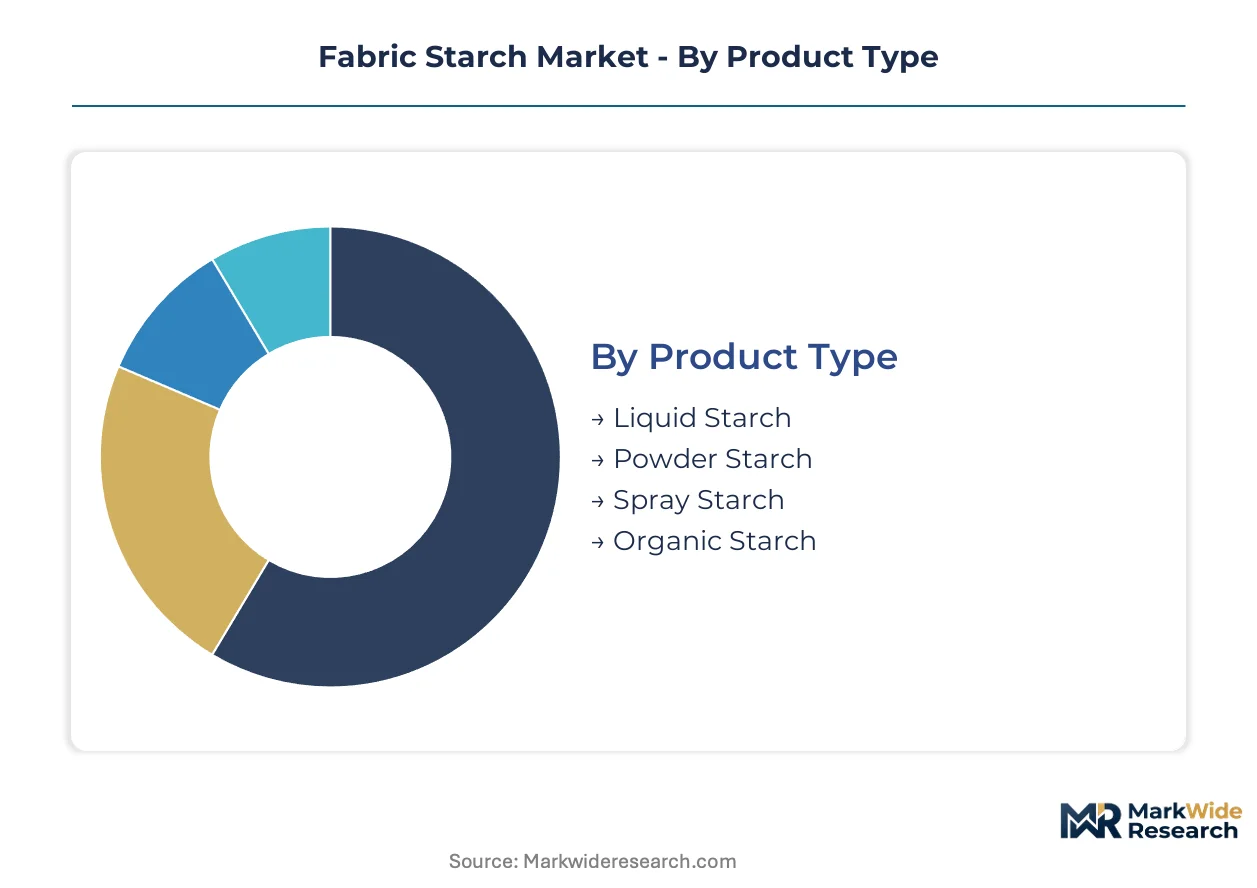
Fabric starch purchasing patterns diverge sharply between volume-driven industrial buyers seeking dip-tank compatibility and convenience-oriented household consumers prioritizing spray application ease. Understanding these segment boundaries clarifies where formulation R&D investments yield returns versus where packaging innovation drives margin capture.
Product Type:
Industrial buyers prioritize solids concentration and viscosity stability for automated dosing systems, while household purchasers trade formulation precision for shelf visibility and application convenience.
- Liquid Starch:Concentrated aqueous suspensions with controlled amylopectin ratios enable precise viscosity metering in tunnel finishing systems. Demand concentrates in Tiruppur and Surat garment clusters where India's National Action Plan for Skill Development in Textiles expands formal finishing capacity, though legacy equipment retrofit costs slow adoption at smaller commercial laundries.
- Spray Starch:Pre-diluted formulations in aerosol or pump dispensers dominate US and European household channels where convenience commands premium positioning. EPA volatile organic compound limits on aerosol propellants are compressing margins for legacy manufacturers while redirecting R&D toward trigger-spray alternatives with equivalent coverage performance.
- Powder Starch:Dried granule formats retain volume in price-sensitive emerging markets and legacy institutional procurement.
- Organic Starch:Certified agricultural sourcing with reduced synthetic additive content captures premium positioning in Benelux and German retail chains.
Volume sits with liquid starch in industrial procurement; growth tilts toward organic starch in certified-sustainable household segments.
Application:
End-use specifications determine formulation chemistry, with industrial dip-tank processes demanding molecular weight precision that household ironing tolerates.
- Industrial Use:Tunnel finishing systems in hotel and healthcare linen services require enzymatically modified polymers with targeted molecular weight distribution. REACH substance registration deadlines are compressing supplier eligibility for EU textile finishers, consolidating procurement relationships around established compounders with full toxicity dossiers.
- Household Use:Spray and liquid formats for domestic ironing prioritize fragrance profiles and fabric safety claims over performance metrics. EPA Safer Choice certification is becoming a gatekeeping requirement for shelf placement in major US retail chains.
- Commercial Use:Independent dry cleaners and small hospitality operators balance cost control with finished-goods presentation standards.
- Textile Manufacturing:Garment export houses integrate starch finishing into quality control workflows for wrinkle-resistance specifications.
Procurement scale favors industrial use; certification requirements are expanding fastest in household channels.
Distribution Channel:
Channel selection reflects buyer urgency, formulation concentration economics, and regulatory disclosure obligations.
- Wholesale:Bulk concentrated suspensions supplied in drum or tote formats serve commercial laundries and textile finishers with established dosing infrastructure. India's BIS certification for textile auxiliaries shapes import eligibility, favoring domestic manufacturers with compliant documentation.
- Online Retail:Concentrated liquid concentrates in refill formats bypass retail shelf-space constraints and enable direct ingredient disclosure for transparency-seeking consumers.
- Supermarkets:Mass-market spray and liquid formats compete for end-cap placement and seasonal promotional cycles.
- Specialty Stores:Premium organic variants and professional-grade concentrates target enthusiast sewers and small commercial operators.
Wholesale channels capture industrial volume; online retail is climbing fastest for concentrated household formats.
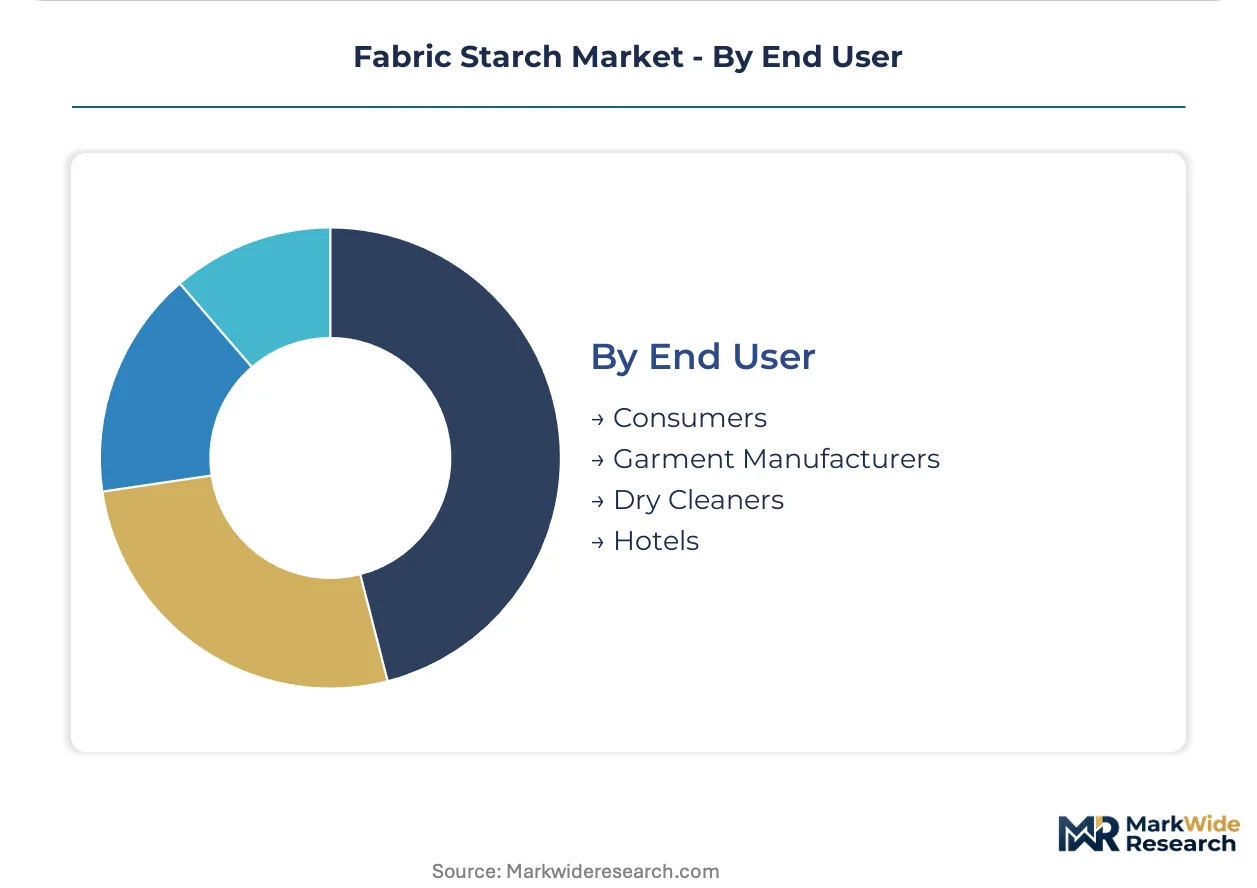
End User:
User technical sophistication determines whether starch procurement emphasizes formulation specifications or brand recognition.
- Garment Manufacturers:Export-oriented operations in India and Bangladesh specify starch performance metrics within supplier quality agreements, with enzymatic modification enabling consistency previously unattainable with raw agricultural extracts.
- Hotels:Chain procurement departments standardize linen finishing specifications across properties, creating volume concentration for approved suppliers with tunnel-system compatibility.
- Consumers:Household purchasers respond to fragrance, ease-of-use claims, and environmental certifications with limited technical evaluation.
- Dry Cleaners:Independent operators balance customer garment care expectations against per-unit processing cost targets.
Contracted volume concentrates with garment manufacturers and hotel chains; dry cleaner procurement is gaining share fastest as commercial laundry automation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Tiruppur and Surat clusters concentrate garment finishing capacity under the National Action Plan for Skill Development in Textiles. Germany's Benelux-adjacent chemical processing zones anchor European starch formulation R&D. The United States maintains aerosol starch manufacturing infrastructure despite EPA volatile organic compound compression.
United States
Hotel and healthcare linen service automation drives concentrated liquid starch procurement. EPA Safer Choice certification gates retail shelf placement for household spray formats. Ohio and North Carolina textile chemical manufacturing corridors host legacy aerosol production infrastructure facing propellant reformulation mandates.
Germany
REACH substance registration deadlines compress import eligibility for non-EU starch compounders. ECHA biocidal product authorization governs antimicrobial additive formulations for hospitality applications. The Lower Rhine chemical processing belt consolidates supplier relationships to ensure continuous industrial starch availability.
India
Tiruppur's export-oriented garment houses specify enzymatically modified starch performance metrics within supplier agreements. BIS certification for textile auxiliaries shapes import eligibility and domestic manufacturing standards. Surat's synthetic textile finishing cluster expands formal capacity under national skill development programs.
Italy
Professional textile finishers in Como and Prato consolidate procurement around established compounders with full REACH toxicity dossiers. EU ECHA enforcement accelerates supplier rationalization among small-batch starch blenders. The Lombardy-Tuscany finishing corridor maintains European leadership in precision dip-tank application systems.
Netherlands
Benelux retail chains remove uncertified starch products from shelf sets, rotating preference toward organic-certified household formats. Environmental labeling carries disproportionate basket-share influence in Dutch supermarket channels. Rotterdam's chemical distribution hub facilitates concentrated liquid starch imports for industrial laundries.
Fabric Starch Market Competitive Landscape
North American grain processors anchor one tier; European specialty chemical houses hold formulation expertise. The vendor base splits between agricultural commodity processors with captive starch supply and dedicated textile chemical compounders with application-specific R&D capabilities. Three archetypes dominate: wet-milling conglomerates with backward integration into grain supply chains, enzymatic modification specialists serving industrial laundries, and branded household marketers with retail distribution scale. Competitive moves concentrate on REACH dossier completion for EU market retention and concentrated liquid format development for tunnel finishing system compatibility.
Among agricultural processors, Ingredion Inc. and Cargill Inc. exemplify the wet-milling archetype with field-to-finished-product infrastructure control. Archer Daniels Midland Company occupies a position bridging commodity supply and industrial formulation. These three anchors represent the scale-driven tier where captive raw material sourcing meets textile chemical processing.
| Leading Market Players |
|---|
| Best Press |
| Bucko Ironing Spray |
| Faultless |
| Ingredion Inc. |
| Cargill Inc. |
| The Laundress |
| Quilter's Starch Savvy |
| Archer Daniels Midland Company |
| Purex |
| Others |
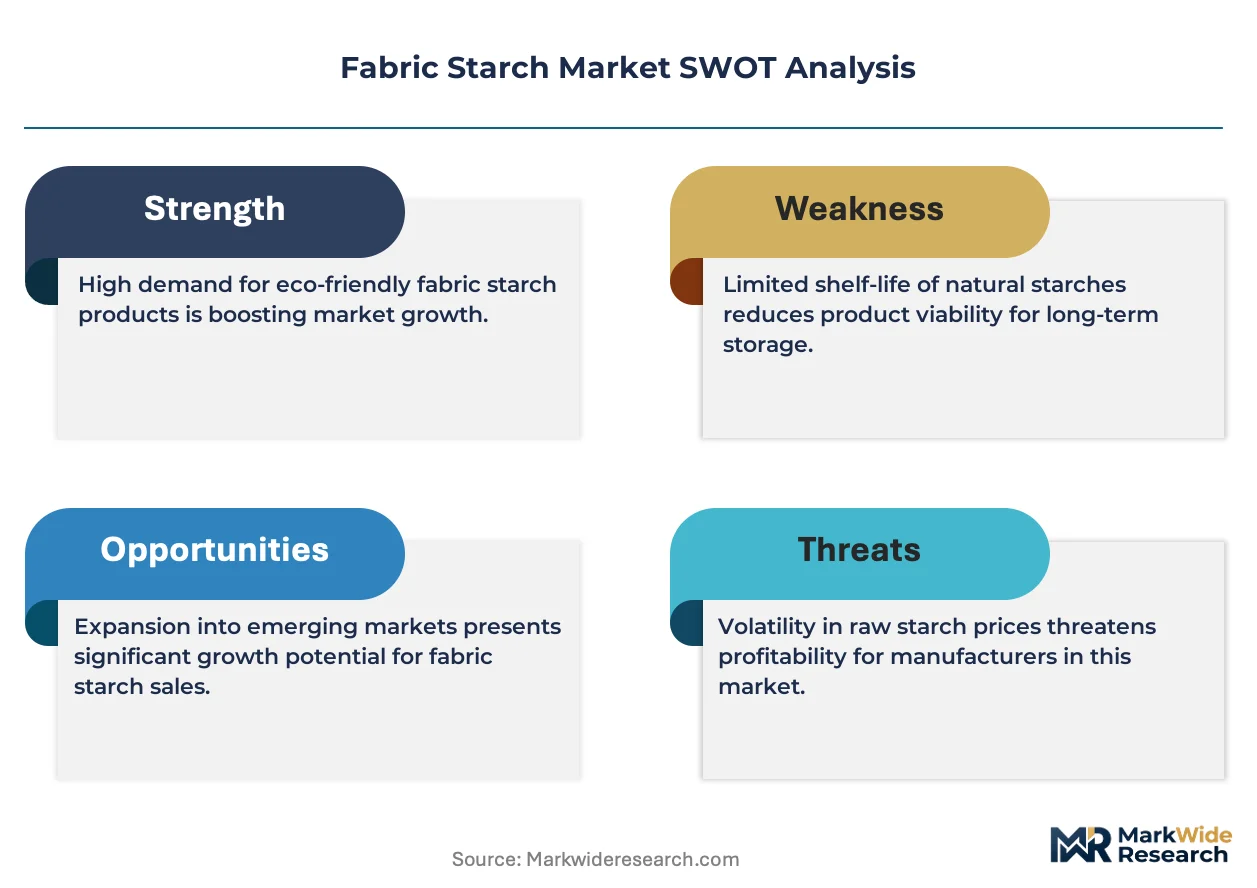
Supply & Pricing Matrix
Chicago Board of Trade corn futures pricing cascades through wet-milling economics into three distinct starch formulation tiers, with enzymatic modification premiums widening as industrial buyers prioritize molecular weight precision over commodity sourcing.
Pricing Analysis
Short lead-time premiums of 15-20% apply to concentrated liquid starch delivered within 48 hours to Tiruppur garment houses facing export deadlines. Three-tier pricing structure across enzymatically modified premium, standard industrial-grade, and commodity powder formats separates formulation precision levels. Cost compression in aerosol household segments intensifies because EPA volatile organic compound compliance mandates reformulation investments. Small commercial laundries exhibit highest price sensitivity due to legacy equipment retrofit burdens, while hotel chains with tunnel systems absorb premium pricing for supply security.
Supply Chain Analysis
Specialty textile starch supply rests on North American corn wet-milling infrastructure, Southeast Asian tapioca processing networks, and European enzymatic modification facilities. Amylopectin extraction, biocidal additive synthesis, and precision viscosity control equipment constitute critical input dependencies. Single-source vulnerability concentrates in Thai cassava harvests where climate volatility transmits directly to organic variant pricing. Distribution runs through drum-format wholesale for industrial buyers and direct-to-consumer refill subscriptions bypassing retail shelf constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fabric starch competitive dynamics have become a vertical-integration race where captive corn supply and enzymatic R&D capabilities determine margin retention against polymer substitute threats.
For Market Incumbents: Acquire enzymatic modification patents and specialist technical talent pools to defend formulation precision advantages against synthetic permanent-press resin displacement. Consolidate supplier relationships with REACH-compliant compounders in Italy and Portugal before registration deadlines eliminate small-batch competitors. Backward integration into Indian BIS-certified manufacturing protects access to Tiruppur and Surat garment cluster procurement. For New Entrants and Emerging Players: Precision-dosed liquid concentrate technology offers a technology-first wedge into home laundry subscription channels where transparency-seeking consumers bypass traditional retail. Target EPA Safer Choice certification gaps in US household spray segments where ingredient disclosure mandates create first-mover shelf placement advantages. Pursue direct-to-consumer refill formats with full supply chain visibility as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap enzymatic specialists with completed REACH dossiers in Germany's Lower Rhine chemical processing belt. Long-term viability over the next decade hinges on tunnel-system compatibility and hospitality antimicrobial additive authorization under EU ECHA frameworks. Watch for consolidation triggers among small-batch starch blenders facing disproportionate compliance cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Supply | Captive corn sourcing from Iowa and Illinois wet-milling infrastructure secures amylopectin ratio consistency for textile coatings. |
| Enzymatic Modification Patent Acquisition | Targeted molecular weight distribution control enables tunnel finishing system compatibility for hotel and healthcare linen services. |
| EPA Safer Choice Certification Investment | Ingredient disclosure compliance gates retail shelf placement in major US supermarket and mass-market channels. |
| REACH Dossier Completion | Full toxicity documentation ensures continuous EU market access for industrial textile finishers in Italy and Portugal. |
| Direct-to-Consumer Refund Format Launch | Concentrated liquid concentrates shipped in refill formats bypass retail shelf-space constraints and enable transparency marketing. |
Research Methodology
Multi-period observation of corn futures pricing, enzymatic modification patent filings, and REACH registration timelines anchored the trend analysis, supplemented by interviews with textile chemical plant managers, procurement leads at hotel linen service operators, distribution channel partners in Benelux retail, and technical R&D directors at wet-milling facilities. Secondary validation drew from US EPA Safer Choice certified product listings, EU ECHA biocidal product authorization databases, India BIS textile auxiliary standards, SEC 10-K disclosures from agricultural processors, and customs trade data for starch derivative imports. Bottom-up volume modeling across product type, application, and distribution channel segments triangulated against top-down macroeconomic demand indicators.
Segment-weighting approaches applied differential growth assumptions to liquid starch industrial procurement versus organic-certified household formats across the projection horizon. Modeled dimensions included product concentration grade, end-use industry vertical, distribution channel format, and regional regulatory cluster. CAGRs were derived from historical volume trajectory analysis adjusted for substitution elasticity between starch and synthetic polymer finishes. Forecast inputs incorporated India's National Action Plan for Skill Development in Textiles capacity expansion schedules and commercial laundry automation penetration curves in US hospitality sectors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cassava harvest disruption scenarios and accelerated synthetic resin adoption in fast-fashion applications. Projections reflect documented assumptions regarding regulatory timeline adherence and grain supply chain stability. A small set of named triggers—REACH enforcement intensity, EPA propellant restriction expansion, and Indian garment export demand fluctuations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Adblue Market
Industrial Chemicals
Mold Powders and Casting Fluxes Market
Industrial Chemicals
Proline Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Fluidizers in Plasterboard Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Global Silicone Fluid Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Kraft Lignin Products Market
Industrial Chemicals
Molecular Sieves Market