

Emulsifiable Metalworking Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsifiable Metalworking Fluid Market Insights
REACH biocide restrictions is hardening the cost-of-entry calculus for emulsifiable metalworking fluid suppliers seeking European market access. Quaker Houghton leverages its technical service network to sustain formulation partnerships with aerospace assemblers facing tightened discharge limits. FUCHS anchors its position through backward integration into base oil refining, while ExxonMobil competes on mineral oil supply security for soluble oil blends.
Emulsifiable metalworking fluids are oil-in-water dispersions containing mineral or synthetic base stocks, emulsifiers, corrosion inhibitors, and biocides, typically diluted to 3-10% concentration for flood or mist application during metal removal operations. These fluids simultaneously cool cutting zones, lubricate tool-workpiece interfaces, and flush chips from machining centers. Semi-synthetic formulations now lead volume growth as metal fabricators balance performance against wastewater treatment burdens, while vegetable oil based alternatives attract mold makers serving medical device clients seeking bio-based credentials. Cooling lubrication technology dominates application spend across turning and milling operations where thermal damage risks drive specification intensity.
EPA discharge rules under the Clean Water Act, REACH Annex XVII biocide limitations, and China's MEE effluent standards collectively redirect demand toward extended-life formulations with lower biocide dependency. ISO 6743-7 classification systems and JIS K 2241 benchmarks further segment product positioning by performance tier and corrosion protection rating. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in multi-national supply chains.
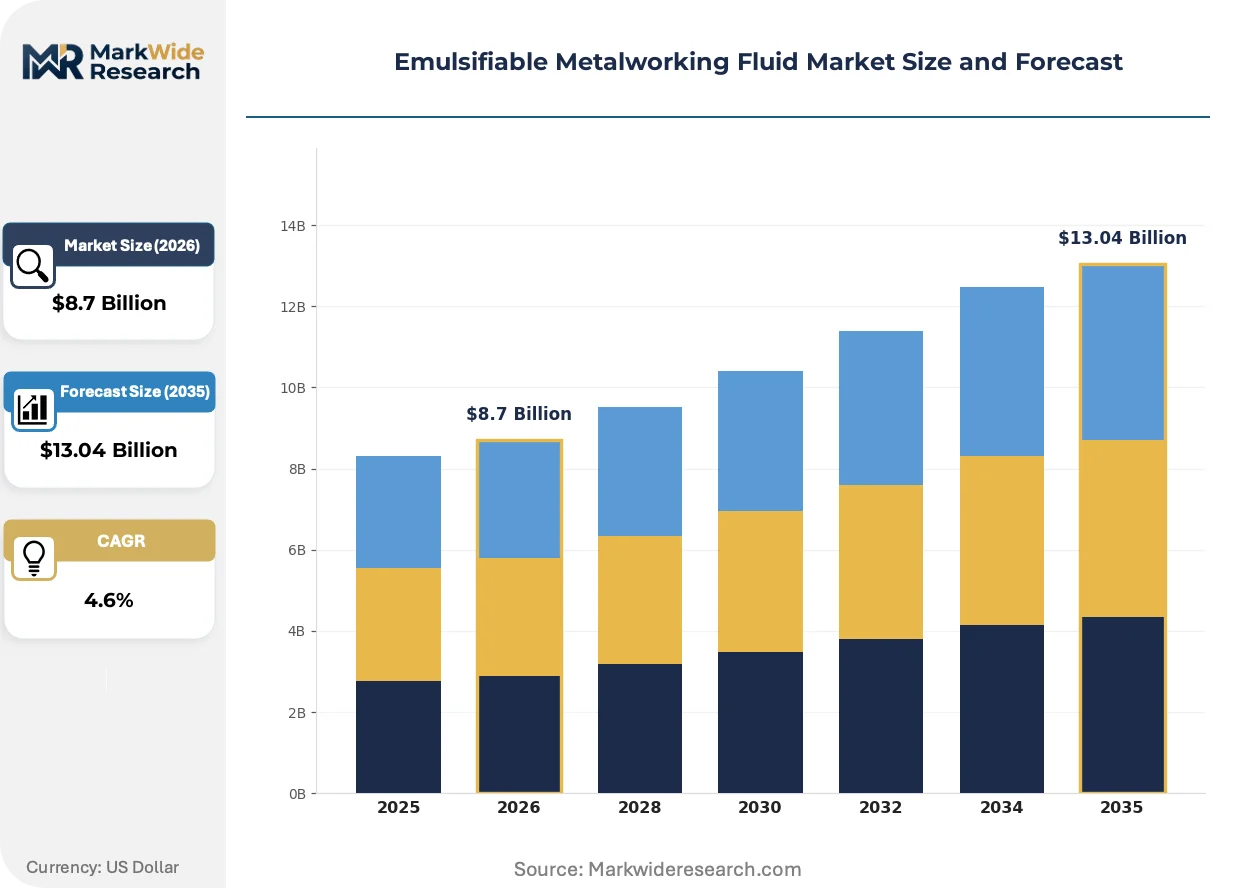
Market Dynamics
REACH Annex XVII biocide thresholds are compressing formulation flexibility for European metalworking fluid suppliers, forcing accelerated R&D spend on preservation chemistry alternatives while semi-synthetic architectures capture specification share from soluble oil legacy products.
Growth Catalysts
- EPA Clean Water Act discharge limits:Tighter effluent standards in the United States are mandating extended-life coolant systems that reduce biocide dosing frequency and wastewater treatment burden.
- Precision machining corridors:Metal fabrication clusters across China, India, and Mexico are upgrading flood coolant infrastructure to support higher-speed machining of aerospace alloys and medical-grade titanium.
- Vegetable oil ester technology:Bio-based base stocks are gaining specification traction among mold makers serving medical device OEMs seeking carbon footprint credentials for Scope 3 reporting.
Market Restraints
- Base oil supply concentration:Captive refining capacity anchors with integrated majors, leaving independent blenders exposed to Group I and Group II mineral oil price volatility and allocation risk.
- Biocide regulatory friction:ECHA's cumulative exposure assessments for formaldehyde-releasing preservatives are forcing reformulation cycles that extend qualification timelines by 18-24 months.
- Water-based coolant substitution:Minimum quantity lubrication systems and cryogenic machining are displacing flood coolant volumes in high-value aerospace turning operations.
Strategic Opportunities
- India's PLI scheme for precision engineering:Production-linked incentives for machine tool and component manufacturing are expanding addressable coolant demand in Bangalore and Pune industrial corridors.
- EU Green Deal procurement mandates:Public tender specifications for bio-based content in maintenance chemicals are creating preferential access pathways for vegetable oil ester formulations.
- Digital coolant monitoring convergence:IoT-enabled concentration and pH sensors are enabling predictive maintenance service models that lock in multi-year supply contracts.
Industry Challenges
- Tribology specialist scarcity:Formulation chemists with simultaneous expertise in corrosion inhibition and emulsion stability are concentrated among retiring cohorts at legacy suppliers.
- ISO 6743-7 certification timelines:Multi-parameter testing for extreme pressure and copper corrosion ratings extends product launch cycles, compressing first-mover advantage windows.
- Legacy system integration:Central coolant recycling installations from the 1990s lack compatibility with next-generation semi-synthetic chemistries, forcing costly retrofit decisions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsifiable Metalworking Fluid Market Trends and Innovations
Formulation architecture is pivoting toward lower-biocide dependency as regulatory pressure intersects with wastewater treatment cost escalation, while digital service layers are redefining supplier-customer relationships beyond commodity chemistry supply.
Semi-synthetic metalworking fluid technology is overtaking soluble oil formulations in specification intensity across German and US aerospace machining centers. These oil-in-water dispersions with 30-50% base oil content deliver equivalent lubricity with lower mist generation and reduced sump maintenance frequency. Tier-1 suppliers are capturing multi-year contracts by guaranteeing extended fluid life that offsets higher per-gallon pricing through treatment cost avoidance.
ECHA's cumulative risk assessment methodology for isothiazolinone biocides is forcing systematic reformulation across European metalworking fluid portfolios. The industrial consequence is accelerated qualification of phenoxyethanol and organic acid preservation systems that previously failed cost benchmarks. Small-to-mid blenders without captive toxicology resources are exiting the market, concentrating supply among integrated majors with regulatory affairs scale.
Machine shop procurement patterns are compressing supplier rosters from multi-source bidding to dual-source framework agreements with technical service commitments. Tier-2 metal fabricators in Mexico's Querétaro aerospace corridor are consolidating coolant spend with suppliers offering on-site fluid management and waste minimization programs. This behavioral shift rewards integrated service capability over standalone product pricing, elevating technical field presence as a competitive differentiator.
Emulsifiable Metalworking Fluid Market Segmentation
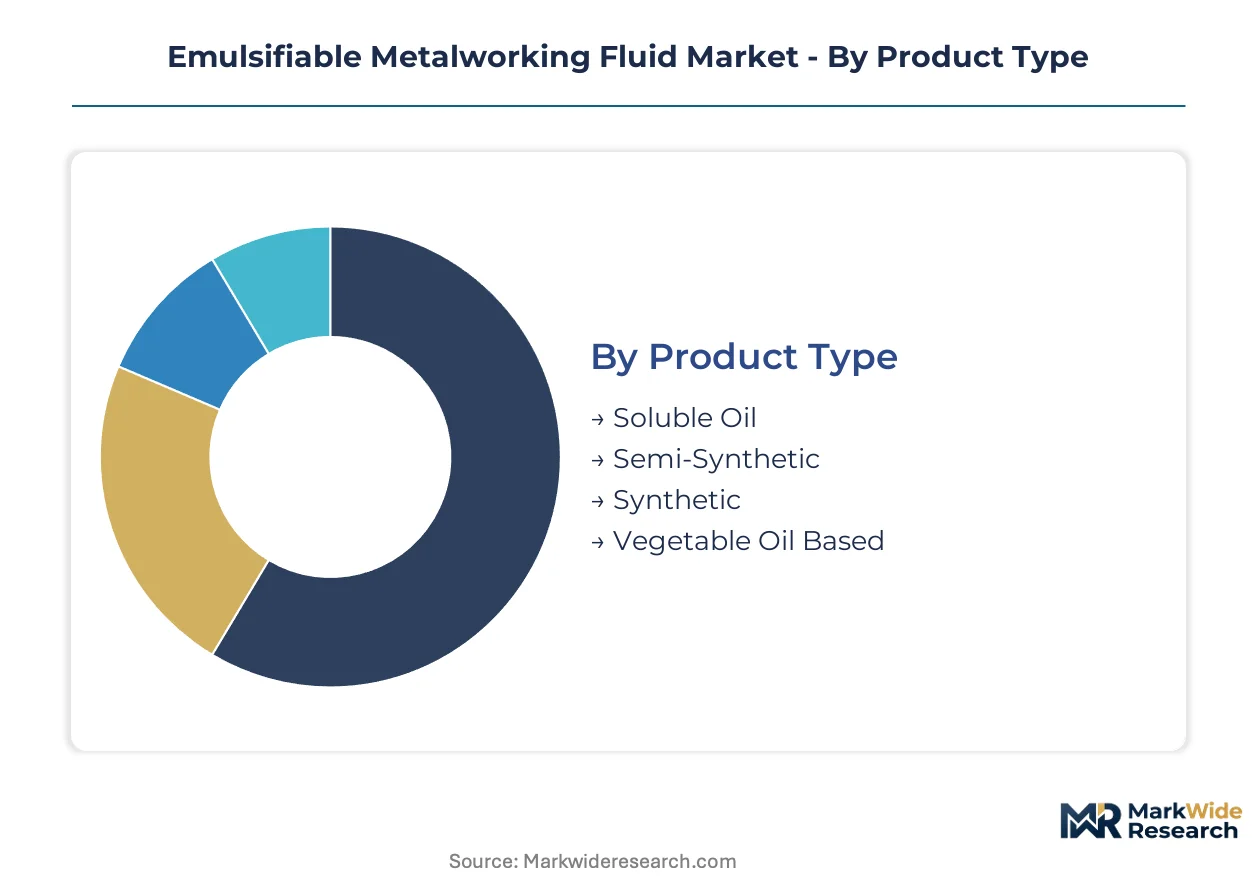
Segmentation in emulsifiable metalworking fluids reveals how formulation chemistry, functional technology, and end-use intensity create divergent margin profiles across the value chain. Suppliers configure R&D portfolios and technical service deployment around these divisions.
Product Type:
Capital intensity varies sharply across formulation architectures, with semi-synthetic and synthetic platforms demanding the highest upfront investment in emulsion stability testing and biocide-free preservation chemistry.
- Semi-Synthetic:Oil-in-water dispersions containing 30-50% synthetic or highly refined base stocks deliver balanced lubricity and thermal stability. Aerospace machining centers in Germany and the United States specify these formulations to meet REACH and EPA discharge thresholds while maintaining tool life in titanium and nickel alloy operations.
- Soluble Oil:Traditional mineral oil-based emulsions with 60-85% petroleum content remain prevalent in cost-sensitive metal fabrication. Legacy installations in India's Pune and Bangalore industrial corridors continue specifying these fluids, though wastewater treatment burdens are accelerating migration toward lower-oil alternatives.
- Synthetic:Chemically engineered base stocks without petroleum content offer maximum cooling capacity and biological resistance. These formulations command premium positioning in precision grinding of medical-grade components where sump life extension justifies higher per-gallon pricing.
- Vegetable Oil Based:Bio-derived esters from rapeseed and palm sources serve mold makers supplying medical device OEMs with Scope 3 carbon reporting requirements. EU Green Deal procurement specifications are expanding addressable demand for these credentials.
Semi-synthetic formulations absorb the bulk of installed capacity; vegetable oil based alternatives are expanding most quickly.
Technology:
Functional specialization determines which fluid properties command specification priority across different metal removal operations.
- Cooling Lubrication:Simultaneous heat dissipation and friction reduction at the tool-workpiece interface dominates specification spend. High-speed machining of aerospace alloys in Mexico's Querétaro corridor relies on advanced cooling lubrication to prevent thermal damage and dimensional drift.
- Corrosion Protection:Ferrous and non-ferrous metal compatibility requirements segment product positioning by alloy specificity. Multi-metal protection chemistry is essential for job shops processing mixed material streams without dedicated sump systems.
- Cleaning:Chip flushing and surface residue control functions prevent re-deposition on machined surfaces. These properties gain priority in automated production lines where downstream inspection rejects are costly.
- Foam Control:Antifoam chemistry maintains emulsion stability under high-pressure delivery and recirculation conditions. Excessive foam generation triggers premature fluid disposal and interrupts continuous production schedules.
Cooling lubrication captures the largest share of technology-linked spend; corrosion protection is climbing fastest as multi-metal machining intensifies.
Application:
Metal removal mechanics dictate fluid delivery method, concentration requirements, and consumption rates across machining operations.
- Machining:Broad category encompassing material removal through cutting tool engagement. General machining operations in China's precision component clusters drive volume demand for standard-duty soluble oil formulations.
- Turning:Rotational workpiece operations with continuous chip formation impose severe thermal loading on cutting inserts. Minimum quantity lubrication and cryogenic alternatives are displacing flood coolant volumes in high-value aerospace turning.
- Milling:Intermittent cutting with variable chip loads requires robust foam control and lubricant film strength. Five-axis milling centers processing complex aerospace structures specify semi-synthetic fluids for extended sump life.
- Grinding:Abrasive material removal with high specific energy input demands maximum cooling efficiency. Synthetic and semi-synthetic formulations dominate precision grinding of hardened steels and ceramics.
- Drilling:Deep-hole operations with constrained chip evacuation paths require high-pressure delivery and lubricity enhancement. Specialized drilling fluids incorporate extreme-pressure additives for stainless steel and superalloy penetration.
Machining commands the greatest fluid volume consumption; milling is gaining share fastest as five-axis complexity spreads through aerospace supply chains.
End User Industry:
Customer technical sophistication and regulatory exposure create tiered service requirements across industrial segments.
- Aerospace Assemblers:Tier-1 manufacturers and their machining subcontractors impose stringent fluid qualification protocols. REACH Annex XVII biocide restrictions and EPA Clean Water Act discharge rules are hardening specification requirements for extended-life, low-biocide formulations.
- Metal Fabricators:General job shops and production machining facilities prioritize cost efficiency over performance extremes. These customers are consolidating supplier relationships toward dual-source frameworks with embedded technical service.
- Mold Makers:Precision tool and die manufacturers serving medical device and automotive clients require bio-based credentials and residue-free finishing. EU Green Deal procurement mandates are creating preferential pathways for vegetable oil ester formulations.
- Heavy Equipment Manufacturers:Large-scale production of construction and agricultural machinery involves high-volume ferrous machining with standard corrosion protection requirements. These operations maintain substantial central coolant recycling infrastructure from prior decades.
Metal fabricators represent the largest installed base; aerospace assemblers are expanding specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production-Linked Incentive scheme for precision engineering concentrates metalworking fluid demand in Bangalore and Pune industrial corridors, where aerospace subcontracting clusters expand flood coolant infrastructure.
United States
EPA Clean Water Act discharge limits mandate extended-life coolant systems across precision machining corridors in Michigan and Ohio. Aerospace assemblers in Wichita and Seattle specify semi-synthetic formulations to meet tightened effluent standards. Tier-1 suppliers capture multi-year contracts through guaranteed fluid life extension.
Germany
REACH Annex XVII biocide thresholds compress formulation flexibility for metalworking fluid suppliers serving Bavarian aerospace machining centers. ECHA's cumulative exposure assessments force systematic reformulation cycles extending qualification timelines. Stuttgart and Munich industrial clusters accelerate migration toward phenoxyethanol preservation systems.
China
MEE effluent standards redirect demand toward extended-life formulations in Yangtze River Delta precision component manufacturing. Local metal fabrication clusters upgrade flood coolant infrastructure to support higher-speed machining of aerospace alloys. Suzhou and Shanghai machining centers drive specification intensity for corrosion protection chemistry.
Mexico
Querétaro aerospace corridor metal fabricators consolidate coolant spend with suppliers offering on-site fluid management programs. Dual-source framework agreements with technical service commitments replace multi-source bidding patterns. Monterrey and Tijuana production machining facilities prioritize wastewater treatment cost avoidance.
India
Bangalore and Pune industrial corridors expand precision engineering capacity under PLI scheme incentives. Local metal fabrication clusters require higher-performance coolant systems for medical-grade titanium machining. Tier-2 fabricators migrate from soluble oil legacy products toward semi-synthetic architectures.
Emulsifiable Metalworking Fluid Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a tiered structure where integrated majors anchor supply security and independents carve service-intensive niches. Three archetypes dominate: petroleum majors leveraging captive base oil refining, specialty chemical houses with emulsion stability expertise, and regional blenders optimizing logistics for proximity-sensitive job shops. M&A activity concentrates preservation chemistry capabilities, while technical service networks expand to lock in multi-year framework agreements.
Among integrated petroleum majors, Quaker Houghton and FUCHS exemplify the technical service-intensive archetype, with the former sustaining formulation partnerships through field presence and the latter anchoring position through backward integration into base oil refining. ExxonMobil occupies the supply security vector, competing on mineral oil allocation reliability for soluble oil blends. These three represent distinct competitive positioning: service-led, vertically integrated, and raw-materials-focused respectively.
| Leading Market Players |
|---|
| Quaker Houghton |
| FUCHS |
| ExxonMobil |
| Shell |
| BP Castrol |
| Chevron |
| TotalEnergies |
| Idemitsu Kosan |
| Yushiro Chemical |
| Others |
Pricing and Supply Chain Analysis
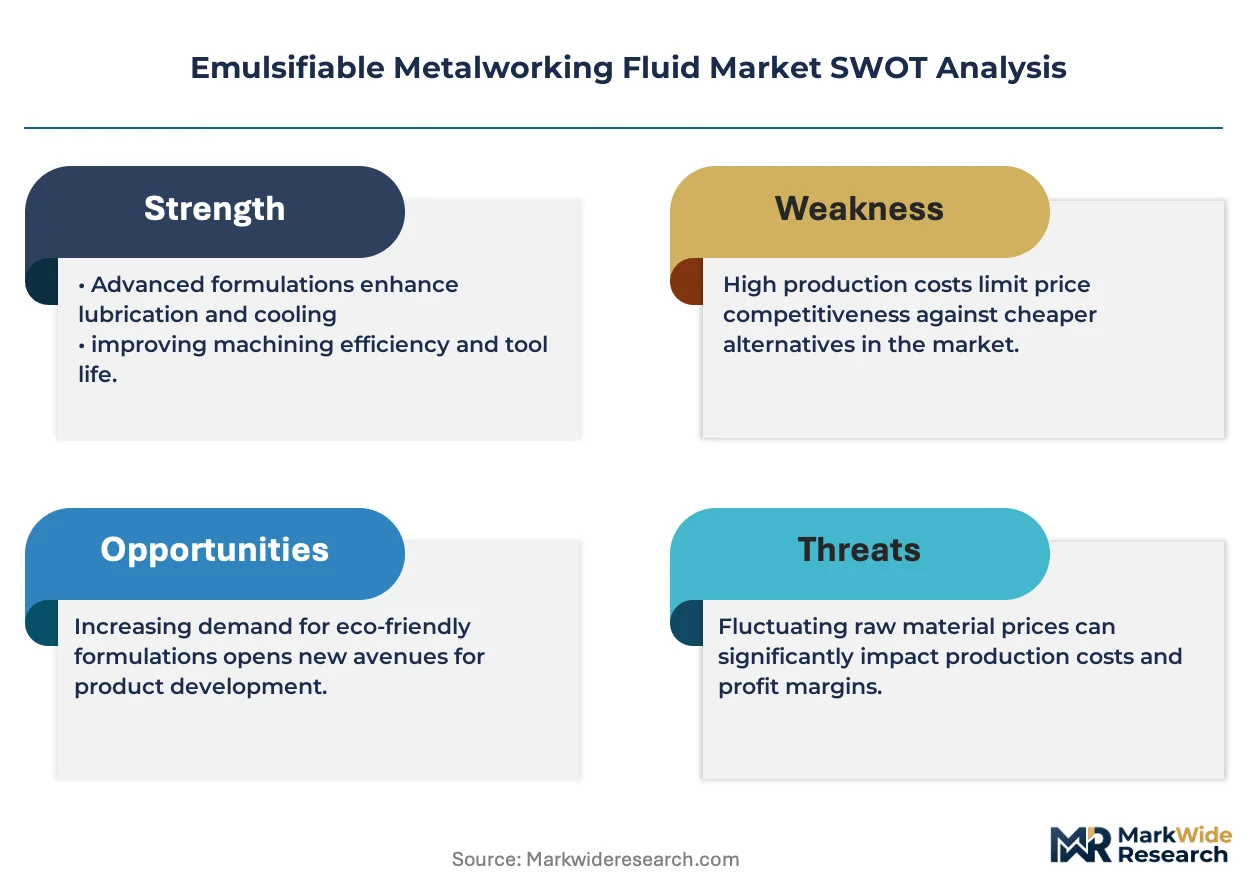
Group II base oil price indices cascade through emulsifiable metalworking fluid supply chains into three-tier pricing structures across premium, standard, and economy levels. REACH biocide compliance costs and EPA discharge treatment burdens concentrate pricing power among integrated suppliers with captive refining and toxicology resources.
Pricing Analysis
Short lead-time premiums of 15-25% apply to semi-synthetic formulations qualifying under ISO 6743-7 extreme pressure ratings, while spot inventory of soluble oil legacy products trades at discounts in India's Pune corridor. Price differentiation hinges on REACH Annex XVII biocide-free certification and volume-scale contract anchoring. Cost compression in standard-grade soluble oils is intensifying because independent blenders lack backward integration into base oil supply. Metal fabricators in Mexico's Querétaro cluster exhibit highest price sensitivity; aerospace assemblers in Germany and the United States demonstrate lowest sensitivity due to wastewater treatment cost avoidance value.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for precision engineering coolant systems in Bangalore and Pune industrial corridors. Supply concentrates in the United States, Germany, and China, with captive refining capacity anchoring with integrated majors. Formulation chemistry draws from Group I and Group II mineral oil base stocks, synthetic ester feedstocks, and isothiazolinone biocide alternatives. Single-source vulnerability persists in phenoxyethanol preservation systems following ECHA cumulative exposure assessments. Distribution runs through technical service-intensive direct channels for aerospace assemblers and distributor networks for general metal fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emulsifiable metalworking fluid markets function as a cost-of-compliance arena where REACH Annex XVII biocide thresholds erect barrier-to-entry moats favoring suppliers with regulatory affairs scale and captive toxicology resources.
For Market Incumbents: Anchor market position through backward integration into base oil refining and accelerated R&D spend on biocide-free preservation chemistry. Minimum quantity lubrication systems threaten flood coolant volumes in aerospace turning operations; defend against substitution by guaranteeing extended fluid life through digital coolant monitoring convergence. Capacity addition in India's PLI-subsidized precision engineering corridors secures volume anchoring.
For New Entrants and Emerging Players: Enter via vegetable oil ester formulations serving mold makers with EU Green Deal procurement mandates, the most penetrable segment given bio-based credential requirements. Target India's Tier-2 metal fabricators migrating from soluble oil legacy products toward semi-synthetic architectures. Go-to-market angle: on-site fluid management programs with waste minimization guarantees.
For Investors and Strategic Acquirers: The window for entry favors specialty chemical houses with emulsion stability expertise and regional blenders optimizing logistics for proximity-sensitive job shops. Long-term viability rests on consolidation of preservation chemistry capabilities amid regulatory divergence between jurisdictions. Watch ECHA's cumulative exposure assessment methodology expansion as inflection indicator for accelerated market concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | FUCHS anchors supply security through captive Group II capacity, insulating against allocation risk. |
| Biocide-Free Preservation Chemistry R&D | Phenoxyethanol and organic acid systems address REACH Annex XVII compliance timelines extending qualification cycles. |
| Digital Coolant Monitoring Convergence | IoT-enabled pH and concentration sensors lock in multi-year framework agreements with technical service commitments. |
| Regional Capacity Expansion in India | PLI scheme incentives concentrate demand in Bangalore and Pune corridors for precision engineering coolant systems. |
| Long-Term Supply Agreements with Aerospace Assemblers | Guaranteed fluid life extension offsets higher per-gallon pricing through wastewater treatment cost avoidance. |
Research Methodology
Document review covered customs and trade flow data, SEC filings from integrated petroleum majors, and ECHA biocide assessment reports, complemented by interviews with plant managers at German aerospace machining centers, procurement leads at Mexican metal fabrication clusters, technical R&D directors at specialty chemical houses, and aftermarket service heads at regional blending operations. Secondary validation drew from MEE effluent standard publications, ISO 6743-7 certification databases, and PLI scheme administrative records. Bottom-up volume builds across formulation tiers triangulated against top-down market sizing from base oil consumption patterns.
Segment-level outputs across the projection horizon reflect discrete modeling of semi-synthetic, soluble oil, synthetic, and vegetable oil based architectures, further dimensionalized by cooling lubrication technology intensity, corrosion protection rating, and end-use industry regulatory exposure. CAGRs were derived from regression analysis of historical base oil price elasticity and biocide regulatory phase-in schedules. Industry-specific inputs included aerospace alloy machining speed parameters and central coolant recycling infrastructure vintage distribution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated REACH biocide restriction expansion or sudden Group II base oil supply disruption. Forecasts reflect assumptions regarding regulatory implementation timelines and industrial adoption rates for extended-life formulations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.