
 Medical Styrenic Polymers Market | 2026-2036
Medical Styrenic Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Styrenic Polymers Market Intelligence
China is tilting toward expanded medical-grade polymer capacity to serve its domestic device manufacturing base. BASF leverages integrated styrenics production across European and Asian sites to sustain supply security for healthcare clients. INEOS ABS Corporation anchors North American resin supply through specialized medical compounding lines. Trinseo S.A. competes on transparency and color consistency for diagnostic component applications.
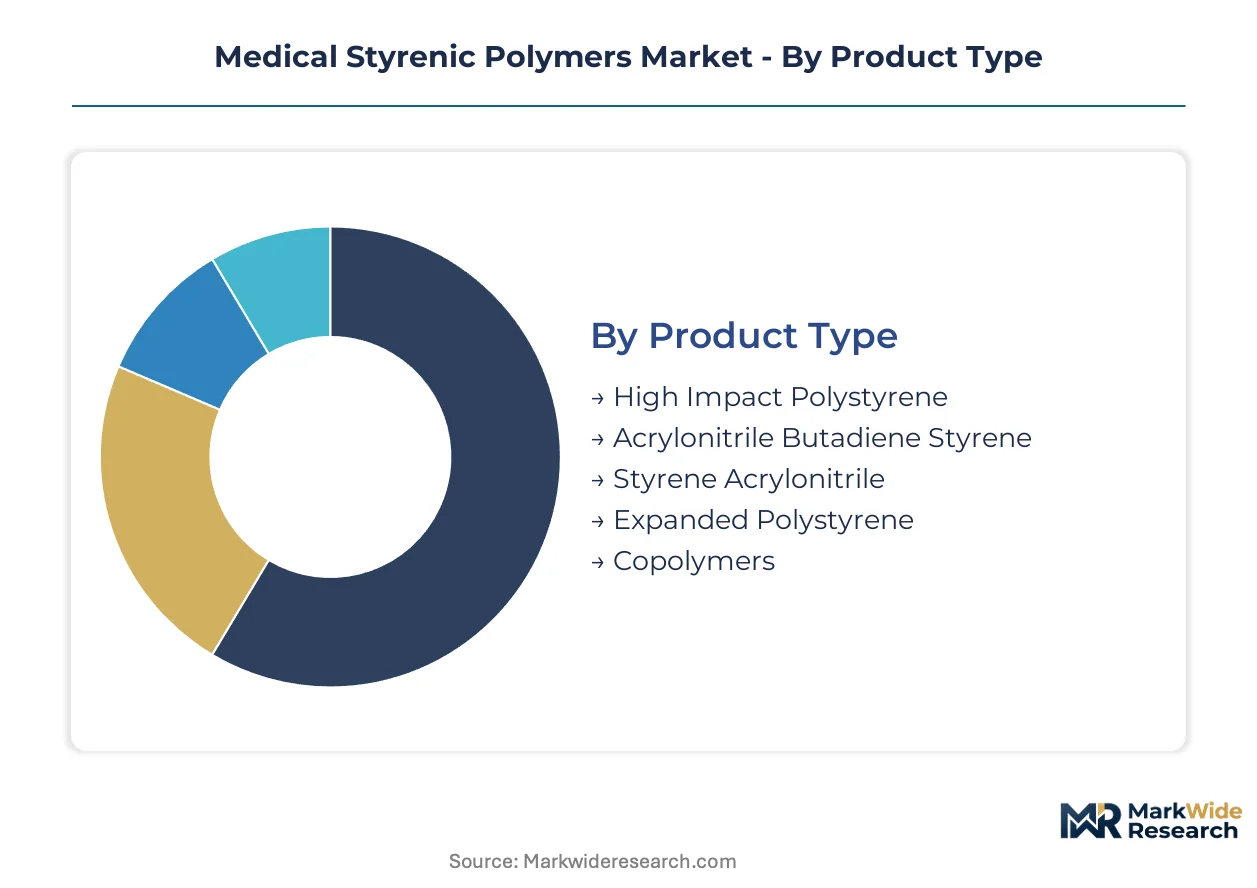
Medical styrenic polymers comprise styrene-based thermoplastic resins formulated with controlled molecular weights, low residual monomer content, and USP Class VI or ISO 10993 biocompatibility certification for healthcare contact applications. These materials deliver sterilization resistance, dimensional stability, and processability via injection molding or extrusion for disposable and reusable medical goods. Acrylonitrile Butadiene Styrene dominates molded housing applications where impact strength and surface finish carry premium value, while Styrene Acrylonitrile occupies optical diagnostic components demanding clarity and chemical resistance. Copolymers represent the fastest-growing product category as device engineers specify customized property blends for drug delivery system geometries.
FDA enforces 21 CFR 177.1640 compliance for polystyrene and rubber-modified polystyrene food-contact polymers that extend to certain medical applications, while EU MDR requires notified body scrutiny of material biocompatibility documentation for higher-risk device classes. ISO 10993 series standards govern biological evaluation testing protocols that manufacturers must complete before commercializing styrenic polymer-containing devices. Stakeholders should monitor evolving regulatory convergence between FDA and European notified body expectations for extractables and leachables testing, as harmonized requirements would reshape qualification timelines and supplier qualification burdens across major medical device export markets.
Market Dynamics
EU MDR biocompatibility documentation requirements are compressing supplier qualification timelines and forcing medical device manufacturers to consolidate polymer sourcing around certified compounders with established ISO 10993 testing protocols.
Growth Catalysts
- FDA 21 CFR 177.1640 compliance:Food-contact polymer standards extending to medical applications create regulatory clarity that accelerates styrenic adoption in disposable device housings.
- Drug delivery system miniaturization:Complex geometries in auto-injectors and infusion pumps demand customized copolymer blends with precise melt-flow characteristics.
- Germany's medical device production cluster:Concentrated manufacturing in Baden-Württemberg and Bavaria sustains localized demand for medical-grade ABS and SAN resins.
Market Restraints
- Styrene monomer price volatility:Feedstock cost fluctuations tied to benzene and ethylene markets compress compounding margins and destabilize long-term supply contracts.
- Specialized medical compounding concentration:North American resin supply depends on a limited number of dedicated production lines, creating single-source vulnerability for Class II device manufacturers.
- Polycarbonate substitution in optical applications:Higher-performance transparent polymers capture share in diagnostic imaging components where SAN clarity proves insufficient.
Strategic Opportunities
- China's domestic device manufacturing expansion:Government initiatives to localize medical production create demand for regional medical-grade polymer capacity expansion.
- Point-of-care diagnostic proliferation:Rapid test cassettes and portable analyzers require injection-molded styrenic housings with sterilization resistance and dimensional precision.
- EU Green Deal sustainable chemistry mandates:Circular economy requirements for healthcare plastics incentivize bio-based styrenic formulations and mechanical recycling integration.
Industry Challenges
- ISO 10993-18 extractables testing expertise:Shortage of analytical chemists proficient in chemical characterization delays biocompatibility documentation for new polymer grades.
- Legacy injection molding asset retrofitting:Converting standard production lines to medical-grade cleanroom standards demands capital expenditure that mid-size processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Styrenic Polymers Market |
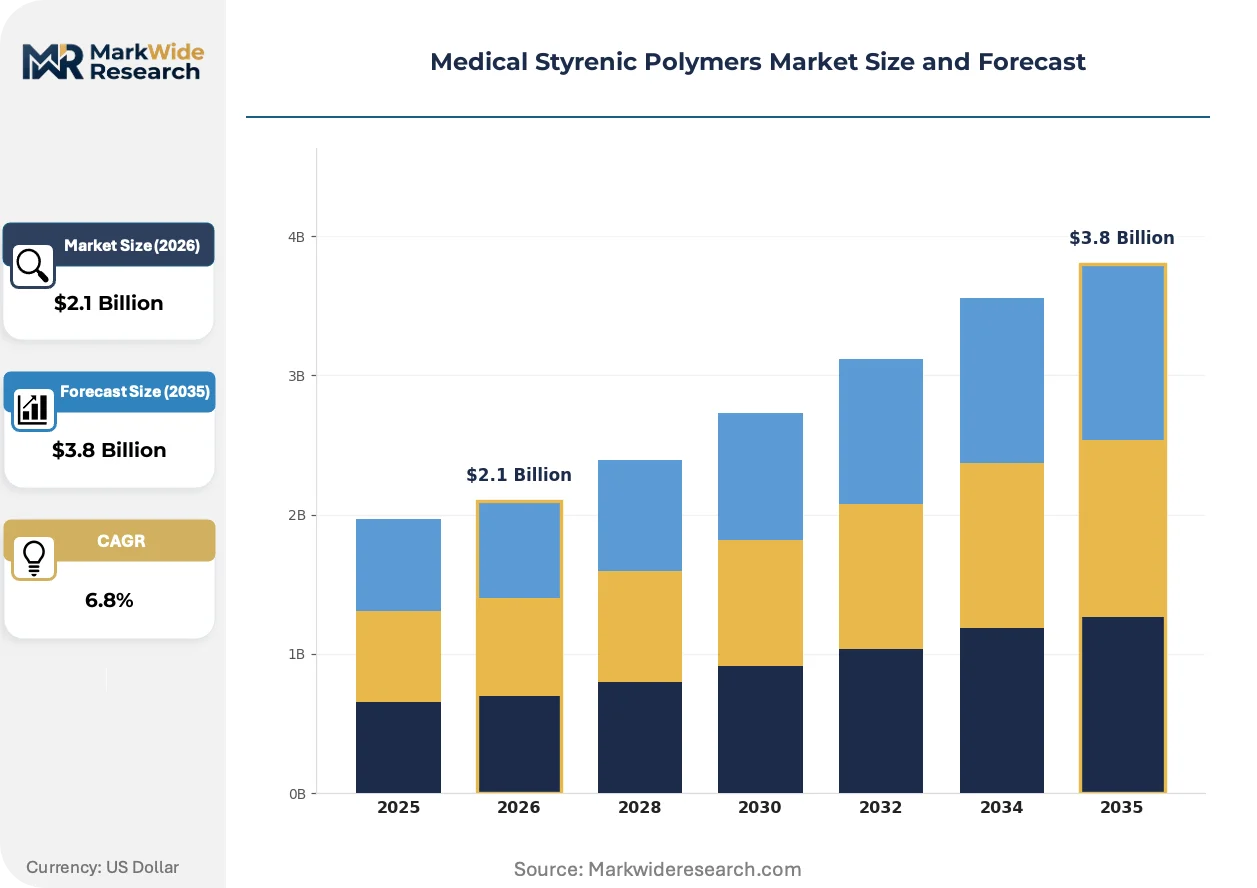
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Impact Polystyrene, Acrylonitrile Butadiene Styrene, Styrene Acrylonitrile, Expanded Polystyrene, Copolymers Application: Medical Devices, Diagnostic Components, Drug Delivery Systems, Surgical Instruments, Laboratory Equipment End User: Hospitals, Diagnostic Laboratories, Pharmaceutical Manufacturers, Clinics, Research Institutions Form: Pellets, Sheets, Films, Molded Parts, Extruded Profiles |
| Companies Covered | Evonik Industries, Americas Styrenics, BASF, Trinseo S.A., Saudi Basic Industries Corporation, LG Chem, Styrolution Group, INEOS ABS Corporation, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Styrenic Polymers Market Strategic Shifts & Innovations
Digital twin technology is compressing polymer formulation cycles and enabling real-time quality prediction across distributed medical compounding operations.
Multi-axis simulation software is virtualizing mold-flow analysis for complex drug delivery geometries before physical tooling commitment. Medical device engineers at diagnostic OEMs now iterate cavity designs in silico, cutting prototype lead times from weeks to days. This capability is virtualizing traditional sequential development stages and compressing supplier selection windows.
REACH SVHC candidate list expansion is forcing reformulation of rubber-modified polystyrene grades to eliminate legacy plasticizers and stabilizers. Compounders must revalidate biocompatibility profiles for modified formulations under EU MDR scrutiny. Higher-risk device classes in Germany and France face extended notified body review cycles as material documentation requirements tighten.
Consolidated procurement at multi-site hospital systems is displacing distributor-centric purchasing for standardized polymer specifications. Integrated delivery networks in the United States now negotiate direct supply agreements with certified compounders, bypassing traditional resin distributors. This concentration is most visible in Midwestern health systems with captive device sterilization operations.
Medical Styrenic Polymers Market Segmentation
Styrenic polymer specifications diverge sharply across medical applications, with biocompatibility tiers, sterilization protocols, and dimensional precision requirements dictating material selection. Device engineers match resin grades to end-use risk classifications and processing constraints.
Product Type:
Medical device housings, optical components, and drug delivery systems each demand distinct property profiles from styrenic formulations.
- Acrylonitrile Butadiene Styrene:Rubber-modified terpolymer delivering exceptional impact resistance and surface aesthetics for molded housings. Demand concentrates in Germany's Baden-Württemberg device cluster, where auto-injector manufacturers specify ABS for drop-resistant casings under EU MDR mechanical testing protocols.
- Copolymers:Customized styrenic blends engineered for precise melt-flow indices and chemical resistance profiles. Drug delivery OEMs in the United States specify these grades for complex infusion pump geometries requiring tight dimensional tolerances.
- High Impact Polystyrene:Cost-effective rubber-modified polystyrene for non-critical disposable components with moderate durability requirements.
- Styrene Acrylonitrile:Transparent amorphous copolymer offering clarity and chemical resistance for optical diagnostic applications.
- Expanded Polystyrene:Cellular structure polymer for protective packaging and insulation in temperature-sensitive medical logistics.
The dominant share belongs to Acrylonitrile Butadiene Styrene, while Copolymers are closing the gap fastest.
Application:
Regulatory risk classification and sterilization frequency determine material specification stringency across medical use cases.
- Medical Devices:Reusable and single-use equipment requiring USP Class VI or ISO 10993 certified resins with gamma and autoclave sterilization resistance. FDA 21 CFR 177.1640 compliance anchors qualification protocols for housings and connectors in the United States.
- Drug Delivery Systems:Auto-injectors, infusion pumps, and inhaler components demanding precise melt-flow control and extractables profiles. Complex geometries in these devices drive specification of customized copolymer grades with narrow molecular weight distributions.
- Diagnostic Components:Optical cuvettes, test cartridge housings, and imaging equipment parts where clarity and dimensional stability intersect.
- Surgical Instruments:Handles and non-implantable tool components requiring sterilization durability and ergonomic surface finish.
- Laboratory Equipment:Pipette housings, centrifuge components, and benchtop analyzer casings with chemical resistance requirements.
Medical Devices commands the largest volume position, though Drug Delivery Systems is expanding most quickly.
End User:
Procurement scale and sterilization infrastructure capacity differentiate customer segments for styrenic polymer suppliers.
- Hospitals:Integrated delivery networks negotiating direct supply agreements with certified compounders for standardized device specifications. Midwestern US health systems with captive sterilization operations concentrate purchasing power.
- Diagnostic Laboratories:High-throughput testing facilities driving demand for optical-grade SAN in cuvettes and microplate components. Point-of-care diagnostic proliferation is reshaping volume patterns.
- Pharmaceutical Manufacturers:Drug companies specifying polymer grades for combination product packaging and delivery device integration.
- Clinics:Smaller-scale outpatient facilities with distributor-mediated purchasing for standard disposable device specifications.
- Research Institutions:Academic and contract research organizations with specialized small-batch requirements and flexible specification tolerance.
Hospitals retain procurement dominance, while Diagnostic Laboratories is gaining share fastest.
Form:
Processing method and supply chain configuration determine the physical presentation of medical-grade styrenics to device manufacturers.
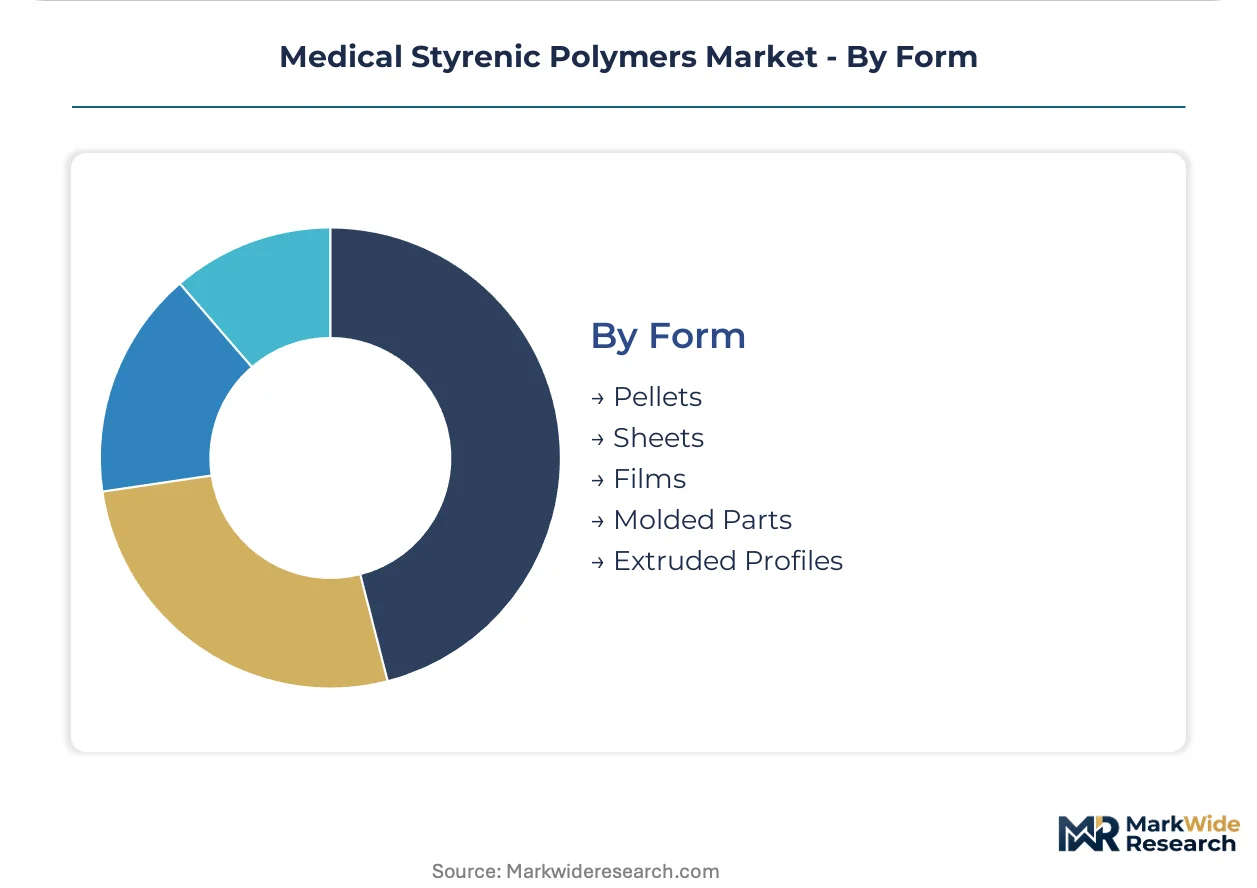
- Pellets:Standard injection molding and extrusion feedstock delivered in bulk to compounders and device manufacturers with in-house processing capabilities.
- Molded Parts:Finished components produced under ISO 13485 quality systems for direct device assembly, bypassing converter relationships.
- Sheets:Thermoforming substrate for tray and packaging applications requiring controlled thickness and surface quality.
- Films:Thin-gauge material for sterile barrier packaging and diagnostic test strip substrates.
- Extruded Profiles:Custom cross-sections for tubing connectors, gaskets, and structural framing in equipment enclosures.
Pellets maintains the dominant position, while Molded Parts is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical compounding capacity clusters in Germany, the United States, and China, with each geography developing distinct supply chain configurations around domestic device manufacturing ecosystems. FDA and EU MDR regulatory convergence is reshaping qualification protocols across these production hubs. Local certification requirements now determine market access more than feedstock proximity.
Germany
Baden-Württemberg's auto-injector manufacturers drive ABS demand for drop-resistant device housings under EU MDR mechanical testing protocols. REACH SVHC candidate list expansion forces reformulation of rubber-modified polystyrene grades to eliminate legacy plasticizers. Bavaria's diagnostic OEM cluster sustains localized SAN consumption for optical cuvette production.
United States
Midwestern integrated delivery networks negotiate direct supply agreements with certified compounders, bypassing traditional resin distributors. FDA enforces 21 CFR 177.1640 compliance for polystyrene food-contact polymers extending to medical applications. Greater Boston's drug delivery engineering firms specify customized copolymer grades for complex infusion pump geometries.
China
Domestic device manufacturing expansion creates demand for regional medical-grade polymer capacity under government localization initiatives. NMPA biocompatibility documentation requirements align with international standards while maintaining separate approval pathways. Yangtze River Delta injection molders are retrofitting standard production lines to medical-grade cleanroom standards.
Japan
PMDA scrutiny of material biocompatibility documentation intensifies for higher-risk device classes in the precision diagnostic segment. METI circular economy mandates incentivize mechanical recycling integration into healthcare plastics supply chains. Osaka-Kobe industrial corridor maintains specialized compounding lines for portable analyzer housings.
Switzerland
Swissmedic oversight of combination products drives polymer qualification rigor for drug-device integration applications. Precision molding subcontractors in the Lake Geneva region serve pharmaceutical manufacturers with ISO 13485-certified component supply. Basel's pharmaceutical cluster sources transparent SAN grades for diagnostic test cartridge production.
Medical Styrenic Polymers Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream where certification and formulation expertise create defensible positions. The vendor base organizes around three archetypes: integrated petrochemical majors with medical-dedicated production lines, specialized compounders with ISO 10993 testing protocols, and regional processors serving captive device manufacturing clusters. Consolidation pressure concentrates around certified compounders as EU MDR documentation requirements compress supplier qualification timelines. Dominant competitive moves include backward integration into styrene monomer supply and geographic expansion of medical compounding capacity into high-growth device manufacturing regions.
Within the integrated chemical major tier, BASF leverages European and Asian production sites to sustain supply security for healthcare clients. INEOS ABS Corporation anchors North American resin supply through specialized medical compounding lines. Trinseo S.A. occupies a position emphasizing transparency and color consistency for diagnostic component applications. These firms represent the certification-heavy segment where regulatory documentation capabilities differentiate market access.
| Leading Market Players |
|---|
| Evonik Industries |
| Americas Styrenics |
| BASF |
| Trinseo S.A. |
| Saudi Basic Industries Corporation |
| LG Chem |
| Styrolution Group |
| INEOS ABS Corporation |
| Covestro AG |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp barge freight corridors transmit benzene cost volatility directly into medical-grade ABS compound pricing, amplifying spreads between ISO 10993-certified premium tiers and standard industrial grades while rewarding suppliers with captive styrene monomer production.
Pricing Analysis
FDA 21 CFR 177.1640 compliance dictates the pricing tier structure across medical styrenic polymers, separating USP Class VI certified grades from food-contact baseline resins. Pricing stratifies across premium certified, standard medical, and economy industrial tiers based on extractables documentation depth and sterilization validation breadth. Cost compression in standard medical grades is intensifying because REACH SVHC-driven reformulation expenses are squeezing compounder margins without commensurate price recovery. Hospital procurement committees exhibit lowest price sensitivity for drug delivery system housings where liability exposure dominates material selection, while disposable diagnostic component buyers negotiate aggressively on volume contracts.
Supply Chain Analysis
Extended payment terms from German auto-injector OEMs to compounders are compressing working capital cycles and favoring integrated petrochemical majors with balance sheet capacity over specialized medical compounders. Feedstock supply concentrates in Germany, the United States, and China where dedicated medical compounding lines draw from regional styrene monomer production. Raw material dependencies encompass benzene derivatives, butadiene rubber modifiers, and acrylonitrile feedstocks. Single-source vulnerability pervades North American medical ABS supply where INEOS ABS Corporation anchors certified resin production. Distribution runs through direct compounder-OEM relationships for high-specification grades, with distributor channels persisting for standard medical formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated delivery network consolidation across Midwestern US health systems has shifted procurement leverage toward buyers with captive sterilization infrastructure, fragmenting historical distributor-mediated purchasing patterns and compressing supplier margins.
For Market Incumbents: Harden ISO 10993-18 testing documentation capabilities against emerging polycarbonate substitution threats in optical diagnostic applications. Deepen backward integration into styrene monomer supply to insulate margin structures from benzene-ethylene feedstock volatility. Expand medical compounding capacity into China's Yangtze River Delta device manufacturing cluster to capture localization-driven demand growth. For New Entrants and Emerging Players: Point-of-care diagnostic OEMs in Southeast Asia represent the most penetrable entry point given limited regional certified compounder presence and accelerating test cassette production. Drug delivery system miniaturization niches demanding customized copolymer melt-flow engineering offer technical differentiation avenues against commodity ABS suppliers. Pursue toll compounding partnerships with established ISO 13485 processors to bypass cleanroom capital expenditure barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized compounders with embedded regulatory documentation expertise over commodity resin producers facing margin compression. Long-term viability hinges on biocompatibility certification moats widening as EU MDR and FDA convergence intensifies testing protocol complexity. Watch for NMPA alignment with international biocompatibility standards as the signal indicating inflection toward China-domestic supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | Captive benzene-ethylene supply secures margin stability against feedstock volatility for German compounders. |
| ISO 10993-18 Testing Protocol Expansion | Extractables documentation capabilities differentiate qualified suppliers under tightening EU MDR scrutiny. |
| China Medical Compounding Capacity Buildout | Yangtze River Delta localization captures government-mandated domestic device manufacturing demand. |
| REACH SVHC Reformulation Investment | Elimination of legacy plasticizers from rubber-modified polystyrene preserves European market access. |
| Direct Hospital System Supply Agreements | Bypassing distributor channels captures consolidated procurement volume from Midwestern integrated delivery networks. |
Research Approach
Operator-level perspectives from medical device procurement managers, biomedical engineers at diagnostic OEMs, polymer compounding plant managers, and GPO contracts administrators anchored the qualitative base. Primary field engagement combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, SEC 10-K disclosures of listed chemical majors, and customs trade data tracking styrenic resin flows. Bottom-up demand modeling across drug delivery system geometries and top-down supply verification from regional production capacity data established analytical triangulation.
Scenario bracketing around regulatory convergence velocity and feedstock cost volatility framed the projection methodology across the analysis window. Segmentation dimensions encompassed product type tiers, application risk classifications, end-user procurement scale, and regional regulatory cluster variations. CAGRs derived from volume-weighted average growth rates across these segments, with drug delivery system miniaturization intensity and point-of-care diagnostic proliferation serving as primary demand elasticity inputs.
Practitioners should monitor EU MDR notified body review cycle durations and NMPA biocompatibility standard alignment progress for early signals of qualification timeline compression. Forecasts embed assumptions regarding regulatory documentation burden stability and styrene monomer supply concentration persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
PEKK Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Biobased Thermosetting Polymers Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Global Alpha Olefins Market