
 Europe Hydrocarbon Solvents Market | 2026-2036
Europe Hydrocarbon Solvents Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydrocarbon Solvents Market Intelligence
Specialized chemical engineering talent is bifurcating the competitive landscape as REACH complexity deepens. TotalEnergies leverages integrated refining and petrochemical platforms to secure feedstock flexibility across its European solvent network. Shell plc anchors its position through North Sea crude integration and proprietary hydroprocessing technology for high-purity isoparaffinic grades. Huntsman International LLC differentiates via specialty amine and polyurethane intermediates that require tightly specified solvent carriers.
Europe hydrocarbon solvents comprise refined petroleum distillates—aliphatic chains (C5–C12), aromatic rings (toluene, xylene), and naphthenic cycloparaffins—produced through catalytic reforming, hydrotreating, and fractional distillation, serving primarily as dissolution media, viscosity modifiers, and drying agents in industrial formulations. Aliphatic solvents lead volume consumption in paints and coatings applications where low odor and controlled evaporation profiles command formulation priority. Aromatic solvents retain entrenched demand in agrochemical emulsifiable concentrates despite sustained regulatory pressure on benzene-content thresholds. Isoparaffinic solvents represent the fastest-expanding product category as personal care and precision cleaning applications escalate requirements for ultra-low residue and negligible toxicity.
REACH registration obligations and the EU Green Deal carbon-border adjustment mechanism are reshaping import competitiveness and domestic production economics for solvent manufacturers. ECHA substance evaluation protocols and F-Gas Regulation phase-down schedules are accelerating reformulation investments toward lower-VOC and fluorine-free alternatives. Stakeholders must monitor bio-based feedstock certification schemes and cracker economics to align capacity planning with tightening Scope 3 disclosure requirements under CSRD-aligned supply chain mandates.
Market Dynamics
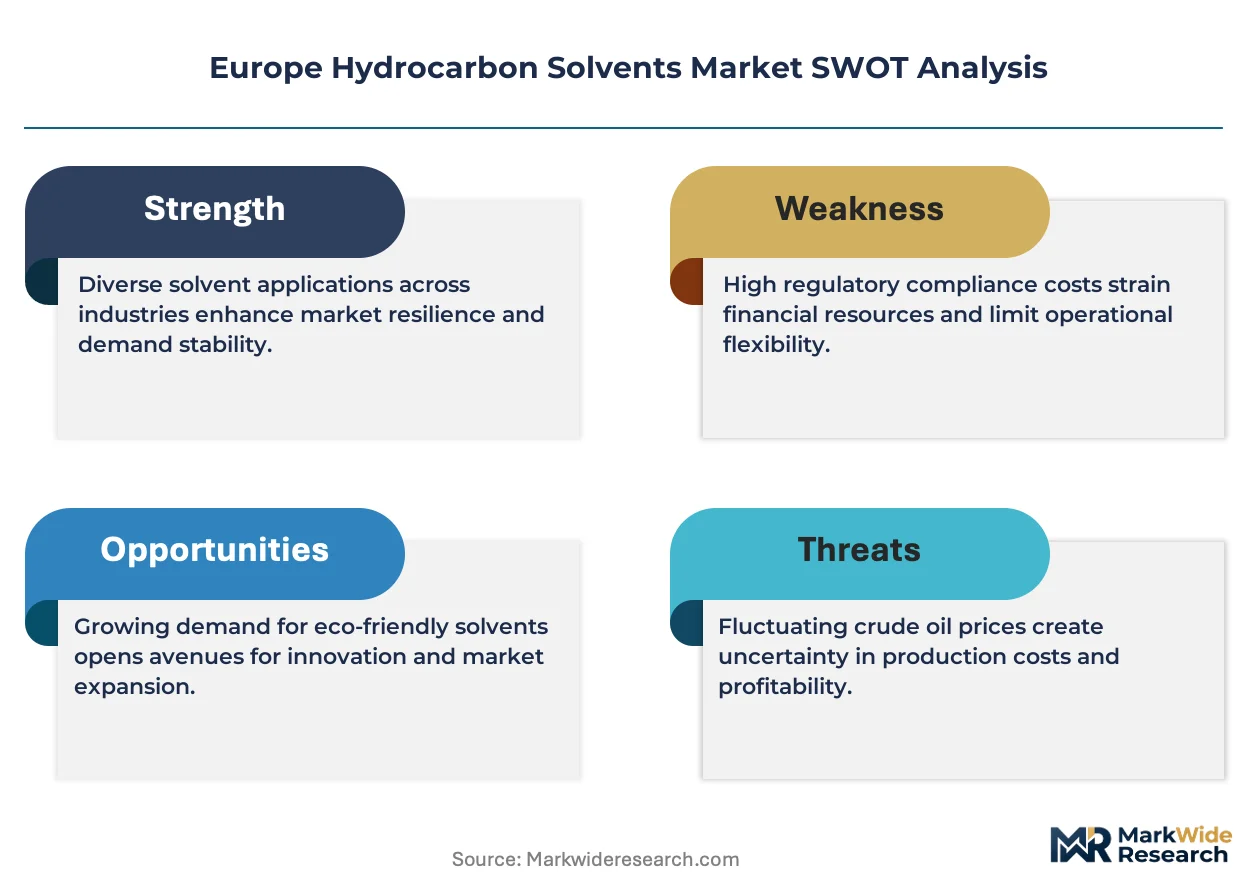
REACH registration obligations and the EU Green Deal carbon-border adjustment mechanism are compressing import competitiveness while forcing domestic solvent manufacturers toward bio-based feedstock certification and Scope 3 disclosure alignment.
Growth Catalysts
- Waterborne coating migration:Specialty paints and coatings manufacturers across Germany and France are expanding solvent procurement as formulation standards tighten. Low-aromatic aliphatic grades command priority in Northern European industrial clusters.
- REACH compliance deepening:ECHA substance evaluation protocols are accelerating reformulation investments toward lower-VOC alternatives. Domestic producers capture volume as import economics erode.
- Isoparaffinic solvent expansion:Personal care and precision cleaning applications escalate requirements for ultra-low residue and negligible toxicity. This product category redirects demand from traditional aromatic grades.
Market Restraints
- Crude feedstock volatility:North Sea crude price swings and refinery margin compression destabilize production economics for naphtha-derived solvents.
- Regulatory friction from F-Gas phase-down:The F-Gas Regulation schedule forces accelerated capital deployment into fluorine-free alternative development before revenue streams mature.
- Substitution threat from bio-based platforms:Terpene and ester solvent blends gain formulation share in agrochemical emulsifiable concentrates previously captive to aromatic hydrocarbons.
Strategic Opportunities
- CSRD-aligned supply chain mandates:Scope 3 disclosure requirements create first-mover advantage for solvent producers with certified bio-based feedstock traceability systems.
- Precision cleaning in Benelux electronics clusters:Semiconductor and advanced optics manufacturers in Eindhoven and Leuven seek ultra-high-purity isoparaffinic grades with sub-ppm residue specifications.
- Carbon-border adjustment arbitrage:Domestic European producers with integrated renewable energy sourcing can undercut import pricing as CBAM enforcement tightens.
Industry Challenges
- Specialized chemical engineering scarcity:REACH complexity and dual carbon goal compliance require talent pools in catalytic reforming process optimization and hydrotreating technology that remain thin across the continent.
- Retrofitting timeline compression:Existing solvent production assets face accelerated hydrotreater and fractionation tower upgrades to meet evolving ECHA purity thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydrocarbon Solvents Market |
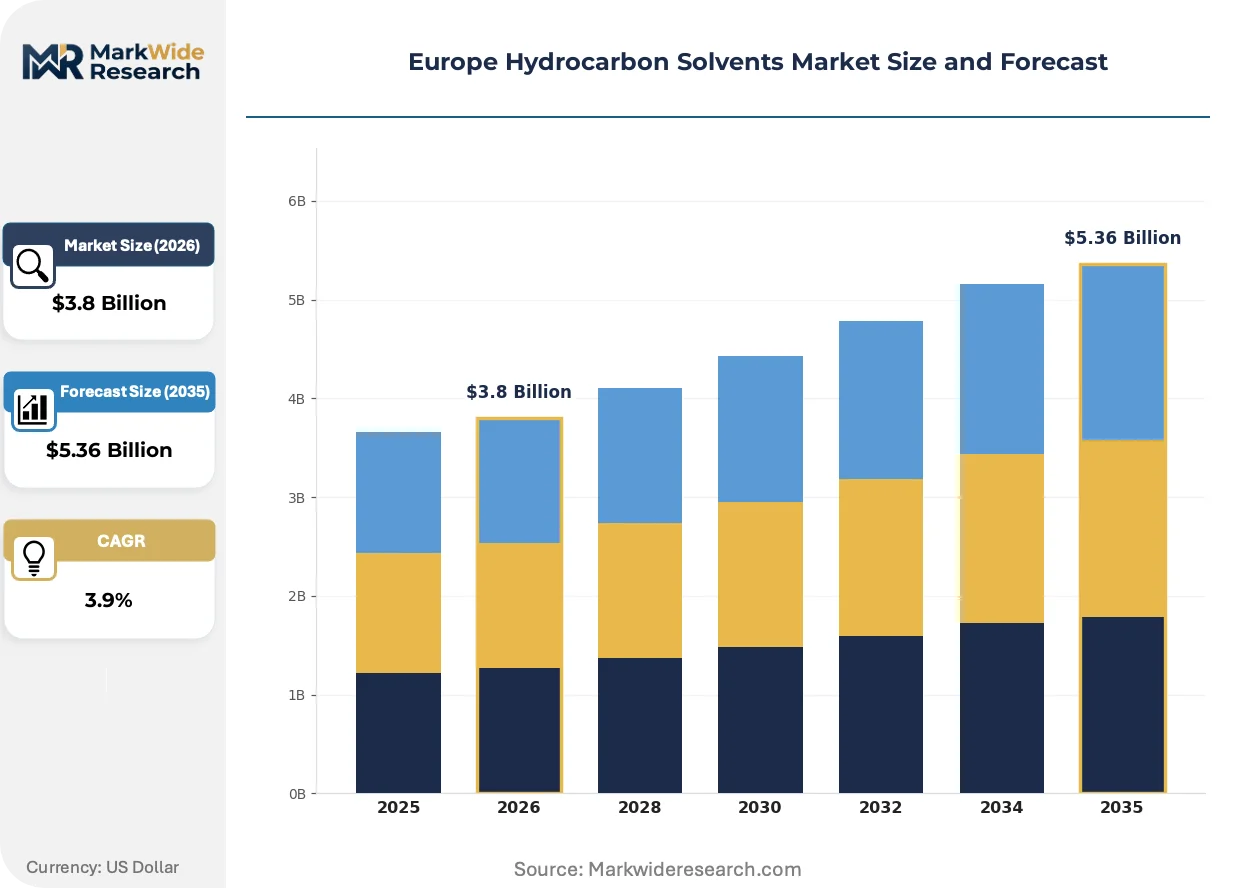
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.36 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aliphatic Solvents, Aromatic Solvents, Naphthenic Solvents, Isoparaffinic Solvents Application: Paints & Coatings, Adhesives & Sealants, Printing Inks, Agrochemicals, Cleaning Agents End User Industry: Pharmaceutical Manufacturing, Chemical Processing, Personal Care Products, Textile Finishing Packaging Type: Drums, Intermediate Bulk Containers, Bottles, Totes |
| Companies Covered | Exxon Mobil Corporation, TotalEnergies, Huntsman International LLC, Eastman Chemical Company, LyondellBasell Industries Holdings B.V., Honeywell International Inc., Ashland, Shell plc, Banner Chemicals Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydrocarbon Solvents Market Strategic Shifts & Innovations
Reformulation chemistry and feedstock provenance verification are diverging competitive capabilities across European solvent supply chains. Producers now compete on carbon intensity documentation and circular feedstock integration rather than commodity scale alone.
Membrane separation technology for solvent recovery and purification is fragmenting traditional distillation-dominated process economics. Specialty coatings manufacturers in the Netherlands and Belgium are piloting closed-loop solvent regeneration systems that reduce virgin material intake. This technology is fragmenting capital allocation patterns as mid-scale producers bypass large integrated refinery dependencies.
The EU Green Deal carbon-border adjustment mechanism tightens import competitiveness thresholds for solvent volumes sourced from non-EU refining centers. Domestic producers with renewable energy-integrated operations gain margin expansion room. Aromatic solvent categories face the steepest compliance cost escalation due to their energy-intensive hydrotreating requirements.
Buyers in automotive OEM coatings and industrial maintenance paints are consolidating supplier relationships around dual-certified partners meeting both REACH and CSRD disclosure standards. Long-term offtake agreements with embedded carbon accounting terms displace spot-market purchasing in Germany and France. This consolidation concentrates procurement decision authority among sustainability-linked sourcing functions at major formulation houses.
Europe Hydrocarbon Solvents Market Segmentation
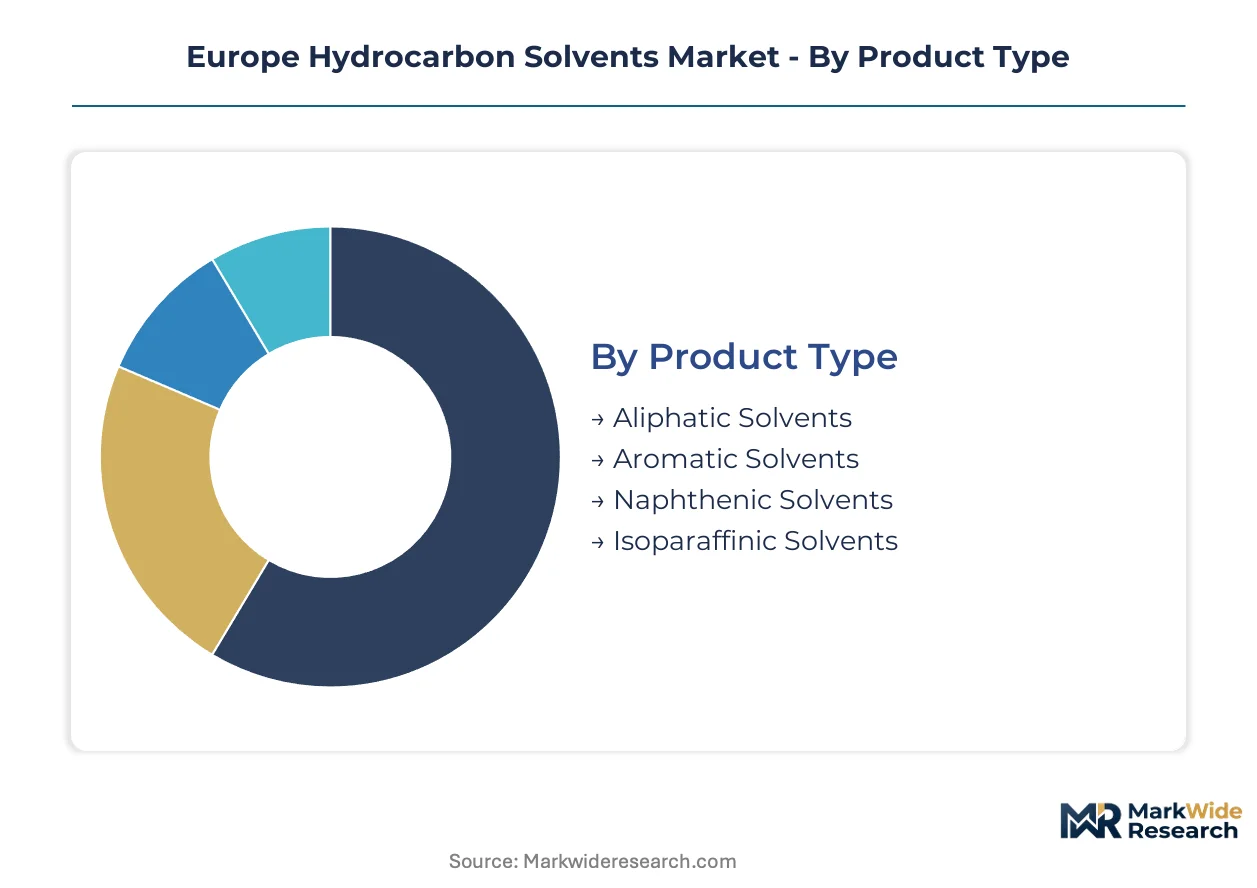
Hydrocarbon solvent demand fragments across formulation chemistry, end-use performance requirements, and supply chain logistics. Each segmentation axis reveals distinct competitive dynamics between integrated refiners and specialty distributors serving European industrial clusters.
Product Type:
Aliphatic and isoparaffinic grades dominate domestic production volumes, while aromatic solvents retain significant import dependency from Mediterranean refining centers.
- Aliphatic Solvents:Refined petroleum distillates with C5–C12 straight-chain and branched paraffins deliver low odor and controlled evaporation profiles. Paints and coatings formulators in Germany's Ruhr industrial belt specify these grades for REACH-compliant waterborne systems. Domestic hydrotreating capacity concentrates in Antwerp and Rotterdam clusters.
- Isoparaffinic Solvents:Highly refined isoparaffins with ultra-low aromatic content and sub-ppm residue specifications serve precision cleaning and personal care applications. Benelux electronics manufacturers in Eindhoven and Leuven drive specification escalation for semiconductor-grade purity.
- Aromatic Solvents:Toluene, xylene, and solvent naphtha fractions retain entrenched demand in agrochemical emulsifiable concentrates despite ECHA pressure on benzene-content thresholds.
- Naphthenic Solvents:Cycloparaffin-rich fractions from catalytic reforming provide high solvency power for industrial cleaning and metalworking applications.
Aliphatic solvents hold the largest share; momentum sits with isoparaffinic grades.
Application:
Coatings and adhesives procurement concentrates among large formulation houses, while agrochemical and cleaning applications fragment across mid-scale distributors.
- Paints & Coatings:Industrial maintenance and automotive OEM coatings represent the dominant volume sink, with specialty manufacturers across France and Germany consolidating supplier relationships around dual-certified partners.
- Agrochemicals:Emulsifiable concentrate formulations in Southern European agricultural belts sustain demand for high-solvency aromatic carriers despite bio-based substitution pressure.
- Adhesives & Sealants:Construction and automotive assembly applications favor fast-evaporating aliphatic grades with tailored viscosity profiles.
- Printing Inks:Publication gravure and flexible packaging segments specify narrow-cut aromatic fractions for pigment dispersion and drying control.
- Cleaning Agents:Precision electronics and industrial degreasing applications escalate purity requirements, redirecting volumes toward isoparaffinic substitutes.
Paints and coatings command the dominant position; agrochemicals face the steepest substitution threat.
End User Industry:
Pharmaceutical and personal care buyers prioritize certified bio-based traceability, while chemical processing and textile operations optimize for unit cost.
- Pharmaceutical Manufacturing:API synthesis and extraction processes require pharmaceutical-grade solvents with comprehensive EMA documentation and batch-level impurity profiling.
- Personal Care Products:Cosmetics and fragrance formulators in France's Grasse region drive demand for ultra-low residue isoparaffins with negligible toxicity profiles.
- Chemical Processing:Intermediate synthesis and reaction media applications consume bulk aliphatic volumes with specification flexibility.
- Textile Finishing:Dye carrier and dry-cleaning applications in Northern Italian industrial districts sustain naphthenic solvent demand.
Chemical processing absorbs the greatest volume; personal care products are expanding most quickly.
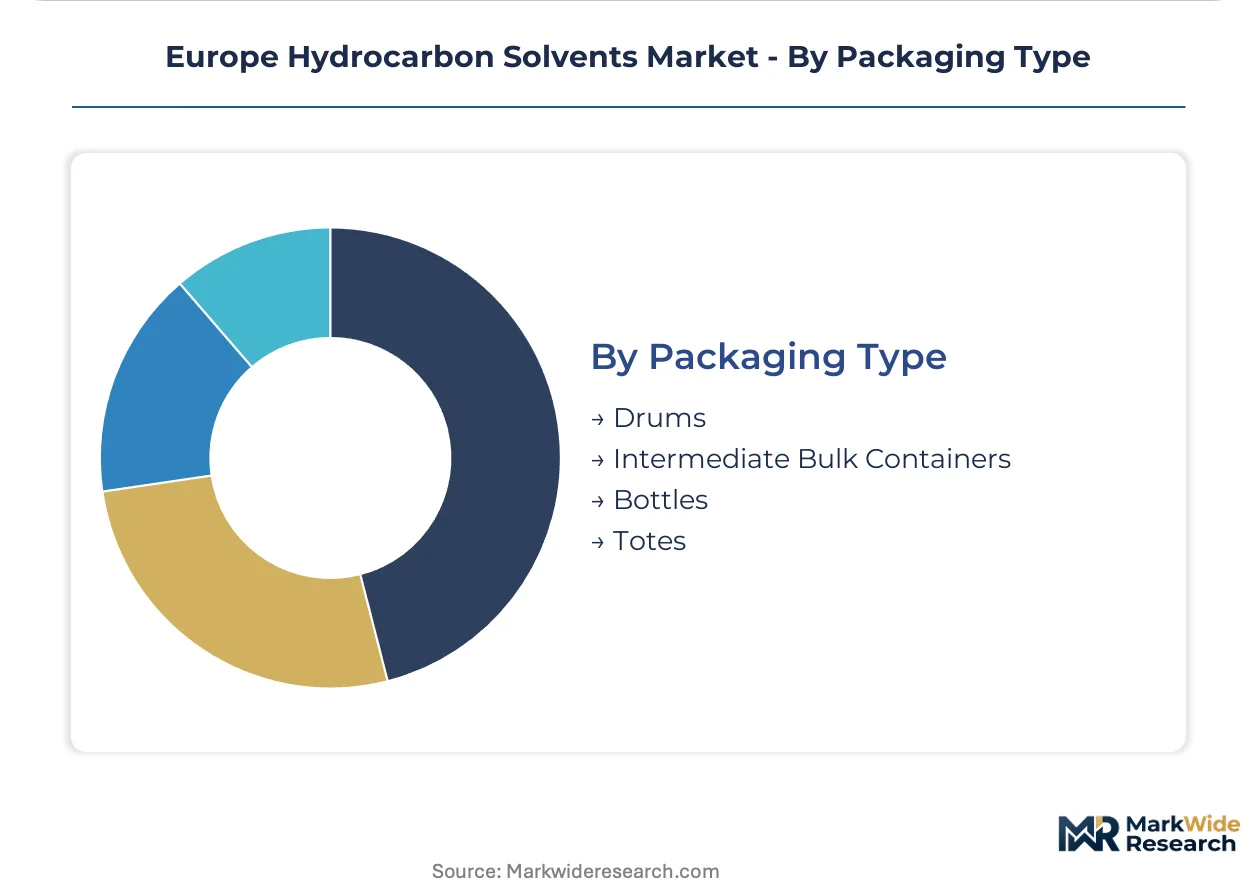
Packaging Type:
Drum and IBC formats serve fragmented distributor networks, while totes and bottles align with direct supply contracts to large formulation houses.
- Drums:Standard 200-liter steel drums remain the workhorse format for mid-volume industrial procurement across European manufacturing clusters.
- Intermediate Bulk Containers:1000-liter IBC totes reduce handling costs for adhesives and coatings manufacturers with steady consumption patterns.
- Totes:Flexible and rigid intermediate bulk formats serve just-in-time delivery requirements for automotive OEM coating lines.
- Bottles:Laboratory and pilot-scale applications in pharmaceutical R&D facilities require amber glass and fluoropolymer-lined containers.
Drums retain the largest installed base; IBC formats are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German solvent producers command pricing premiums over Mediterranean imports as REACH compliance costs widen the cost-quality spread across European refining clusters.
Germany
Ruhr industrial belt coatings manufacturers drive aliphatic solvent procurement for waterborne formulation systems. The Federal Environment Agency enforces strict VOC limits under the 31st Federal Immission Control Ordinance. Antwerp-Rotterdam pipeline connectivity secures feedstock flexibility for Cologne-area hydrotreating facilities.
France
Grasse region fragrance houses escalate isoparaffinic solvent specifications for personal care applications. ANSM oversees pharmaceutical-grade solvent certification under EU GMP frameworks. Lyon-based specialty chemical distributors consolidate procurement around dual-certified supply partners.
Netherlands
Eindhoven semiconductor fabs demand sub-ppm residue isoparaffins for precision wafer cleaning. The National Institute for Public Health and the Environment coordinates REACH enforcement with ECHA protocols. Rotterdam refining clusters anchor Northwest European solvent distribution logistics.
Belgium
Leuven optics manufacturers source ultra-high-purity grades for advanced lens manufacturing. Federal Public Service Health enforces chemical substance registration aligned with EU Green Deal timelines. Antwerp petrochemical complexes integrate renewable energy sourcing for carbon-border adjustment compliance.
Italy
Northern Italian textile finishers sustain naphthenic solvent consumption for dye carrier applications. The Ministry of Environment implements national REACH coordination through the National Chemicals Center. Milan industrial districts face accelerating bio-based substitution pressure from agrochemical formulators.
Europe Hydrocarbon Solvents Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the European solvent supply base. Integrated petrochemical majors leverage refinery-solvent integration for feedstock security, while specialty distributors compete on formulation technical service and certified bio-based sourcing. The market structure divides between hydrotreating-integrated producers and independent blenders serving fragmented industrial accounts. Dominant competitive moves include capacity rationalization at legacy aromatic solvent units and strategic partnerships with coatings formulators for long-term offtake agreements.
Among integrated petrochemical groups, TotalEnergies, Shell plc, and Exxon Mobil Corporation occupy positions spanning the technology-cost spectrum. TotalEnergies exemplifies the integrated refinery-petrochemical archetype with North Sea crude access. Shell plc anchors the high-purity isoparaffinic segment through proprietary hydroprocessing positions. Exxon Mobil Corporation represents the scale-driven multinational with global feedstock arbitrage capabilities serving European formulation houses.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| TotalEnergies |
| Huntsman International LLC |
| Eastman Chemical Company |
| LyondellBasell Industries Holdings B.V. |
| Honeywell International Inc. |
| Ashland |
| Shell plc |
| Banner Chemicals Limited |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements with embedded carbon accounting terms lock in both supply access and price visibility for coatings formulators across Germany and France. These contracts insulate procurement teams from spot-market volatility while satisfying CSRD-aligned disclosure mandates from downstream customers.
Pricing Analysis
Antwerp-Rotterdam corridor producers command pricing premiums over Mediterranean imports as REACH compliance costs widen spreads across European refining clusters. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and technical-grade levels reflects certification investment and hydrotreating intensity. Cost compression in aromatic solvent tiers is intensifying because energy-intensive hydrotreating requirements escalate under EU Green Deal timelines. Mid-scale distributors serving fragmented industrial accounts exhibit highest price sensitivity, while pharmaceutical and personal care buyers prioritize certified bio-based traceability over unit economics.
Supply Chain Analysis
Belgium and the Netherlands anchor Northwest European solvent production through Antwerp and Rotterdam refining clusters integrated with North Sea crude access. Catalytic reforming units, hydrotreating reactors, and fractional distillation towers draw from naphtha feedstocks sourced via pipeline networks. Single-source vulnerability concentrates in specialty isoparaffinic grades where proprietary hydroprocessing technology limits qualified suppliers. Distribution runs through Rotterdam tank terminals serving drum, IBC, and bulk tanker formats to formulation houses across the Ruhr industrial belt and Northern French manufacturing districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based terpene and ester solvent blends are accelerating substitution pressure on aromatic hydrocarbon incumbents. Defending market position requires strategic repositioning around certification barriers and carbon-border compliance.
For Market Incumbents: Fortify hydrotreating-integrated positions through backward integration into renewable energy sourcing for carbon-border adjustment compliance. Secure long-term offtake agreements with coatings formulators embedding Scope 3 disclosure terms to lock out bio-based substitutes. Invest in catalytic reforming process optimization talent pools that remain scarce across the continent. For New Entrants and Emerging Players: EU bio-based feedstock certification fast-tracks offer entry pathways into personal care and pharmaceutical-grade segments where incumbents lack traceability systems. Target precision cleaning applications in Benelux electronics clusters demanding sub-ppm residue specifications that integrated refiners underinvest in. Pursue white-label partnerships with mid-scale distributors serving fragmented industrial accounts across Northern Italy. For Investors and Strategic Acquirers: Capital is best deployed toward specialty isoparaffinic producers with proprietary hydroprocessing technology and established EMA documentation pathways. Long-term viability hinges on differentiation from commodity aliphatic grades facing margin compression. Monitor F-Gas Regulation phase-down schedules as inflection indicators for fluorine-free alternative development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Energy | Antwerp and Rotterdam producers gain carbon-border adjustment arbitrage against Mediterranean imports. |
| Long-term Supply Agreement with Embedded Carbon Terms | German coatings formulators consolidate procurement around dual-certified REACH and CSRD partners. |
| Capacity Expansion in Isoparaffinic Grades | Eindhoven and Leuven semiconductor fabs require ultra-high-purity solvents with sub-ppm residue specifications. |
| Green Manufacturing Transition via Bio-based Certification | Grasse region fragrance houses escalate demand for ultra-low residue grades with negligible toxicity profiles. |
| Joint Venture for Closed-loop Solvent Regeneration | Dutch specialty coatings manufacturers pilot systems reducing virgin material intake across Benelux clusters. |
Research Approach
The analysis maps aliphatic, isoparaffinic, aromatic, and naphthenic solvent sub-sectors, each validated through plant managers at Antwerp and Rotterdam refining complexes, procurement leads at German coatings formulators, distribution channel partners serving Northern Italian industrial districts, and technical R&D directors at personal care manufacturers. Primary interview insights triangulate against customs and trade data from Eurostat, Cefic industry reports, ECHA substance registration databases, and SEC 10-K filings from integrated petrochemical majors. Bottom-up volume modeling across grade tiers, end-use industries, packaging formats, and regional production hubs reconciles with top-down market sizing.
Consistency checks validate volume and value outputs against external benchmarks including refinery utilization rates, downstream coatings production indices, and agrochemical formulation activity across Southern European agricultural belts. The analytical framework segments demand across the projection horizon by product chemistry, application performance requirements, and supply chain logistics configurations. CAGRs derive from regression analysis of historical consumption patterns adjusted for regulatory phase-in schedules, feedstock cost trajectories, and substitution elasticity parameters. Industry-specific inputs include ECHA substance evaluation timelines, cracker economics for naphtha-derived feedstocks, and bio-based certification penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement intensity and gradual CBAM implementation; material deviation in regulatory timelines or crude price volatility would warrant model refresh. Recalibration cycles align with material shifts in ECHA substance evaluation protocols, F-Gas Regulation phase-down milestones, and EU Green Deal carbon-border adjustment enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Nitroglycerin Market
Solvents
Monochlorobenzene Market
Solvents
India High Purity Solvents Market
Solvents
Diethyl Ether Market
Solvents
Decanol Market
Solvents
Global Solvent Evaporation Market
Solvents
Meta-Xylene Market
Solvents
Aliphatic Hydrocarbon Solvents and Thinners Market
Solvents
Dimethyl Sulfoxide Market
Solvents
Methyl Acetate Market
Solvents
Global Glycol Market
Solvents
Mono Propylene Glycol Market
Solvents
Global Solvents Market
Solvents
Oxygenated Solvents Market
Solvents
Phenol Derivatives Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market