
 Intrauterine Devices (IUD) Market | 2026-2036
Intrauterine Devices (IUD) Market Size, Share, and Industry Trends Forecast 2026-2036
Intrauterine Devices (IUD) Market Intelligence
Copper wire is expanding its role in non-hormonal IUD construction as manufacturers seek alternatives to hormone-linked side effects and supply chain dependencies. Bayer AG leverages polymer engineering expertise to sustain premium positioning across European clinical channels. CooperSurgical anchors its presence through deep integration with gynecological practice networks and specialized training infrastructure.
An intrauterine device is a small, T-shaped contraceptive implant inserted into the uterus, typically constructed from polyethylene frames with copper wire wrapping or hormone-eluting reservoirs that release levonorgestrel locally over three to ten years to prevent fertilization or implantation. Hormonal IUDs dominate value generation due to superior amenorrhea rates and extended replacement intervals that reduce total cost of ownership for payers. Copper IUDs compete aggressively on upfront affordability and absence of systemic hormonal effects, particularly across public health procurement channels in lower-middle-income settings where family planning centers serve as primary access points.
FDA premarket notification pathways and EMA contraceptive device directives shape clinical trial requirements and post-market surveillance obligations that determine market entry timelines. BIS certification mandates in India and CDSCO quality specifications for copper purity and tensile strength govern domestic manufacturing eligibility and public tender participation. Stakeholders must monitor evolving reimbursement classifications for long-acting reversible contraceptives as health technology assessment bodies recalibrate cost-effectiveness thresholds against newer fertility management modalities.
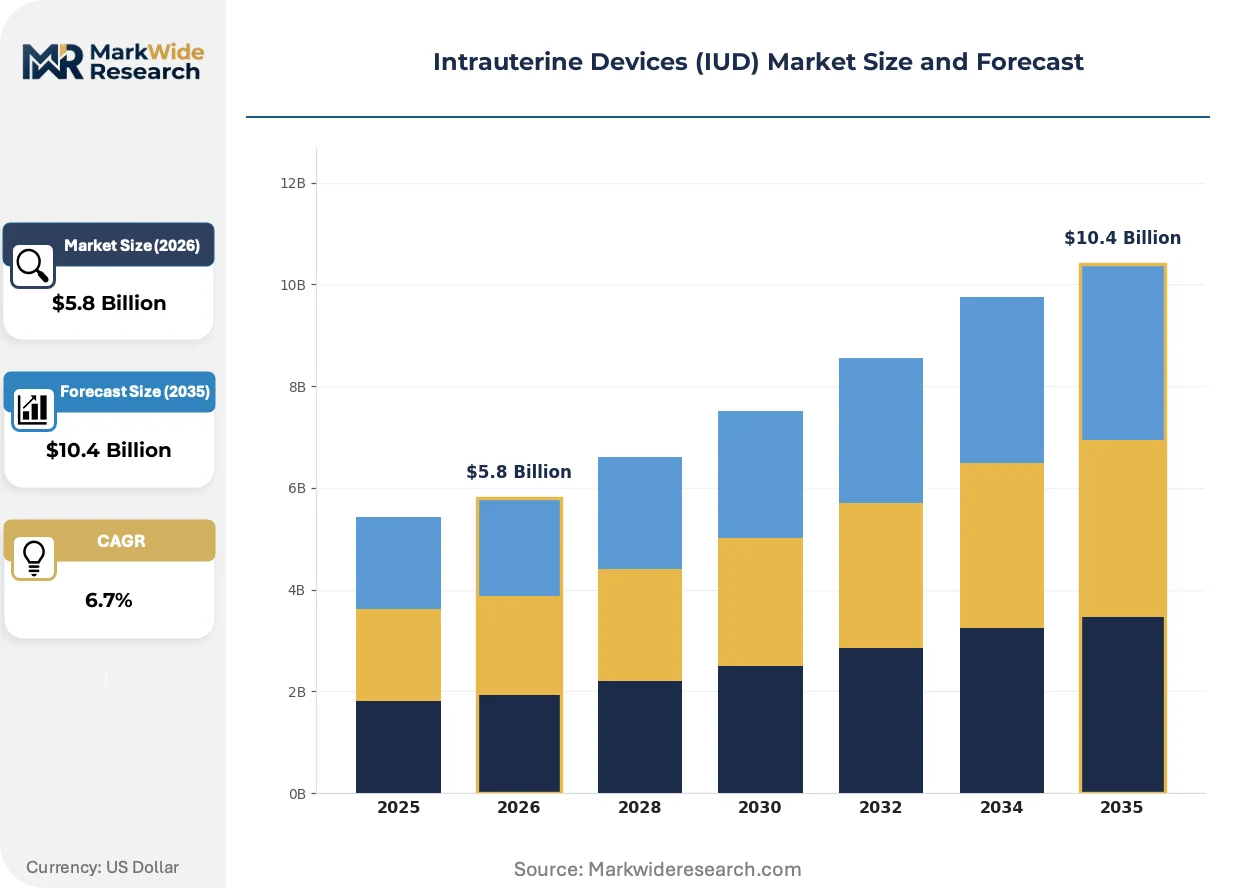
Market Dynamics
EMA contraceptive efficacy standards and BIS copper purity mandates are restructuring competitive access across European and Indian procurement channels, privileging manufacturers with integrated polymer engineering and metallurgical certification capabilities.
Growth Catalysts
- Copper wire substitution:Non-hormonal device demand accelerates as family planning centers in India prioritize BIS-certified copper IUDs through government procurement programs.
- Extended replacement intervals:Hormonal reservoir technology reduces total cost of ownership for payers across Germany, France, and the United Kingdom.
- Levonorgestrel localization:Sustained-release polymer matrices improve amenorrhea rates in clinical settings governed by EMA post-market surveillance obligations.
Market Restraints
- Copper price volatility:Raw material cost swings in commodity markets compress margins for manufacturers dependent on high-purity copper wire sourcing.
- Supply concentration:Polymer frame production clusters among specialized medical device converters in Western Europe, creating single-source vulnerabilities.
- FDA premarket pathways:Extended clinical trial timelines for novel hormone-eluting reservoirs delay market entry for non-incumbent developers.
Strategic Opportunities
- Underpenetrated Indian states:Bihar, Uttar Pradesh, and Rajasthan present expansion potential as CDSCO quality specifications enable domestic manufacturing eligibility for public tenders.
- Telemedicine integration:Remote consultation platforms are reducing geographic barriers to IUD insertion services in rural United Kingdom primary care networks.
- PLI scheme alignment:India's production-linked incentive framework for medical devices subsidizes capital expenditure for copper IUD assembly lines meeting BIS tensile strength standards.
Industry Challenges
- Gynecological training infrastructure:Insertion technique certification bottlenecks limit provider capacity expansion in high-volume public health systems.
- Legacy sterilization validation:Ethylene oxide residue testing protocols add 8-12 weeks to batch release timelines for polyethylene frame components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrauterine Devices (IUD) Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.4 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper IUD, Hormonal IUD, Silver IUD, Multi-load IUD Delivery Mode: Transcervical, Intrauterine, Non-surgical, Surgical End User: Clinics, Hospitals, Family Planning Centers, Gynecological Practices Application: Contraception, Menstrual Regulation, Endometrial Protection, Fertility Regulation |
| Companies Covered | Bayer AG, AbbVie Inc., CooperSurgical Inc., Pregna International Limited, DKT International, SMB Corporation, Mona Lisa N.V., Prosan International BV, HLL Lifecare Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrauterine Devices (IUD) Market Strategic Shifts & Innovations
Bioresorbable polymer research and digital fertility tracking integration are disrupting traditional device design paradigms, while regulatory convergence across FDA and EMA frameworks accelerates approval pathway standardization.
Copper-nickel alloy wire is converging with traditional pure copper construction as manufacturers optimize tensile strength and corrosion resistance for extended 10-year device lifespans. Family planning centers in lower-middle-income settings are adopting these hybrid materials at accelerated procurement cycles. This metallurgical shift is converging with cost-engineering imperatives to compress unit economics for public tender participation.
EU MDR recast requirements for Class III contraceptive devices impose enhanced clinical evidence standards and post-market clinical follow-up obligations. Manufacturers must now maintain active implant registries across multiple member states. Hormonal IUD segments face the steepest compliance burden as EMA demands real-world safety data on levonorgestrel systemic absorption profiles.
Direct-to-clinic procurement models are displacing traditional distributor intermediaries in European gynecological practice networks. Specialized buying groups in France and Germany negotiate frame-plus-reservoir bundles with manufacturers holding EMA quality management system certification. This channel consolidation is most visible in the United Kingdom, where NHS Integrated Care Boards centralize long-acting reversible contraceptive purchasing decisions.
Intrauterine Devices (IUD) Market Segmentation
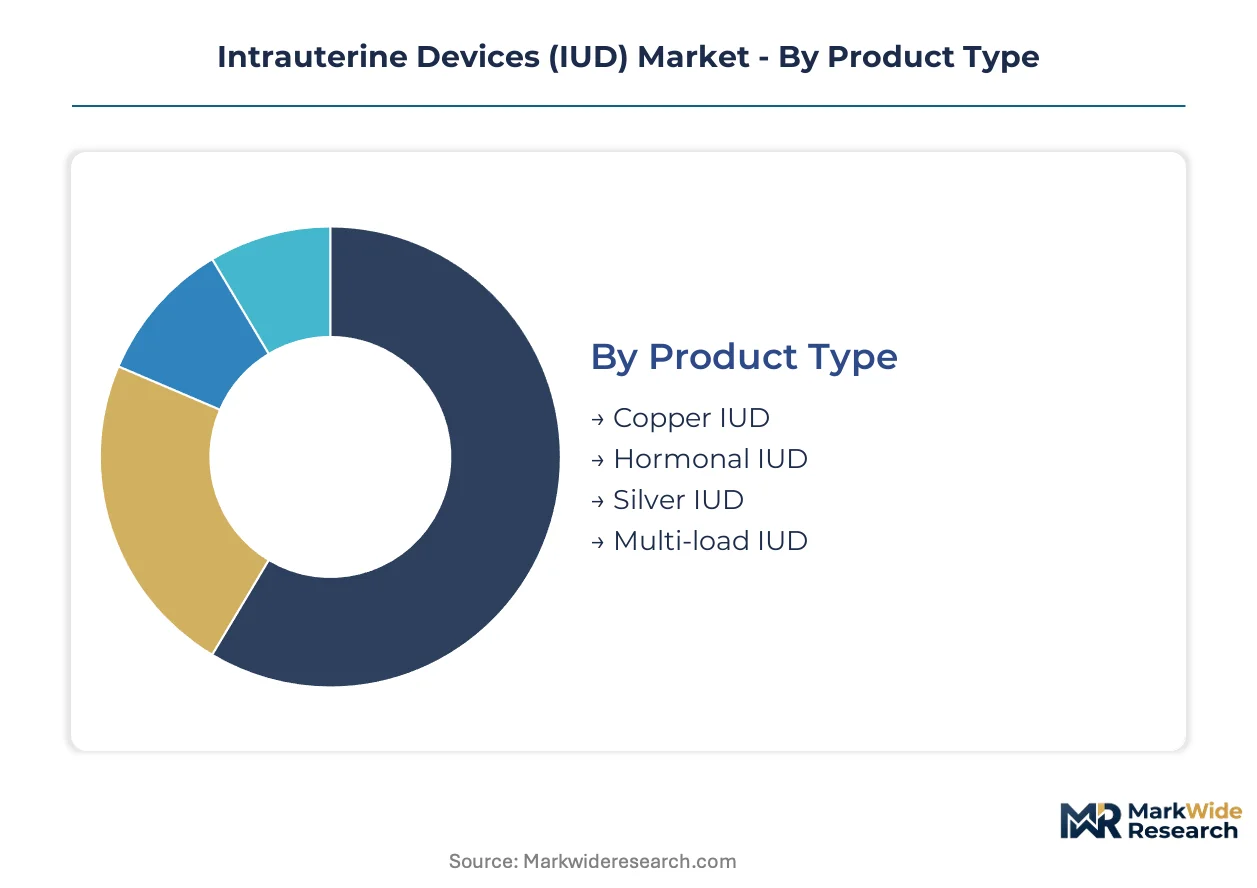
Segmentation in the IUD market reveals how regulatory pathways and clinical settings reshape competitive access. Certification requirements vary sharply across product categories, with hormonal reservoirs facing EMA post-market surveillance while copper variants navigate BIS tensile strength mandates.
Product Type:
EMA contraceptive efficacy standards and BIS copper purity certifications impose divergent compliance burdens across this category, privileging manufacturers with integrated metallurgical or polymer engineering capabilities.
- Hormonal IUD:Polyethylene frames incorporate levonorgestrel-eluting reservoirs that release hormone locally over three to ten years. Demand concentrates in Germany, France, and the United Kingdom where EMA post-market surveillance obligations and superior amenorrhea rates drive clinical preference among gynecological practices.
- Copper IUD:T-shaped polyethylene structures wrapped with high-purity copper wire create a spermicidal environment through ion release. Family planning centers in India prioritize BIS-certified variants through government procurement programs, prioritizing upfront affordability and absence of systemic hormonal effects.
- Silver IUD:Copper-silver alloy construction targets extended corrosion resistance for 10-year device lifespans.
- Multi-load IUD:Enhanced frame geometry with multiple copper wire loads for intensified local contraceptive effect.
Hormonal IUD sits at the top of the volume ranking, with Copper IUD climbing the fastest.
Delivery Mode:
Cost tier differentiation separates office-based insertion from surgical suite requirements, with reimbursement classifications determining channel economics across European and Indian health systems.
- Transcervical:Standard insertion technique through cervical canal without surgical incision, performed in outpatient settings. Gynecological practices in France and Germany favor this mode for same-day discharge protocols under EMA quality management system certification.
- Intrauterine:Direct uterine cavity placement using specialized inserters with depth-gauging mechanisms. Family planning centers across Bihar, Uttar Pradesh, and Rajasthan deploy this mode for high-volume public health campaigns meeting CDSCO specifications.
- Non-surgical:Minimally invasive placement avoiding operative theater overhead and anesthesia costs.
- Surgical:Operating room-based insertion for complex anatomical presentations or concurrent procedures.
Transcervical dominates procedure volume, while Non-surgical gains share fastest through telemedicine-integrated remote consultation platforms.
End User:
Customer type fragmentation across public procurement channels and private clinical networks creates divergent pricing and service bundling requirements.
- Family Planning Centers:Government-funded facilities serving as primary access points in lower-middle-income settings. India's BIS quality mandates and PLI scheme subsidies enable domestic manufacturing eligibility for public tenders across underpenetrated states.
- Gynecological Practices:Specialized private clinics in France and Germany negotiating frame-plus-reservoir bundles through direct-to-clinic procurement models. EMA MDR recast requirements for Class III devices impose enhanced clinical evidence standards and active implant registry maintenance.
- Clinics:General outpatient facilities with basic insertion capability and limited follow-up infrastructure.
- Hospitals:Tertiary centers managing complex cases and complication referrals with full surgical backup.
Family Planning Centers anchor volume through procurement scale, with Gynecological Practices expanding most quickly via channel consolidation.
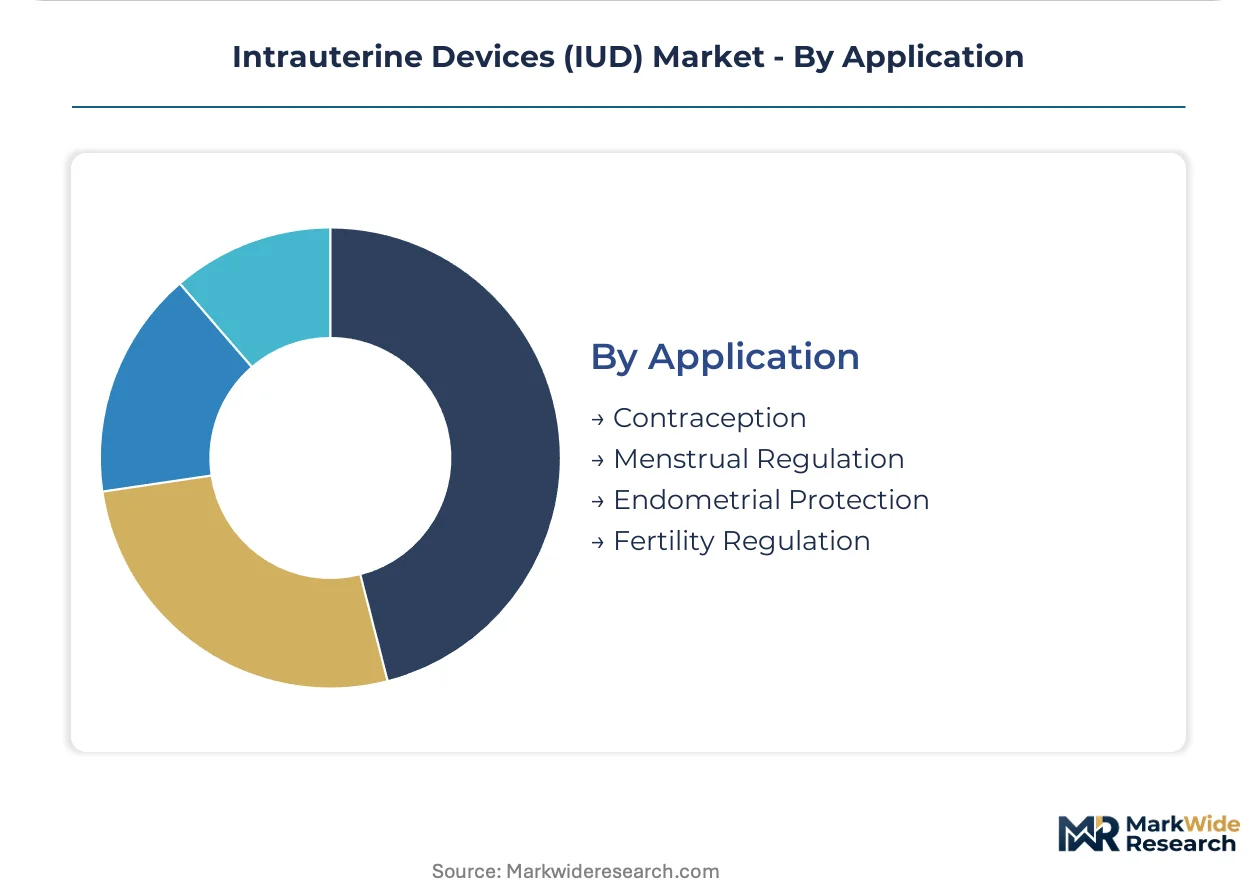
Application:
Volume concentration in contraceptive indications contrasts with emerging clinical utility in menstrual and endometrial management, reshaping prescriber training priorities.
- Contraception:Primary indication preventing fertilization or implantation through local copper ion toxicity or hormonal suppression. NHS Integrated Care Boards in the United Kingdom centralize long-acting reversible contraceptive purchasing decisions for this application.
- Menstrual Regulation:Levonorgestrel-eluting devices reduce bleeding intensity and frequency. EMA demands real-world safety data on systemic absorption profiles for this expanding indication across German and French clinical networks.
- Endometrial Protection:Hormonal suppression of endometrial proliferation for high-risk patient populations.
- Fertility Regulation:Interval contraception with rapid return to fertility following removal.
Contraception holds the volume base, while Menstrual Regulation shows the steepest expansion trajectory as prescriber awareness spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's family planning infrastructure anchors procurement volume for copper IUD variants, while EMA-governed European markets concentrate hormonal device demand across specialized gynecological networks.
India
Bihar, Uttar Pradesh, and Rajasthan drive copper IUD volume through government family planning programs. BIS certification mandates and CDSCO quality specifications for copper purity enable domestic manufacturers to compete for public tenders. PLI scheme subsidies support assembly line investments in manufacturing clusters near Delhi-NCR and Maharashtra.
Germany
Gynecological practices in Bavaria and North Rhine-Westphalia prioritize hormonal IUDs with extended replacement intervals. EMA MDR recast requirements for Class III devices impose active implant registry obligations. Specialized buying groups in Frankfurt and Munich negotiate direct-to-clinic procurement bundles.
France
Île-de-France and Auvergne-Rhône-Alpes concentrate demand for levonorgestrel-eluting devices among private clinical networks. ANSM post-market surveillance protocols align with EMA contraceptive efficacy standards. Lyon-based polymer engineering facilities supply frame components to device assemblers.
United Kingdom
NHS Integrated Care Boards centralize long-acting reversible contraceptive purchasing across England and Scotland. Telemedicine-integrated remote consultation platforms expand access in rural primary care networks. London and Manchester anchor gynecological training infrastructure for insertion technique certification.
United States
FDA premarket notification pathways shape clinical trial timelines for novel hormone-eluting reservoirs. Texas and California host the largest concentrations of family planning centers and gynecological practices. Regional health systems negotiate value-based contracts for device procurement.
Intrauterine Devices (IUD) Market Key Industry Players
Global majors compete with regional champions across certification capabilities and procurement channel access. The vendor base separates into integrated polymer-metallurgy specialists, pure-play copper wire fabricators, and hormonal reservoir technology holders. Three archetypes dominate: EMA-certified European incumbents, BIS-certified Indian domestic producers, and FDA-cleared North American innovators. Competitive moves concentrate on direct-to-clinic channel consolidation and backward integration into polymer frame production.
Within the integrated specialist tier, Bayer AG exemplifies polymer engineering capabilities sustaining premium positioning, while CooperSurgical occupies a position anchored through gynecological practice network integration. Among Asia-Pacific manufacturers, Pregna International Limited represents the BIS-certified domestic producer archetype competing for Indian public tenders. These three entities illustrate how certification geography and channel depth separate competitive positions.
| Leading Market Players |
|---|
| Bayer AG |
| AbbVie Inc. |
| CooperSurgical Inc. |
| Pregna International Limited |
| DKT International |
| SMB Corporation |
| Mona Lisa N.V. |
| Prosan International BV |
| HLL Lifecare Limited |
| Others |
Cost & Logistics Intelligence
Polymer engineering specialists in Western Germany command wage premiums that compress standard-tier margins while amplifying spread between EMA-certified hormonal reservoirs and BIS-grade copper alternatives. Labor-cost differentials between European metallurgical certification hubs and Indian domestic assembly clusters directly determine three-tier pricing stratification across procurement channels.
Pricing Analysis
Input-cost pass-through from high-purity copper wire and specialized polyethylene frame resins shapes transactional per-unit pricing across certification tiers. Price differentiation separates EMA-registered hormonal devices with active implant registries from BIS-certified copper variants and unbundled economy-grade alternatives. Pricing pressure stems from copper commodity volatility and compressed public tender budgets in Indian family planning programs. Family planning centers in lower-middle-income settings exhibit highest price sensitivity, while gynecological practices in Germany and France prioritize clinical performance over unit cost.
Supply Chain Analysis
High-purity copper wire supply rests on Chilean mining output and German metallurgical refinement capacity, with polymer frame production concentrated in Belgium, France, and Western Germany. Raw material dependencies include copper cathode, medical-grade polyethylene, and levonorgestrel API. Single-source vulnerability pervades specialized inserter mechanism manufacturing clustered in Italian precision engineering facilities. Distribution runs through direct-to-clinic procurement models displacing traditional distributor networks across European gynecological practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
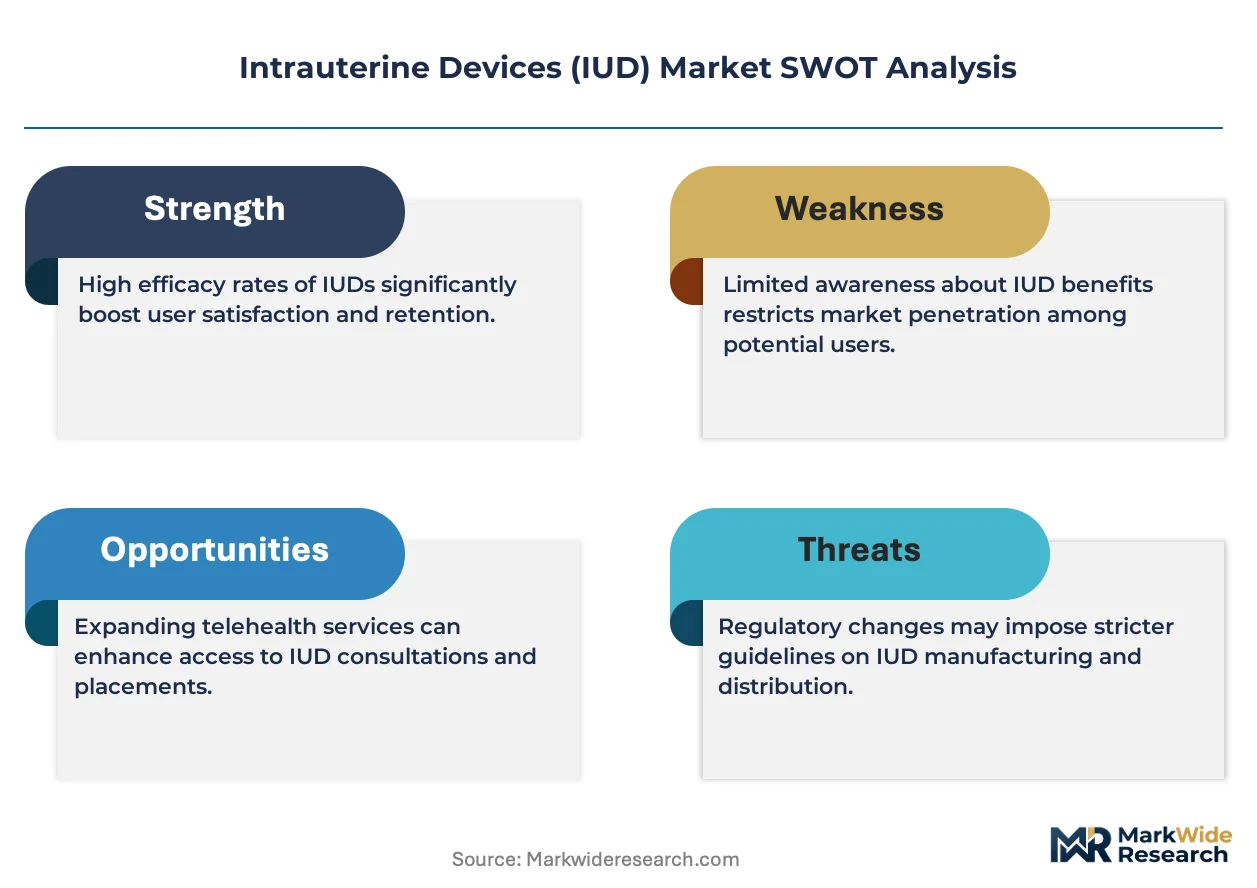
The IUD market functions as a stable compounder anchored by replacement-cycle revenue from extended-duration devices and recurring public procurement commitments. Government family planning program budgets provide predictable demand baselines resistant to cyclical downturns.
For Market Incumbents: Extend EMA MDR recast compliance lead time into exclusive direct-to-clinic contracting with NHS Integrated Care Boards and German buying groups. Deepen backward integration into polymer frame production to offset polyethylene resin cost volatility and neutralize emerging Asian converter competition.
For New Entrants and Emerging Players: Capture underpenetrated Indian states—Bihar, Uttar Pradesh, Rajasthan—through PLI scheme-aligned domestic manufacturing and CDSCO-certified copper IUD assembly. Prioritize telemedicine-integrated insertion training partnerships with rural primary care networks as differentiated market entry channel.
For Investors and Strategic Acquirers: Specialized gynecological device platforms are the most active acquirer in this space, seeking hormonal reservoir technology and EMA quality management system certification assets. Five-to-ten year viability hinges on EU MDR recast compliance completion and active implant registry infrastructure. Monitor BIS certification approval velocity in Indian domestic manufacturers as inflection indicator for public tender competitiveness shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Recast Compliance Investment | Active implant registry infrastructure satisfies Class III device post-market surveillance obligations across Germany and France. |
| Backward Integration into Polymer Frame Production | In-house polyethylene component manufacturing reduces single-source dependency on Belgian and French medical device converters. |
| PLI Scheme Manufacturing Alignment | Indian production-linked incentives subsidize capital expenditure for BIS-certified copper IUD assembly lines near Delhi-NCR. |
| Telemedicine-Integrated Insertion Training | Remote consultation platforms expand provider capacity in rural United Kingdom primary care networks and Indian district hospitals. |
| Direct-to-Clinic Procurement Consolidation | Bypassing distributor intermediaries captures margin in French and German gynecological practice network purchasing decisions. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with gynecological practice administrators, family planning center procurement officers, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA device registration databases, CDSCO manufacturing approvals, BIS certification records, and hospital procurement contract disclosures. Bottom-up segment sizing and top-down macroeconomic anchoring provided cross-check triangulation.
Comparable-period anchoring tied projection assumptions to historical replacement interval patterns and regulatory approval cycle durations across the modeling period. Segmentation dimensions modeled include product type, delivery mode, end-user channel, application indication, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to public health program budget trajectories and private clinical adoption rates, with copper price volatility and EMA MDR implementation timelines as key forecast sensitivity inputs.
Underlying measurement precision varies by segment; hormonal IUD value estimates carry tighter precision than copper variant volume projections due to consolidated manufacturer disclosure. Forecasts embed assumptions regarding BIS certification approval timelines and NHS Integrated Care Board centralization pace. Material deviation in copper commodity pricing or EMA post-market surveillance enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Pipette Controllers Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Implant Handpiece Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Skincare Devices Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Canada Respiratory Devices Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Knee Walkers Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Global Cardiac Holter Monitor Market