
 Global Blood Transfusion Devices Market | 2026-2036
Global Blood Transfusion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Transfusion Devices Market Foresight
Polymer-based disposable sets are consolidating around phthalate-free alternatives as EU REACH restrictions tighten supply economics. Fresenius Kabi AG leverages its integrated IV therapy portfolio to anchor hospital procurement contracts across Western Europe. Haemonetics Corporation specializes in automated blood collection and processing platforms that dominate high-volume plasma center operations. Becton Dickinson controls distribution networks for needleless connectors that reduce clinician needlestick exposure.
Blood transfusion devices encompass electromechanical and mechanical systems engineered to collect, filter, warm, and deliver blood components with precision flow rates typically ranging from 2 to 150 mL per minute and temperature maintenance at 37°C to prevent hypothermic patient complications. These systems serve critical therapeutic delivery in surgical, trauma, and chronic anemia settings where hemodynamic stability depends on controlled infusion parameters. Blood warmers and automated systems command premium positioning due to integrated safety algorithms and real-time bubble detection that reduce adverse event liability. Disposable transfusion sets and needleless connectors represent high-velocity revenue streams driven by single-use mandates and infection control protocols. Electromechanical units with wireless monitoring capability are displacing legacy mechanical devices in tertiary care settings where centralized nursing station oversight reduces staffing intensity.
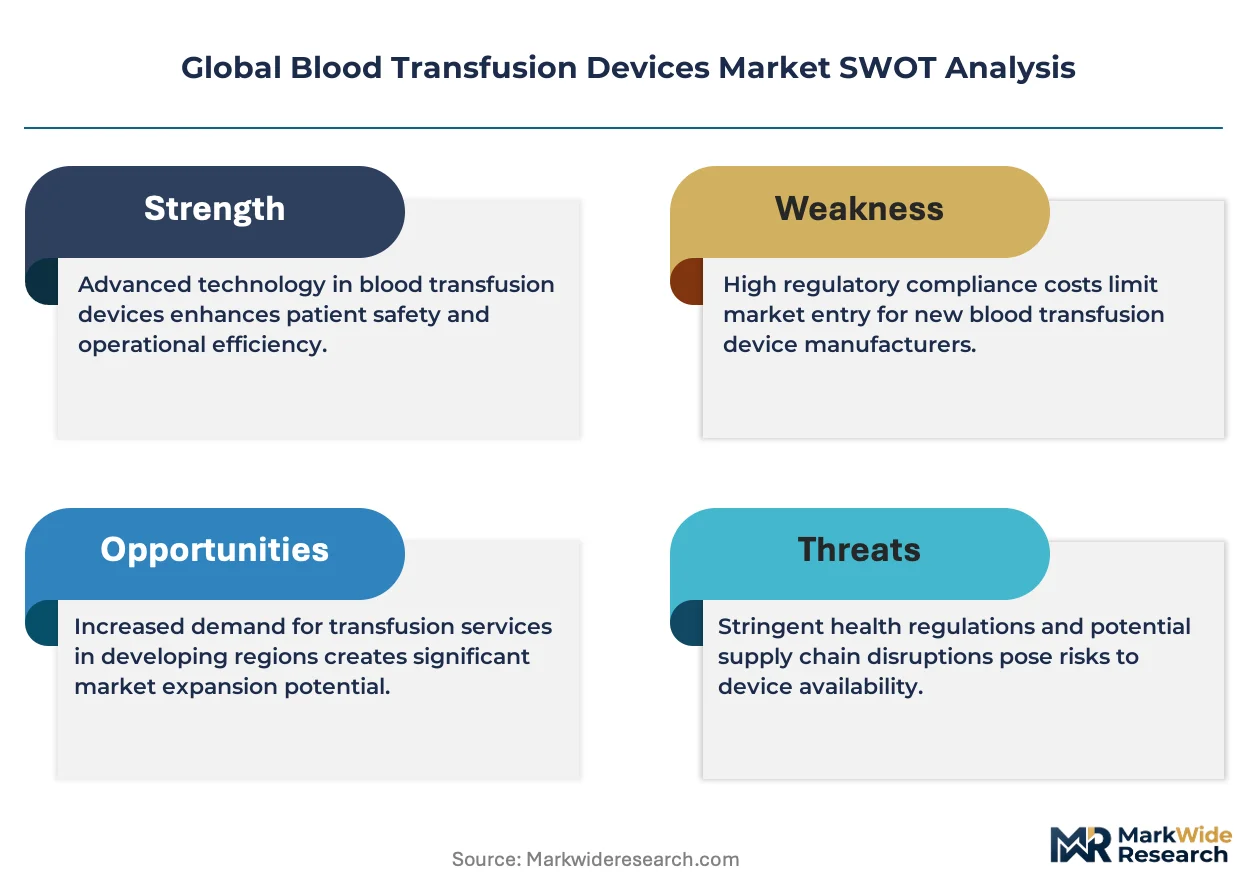
FDA blood product regulations, EU MDR Class IIa device requirements, and ISO 1135 standards for transfusion equipment collectively elevate barrier costs for market entry while mandating biocompatibility testing that favors established manufacturers with captive laboratory resources. Japan's PMDA enforces additional clinical data requirements for automated systems that slow approval timelines but reward early registrants with multi-year exclusivity in national university hospital networks. Stakeholders must monitor harmonization gaps between FDA 510(k) pathways and EU MDR technical documentation demands that fragment product development roadmaps and inflate dual-market certification spending.
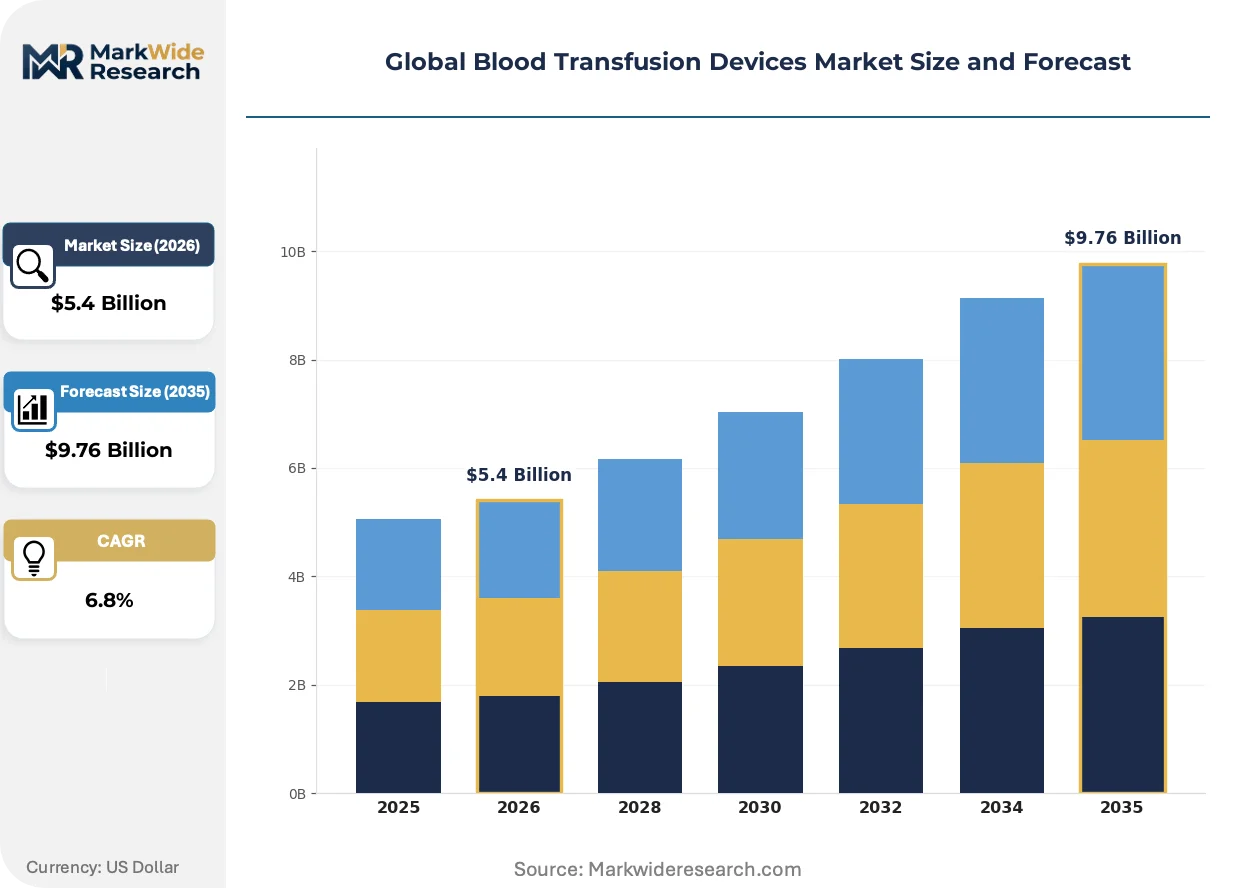
Market Dynamics
Automated transfusion infrastructure deployment is compressing replacement cycles for legacy mechanical devices as hospitals and surgical centers prioritize integrated safety algorithms and real-time monitoring capabilities that reduce adverse event liability.
Growth Catalysts
- EU MDR Class IIa compliance deadlines:Device replacement mandates across Western European hospital networks are accelerating procurement of certified electromechanical systems with enhanced biocompatibility documentation.
- Phthalate-free polymer formulations:REACH restrictions on plasticizers are redirecting disposable set manufacturing toward compliant supply chains that command procurement preference in German and French markets.
- Plasma center automation:High-volume collection facilities are standardizing on automated blood processing platforms that reduce staffing intensity and improve component yield consistency.
Market Restraints
- Medical-grade polymer supply concentration:Specialty resin production clusters in Northeast Asia create input cost volatility for disposable set manufacturers dependent on just-in-time delivery.
- PMDA clinical data requirements:Japan's extended approval timelines for automated systems delay market entry and inflate development spending for non-Japanese manufacturers.
- Needleless connector standardization gaps:Incompatible interface designs across supplier portfolios force hospitals to maintain redundant inventory and limit supplier consolidation benefits.
Strategic Opportunities
- Wireless monitoring convergence:Integration of Bluetooth-enabled flow sensors with centralized nursing station dashboards is creating premium positioning for tertiary care adoption in United States academic medical centers.
- India's hospital infrastructure expansion:Government-funded surgical capacity programs in tier-2 cities are generating first-time demand for temperature-controlled transfusion systems previously concentrated in metropolitan facilities.
- ISO 1135 harmonization initiatives:Alignment of transfusion equipment standards across regulatory zones is reducing dual-certification burden and enabling faster geographic expansion for compliant manufacturers.
Industry Challenges
- Biocompatibility testing capacity:Captive laboratory resources at established manufacturers create capability scarcity for mid-scale entrants attempting ISO 1135 compliance.
- Legacy mechanical device integration:Electromechanical system deployment requires costly retrofit of existing hospital infrastructure and staff retraining programs that delay realization of efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Transfusion Devices Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, Blood Warmers, Transfusion Sets, Needleless Connectors, Blood Collection Systems Application: Emergency Care, Surgery, Anemia Treatment, Oncology, Trauma Care End User: Blood Banks, Diagnostic Laboratories, Specialty Clinics, Ambulatory Surgical Centers, Home Healthcare Providers Technology: Automated Systems, Mechanical Devices, Disposable Devices, Electromechanical Units, Wireless Monitoring |
| Companies Covered | Fresenius Kabi AG, Haemonetics Corporation, Becton Dickinson, Baxter International, Immucor, Terumo Corporation, Grifols, Medtronic, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Transfusion Devices Market Shifts & Advancements
Device intelligence and connectivity architectures are displacing standalone mechanical operation as the defining performance dimension, with safety algorithm integration becoming the primary procurement discriminator across hospital purchasing committees.
RFID-enabled blood component tracking is absorbing inventory management functions previously handled by manual barcode scanning, with tertiary care centers in Germany and the United States adopting the technology at accelerated pace. Hospital blood banks are reducing component wastage and improving chain-of-custody documentation. This convergence is absorbing middleware vendor roles and compressing value capture for standalone tracking solution providers.
EU MDR technical documentation demands are fragmenting product development roadmaps for manufacturers attempting simultaneous FDA 510(k) and CE marking pathways. Dual-market certification spending is inflating by approximately one-third for electromechanical device categories. Automated transfusion system portfolios face the most acute documentation burden due to software validation requirements and clinical evidence thresholds.
Consolidated procurement contracts are displacing discrete device purchasing across Western European hospital networks, with integrated IV therapy portfolios capturing multi-year supply agreements. Group purchasing organizations are unbundling after-sales service from capital equipment pricing and negotiating performance-based maintenance terms. This behavioral shift is most visible in German and French markets where public hospital consolidation has concentrated buying power.
Global Blood Transfusion Devices Market Segmentation
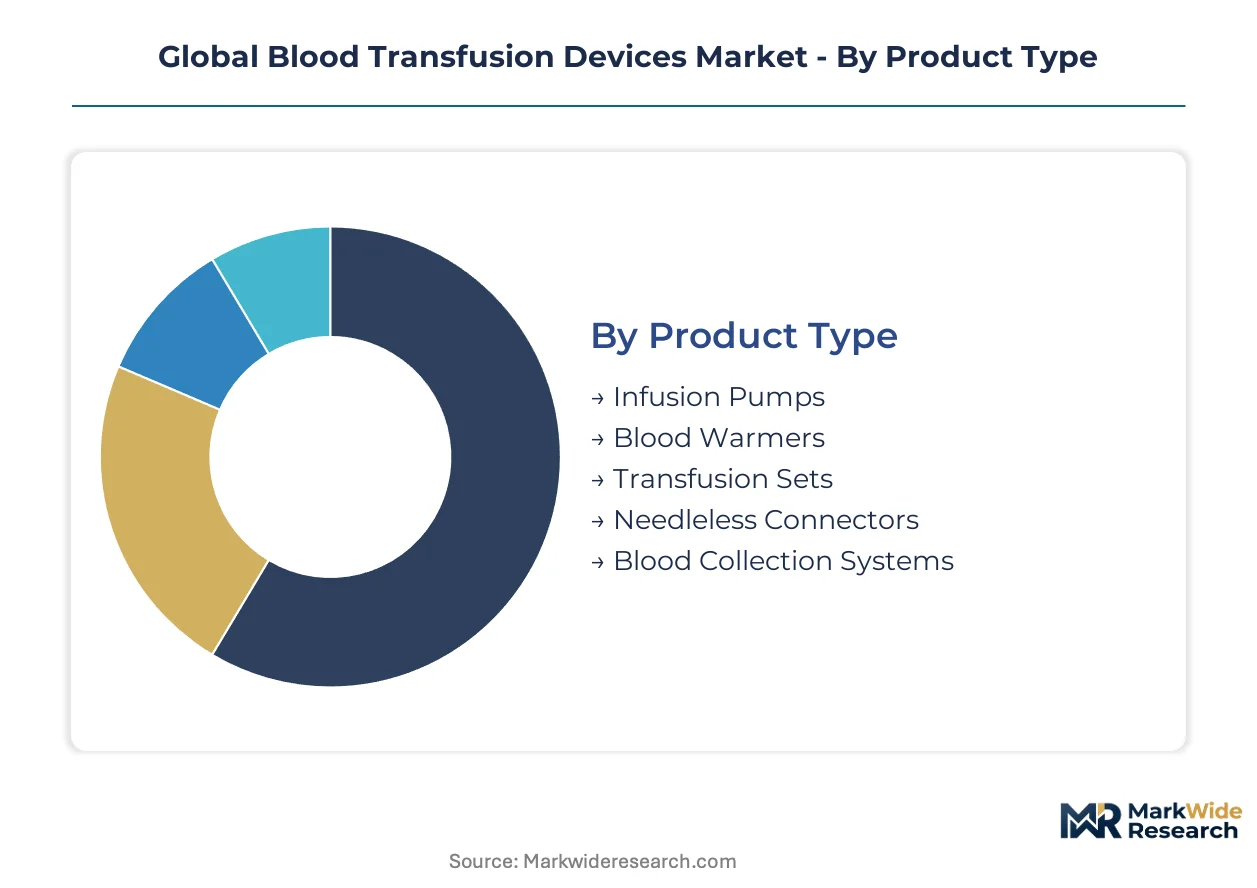
Device specification and integration complexity vary sharply across transfusion modalities, with automated platforms commanding distinct procurement criteria versus disposable consumables. Segmentation reveals where capital equipment investment concentrates versus recurring revenue streams driven by single-use mandates and infection control protocols.
Product Type:
Precision flow control and thermal management specifications define performance tiers across the product spectrum, with integrated safety algorithms commanding premium positioning.
- Infusion Pumps:Electromechanical units deliver calibrated flow rates from 2 to 150 mL per minute with integrated bubble detection and occlusion alarms. Demand concentrates in United States academic medical centers where centralized nursing station oversight reduces staffing intensity and adverse event liability.
- Blood Warmers:Counter-current heat exchange systems maintain infusate at 37°C to prevent hypothermic complications during massive transfusion protocols. German trauma centers are standardizing on these units as EU MDR compliance deadlines accelerate replacement of unvalidated legacy warmers.
- Transfusion Sets:Polymer-based disposable tubing assemblies with drip chambers and roller clamps for gravity-fed delivery.
- Needleless Connectors:Split-septum and mechanical valve designs that eliminate clinician needlestick exposure during line access.
- Blood Collection Systems:Integrated phlebotomy sets with anticoagulant reservoirs for component separation and processing.
Mature deployment sits with transfusion sets and needleless connectors. Newer deployment is concentrated in infusion pumps with wireless monitoring capability.
Application:
Clinical urgency and hemodynamic instability severity determine device sophistication requirements, with controlled elective settings permitting simpler mechanical solutions.
- Emergency Care:Rapid infusion capability with pressure-driven flow and warming integration for hemorrhagic shock resuscitation. United States Level I trauma centers are prioritizing automated platforms that reduce cognitive load during high-stakes interventions.
- Surgery:Controlled transfusion with real-time hemoglobin monitoring and cell salvage compatibility for intraoperative blood management. Japanese university hospitals are adopting these systems under PMDA-approved protocols that reward early registrants with procurement preference.
- Anemia Treatment:Chronic outpatient transfusion programs for thalassemia and sickle cell disease requiring portable warming solutions.
- Oncology:Chemotherapy-induced cytopenia support with platelet and red cell component delivery.
- Trauma Care:Pre-hospital and battlefield applications driving demand for battery-operated, ruggedized warming units.
High-acuity deployment dominates emergency and surgical segments. Volume expansion is climbing fastest in anemia treatment as population aging extends chronic transfusion dependency.
End User:
Capital intensity and regulatory scrutiny scale with patient volume and component handling complexity, fragmenting procurement authority across facility types.
- Blood Banks:High-volume component processing and storage with automated collection platforms and leukoreduction filtration systems. Plasma centers in the United States are standardizing on integrated processing equipment that improves yield consistency and reduces staffing requirements.
- Diagnostic Laboratories:Specimen handling and quality control transfusion support with lower throughput requirements.
- Specialty Clinics:Hematology and oncology-focused outpatient transfusion services with limited warming infrastructure.
- Ambulatory Surgical Centers:Same-day procedure support with disposable mechanical devices and basic warming capability.
- Home Healthcare Providers:Emerging demand for portable infusion pumps with telemedicine integration for rare disease management.
Consolidated procurement power rests with blood banks. Regulatory compliance investment is expanding most quickly in diagnostic laboratories as ISO 1135 documentation requirements tighten.
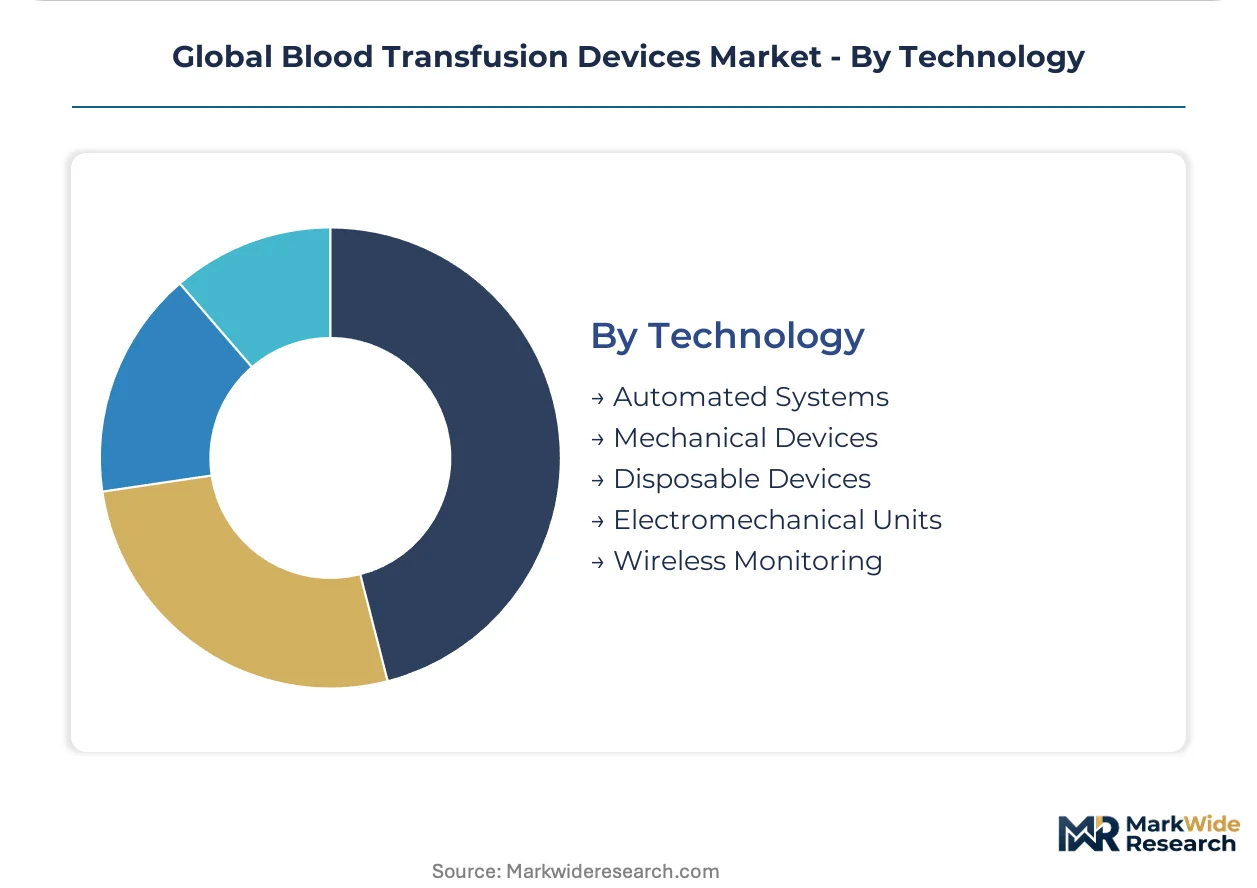
Technology:
Connectivity architecture and algorithmic safety layers are displacing mechanical reliability as the primary value proposition in tertiary care settings.
- Automated Systems:Software-controlled flow regulation with real-time sensor feedback and predictive occlusion management. German hospital networks are deploying these platforms under consolidated procurement contracts that bundle after-sales service with capital equipment pricing.
- Wireless Monitoring:Bluetooth-enabled flow sensors transmitting to centralized dashboards for remote surveillance. United States academic medical centers are adopting this capability to reduce nursing station staffing intensity and improve response times to adverse events.
- Mechanical Devices:Gravity-fed systems with manual flow control and basic warming elements for cost-constrained settings.
- Disposable Devices:Single-use transfusion sets and collection assemblies driven by infection control mandates and phthalate-free polymer transitions.
- Electromechanical Units:Hybrid platforms combining motor-driven precision with disposable fluid pathways.
Installed base concentration remains with mechanical and disposable technologies. Capability investment is gaining share fastest in wireless monitoring as nursing shortage pressures intensify across developed markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentration in the United States, Germany, and Japan absorbs the majority of automated transfusion system shipments. Aging demographics across these markets extend chronic transfusion dependency for thalassemia, sickle cell disease, and chemotherapy-induced cytopenia.
United States
Level I trauma centers and academic medical centers drive demand for wireless-enabled infusion platforms with centralized nursing station oversight. FDA blood product guidance updates accelerate replacement cycles for legacy mechanical devices. The Boston-Cambridge cluster anchors development of safety algorithm software for automated transfusion systems.
Germany
Public hospital consolidation concentrates procurement power behind integrated IV therapy portfolios spanning multiple device categories. EU MDR Class IIa compliance deadlines force replacement of unvalidated legacy warmers across trauma center networks. The Rhine-Ruhr metropolitan region hosts manufacturing facilities for phthalate-free polymer disposable sets.
Japan
University hospital networks standardize on PMDA-approved automated platforms that reward early registrants with multi-year exclusivity. Extended clinical data requirements delay market entry for non-Japanese manufacturers but protect incumbent positions. The Kanto region around Tokyo concentrates plasma center automation deployments.
India
Government-funded surgical capacity programs in tier-2 cities generate first-time demand for temperature-controlled transfusion systems. Central Drugs Standard Control Organization regulations tighten biocompatibility documentation requirements for imported devices. The Maharashtra-Gujarat industrial corridor attracts contract manufacturing for disposable transfusion sets.
United Kingdom
NHS blood and transplant services consolidate procurement around automated collection platforms with leukoreduction filtration. MHRA alignment with EU MDR technical documentation demands fragments product development roadmaps for dual-market manufacturers. The Oxford-Cambridge arc hosts clinical trial infrastructure for transfusion safety algorithm validation.
Global Blood Transfusion Devices Market Competitive Landscape
Consolidated procurement contracts dominate the current landscape as group purchasing organizations unbundle after-sales service from capital equipment pricing. The vendor base organizes around three tiers: diversified medical technology conglomerates with integrated IV therapy portfolios, specialized blood management companies with automated processing platforms, and regional disposable set manufacturers with polymer formulation expertise. Capacity expansion and strategic partnerships represent the primary competitive moves, with manufacturers seeking captive laboratory resources for biocompatibility testing and software validation capabilities.
Among diversified medical technology conglomerates, Fresenius Kabi AG and Becton Dickinson exemplify archetypes with procurement anchoring power across Western European and North American hospital networks. Haemonetics Corporation occupies a specialist position in automated blood collection and processing platforms, particularly within high-volume plasma center operations. These three entities represent distinct strategic postures: integrated portfolio breadth, distribution network control, and vertical specialization in automated workflows.
| Leading Market Players |
|---|
| Fresenius Kabi AG |
| Haemonetics Corporation |
| Becton Dickinson |
| Baxter International |
| Immucor |
| Terumo Corporation |
| Grifols |
| Medtronic |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in European disposable set manufacturing anchor supply discipline through consolidated polymer sourcing contracts that compress input cost volatility into predictable pricing bands for hospital procurement committees.
Pricing Analysis
High-volume transfusion sets generate thin margins offset by recurring revenue density, while automated electromechanical platforms capture premium positioning through integrated safety software and wireless monitoring capabilities. Price differentiation separates FDA-validated systems from basic mechanical warmers, with EU MDR certification tier commanding procurement preference in German and French hospital networks. Pricing pressure stems from REACH-mandated phthalate-free polymer transitions that elevate raw material costs for disposable manufacturers. Blood banks and plasma centers exhibit lowest price sensitivity due to yield-consistency requirements, whereas ambulatory surgical centers prioritize economy-tier mechanical devices.
Supply Chain Analysis
Direct-to-hospital channels handle automated platform deployments for United States academic medical centers, while distribution runs through regional medical supply wholesalers for disposable consumables. Specialty resin production concentrates in China, South Korea, and Japan, creating geographic dependency for polymer tubing and connector components. Raw material sourcing draws from medical-grade PVC alternatives, anticoagulant coatings, and precision-molded plastics. Single-source vulnerability in Northeast Asian resin clusters exposes manufacturers to logistics chokepoint risk during regional disruption events.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR compliance deadlines and biocompatibility testing cost burdens force mid-scale mechanical device manufacturers toward exit or acquisition.
For Market Incumbents: Lock in multi-year procurement contracts with German and French hospital networks before smaller competitors achieve MDR certification. Deepen backward integration into phthalate-free polymer formulation through captive laboratory resources that create capability scarcity for challengers attempting ISO 1135 compliance.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in wireless-enabled infusion pumps creates white-space opportunity for mid-tier electromechanical platforms with basic Bluetooth monitoring. Target India's tier-2 city hospital infrastructure expansion where first-time temperature-controlled transfusion system demand outruns established distributor relationships. Pursue CDSCO fast-track pathways for imported devices with simplified biocompatibility documentation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor automated blood processing specialists in Japan where PMDA exclusivity periods protect incumbent cash flows. Long-term viability hinges on software-validation capabilities and hospital system integration depth rather than hardware manufacturing scale. Monitor harmonization progress between FDA 510(k) and EU MDR technical documentation demands as inflection signal for dual-market certification cost relief.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Accelerates device replacement cycles across Western European trauma center networks. |
| Hospital System Partnership | Secures multi-year supply agreements with consolidated procurement power in German public networks. |
| Software Companion Development | Enables wireless monitoring convergence with centralized nursing station dashboards in United States academic centers. |
| Backward Integration into Polymer Supply | Captures phthalate-free formulation expertise as REACH restrictions tighten supply economics. |
| Reimbursement Strategy | Aligns automated platform value propositions with CMS and NHS blood management quality metrics. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, plasma center operations data, and regulatory filing databases underwrites the qualitative findings in this study. Primary fieldwork engaged biomedical engineers, GPO contracts managers, hospital procurement directors, and blood bank operations leads across United States, German, and Japanese facilities. Secondary validation drew from FDA 510(k) submissions, EUDAMED device registrations, PMDA approval summaries, and hospital procurement database extracts. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separated volume expansion from price-mix effects across product type, application, end user, and technology segmentation dimensions. CAGRs were derived through regression analysis of historical shipment data against regulatory event timelines and hospital infrastructure investment cycles. Forecast inputs incorporated EU MDR compliance deadline schedules, REACH polymer restriction phase-ins, and government-funded surgical capacity programs in emerging markets.
Inputs from hospital procurement databases and regulatory filing systems were available through the study window; gaps in real-time plasma center automation deployment rates introduce uncertainty bands around high-volume collection facility projections. Forecasts reflect assumptions about harmonization progress between FDA and EU technical documentation demands. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Ultrasonic Nebulizers Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Anti-Snore Device Market
Medical Devices
Global Microcatheter Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Global MRI Safe Cardiac Resynchronization Therapy Device Market
Medical Devices
MIS Sacroiliac Joint Fusion Market