
 Germany Contraceptive Devices Market | 2026-2036
Germany Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Contraceptive Devices Market Foresight
Digital health integration with telemedicine prescribing and remote contraceptive counseling is rewriting how German patients access and manage reproductive health. Bayer AG leverages its integrated pharmaceutical-device portfolio to sustain dominance in hormonal intrauterine systems. Pfizer Inc. competes through specialized hormone delivery research, while The Cooper Companies Inc. differentiates via its copper and hormonal IUD manufacturing scale across European distribution networks.
Germany contraceptive devices encompass medically regulated products designed to prevent pregnancy through hormonal suppression, physical barrier mechanisms, or behavioral timing protocols, with intrauterine devices typically constructed from polyethylene frames with copper wire or levonorgestrel reservoirs and condoms manufactured from natural rubber latex or synthetic polyisoprene to specified tensile strength and permeability standards. These devices serve primary commercial purposes in fertility management, sexually transmitted infection prevention, and gynecological therapeutic applications. Intrauterine devices command the largest installed base among product types due to their multi-year efficacy and favorable cost-per-month profiles, while hormonal patches represent a faster-growing segment driven by patient preference for non-invasive, self-administered alternatives. Within technology categories, hormonal systems anchor margin pools through prescription-linked recurring revenue, whereas barrier methods occupy broader pharmacy and online retail channels with lower clinical intervention requirements.
Germany's Federal Institute for Drugs and Medical Devices (BfArM) oversees contraceptive device market authorization under Medical Device Regulation (MDR) conformity assessment procedures, while the Joint Federal Committee (G-BA) determines statutory reimbursement eligibility through health technology assessments that directly shape patient out-of-pocket exposure and manufacturer pricing flexibility. The EU F-Gas Regulation indirectly affects manufacturing by restricting fluorinated greenhouse gas use in certain pharmaceutical production processes, nudging suppliers toward reformulated delivery systems. Stakeholders must monitor evolving MDR implementation timelines and G-BA benefit assessment outcomes to anticipate reimbursement shifts that will determine competitive positioning in Germany's publicly funded healthcare procurement environment.
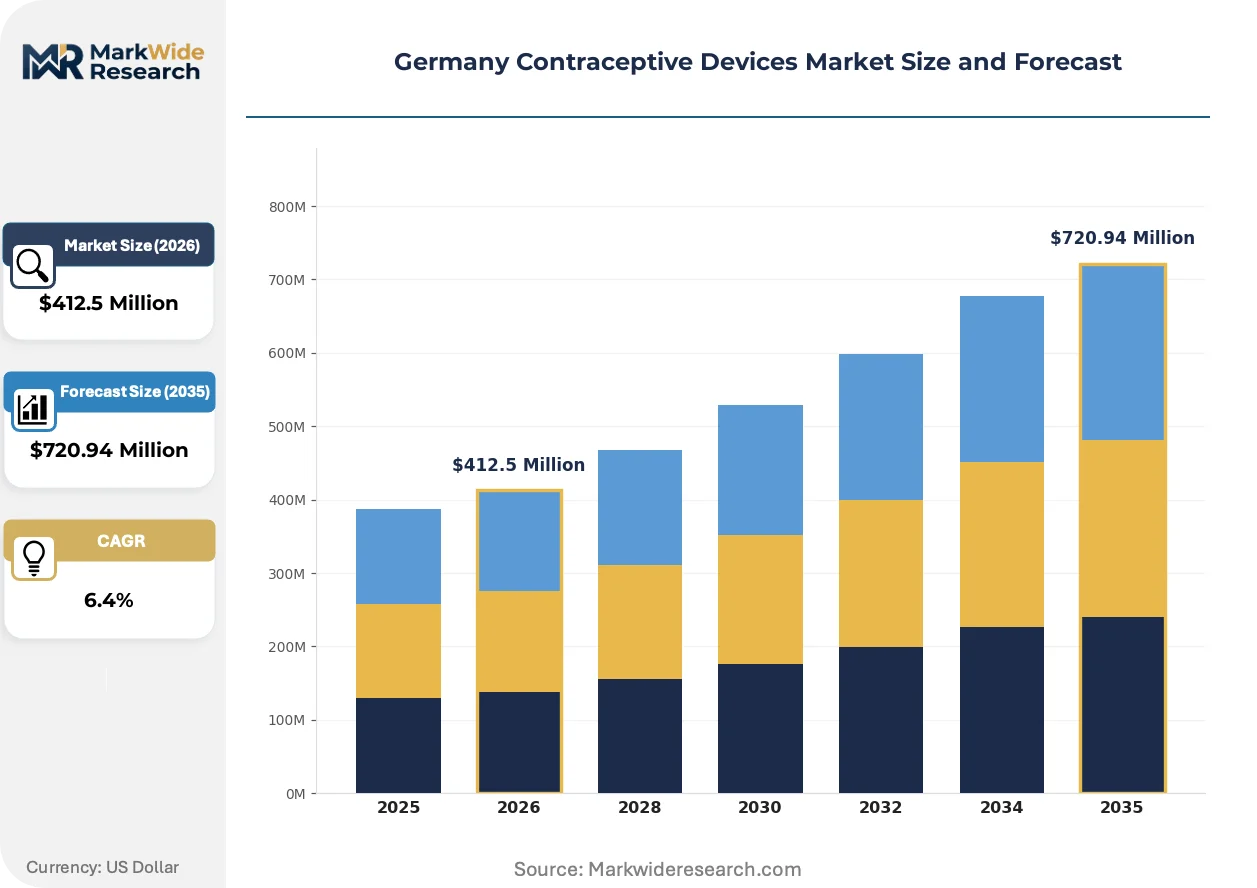
Market Dynamics
Germany's Statutory Health Insurance reimbursement recalibration for long-acting reversible contraceptives is compressing patient out-of-pocket exposure while expanding clinic service capacity across urban hospital networks.
Growth Catalysts
- G-BA Benefit Assessments:The Joint Federal Committee's expanded reimbursement eligibility for hormonal intrauterine devices eliminates cost barriers for insured patients.
- Telemedicine Integration:Remote contraceptive counseling platforms enable gynecology clinics in Berlin and Hamburg to extend reach into underserved rural catchments.
- Copper Wire Supply Localization:European manufacturers securing regional sourcing for IUD raw materials reduce import dependency and stabilize production schedules.
Market Restraints
- MDR Conformity Costs:The Medical Device Regulation's enhanced clinical evidence requirements impose documentation burdens that disproportionately constrain mid-tier manufacturers.
- Specialized Gynecologist Concentration:Long-acting reversible contraceptive insertion services cluster in Bavaria and North Rhine-Westphalia, leaving eastern federal states with access deficits.
- Levonorgestrel Price Volatility:Active pharmaceutical ingredient sourcing fluctuations from Asian suppliers inject margin uncertainty into hormonal IUD production economics.
Strategic Opportunities
- Pharmacy Channel Expansion:Non-prescription barrier method distribution through German pharmacy networks captures convenience-seeking patient segments.
- EU F-Gas Reformulation:Restrictions on fluorinated greenhouse gases in pharmaceutical processes create first-mover advantages for suppliers deploying alternative hormone delivery chemistries.
- Digital Therapeutics Convergence:Integration of fertility tracking applications with hormonal patch adherence monitoring opens subscription revenue models.
Industry Challenges
- MDR Implementation Timeline Compression:BfArM's phased conformity assessment deadlines force simultaneous portfolio re-certification across multiple device categories.
- Specialized Insertion Training Bottlenecks:Gynecology clinics face certified practitioner shortages for copper and hormonal IUD placement procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Contraceptive Devices Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrauterine Devices, Condoms, Vaginal Rings, Diaphragms, Hormonal Patches Technology: Hormonal, Barrier, Natural, Behavioral, Sterilization Application: Family Planning, STD Prevention, Fertility Regulation, Postpartum Control, Menstrual Management End User: Hospitals, Gynecology Clinics, Family Planning Centers, Pharmacies, Online Retailers |
| Companies Covered | Bayer AG, AbbVie, Pfizer Inc., Reckitt Benckiser Group Plc, The Cooper Companies Inc., Jenapharm GmbH & Co. KG, WÖRWAG Pharma GmbH & Co. KG, MSD Sharp & Dohme GmbH, Merck & Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Contraceptive Devices Market Shifts & Advancements
Digital health infrastructure is rewiring patient-provider interaction models across German reproductive care, while regulatory stringency and shifting procurement behaviors reshape competitive terrain.
Hormonal intrauterine systems with extended-release levonorgestrel reservoirs are collapsing the traditional replacement cycle for long-acting contraceptives. Gynecology clinics in Munich and Hamburg are prioritizing these devices for patient cohorts seeking multi-year efficacy without daily adherence burdens. The technology is collapsing revenue predictability for oral contraceptive manufacturers as clinic formularies reallocate toward insertion-based alternatives.
The EU Medical Device Regulation's clinical evidence requirements are forcing German manufacturers to reconstruct post-market surveillance systems. BfArM's heightened scrutiny of biocompatibility data extends approval timelines for novel intrauterine device submissions. Hormonal system suppliers with legacy European market presence are accelerating real-world evidence collection to defend existing certificates against MDR transition deadlines.
Patient-initiated switching between contraceptive modalities is compressing brand loyalty cycles historically anchored by prescription renewal patterns. Specialized family planning centers in Berlin report elevated demand for method transitions driven by side-effect tolerance and lifestyle fit assessments. Urban hospital networks are responding with integrated counseling workflows that accommodate rapid product substitution without specialist referral delays.
Germany Contraceptive Devices Market Segmentation
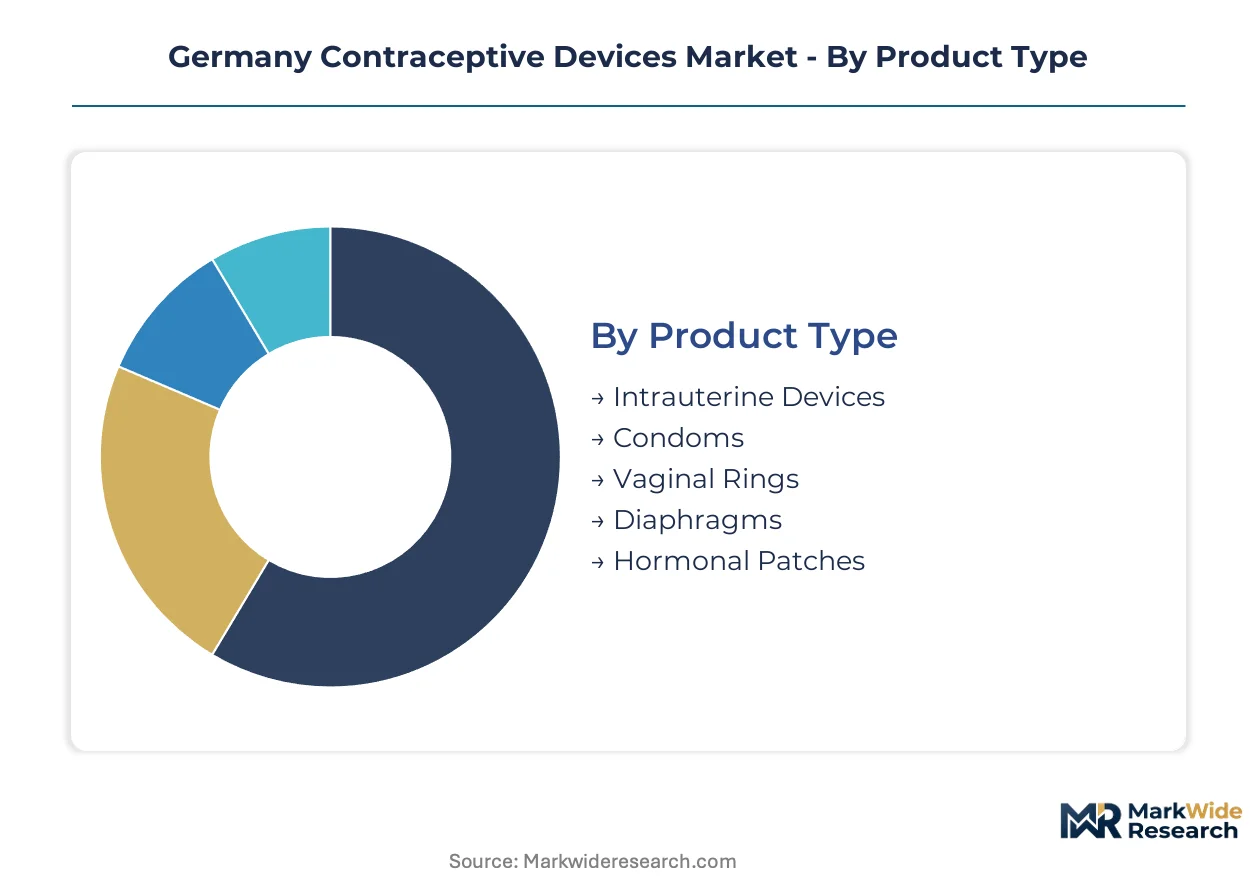
Segmentation in Germany's contraceptive devices market reveals distinct service intensity requirements across product categories. Hormonal systems demand ongoing clinical monitoring and insertion expertise, while barrier methods shift fulfillment burden toward pharmacy and digital channels.
Product Type:
After-sales service intensity varies dramatically across product categories, with insertion-based devices requiring certified practitioner networks and follow-up protocols that self-administered alternatives bypass entirely.
- Intrauterine Devices:Polyethylene frames with copper wire or levonorgestrel reservoirs deliver multi-year efficacy. Demand concentrates in Munich and Hamburg gynecology clinics where GKV reimbursement eliminates patient cost barriers. Insertion complexity creates practitioner dependency that sustains clinic channel loyalty.
- Condoms:Natural rubber latex or synthetic polyisoprene barriers manufactured to tensile strength and permeability standards. Pharmacy networks in Berlin and Hamburg capture convenience-seeking segments through non-prescription distribution. Low clinical intervention requirements compress margin pools but expand volume potential.
- Vaginal Rings:Flexible polymer devices releasing etonogestrel and ethinyl estradiol for three-week cycles. Specialized family planning centers in Bavaria report rising patient preference for self-administered hormonal alternatives.
- Diaphragms:Silicone or latex cervical barriers requiring fitting services. Access concentrates in urban hospital networks with dedicated family planning departments.
- Hormonal Patches:Transdermal norelgestromin and ethinyl estradiol delivery systems. Patient preference for non-invasive administration is expanding pharmacy channel presence across North Rhine-Westphalia.
By volume, Condoms leads. By growth pace, Hormonal Patches is climbing the fastest.
Technology:
Cost tier stratification separates prescription-linked hormonal systems from over-the-counter barrier methods, with reimbursement eligibility determining patient out-of-pocket exposure and channel economics.
- Hormonal:Levonorgestrel and etonogestrel delivery via intrauterine systems, implants, patches, and rings. G-BA benefit assessments anchor margin pools through statutory reimbursement coverage.
- Barrier:Physical prevention through condoms, diaphragms, and cervical caps. Pharmacy and online retail channels dominate with minimal clinical gatekeeping.
- Natural:Fertility awareness and withdrawal methods. Digital therapeutics integration with tracking applications is emerging in Berlin's telemedicine platforms.
- Behavioral:Calendar-based and lactational amenorrhea approaches. Demand concentrates in specialized family planning centers offering comprehensive counseling.
- Sterilization:Permanent surgical intervention. Hospital networks in Bavaria and North Rhine-Westphalia maintain procedural concentration.
Hormonal commands the largest revenue share. Natural methods are gaining share fastest through digital convergence.
Application:
End-use purpose determines regulatory pathway and reimbursement positioning, with therapeutic indications accessing broader GKV coverage than purely contraceptive claims.
- Family Planning:Primary pregnancy prevention across reproductive lifespans. Gynecology clinics in Hamburg and Munich prioritize long-acting reversible options.
- STD Prevention:Barrier method deployment for infection risk reduction. Pharmacy channel expansion captures asymptomatic patient segments.
- Fertility Regulation:Interval spacing and timing optimization. Telemedicine platforms in Berlin extend counseling reach into rural catchments.
- Postpartum Control:Immediate and extended post-delivery contraception. Hospital networks integrate insertion services with maternity discharge protocols.
- Menstrual Management:Hormonal suppression for heavy bleeding or cycle regulation. G-BA assessments increasingly recognize therapeutic indications beyond contraception.
Family Planning dominates procedure volume. Menstrual Management shows the steepest expansion trajectory as therapeutic indications broaden.
End User:
Channel maturity varies across institutional and retail settings, with certified insertion capacity constraining service expansion in eastern federal states.
- Hospitals:Integrated maternity and gynecology departments with emergency complication capacity. Urban networks in Berlin, Hamburg, and Munich anchor regional referral systems.
- Gynecology Clinics:Specialized contraceptive counseling and insertion services. Bavaria and North Rhine-Westphalia concentrate practitioner expertise.
- Family Planning Centers:Dedicated reproductive health facilities. Berlin's specialized centers report elevated demand for method switching workflows.
- Pharmacies:Non-prescription barrier method distribution. Convenience positioning captures method-switching patients between clinical visits.
- Online Retailers:Direct-to-consumer barrier method fulfillment. Privacy preferences drive urban adoption in Hamburg and Munich.
Gynecology Clinics lead by service revenue. Online Retailers are expanding most quickly as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contraceptive device manufacturers supply integrated pharmaceutical-device portfolios to hospital networks across Central Europe, with distribution corridors extending into neighboring health systems seeking MDR-compliant reproductive health technologies.
North Rhine-Westphalia
Gynecology clinics in Cologne and Düsseldorf anchor Germany's highest concentration of long-acting reversible contraceptive insertion services. The Joint Federal Committee's expanded GKV reimbursement for hormonal intrauterine devices eliminates patient cost barriers across this industrial heartland. Hospital networks in the Ruhr region integrate maternity discharge protocols with immediate postpartum IUD placement capacity.
Bavaria
Munich's specialized family planning centers report elevated demand for method-switching workflows between hormonal and copper intrauterine systems. BfArM's MDR conformity assessment procedures extend approval timelines for novel device submissions originating from Bavarian manufacturing facilities. The state's medical technology clusters concentrate practitioner expertise for certified insertion training programs.
Berlin-Brandenburg
Telemedicine platforms in Berlin extend remote contraceptive counseling reach into underserved rural catchments across eastern federal states. Digital health infrastructure investments from the Federal Ministry of Health accelerate patient-provider interaction models for fertility tracking applications. Urban hospital networks prioritize integrated counseling workflows accommodating rapid product substitution.
Hamburg
Pharmacy channel expansion for non-prescription barrier methods concentrates in Hamburg's convenience-oriented retail corridors. The city's port logistics infrastructure supports import distribution of natural rubber latex and synthetic polyisoprene raw materials for condom manufacturing. Online retailers leverage Hamburg's fulfillment density to capture privacy-preferring patient segments.
Baden-Württemberg
Medical device engineering clusters in Stuttgart and Karlsruhe develop extended-release levonorgestrel reservoir technologies for next-generation hormonal systems. The EU F-Gas Regulation's restrictions on fluorinated greenhouse gases nudge regional suppliers toward reformulated hormone delivery chemistries. Research partnerships between technical universities and pharmaceutical manufacturers accelerate real-world evidence collection for MDR compliance.
Germany Contraceptive Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated pharmaceutical-device portfolios that combine hormonal active ingredients with specialized delivery mechanisms. Tiered competitive positioning separates prescription-linked hormonal systems from over-the-counter barrier methods with divergent margin and channel economics. Three archetypes dominate: diversified pharmaceutical conglomerates with device manufacturing capabilities, specialized reproductive health companies with focused product portfolios, and generic pharmaceutical manufacturers competing on cost. Competitive moves concentrate on M&A for technology access and geographic expansion into reimbursed clinic channels.
Within the integrated pharmaceutical-device tier, Bayer AG and Pfizer Inc. exemplify conglomerate positioning that spans active pharmaceutical ingredient production through finished device distribution. The Cooper Companies Inc. occupies a specialist position concentrated on intrauterine device manufacturing scale. Among Germany-based entities, Jenapharm GmbH & Co. KG and WÖRWAG Pharma GmbH & Co. KG represent mid-market pharmaceutical manufacturers with regional distribution strength. MSD Sharp & Dohme GmbH anchors multinational presence through its German operating subsidiary. These named entities collectively illustrate the market's structural division between global scale players and regionally focused specialists competing on reimbursement access and practitioner relationship depth.
| Leading Market Players |
|---|
| Bayer AG |
| AbbVie |
| Pfizer Inc. |
| Reckitt Benckiser Group Plc |
| The Cooper Companies Inc. |
| Jenapharm GmbH & Co. KG |
| WÖRWAG Pharma GmbH & Co. KG |
| MSD Sharp & Dohme GmbH |
| Merck & Co., Inc. |
| Others |
Supply & Pricing Matrix
Asian API concentration for levonorgestrel and etonogestrel feeds directly into margin capture by hormonal system manufacturers, while copper wire sourcing from European smelters insulates copper IUD producers from currency-driven cost volatility. The divergence between these input profiles explains why prescription-linked hormonal devices command premium positioning against commodity barrier methods.
Pricing Analysis
Next-generation extended-release levonorgestrel reservoirs command 40-60% premiums over standard 3-year systems, while legacy copper wire devices occupy mid-tier positioning and economy generics face margin compression. Three-tier pricing structure across premium, standard, and economy levels reflects G-BA reimbursement tiers, certification grade, and insertion service bundling. Pricing pressure stems from GKV reimbursement rate negotiations that constrain manufacturer net realization. Pharmacy channel barrier method buyers exhibit highest price sensitivity; gynecology clinic patients with statutory coverage show lowest sensitivity due to eliminated out-of-pocket exposure.
Supply Chain Analysis
Levonorgestrel API feeds from India and China, copper wire from Chile and Germany, and medical-grade polyethylene from Belgium and the Netherlands. Raw material dependencies span hormonal actives, non-ferrous metals, and polymer frames with specialized biocompatibility profiles. Single-source vulnerability in Asian API supply injects production scheduling risk for hormonal system manufacturers. Distribution runs through hospital network procurement consortia, pharmacy wholesale cooperatives, and direct-to-clinic fulfillment for insertion-based devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's contraceptive devices market is recovering from MDR transition disruption, with reimbursement recalibration by the Joint Federal Committee driving cyclical demand normalization across gynecology clinic networks.
For Market Incumbents: Build regulatory data moats through accelerated real-world evidence collection for MDR certificate defense. Deepen practitioner training partnerships in Bavaria and North Rhine-Westphalia to constrain competitor insertion capacity expansion. Threat of mid-tier manufacturers achieving MDR compliance necessitates preemptive formulary lock-in with hospital procurement consortia. Leverage vertical integration into hormone API sourcing to offset Asian supply volatility. For New Entrants and Emerging Players: Eastern federal states with certified gynecologist deficits represent the most penetrable entry point for telemedicine-integrated remote counseling platforms. Self-administered hormonal patches in North Rhine-Westphalia pharmacy channels offer secondary white-space with lower clinical gatekeeping requirements. Go-to-market angle should emphasize digital therapeutics convergence with fertility tracking applications to bypass incumbent practitioner network dependencies. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MDR compliance infrastructure and real-world evidence generation capabilities. Long-term viability favors platform players with integrated pharmaceutical-device portfolios spanning hormonal and barrier categories. Acquisition target archetype: specialized IUD manufacturers with European manufacturing footprint and pending MDR certification. Signal to watch: G-BA benefit assessment expansions into therapeutic indications beyond contraception.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certificate Defense Program | Real-world evidence collection protects market access against BfArM deadline pressure. |
| G-BA Reimbursement Strategy | Therapeutic indication expansion unlocks statutory coverage for menstrual management applications. |
| Telemedicine Platform Integration | Remote counseling extends reach into eastern federal states with practitioner shortages. |
| European Copper Wire Localization | Regional sourcing reduces import dependency and stabilizes production economics. |
| Digital Therapeutics Convergence | Fertility tracking integration opens subscription revenue models for self-administered methods. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BfArM regulatory filings, G-BA benefit assessment documentation, and hospital procurement database extracts. Primary interviews engaged gynecology clinic directors, biomedical engineers at IUD manufacturers, GPO contracts managers, and pharmacy procurement leads. Secondary validation drew from statutory health insurance reimbursement records, medical device trade flow data, and MDR implementation guidance. Bottom-up demand modeling triangulates against top-down healthcare expenditure allocations.
Forecast inputs include G-BA assessment timelines, MDR certificate renewal schedules, and regional practitioner training capacity expansion. Modeled segmentation spans product type, technology category, application purpose, and end-user channel across the analysis window. CAGRs derive from fitted adoption curves adjusted for reimbursement policy inflections. Industry-specific inputs incorporate telemedicine penetration rates and copper commodity price trajectories.
Practitioners should monitor G-BA benefit assessment outcomes and MDR enforcement intensity for early signals of demand trajectory revision. Cross-checking against statutory health insurance expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Prefilled Syringe Contract Manufacturing Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Europe Ventilator Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Epidural Anesthesia Sets Market