
 Pectus Bar Market | 2026-2036
Pectus Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Pectus Bar Market Insights
CE marking under the EU Medical Device Regulation is rotating the competitive landscape toward manufacturers with notified-body relationships and quality-management depth. Zimmer Biomet leverages its orthopedic implant infrastructure to sustain European distribution reach. Biotech GmbH anchors its position through dedicated thoracic specialization and direct surgeon training programs. KLS Martin Group competes across Central European surgical centers with established pectus repair portfolios.
A pectus bar is a curved metallic implant, typically fashioned from stainless steel or titanium alloy with a convex profile matched to anterior chest-wall geometry, designed to elevate the sternum in patients with pectus excavatum via subcutaneous placement and subsequent retention for two to four years. The device serves the primary commercial purpose of enabling minimally invasive correction of congenital chest-wall deformities without rib resection or prolonged thoracotomy recovery. Titanium bars command premium positioning due to magnetic-resonance compatibility and reduced corrosion susceptibility in long-term implantation. Minimally invasive technology segments absorb the majority of new procedural adoption as hospital systems prioritize reduced postoperative length-of-stay metrics.
FDA 510(k) premarket notification requirements govern United States market access and compel equivalence demonstrations against predicate devices, while the EU MDR imposes clinical-evaluation and post-market surveillance obligations that extend certification timelines. Japan's PMDA maintains distinct master-file procedures for foreign-manufactured thoracic implants, creating additional documentation burdens for non-domestic suppliers. Stakeholders must monitor evolving notified-body capacity constraints in Europe and shifting CMS reimbursement determinations for minimally invasive chest-wall procedures.
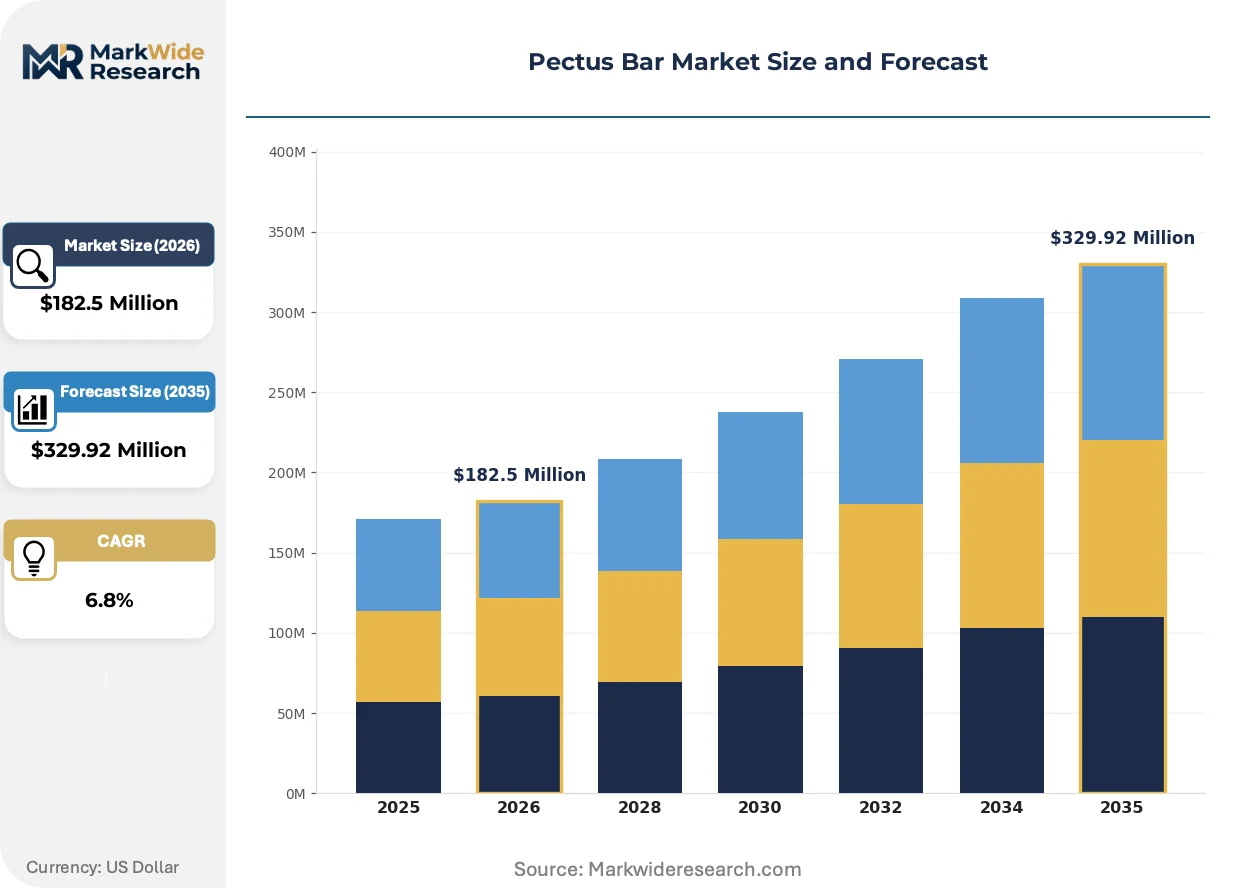
Market Dynamics
The transition from stainless steel to titanium alloy pectus bars is compressing procurement timelines as tertiary hospitals prioritize magnetic-resonance compatibility and long-term implant durability in pediatric thoracic surgery programs.
Growth Catalysts
- FDA 510(k) Pathway:The premarket notification framework accelerates device entry for manufacturers demonstrating predicate equivalence, reducing regulatory friction for implantable metal innovations.
- Pediatric Thoracic Specialization:Dedicated chest-wall surgery centers in the United States, Germany, and South Korea have achieved procedural mass that sustains recurring demand for minimally invasive correction devices.
- Titanium Alloy Adoption:Magnetic-resonance imaging compatibility and corrosion resistance properties are pulling hospital procurement toward premium-grade materials despite higher unit costs.
Market Restraints
- Notified-Body Bottlenecks:EU MDR certification timelines have extended 12-18 months as European notified bodies face capacity constraints for Class III implantable device reviews.
- Input Material Volatility:Titanium sponge and surgical-grade stainless steel prices fluctuate with aerospace and energy sector demand, compressing manufacturer margins on fixed-price hospital contracts.
- Surgeon Training Requirements:The Nuss procedure demands specialized minimally invasive technique certification, creating a bottleneck in procedural expansion beyond established academic medical centers.
Strategic Opportunities
- Japan PMDA Master-File Entry:Foreign manufacturers can establish device master files with Japan's Pharmaceuticals and Medical Devices Agency to unlock access to Asia's second-largest thoracic surgery market.
- Outpatient Migration:Ambulatory surgery centers in the United States are developing fast-track protocols for bar removal procedures, creating channel diversification beyond inpatient tertiary settings.
- Adult Pectus Correction:Underpenetrated demand among adult patients with long-standing excavatum deformities offers expansion beyond the traditional pediatric demographic.
Industry Challenges
- Biocompatibility Documentation:Extended implantation periods of 24-48 months require comprehensive long-term corrosion and fatigue data that strain preclinical testing budgets.
- Surgeon Volume Concentration:A limited cohort of high-volume pectus specialists controls referral flows, forcing manufacturers to maintain intensive proctoring and direct-to-surgeon education investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pectus Bar Market |
| Market Size in 2026 | $182.5 Million |
| Market Size in 2035 | $329.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Bars, Titanium Bars, Composite Bars, Stainless Steel Bars End User: Hospitals, Surgical Centers, Clinics, Specialty Care Facilities Delivery Mode: In-Person, Telehealth, Home Care, Outpatient Services Technology: Open Surgery, Minimally Invasive, Robotic Surgery, Hybrid Techniques |
| Companies Covered | Zimmer Biomet, Biotech GmbH, IDEAR S.R.L., MedXpert GmbH, KLS Martin Group, Reid Healthcare, Ventura Medical Technologies, Stryker Corporation, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pectus Bar Market Trends and Innovations
Material science advances and regulatory harmonization pressures are simultaneously elevating performance standards and compressing commercialization timelines across the implantable thoracic device category.
Bioresorbable sternal support technologies are fragmenting the long-term implant paradigm. Polylactic acid and magnesium alloy prototypes currently in preclinical evaluation promise elimination of secondary removal surgeries. Pediatric research consortia in South Korea and Germany are accelerating animal model studies. This developmental trajectory is fragmenting R&D budgets away from incremental metal bar improvements toward bioabsorption platforms.
EU MDR post-market surveillance obligations are tightening clinical evidence requirements for legacy devices. Manufacturers must now submit periodic safety update reports and maintain risk management files throughout the product lifecycle. Class III thoracic implants face the steepest documentation burdens, with notified bodies demanding real-world performance data from European implant registries.
Hospital value-analysis committees are consolidating purchasing authority for high-cost implants. Individual surgeon preference is yielding to centralized procurement review in United States health systems, with standardized vendor scorecards replacing discretionary selection. This behavioral shift concentrates contract negotiations with integrated delivery networks in Texas, California, and Florida where pediatric thoracic volumes justify dedicated supply agreements.
Pectus Bar Market Segmentation
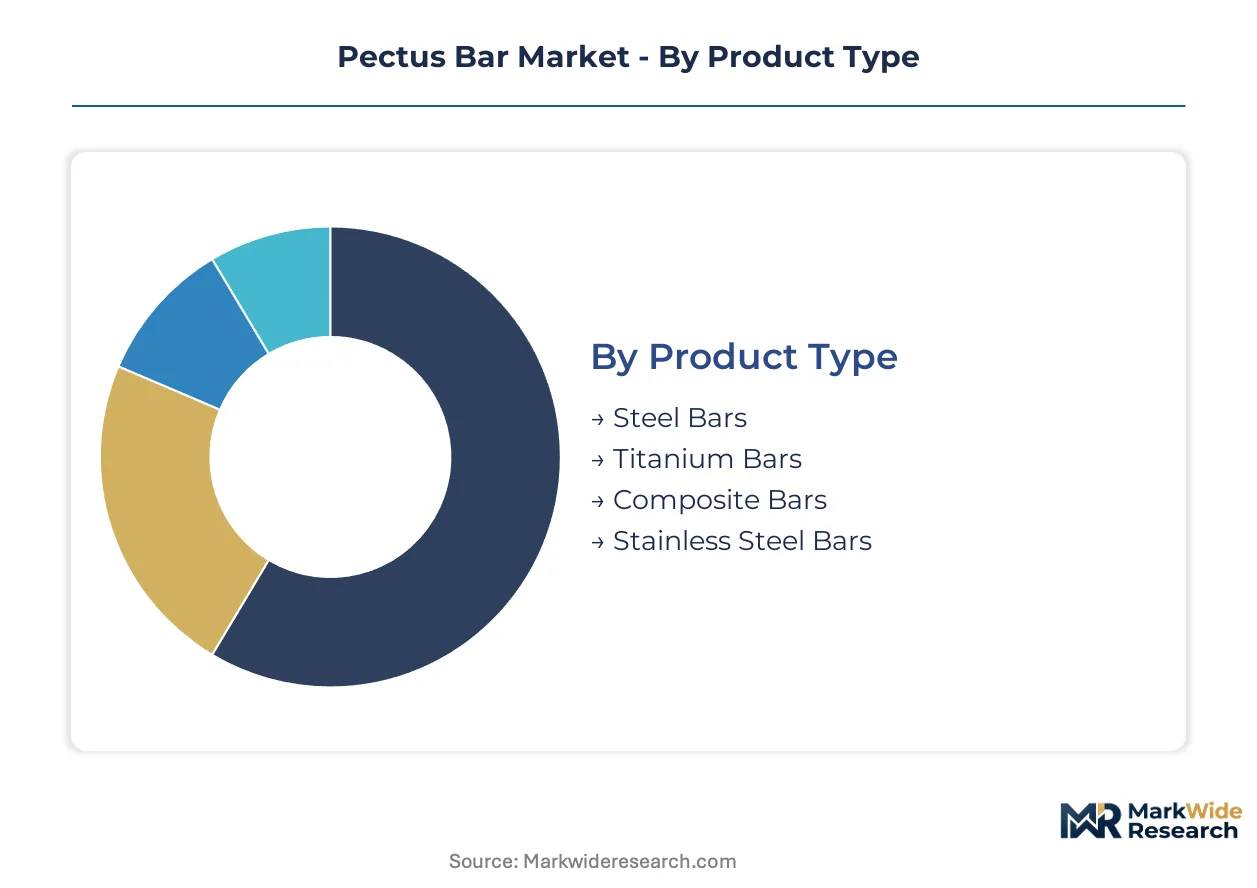
Pectus bar procurement patterns diverge sharply across material grades, surgical settings, and technique sophistication. Hospital value-analysis committees now segment purchasing decisions by magnetic-resonance compatibility and long-term implant durability rather than unit cost alone.
Product Type:
FDA 510(k) predicates and EU MDR technical documentation requirements create divergent certification burdens across metallic compositions, with titanium alloys demanding more extensive biocompatibility dossiers than ferrous alternatives.
- Titanium Bars:These implants utilize Ti-6Al-4V ELI alloy with optimized elastic modulus matching pediatric rib compliance. Demand concentrates in tertiary children's hospitals across the United States and Germany where MRI surveillance protocols dominate postoperative monitoring. Magnetic-resonance compatibility eliminates imaging artifacts during cardiac and spinal evaluation.
- Stainless Steel Bars:Surgical-grade 316L stainless delivers cost-efficient sternal elevation with established fatigue resistance profiles. Procurement remains anchored in South Korean and Indian hospital systems where capital budgets prioritize procedure volume over imaging flexibility.
- Composite Bars:Carbon-fiber-reinforced polymer prototypes target niche applications demanding radiolucency.
- Steel Bars:Generic carbon-steel variants serve budget-constrained markets with shorter implantation horizons.
Titanium bars handle the majority of throughput in premium-tier procurement; composite bars are expanding most quickly in experimental protocols.
End User:
Capital equipment intensity and surgeon certification requirements stratify purchasing authority across facility types, with inpatient surgical infrastructure determining device selection latitude.
- Hospitals:Academic medical centers with dedicated pediatric thoracic divisions command the highest pectus bar volumes, leveraging fellowship-trained specialists and hybrid operating suites. United States children's hospitals in Boston, Philadelphia, and Cincinnati maintain dedicated chest-wall surgery programs with recurring annual caseloads.
- Surgical Centers:Ambulatory facilities concentrate on bar removal procedures as fast-track protocols mature, creating discrete procurement streams distinct from primary implantation.
- Clinics:Diagnostic and referral hubs coordinate preoperative imaging and postoperative surveillance without direct device purchasing authority.
- Specialty Care Facilities:Congenital anomaly centers integrate pectus correction within multidisciplinary chest-wall reconstruction portfolios.
Hospitals absorb the dominant share of implant procurement; surgical centers are gaining share fastest as removal procedures migrate outpatient.
Delivery Mode:
Reimbursement coding and facility fee structures determine where procedural episodes physically occur, with device procurement following patient flow rather than driving it.
- In-Person:Traditional hospital-based surgical encounters retain dominance for primary Nuss procedure implantation, requiring general anesthesia and thoracoscopic visualization infrastructure.
- Outpatient Services:Bar removal procedures increasingly shift to ambulatory surgical settings with reduced anesthesia requirements and same-day discharge protocols.
- Telehealth:Virtual consultation platforms manage preoperative screening and postoperative surveillance without device handling.
- Home Care:Pain management and physical therapy protocols extend recovery monitoring beyond facility walls.
In-person delivery maintains procedural dominance; outpatient services are climbing the fastest as payors incentivize site-of-care migration.
Technology:
Surgeon training pipelines and equipment amortization schedules lock technique adoption patterns, with minimally invasive certification bottlenecks constraining procedural expansion.
- Minimally Invasive:The Nuss procedure utilizing thoracoscopic guidance and substernal bar placement has displaced open techniques across trained surgeon cohorts. South Korean and German surgical consortia have standardized proctoring pathways that accelerate technique dissemination.
- Open Surgery:Ravitch procedure modifications persist for complex redo operations and asymmetric deformities beyond standard bar correction geometry.
- Robotic Surgery:Da Vinci platform utilization remains experimental, with instrument collision constraints limiting adoption in narrow pediatric thoracic cavities.
- Hybrid Techniques:Combined approaches merge limited open access with thoracoscopic visualization for revision cases.
Minimally invasive technology commands the steepest expansion trajectory; open surgery retains relevance in revision and complex primary cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric thoracic surgery programs concentrate procurement authority in academic medical centers with dedicated chest-wall divisions, creating geographic demand clusters around fellowship-trained specialist cohorts.
United States
Children's hospitals in Boston, Philadelphia, and Cincinnati maintain dedicated pectus surgery programs with recurring annual caseloads. FDA 510(k) premarket notification pathways govern device entry timelines for implantable metal innovations. Texas and Florida health systems are consolidating purchasing authority through integrated delivery network contracts.
Germany
Tertiary hospitals in Berlin and Munich prioritize titanium alloy procurement for MRI-compatible pediatric protocols. EU MDR CE marking requirements under the Medical Device Regulation extend certification timelines for Class III thoracic implants. The country's notified-body relationships anchor European distribution reach for specialized manufacturers.
South Korea
Seoul-based pediatric thoracic centers have achieved procedural mass that sustains recurring demand for minimally invasive correction devices. The MFDS maintains distinct regulatory pathways for foreign-manufactured implants. Research consortia in the capital region are accelerating preclinical evaluation of bioresorbable sternal support prototypes.
Japan
PMDA master-file procedures for foreign-manufactured thoracic implants create documentation burdens that filter market entry. Tokyo and Osaka academic medical centers concentrate specialized Nuss procedure expertise. The country's national health insurance reimbursement determinations shape hospital procurement priorities for implantable devices.
United Kingdom
London and Birmingham pediatric surgery units are expanding minimally invasive program volumes within NHS framework agreements. MHRA post-Brexit regulatory alignment with EU MDR standards maintains certification continuity for CE-marked devices. Regional specialist commissioning groups are consolidating referral pathways for congenital chest-wall deformities.
Pectus Bar Market Competitive Landscape
Player mix skews toward orthopedic implant conglomerates with thoracic diversification and dedicated chest-wall specialists with surgeon training infrastructure. Market structure exhibits moderate consolidation around manufacturers with notified-body relationships and quality-management depth. Two strategic archetypes dominate: diversified orthopedic portfolios leveraging existing distribution infrastructure, and focused thoracic specialists competing through direct surgeon education investments. Competitive moves concentrate on European MDR certification capacity and US hospital value-analysis committee penetration.
Among Germany-based specialists, Biotech GmbH and KLS Martin Group exemplify the dedicated thoracic archetype, occupying positions sustained through direct proctoring relationships and specialized repair portfolios. Zimmer Biomet represents the diversified orthopedic conglomerate model, anchoring European distribution reach through existing implant infrastructure. IDEAR S.R.L. and Ventura Medical Technologies sit within mid-tier specialist cohorts competing across Mediterranean and Latin American surgical centers.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Biotech GmbH |
| IDEAR S.R.L. |
| MedXpert GmbH |
| KLS Martin Group |
| Reid Healthcare |
| Ventura Medical Technologies |
| Stryker Corporation |
| Medtronic |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month EU MDR certification lead times concentrate procurement negotiating power among notified-body-endorsed manufacturers, compressing margin structures for titanium alloy suppliers while elevating price premiums for MRI-compatible implant grades.
Pricing Analysis
Cost-plus contracts with titanium sponge indexation dominate hospital system agreements, linking implant pricing to aerospace sector commodity volatility. Three-tier pricing structure across premium titanium, standard stainless steel, and economy carbon-steel levels separates procurement tiers by magnetic-resonance compatibility and fatigue-resistance documentation. Pricing pressure stems from fixed-price contract exposure when raw material costs spike, particularly affecting 316L stainless suppliers serving South Korean volume purchasers. Pediatric thoracic divisions at academic medical centers exhibit lowest price sensitivity due to MRI protocol mandates, while Indian hospital systems prioritize economy grades.
Supply Chain Analysis
China and Russia produce the majority of titanium sponge feedstock for medical-grade alloy production. Surgical-grade stainless steel draws from German and Japanese mill operations with established orthopedic implant certifications. Single-source vulnerability concentrates in titanium sponge refining capacity, where aerospace demand spikes disrupt medical alloy allocation. Distribution runs through orthopedic implant distributors with dedicated thoracic surgery sales specialists, bypassing general surgical device channels for high-volume pectus programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioresorbable sternal support technologies threaten long-term metal bar demand, forcing incumbents to defend implant revenue while funding next-generation material platforms.
For Market Incumbents: Shield titanium alloy market share by deepening backward integration into surgical-grade titanium billet supply. Accelerate EU MDR technical documentation investment to exploit notified-body capacity constraints that filter competitor entry. Prioritize direct surgeon proctoring relationships to lock referral flows against bioresorbable trial recruitment. For New Entrants and Emerging Players: Surgeon training infrastructure gaps in secondary metropolitan markets offer white-space entry points beyond established academic centers. Target adult pectus correction segments where specialist concentration remains thin and hospital value-analysis committees lack standardized vendor scorecards. Pursue fast-track bar removal protocol partnerships with ambulatory surgery centers to build procedural volume credibility. For Investors and Strategic Acquirers: Long-term, this sits as a substitution-defense play because bioresorbable platform maturation will fragment R&D returns across material paradigms. Target acquisition profiles should emphasize notified-body relationships and quality-management depth over pure market share. Monitor South Korean and German pediatric research consortium publication velocity as the inflection signal for bioabsorption timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR certification unlocks access to German and UK pediatric thoracic centers with consolidated purchasing authority. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and Florida concentrate volume commitments for multi-year procurement cycles. |
| Software Companion Development | Preoperative sternal modeling platforms differentiate titanium bar offerings in academic medical center value analyses. |
| Reimbursement Strategy | CMS determination requests for minimally invasive chest-wall procedures shape hospital capital equipment investment timelines. |
| FDA Submission | 510(k) predicate equivalence demonstrations accelerate market entry against established stainless steel and titanium devices. |
Research Methodology
A standing panel of pediatric thoracic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified-body certification records, CMS Medicare reimbursement determinations, and hospital procurement database extracts. Bottom-up implant volume estimates triangulated against top-down market sizing from orthopedic implant trade associations.
Consistency checks validated volume and value outputs against external benchmarks including surgical procedure registries and medical device import-export trade flows across the analysis window. Segmentation modeling incorporated material grade, end-user facility type, delivery mode, and surgical technique sophistication. CAGRs derived from surgeon cohort expansion rates and pediatric thoracic fellowship graduation trajectories, cross-referenced against hospital infrastructure investment pipelines.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR notified-body operations; material policy shifts would require re-modeling. Specific risks include titanium sponge supply disruption from aerospace demand spikes and bioresorbable technology clinical trial success that accelerates substitution timelines. Recalibration cycles align with material shifts in surgeon training pipeline output and notified-body capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Needle Destroyer Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Creatinine Meter Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Medical Connector Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Feeding Tubes Market
Medical Devices
Ablation Devices Market
Medical Devices
Medical Device Cros Market
Medical Devices
Electrosurgical Devices Market