
 Global Motion Preservation Devices Market | 2026-2036
Global Motion Preservation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motion Preservation Devices Market Foresight
Modular implant kits that pair artificial discs with dynamic stabilization hardware is recalibrating how orthopedic clinics evaluate total procedure economics. Medtronic leverages its integrated surgical navigation ecosystem to anchor premium positioning across cervical and lumbar applications. Zimmer Biomet competes through specialized cobalt-chromium alloy platforms that dominate European regulatory submissions. Globus Medical differentiates via vertically controlled manufacturing of polyethylene cores that sustain margin pools in nucleus replacement.
Motion preservation devices comprise spinal implants engineered to restore segmental kinematics without fusion, typically incorporating cobalt-chromium endplates, ultra-high molecular weight polyethylene bearings, or silicone elastomer cores designed to withstand ten million cycles under ISO 18192-1 wear testing protocols. These systems serve the primary purpose of delaying or preventing adjacent segment disease following index-level decompression. Artificial disc systems occupy the largest revenue share due to established long-term clinical data and broad reimbursement coverage, while dynamic stabilization devices represent the fastest-expanding category as surgeons seek motion-sparing alternatives for younger, active patients. Metallic alloy platforms retain the deepest installed base, though composite materials are gaining structural traction among academic hospitals pursuing patient-specific modulus matching.
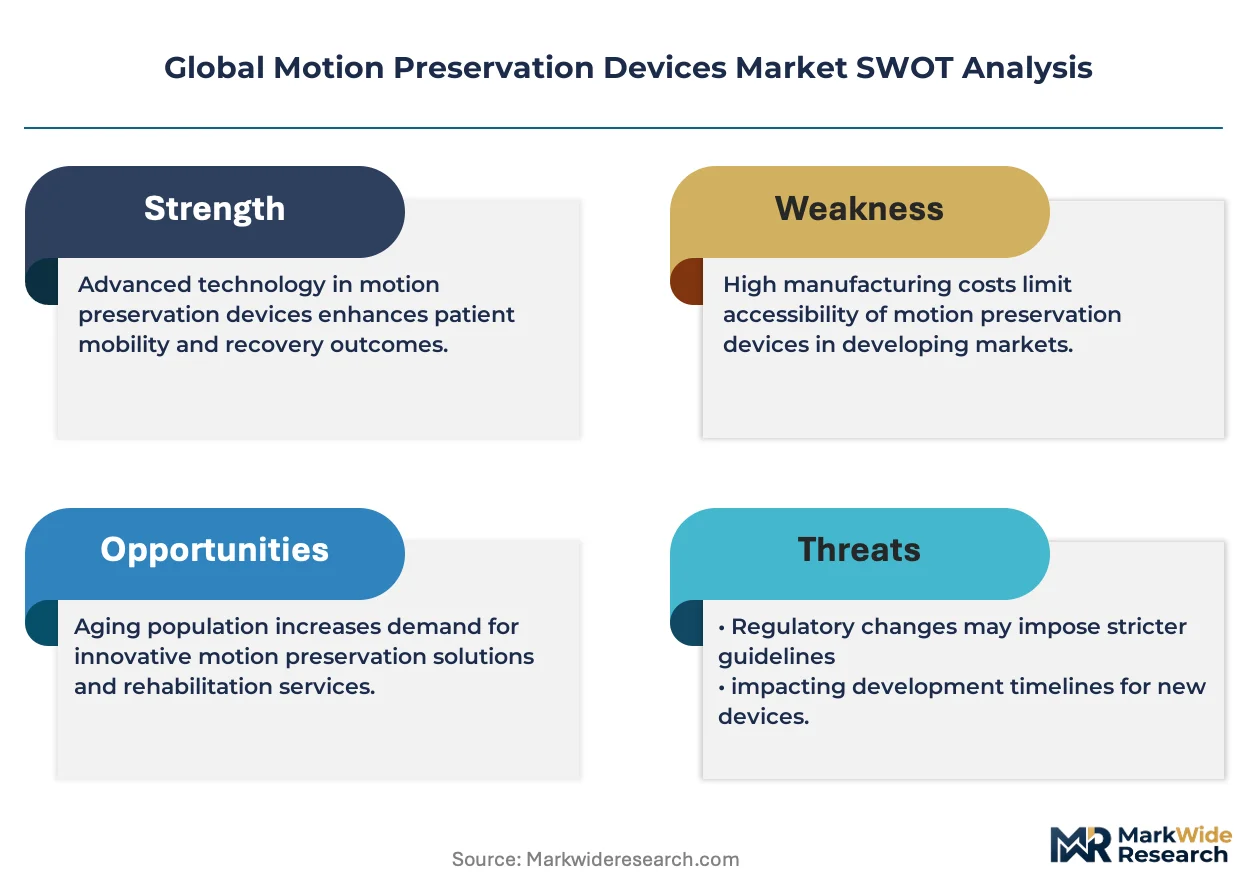
The FDA's stringent premarket approval requirements for cervical artificial discs shape trial design costs and timeline risk for entrants, while the EU Medical Device Regulation mandates enhanced clinical evidence through notified body oversight that constrains mid-tier manufacturers. Japan's PMDA enforces JIS-compliant biocompatibility testing that filters non-domestic suppliers from reimbursement eligibility. Stakeholders must monitor evolving health technology assessment criteria across Germany's G-BA and England's NICE, as these bodies increasingly condition reimbursement on demonstrated superiority to fusion at five-year follow-up intervals.
Market Dynamics
The FDA's premarket approval pathway for Class III spinal devices concentrates development risk among well-capitalized manufacturers, while Japan's PMDA biocompatibility standards filter reimbursement eligibility and reshape competitive entry economics across the cervical and lumbar implant segments.
Growth Catalysts
- Aging surgical populations:Germany, Japan, and the United States report expanding volumes of patients over sixty-five seeking motion-sparing alternatives to fusion, driving hospital procurement of artificial disc systems.
- ISO 18192-1 wear testing validation:Standardized ten-million-cycle endurance protocols now underpin regulatory submissions across cobalt-chromium and polyethylene bearing platforms, compressing clinical evidence timelines for novel materials.
- Adjacent segment disease prevention:Academic medical centers in Switzerland and Australia prioritize implants that preserve kinematics at index levels, shifting surgical training curricula toward dynamic stabilization techniques.
Market Restraints
- Cobalt-chromium alloy supply concentration:Primary smelting capacity for medical-grade alloys clusters in Germany and Japan, exposing device manufacturers to input cost volatility and geopolitical supply friction.
- EU Medical Device Regulation clinical evidence burdens:Enhanced notified body oversight for Class III implants extends review timelines and elevates documentation costs for mid-tier manufacturers without established predicate devices.
- Adjacent segment disease uncertainty:Five-year superiority data required by England's NICE and Germany's G-BA remains incomplete for several dynamic stabilization platforms, constraining reimbursement expansion.
Strategic Opportunities
- Underpenetrated Latin American markets:Brazil's ANVISA pathway for imported spinal implants lacks domestic manufacturing requirements, creating first-mover positioning for ISO 13485-certified suppliers establishing distributor networks.
- Composite modulus-matching platforms:Patient-specific titanium-polymer hybrids that replicate vertebral stiffness are gaining traction at academic hospitals in the Netherlands and Sweden seeking alternatives to metallic alloy rigidity.
- Japan's PMDA streamlined review:Sakigake designation for breakthrough devices offers priority consultation and compressed approval timelines for artificial disc systems with novel bearing surfaces.
Industry Challenges
- Biomechanical testing talent scarcity:Specialized engineers capable of ISO 18192-1 protocol execution and finite element modeling for spine kinematics command premium compensation, constraining R&D throughput at emerging manufacturers.
- Legacy navigation system integration:Surgical platforms from competing ecosystem vendors utilize proprietary tracking protocols, forcing implant manufacturers to fund multi-platform compatibility engineering or surrender addressable case volume.
- CE marking transition timelines:Legacy MDD certificates expiring under the EU MDR require renewed clinical evidence for grandfathered devices, diverting regulatory affairs resources from novel product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motion Preservation Devices Market |
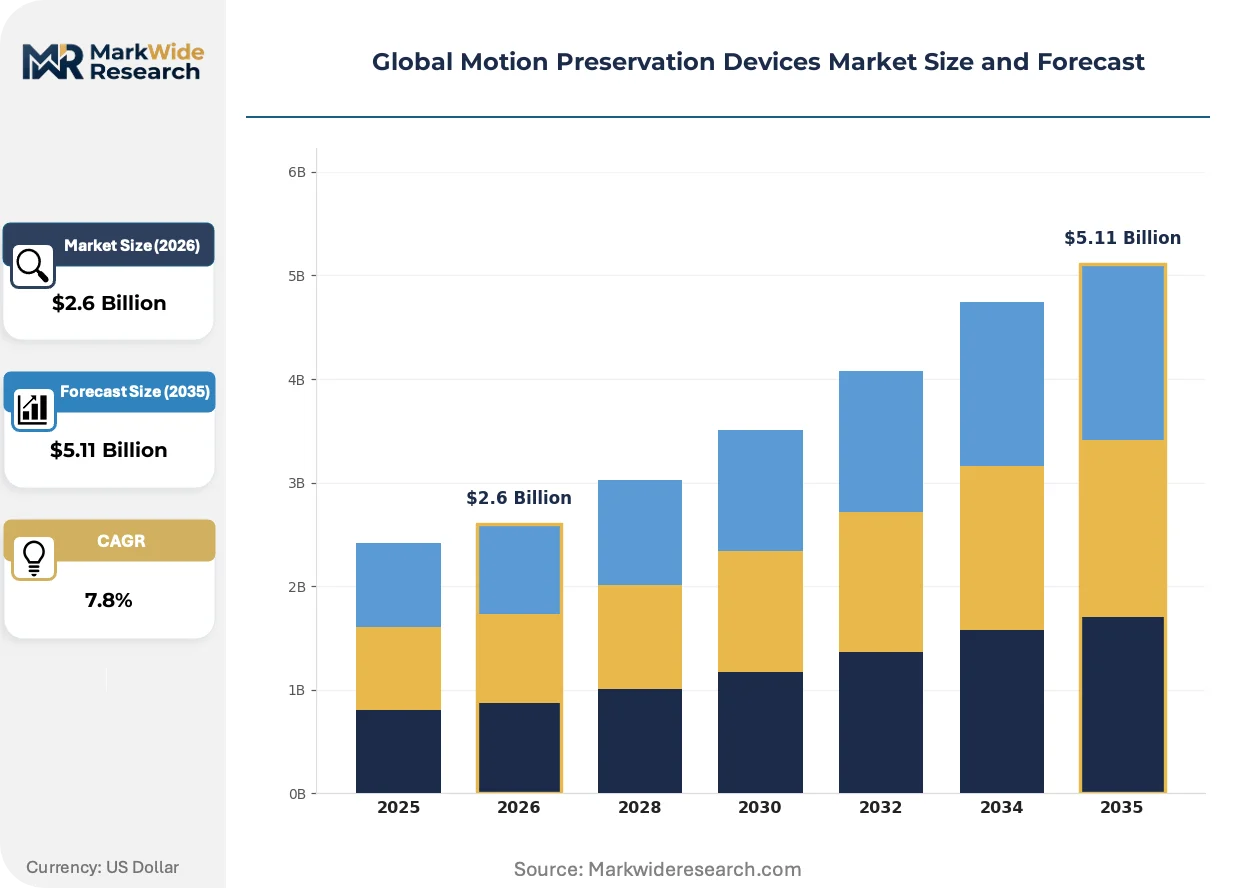
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $5.11 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Disc, Dynamic Stabilization Device, Nucleus Replacement, Facet Joint Replacement, Interspinous Process Implant Technology: Metallic Alloys, Polyethylene, Silicone Elastomers, Ceramics, Composite Materials Application: Cervical Spine, Lumbar Spine, Thoracic Spine, Adjacent Segment Disease, Chronic Back Pain End User: Orthopedic Clinics, Specialized Spine Centers, Rehabilitation Facilities, Ambulatory Surgery Centers, Academic Hospitals |
| Companies Covered | Medtronic, Johnson & Johnson (DePuy Synthes), Zimmer Biomet, Globus Medical, B. Braun Melsungen AG, Orthofix Medical, Aurora Spine, HPI Implants, NuVasive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motion Preservation Devices Market Shifts & Advancements
Modular implant architectures that pair artificial discs with dynamic stabilization hardware are recalibrating how orthopedic clinics evaluate total procedure economics and surgical training investments across cervical and lumbar applications.
Silicone elastomer core technology is consolidating as the preferred bearing material for nucleus replacement systems in younger patient cohorts. Academic spine centers in Switzerland and the Netherlands are adopting these platforms for single-level procedures. The shift is compressing demand for traditional metallic fusion cages in patients under fifty.
Japan's PMDA has tightened JIS-compliant biocompatibility testing requirements for non-domestic spinal implant suppliers. The regulation now mandates extended cytotoxicity and sensitization studies beyond ISO 10993 baselines. European manufacturers without Tokyo-based quality subsidiaries face exclusion from Japan's reimbursement formulary.
Hospital procurement committees now unbundle implant costs from bundled spinal procedure payments, forcing device vendors to justify premium positioning through demonstrated reductions in revision surgery rates. The change is most visible in Germany's G-DRG system and England's NHS tariff structures, where motion preservation devices must prove cost-effectiveness against fusion at thirty-six-month intervals.
Global Motion Preservation Devices Market Segmentation
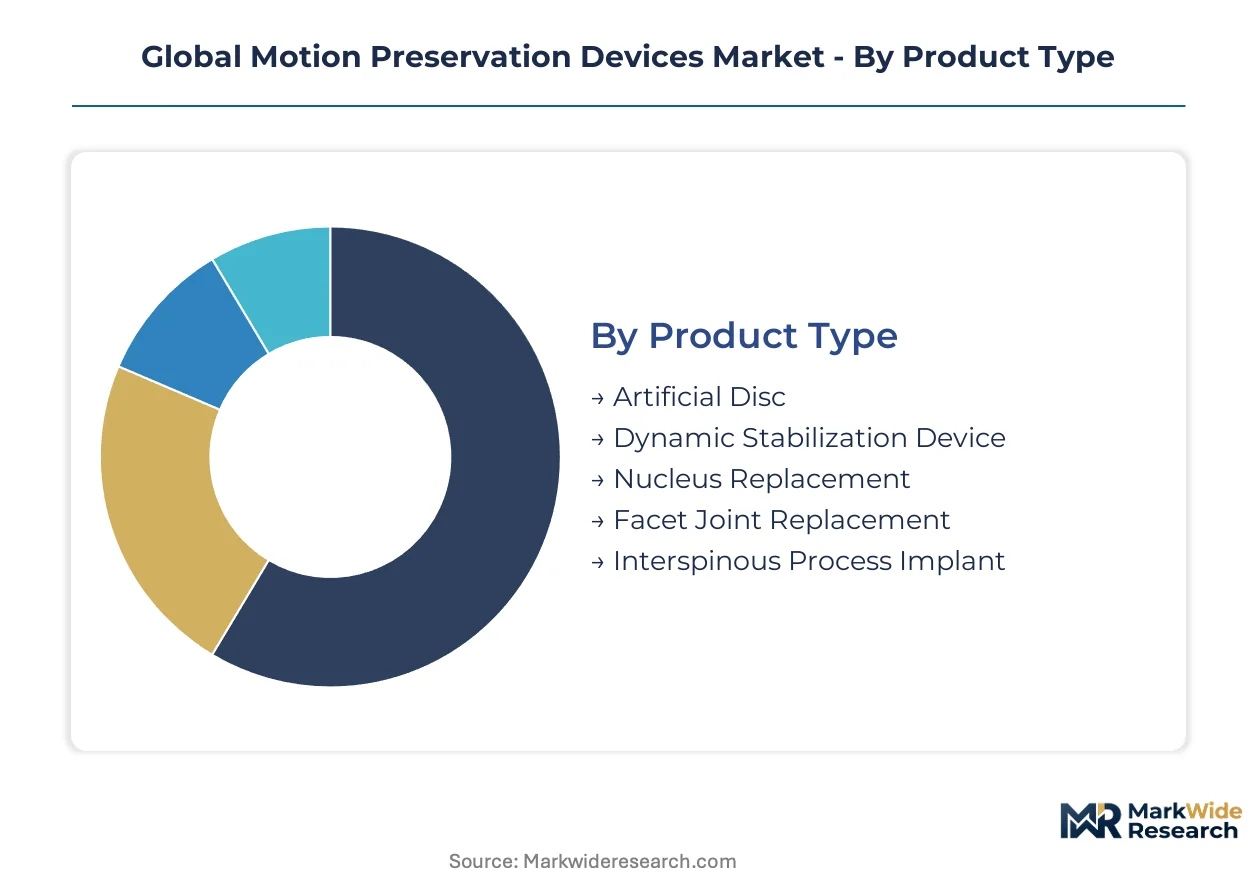
Segmentation in motion preservation devices reveals how capital allocation, regulatory burden, and surgical training investments concentrate across distinct technology platforms. Manufacturers prioritize segments where reimbursement pathways and clinical evidence requirements align with their balance sheet capacity.
Product Type:
Capital intensity varies sharply across implant categories, with artificial disc systems demanding the heaviest upfront investment in long-term clinical trials and PMA pathway navigation.
- Artificial Disc:Cobalt-chromium endplates paired with ultra-high molecular weight polyethylene bearings dominate cervical and lumbar applications. United States hospital procurement committees favor these systems where FDA premarket approval and established reimbursement codes reduce procurement risk.
- Dynamic Stabilization Device:Pedicle screw-based systems with flexible rods or interspinous spacers preserve motion while limiting range. Germany's specialized spine centers are expanding adoption for younger, active patients seeking alternatives to fusion.
- Nucleus Replacement:Silicone elastomer or hydrogel cores replace damaged nucleus pulposus while preserving annulus integrity.
- Facet Joint Replacement:Metallic or polymer implants address facet-mediated pain in patients with preserved disc height.
- Interspinous Process Implant:Minimally invasive spacers distract the spinous processes to relieve neurogenic claudication.
Artificial disc systems absorb the bulk of installed capacity; dynamic stabilization devices are expanding most quickly.
Technology:
Material selection governs wear performance, imaging compatibility, and modulus matching to vertebral bone, with metallic platforms currently holding the deepest clinical evidence repositories.
- Metallic Alloys:Cobalt-chromium-molybdenum and titanium alloys provide structural rigidity and proven biocompatibility under ISO 18192-1 wear protocols. Japan's PMDA maintains stringent JIS-compliant testing standards that filter non-domestic suppliers.
- Polyethylene:Cross-linked ultra-high molecular weight polyethylene serves as the dominant bearing surface in artificial disc cores. Academic hospitals in Switzerland prioritize these platforms for established long-term wear data.
- Silicone Elastomers:Flexible cores in nucleus replacement systems replicate native disc mechanics.
- Ceramics:Alumina and zirconia compositions offer extreme wear resistance and biocompatibility.
- Composite Materials:Titanium-polymer hybrids enable patient-specific modulus matching to vertebral stiffness.
Metallic alloys command the largest share of current implant volumes; composite materials are climbing the fastest as academic centers pursue personalized biomechanics.
Application:
Surgical volume and reimbursement complexity diverge sharply between cervical and lumbar segments, with cervical procedures commanding premium positioning due to technical precision requirements.
- Cervical Spine:Artificial disc replacement at C3-C7 levels preserves motion in patients with radiculopathy or myelopathy. United States Medicare coverage determinations favor these procedures over fusion in appropriately selected candidates.
- Lumbar Spine:Dynamic stabilization and artificial disc systems address degenerative disc disease at L1-L5. Germany's G-BA health technology assessments increasingly condition reimbursement on demonstrated superiority to fusion.
- Thoracic Spine:Motion preservation remains limited by anatomical constraints and surgical access challenges.
- Adjacent Segment Disease:Index-level motion preservation aims to prevent accelerated degeneration at neighboring segments.
- Chronic Back Pain:Diagnostic-specific implants target pain generators without fusion.
Cervical applications dominate revenue concentration; lumbar segments are gaining share fastest as dynamic stabilization training expands.
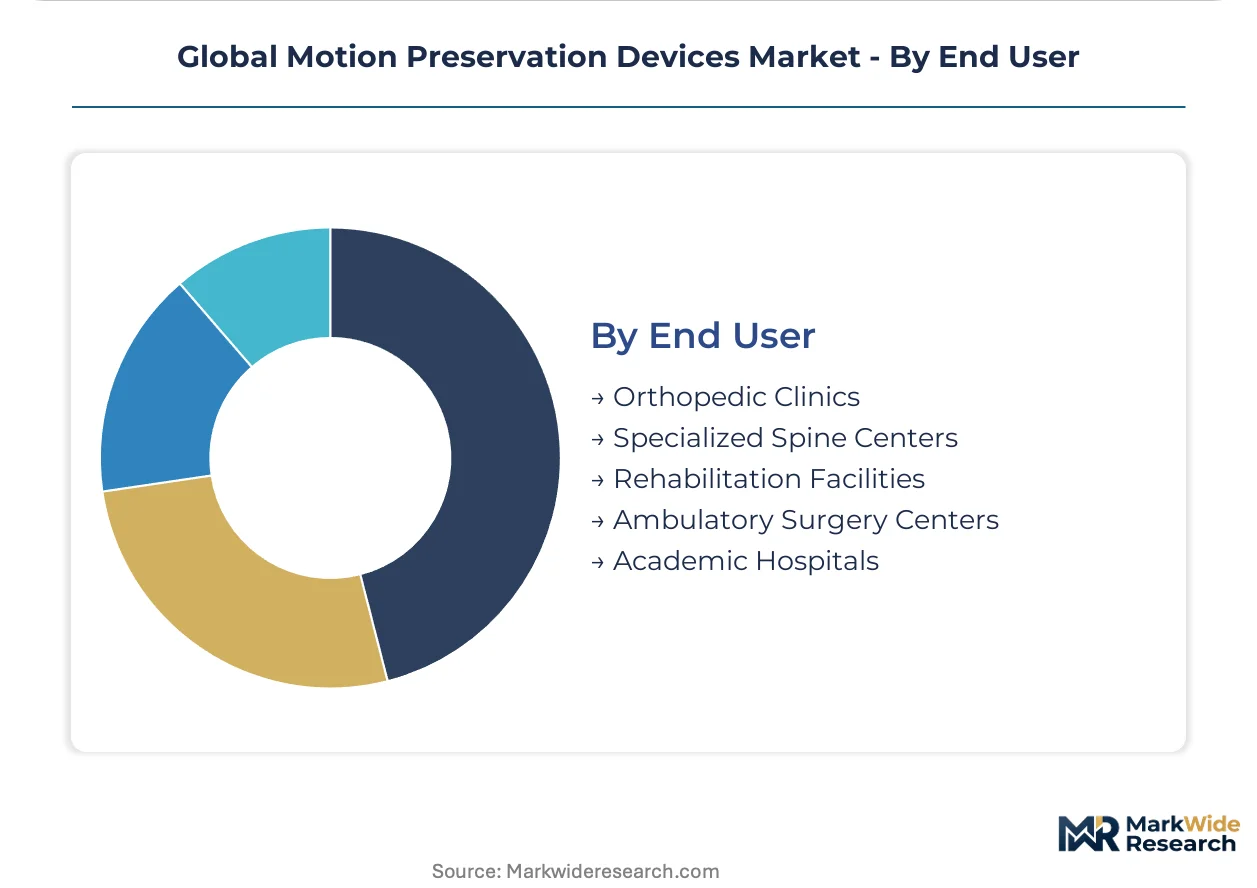
End User:
Procurement authority and case volume distribution vary across facility types, with specialized spine centers capturing the highest per-procedure implant values.
- Orthopedic Clinics:Outpatient-based practices focus on diagnostic workup and postoperative rehabilitation, with limited implant purchasing authority.
- Specialized Spine Centers:Dedicated facilities concentrate surgical volume and surgeon expertise for complex motion preservation procedures. Japan's urban academic clusters in Tokyo and Osaka anchor regional demand.
- Rehabilitation Facilities:Postoperative care and functional recovery programs support implant outcomes.
- Ambulatory Surgery Centers:Cost-conscious settings increasingly eligible for select cervical disc procedures.
- Academic Hospitals:Research-active institutions drive adoption of novel materials and train surgical residents in motion preservation techniques.
Specialized spine centers capture the highest implant values per procedure; ambulatory surgery centers are expanding eligibility fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of cobalt-chromium medical alloys concentrates in Germany and Japan, while surgical demand clusters in aging populations across the United States, Germany, and Japan. This geographic split shapes procurement patterns and regulatory compliance costs for device manufacturers.
United States
Medicare coverage determinations for cervical artificial disc replacement drive hospital procurement volumes, particularly for patients over sixty-five seeking alternatives to fusion. The FDA's premarket approval pathway for Class III spinal devices extends development timelines and elevates capital requirements for entrants. Specialized spine centers in Texas and California anchor regional surgical training and implant adoption curves.
Germany
Germany's G-BA health technology assessments increasingly condition reimbursement on five-year superiority data versus fusion, compressing margins for devices lacking long-term clinical evidence. The EU Medical Device Regulation mandates enhanced notified body oversight that extends review timelines for spinal implants. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg concentrate cobalt-chromium smelting capacity and precision machining for implant components.
Japan
Japan's PMDA enforces JIS-compliant biocompatibility testing that filters non-domestic suppliers from reimbursement eligibility, creating structural advantages for domestic manufacturers. The Sakigake designation for breakthrough devices offers priority consultation and compressed approval timelines for novel bearing surfaces. Urban academic clusters in Tokyo and Osaka concentrate surgical volume for motion preservation procedures and anchor regional demand.
Switzerland
Academic spine centers in Zurich and Geneva prioritize implants that preserve kinematics at index levels, shifting surgical training curricula toward dynamic stabilization techniques. Swissmedic maintains stringent clinical evidence requirements that align with EU MDR standards while permitting streamlined parallel submissions. The country's precision engineering heritage supports specialized manufacturing of polyethylene bearings and titanium-polymer composite platforms.
Brazil
Brazil's ANVISA pathway for imported spinal implants lacks domestic manufacturing requirements, creating first-mover positioning for ISO 13485-certified suppliers establishing distributor networks. Private hospital chains in São Paulo and Rio de Janeiro drive demand for premium motion preservation devices as out-of-pocket surgical volumes expand. Regulatory harmonization with Mercosur standards is compressing import documentation timelines for established suppliers.
Global Motion Preservation Devices Market Competitive Landscape
The competitive structure tilts toward diversified orthopedic conglomerates with integrated surgical navigation ecosystems and specialized spine-focused manufacturers with vertically controlled component production. Capital intensity and regulatory burden create tiered entry barriers that favor well-capitalized players with established predicate devices and long-term clinical data repositories. Two dominant archetypes occupy the premium tier: diversified medtech conglomerates leveraging cross-selling synergies, and specialized spine manufacturers controlling critical material inputs. Competitive moves concentrate on strategic partnerships for navigation system compatibility and backward integration into cobalt-chromium alloy supply.
Among diversified medtech conglomerates, Medtronic and Johnson & Johnson (DePuy Synthes) exemplify the integrated ecosystem archetype, anchoring premium positioning through surgical navigation and capital equipment bundling. Zimmer Biomet occupies a distinct position within the metallic alloy platform specialization tier. These three entities represent the primary competitive anchors against which mid-tier manufacturers and emerging specialists calibrate their market entry strategies and partnership priorities.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson (DePuy Synthes) |
| Zimmer Biomet |
| Globus Medical |
| B. Braun Melsungen AG |
| Orthofix Medical |
| Aurora Spine |
| HPI Implants |
| NuVasive |
| Others |
Supply & Pricing Matrix
Hospital procurement committees in Germany and England now unbundle implant costs from bundled spinal procedure payments, forcing device vendors to justify premium positioning through demonstrated reductions in revision surgery rates rather than brand heritage alone. This specification shift compresses margins for manufacturers lacking thirty-six-month clinical evidence while rewarding suppliers with vertically controlled production of polyethylene bearings and cobalt-chromium endplates.
Pricing Analysis
Cost-down pressure on mid-tier manufacturers accelerates because England's NICE and Germany's G-BA increasingly condition reimbursement on five-year superiority data versus fusion. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved systems with decade-long follow-up from CE-marked alternatives with shorter evidence bases. Price differentiation rests on ISO 18192-1 wear testing validation and JIS-compliant biocompatibility certification. Academic medical centers in Switzerland and Japan show least price sensitivity; ambulatory surgery centers in the United States exhibit highest.
Supply Chain Analysis
Explant retrieval and bearing surface analysis programs at academic hospitals in Switzerland and the Netherlands now feed refurbishment protocols for dynamic stabilization rods and interspinous spacers. Primary smelting capacity for medical-grade cobalt-chromium-molybdenum alloys clusters in Germany and Japan, with secondary machining of titanium-polymer composites concentrating in Switzerland. Raw material dependencies span cobalt ore from the Democratic Republic of Congo, chromium from South Africa, and medical-grade polyethylene resin from the United States. Single-source vulnerability in German alloy production exposes manufacturers to geopolitical friction. Distribution runs through specialized spine centers and GPO-contracted hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade cobalt-chromium alloy smelting capacity concentrates in two industrial clusters, propping pricing power for manufacturers with captive supply or long-term offtake agreements.
For Market Incumbents: Deploy backward integration into polyethylene core manufacturing to defend margin pools against emerging composite material platforms. Secure JIS-compliant testing capabilities in Tokyo-based quality subsidiaries before Japan's PMDA tightens reimbursement eligibility further. Lock in five-year clinical trial commitments at academic hospitals in Switzerland and Australia to satisfy Germany's G-BA superiority requirements. For New Entrants and Emerging Players: Ambulatory surgery centers in the United States seeking cervical disc procedures represent the most penetrable buyer archetype as Medicare coverage determinations expand eligibility. Brazil's ANVISA pathway for imported spinal implants lacks domestic manufacturing requirements, creating first-mover positioning for ISO 13485-certified suppliers. Partner with distributor networks in São Paulo and Rio de Janeiro rather than building direct sales infrastructure. For Investors and Strategic Acquirers: The window for entry favors specialized spine manufacturers with vertically controlled component production and established predicate devices for FDA premarket approval pathways. Long-term viability hinges on navigating EU MDR clinical evidence burdens and Japan's PMDA biocompatency filtering. Monitor England's NICE five-year superiority determinations for dynamic stabilization platforms as inflection indicator for reimbursement expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Class III spinal device designation extends timelines but anchors premium reimbursement positioning. |
| CE Marking Under EU MDR | Enhanced notified body oversight filters mid-tier manufacturers without established predicate devices. |
| Hospital System Partnership | GPO contracts with specialized spine centers in Texas and California secure procedural volume. |
| Software Companion Development | Surgical navigation ecosystem integration from Medtronic and Johnson & Johnson forces compatibility investment. |
| Reimbursement Strategy | Germany's G-BA and England's NICE condition coverage on demonstrated fusion superiority. |
Research Methodology
Independent corroboration across FDA premarket approval filings, EU MDR notified body submissions, and Japan's PMDA Sakigake designations underwrites the qualitative findings in this analysis. Primary interviews with spine surgeons at academic hospitals in Switzerland and the Netherlands, biomedical engineers at German cobalt-chromium smelters, and GPO contracts managers at United States hospital systems combined with secondary validation from ISO 18192-1 wear testing protocols and CMS Medicare coverage determinations. Bottom-up implant volume estimates and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical PMA approval timelines and reimbursement coverage expansion curves shaped the forecast framework across the projection horizon. Segmentation dimensions modeled include product type (artificial disc, dynamic stabilization, nucleus replacement), technology platform (metallic alloy, polyethylene, composite), application level (cervical, lumbar), and end-user facility type. CAGRs derive from surgical volume trajectories in aging populations over sixty-five and procurement committee unbundling trends. Industry-specific inputs span ISO 18192-1 wear cycle completion rates and JIS biocompatibility study durations.
Revisions become necessary when FDA premarket approval pathways extend beyond historical precedent, EU MDR notified body capacity constraints materialize, or Japan's PMDA tightens JIS testing requirements further. Practitioners should monitor England's NICE five-year superiority determinations and Germany's G-BA health technology assessment criteria for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Middle East and Africa Hip and Knee Reconstruction Devices Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
Arthroscopy Market
Medical Devices
Middle East and Africa Surgical Equipment Market
Medical Devices
Urine Flow Meters Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
External Defibrillator Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Global Non-Surgical Aesthetic Devices Market
Medical Devices
Non-Destructive Medical Technologies Market