
 Nasal Atomizer Devices Market | 2026-2036
Nasal Atomizer Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Atomizer Devices Market Outlook
Micro-dosing pump technology is reconfiguring precision standards across nasal delivery platforms. Teleflex Incorporated leverages its critical care portfolio to anchor hospital channel dominance in acute settings. Becton Dickinson and Company sustains manufacturing scale across disposable atomizer lines for emergency and pre-hospital use. Kurve Therapeutics differentiates through specialized intranasal therapeutic delivery systems targeting neurological indications.
Nasal atomizer devices are mechanical or electromechanical instruments designed to aerosolize liquid formulations into particle sizes typically ranging from 10 to 50 microns for deposition onto the nasal mucosa, serving primary purposes in rapid drug absorption, vaccine administration, and topical decongestant delivery. The manual product type occupies the largest installed base due to low cost and minimal training requirements, though electric variants are gaining traction in institutional settings where dosing consistency matters. Among applications, vaccine delivery represents the fastest-expanding segment as public health agencies stockpile intranasal immunization platforms, while pain management retains the deepest margin pools due to opioid-sparing protocols in emergency departments.
The FDA oversees combination product classifications for drug-device nasal systems, while ISO 13485 quality management standards govern manufacturing consistency across suppliers seeking market access. The EPA regulates propellant chemistries in metered-dose formats, creating reformulation obligations for manufacturers with legacy aerosol portfolios. Stakeholders must monitor evolving pharmacopeial standards for droplet size distribution and biocompatibility testing as regulatory convergence between drug and device pathways intensifies.
Market Dynamics
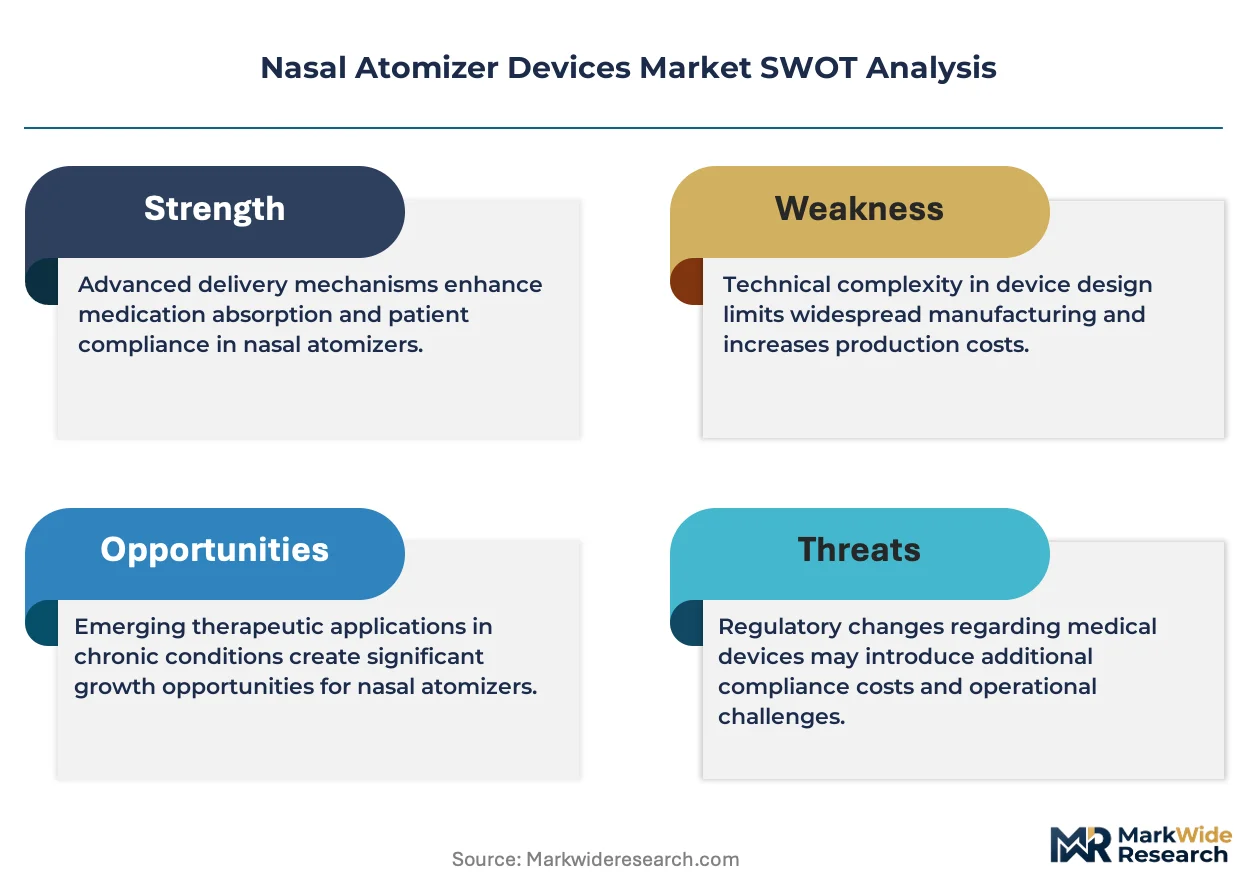
Micro-dosing pump technology is compressing tolerances for particle size distribution, forcing manufacturers to retool legacy mechanical platforms or cede acute-care procurement contracts to precision-engineered alternatives.
Growth Catalysts
- FDA combination product guidance:Tighter device-drug interface standards are accelerating hospital procurement of validated nasal delivery systems over unregulated alternatives.
- Intranasal vaccine platforms:Public health stockpiling programs are expanding institutional demand for single-use atomizers with validated sterility assurance.
- Emergency medicine protocols:Opioid-sparing pain management pathways in trauma centers are embedding atomized intranasal delivery into standard-of-care workflows.
Market Restraints
- Medical-grade polymer feedstock volatility:Specialized polypropylene and polycarbonate resins face price instability tied to petrochemical supply chains concentrated in the US Gulf Coast.
- Propellant chemistry constraints:EPA regulations on hydrofluorocarbon emissions are forcing reformulation of legacy metered-dose formats, raising R&D overhead for established portfolios.
- Silicone component concentration:Precision pump diaphragms and seals rely on specialized medical silicone suppliers concentrated in Germany and Japan, creating single-source vulnerability.
Strategic Opportunities
- Neurological therapeutic delivery:Blood-brain barrier penetration via optimized olfactory deposition is opening CNS indication development for specialized device developers.
- Pre-hospital emergency services:Fire department and ambulance corps procurement outside traditional hospital channels remains underpenetrated relative to clinical adoption depth.
- ISO 13485 convergence:Harmonized quality management standards across notified bodies are reducing duplicate certification costs for multi-market entrants.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for novel polymer formulations extend product development cycles by 12-18 months.
- Cross-functional talent scarcity:Combined pharmaceutical and mechanical engineering expertise for combination product development commands premium compensation and limited availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Atomizer Devices Market |
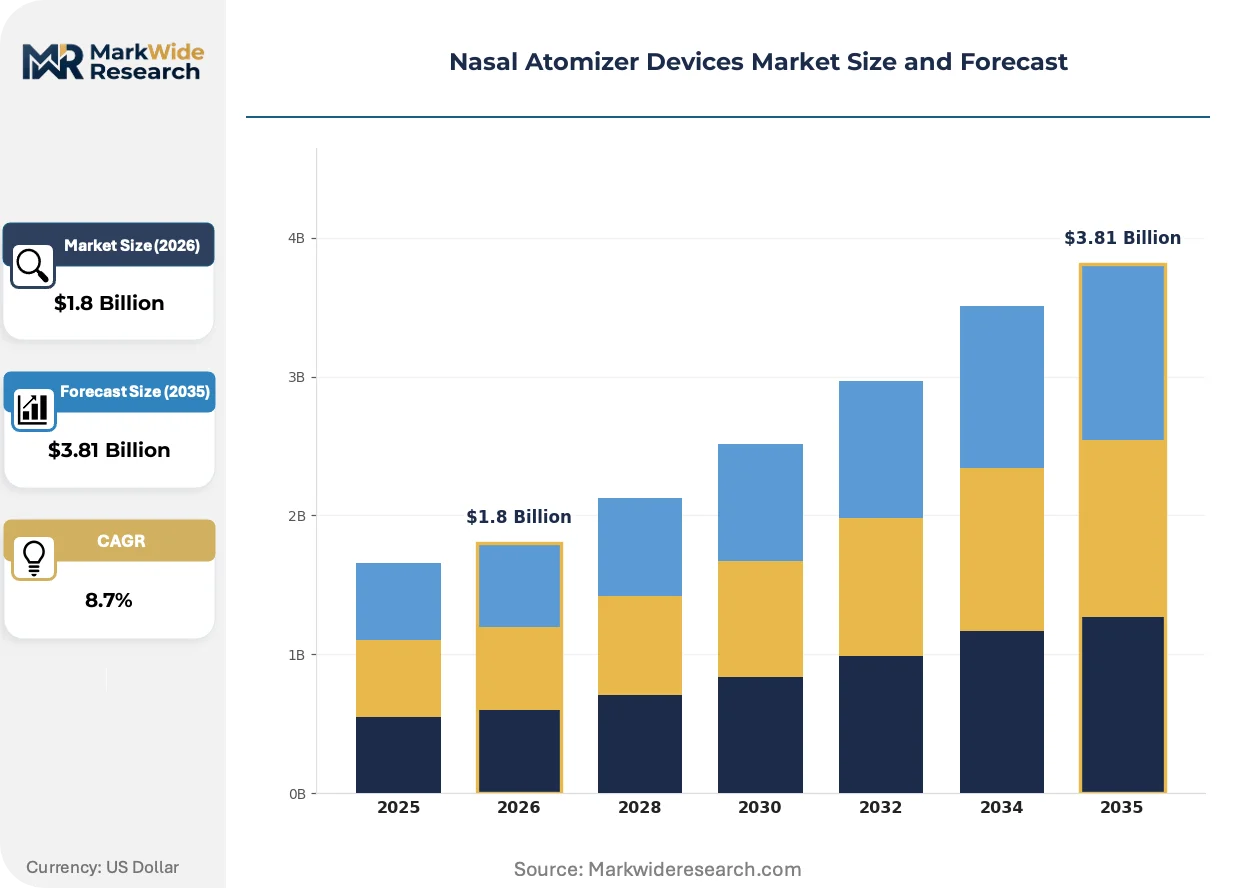
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Disposable, Reusable End User: Home Care, Hospitals, Clinics, Pharmacies Delivery Mode: Aerosol, Metered Dose, Spray, Powder Application: Allergy Treatment, Pain Management, Nasal Congestion, Vaccine Delivery |
| Companies Covered | Teleflex Incorporated, Becton Dickinson and Company, DeVilbiss Healthcare LLC, Cook Medical, Medspray, Intersurgical Ltd., Medline Industries, Pulmodyne Inc., Kurve Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Atomizer Devices Market Strategic Shifts
Precision manufacturing and regulatory convergence are compressing development cycles while fragmenting competitive advantage across specialized technical capabilities rather than scale economics alone.
Electromechanical micro-pump architectures with piezoelectric actuation are achieving sub-10-micron droplet consistency for deep nasal cavity deposition. Academic medical centers and military medical procurement units are piloting these platforms for rapid-onset analgesic and anti-seizure protocols. Fixed-volume mechanical squeeze bottles are rendering obsolete in settings where dosing precision affects therapeutic outcome.
REACH chemical registration requirements in Europe are tightening disclosure obligations for propellant and surfactant chemistries in metered-dose nasal systems. Manufacturers with legacy aerosol portfolios face substance evaluation costs that favor reformulation toward mechanical pump alternatives. The MDR medical device regulation is accelerating this transition by elevating clinical evidence requirements for drug-device combinations.
Hospital procurement departments are consolidating vendor lists around suppliers with validated combination product dossiers, displacing fragmented purchasing across multiple single-use device categories. Group purchasing organizations are centralizing nasal delivery contracts with manufacturers holding FDA-approved device master files. This concentration is most visible in United States trauma center networks and military health system procurement.
Nasal Atomizer Devices Market Segmentation
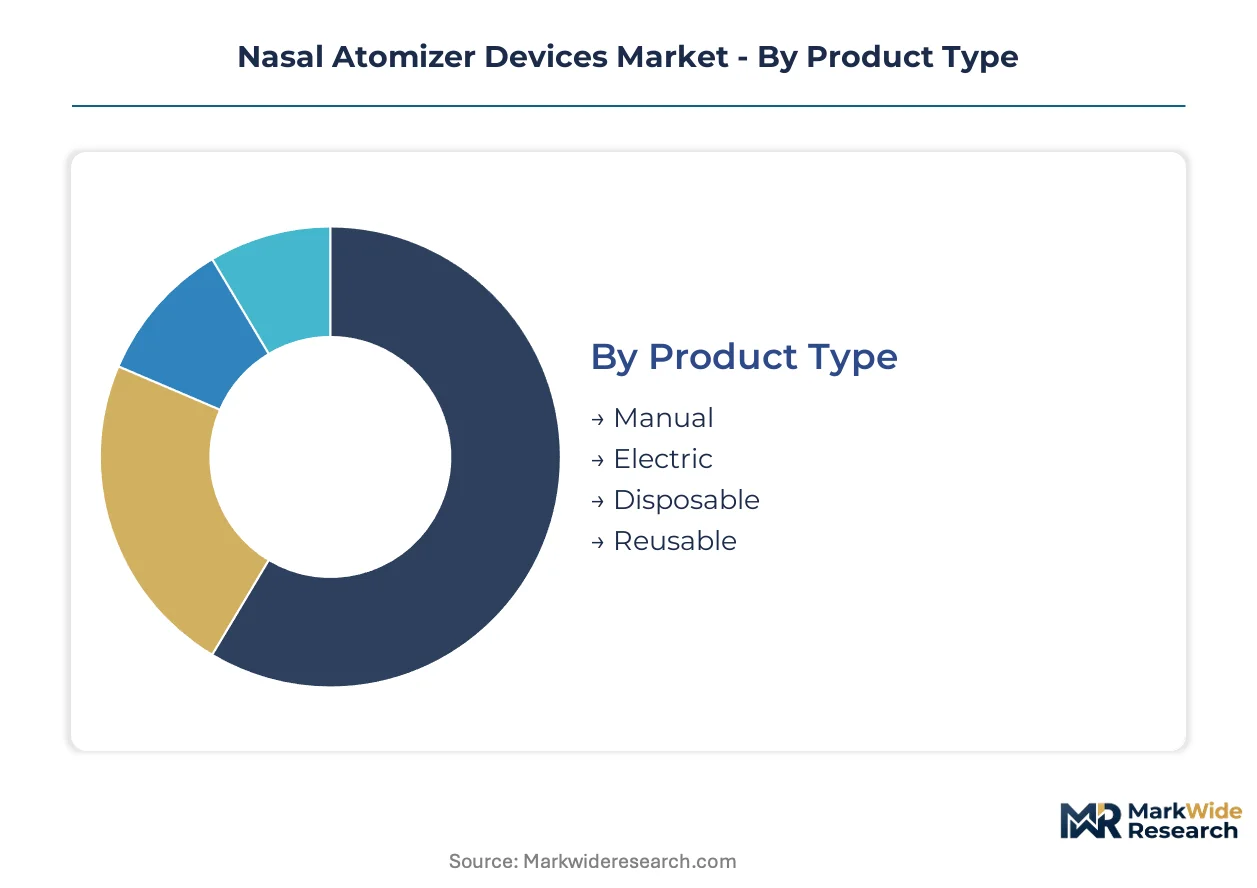
Nasal atomizer segmentation separates procurement channels by service intensity and clinical validation requirements. Hospital buyers prioritize validated combination product dossiers, while home care channels emphasize simplicity and cost minimization.
Product Type:
After-sales service intensity varies sharply across mechanical and electromechanical platforms, with electric variants demanding calibration protocols and field service networks that reshape distributor economics.
- Manual:Squeeze-bottle or bulb-actuated mechanical designs deliver 10-50 micron droplets through passive force generation. Trauma centers in the United States anchor procurement volume for emergency analgesia protocols where speed trumps precision tolerance.
- Electric:Piezoelectric or battery-driven micro-pump architectures achieve sub-10-micron consistency for deep olfactory deposition. Academic medical centers and military medical units in the United States are piloting these platforms for rapid-onset CNS therapeutics where dosing precision affects therapeutic outcome.
- Disposable:Single-use polymer assemblies eliminate cross-contamination risk in institutional settings. Public health stockpiling programs favor validated sterility assurance.
- Reusable:Autoclavable metal and medical-grade polymer constructions reduce per-dose cost for chronic therapy regimens. Home care channels in the United States prefer these for long-term allergy management.
Manual devices hold the largest share; momentum sits with electric variants as precision requirements tighten in acute care.
End User:
Cost tier stratification separates premium-validated institutional procurement from economy-oriented consumer channels, with reimbursement codes determining viable price points.
- Home Care:Direct-to-patient distribution through retail pharmacy and e-commerce channels emphasizes intuitive operation without clinical supervision. Medicare reimbursement for durable medical equipment shapes viable product configurations in the United States.
- Hospitals:Emergency medicine departments and trauma centers command the deepest procurement volumes with validated combination product requirements. FDA device master file holders capture concentrated purchasing through group purchasing organization contracts in the United States.
- Clinics:Outpatient settings balance cost sensitivity with regulatory compliance for moderate-acuity indications. Allergy specialists and pain management practices drive recurring consumption.
- Pharmacies:Community and specialty pharmacy dispensing of co-packaged drug-device combinations requires inventory integration with pharmaceutical distribution networks. United States retail chains are expanding clinical service offerings that include nasal delivery training.
Hospitals command the deepest volume pools; home care is climbing the fastest as chronic indication penetration expands.
Delivery Mode:
Application specificity determines viable particle size distribution and deposition patterns, with vaccine platforms demanding validated sterility that constrains format selection.
- Aerosol:Propellant-driven continuous mist generation achieves broad nasal cavity coverage. EPA hydrofluorocarbon regulations in the United States are forcing reformulation of legacy chemistries.
- Metered Dose:Fixed-volume mechanical or electromechanical actuation delivers precise unit doses for pharmaceutical co-development. FDA combination product guidance elevates validation requirements for device-drug interfaces in the United States.
- Spray:Pump-actuated mechanical systems dominate institutional procurement for emergency medicine applications. Low unit cost and minimal training requirements sustain installed base.
- Powder:Dry particle aerosolization eliminates cold-chain requirements for thermolabile biologics. Vaccine delivery platforms are gaining traction in public health stockpiling.
Spray formats hold the largest share; powder delivery is gaining share fastest as thermostable vaccine platforms advance.
Application:
Margin structure varies by therapeutic category, with acute pain management commanding premium pricing and vaccine platforms prioritizing scale economics over per-unit margin.
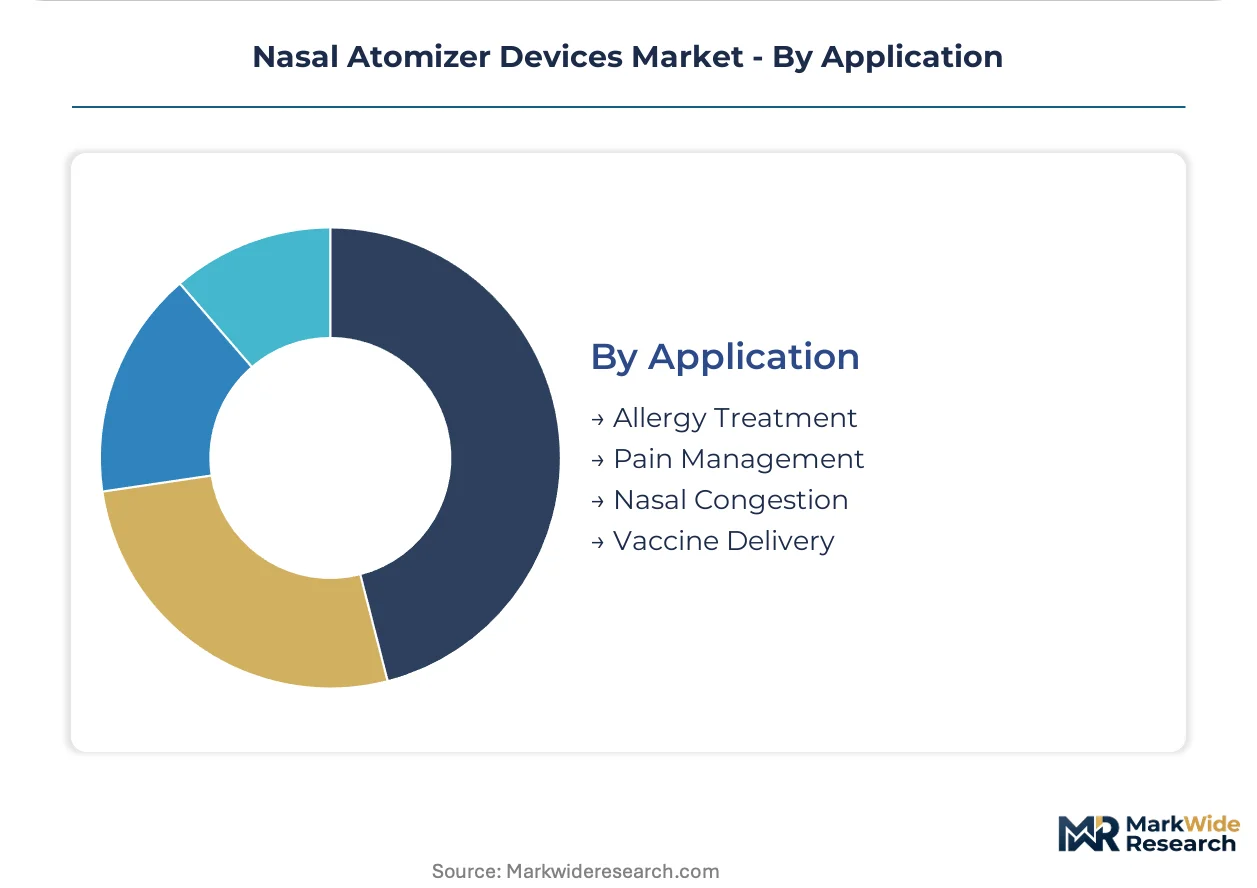
- Allergy Treatment:Chronic seasonal and perennial rhinitis management drives recurring consumption of corticosteroid and antihistamine delivery. United States retail pharmacy channels dominate volume.
- Pain Management:Opioid-sparing emergency protocols for trauma and burn care embed atomized intranasal delivery into standard-of-care workflows. United States hospital procurement anchors the deepest margin pools.
- Nasal Congestion:Decongestant and saline irrigation applications serve acute symptomatic relief with high purchase frequency. Over-the-counter retail channels in the United States concentrate volume.
- Vaccine Delivery:Intranasal immunization platforms for respiratory pathogens are expanding institutional demand with validated sterility requirements. CDC and BARDA procurement in the United States is accelerating adoption.
Pain management retains the deepest margin pools; vaccine delivery shows the steepest expansion trajectory as pandemic preparedness programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision pump manufacturers export electromechanical atomizer components to United States trauma centers and military medical procurement units, anchoring transatlantic trade flows in high-acute care delivery systems.
United States
Trauma centers and military medical procurement anchor institutional demand for validated combination product dossiers. FDA device master file requirements tighten quality benchmarks for drug-device interface submissions. Boston and Minneapolis medical device clusters concentrate electromechanical micro-pump development for neurological therapeutic delivery.
Germany
Specialized medical silicone suppliers and precision pump diaphragm manufacturers serve global device OEMs from industrial bases in Baden-Württemberg. REACH chemical registration obligations tighten disclosure requirements for propellant chemistries in metered-dose formats. Stuttgart-area engineering firms retool legacy mechanical platforms toward piezoelectric actuation systems.
Japan
PMDA quality management standards govern manufacturing consistency for suppliers seeking market access across East Asian hospital networks. METI industrial policy supports domestic production of medical-grade polymers for single-use atomizer assemblies. Osaka-Kobe manufacturing corridor concentrates sterilization validation capabilities for public health stockpiling programs.
United Kingdom
NHS procurement frameworks prioritize validated sterility assurance in emergency medicine departments transitioning to opioid-sparing pain protocols. MHRA convergence with MDR elevates clinical evidence requirements for drug-device combinations. Cambridge and Oxford medical research clusters pilot intranasal delivery platforms for blood-brain barrier penetration.
India
CDSCO regulatory pathways for combination products attract contract manufacturing investment from multinational device developers seeking cost-optimized production. PLI scheme incentives support domestic fabrication of disposable polymer atomizer components. Hyderabad and Ahmedabad pharmaceutical clusters integrate nasal delivery training into expanding clinical service offerings.
Nasal Atomizer Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement tiers differentiated by validation depth and service intensity. Hospital group purchasing organizations consolidate vendor lists around FDA master file holders, compressing fragmented purchasing into concentrated contracts. Three archetypes dominate: diversified critical care conglomerates, disposable device scale manufacturers, and specialized neurological delivery developers. M&A activity targets combination product capabilities, while strategic partnerships secure silicone component supply from German and Japanese specialty chemical suppliers.
Within the diversified medical technology tier, Teleflex Incorporated and Becton Dickinson and Company exemplify channel-controlling players with hospital procurement scale. Kurve Therapeutics occupies a specialist position focused on neurological therapeutic delivery systems. These three entities represent distinct competitive vectors: acute-care channel dominance, disposable manufacturing scale, and precision indication targeting.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Becton Dickinson and Company |
| DeVilbiss Healthcare LLC |
| Cook Medical |
| Medspray |
| Intersurgical Ltd. |
| Medline Industries |
| Pulmodyne Inc. |
| Kurve Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's precision pump manufacturing cluster feeds electromechanical micro-pump assemblies to United States trauma centers, with capacity allocation decisions rippling through downstream contract pricing for acute-care procurement channels.
Pricing Analysis
Current-generation piezoelectric micro-pump systems command substantial premiums over legacy mechanical squeeze bottles and early electric alternatives, with three-tier pricing structure across premium, standard, and economy levels separating FDA-validated combination products from unregulated alternatives and commodity disposable lines. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling, with calibration protocols and field service networks adding recurring revenue layers. Pricing pressure stems from hospital group purchasing organization consolidation favoring vendors with device master files. Home care channels exhibit highest price sensitivity; military medical procurement shows lowest.
Supply Chain Analysis
Contract manufacturing concentrates among German precision pump specialists and Japanese medical silicone component suppliers serving global device OEMs from Stuttgart-area and Osaka-Kobe industrial bases. Geographic supply concentration centers on Germany, Japan, and United States for specialized pump diaphragms, piezoelectric actuators, and medical-grade polymer feedstocks. Raw material dependencies include specialized polypropylene and polycarbonate resins, medical-grade silicone for seals, and rare-earth elements for piezoelectric ceramics. Single-source vulnerability for precision silicone components creates structural risk. Distribution runs through group purchasing organization contracts and military procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics are reshaping competitive positioning as calibration, sterilization validation, and field maintenance contracts expand faster than hardware unit sales, with recurring revenue pools deepening for electromechanical platform vendors.
For Market Incumbents: Pre-empt emerging entrant challenges by deepening backward integration into medical-grade silicone supply through captive production or exclusive offtake agreements with Baden-Württemberg specialty chemical suppliers, and anchor hospital procurement scale through expanded FDA device master file portfolios covering combination product submissions. Vertical integration into precision pump diaphragm manufacturing is the priority lever against Japanese supplier concentration risk. For New Entrants and Emerging Players: Pre-hospital emergency services in United States fire departments and ambulance corps represent the most penetrable white-space target, with opioid-sparing pain protocols creating immediate clinical demand and lower validation barriers than hospital GPO contracts. Target neurological therapeutic delivery as the fastest-expanding application segment, and secure entry through strategic partnerships with academic medical centers piloting blood-brain barrier penetration platforms. For Investors and Strategic Acquirers: Long-term, this sits as a precision-indication consolidation play because electromechanical micro-pump capabilities for CNS drug delivery are fragmenting across specialist developers while hospital procurement consolidation favors scaled combination product dossiers. Target acquisition archetype: mid-cap device developers with validated neurological delivery platforms and FDA master file holdings. The signal to watch is BARDA and CDC intranasal vaccine stockpiling award velocity as pandemic preparedness program scaling indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Combination Product Submission | Device master file validation unlocks hospital GPO contract eligibility and procurement consolidation. |
| Backward Integration into Silicone Supply | Captive diaphragm production mitigates single-source dependency on German and Japanese specialty suppliers. |
| Pre-Hospital Emergency Services Partnership | Fire department and ambulance corps procurement channels remain underpenetrated relative to clinical adoption depth. |
| Neurological Delivery Platform Development | Blood-brain barrier penetration capabilities open CNS indication development for specialized device developers. |
| Reimbursement Strategy for Home Care | Medicare durable medical equipment codes shape viable product configurations in United States retail channels. |
Study Parameters
The analysis maps manual, electric, disposable, and reusable device categories, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and emergency medicine clinicians, combining primary interviews with secondary validation against FDA 510(k) filings, ISO 13485 certification databases, hospital procurement records, and military medical procurement disclosures, with bottom-up unit demand modeling and top-down market sizing triangulation.
Assumptions held fixed include FDA combination product guidance trajectory, EPA propellant chemistry regulations, and ISO 10993 biocompatibility testing timelines, while variables included intranasal vaccine platform adoption velocity, electromechanical micro-pump cost curves, and medical-grade polymer feedstock price volatility across the analysis window. Segmentation dimensions modeled encompass product type, end user, delivery mode, application, and regional regulatory cluster, with CAGRs derived from trend extrapolation and adoption curve analysis anchored to hospital procurement data and public health stockpiling program announcements.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or vertical integration moves by diversified critical care conglomerates would shift outcomes beyond modeled ranges. Cross-checking against CDC and BARDA procurement award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI Compatible IV Infusion Pumps Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Spinal Stenosis Implant Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Europe Breast Pumps Market
Medical Devices
Elbow Fixators Market
Medical Devices
Reusable Resuscitators Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Europe Wearable Medical Devices Market
Medical Devices
Surgical Mesh Market
Medical Devices
Flow Cytometry Products Market