
 Transseptal Access Systems Market | 2026-2036
Transseptal Access Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Transseptal Access Systems Market Outlook
A capital-intensity divergence between integrated manufacturers and component assemblers is reorganizing competitive tiers in transseptal access. Medtronic plc leverages captive needle production and in-house sterilization infrastructure to sustain margin capture across the catheter-to-sheath workflow. Boston Scientific Corporation anchors its position through dedicated electrophysiology channel control in tertiary cardiac centers. Merit Medical Systems competes on procedural kit bundling that reduces hospital inventory complexity.
Transseptal access systems comprise needles, sheaths, guides, and dilation balloons engineered for precise atrial septum puncture, typically constructed from stainless steel hypotubes, braided Pebax shafts, and radiopaque marker bands to enable fluoroscopic visualization during left atrial entry. These devices serve the primary purpose of establishing safe intracardiac passage for ablation catheters, mitral repair tools, and septostomy balloons. Needles and sheaths together occupy the dominant value share given their single-use consumption per procedure, while robotic-assisted systems represent the fastest-expanding technology dimension as hospitals integrate magnetic navigation with transseptal platforms. Imaging-assisted systems command premium positioning where intracardiac echocardiography guidance reduces complication rates.
FDA 510(k) clearance pathways and the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for transseptal needle and sheath manufacturers seeking market access. ISO 13485 quality management standards and biocompatibility testing under ISO 10993 further constrain material selection and sterilization validation for polymer-based sheaths. Stakeholders must monitor how FDA draft guidance on robotic surgical devices and EUDAMED registration deadlines will alter competitive entry costs and distribution compliance burdens.
Market Dynamics
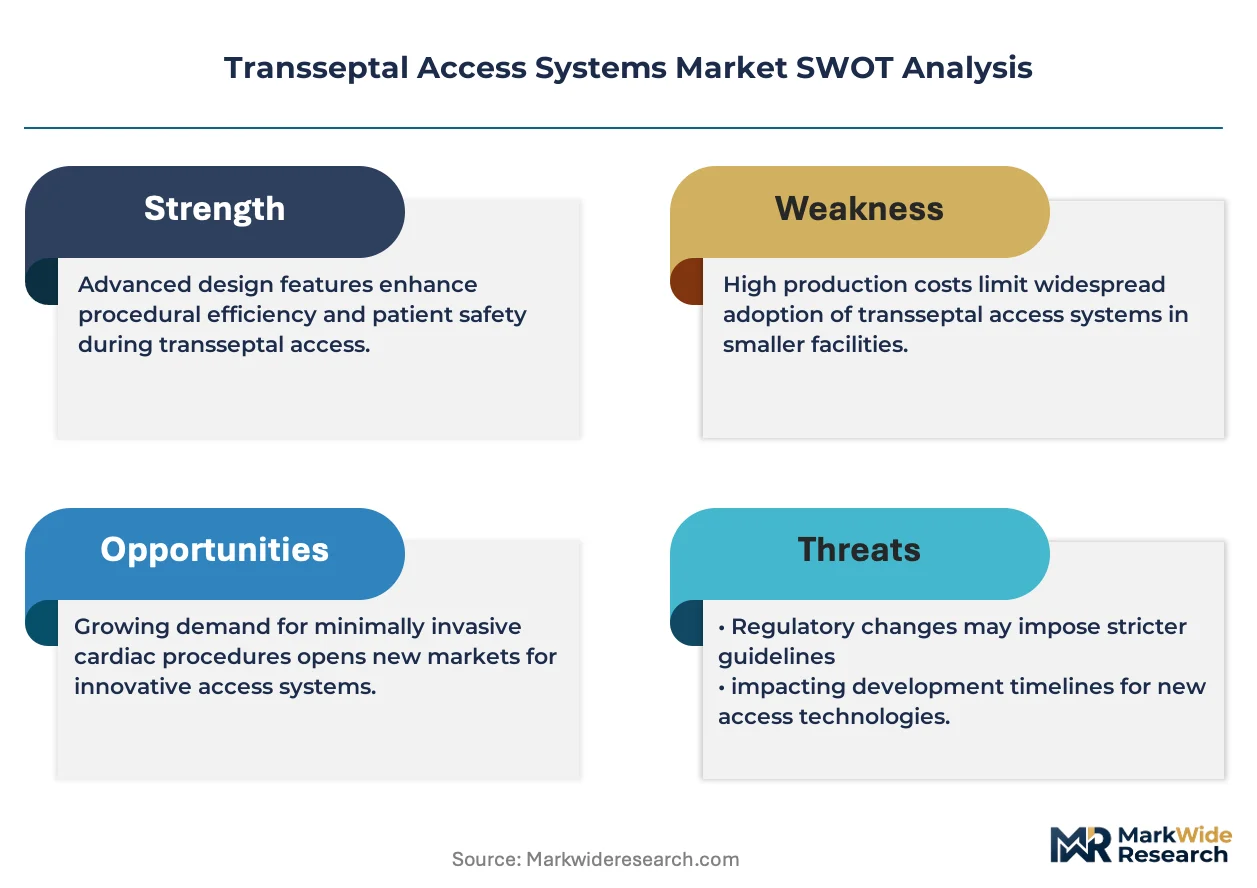
Magnetic navigation integration with transseptal platforms is compressing procedural times and redistributing value capture toward robotic-capable manufacturers, forcing capital-light competitors into component supply roles.
Growth Catalysts
- Catheter-based cardiac intervention expansion:Electrophysiology labs in tertiary hospitals are replacing surgical alternatives with transseptal approaches for atrial fibrillation ablation, consuming single-use needles and sheaths at rising volumes.
- FDA 510(k) pathway maturation:Streamlined clearance for predicate device modifications accelerates iterative sheath and needle improvements, reducing time-to-market for biocompatibility-validated products.
- Japan's aging cardiac patient pool:PMDA-registered electrophysiology infrastructure in Tokyo, Osaka, and Nagoya creates concentrated demand for precision transseptal tools among specialized cardiac centers.
Market Restraints
- Stainless steel hypotube supply concentration:Precision tubing for needle construction sources predominantly from German and Swiss specialty metal processors, exposing assemblers to input bottlenecks.
- EU MDR clinical evidence escalation:Extended validation timelines for polymer sheath biocompatibility under ISO 10993-5 and ISO 10993-10 delay product launches and freeze smaller competitors.
- Structural heart surgical alternatives:Transcatheter mitral valve repair via non-transseptal femoral approaches in select anatomies limits addressable procedure growth in specific patient cohorts.
Strategic Opportunities
- Intracardiac echocardiography convergence:Real-time imaging guidance integration with transseptal needle systems enables premium positioning and complication reduction in complex left atrial appendage closure procedures.
- India's electrophysiology infrastructure buildout:CDSCO-regulated catheter lab expansion in Delhi, Mumbai, and Hyderabad creates first-mover advantage for sheath-needle kit suppliers establishing local distribution.
- Outcome-based hospital procurement:Bundled payment models for atrial fibrillation ablation episodes incentivize integrated transseptal system purchases that reduce inventory complexity and procedural variability.
Industry Challenges
- Electrophysiologist training pipeline constraints:Specialized transseptal puncture competency requires extended fellowship exposure, limiting procedure volume scaling in markets with thin interventional cardiology labor pools.
- Robotic platform integration complexity:Magnetic navigation compatibility demands proprietary interface protocols, forcing sheath manufacturers into costly co-development arrangements with robotic system vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transseptal Access Systems Market |
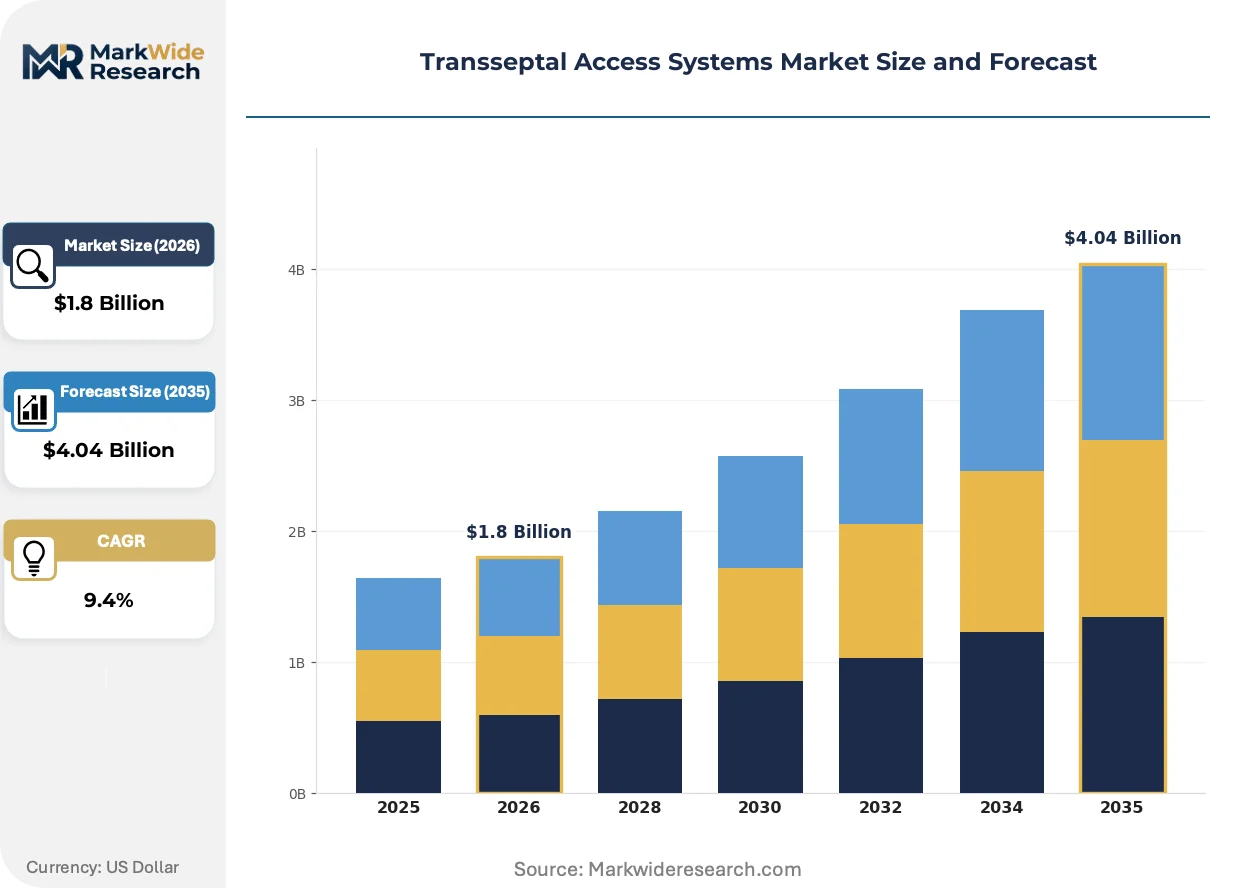
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needles, Sheaths, Guides, Dilation Balloons Procedure Type: Atrial Septostomy, Electrophysiology Procedures, Mitral Valve Repair, Cardiac Ablation End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Research Institutions Technology: Manual Systems, Robotic-Assisted Systems, Imaging-Assisted Systems, Disposable Systems |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Merit Medical Systems, Baylis Medical Company, Biosense Webster, Terumo Corporation, Cook Medical, Abbott Laboratories, Transseptal Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transseptal Access Systems Market Strategic Shifts
Transseptal access technology is converging around visualization enhancement and automation, with three distinct vectors reshaping product architecture and procurement patterns across cardiac intervention suites.
Steerable sheath technology is miniaturizing. Braided Pebax shafts with variable stiffness zones now enable precise atrial navigation through 8 French profiles, down from 12 French predecessors. Academic electrophysiology departments in the United States and Germany are adopting these platforms for complex pulmonary vein isolation cases, compressing fluoroscopy exposure and enabling same-day discharge protocols that alter hospital reimbursement economics.
REACH substance restrictions and EU MDR biocompatibility mandates are tightening polymer selection criteria for long-dwelling sheaths. Manufacturers must now validate phthalate-free Pebax alternatives and novel radiopaque fillers under extended cytotoxicity protocols. European notified bodies are prioritizing review resources toward MDR technical files with comprehensive chemical characterization, disadvantaging assemblers dependent on legacy material formulations.
Hospital procurement departments are consolidating transseptal spend into single-source agreements with procedural kit bundling. Tertiary cardiac centers in Japan and the United States are replacing discrete needle, sheath, and dilator purchases with integrated platform contracts that lock in volume commitments. This shift compresses supplier margins while rewarding manufacturers with captive sterilization infrastructure and regional distribution density.
Transseptal Access Systems Market Segmentation
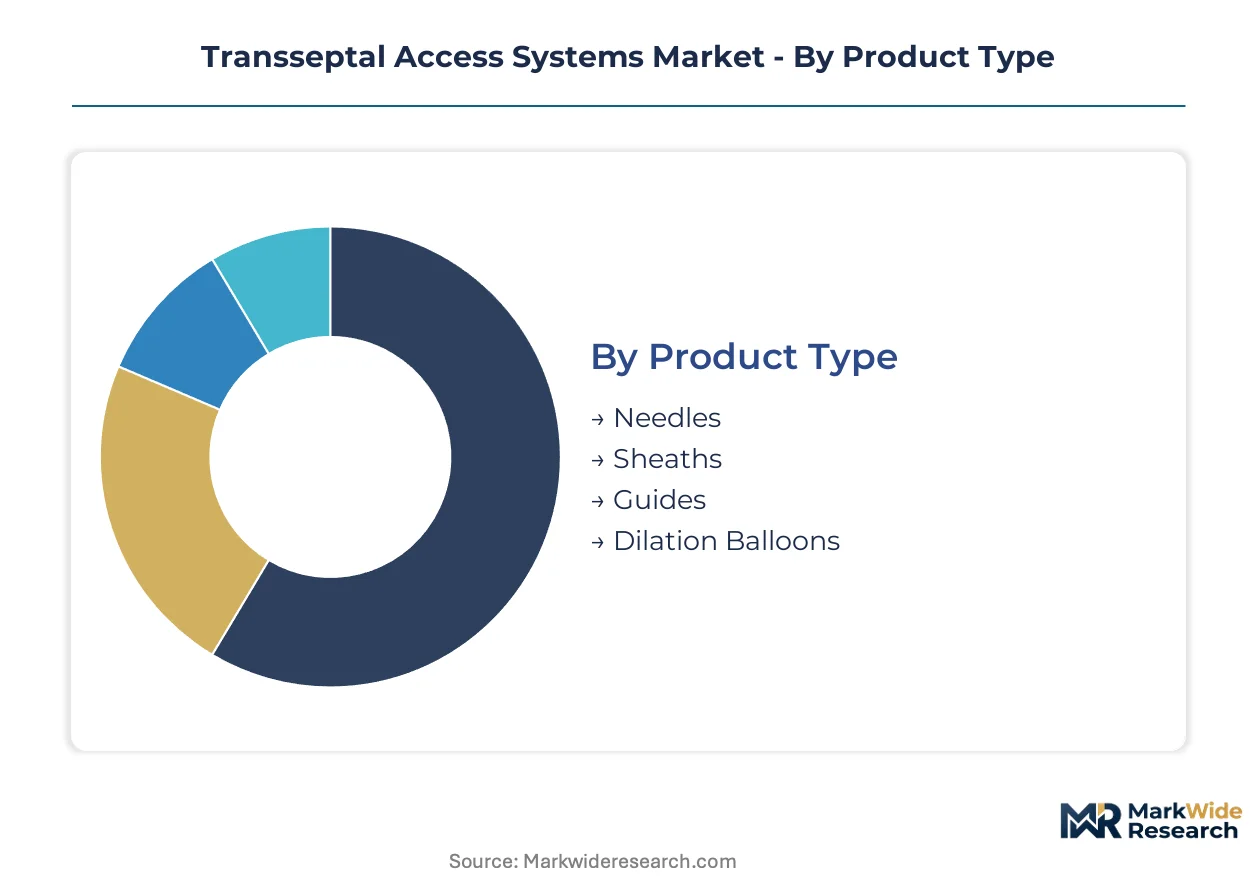
Transseptal access systems fragment across four critical dimensions that determine procurement patterns, margin profiles, and competitive entry barriers. Product architecture choices, procedural applications, site-of-care economics, and technology integration levels each create distinct value capture opportunities for manufacturers navigating FDA and EU MDR compliance pathways.
Product Type:
Needles and sheaths face intensifying substitution pressure from integrated procedural kits that bundle multiple components under single-source hospital contracts.
- Needles:Stainless steel hypotubes with echogenic tips and radiopaque markers enable fluoroscopic and ultrasound-guided septal puncture. Demand concentrates in electrophysiology labs at tertiary hospitals in the United States and Germany where catheter ablation volumes drive single-use consumption. FDA 510(k) pathway maturation accelerates iterative tip geometry improvements.
- Sheaths:Braided Pebax shafts with variable stiffness zones and hemostasis valves maintain access during catheter exchanges. REACH substance restrictions and EU MDR biocompatibility mandates are forcing phthalate-free polymer validation, extending development timelines for European market entry.
- Guides:Deflectable delivery platforms steer therapeutic devices through tortuous atrial anatomy.
- Dilation Balloons:High-pressure balloons dilate the interatrial septum to accommodate large-bore sheaths for structural heart interventions.
Sheaths anchor the volume base while robotic-compatible needle systems gain share at the steepest rate.
Procedure Type:
Cost tier divergence separates high-complexity structural interventions from high-volume electrophysiology workflows.
- Electrophysiology Procedures:Atrial fibrillation ablation consumes the majority of transseptal needle and sheath units through repeated left atrial access for pulmonary vein isolation. Japan's PMDA-registered cardiac centers in Tokyo and Osaka generate concentrated demand for precision puncture tools.
- Mitral Valve Repair:Transcatheter edge-to-edge repair via transseptal delivery commands premium sheath specifications for large-bore device accommodation.
- Cardiac Ablation:Ventricular tachycardia and atypical flutter ablations utilize transseptal access for left-sided substrate mapping.
- Atrial Septostomy:Balloon septostomy for pulmonary hypertension creates specialized demand for cutting balloons and graded dilators.
Electrophysiology procedures anchor the volume base while mitral valve repair applications climb the fastest as transcatheter structural heart adoption accelerates.
End User:
Customer type stratification reflects capital intensity requirements and sterilization infrastructure availability.
- Hospitals:Tertiary cardiac centers with dedicated electrophysiology labs achieve scale economies through high procedure throughput and integrated kit procurement. CDSCO-regulated catheter lab expansion in Delhi, Mumbai, and Hyderabad creates first-mover opportunities for suppliers establishing local distribution.
- Cardiology Clinics:Specialized outpatient facilities focus on diagnostic electrophysiology studies with lower transseptal penetration.
- Ambulatory Surgical Centers:Same-day discharge protocols for simple ablations drive demand for miniaturized 8 French sheath profiles.
- Research Institutions:Academic medical centers validate next-generation robotic and imaging-assisted platforms.
Hospitals anchor the volume base while ambulatory surgical centers expand most quickly as reimbursement shifts toward site-neutral payment models.
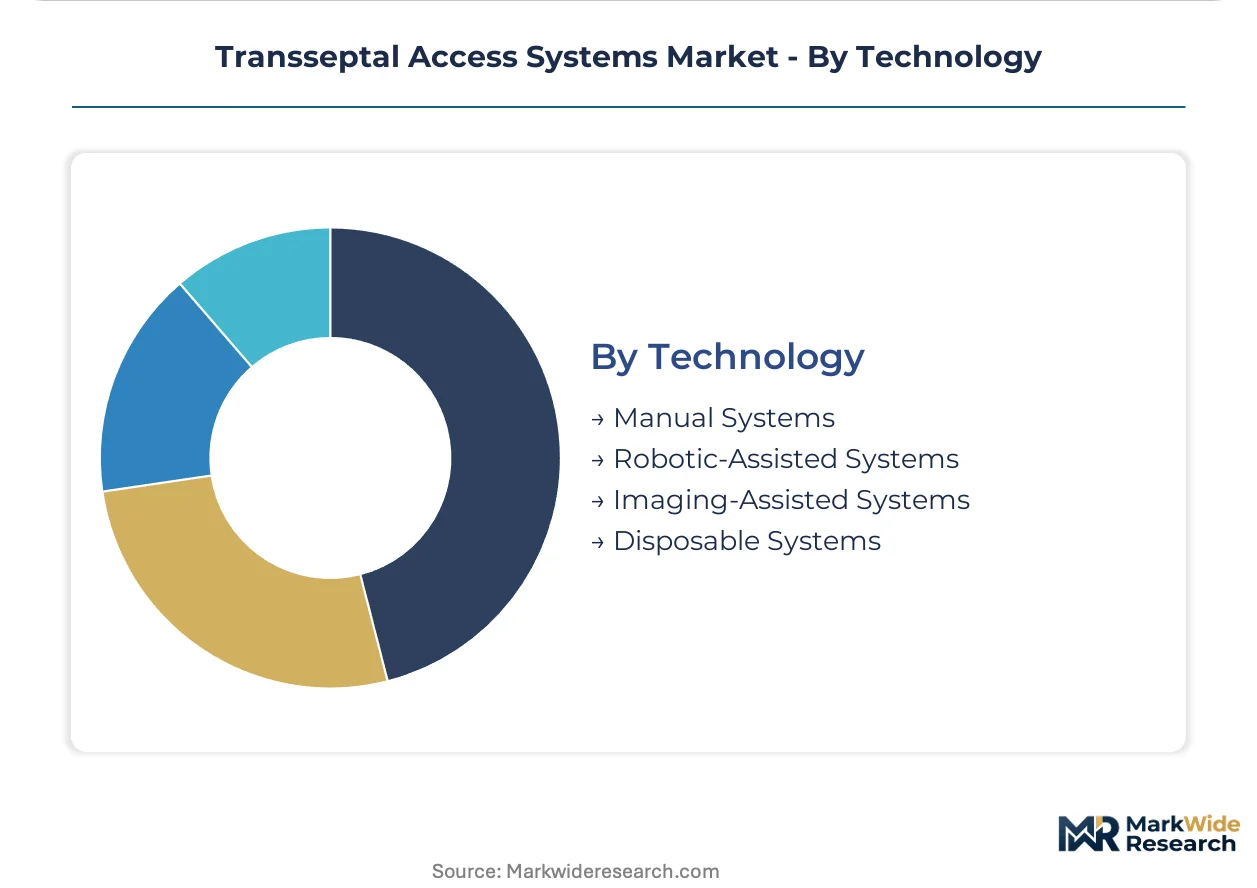
Technology:
Supply concentration in magnetic navigation interfaces creates partnership barriers for standalone sheath manufacturers.
- Robotic-Assisted Systems:Magnetic navigation integration with proprietary sheath interfaces compresses procedural times and redistributes value capture toward system vendors. Co-development arrangements with robotic platform manufacturers impose costly interface protocol compliance.
- Imaging-Assisted Systems:Intracardiac echocardiography convergence enables real-time needle visualization and complication reduction in complex left atrial appendage closure.
- Manual Systems:Conventional fluoroscopy-dependent platforms dominate installed base.
- Disposable Systems:Single-use sterilized kits reduce hospital reprocessing burden and inventory complexity.
Manual systems anchor the volume base while robotic-assisted platforms capture expanding share through magnetic navigation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Japanese cardiac centers absorb premium pricing for robotic-compatible systems, while Indian procurement departments drive hard bargains on standard sheath-needle kits. German hospitals occupy the middle ground, demanding performance validation without excessive cost escalation.
United States
Tertiary electrophysiology labs in Cleveland Clinic and Mayo Clinic networks generate concentrated demand for integrated transseptal platforms. FDA 510(k) pathway maturation accelerates iterative device improvements while maintaining safety thresholds. The Boston-to-Philadelphia corridor anchors specialized cardiac center density with high ablation procedure throughput.
Germany
REACH substance restrictions and EU MDR biocompatibility mandates force phthalate-free polymer validation for sheath manufacturers. German notified bodies prioritize technical files with comprehensive chemical characterization. The Rhine-Main cluster around Frankfurt concentrates electrophysiology infrastructure with university hospital scale.
Japan
PMDA-registered cardiac centers in Tokyo, Osaka, and Nagoya create concentrated demand for precision puncture tools among aging patient populations. METI industrial policy supports domestic medical device manufacturing capacity. The Kanto region around Tokyo maintains the highest per-capita electrophysiologist density in Asia-Pacific.
India
CDSCO-regulated catheter lab expansion in Delhi, Mumbai, and Hyderabad creates first-mover advantage for kit suppliers establishing local distribution. Central government PLI scheme incentives for medical device manufacturing reduce import dependency. The National Capital Region anchors private hospital chain investment in electrophysiology infrastructure.
Switzerland
Swissmedic regulatory alignment with EU MDR streamlines market access for precision needle manufacturers. Swiss specialty metal processors dominate stainless steel hypotube supply for transseptal needle construction. The Basel-Zurich corridor concentrates contract manufacturing capabilities serving global device assemblers.
Transseptal Access Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated multinationals with captive sterilization infrastructure capture margin across the catheter-to-sheath workflow, while component assemblers compete on kit bundling and inventory simplification. The market stratifies into three archetypes: full-platform vendors, procedural kit specialists, and niche component suppliers. Dominant competitive moves include strategic partnerships for magnetic navigation compatibility and backward integration into polymer compounding to secure REACH-compliant material supply.
Among integrated platform manufacturers, Medtronic plc and Boston Scientific Corporation exemplify the full-system archetype with comprehensive electrophysiology portfolios. Merit Medical Systems occupies a distinct position as a kit bundling specialist targeting hospital procurement consolidation. These three companies anchor the competitive landscape through divergent approaches to value capture—captive manufacturing, channel control, and inventory complexity reduction respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Merit Medical Systems |
| Baylis Medical Company |
| Biosense Webster |
| Terumo Corporation |
| Cook Medical |
| Abbott Laboratories |
| Transseptal Solutions |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at specialized electrophysiology labs in the United States and Germany shapes both supply concentration and price floors for transseptal access systems. High-throughput tertiary centers command volume discounts on integrated procedural kits while smaller facilities absorb premium markups on discrete needle and sheath purchases, creating a bifurcated pricing landscape.
Pricing Analysis
After-sales revenue from sterilization services and extended kit replenishment contracts drives lifetime value for manufacturers with captive infrastructure. Three-tier pricing structure across premium robotic-compatible, standard imaging-assisted, and economy manual systems reflects FDA 510(k) clearance tier and magnetic navigation certification. Cost compression in economy manual tiers is intensifying because Indian procurement departments leverage CDSCO-regulated local manufacturing against import premiums. Ambulatory surgical centers exhibit highest price sensitivity due to site-neutral reimbursement constraints, while Japanese tertiary cardiac centers absorb premium positioning for PMDA-registered precision tools.
Supply Chain Analysis
Just-in-time inventory preferences dominate electrophysiology labs with high procedure throughput, while strategic stockpiling concentrates among distributors serving fragmented cardiology clinics. German and Swiss specialty metal processors anchor stainless steel hypotube supply for needle construction. Braided Pebax shafts and radiopaque marker bands draw from polymer compounders in the United States and Japan. Single-source vulnerability in precision tubing exposes assemblers to input bottlenecks when REACH substance restrictions trigger material reformulation. Distribution runs through dedicated cardiac device distributors with sterile logistics capabilities, hospital GPO contracts, and direct-to-lab platform agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transseptal access systems represent an early-cycle expansion story as catheter-based cardiac intervention displaces surgical alternatives in atrial fibrillation treatment. Magnetic navigation integration with proprietary sheath interfaces accelerates adoption curves beyond traditional fluoroscopy-dependent platforms.
For Market Incumbents: Fortify margin capture through backward integration into polymer compounding to secure REACH-compliant Pebax alternatives ahead of EU MDR biocompatibility deadlines. Expand sterilization infrastructure in the Kanto region to serve PMDA-registered Tokyo cardiac centers without import logistics burden. Magnetic navigation co-development demands from robotic platform vendors threaten standalone sheath manufacturers with interface protocol lockout.
For New Entrants and Emerging Players: Post-procedure kit replenishment services represent a service-layer gap where incumbents under-serve mid-tier hospitals with fragmented procurement. Target CDSCO-regulated catheter lab expansion in Delhi and Hyderabad with localized sheath-needle bundling that reduces inventory complexity for first-time electrophysiology infrastructure. Partner with Indian distributors holding PLI scheme incentives to bypass import premium disadvantages.
For Investors and Strategic Acquirers: Niche component suppliers with FDA 510(k) validated needle geometries and established relationships with German specialty metal processors present acquisition target archetypes with defensible input sourcing. Long-term viability hinges on magnetic navigation compatibility certification trajectories across the analysis window. Watch for FDA draft guidance finalization on robotic surgical devices as inflection indicator for interface protocol standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Navigation Partnership | Proprietary sheath interface protocols with robotic platform vendors compress procedural times and lock in premium positioning. |
| EU MDR Technical File Investment | Comprehensive ISO 10993 chemical characterization accelerates notified body review timelines for phthalate-free polymer validation. |
| CDSCO Local Distribution Buildout | Delhi and Mumbai catheter lab expansion creates first-mover advantage against import-dependent competitors. |
| Integrated Procedural Kit Bundling | Single-source hospital contracts reduce inventory complexity and capture volume commitments from procurement consolidation. |
| Intracardiac Echocardiography Convergence | Real-time needle visualization integration enables premium positioning in complex left atrial appendage closure procedures. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, EU MDR technical file registries, and PMDA approval records. Electrophysiologists at tertiary cardiac centers in Cleveland Clinic and Mayo Clinic networks, hospital purchasing committee directors, biomedical engineers specializing in catheter lab infrastructure, and GPO contracts managers provided stakeholder input. Bottom-up procedure volume estimates from hospital procurement databases triangulate against top-down manufacturer shipment data.
Segmentation dimensions modeled include product architecture (needles, sheaths, guides, dilation balloons), procedure type (electrophysiology, mitral valve repair, cardiac ablation, atrial septostomy), site-of-care economics (hospitals, cardiology clinics, ambulatory surgical centers, research institutions), and technology integration level (robotic-assisted, imaging-assisted, manual, disposable). CAGRs derive from regression analysis of historical adoption curves and penetration rate assumptions across the projection horizon. Magnetic navigation installation base expansion and REACH substance restriction implementation timelines serve as industry-specific forecast inputs.
Underlying assumptions cover electrophysiologist training pipeline throughput, EU MDR notified body review resource allocation, and PMDA registration pathway efficiency, with deviation risk concentrated in regulatory timeline slippage and robotic platform vendor partnership exclusivity. Revision becomes warranted when magnetic navigation compatibility certification thresholds cross hospital procurement mandate levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
APAC AMH Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Medical Tricorder Market
Medical Devices
Struts Implants Market
Medical Devices
Lactation Massager Market
Medical Devices
Non-Rebreathing Oxygen Mask Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
New Zealand Diabetes Devices Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Blood Thawing System Market