
 Left Atrial Appendage Devices Market | 2026-2036
Left Atrial Appendage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Left Atrial Appendage Devices Market Foresight
Modular procedure kits bundling closure devices with delivery systems and access accessories is repositioning how hospital purchasing committees evaluate total procedure economics. Boston Scientific Corporation leverages its integrated electrophysiology platform to anchor bundled contracts across integrated delivery networks. Abbott Laboratories sustains competitive positioning through specialized structural heart sales teams that navigate complex catheter lab procurement processes. AtriCure Inc. differentiates via open surgical closure systems that occupy a distinct niche alongside percutaneous alternatives.
Left atrial appendage devices are implantable or deployed medical instruments designed to exclude the LAA from systemic circulation, typically constructed from nitinol mesh frames with polymer membranes and delivered through transseptal catheter access or surgical application. These devices functionally eliminate a primary source of thrombus formation in non-valvular atrial fibrillation patients who face contraindications to long-term oral anticoagulation therapy. Closure devices and occluders lead procedural volume due to established clinical evidence and broad labeling, while bioabsorbable materials represent the fastest-developing segment as manufacturers pursue elimination of permanent implants and reduced long-term complications. Hospital end users concentrate the largest margin pools through bundled device-procedure reimbursement structures that favor high-volume cardiovascular centers.
FDA premarket approval requirements and the EU Medical Device Regulation shape product development timelines and market access conditions, with FDA maintaining stringent clinical evidence standards for LAA closure indications while EMA's MDR transition demands enhanced post-market surveillance infrastructure. The Centers for Medicare & Medicaid Services national coverage determination framework directly influences United States hospital adoption velocity by establishing reimbursement thresholds for eligible patient populations. Stakeholders must monitor evolving anticoagulation therapy guidelines and comparative effectiveness data to assess whether device-based LAA closure expands beyond current contraindicated patient populations into broader atrial fibrillation management algorithms.
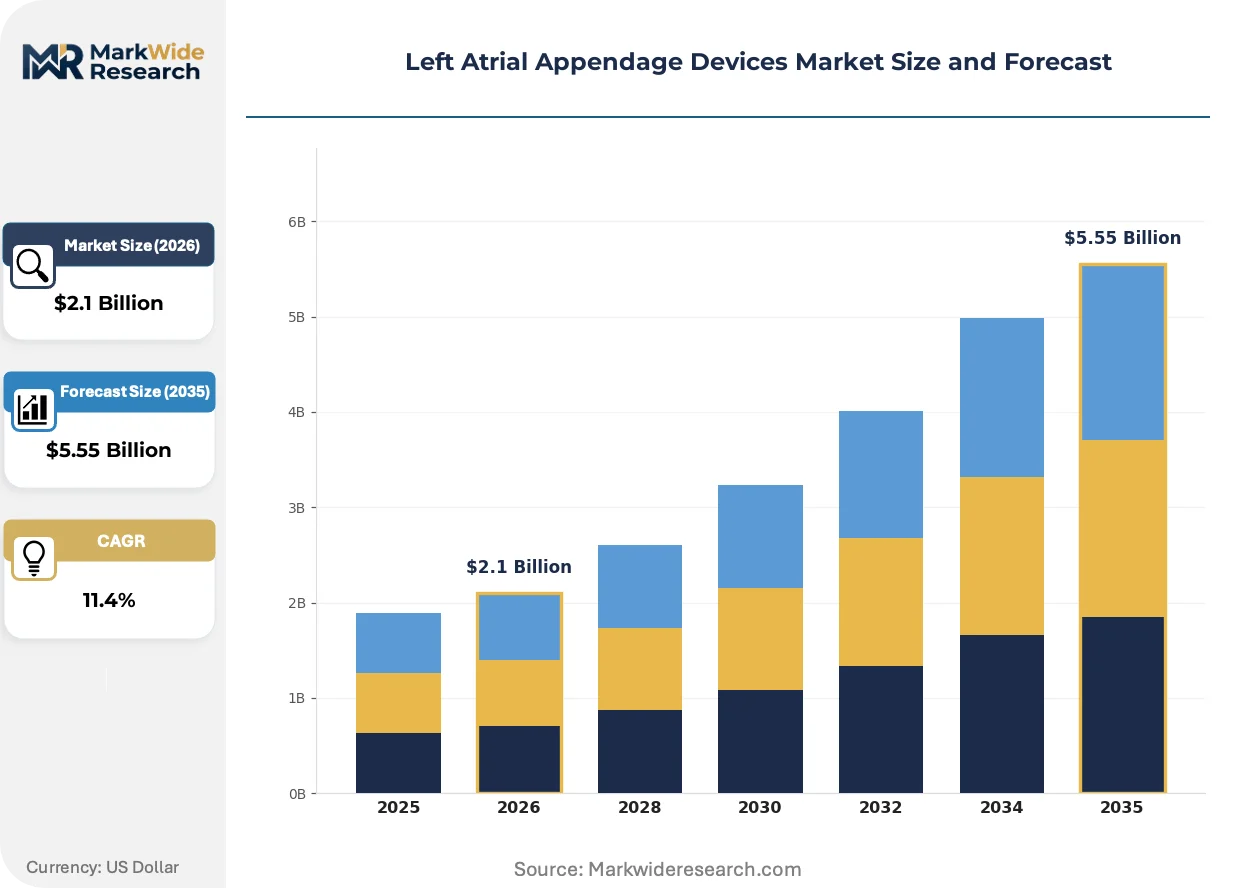
Market Dynamics
Hospital procurement committees are consolidating catheter lab purchasing around bundled procedure economics, compressing standalone device margins while rewarding integrated platform vendors with multi-year supply agreements across cardiovascular service lines.
Growth Catalysts
- CMS National Coverage Determination:The expanded reimbursement framework for percutaneous LAA closure in the United States removes prior authorization barriers and accelerates hospital program adoption.
- Nitinol mesh manufacturing advances:Precision laser-cutting and thermal shape-setting processes enable thinner strut profiles that improve deliverability through tortuous transseptal anatomy.
- Aging demographics in Germany:Elevated atrial fibrillation prevalence among patients over 75 years generates procedural volume concentration in tertiary cardiac centers.
Market Restraints
- Permanent implant complications:Device-related thrombus formation and pericardial effusion risks require lifelong antiplatelet therapy, limiting addressable populations with dual bleeding and clotting risks.
- Platinum-iridium electrode dependency:Concentrated sourcing of radiopaque marker materials from South African refineries exposes manufacturers to supply volatility and ESG scrutiny.
- EU MDR transition costs:Enhanced post-market surveillance infrastructure demands and notified body capacity constraints extend recertification timelines for legacy device families.
Strategic Opportunities
- Bioabsorbable polymer platforms:Elimination of permanent nitinol implants addresses long-term structural concerns and opens pediatric and younger adult populations currently excluded from closure indications.
- Japan's super-aging society:PMDA streamlined review pathways for breakthrough devices create first-mover advantages for manufacturers establishing local clinical evidence generation.
- Teleproctoring networks:Real-time procedural support from high-volume academic centers enables community hospital adoption without on-site specialist coverage.
Industry Challenges
- Transseptal puncture proficiency gaps:Safe left atrial access requires dedicated electrophysiology training programs that outpace current fellowship graduation rates.
- ICE catheter capital requirements:Intracardiac echocardiography systems represent substantial upfront investment for facilities initiating LAA closure programs without existing EP infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Left Atrial Appendage Devices Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Closure Devices, Occluders, Puncture Closure Devices, Retrieval Devices Material: Polymer, Metal, Composite, Bioabsorbable End User: Hospitals, Ambulatory Surgical Centers, Cardiology Clinics, Research Institutions Application: Atrial Fibrillation, Stroke Prevention, Heart Surgery, Device Implantation |
| Companies Covered | Boston Scientific Corporation, Abbott Laboratories, AtriCure Inc., Johnson & Johnson, Medtronic, Lifetech Scientific, Cardia Inc., Occlutech International AB, SentreHEART Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Left Atrial Appendage Devices Market Shifts & Advancements
Device architecture is converging with imaging and navigation platforms, creating integrated procedural ecosystems that redefine competitive differentiation beyond standalone implant performance metrics.
Next-generation closure systems are unifying real-time 3D echocardiographic guidance with robotic catheter steering, enabling single-operator procedures that previously required dual-physician teams. Community hospitals in the United States are adopting these platforms to compensate for interventional cardiologist staffing constraints. The technology is unifying imaging, navigation, and deployment into consolidated capital equipment purchases that favor vendors with broad cardiovascular portfolios.
The EU Medical Device Regulation's enhanced clinical evidence requirements are forcing manufacturers to maintain active implant registries with 10-year follow-up obligations. This policy compresses product lifecycle economics and elevates post-market infrastructure costs. High-volume European centers are responding by consolidating purchasing around vendors with demonstrated registry compliance capabilities.
Integrated delivery networks are unbundling device reimbursement from professional fees, creating direct contracting relationships with manufacturers that bypass traditional distributor markups. This purchasing pattern concentrates volume at cardiovascular centers achieving threshold procedure counts. The shift is most visible in United States health systems operating multiple catheter labs across metropolitan hospital networks.
Left Atrial Appendage Devices Market Segmentation
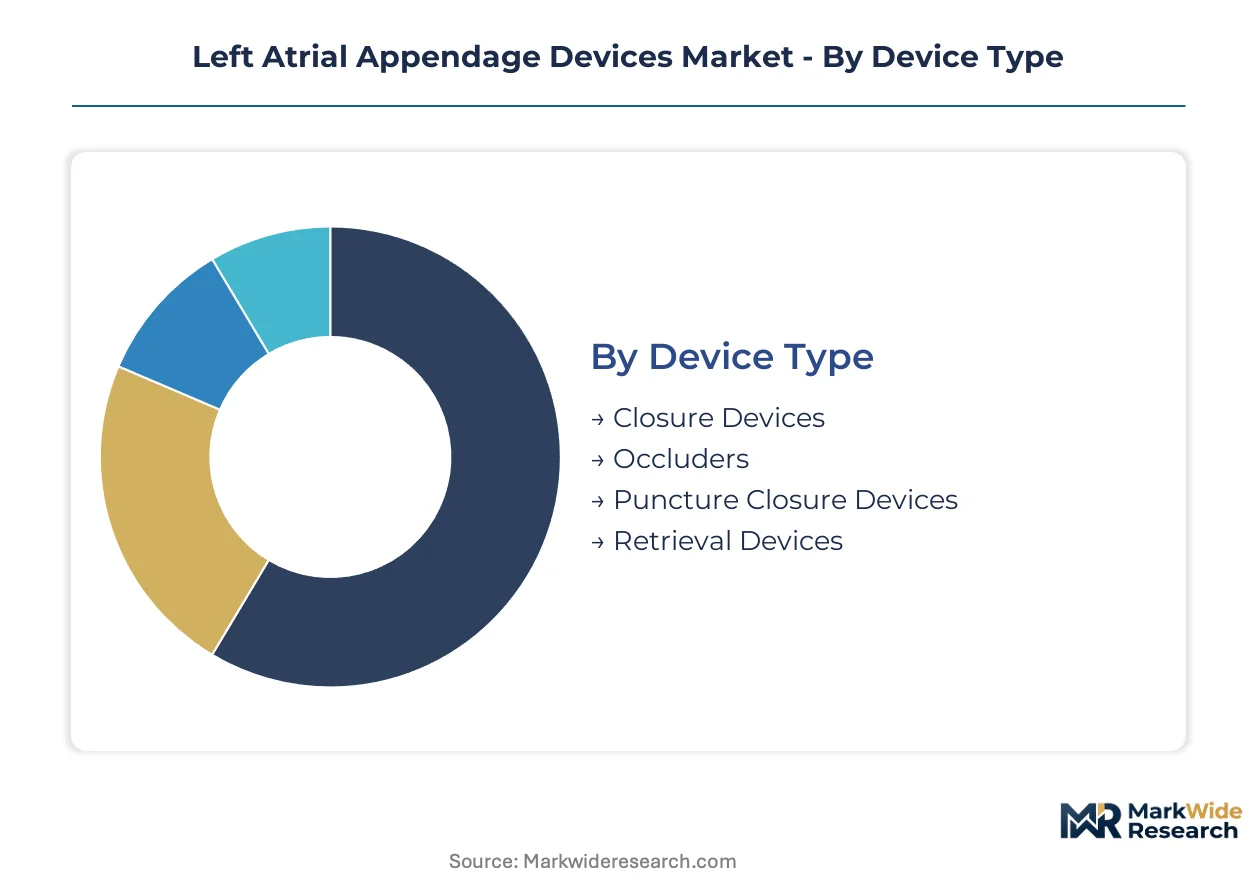
Segmentation in left atrial appendage devices reveals how clinical indication, implant material, and care setting interact to determine procurement patterns. Each dimension carries distinct margin profiles and regulatory pathways that shape manufacturer strategy.
Device Type:
Hospital purchasing committees evaluate these categories through distinct procedural economics and training requirements.
- Closure Devices:Nitinol mesh frames with polymer membranes deploy through transseptal catheter access to permanently exclude the LAA from circulation. Demand concentrates in United States tertiary cardiac centers where CMS reimbursement bundles favor high-volume programs with established electrophysiology infrastructure.
- Occluders:Self-expanding implants with dual-layer filtration membranes block thrombus egress while permitting endothelialization. German university hospitals drive procedural volume amid elevated atrial fibrillation prevalence in patients over 75 years and streamlined EMA MDR compliance pathways.
- Puncture Closure Devices:Transseptal access site management tools reduce procedural bleeding complications.
- Retrieval Devices:Snare-based systems enable percutaneous extraction of malpositioned or embolized implants.
Closure devices lead volumes today; occluders are gaining share fastest.
Material:
Material selection determines long-term biocompatibility profiles and opens or closes addressable patient populations.
- Polymer:Expanded polytetrafluoroethylene and polyethylene terephthalate fabrics form occlusive barriers with proven thrombogenic resistance. United States integrated delivery networks favor polymer-dominant implants for their extensive clinical registries and FDA PMA track records.
- Metal:Nitinol superelastic alloys enable catheter deliverability through tortuous anatomy. Manufacturers source precision-laser-cut mesh from specialized foundries with thermal shape-setting capabilities.
- Composite:Hybrid architectures combine metallic frames with polymeric occlusive elements.
- Bioabsorbable:Polylactic acid and polyglycolic acid scaffolds eliminate permanent foreign bodies. Japan's PMDA breakthrough device pathways accelerate clinical evidence generation for this category.
Metal and polymer platforms dominate current implantation; bioabsorbable materials show the steepest expansion trajectory.
End User:
Site-of-care economics and capital equipment requirements fragment demand across facility types.
- Hospitals:Tertiary cardiovascular centers with catheterization laboratories and electrophysiology suites capture the largest procedure volumes. Bundled reimbursement structures in United States health systems concentrate purchasing power at high-volume institutions.
- Ambulatory Surgical Centers:Outpatient facilities with cardiac catheterization capabilities serve selected low-risk patients. Regulatory frameworks in select United States states permit same-day discharge protocols.
- Cardiology Clinics:Office-based practices with diagnostic capabilities identify candidates for referral.
- Research Institutions:Academic medical centers generate pivotal clinical trial data and train procedural specialists.
Hospitals anchor current procedure volume; ambulatory surgical centers are expanding capacity most rapidly.
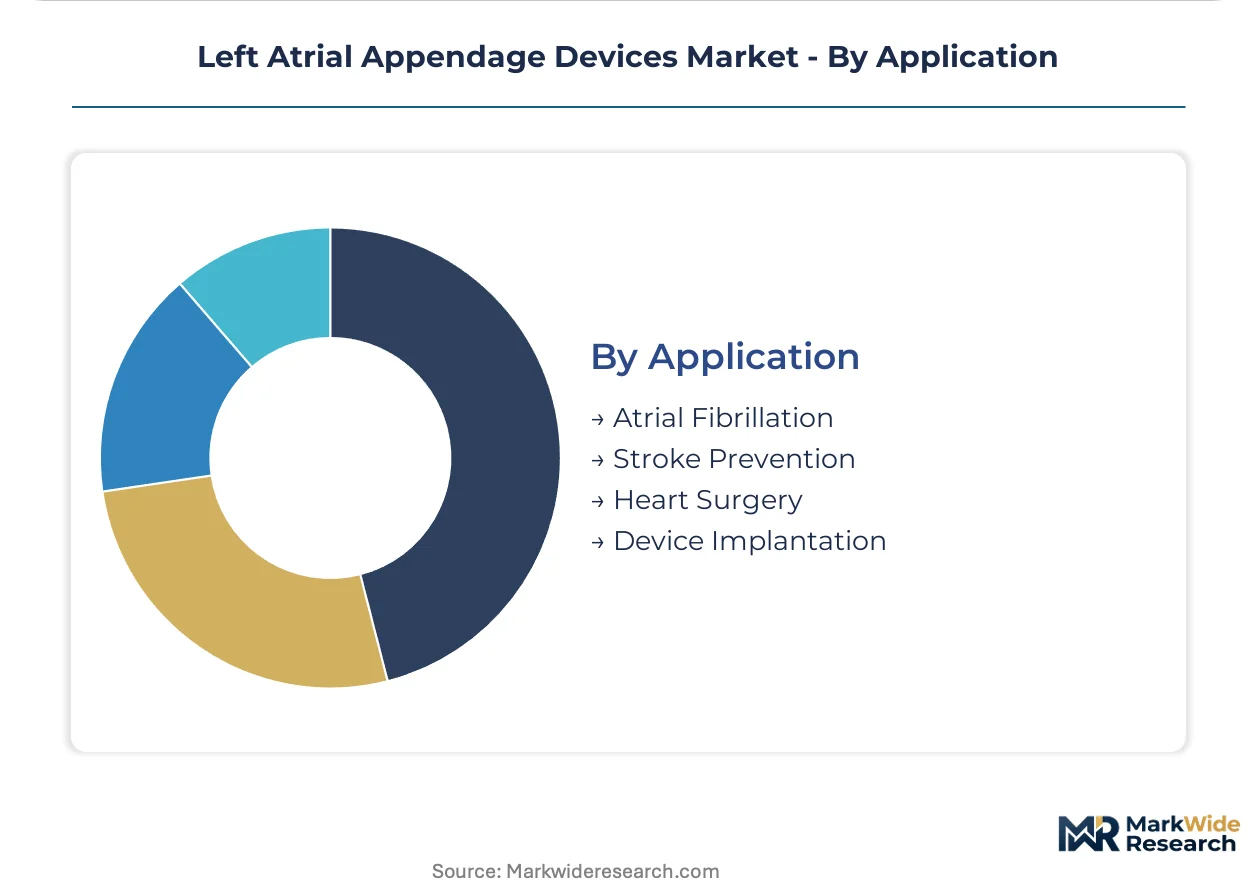
Application:
Clinical indication determines patient selection criteria and anticoagulation management protocols.
- Atrial Fibrillation:Non-valvular atrial fibrillation with contraindications to long-term oral anticoagulation represents the core labeled indication. United States electrophysiology service lines integrate LAA closure into comprehensive rhythm management protocols.
- Stroke Prevention:Ischemic stroke risk reduction drives payer coverage determinations. CMS national coverage frameworks establish reimbursement thresholds based on CHA2DS2-VASc scores.
- Heart Surgery:Concomitant surgical closure during cardiac procedures addresses patients undergoing valve repair or coronary bypass.
- Device Implantation:Prophylactic closure during left-sided lead placement or ablation procedures.
Atrial fibrillation indications command the largest eligible population; stroke prevention applications are deepening penetration fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The left atrial appendage devices industry traces its commercial origins to transcatheter closure systems pioneered in United States academic medical centers during the early 2000s. European regulators subsequently validated the technology through CE marking pathways. Asian markets adopted the procedure following Japan's PMDA breakthrough device designations.
United States
Tertiary cardiac centers in Cleveland and Houston generate the highest procedural volumes for catheter-based LAA closure. CMS national coverage determinations established reimbursement frameworks that removed prior authorization barriers for eligible patients. Integrated delivery networks in Texas and Ohio now bundle LAA occlusion into comprehensive atrial fibrillation management protocols.
Germany
University hospitals in Munich and Heidelberg drive European procedural concentration amid elevated atrial fibrillation prevalence among patients exceeding 75 years. EMA's MDR transition demands enhanced post-market surveillance infrastructure that favors manufacturers with established registry compliance. The Bavarian cardiac cluster anchors continental clinical evidence generation for next-generation device architectures.
Japan
PMDA streamlined review pathways for breakthrough devices accelerate market access for novel closure technologies in Tokyo and Osaka metropolitan areas. The country's super-aging society generates expanding eligible populations with contraindications to long-term oral anticoagulation. Kanto region medical centers lead Asia-Pacific adoption of integrated electrophysiology platforms combining imaging with robotic catheter steering.
United Kingdom
NHS specialized commissioning frameworks concentrate LAA closure procedures at designated cardiac centers in London and Manchester. NICE technology appraisals establish cost-effectiveness thresholds that shape hospital procurement committee evaluations. The Thames Valley cardiovascular network coordinates regional training programs addressing transseptal puncture proficiency gaps.
China
NMPA regulatory harmonization with international standards accelerates domestic device approvals for Shanghai and Beijing hospital systems. Local manufacturers leverage precision nitinol mesh manufacturing capabilities in Jiangsu province. The Yangtze River Delta cardiac intervention cluster drives volume expansion through provincial medical insurance reimbursement expansion.
Left Atrial Appendage Devices Market Competitive Landscape
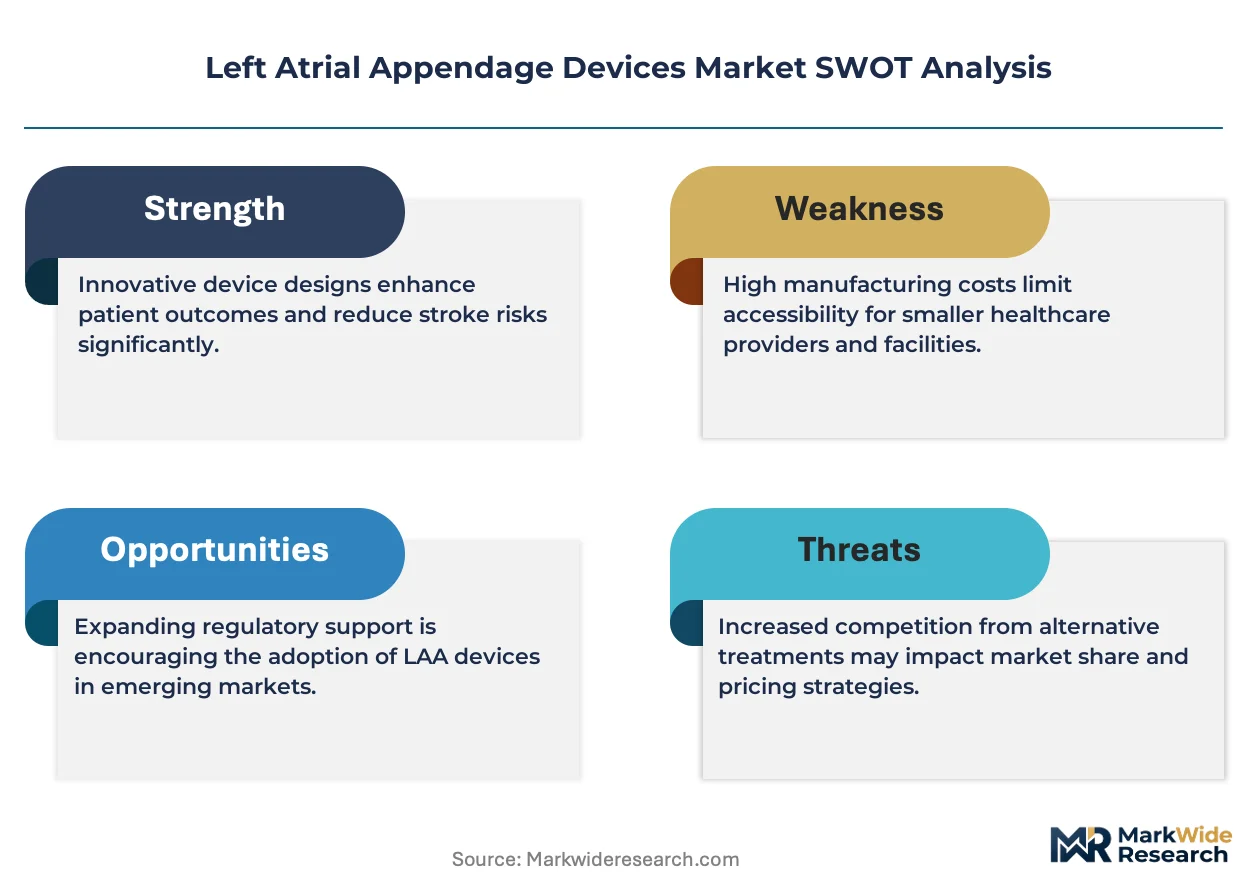
The competitive structure tilts toward integrated cardiovascular platform vendors with established electrophysiology infrastructure. Hospital procurement committees favor multi-year supply agreements covering closure devices, delivery systems, and imaging accessories. Three archetypes dominate: diversified medical technology conglomerates with structural heart divisions, specialized electrophysiology-focused enterprises, and emerging regional manufacturers with cost-optimized production. Dominant competitive moves include bundled contracting across integrated delivery networks and backward integration into nitinol mesh manufacturing.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Abbott Laboratories exemplify platform-centric positioning that spans closure devices through integrated procedural ecosystems. AtriCure Inc. occupies a distinct surgical closure niche alongside percutaneous alternatives, representing specialized structural heart focus that navigates complex catheter lab procurement processes differently than catheter-based competitors.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Abbott Laboratories |
| AtriCure Inc. |
| Johnson & Johnson |
| Medtronic |
| Lifetech Scientific |
| Cardia Inc. |
| Occlutech International AB |
| SentreHEART Inc. |
| Others |
Supply & Pricing Matrix
Precision nitinol laser-cutting specialists concentrated in Jiangsu province and Bavaria command wage premiums that widen pricing spreads between premium-tier FDA PMA-approved devices and economy-grade regional alternatives. Labor-cost differentials in mesh manufacturing translate directly into procurement-tier stratification as hospital systems evaluate total procedure economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates hospital procurement negotiations, with FDA PMA track records and CE MDR compliance status driving tier placement. Price differentiation hinges on clinical registry depth and after-sales procedural support bundling. Cost compression in the standard tier is intensifying because integrated delivery networks consolidate purchasing volume around platform vendors. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with established electrophysiology infrastructure demonstrate lowest.
Supply Chain Analysis
Device retrieval and refurbishment flows remain underdeveloped, though retrieval systems for malpositioned implants create nascent reverse-logistics channels. Nitinol mesh supply concentrates in China, Germany, and the United States, with precision laser-cutting capabilities anchoring regional manufacturing clusters. Platinum-iridium radiopaque marker sourcing draws from South African refineries, creating single-source vulnerability for radiopacity compliance. Distribution runs through specialized cardiovascular distributors with catheter lab relationships, bypassing general medical device wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The left atrial appendage devices market functions as a stable compounder, with aging demographics in developed economies generating procedural volume growth that outpaces economic cyclicality.
For Market Incumbents: To counter bioabsorbable polymer platforms from specialized entrants, anchor hospital relationships through multi-year bundled contracts spanning closure devices, delivery systems, and ICE catheter placements. Deepen backward integration into nitinol mesh manufacturing to capture margin pools currently held by specialized foundries.
For New Entrants and Emerging Players: PMDA breakthrough device pathways in Japan open a window for bioabsorbable scaffold developers to establish clinical evidence ahead of FDA PMA requirements. Target Japan's super-aging society and younger adult populations currently excluded from permanent implant indications. Pursue teleproctoring partnerships with high-volume academic centers to overcome community hospital staffing constraints.
For Investors and Strategic Acquirers: Diversified cardiovascular platform vendors are the most active acquirer in this space, seeking electrophysiology infrastructure to complete integrated service line offerings. Five-to-ten-year viability rests on registry compliance capabilities and reimbursement strategy execution. Monitor CMS national coverage determination expansions for early signals of addressable population broadening.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Bundled contracts with integrated delivery networks lock in multi-year procedural volume across cardiovascular service lines. |
| FDA Submission | PMA pathway completion validates clinical evidence packages for CMS reimbursement eligibility. |
| CE Marking Pathway | MDR compliance demonstrates post-market surveillance infrastructure for European hospital procurement committees. |
| Backward Integration | In-house nitinol mesh manufacturing captures margin pools from specialized foundries and reduces supply volatility. |
| Reimbursement Strategy | CMS national coverage determination alignment accelerates hospital program adoption velocity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA PMA filings, CMS Medicare reimbursement data, EMA MDR registration databases, and hospital procurement records. Bottom-up procedure volume estimates and top-down market sizing triangulated across the analysis window.
Historical reference periods anchored the projection horizon, with growth trajectories derived from demographic prevalence modeling and reimbursement expansion scenarios. Segmentation dimensions included device type, implant material, end-user facility category, and clinical indication. CAGRs incorporated electrophysiology infrastructure deployment rates and anticoagulation guideline evolution patterns.
Revisions become necessary when regulatory pathway delays, anticoagulation therapy paradigm shifts, or permanent implant complication signal changes materialize. Forecasts reflect documented assumptions about reimbursement stability and training pipeline capacity. Practitioners should monitor CMS coverage determination updates and EU MDR notified body capacity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Diabetes Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Ultrasound Transducers Market
Medical Devices
Support Surfaces Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Asia Pacific Apheresis Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Neurotechnology Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Ultrasonic Diathermy Market
Medical Devices
Low Vision Aids Market
Medical Devices
Multi Dose Drug Vial Adapters Market