
 Treatment Pumps Market | 2026-2036
Treatment Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Treatment Pumps Market Analytics
Home care providers is collapsing the historical hospital-centric procurement model for treatment pumps. Grundfos anchors its position through vertical integration across motor and control system production. Xylem differentiates via technology leadership in electronic pump platforms for precision medication delivery. Wilo SE sustains geographic dominance across European home care channels through specialized distribution partnerships.
Treatment pumps are electromechanical devices engineered to deliver fluids, medications, or nutrients at controlled flow rates, typically incorporating peristaltic tubing, piston-driven syringe mechanisms, or motor-driven piston systems with flow accuracy specifications reaching plus or minus two percent. These systems serve primary commercial purposes across clinical medication administration, chronic pain management, chemotherapy infusion, and enteral nutritional support. Infusion pumps occupy the largest installed base among product types while ambulatory pumps represent the fastest-growing category as patient mobility preferences intensify. Motor-driven technology leads current revenue pools though electronic platforms capture expanding margin concentration through software-enabled dose tracking and remote monitoring capabilities.
FDA medical device regulations, EU MDR conformity requirements, and ISO 13485 quality management standards collectively elevate barriers for new entrants while mandating post-market surveillance protocols that extend manufacturer liability windows. These frameworks shape demand by restricting market access to certified suppliers and accelerating replacement cycles as legacy devices fail updated safety benchmarks. Stakeholders must monitor evolving cybersecurity guidance from regulators as connected pump architectures expand attack surfaces and trigger new compliance investment requirements.
Market Dynamics
Home care migration is compressing hospital procurement volumes while amplifying demand for portable, software-enabled pump systems with remote monitoring capabilities. This structural shift forces manufacturers to reconfigure distribution networks and service models around dispersed patient locations rather than centralized clinical facilities.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for predicate-device submissions reduce time-to-market for next-generation infusion platforms targeting chronic disease management.
- Peristaltic mechanism miniaturization:Advances in tubing materials and motor efficiency enable wearable pump formats that match hospital-grade flow accuracy specifications.
- Germany's hospital-at-home reimbursement expansion:Statutory health insurance coverage for domiciliary infusion therapy sustains procurement momentum across ambulatory pump categories.
Market Restraints
- Semiconductor component concentration:Dependency on Taiwanese and South Korean foundries for motor control chips creates supply vulnerability during geopolitical disruptions.
- EU MDR technical documentation burdens:Expanded clinical evidence requirements for Class IIa and IIb devices extend certification timelines and elevate compliance costs.
- Gravity-fed infusion sets:Low-cost mechanical alternatives retain share in emerging markets where electronic pump penetration faces price sensitivity barriers.
Strategic Opportunities
- Japan's super-aged demographic corridor:Prefectures with 30%+ population over 65 present concentrated demand for enteral and parenteral nutrition pumps with Japanese-language interfaces.
- Closed-loop insulin delivery convergence:Integration of continuous glucose monitors with smart pump algorithms creates new product category expansion in diabetes management.
- Direct-to-patient subscription channels:Bypassing durable medical equipment distributors through manufacturer-operated rental programs captures recurring revenue streams.
Industry Challenges
- Cybersecurity engineering talent scarcity:Shortage of firmware developers with FDA cybersecurity guidance familiarity delays connected pump platform launches.
- ISO 13485 quality management system audits:Third-party certification body backlogs extend readiness timelines for market entry.
- Legacy hospital IT integration complexity:HL7 FHIR interoperability requirements demand substantial middleware development for EMR connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treatment Pumps Market |
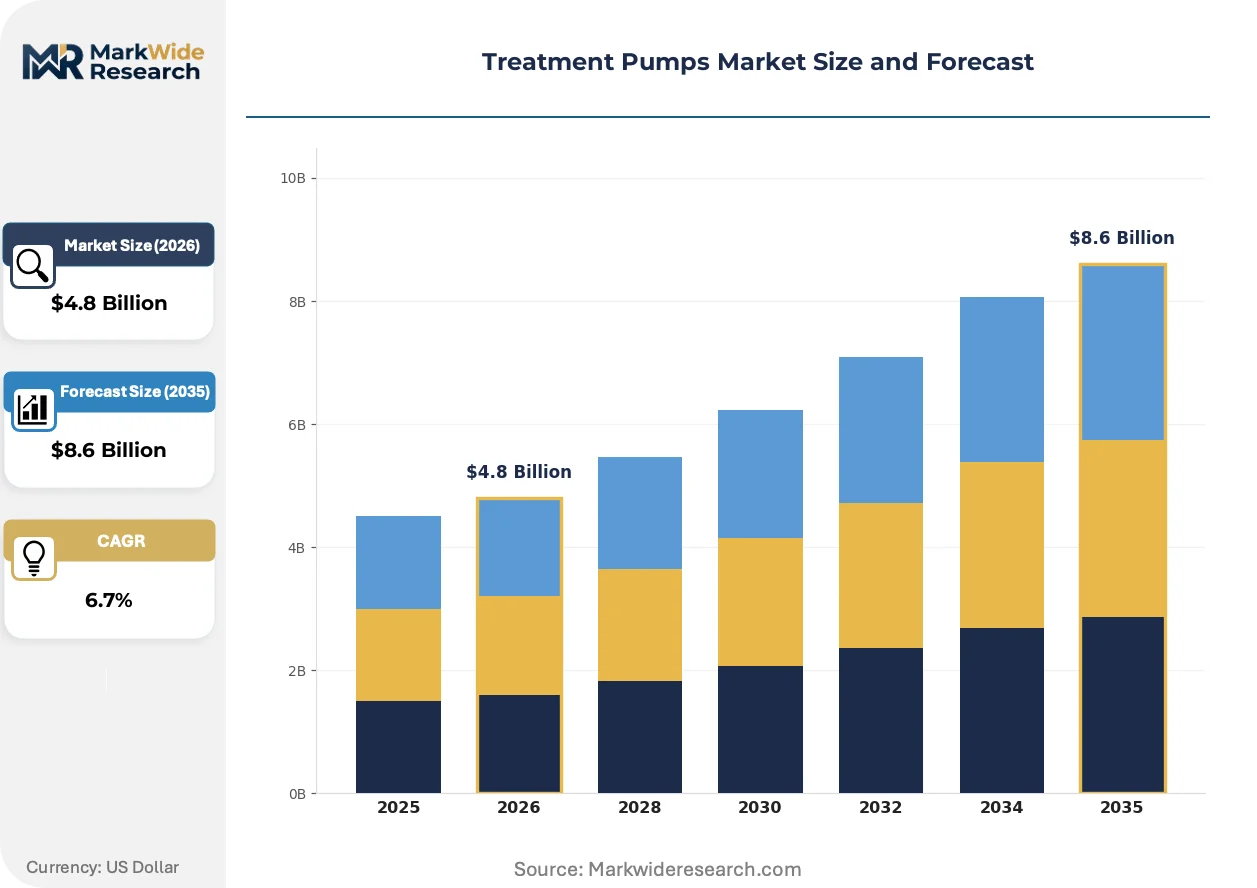
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infusion Pumps, Enteral Pumps, Insulin Pumps, Ambulatory Pumps Technology: Motor-driven, Peristaltic, Syringe-based, Electronic End User: Hospitals, Home Care, Clinics, Long-term Care Facilities Application: Medication Administration, Pain Management, Chemotherapy, Nutritional Support |
| Companies Covered | Grundfos, Xylem, Sulzer, Flowserve Corporation, KSB, Ebara Corporation, Wilo SE, Pentair, The Weir Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treatment Pumps Market Evolving Landscape
Software-defined pump architectures are displacing fixed-function hardware designs, enabling post-market feature updates and predictive maintenance algorithms. This transformation restructures competitive advantage around data platform capabilities rather than mechanical engineering alone.
Electronic peristaltic drive systems with brushless DC motors and real-time flow sensors are supplanting legacy stepper motor configurations in precision infusion applications. Oncology and pain management clinics in the United States are adopting these platforms at accelerated replacement cycles. The technology is compressing differentiation windows for competitors reliant on mechanical precision alone, forcing R&D investment toward embedded software and connectivity stacks.
EU MDR's Unique Device Identification mandate and enhanced post-market surveillance requirements are reshaping manufacturer liability structures. Economic operators must maintain technical documentation and vigilance systems for device lifespans extending 15-20 years. Ambulatory pump portfolios face the steepest compliance burdens, prompting portfolio rationalization among mid-tier manufacturers lacking regulatory affairs scale.
Hospital purchasing consortiums are consolidating procurement authority into centralized committees with standardized device specifications. Integrated delivery networks in the United States are displacing individual facility autonomy with enterprise-wide pump fleet standardization. This concentration is most visible in multi-state health systems negotiating sole-source agreements for smart infusion platforms with cybersecurity certification requirements.
Treatment Pumps Market Segmentation
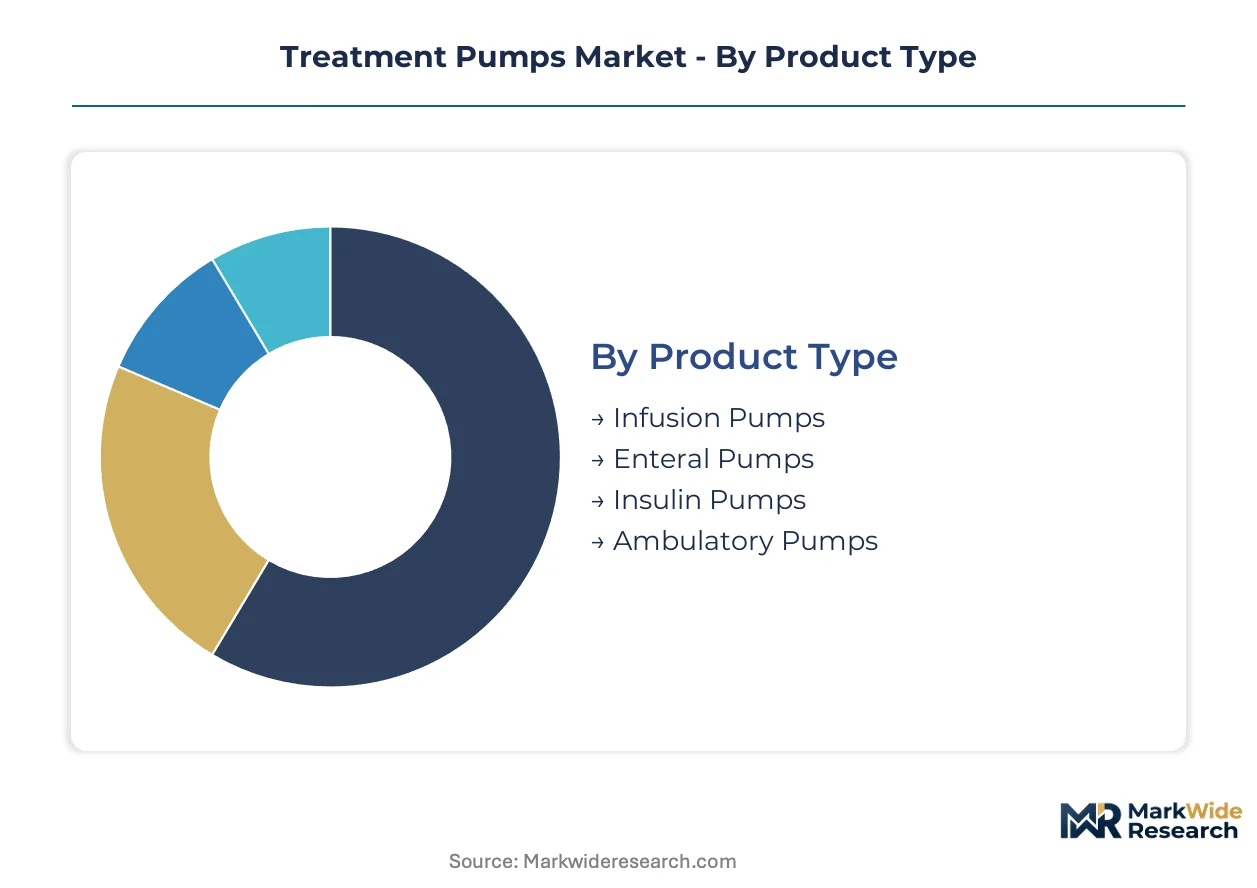
Segmentation in treatment pumps reveals how regulatory classification, clinical workflow, and patient mobility requirements partition procurement decisions across healthcare delivery settings. Each dimension carries distinct compliance burdens and margin structures that shape manufacturer portfolio strategy.
Product Type:
FDA Class II device regulations and EU MDR conformity pathways impose divergent technical documentation requirements across pump categories, with infusion systems facing the steepest clinical evidence thresholds.
- Infusion Pumps:These electromechanical systems deliver fluids, medications, or nutrients through intravenous, subcutaneous, or epidural routes with programmable flow rates and alarm functions. Hospital purchasing consortiums in the United States concentrate procurement volume for these systems as integrated delivery networks standardize fleet specifications across multi-state footprints. FDA 510(k) pathway streamlining accelerates clearance for predicate-device submissions targeting chronic disease management.
- Ambulatory Pumps:Wearable, battery-powered devices enable patient mobility during continuous infusion therapy outside clinical facilities. Germany's hospital-at-home reimbursement expansion sustains procurement momentum as statutory health insurance covers domiciliary infusion therapy. Peristaltic mechanism miniaturization advances enable wearable formats matching hospital-grade flow accuracy.
- Enteral Pumps:Specialized systems deliver liquid nutrition directly to the gastrointestinal tract via feeding tubes with bolus or continuous delivery modes. Long-term care facilities represent concentrated demand channels.
- Insulin Pumps:Programmable devices administer subcutaneous insulin with basal rate and bolus dosing capabilities for diabetes management. Closed-loop integration with continuous glucose monitors creates new product category expansion.
Infusion pumps handle the majority of throughput; ambulatory pumps are expanding most quickly on share.
Technology:
Cost tier stratification separates premium electronic platforms from standard motor-driven systems, with peristaltic mechanisms occupying mid-tier positioning based on precision requirements.
- Motor-driven:Stepper and brushless DC motor configurations power piston or syringe mechanisms with mechanical flow control. These systems dominate current revenue pools through established reliability in hospital settings.
- Electronic:Software-defined architectures with embedded sensors, connectivity stacks, and predictive algorithms capture expanding margin concentration. Electronic peristaltic drive systems with real-time flow sensors are supplanting legacy configurations in oncology and pain management clinics across the United States.
- Peristaltic:Tubing compression mechanisms using rotating rollers or fingers create fluid displacement without valve contact. Advances in tubing materials and motor efficiency enable wearable pump formats.
- Syringe-based:Piston-driven systems deliver precise medication volumes from disposable syringes in anesthesia and critical care applications. These systems retain share in operating room environments.
Motor-driven technology anchors volume shipments; electronic platforms command the steepest expansion trajectory.
End User:
Customer type determines service model configuration, with home care channels requiring remote monitoring infrastructure and decentralized logistics networks.
- Hospitals:Acute care facilities with 24-hour pharmacy and biomedical engineering support maintain the largest installed base. Centralized purchasing committees displace individual facility autonomy with enterprise-wide pump fleet standardization.
- Home Care:Domiciliary settings with visiting nurse oversight drive demand for portable, software-enabled systems with remote monitoring capabilities. This segment is gaining share fastest as patient mobility preferences intensify and reimbursement frameworks adapt.
- Clinics:Outpatient infusion centers for chemotherapy and specialty medication administration require intermediate durability specifications. These facilities balance capital constraints with throughput requirements.
- Long-term Care Facilities:Nursing homes and skilled nursing facilities concentrate demand for enteral nutrition pumps with simplified interfaces. Staff turnover challenges elevate importance of intuitive operation.
Hospitals retain the dominant procurement volume; home care is climbing the fastest on share.
Application:
Clinical indication shapes flow accuracy requirements and safety interlock specifications, with chemotherapy and pain management demanding the tightest tolerances.
- Medication Administration:Broad category encompassing antibiotic, hydration, and specialty drug delivery across inpatient and ambulatory settings. This application captures the widest end-user dispersion.
- Chemotherapy:Cytotoxic drug infusion requires closed-system transfer devices and precise flow control to minimize extravasation risk. Oncology clinics in the United States are adopting electronic peristaltic platforms at accelerated replacement cycles.
- Pain Management:Patient-controlled analgesia and continuous regional anesthesia demand programmable bolus limits and respiratory monitoring integration. These systems face heightened cybersecurity scrutiny for connected architectures.
- Nutritional Support:Enteral and parenteral feeding applications serve patients with compromised gastrointestinal function. Japan's super-aged prefectures present concentrated demand for pumps with Japanese-language interfaces.
Medication administration spans the broadest throughput; nutritional support is expanding most rapidly on demographic drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese manufacturers export precision pump systems to United States hospital networks and home care providers, establishing transatlantic and transpacific trade corridors that concentrate high-value procurement in aging Western markets.
United States
Integrated delivery networks in Texas and Florida standardize infusion pump fleets across multi-state footprints, compressing vendor diversity into sole-source agreements. FDA 510(k) pathway streamlining accelerates predicate-device clearances for chronic disease platforms. The Boston-Cambridge corridor anchors development of closed-loop insulin delivery systems integrating continuous glucose monitors.
Germany
Statutory health insurance expansion for hospital-at-home reimbursement sustains ambulatory pump procurement volumes across Bavaria and North Rhine-Westphalia. EU MDR technical documentation requirements for Class IIb devices extend certification timelines for manufacturers in Baden-Württemberg. Dortmund-based distribution partnerships channel specialized peristaltic systems into European home care networks.
Japan
Prefectures with super-aged demographics exceeding thirty percent population over sixty-five drive concentrated demand for enteral nutrition pumps with localized interfaces. PMDA post-market surveillance protocols mandate extended vigilance systems for device lifespans reaching two decades. The Kansai region around Osaka hosts manufacturing clusters for precision motor control systems supplying domestic pump assemblers.
United Kingdom
NHS England procurement frameworks consolidate purchasing authority for infusion platforms across acute trusts and community services. MHRA alignment with EU MDR transitional provisions maintains regulatory continuity for devices marketed in Northern Ireland. The Cambridge-Oxford arc concentrates software development for remote monitoring capabilities in ambulatory pump systems.
South Korea
MFDS accelerated review pathways for innovative medical devices reduce time-to-market for next-generation electronic pump platforms. Semiconductor foundries in Gyeonggi Province supply motor control chips to domestic and international pump manufacturers, creating supply chain interdependence. Seoul-based health technology clusters prototype wearable infusion formats targeting export markets.
Treatment Pumps Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive pump divisions alongside specialized fluid technology pure-plays. Market structure exhibits moderate consolidation at the premium tier with fragmentation in regional home care channels. Two strategic archetypes dominate: vertically integrated motor-and-control manufacturers and software-defined platform specialists. Competitive moves center on backward integration into precision tubing production and geographic expansion through specialized distribution partnerships.
Among European-headquartered conglomerates, Grundfos and Wilo SE exemplify the integrated manufacturing archetype with in-house production of motors and control systems. Xylem represents the technology-forward specialist position emphasizing electronic platforms for precision medication delivery. These three anchors illustrate divergent paths to margin capture: captive supply chain control versus software-enabled service differentiation.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| Sulzer |
| Flowserve Corporation |
| KSB |
| Ebara Corporation |
| Wilo SE |
| Pentair |
| The Weir Group |
| Others |
Value Network & Pricing Analysis
Brushless DC motor substitution for legacy stepper configurations simultaneously redraws supply geography toward East Asian semiconductor foundries and compresses pricing premiums for electronic pump platforms. This technology transition rewards manufacturers with captive motor control production while squeezing margins for assemblers dependent on merchant chip supply.
Pricing Analysis
Next-generation electronic platforms command 40-60% premiums over motor-driven systems, while prior-generation gravity-fed alternatives anchor economy tiers in emerging markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared smart pumps with cybersecurity certification from basic peristaltic units and mechanical alternatives. Price differentiation hinges on ISO 13485 quality tier and bundled remote monitoring service contracts. Cost compression in standard-tier electronic pumps is intensifying because Taiwanese foundry capacity constraints elevate motor control chip procurement costs. Home care providers exhibit highest price sensitivity due to reimbursement rate pressures, while integrated delivery networks in the United States demonstrate lowest sensitivity given cybersecurity compliance mandates.
Supply Chain Analysis
Port congestion on transpacific lanes from Shanghai to Long Beach elevates inbound logistics costs for precision tubing and sensor assemblies sourced from East Asian manufacturing clusters. Component concentration centers on Taiwan and South Korea for motor control semiconductors, Germany for precision peristaltic tubing, and Japan for flow sensor modules. Raw material dependencies encompass medical-grade silicone, rare-earth magnets for brushless motors, and specialized polymer formulations. Single-source vulnerability around Taiwanese foundry capacity for FDA-compliant motor controllers represents the dominant structural risk. Distribution runs through specialized durable medical equipment distributors in developed markets and direct hospital procurement consortiums in consolidated United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home care migration fragments historical hospital-centric demand into dispersed geographic niches, creating entry points for specialized service providers. This structural shift rewards players configuring decentralized logistics and remote monitoring infrastructure around patient locations rather than clinical facilities.
For Market Incumbents: Compound defensive positioning through backward integration into precision tubing production and software platform standardization across ambulatory pump portfolios. Threats from cybersecurity-engineering talent scarcity delay connected platform launches for competitors lacking firmware development scale. Certification investment in EU MDR technical documentation capabilities anchors market access retention.
For New Entrants and Emerging Players: Remote patient monitoring service gaps in Japan's super-aged prefectures offer white-space penetration for localized enteral pump platforms with Japanese-language interfaces. Direct-to-patient subscription channels bypass entrenched durable medical equipment distributor relationships. Reimbursement strategy alignment with Germany's hospital-at-home statutory coverage expansion provides the most penetrable geographic entry vector.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electronic platform specialists lacking regulatory affairs scale for EU MDR transition. Long-term viability over a multi-year horizon favors targets with software-defined architectures and data platform capabilities rather than mechanical engineering dependencies. Watch FDA cybersecurity guidance finalization as the signal indicating accelerated replacement cycles for legacy connected pumps.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity accelerates market access across German home care channels. |
| Hospital System Partnership | Sole-source agreements with United States integrated delivery networks consolidate procurement volume. |
| Software Companion Development | Remote monitoring applications capture recurring revenue from dispersed home care deployments. |
| Backward Integration | In-house precision tubing production insulates margins from medical-grade silicone price volatility. |
| Reimbursement Strategy | Alignment with Japan's long-term care insurance expansion unlocks enteral pump demand corridors. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, home care nurse coordinators, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS Medicare durable medical equipment fee schedules. Bottom-up installed base estimates triangulated against top-down reimbursement expenditure analysis.
Sensitivity analysis around semiconductor supply disruption scenarios and regulatory timeline variations informed probabilistic output ranges across the modeling period. Segmentation dimensions encompassed product type, technology generation, end-user setting, and clinical application. CAGRs derived from replacement cycle analysis, demographic projection alignment, and reimbursement policy trajectory assessment. Forecast inputs incorporated FDA cybersecurity guidance evolution and EU MDR transition completion pace.
Material uncertainties — geopolitical disruption of Taiwanese foundry supply, EU MDR certification timeline extensions, and cybersecurity incident liability frameworks — sit outside the modeled envelope. Forecasts reflect assumptions regarding reimbursement stability and regulatory continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Global Glucometer Market
Medical Devices
3D and 4D Ultrasound Devices Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
Facial Pumps Market
Medical Devices
IV Equipment Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Global Medical Drones Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Sputum Ejection Machine Market