
 Anesthesia Laryngeal Masks Market | 2026-2036
Anesthesia Laryngeal Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Anesthesia Laryngeal Masks Market Analysis
ISO 10993 biocompatibility testing is reorganizing competitive entry in the anesthesia laryngeal masks sector, forcing manufacturers to demonstrate cytotoxicity and sensitization compliance before commercialization. Medtronic Plc leverages its vertically integrated silicone supply chain to sustain cost advantages across multiple product tiers. Ambu A/S anchors its position through single-use disposable specialization that aligns with infection control protocols in European and North American hospitals.
An anesthesia laryngeal mask is a supraglottic airway device comprising a silicone or PVC mask with an inflatable cuff and airway tube, designed to secure ventilation without tracheal intubation during general anesthesia or emergency airway management; cuff inflation pressures typically range from 20 to 60 cm H₂O to balance seal integrity against mucosal perfusion. Disposable masks command the largest revenue pool due to cross-contamination liability and hospital preference for single-patient use, while specialty masks designed for difficult airways capture premium pricing through differentiated clinical outcomes. Silicone dominates material selection for reusable portfolios, though thermoplastic elastomer variants are gaining traction in cost-sensitive procurement channels.
The FDA's 510(k) pathway and the EU Medical Device Regulation (MDR) establish divergent conformity requirements that shape regional product portfolios and timeline-to-market for manufacturers serving both jurisdictions. Health Canada's device licensing framework adds a third qualification layer for North American market access, particularly impacting mid-tier competitors with limited regulatory affairs capacity. Stakeholders must monitor how evolving MDR notified body capacity constraints and FDA cybersecurity guidance for connected airway devices reshape competitive positioning and capital allocation priorities.
Market Dynamics
Hospital consolidation across the United States is compressing vendor counts and forcing anesthesia laryngeal mask manufacturers to negotiate system-wide contracts with integrated delivery networks rather than individual facilities.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volume in United States freestanding surgery centers is pulling disposable mask procurement away from traditional hospital supply chains.
- EU MDR implementation:Stricter conformity assessment under the Medical Device Regulation is filtering out subscale competitors and clearing shelf space for qualified suppliers in European markets.
- Silicone-to-elastomer material migration:Thermoplastic elastomer variants are opening cost-sensitive procurement channels in emerging markets previously locked out by silicone pricing.
Market Restraints
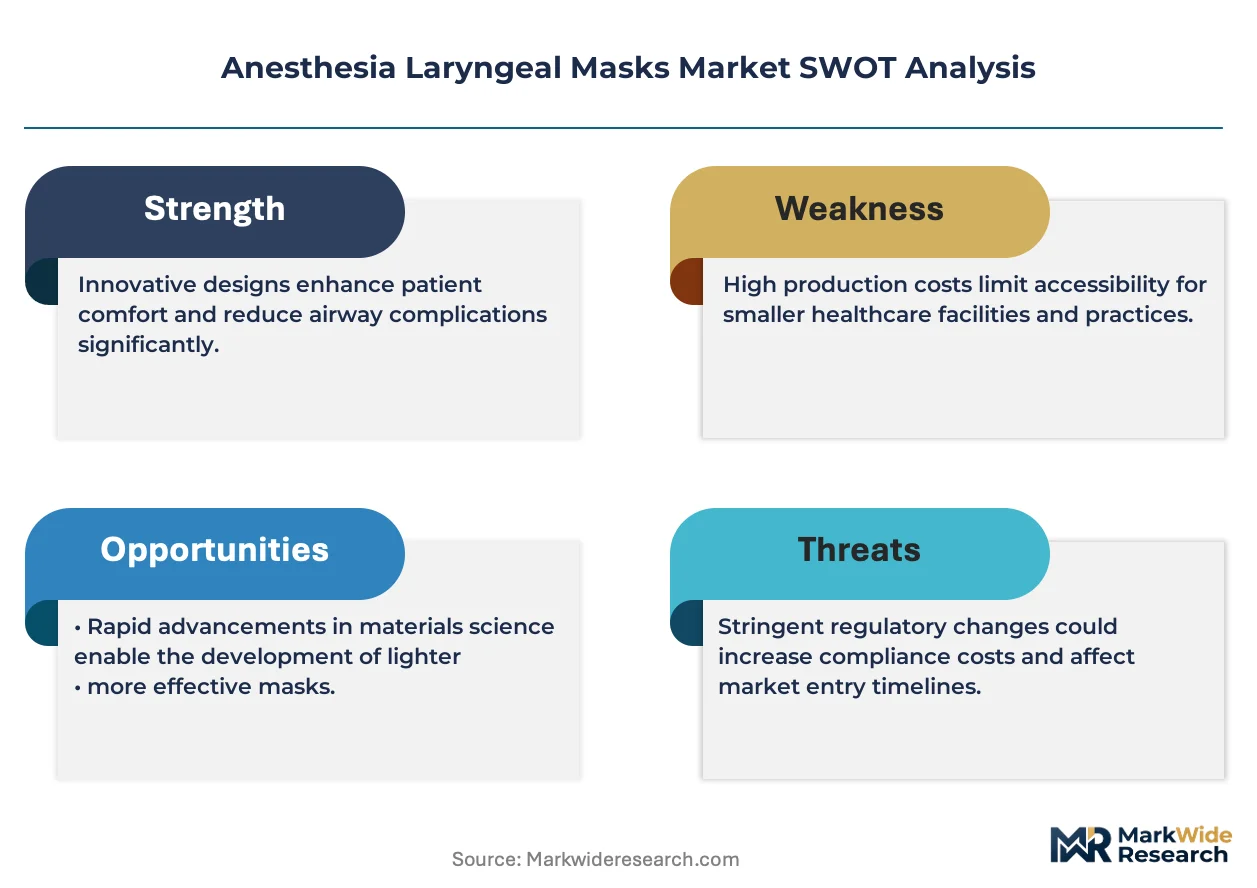
- Raw material concentration:Medical-grade silicone supply concentrates among a handful of European and Asian chemical processors, exposing mask manufacturers to input volatility.
- FDA 510(k) pathway friction:Updated predicate device requirements and enhanced biocompatibility documentation are extending clearance timelines for novel designs.
- Video laryngoscope substitution:Advanced airway visualization systems are capturing cases in anticipated difficult airways, constraining premium mask adoption in high-acuity settings.
Strategic Opportunities
- Underpenetrated Indian hospital sector:Tier-2 and Tier-3 cities in India lack standardized supraglottic airway protocols, creating first-mover advantage for training-bundle offerings.
- Pediatric specialization gap:Size-appropriate masks for neonatal and infant populations remain underserved relative to adult portfolios across all major markets.
- Health Canada accelerated review:The Medical Devices Bureau's priority review pathway for novel airway devices offers faster market access for innovators meeting clinical evidence thresholds.
Industry Challenges
- Regulatory affairs talent scarcity:Qualified professionals capable of navigating simultaneous FDA, EU MDR, and Health Canada submissions command premium compensation and extend hiring cycles.
- Legacy sterilization infrastructure:Reusable mask portfolios require ethylene oxide or steam sterilization validation that conflicts with hospital sustainability targets and capital replacement schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anesthesia Laryngeal Masks Market |
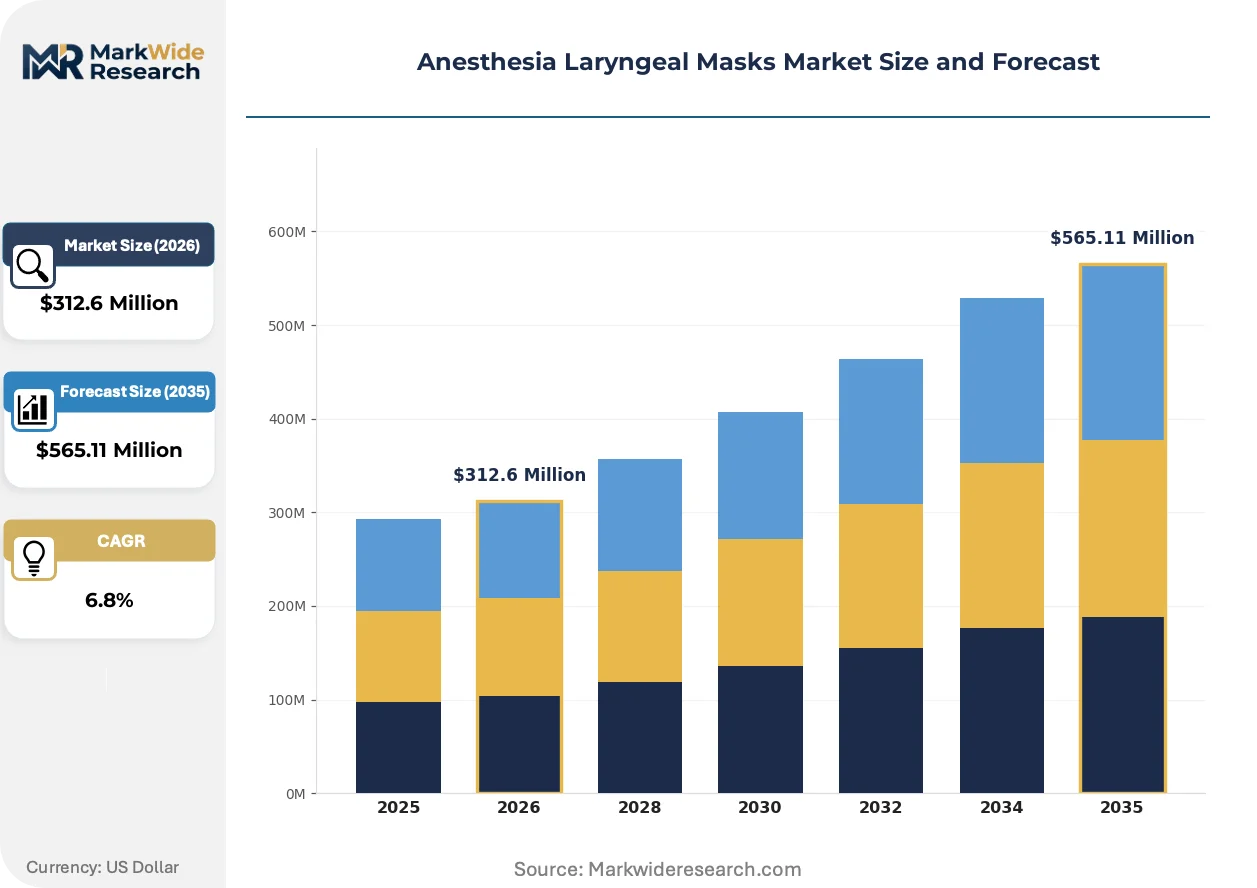
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reusable Masks, Disposable Masks, Specialty Masks, Neonatal Masks Material: Silicone, PVC, Thermoplastic Elastomer, Latex End User: Hospitals, Surgical Centers, Home Care, Emergency Services Application: General Anesthesia, Emergency Intubation, Sedation, Respiratory Support |
| Companies Covered | Intersurgical Ltd., Medline Industries, Inc., Ambu A/S, ICU Medical Inc., Hitec Medical Co. Ltd., Teleflex Incorporated, Smiths Medical, Besmed Health Business Corp., Medtronic Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anesthesia Laryngeal Masks Market Emerging Trajectories
Digital integration and material science advances are rewriting performance benchmarks for airway management devices, while procurement centralization is compressing traditional distribution hierarchies.
Integrated pressure monitoring sensors embedded within mask cuffs are fragmenting the traditional manual-inflation segment. Academic medical centers in Germany and the United States are piloting these connected devices to prevent overinflation injuries. Real-time pressure telemetry is enabling outcome-based contracting models that tie supplier payment to perioperative airway complication rates.
The EU Medical Device Regulation's enhanced clinical evidence requirements are restructuring product development budgets. Manufacturers must now commission prospective studies or systematic literature reviews for 510(k)-cleared predicates seeking MDR conformity. Mid-tier suppliers with limited post-market surveillance infrastructure are retreating from European markets, ceding share to larger competitors with dedicated regulatory affairs divisions.
Group purchasing organization consolidation is concentrating buying power among three dominant United States healthcare procurement networks. Independent hospitals and smaller health systems are losing negotiating leverage as these GPOs demand exclusive multi-year contracts with standardized product formularies. Suppliers are responding by dedicating national account teams to GPO relationship management rather than field sales forces.
Anesthesia Laryngeal Masks Market Segmentation
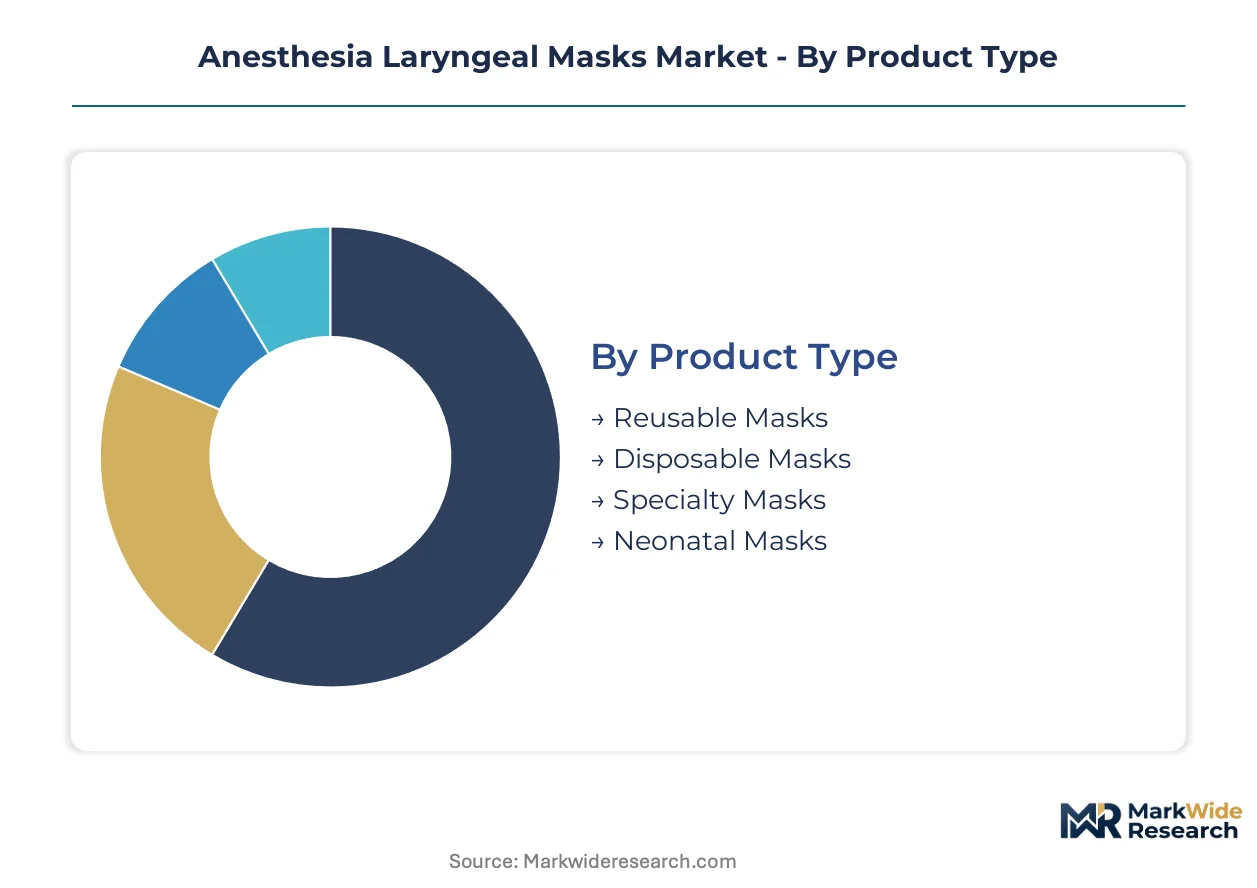
Product differentiation in anesthesia laryngeal masks follows distinct clinical risk profiles and procurement economics. Material composition and sterility requirements create divergent margin structures across each segment category.
Product Type:
FDA 510(k) clearance pathways diverge sharply between reusable and disposable portfolios, with the former requiring sterilization validation and the latter demanding biocompatibility dossiers under ISO 10993.
- Disposable Masks:Single-use silicone or PVC construction eliminates cross-contamination liability. Hospital procurement in the United States concentrates here as integrated delivery networks standardize on disposable formularies to reduce infection control overhead.
- Reusable Masks:Medical-grade silicone withstands 40+ autoclave cycles. European hospitals retain higher reusable penetration due to sustainability mandates and ethylene oxide sterilization infrastructure, though this segment faces pressure from green procurement targets.
- Specialty Masks:Designed for anticipated difficult airways with reinforced tubes or gastric access channels.
- Neonatal Masks:Ultra-low-volume cuffs sized for infants under 5 kg; limited supplier base due to precision molding requirements.
Disposable masks handle the majority of throughput; specialty masks are expanding most quickly on share as difficult airway protocols proliferate.
Material:
Cost tier stratification separates premium silicone from economy thermoplastic alternatives, with raw material sourcing geography determining landed cost competitiveness.
- Silicone:Platinum-cured medical silicone delivers superior cuff compliance and tissue biocompatibility. German and Japanese chemical processors dominate supply, constraining mid-tier manufacturers without long-term supply agreements.
- Thermoplastic Elastomer:TPE variants cut unit costs by 30-40% versus silicone. Indian and Southeast Asian procurement channels favor this material as hospital budgets stretch to cover expanding surgical volumes.
- PVC:Legacy material for single-use economy masks; phthalate concerns limit growth in regulated markets.
- Latex:Declining share due to Type I hypersensitivity risk; retained only in cost-minimized emergency stockpiles.
Silicone commands the premium tier by volume; thermoplastic elastomer climbs fastest as emerging markets scale purchasing.
End User:
Customer type determines packaging, training bundle requirements, and contract structure, with surgical centers demanding just-in-time logistics distinct from hospital central supply models.
- Hospitals:High-volume purchasers negotiating system-wide contracts with mandatory conversion clauses. Operating room throughput requirements drive preference for established mask designs with proven insertion success rates.
- Surgical Centers:Freestanding ambulatory facilities in the United States are pulling volume from hospital supply chains. These customers prioritize compact packaging and minimal training overhead for rotating clinical staff.
- Emergency Services:Pre-hospital airway management requires ruggedized packaging and rapid deployment features.
- Home Care:Limited penetration; palliative sedation protocols in select European markets drive niche demand.
Hospitals retain the dominant procurement position; surgical centers are gaining share fastest as outpatient migration accelerates.
Application:
Clinical indication dictates performance specifications, with emergency intubation scenarios demanding rapid-seal reliability distinct from elective anesthesia workflows.
- General Anesthesia:Elective surgical procedures in operating rooms represent the core use case. Cuff pressure monitoring and gastric access ports differentiate premium offerings in this high-volume segment.
- Emergency Intubation:Pre-hospital and emergency department use requires blind insertion success rates exceeding 95% on first attempt. Military and disaster medicine procurement channels specify reinforced airway tubes.
- Sedation:Procedural sedation in endoscopy suites drives demand for masks with bite blocks and suction channels.
- Respiratory Support:Bridge ventilation in ICU step-down units; limited to short-term use due to aspiration risk.
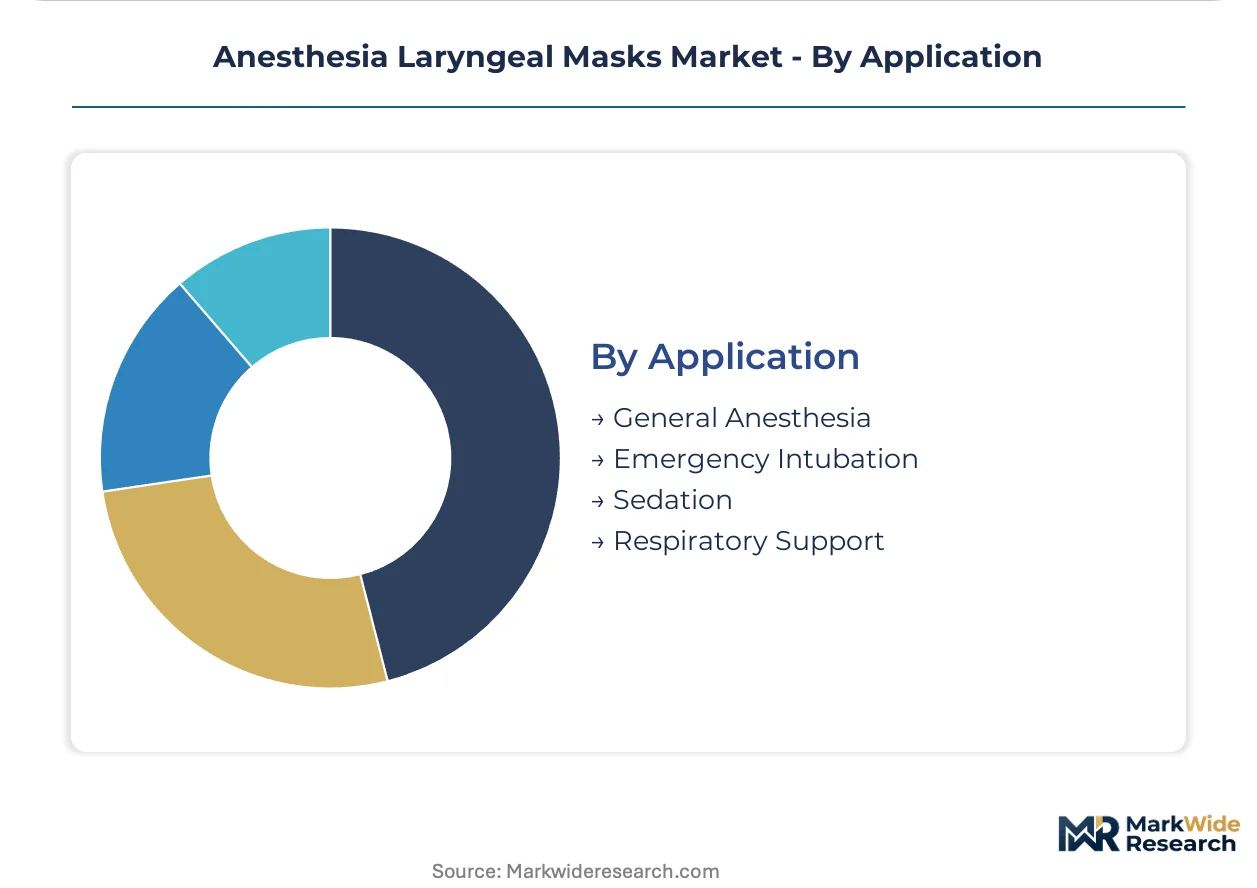
General anesthesia carries the highest procedure volume; emergency intubation applications are scaling fastest as pre-hospital airway protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics corridor underwrites European distribution efficiency for airway management products entering the continent.
United States
Hospital consolidation into integrated delivery networks concentrates disposable mask procurement through three dominant group purchasing organizations. The FDA's updated 510(k) predicate device requirements extend clearance timelines for novel designs. The Cleveland Clinic and Mayo Clinic anchor demand in the Midwest, standardizing on single-use silicone formularies across their surgical networks.
Germany
Academic medical centers in Munich and Heidelberg pilot integrated pressure-monitoring sensors for cuff inflation telemetry. The EU MDR's enhanced clinical evidence requirements filter out subscale competitors lacking post-market surveillance infrastructure. The Rhine-Main industrial corridor hosts sterilization validation facilities serving reusable mask portfolios across Central Europe.
India
Tier-2 and Tier-3 cities lack standardized supraglottic airway protocols, creating first-mover advantage for training-bundle offerings. The CDSCO's medical device rules align with global harmonization initiatives while maintaining country-specific labeling requirements. Maharashtra's Mumbai-Pune pharmaceutical belt concentrates domestic manufacturing of thermoplastic elastomer variants for cost-sensitive procurement channels.
China
NMPA's streamlined Class II device registration accelerates market access for established silicone mask designs. The Yangtze River Delta medical device cluster in Jiangsu and Zhejiang provinces scales thermoplastic elastomer production for domestic and Southeast Asian export markets. Shanghai's Ruijin Hospital anchors clinical validation studies for pediatric mask sizing protocols.
Japan
PMDA's quality management system inspections enforce rigorous biocompatibility documentation for silicone cuff materials. The Kansai region's Osaka-Kobe medical device manufacturing base supplies premium reusable portfolios across East Asia. Tokyo's National Center for Child Health and Development drives neonatal mask specification standards for the Asia-Pacific region.
Anesthesia Laryngeal Masks Market Vendor Landscape
Listed leaders compete with private specialists across regulatory compliance capacity, creating a tiered structure where scale determines European and North American market access. The vendor base separates into three archetypes: diversified medtech conglomerates with captive silicone supply chains, single-use disposable specialists aligned with infection control protocols, and regional fabricators serving price-sensitive emerging markets. Dominant competitive moves include backward integration into medical-grade polymer processing and exclusive multi-year contracting with consolidated health systems.
Within the premium-tier vector, Medtronic Plc and Teleflex Incorporated occupy positions anchored by vertically integrated supply chains and established 510(k) predicate libraries. Ambu A/S exemplifies the single-use specialization archetype, with its Danish corporate structure signaling European regulatory fluency. Hitec Medical Co. Ltd. represents the Asia-based manufacturing tier, with its corporate designation indicating capacity for thermoplastic elastomer production at scale.
| Leading Market Players |
|---|
| Intersurgical Ltd. |
| Medline Industries, Inc. |
| Ambu A/S |
| ICU Medical Inc. |
| Hitec Medical Co. Ltd. |
| Teleflex Incorporated |
| Smiths Medical |
| Besmed Health Business Corp. |
| Medtronic Plc |
| Others |
Supply Flow & Price Mechanics
Multi-year exclusive contracting with integrated delivery networks locks in supply access and price visibility for anesthesia laryngeal mask manufacturers serving United States hospital systems. These arrangements bundle volume commitments with formula pricing tied to medical-grade silicone indices, insulating qualified suppliers from spot-market volatility while compressing margins for competitors outside preferred vendor lists.
Pricing Analysis
Volume-discount tiering structures separate national account pricing for GPO-integrated health systems from spot procurement rates paid by independent surgical centers. Price differentiation rests on FDA 510(k) predicate status and ISO 10993 biocompatibility certification tier, with cleared silicone portfolios commanding premiums over thermoplastic elastomer alternatives. Pricing pressure stems from group purchasing organization consolidation demanding standardized formularies at contracted rates. Independent ambulatory surgical centers exhibit highest price sensitivity, while academic medical centers prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Inventory lead times for medical-grade silicone extend due to platinum-cured polymer processing constraints at German and Japanese chemical processors. Geographic supply concentration centers on Germany, Japan, and China, with the Yangtze River Delta scaling thermoplastic elastomer production for cost-sensitive channels. Raw material dependencies include platinum-cured silicone, thermoplastic elastomer compounds, and medical-grade PVC resin. Single-source vulnerability pervades platinum catalyst supply chains. Distribution runs through medical device distributors serving hospital central supply and surgical center just-in-time logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anesthesia laryngeal masks market is accelerating through EU MDR regulatory disruption that filters out subscale competitors lacking clinical evidence infrastructure. This inflection concentrates procurement power among qualified suppliers with dedicated regulatory affairs divisions.
For Market Incumbents: Consolidate market position by deepening backward integration into medical-grade silicone processing and securing exclusive multi-year GPO contracts before MDR implementation peaks. Video laryngoscope substitution threatens premium mask adoption in high-acuity settings; defend by embedding pressure-monitoring sensors that enable outcome-based contracting with academic medical centers. For New Entrants and Emerging Players: Differentiate on pediatric specialization and training-bundle offerings targeting Tier-2 and Tier-3 Indian cities lacking standardized supraglottic airway protocols. Neonatal mask sizing remains underserved relative to adult portfolios across all major markets. Partner with regional distributors possessing hospital system relationships rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers with FDA 510(k) predicate libraries and incomplete EU MDR conformity assessments, where regulatory completion creates immediate European market access. Long-term viability favors suppliers with vertically integrated polymer processing and established GPO relationships. Watch for MDR notified body capacity constraints as the inflection signal for competitive clearing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Completion | Unlocks European market access as notified body capacity constraints filter subscale competitors. |
| Integrated Pressure Sensor Development | Enables outcome-based contracting with Cleveland Clinic and Mayo Clinic surgical networks. |
| Silicone Supply Chain Integration | Secures medical-grade polymer access against raw material concentration among German and Japanese processors. |
| Pediatric Mask Portfolio Expansion | Captures underserved neonatal sizing demand across Asia-Pacific academic medical centers. |
| Indian Training Bundle Deployment | Establishes first-mover protocol standardization in Tier-2 and Tier-3 city hospital networks. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with anesthesia department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and customs trade records. Bottom-up volume estimates triangulated with top-down market sizing across product type, material composition, end user category, and application segments.
Across the analysis window, the forecasting framework modeled disposable versus reusable mask penetration, silicone-to-elastomer material migration, and ambulatory surgical center volume capture. CAGRs derived from procedure volume projections, regulatory timeline assumptions, and procurement centralization patterns. Industry-specific inputs included FDA 510(k) clearance pipeline data and EU MDR notified body appointment rates.
The analysis sits within stated boundaries; outcomes outside sustained hospital consolidation, stable silicone supply availability, or unchanged MDR implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding procedure volume trajectories and regulatory enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Aesthetic Devices Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Patient Lift Slings Market
Medical Devices
United Kingdom Neonatal and Prenatal Devices Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
PC-Based Resting Electrocardiograph Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Liposuction Devices Market
Medical Devices
Australia Minimally Invasive Surgery Devices Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Massage Equipment Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Jet Nebulizers Market