
 Ophthalmoscopes Market | 2026-2036
Ophthalmoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmoscopes Market Intelligence
High-definition imaging specifications is bifurcating the ophthalmoscopes landscape into premium diagnostic suites and cost-optimized point-of-care units. Carl Zeiss Meditec AG leverages its optical heritage to dominate retinal imaging workstations. HEINE Optotechnik anchors the handheld segment through German-engineered LED illumination systems. Nidek Co., Ltd. competes aggressively in automated fundus photography across Asian eye hospital networks.
An ophthalmoscope is a diagnostic instrument that projects controlled light through the pupil to visualize the retina, optic disc, and vasculature, typically employing coaxial optics with adjustable diopter lenses ranging from minus 35 to plus 40 for refractive compensation. The device serves ophthalmologists and optometrists in detecting glaucoma, diabetic retinopathy, and macular degeneration during routine and emergency examinations. Digital ophthalmoscopes command premium pricing by integrating CMOS sensors and wireless image capture for telemedicine workflows. Handheld variants represent the fastest-growing product category as primary care physicians deploy them for bedside diabetic eye screening. LED illumination technology has displaced halogen across all tiers, reducing heat emission and extending bulb life tenfold.
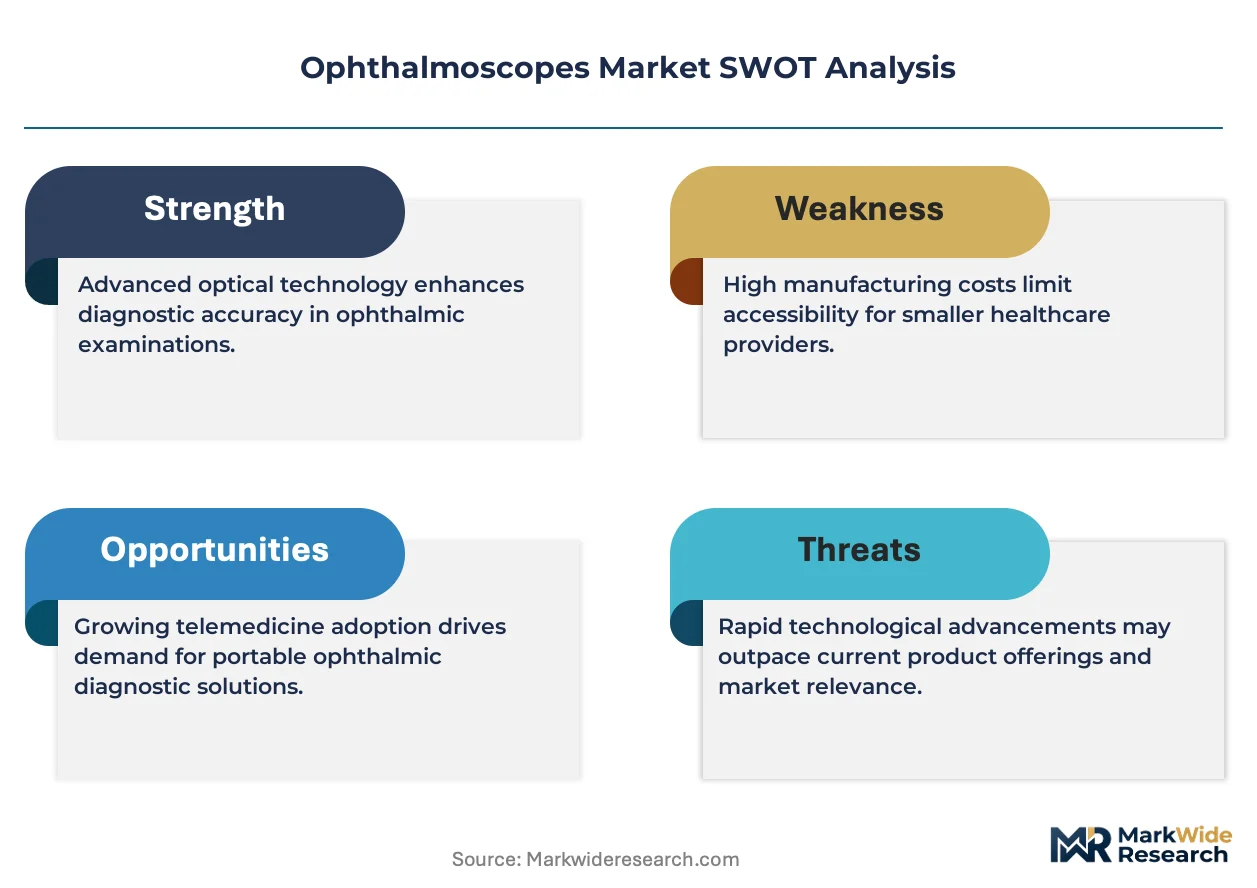
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) impose clinical validation burdens that slow market entry for new manufacturers while reinforcing incumbents with established quality management systems. The EPA's mercury lamp restrictions indirectly accelerate LED conversion timelines for instrument refurbishers. Stakeholders must monitor reimbursement coding changes for remote retinal imaging, as telehealth parity laws in the United States and Germany will determine whether captured fundus photographs qualify for standalone professional fees or require synchronous physician interpretation.
Market Dynamics
LED illumination systems and CMOS sensor integration are compressing form factors while expanding diagnostic capabilities, forcing incumbents to reengineer optical pathways for handheld dominance and telemedicine compatibility.
Growth Catalysts
- Diabetic retinopathy screening mandates:National health programs in Germany and Japan now require annual fundus examinations for diabetic patients, driving volume through primary care networks.
- Telehealth parity legislation:Reimbursement coding changes in the United States now recognize asynchronous retinal image interpretation as billable professional services.
- Halogen-to-LED conversion:EPA mercury lamp restrictions accelerate refurbishment cycles across hospital capital equipment fleets.
Market Restraints
- Optical component supply concentration:Precision lens grinding capacity concentrates in Jena, Germany and Osaka, Japan, creating single-source vulnerabilities.
- EU MDR clinical validation burdens:Extended conformity assessment timelines delay market entry for new manufacturers lacking established quality management systems.
- Smartphone-based fundus imaging:Low-cost adapter systems threaten standalone ophthalmoscope demand in resource-limited settings.
Strategic Opportunities
- Underserved rural India:Vision screening camps and mobile diabetic clinics create demand for battery-powered, dust-resistant handheld units.
- AI-assisted diagnostic convergence:Integration of automated disease detection algorithms with wireless image capture enables point-of-care decision support.
- Subscription-based service models:Device-as-a-service offerings bundle hardware, software updates, and remote specialist access for independent optometry practices.
Industry Challenges
- Optical engineering talent scarcity:Precision lens design and coaxial alignment expertise concentrates among aging specialists in traditional optics hubs.
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for novel illumination wavelengths require extensive bench testing documentation.
- Legacy EMR integration complexity:DICOM compliance and proprietary hospital network protocols demand customized software development for each deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmoscopes Market |
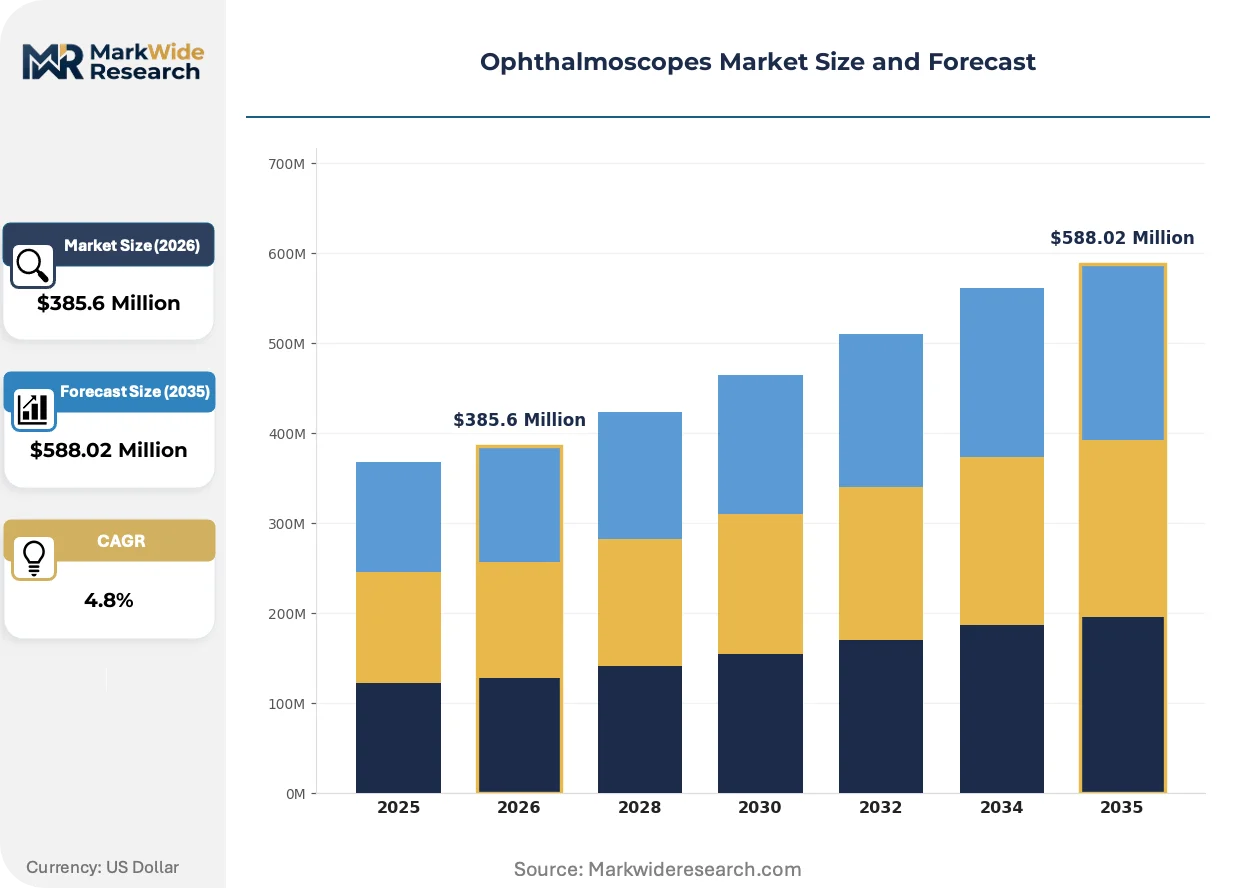
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Ophthalmoscopes, Handheld Ophthalmoscopes, Indirect Ophthalmoscopes, Direct Ophthalmoscopes End User: Eye Hospitals, Ophthalmology Clinics, Home Healthcare, Research Institutes Technology: Optical Coherence Tomography, Fundus Imaging, Retinal Photography, LED Illumination Distribution Channel: Online Retail, Distributors, Direct Sales, Pharmacies |
| Companies Covered | HEINE Optotechnik, Rudolf Riester GmbH, Welch Allyn, Nidek Co., Ltd., Iridex Corporation, Zumax Medical Co., Ltd., Carl Zeiss Meditec AG, Topcon Corporation, Keeler Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmoscopes Market Strategic Shifts & Innovations
Digital capture capabilities and wireless connectivity are dissolving the boundary between diagnostic hardware and clinical software, creating integrated screening ecosystems that extend ophthalmic expertise beyond specialist suites.
CMOS sensor arrays with adaptive noise reduction are miniaturizing high-resolution fundus photography into pocket-sized devices. Primary care physicians in the United States and Germany now deploy these units for bedside diabetic eye screening without pupil dilation. The technology is miniaturizing equipment footprints while preserving diagnostic fidelity previously restricted to tabletop retinal cameras.
EU Medical Device Regulation (MDR) Article 10 clinical evaluation requirements now mandate post-market surveillance systems for all Class IIa optical diagnostic devices. Manufacturers must establish periodic safety update reports and trend analysis protocols. Asian exporters to European markets are responding by acquiring notified body partnerships and building dedicated regulatory affairs teams in Dublin and Amsterdam.
Hospital procurement departments now unbundle capital equipment purchases from service contracts and software licensing. Standalone hardware tenders favor lowest-unit-cost suppliers while imaging platforms and maintenance agreements route through separate IT and facilities budgets. This bifurcation is most visible in German university hospital networks and United States integrated delivery systems seeking operational expenditure flexibility.
Ophthalmoscopes Market Segmentation
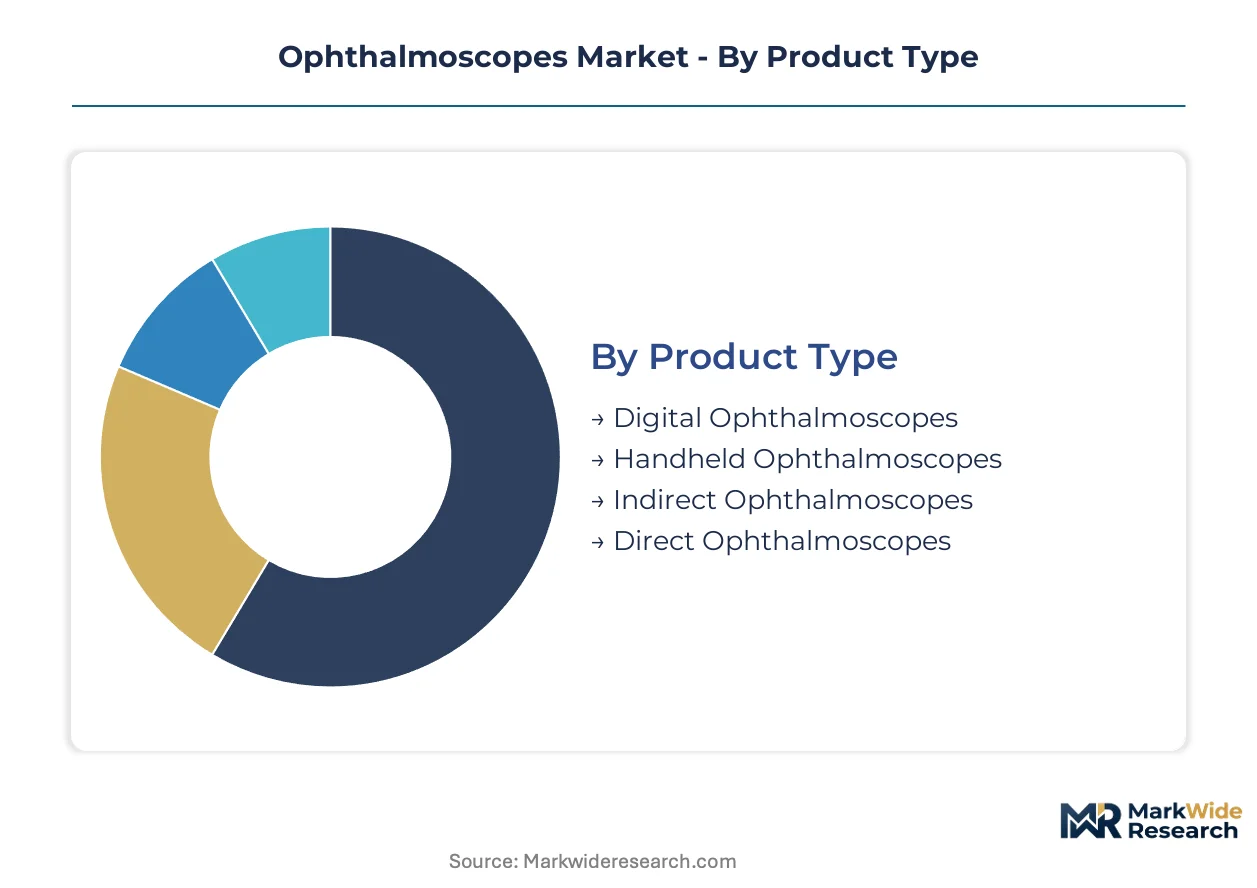
Segmentation in the ophthalmoscopes market reveals distinct margin architectures across product tiers and channel structures. Understanding where value concentrates helps manufacturers allocate R&D resources and optimize commercial strategies.
Product Type:
Margin pools concentrate in digital capture capabilities and wireless connectivity features that command premium positioning.
- Digital Ophthalmoscopes:CMOS sensor arrays with adaptive noise reduction enable high-resolution fundus photography without pupil dilation. Demand concentrates in German university hospital networks and United States integrated delivery systems where telemedicine workflows require DICOM-compliant image capture.
- Handheld Ophthalmoscopes:Battery-powered LED illumination systems with coaxial optics serve primary care physicians for bedside diabetic eye screening. Primary care networks in Japan and rural India deploy these units for mobile screening camps, driven by national diabetic retinopathy mandates.
- Indirect Ophthalmoscopes:Binocular viewing systems with condensing lenses provide stereoscopic retinal examination for surgical planning.
- Direct Ophthalmoscopes:Traditional monocular designs with adjustable diopter lenses remain standard equipment in resource-limited settings.
Digital ophthalmoscopes hold installed capacity. Handheld ophthalmoscopes are rotating up the share rankings.
End User:
Volume concentration shifts toward outpatient settings as screening protocols expand beyond specialist suites.
- Eye Hospitals:Multi-station retinal imaging suites with automated fundus photography handle high-throughput screening volumes. Asian eye hospital networks in Japan and South Korea drive replacement cycles for legacy halogen systems.
- Ophthalmology Clinics:Compact digital units with EMR integration serve private practice workflows in Germany and the United States. Reimbursement coding changes for asynchronous image interpretation accelerate adoption in independent settings.
- Home Healthcare:Smartphone-compatible adapters and portable screening devices support remote monitoring programs.
- Research Institutes:Spectral-domain optical coherence tomography systems enable longitudinal clinical studies.
Eye hospitals hold installed capacity. Ophthalmology clinics are rotating up the share rankings.
Technology:
Patent-protected imaging modalities capture disproportionate value compared to commoditized illumination components.
- Optical Coherence Tomography:Interferometric depth-resolved imaging generates cross-sectional retinal maps for glaucoma progression monitoring. Tertiary care centers in Germany and Japan deploy swept-source variants for posterior segment pathology.
- Fundus Imaging:Wide-field digital capture systems with red-free and autofluorescence filters support diabetic retinopathy screening programs. United States primary care networks favor these units for telehealth parity reimbursement.
- Retinal Photography:Standard color fundus documentation for clinical records and referral documentation.
- LED Illumination:Solid-state light engines with tunable color temperature have displaced halogen across all product tiers.
Optical coherence tomography holds installed capacity. Fundus imaging is rotating up the share rankings.
Distribution Channel:
Procurement decentralization favors flexible purchasing arrangements over traditional capital equipment sales cycles.
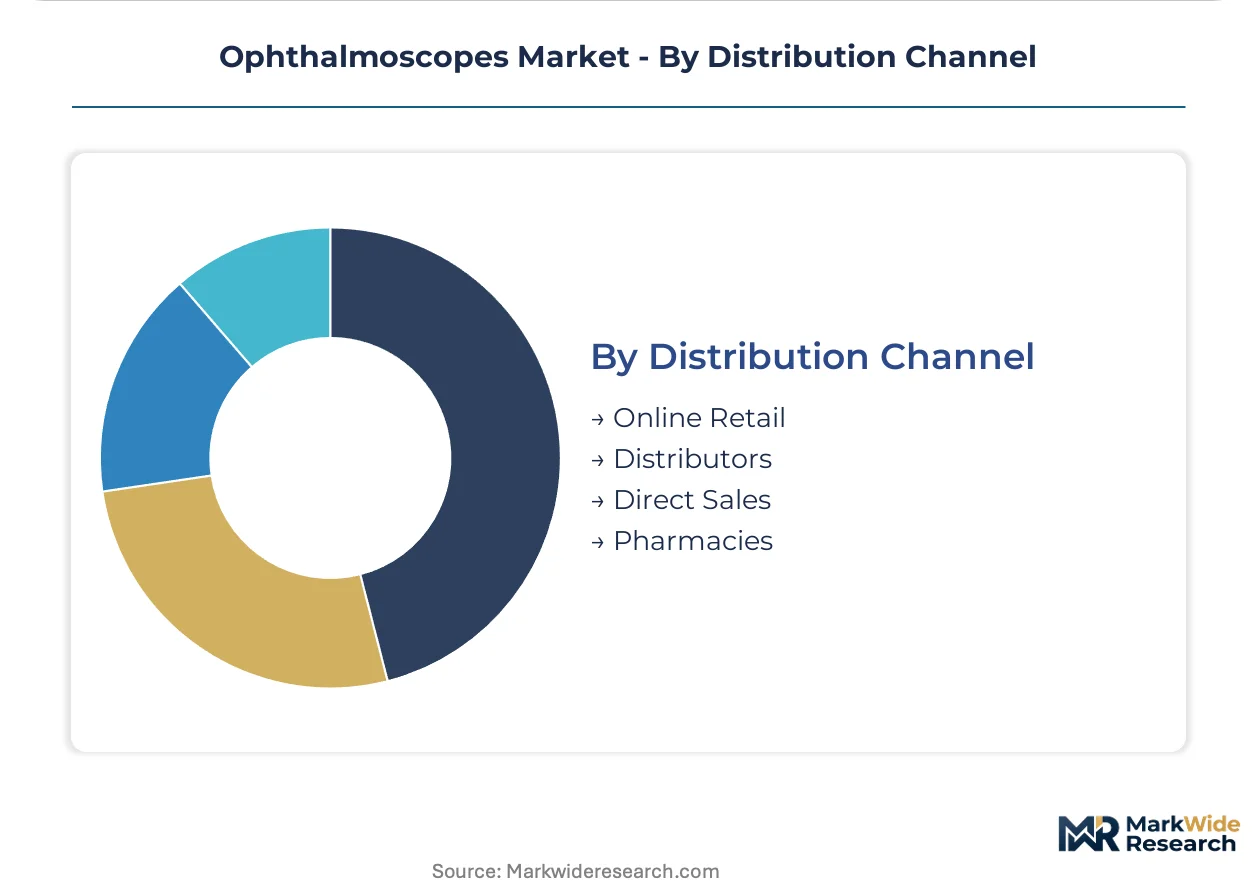
- Direct Sales:Manufacturer field engineers provide installation, training, and service integration for complex multi-station suites. German university hospital networks prefer this channel for customized EMR connectivity.
- Distributors:Regional inventory and technical support networks serve mid-tier ophthalmology clinics in the United States and Japan. These intermediaries handle FDA 510(k) documentation and EU MDR conformity logistics.
- Online Retail:E-commerce platforms with specification comparison tools attract independent optometrists and small practices.
- Pharmacies:Limited over-the-counter availability for basic screening devices in select markets.
Direct sales holds installed capacity. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for precision diagnostic suites, while primary care networks in India and rural United States prioritize cost-optimized handheld units for screening scale.
United States
Integrated delivery systems and telehealth parity legislation drive demand for DICOM-compliant digital capture systems. FDA 510(k) clearance pathways shape product development timelines for optical medical devices. The Greater Boston corridor concentrates ophthalmic imaging R&D activity alongside venture capital deployment for AI-assisted diagnostics.
Germany
National diabetic retinopathy screening mandates and aging demographics sustain replacement cycles for LED-illuminated workstations. EU MDR Article 10 clinical evaluation requirements impose conformity assessment burdens on Asian exporters. Jena maintains precision lens grinding concentration alongside established optical engineering expertise clusters.
Japan
Universal health coverage and automated fundus photography adoption across eye hospital networks sustain premium equipment demand. PMDA regulatory frameworks align with international standards for optical diagnostic device approval. Osaka anchors retinal imaging component manufacturing alongside precision optics supply chain concentration.
India
Vision screening camps and mobile diabetic clinics create demand for battery-powered, dust-resistant handheld ophthalmoscopes. CDSCO medical device regulations are harmonizing with international standards for import clearance. Maharashtra and Karnataka concentrate ophthalmic device distribution networks alongside metropolitan hospital procurement expansion.
South Korea
MFDS regulatory efficiency and national health insurance coverage support rapid adoption of digital diagnostic platforms. Government-funded smart hospital initiatives accelerate EMR-integrated imaging deployment. Seoul Capital Area concentrates ophthalmology clinic density alongside medical device manufacturing capabilities.
Ophthalmoscopes Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the ophthalmoscopes landscape. Premium diagnostic suites command margins through proprietary imaging modalities and software integration, while handheld specialists compete on manufacturing scale and distribution reach. Three archetypes dominate: optical heritage conglomerates with retinal imaging workstations, German-engineered LED illumination specialists, and Asian automated fundus photography manufacturers. Competitive moves concentrate on strategic partnerships for AI algorithm integration and geographic expansion through distributor network acquisition.
Within the optical heritage tier, Carl Zeiss Meditec AG and Topcon Corporation exemplify precision engineering consolidation. HEINE Optotechnik occupies a position among German-engineered illumination specialists. Nidek Co., Ltd. anchors the automated fundus photography segment. These three represent distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| HEINE Optotechnik |
| Rudolf Riester GmbH |
| Welch Allyn |
| Nidek Co., Ltd. |
| Iridex Corporation |
| Zumax Medical Co., Ltd. |
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| Keeler Ltd. |
| Others |
Cost & Logistics Intelligence
Precision lens grinding capacity utilization in Jena and Osaka shapes both supply concentration and price floors for optical diagnostic devices. German and Japanese engineering clusters maintain tenured expertise in coaxial alignment systems, creating natural barriers to entry that sustain premium pricing tiers while limiting downward price mobility for quality-validated instruments.
Pricing Analysis
EU MDR Article 10 clinical evaluation requirements dictate the pricing tier structure for ophthalmoscopes sold across European markets. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared digital imaging suites from CE-marked handheld units and unbundled refurbishment components. Price differentiation rests on certification grade and after-sales service bundling, with German university hospital networks showing lowest sensitivity and rural Indian primary care networks driving cost compression. Margins are tightening due to smartphone-based fundus imaging alternatives in resource-limited settings.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes periodically disrupt inbound logistics for CMOS sensor arrays and precision optical components. Manufacturing gravity centers on Germany, Japan, and South Korea, with component sourcing drawing from Taiwanese semiconductor foundries and Chinese LED substrate suppliers. Single-source vulnerability concentrates in Jena-based precision lens grinding capacity. Distribution runs through manufacturer field engineers for complex suites and regional distributors for mid-tier clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of coaxial alignment specialists with precision optics training constrains manufacturing expansion and sustains incumbent positioning. This capability gap limits how quickly new production capacity can enter even when capital is available.
For Market Incumbents: Fortify regulatory affairs infrastructure in Dublin and Amsterdam to navigate EU MDR conformity assessment timelines for Asian market access. Acquire notified body partnerships ahead of competitor moves, and deepen in-house production of LED illumination engines to offset optical component supply concentration risks from single-source Japanese suppliers. For New Entrants and Emerging Players: Lead with AI-assisted diagnostic software bundled with commodity hardware to bypass optical engineering talent scarcity. Target rural India and underserved United States primary care networks where smartphone-compatible screening devices face reimbursement coding tailwinds, and pursue distributor acquisition in Maharashtra and Karnataka rather than direct sales buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device-as-a-service platforms with embedded software updates and remote specialist access. Long-term viability favors acquisition targets with established GPO contracts and hospital system purchasing committee relationships. Watch telehealth parity legislation expansion in German Länder as inflection indicator for asynchronous retinal imaging reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance unlocks German and French hospital procurement channels. |
| Hospital System Partnership | Integrated delivery systems in the United States favor DICOM-compliant EMR integration. |
| Software Companion Development | AI-assisted diagnostic algorithms enable point-of-care decision support for primary care physicians. |
| Reimbursement Strategy | Telehealth parity laws in Germany and the United States determine standalone professional fee eligibility. |
| Backward Integration | In-house LED illumination production reduces dependency on Japanese substrate suppliers. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with ophthalmology clinic directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists; and secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement coding updates. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and distribution channel dimensions.
Across the analysis window, the analytical framework modeled volume and value outputs through segmentation by product tier, illumination technology, geographic regulatory cluster, and procurement channel structure. CAGRs were derived from installed base replacement cycles and screening protocol expansion trajectories. Forecast inputs incorporated diabetic retinopathy mandate implementation timelines and LED conversion rates from legacy halogen systems.
Underlying assumptions cover reimbursement coding stability for asynchronous retinal imaging and continued EU MDR enforcement stringency, with deviation risk concentrated in telehealth parity legislation reversals and optical component supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Aerosol Drug Delivery Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
APAC AMH Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Nitinol-Based Guide Wire Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Contraceptive Rings Market
Medical Devices
T-Piece Resuscitator Market