
 Global Cardiopulmonary Bypass Accessory Equipment Market | 2026-2036
Global Cardiopulmonary Bypass Accessory Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiopulmonary Bypass Accessory Equipment Market Foresight
The EU Green Deal is shifting procurement criteria toward lower-carbon manufacturing footprints in cardiovascular device supply chains. Medtronic leverages its integrated perfusion platform to sustain market presence across European cardiac centers. Terumo Cardiovascular anchors its position through specialized oxygenator technology leadership. LivaNova PLC differentiates via geographic dominance in Latin American and Middle Eastern surgical markets.
Cardiopulmonary bypass accessory equipment encompasses the disposable and capital components that constitute the extracorporeal circuit, including oxygenators with hollow-fiber polymethylpentene membranes, arterial filters, cardiotomy reservoirs, and roller or centrifugal pump heads designed to temporarily assume heart and lung function during open-chest procedures. The primary industrial purpose is maintaining systemic perfusion and gas exchange while the native circulation is arrested for cardiac surgery. Oxygenators and tubing sets capture the dominant share of product-type revenue due to their single-use nature and per-procedure consumption pattern. Membrane oxygenation technology leads the technology split as bubble oxygenation recedes on safety profiles, while coronary artery bypass grafting remains the largest application volume pool despite heart transplantation showing faster procedural growth in specialized centers.
FDA 510(k) clearance pathways and EU MDR conformity assessment govern market access for bypass circuits, with ISO 10993 biocompatibility testing serving as a baseline technical requirement across both jurisdictions. Japan's PMDA maintains distinct clinical data expectations for novel oxygenator materials that extend registration timelines relative to US and European pathways. Stakeholders must monitor evolving sterilization validation requirements and regional reimbursement adjustments for minimally invasive alternatives that could redirect procedural volumes.
Market Dynamics
Membrane oxygenation systems are displacing legacy bubble oxygenators across cardiac surgical centers, driven by superior gas exchange efficiency and reduced hemolysis risk during prolonged perfusion runs.
Growth Catalysts
- EU MDR biocompatibility mandates:Stricter ISO 10993 testing requirements for perfusion circuits are accelerating hospital upgrades to certified membrane oxygenator platforms.
- Coronary artery bypass grafting volume:Aging demographics in Germany and Japan are expanding the procedural base requiring extracorporeal circulation support.
- Hollow-fiber polymethylpentene membranes:These materials deliver extended durability for complex cardiac procedures, pulling adoption from academic medical centers into community hospital systems.
Market Restraints
- Silicone supply concentration:Hollow-fiber membrane production depends on specialized silicone feedstock with limited qualified suppliers in East Asia.
- Japan PMDA registration timelines:Novel oxygenator materials face extended clinical data requirements that delay commercial entry by 18-24 months versus FDA pathways.
- Minimally invasive cardiac surgery:Off-pump coronary artery bypass techniques reduce per-procedure consumption of disposable bypass circuits.
Strategic Opportunities
- Middle Eastern cardiac center expansion:Greenfield hospital construction in Saudi Arabia and the UAE is creating first-mover advantages for perfusion platform vendors.
- EU Green Deal procurement criteria:Lower-carbon manufacturing footprints are becoming weighted scoring factors in tender evaluations for cardiovascular devices.
- Centrifugal pump-membrane oxygenator integration:Converged single-unit designs reduce priming volume and hemodilution risk, opening premium positioning in pediatric cardiac surgery.
Industry Challenges
- Perfusionist workforce shortages:Specialized training programs in the United States and Europe are failing to match retirement rates, constraining procedural capacity expansion.
- Sterilization validation complexity:Transition from ethylene oxide to alternative methods requires extensive bioburden testing that extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiopulmonary Bypass Accessory Equipment Market |
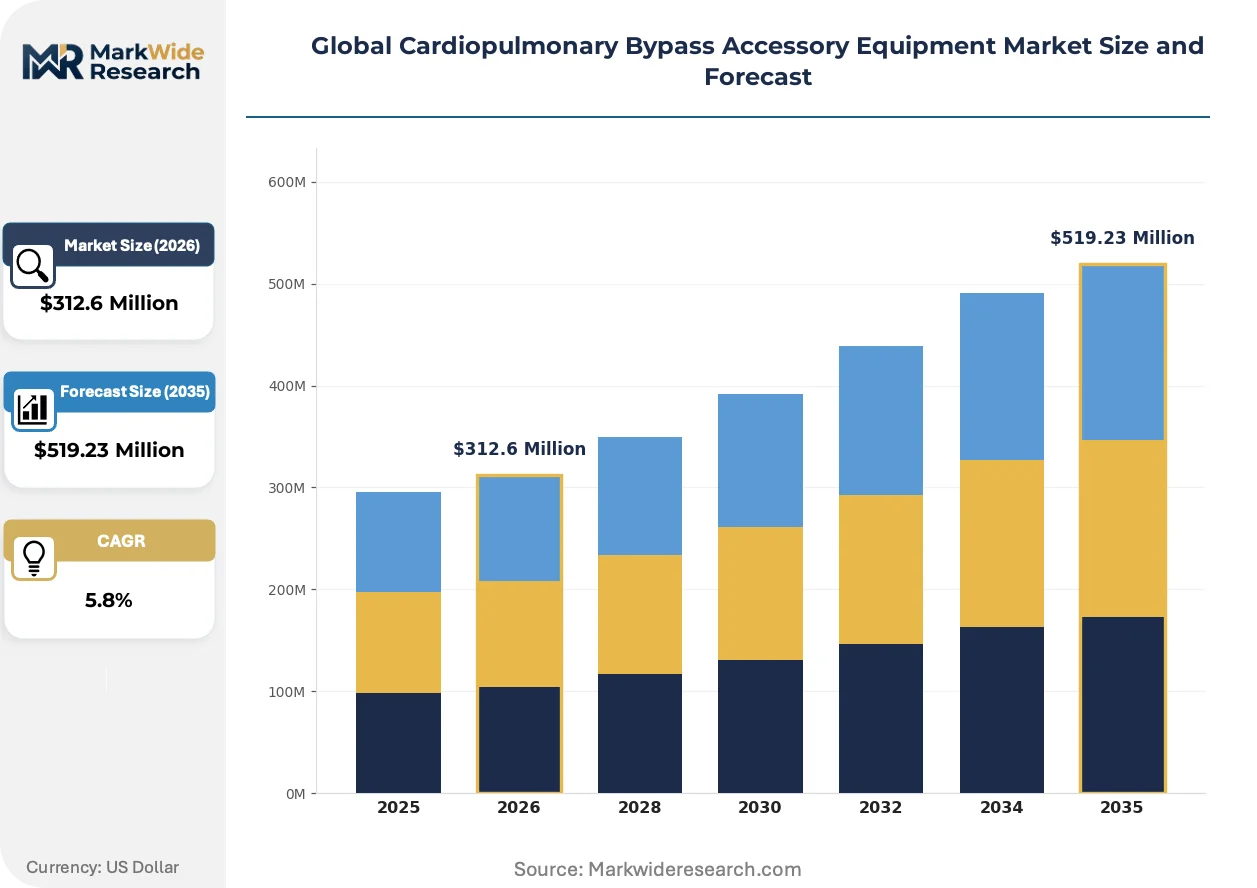
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygenators, Cannulas, Tubing Sets, Reservoirs, Pumps Technology: Membrane Oxygenation, Bubble Oxygenation, Centrifugal Pump, Roller Pump Application: Coronary Artery Bypass, Valve Replacement, Aortic Surgery, Heart Transplantation End User: Cardiac Surgical Centers, Specialized Clinics, Research Laboratories, Educational Institutions |
| Companies Covered | Medtronic, Terumo Cardiovascular, LivaNova PLC, Getinge AB, Edwards Lifesciences, Braile Biomedica, MAQUET, Tianjin Medical, Sorin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiopulmonary Bypass Accessory Equipment Market Shifts & Advancements
Active innovation across materials science, regulatory science, and procurement mechanics is compressing product lifecycles and reshaping vendor-customer relationships in cardiovascular perfusion.
Polymethylpentene hollow-fiber membrane oxygenation is consolidating its position as the default technology for adult cardiac surgery. Academic medical centers in Germany and Japan have completed wholesale platform conversions, while United States community hospitals are now following at accelerated procurement cycles. This technology shift is consolidating purchasing power around integrated perfusion system vendors capable of delivering complete circuit compatibility.
EU MDR conformity assessment pathways are tightening clinical evidence requirements for novel oxygenator materials. Manufacturers must now submit extended biocompatibility profiles and post-market surveillance plans that exceed previous Medical Device Directive standards. European cardiac centers are responding by extending supplier qualification timelines and consolidating vendor relationships to reduce regulatory audit burden.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases. German and Japanese cardiac centers now separately negotiate preventive maintenance, disposable replenishment, and clinical training modules. This behavioral shift is most visible in multi-hospital systems seeking to standardize perfusion protocols while diversifying supplier risk across regional clusters.
Global Cardiopulmonary Bypass Accessory Equipment Market Segmentation
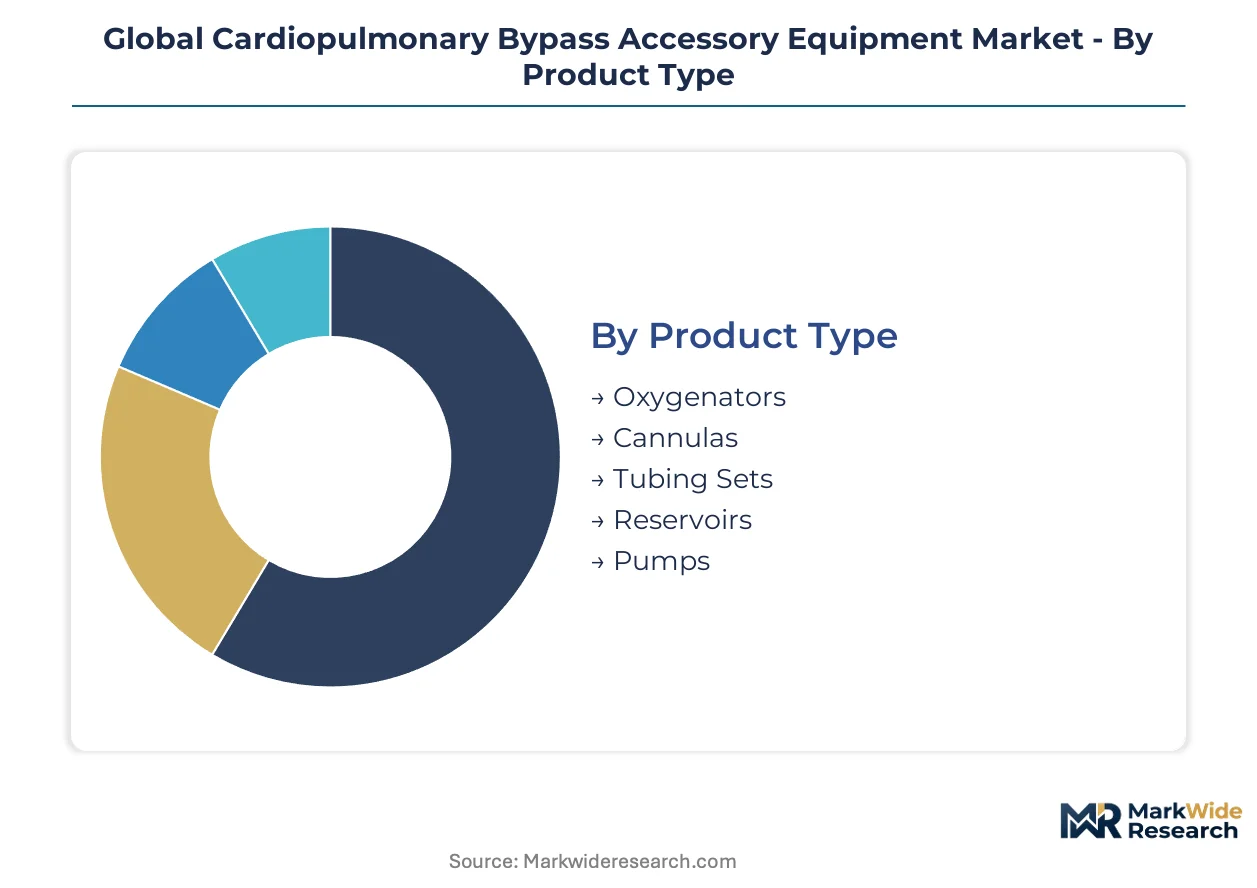
Segmentation in cardiopulmonary bypass accessory equipment reveals distinct procurement patterns across disposable versus capital equipment categories. Hospital purchasing committees weight per-procedure consumption rates differently from platform technology investments. Technology maturity and regulatory certification status further stratify vendor selection criteria.
Product Type:
Hospital procurement committees prioritize single-use disposables over capital equipment based on reimbursement alignment and inventory turnover economics.
- Oxygenators:Hollow-fiber polymethylpentene membrane devices dominate circuit configurations. German and Japanese cardiac centers drive specification upgrades toward integrated arterial filter designs that reduce priming volume.
- Tubing Sets:Biocompatible PVC and silicone configurations constitute the highest-volume disposable category. Community hospital systems in the United States standardize on pre-connected sterile packs to reduce perfusionist setup time.
- Cannulas:Arterial and venous access devices with reinforced walls prevent kinking during prolonged perfusion runs.
- Reservoirs:Hard-shell cardiotomy reservoirs with integrated filtration manage venous return and vent blood.
- Pumps:Disposable pump heads for roller and centrifugal platforms represent capital-sparing alternatives to complete console replacement.
Oxygenators lead on scale; pump heads gain share fastest through modular upgrade cycles.
Technology:
Technology selection tracks directly to procedural duration and patient acuity profiles across cardiac surgical programs.
- Membrane Oxygenation:Polymethylpentene hollow-fiber systems deliver superior gas exchange with reduced hemolysis risk. Academic medical centers in Germany completed platform conversions first, with United States community hospitals now accelerating adoption.
- Centrifugal Pump:Magnetic levitation and mechanical bearing designs reduce shear stress on blood elements. Pediatric cardiac programs specify these platforms for extended perfusion support during complex repairs.
- Bubble Oxygenation:Legacy systems persist in cost-constrained settings despite higher gaseous microemboli risk profiles.
- Roller Pump:Occlusive roller head mechanisms retain position in low-cost circuit configurations and educational training environments.
Membrane oxygenation leads on scale; centrifugal pump integration climbs fastest through pediatric specialization.
Application:
Procedure volume distribution concentrates procurement planning around coronary revascularization platforms.
- Coronary Artery Bypass:Multivessel grafting procedures constitute the foundational demand pool for extracorporeal circulation. Aging demographics in Japan and Germany expand the addressable patient base requiring on-pump techniques.
- Heart Transplantation:Orthotopic procedures require extended perfusion support with advanced oxygenator durability. Specialized centers in the United States and Germany drive specification toward integrated centrifugal pump-membrane oxygenator units.
- Valve Replacement:Aortic and mitral procedures utilize modified circuit configurations with left ventricular venting.
- Aortic Surgery:Arch and root repairs demand selective cerebral perfusion capabilities and temperature management.
Coronary artery bypass leads on scale; heart transplantation expands most quickly through center specialization.
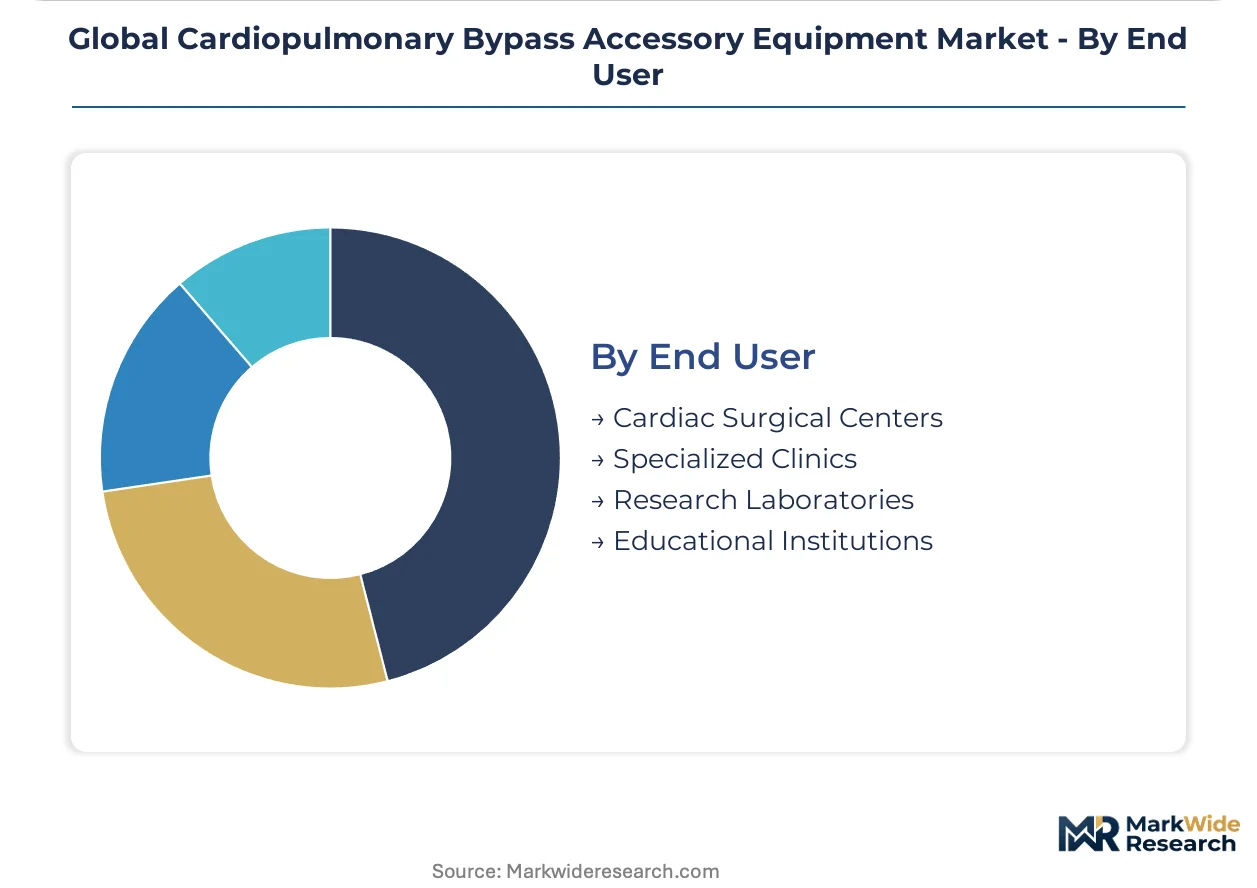
End User:
Customer type determines service contract structures and clinical training bundling in vendor negotiations.
- Cardiac Surgical Centers:High-volume hospitals perform the majority of on-pump procedures annually. Multi-hospital systems in Germany and the United States consolidate purchasing power through standardized perfusion protocols.
- Specialized Clinics:Focused cardiac surgery units concentrate on specific procedure types. These facilities in Japan prioritize compact, integrated perfusion platforms with reduced footprint requirements.
- Research Laboratories:Preclinical and hemocompatibility testing facilities require specialized circuit configurations.
- Educational Institutions:Perfusion training programs specify durable, reusable components for student instruction.
Cardiac surgical centers lead on scale; specialized clinics gain share fastest through ambulatory surgery expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiopulmonary bypass technology originated in the United States during the 1950s, with the first successful open-heart procedures establishing the country as the foundational market for perfusion equipment development and clinical adoption.
United States
Aging demographics and expanding coronary revascularization volumes drive hospital procurement of membrane oxygenator platforms. FDA 510(k) clearance pathways govern market entry for novel perfusion circuits, with ISO 10993 biocompatibility testing serving as baseline technical requirements. The Cleveland Clinic and Mayo Clinic anchor specialized cardiac surgical clusters in Ohio and Minnesota, respectively, where academic medical centers pilot integrated centrifugal pump-oxygenator systems.
Germany
Multi-vessel coronary artery bypass grafting procedures constitute the dominant demand pool for extracorporeal circulation equipment. EU MDR conformity assessment pathways tighten clinical evidence requirements for novel oxygenator materials, extending supplier qualification timelines. The Rhine-Ruhr metropolitan region concentrates cardiac surgical capacity, with university hospitals in Essen and Düsseldorf completing wholesale platform conversions to polymethylpentene membrane systems.
Japan
Heart transplantation volume expansion and specialized pediatric cardiac surgery programs generate procurement demand for extended-duration perfusion support. PMDA maintains distinct clinical data expectations for novel oxygenator materials that extend registration timelines relative to FDA pathways. The Keihanshin corridor linking Osaka, Kyoto, and Kobe hosts concentrated academic medical center capacity where membrane oxygenation adoption rates exceed national averages.
Saudi Arabia
Greenfield hospital construction and cardiac center expansion create first-mover advantages for perfusion platform vendors entering Middle Eastern markets. SFDA registration requirements align with international standards while permitting accelerated review for devices with prior FDA or CE marking. Riyadh and Jeddah anchor the kingdom's surgical infrastructure buildout, with Saudi German Hospital and King Faisal Specialist Hospital driving specification standards for integrated perfusion systems.
Brazil
Public health system procurement through SUS (Sistema Único de Saúde) channels concentrates demand for cost-optimized perfusion circuit configurations. ANVISA regulatory pathways require in-country testing for novel materials, though established oxygenator platforms with prior international certification receive expedited review. São Paulo's Instituto do Coração and Hospital das Clínicas anchor the southeastern surgical cluster where private hospital groups increasingly specify membrane oxygenation technology.
Global Cardiopulmonary Bypass Accessory Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with integrated perfusion platform vendors commanding pricing power over component specialists. The vendor base stratifies into three tiers: multinational cardiovascular device conglomerates with full-platform capabilities; regional specialists concentrating on single-product categories; and emerging market fabricators competing on disposable cost positioning. Dominant competitive moves include backward integration into hollow-fiber membrane production and strategic partnerships with academic medical centers for clinical validation studies.
Within the multinational tier, Medtronic and Terumo Cardiovascular occupy positions as archetypal integrated platform vendors, while LivaNova PLC exemplifies geographic specialization strategies. Medtronic leverages its Dublin-based corporate structure and Minnesota operational roots to anchor North American and European cardiac center relationships. Terumo Cardiovascular represents Japanese precision manufacturing heritage in cardiovascular perfusion technology. LivaNova PLC, formed through merger activity with historical roots in European cardiac surgery equipment, concentrates competitive positioning across Latin American and Middle Eastern surgical markets where its platform standardization protocols have achieved clinical adoption.
| Leading Market Players |
|---|
| Medtronic |
| Terumo Cardiovascular |
| LivaNova PLC |
| Getinge AB |
| Edwards Lifesciences |
| Braile Biomedica |
| MAQUET |
| Tianjin Medical |
| Sorin |
| Others |
Supply & Pricing Matrix
Silicone feedstock pricing indices cascade through hollow-fiber membrane production costs, stratifying final equipment tiers across German, Japanese, and United States cardiac centers. Procurement committees weight polymethylpentene membrane specifications against biocompatibility certification tiers, with EU MDR compliance premiums widening spreads between certified and legacy platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs membrane oxygenator procurement, with ISO 10993 biocompatibility certification and integrated arterial filter designs commanding tier-one positioning. Price differentiation stems from hollow-fiber membrane durability ratings and after-sales service bundling depth. Cost compression in economy tiers intensifies as Brazilian and Saudi public hospital systems consolidate volume tenders. Community hospital systems in the United States exhibit highest price sensitivity; specialized pediatric cardiac centers in Japan demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States operate hub-and-spoke patterns to serve cardiac surgical clusters with temperature-controlled sterile packaging. Hollow-fiber membrane production draws from specialized silicone and polymethylpentene resin feedstocks concentrated in East Asian chemical processing hubs. Single-source vulnerability in qualified silicone suppliers creates procurement risk during geopolitical disruptions. Distribution runs through hospital GPO contracts and direct manufacturer agreements with multi-hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
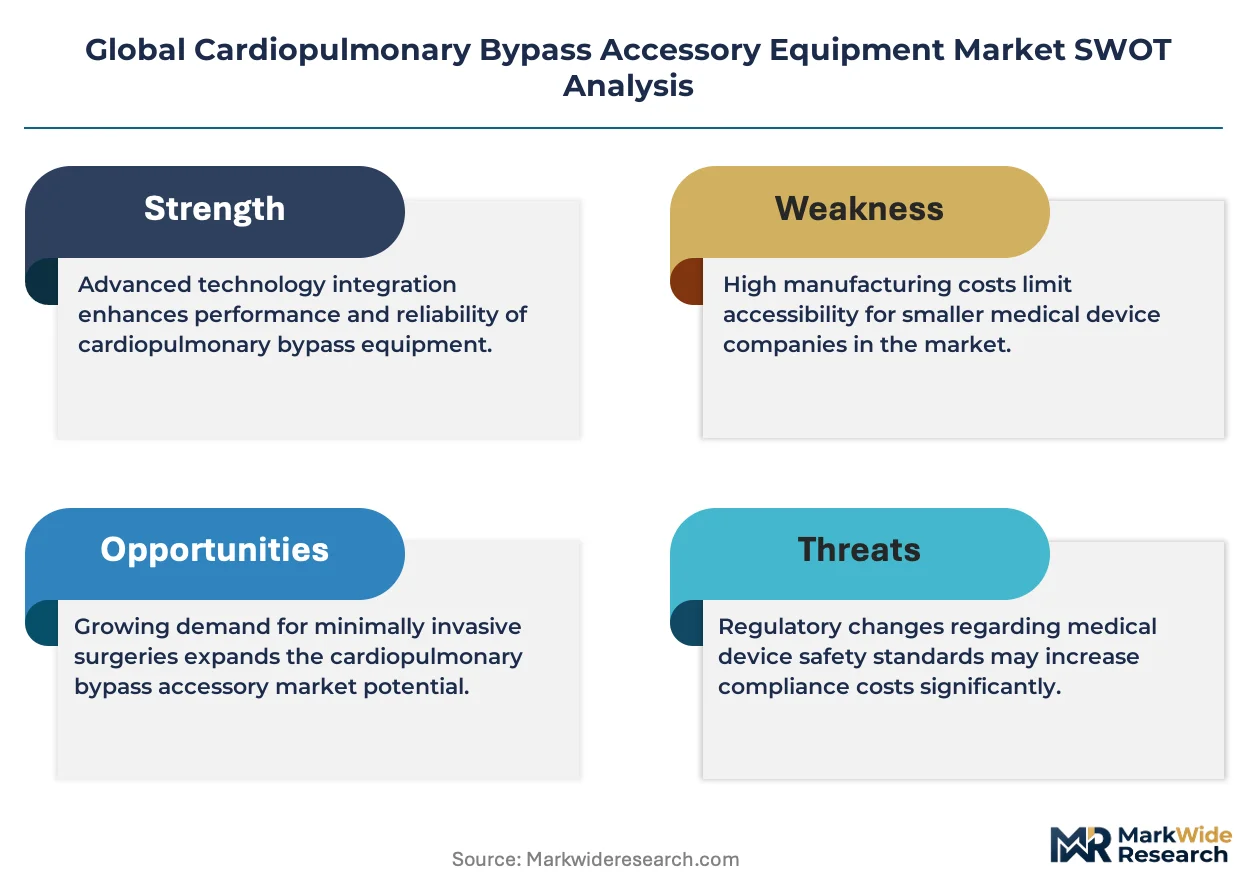
The Global Cardiopulmonary Bypass Accessory Equipment Market compounds steadily as aging demographics in Germany and Japan expand coronary revascularization volumes requiring extracorporeal circulation support.
For Market Incumbents: Acquire hollow-fiber membrane production capabilities to secure supply continuity against East Asian feedstock concentration. Consolidate vendor relationships with German multi-hospital systems facing EU MDR audit burden. Backward integration into polymethylpentene resin sourcing mitigates silicone supply disruption threats from limited qualified suppliers. For New Entrants and Emerging Players: Centrifugal pump-membrane oxygenator convergence technology offers entry wedge into pediatric cardiac surgery segments underserved by integrated platform incumbents. Target Saudi Arabian and UAE greenfield cardiac centers where first-mover advantages remain available for perfusion platform vendors. Pursue hospital system partnerships emphasizing compact footprint designs for ambulatory surgery expansion. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing CE-marked membrane oxygenator platforms and established Middle Eastern distribution. Five-to-ten year viability hinges on EU MDR certification maintenance and pediatric specialization depth. Monitor Japan PMDA registration timeline compression as signal for novel materials market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | CE marking pathways for novel oxygenator materials unlock German and French hospital procurement access. |
| Backward Integration into Membrane Production | In-house polymethylpentene hollow-fiber manufacturing reduces silicone feedstock dependency concentration risk. |
| Pediatric Platform Specialization | Centrifugal pump-oxygenator integration targets complex congenital repair procedures in academic medical centers. |
| Middle Eastern Distribution Partnership | Saudi SFDA registration alignment with prior FDA clearance accelerates Riyadh and Jeddah hospital penetration. |
| Service Contract Unbundling | Separate preventive maintenance and clinical training modules respond to German multi-hospital system procurement preferences. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining perfusionist interviews, hospital purchasing committee discussions, and biomedical engineering director consultations with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, Japan PMDA submission records, and hospital procurement database extracts. Bottom-up procedure volume modeling and top-down equipment expenditure triangulation anchored market size estimation.
Segment-weighted forecasting applied product type, technology, application, and end user dimensions across the projection horizon, with coronary artery bypass grafting volume trajectories and heart transplantation center expansion rates informing oxygenator demand curves. CAGRs derived from procedure growth elasticities and per-procedure disposable consumption patterns, incorporating EU MDR transition timelines and Japan PMDA registration lag effects.
The model holds under stable regulatory transition schedules; deviation in EU MDR audit backlogs or silicone supply disruptions would shift equipment availability timelines. Forecasts reflect documented assumptions around procedural volume continuity and reimbursement stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Stimulation Therapies Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Rigid Laparoscope Market
Medical Devices
North America Pen Needles Market
Medical Devices
Smart Medical Loupes Market