
 Japan Artificial Organs and Bionic Implants Market | 2026-2036
Japan Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Artificial Organs and Bionic Implants Market Foresight
Project finance and leasing arrangements for high-value implant systems is tilting competitive dynamics toward firms with balance-sheet depth. Medtronic leverages its hospital partnership networks to secure long-term service contracts. Baxter International sustains R&D intensity across artificial kidney platforms. Cochlear Limited anchors its Japan position through direct-to-clinic technical training programs.
Artificial organs and bionic implants comprise electromechanical and biological substitutes designed to replace or augment native physiological functions, typically incorporating biocompatible alloys, polymers, or living tissue constructs manufactured under ISO 13485 quality management protocols. These devices restore sensory, motor, or organ-level performance in patients with irreversible tissue damage or congenital deficits. Cochlear implants and bionic limbs command concentrated margin pools due to customization requirements and follow-up service dependencies. Heart valves and artificial kidneys face stiffer reimbursement negotiation but benefit from recurring replacement cycles. Hospitals dominate end-user procurement volumes, though rehabilitation centers are gaining traction for post-implant functional training.
PMDA enforces stringent clinical evidence standards under Japan's Pharmaceutical and Medical Device Act, extending trial timelines but elevating product credibility upon approval. METI coordinates industrial policy for advanced medical device manufacturing, while JIS standards govern material biocompatibility testing protocols. Stakeholders must monitor PMDA's evolving regenerative medicine framework and METI's next-phase subsidy allocations to anticipate which technology categories will receive accelerated regulatory pathways.
Market Dynamics
Japan's artificial organs and bionic implants market is undergoing structural compression as PMDA's regenerative medicine framework accelerates approval timelines for tissue-engineered products while traditional electromechanical device pathways remain elongated. This bifurcation is reallocating R&D capital toward biological substitutes and reshaping competitive entry barriers.
Growth Catalysts
- METI Biomaterial Subsidies:The Ministry of Economy, Trade and Industry's targeted funding for domestic collagen scaffold and cell-sheet manufacturing is lowering capital barriers for university spinouts entering cardiac patch and corneal implant commercialization.
- Tokyo Metropolitan Hospital Clusters:Concentrated procurement authority across Keio University Hospital, St. Luke's International, and Tokyo Medical and Dental University is creating anchor demand for next-generation cochlear and neurostimulation platforms.
- Osaka Manufacturing Corridor:Proximity of Tanabe Seiyaku, Nipro, and Terumo production facilities to Kansai International Airport enables just-in-time biomaterial supply chains for time-sensitive organ transport logistics.
Market Restraints
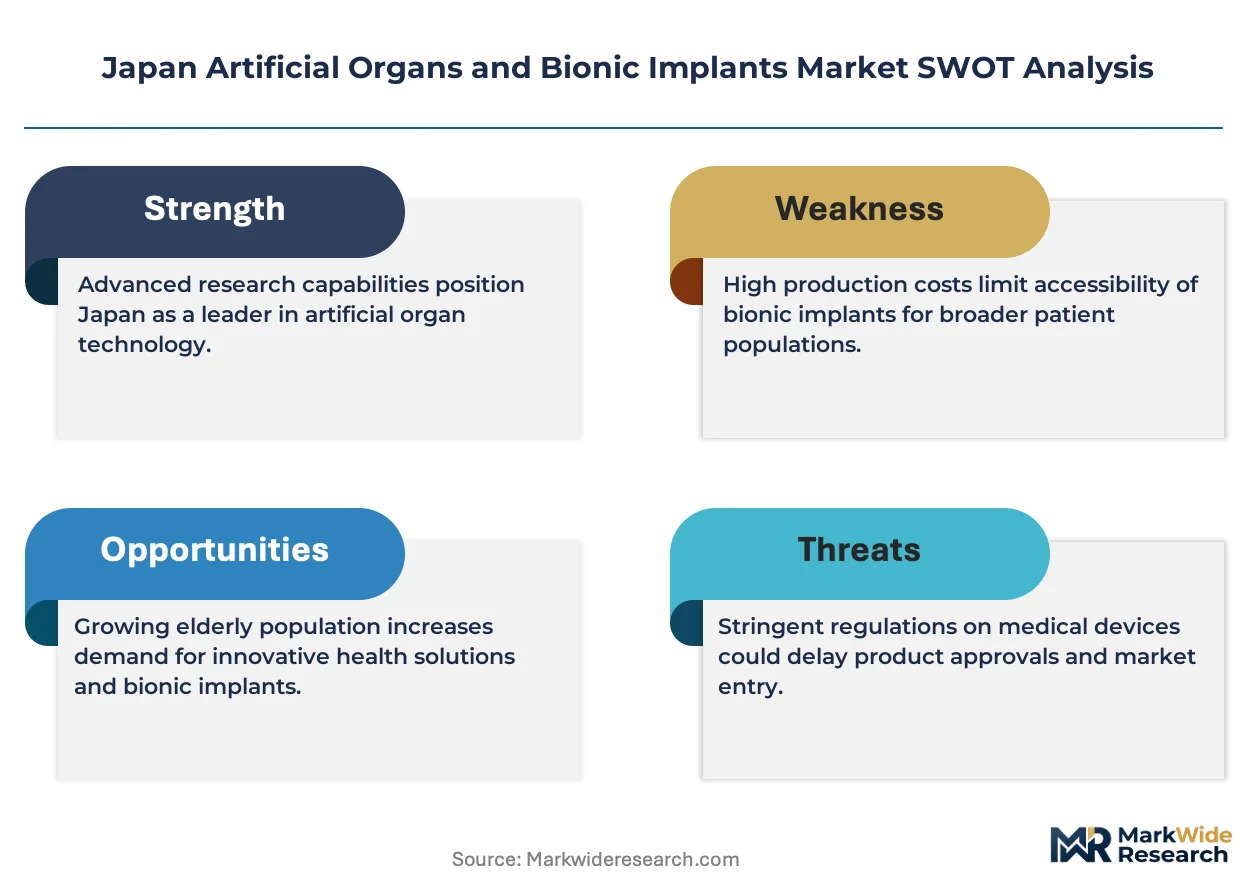
- PMDA Clinical Evidence Burden:The Pharmaceuticals and Medical Devices Agency's requirement for Japanese patient cohort data in regenerative medicine trials extends development timelines by 18-24 months compared to FDA breakthrough pathways.
- Titanium Alloy Supply Concentration:Domestic dependence on imported medical-grade titanium sponge from Russian and Chinese smelters exposes manufacturers to input cost volatility and geopolitical supply interruptions.
- Biological Scaffold Degradation:Variable resorption rates in porcine-derived extracellular matrix implants create revision surgery risks that limit initial adoption in orthopedic load-bearing applications.
Strategic Opportunities
- Fukuoka Regenerative Medicine Zone:Designated special economic zone status offers streamlined PMDA consultations and tax incentives for foreign firms establishing cell processing centers targeting Asian export markets.
- Home Hemodialysis Convergence:Integration of wearable artificial kidney prototypes with remote patient monitoring platforms opens reimbursement pathways outside traditional hospital-based dialysis centers.
- JIS Biocompatibility Fast-Track:Revised Japanese Industrial Standards for ISO 10993-18 chemical characterization enable parallel submission with PMDA, compressing total time-to-market for polymer-based neural interfaces.
Industry Challenges
- Cell Processing Engineer Scarcity:Limited training programs for GMP-compliant cell culture technicians at Japanese universities creates hiring bottlenecks for autologous tissue engineering scale-up.
- Multi-Site PMDA Inspection Coordination:Synchronized audits across overseas contract manufacturing organizations and domestic final assembly facilities demand specialized regulatory affairs staffing that mid-cap firms struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Artificial Organs and Bionic Implants Market |
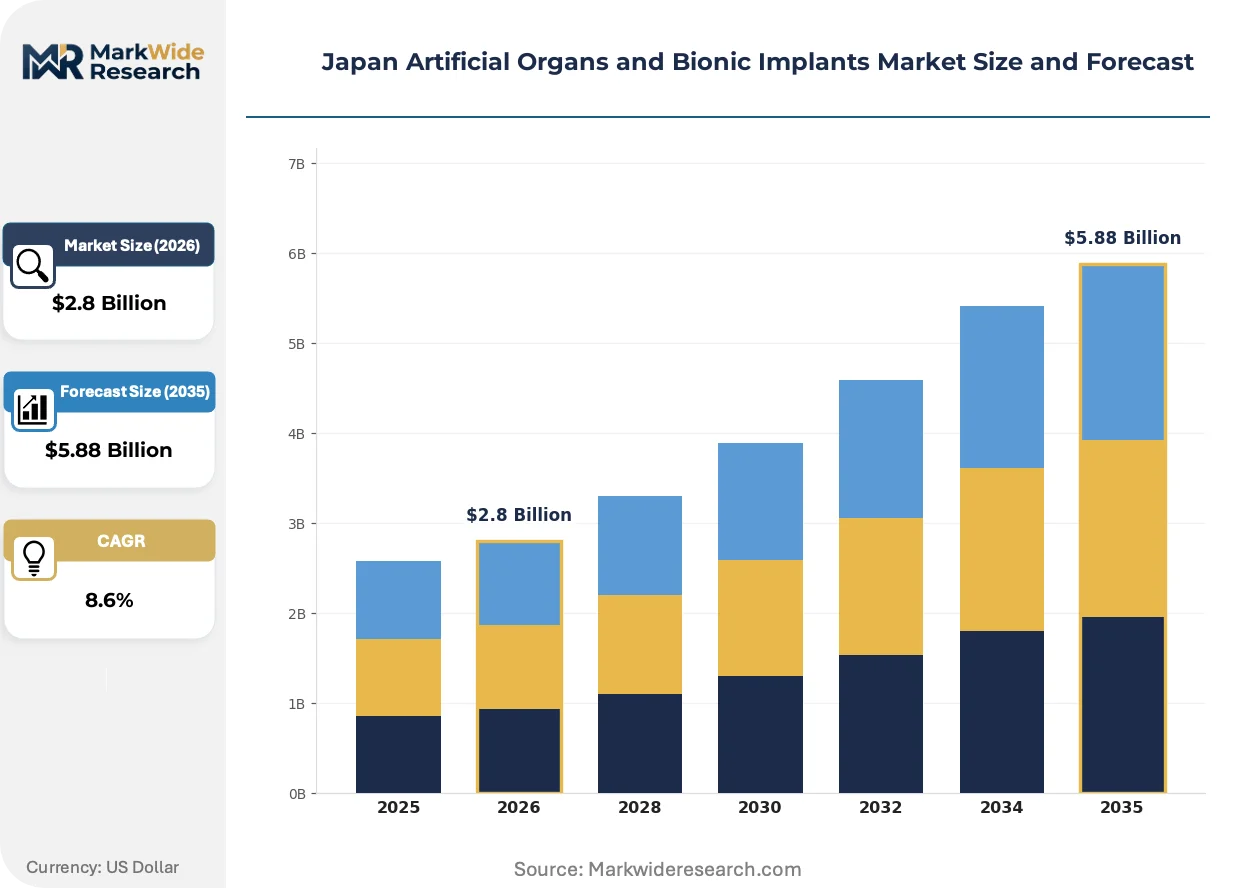
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Valves, Artificial Kidneys, Cochlear Implants, Bionic Limbs End User: Hospitals, Rehabilitation Centers, Specialty Clinics, Research Institutes Technology: 3D Bioprinting, Biomaterials, Neuromorphic Systems, Minimally Invasive Application: Cardiovascular, Neurological, Orthopedic, Dental |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abiomed, Cochlear Limited, Össur hf, Baxter International, Berlin Heart GmbH, Abbott Laboratories, Zimmer Biomet Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Artificial Organs and Bionic Implants Market Shifts & Advancements
Biological tissue engineering is displacing electromechanical dominance across sensory restoration applications, while regulatory sandboxes and procurement centralization are compressing traditional commercialization timelines. Three converging developments are restructuring competitive positioning.
Decellularized porcine heart valves with autologous endothelial seeding are collapsing the historical tradeoff between mechanical durability and biological compatibility that has segmented the valve replacement market for decades. Osaka-based cardiac surgery departments at National Cerebral and Cardiovascular Center are piloting these constructs in intermediate-age patients previously excluded from tissue valve eligibility. The technology is collapsing the addressable patient pool for traditional mechanical valves into niche anticoagulation-intolerant segments.
METI's 2024 revision to the Act on Securing Quality, Efficacy and Safety of Pharmaceuticals and Medical Devices introduced conditional early approval pathways for combination products incorporating living cells and synthetic scaffolds. Device manufacturers must now submit real-world evidence protocols alongside premarket applications, shifting post-market surveillance from passive reporting to active data collection infrastructure. Cardiac patch and tracheal implant categories are responding by embedding Bluetooth-enabled pressure sensors to automate outcome documentation.
Hospital procurement consortia in the Kanto region are consolidating implant purchasing authority through shared service organizations that negotiate system-wide pricing for cochlear and limb prosthetic platforms. Device vendors must now staff dedicated account teams for consolidated buyers rather than individual hospital relationship managers. This concentration is most visible in Yokohama City University Medical Center's lead role in negotiating multi-year bionic limb service contracts covering 14 affiliated institutions.
Japan Artificial Organs and Bionic Implants Market Segmentation
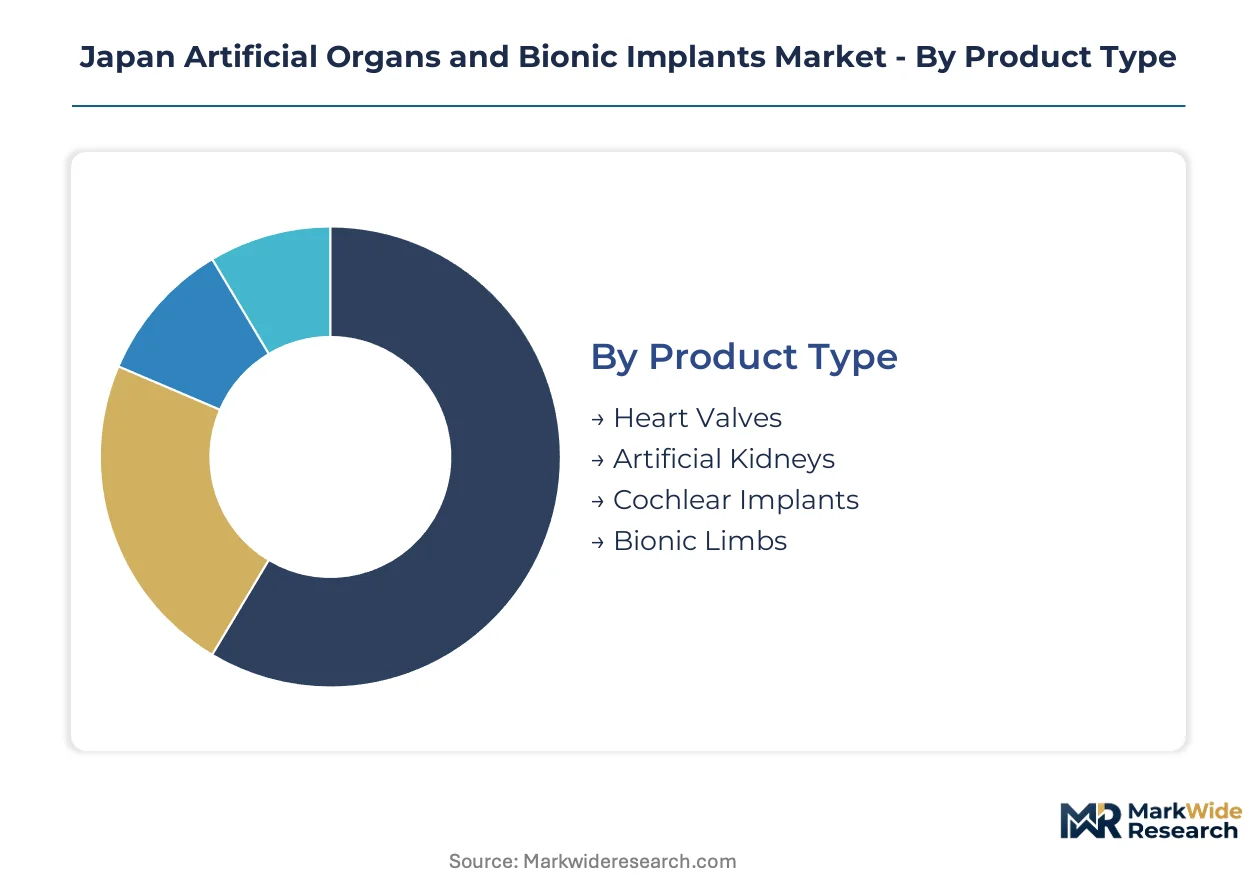
Segmentation reveals how procurement authority and reimbursement pathways fragment across Japan's artificial organs and bionic implants landscape. Product categories diverge sharply in margin structure and regulatory intensity, while end-user concentration determines vendor go-to-market economics.
Product Type:
The use-case spectrum spans acute surgical intervention through chronic disease management and sensory restoration.
- Cochlear Implants:Electromechanical devices converting sound to neural signals through electrode arrays threaded into the cochlea. Tokyo metropolitan hospital clusters anchor procurement volumes for pediatric congenital cases and age-related sensorineural loss, with PMDA's streamlined neurological device pathway compressing approval timelines relative to cardiac categories.
- Bionic Limbs:Myoelectric and osseointegrated prostheses restoring motor function through EMG signal interpretation or direct skeletal attachment. Osaka's manufacturing corridor supplies titanium alloy components for Kansai rehabilitation networks, though socket fit customization creates recurring service revenue streams that sustain specialist orthotics firms.
- Heart Valves:Mechanical and biological substitutes replacing diseased native valves, with tissue-engineered constructs gaining conditional approval under METI's regenerative medicine framework.
- Artificial Kidneys:Hemodialysis membranes and wearable filtration systems addressing end-stage renal disease, concentrated in hospital-based dialysis centers with emerging home therapy pilots.
Established volume favors heart valves; emerging adoption favors bionic limbs.
End User:
Customer concentration shapes pricing power and service bundling requirements across the procurement landscape.
- Hospitals:Academic medical centers and metropolitan general hospitals dominate high-value implant procurement through centralized purchasing committees. Keio University Hospital and St. Luke's International negotiate multi-year service contracts covering device implantation, programming, and revision protocols.
- Rehabilitation Centers:Post-acute facilities specializing in functional training for limb prosthesis and cochlear implant recipients. Yokohama City University Medical Center's consortium model aggregates demand across 14 affiliated institutions, forcing vendors to staff dedicated account teams.
- Specialty Clinics:Focused ENT and orthopedic practices handling initial screening and device candidacy assessment.
- Research Institutes:National Cerebral and Cardiovascular Center and RIKEN biodesign labs piloting next-generation tissue-engineered constructs under PMDA exploratory trial frameworks.
Procurement authority concentrates in hospitals; patient touchpoint expansion favors rehabilitation centers.
Technology:
Manufacturing methodology determines regulatory pathway length and capital intensity for market entry.
- Biomaterials:Collagen scaffolds, decellularized extracellular matrices, and synthetic polymers forming the structural substrate for tissue-engineered organs. METI subsidies for domestic collagen manufacturing lower barriers for university spinouts entering cardiac patch commercialization.
- 3D Bioprinting:Layer-by-layer fabrication of living tissue constructs combining cells, growth factors, and hydrogels. Fukuoka Regenerative Medicine Zone offers tax incentives for foreign firms establishing cell processing centers targeting Asian export markets.
- Neuromorphic Systems:Brain-inspired computing architectures enabling adaptive signal processing in neural interfaces and sensory prostheses.
- Minimally Invasive:Transcatheter delivery systems and laparoscopic implantation techniques reducing surgical trauma and recovery timelines.
Regulatory maturity favors biomaterials; steepest expansion trajectory favors 3D bioprinting.
Application:
Clinical indication determines reimbursement tier and patient eligibility criteria across Japan's universal health coverage system.
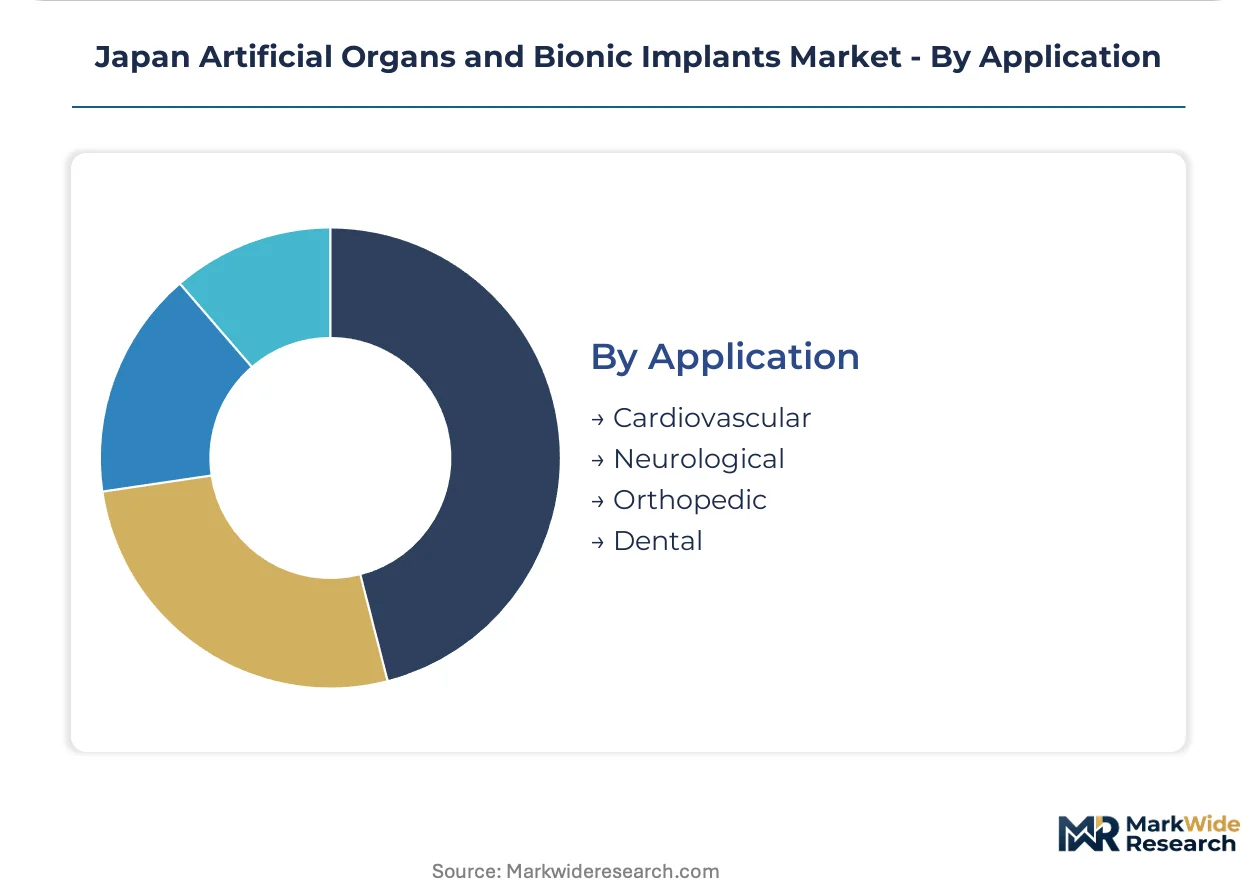
- Cardiovascular:Heart valves, cardiac patches, and vascular grafts addressing ischemic and structural disease. National Cerebral and Cardiovascular Center pilots decellularized porcine valves with autologous endothelial seeding for intermediate-age patients previously excluded from tissue valve eligibility.
- Neurological:Cochlear implants, deep brain stimulators, and neural interfaces restoring sensory and motor function. PMDA's neurological device pathway offers faster approval than regenerative medicine frameworks, concentrating vendor R&D investment.
- Orthopedic:Joint replacements, spinal implants, and limb prostheses addressing trauma and degenerative conditions.
- Dental:Osseointegrated implants and maxillofacial reconstruction prostheses.
Reimbursement stability favors cardiovascular; technology disruption favors neurological.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's regenerative medicine subsidies and PMDA's conditional approval pathways are redistributing manufacturing investment across Japan's major economic zones. Hospital procurement centralization in metropolitan clusters is amplifying regional concentration effects.
Kanto/Tokyo
Tokyo's metropolitan hospital clusters anchor national demand for cochlear implants and neurostimulation platforms. Keio University Hospital and St. Luke's International negotiate multi-year service contracts covering device implantation through revision protocols. The National Center for Child Health and Development concentrates pediatric congenital cases requiring specialized surgical coordination.
Kansai/Osaka
Osaka's manufacturing corridor supplies titanium alloy components and biomaterial substrates to domestic and export markets. Tanabe Seiyaku, Nipro, and Terumo production facilities leverage proximity to Kansai International Airport for time-sensitive organ transport logistics. Osaka University Hospital pilots decellularized cardiac constructs under PMDA exploratory frameworks.
Kyushu
Fukuoka's designated Regenerative Medicine Zone offers streamlined PMDA consultations and tax incentives for cell processing centers. Foreign firms establish GMP-compliant facilities targeting Asian export markets. Kyushu University Hospital anchors clinical trial networks for autologous tissue engineering applications.
Chubu/Nagoya
Nagoya's medical device manufacturing base specializes in precision-machined components for cardiac and orthopedic implants. Toyota Memorial Hospital and Nagoya University Hospital coordinate procurement for central Japan's aging population. Regional suppliers feed into Osaka and Tokyo final assembly operations.
Hokkaido
Hokkaido University Hospital and Sapporo Medical University manage dispersed rural demand through telemedicine-linked implant programming services. Cold-chain logistics infrastructure supports biologics transport from Honshu manufacturing centers. Limited local production concentrates on rehabilitation device distribution.
Japan Artificial Organs and Bionic Implants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. Hospital partnership networks and long-term service contracts determine market access more than device specifications alone. The vendor base stratifies into three archetypes: diversified multinationals with balance-sheet depth for project finance, mid-cap specialists with concentrated orthopedic or auditory portfolios, and university spinouts commercializing tissue-engineered constructs. Dominant competitive moves include securing multi-year hospital service contracts and embedding remote monitoring capabilities to lock in recurring revenue streams.
Among diversified multinationals, Medtronic and Boston Scientific occupy positions spanning cardiac rhythm management through structural heart interventions. Cochlear Limited anchors the auditory restoration segment through direct-to-clinic technical training infrastructure. Baxter International exemplifies the renal replacement archetype with sustained R&D allocation across dialysis platforms. These entities represent the channel-control tier where procurement consolidation favors established service relationships over novel device introductions.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abiomed |
| Cochlear Limited |
| Össur hf |
| Baxter International |
| Berlin Heart GmbH |
| Abbott Laboratories |
| Zimmer Biomet Holdings |
| Others |
Supply & Pricing Matrix
Titanium alloy import dependency from Russian and Chinese smelters compresses margin structures across electromechanical implant tiers while simultaneously forcing procurement diversification into Southeast Asian secondary suppliers. This single-source vulnerability widens price spreads between PMDA-certified premium devices and unvalidated economy alternatives, reshaping inventory holding patterns at Osaka manufacturing facilities.
Pricing Analysis
Certification level under JIS T 0301 and ISO 10993-18 creates the primary spread between premium regenerative constructs and standard electromechanical devices. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and real-world evidence commitments mandated by METI's conditional approval framework. Cost compression in standard-tier bionic limbs is intensifying because rehabilitation center consortia aggregate procurement volumes across Kanto hospital networks. Academic medical centers demonstrate least price sensitivity due to research funding offsets, while rural Hokkaido clinics face acute budget constraints.
Supply Chain Analysis
Geopolitical exposure in medical-grade titanium sponge imports from Russia and China dominates supply risk calculations for Osaka-based manufacturers. Domestic production draws from Australian rutile sand and Malaysian zirconium feedstock, with Terumo and Nipro facilities anchoring final assembly. Single-source vulnerability in porcine-derived extracellular matrix from domestic SPF farms threatens biological scaffold continuity. Distribution runs through just-in-time cold chains from Kansai International Airport to Tokyo metropolitan hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization across hospital consortia fragments vendor access, creating specialized service niches for firms with cell processing expertise and remote monitoring capabilities.
For Market Incumbents: Entrench market position through backward integration into titanium alloy recycling and captive collagen scaffold production. Secure multi-year service contracts with Yokohama City University Medical Center's 14-institution consortium before tissue-engineered substitutes gain full PMDA reimbursement codes. Priority investment in GMP-compliant cell culture training programs addresses engineer scarcity bottlenecks. For New Entrants and Emerging Players: Build out Fukuoka Regenerative Medicine Zone facilities to capture streamlined PMDA consultation pathways and Asian export tax incentives. Home hemodialysis convergence offers the most penetrable white space, with wearable artificial kidney prototypes enabling reimbursement outside hospital-based dialysis centers. Direct-to-clinic technical training partnerships bypass consolidated procurement gatekeepers. For Investors and Strategic Acquirers: PMDA's evolving regenerative medicine framework reshapes the acquisition landscape toward cell-sheet manufacturing capabilities and real-world evidence infrastructure. Long-term viability centers on platforms combining biological scaffolds with embedded sensor telemetry. Monitor METI subsidy allocation announcements as the signal for which technology categories will receive accelerated regulatory pathways.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Conditional Approval Pathway | METI's revised framework compresses timelines for tissue-engineered cardiac patches with autologous cell seeding. |
| Hospital System Partnership | Keio University Hospital's multi-year service contracts lock in cochlear implant programming and revision revenue streams. |
| Backward Integration into Biomaterials | Domestic collagen scaffold production reduces exposure to porcine-derived extracellular matrix supply interruptions. |
| Software Companion Development | Bluetooth-enabled pressure sensors in cardiac patches automate real-world evidence collection for PMDA compliance. |
| Reimbursement Strategy | Home hemodialysis reimbursement codes outside hospital centers unlock wearable artificial kidney market access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of PMDA approval databases, METI subsidy disclosure filings, and hospital procurement contract registries. Clinicians at National Cerebral and Cardiovascular Center, biomedical engineers at Terumo manufacturing facilities, GPO contracts managers at Tokyo metropolitan hospital clusters, and regulatory affairs specialists at university spinouts provided structured input. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across Japan's universal health coverage system.
Forecast inputs span product type segmentation across cochlear implants through artificial kidneys, technology tiers from biomaterials to 3D bioprinting, and end-user concentration from academic medical centers to rehabilitation consortia. CAGRs derive from regression analysis against aging demographic trajectories and PMDA approval velocity metrics across the projection horizon. Reimbursement pathway evolution and cell processing engineer supply constraints inform scenario weightings.
Stress conditions across titanium alloy import disruption, PMDA timeline extension, and METI subsidy reallocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regenerative medicine framework maturation and procurement consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Pipetting Systems Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Capnography Devices Market
Medical Devices
Mechanical Chest Compression System Market