
 Halogen Free Flame Retardant Bopet Films Market | 2026-2036
Halogen Free Flame Retardant Bopet Films Market Size, Share, and Industry Trends Forecast 2026-2036
Halogen Free Flame Retardant Bopet Films Market Intelligence
Direct-to-OEM sales channels for high-performance films are tilting towards integrated supply partnerships with automotive and electronics manufacturers. Toray Industries, Inc. leverages its material science expertise to offer customized solutions for electric vehicle battery packs. DuPont Teijin Films sustains a strong market position through its extensive global distribution network. SKC Co., Ltd. specializes in high-thickness films for industrial insulation applications, serving niche segments that require superior mechanical strength and thermal resistance.
Halogen-free flame retardant BOPET films are biaxially-oriented polyethylene terephthalate films engineered with non-halogenated additives, such as phosphorus or nitrogen-based compounds. These films provide excellent dielectric strength, thermal stability, and fire safety for components in sensitive electronic and electrical applications. The electronics end-use industry represents the largest source of demand, driven by electrical insulation requirements. Within the thickness segmentation, films below 75 microns are critical for flexible circuits, while thicker gauges serve structural purposes in automotive components.
Regulatory frameworks like the EU's RoHS and REACH directives strictly limit the use of halogenated compounds in electronic equipment, creating a mandatory market for these films. In parallel, China's GB standards for electronics and automotive parts impose similar fire safety and material composition requirements. Future material development will focus on enhancing thermal conductivity without compromising the film's flame retardancy or dielectric properties, a key challenge for material scientists.
Market Dynamics
The market's central dynamic is the mandatory substitution of materials driven by stringent safety regulations in the electronics and automotive industries. Directives like the EU's RoHS and China's GB standards are forcing a non-negotiable shift from halogenated flame retardants to safer alternatives.
Growth Catalysts
- Regulatory Mandates:The European Union's RoHS directive explicitly restricts hazardous substances in electrical and electronic equipment, creating a direct and enforceable demand for halogen-free film alternatives in components sold within the bloc.
- Electric Vehicle Expansion:The rapid scale-up of electric vehicle production, particularly in China, Germany, and the United States, requires high-performance insulation for battery packs and power electronics, a primary application for these films.
- Electronics Manufacturing Concentration:Demand is heavily concentrated in electronics production hubs across Asia, with South Korea and Taiwan serving as epicenters for advanced semiconductor and flexible circuit manufacturing that utilize thin-gauge flame retardant films.
Market Restraints
- Cost Premium:Phosphorus-based and other non-halogenated flame retardant additives are inherently more expensive than traditional brominated compounds, leading to higher final film costs that can deter adoption in price-sensitive applications.
- Performance Trade-offs:Incorporating high loadings of flame retardant additives can compromise the film's mechanical properties, such as tensile strength and flexibility, posing a significant material science challenge for manufacturers.
- Additive Supply Constraints:The supply chain for high-purity, specialized phosphorus compounds used in film production is concentrated among a few chemical manufacturers, creating potential bottlenecks and price volatility for film converters.
Strategic Opportunities
- Flexible and Wearable Electronics:The emergence of flexible displays, wearable medical sensors, and smart textiles presents a significant opportunity for ultra-thin, high-flexibility halogen-free BOPET films that provide fire safety without adding rigidity.
- Enhanced Thermal Conductivity:Developing films that combine flame retardancy with improved thermal conductivity is a key opportunity, addressing heat dissipation challenges in high-density power modules and 5G telecommunications equipment. *Bio-based PET Resins: The integration of bio-based polyethylene terephthalate resins into film production offers a pathway to improve the sustainability profile of these products, appealing to OEMs with corporate ESG targets.
Industry Challenges
- Complex Certification Pathways:Navigating and securing compliance with multiple, often diverging, international standards like the EU's REACH and China's GB standards for the same product creates significant administrative and testing burdens for suppliers.
- Maintaining Optical Clarity:The addition of flame retardant particles can negatively impact the optical properties of the BOPET film, creating haze or reducing transparency, which is a challenge for applications requiring visual inspection or light transmission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halogen Free Flame Retardant Bopet Films Market |
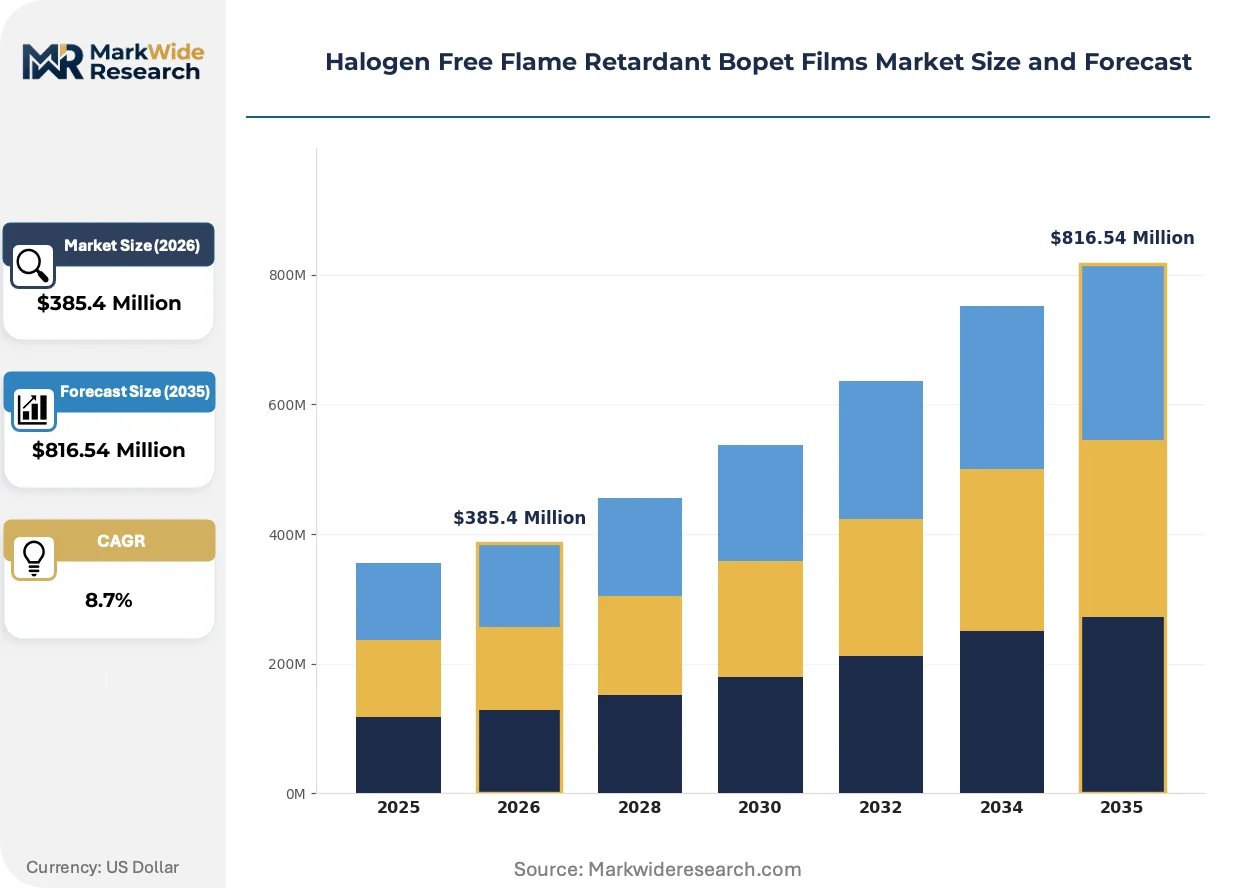
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Matte, Coated, Composite End Use Industry: Electronics, Automotive, Aerospace, Construction Application: Packaging, Insulation, Lamination, Electrical Thickness: 50 Micron, 75 Micron, 100 Micron, 125 Micron |
| Companies Covered | Toray Industries, Inc., DuPont Teijin Films, Mitsubishi Polyester Film, SKC Co., Ltd., Polyplex, Shanghai Huzheng Industrial Co., Ltd., Mainyang Prochema Commercial Co., Ltd., Teraoka Seisakusho Co., Ltd., Uflex Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halogen Free Flame Retardant Bopet Films Market Strategic Shifts & Innovations
Material science advancements are focused on creating multifunctional films that meet escalating performance requirements from high-density electronics and electric vehicles. This innovation is a direct response to a regulatory environment that continuously tightens safety and environmental standards across major economic blocs.
Phosphorus and nitrogen-based compounds provide the core flame-retardant functionality in modern BOPET films. Electronics OEMs are rapidly adopting these films for critical insulation in battery packs, flexible printed circuits, and wire insulation. The technology **is migrating from** serving a single purpose of fire safety to enabling multifunctional performance, where films also deliver superior dielectric strength and thermal management within a single layer.
China's national GB standards for electronic products and automotive parts are a powerful regulatory force shaping material specifications. These standards impose stringent fire safety and material composition requirements that directly favor halogen-free solutions over traditional alternatives. Consequently, any company manufacturing consumer electronics or EV components for the Chinese market must ensure their supply chain utilizes compliant films, directly impacting material selection for a vast portion of the electronics industry.
Direct-to-OEM co-development is displacing traditional, tiered distribution models for high-performance films. Instead of purchasing from a catalog, major automotive and electronics manufacturers in Japan and Germany are forming integrated partnerships with film producers to create customized solutions for specific applications like EV battery liners. This collaborative approach is most visible in advanced technology sectors where off-the-shelf products cannot meet unique thermal and mechanical specifications.
Halogen Free Flame Retardant Bopet Films Market Segmentation
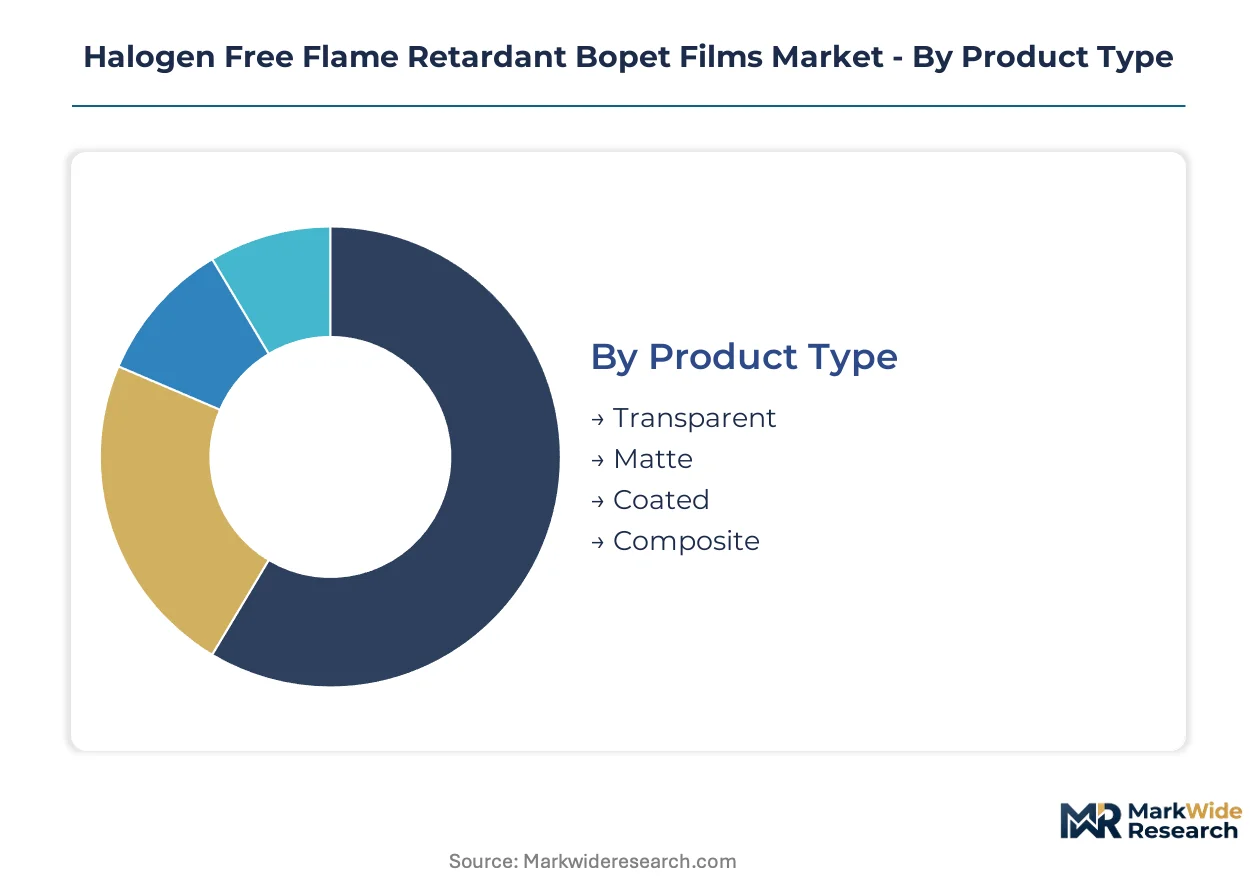
Market segmentation provides a granular understanding of demand drivers and technological specifications for halogen-free flame retardant BOPET films. Analyzing these distinct categories reveals how regulatory pressures and evolving end-use requirements shape product development and market concentration across various applications.
Product Type:
The product type dimension delineates the specific film characteristics and their functional enhancements for diverse industrial needs.
- Transparent:These films offer high optical clarity, essential for applications requiring visual inspection or light transmission, such as display components and certain flexible circuits. Demand concentrates in consumer electronics manufacturing hubs like South Korea, driven by stringent quality control standards.
- Matte:Matte films provide a non-glossy surface, reducing glare and improving printability, often used in labeling and specific packaging applications where aesthetics are important.
- Coated:Coated films feature additional layers for enhanced properties like barrier protection, adhesion, or improved print receptivity, expanding their utility in specialized electronic insulation and flexible packaging. Demand is accelerating in Germany for advanced automotive electronics, where customized performance layers are critical.
- Composite:Composite films combine multiple material layers to achieve synergistic properties, such as superior mechanical strength or advanced thermal management, serving high-performance industrial uses.
Transparent films command the established base. The steepest expansion runs through Coated films.
End Use Industry:
Demand patterns vary significantly across end-use industries, reflecting distinct safety requirements and performance standards for halogen-free BOPET films.
- Electronics:This industry represents the largest source of demand, primarily for electrical insulation in components like battery packs, flexible printed circuits, and wire insulation. Stringent regulations like the EU's RoHS directive in Europe and China's GB standards directly influence material selection in this segment.
- Automotive:Automotive applications utilize these films for insulation in electric vehicle battery packs, power electronics, and wiring harnesses, where thermal stability and fire safety are paramount. The rapid scale-up of EV production in China and the United States drives significant material specification.
- Aerospace:Aerospace applications require films with exceptional thermal stability and flame retardancy for critical insulation in aircraft wiring and interior components, adhering to rigorous safety certifications.
- Construction:The construction sector employs these films for insulation in building materials and specialized fire-resistant laminates, contributing to overall structural safety.
Electronics demand remains foundational, while Automotive applications are expanding most quickly.
Application:
Specific functional requirements define the application segments for halogen-free flame retardant BOPET films, ranging from protective barriers to critical electrical components.
- Packaging:Films in packaging applications offer protective barriers and fire safety for sensitive goods, particularly in electronics packaging.
- Insulation:Insulation applications leverage the dielectric strength and thermal stability of these films for electrical and thermal management in various devices. This segment is critical for battery packs in electric vehicles, where high-performance insulation prevents thermal runaway.
- Lamination:Lamination uses involve bonding films to other substrates to enhance fire retardancy, mechanical strength, or barrier properties in composite structures.
- Electrical:Electrical applications specifically utilize these films for components like flexible circuits, motor slot liners, and wire wraps, demanding high dielectric strength and fire safety. This segment experiences significant demand from advanced semiconductor manufacturing in Taiwan.
Insulation applications represent a mature segment, but Electrical uses are demonstrating significant growth.
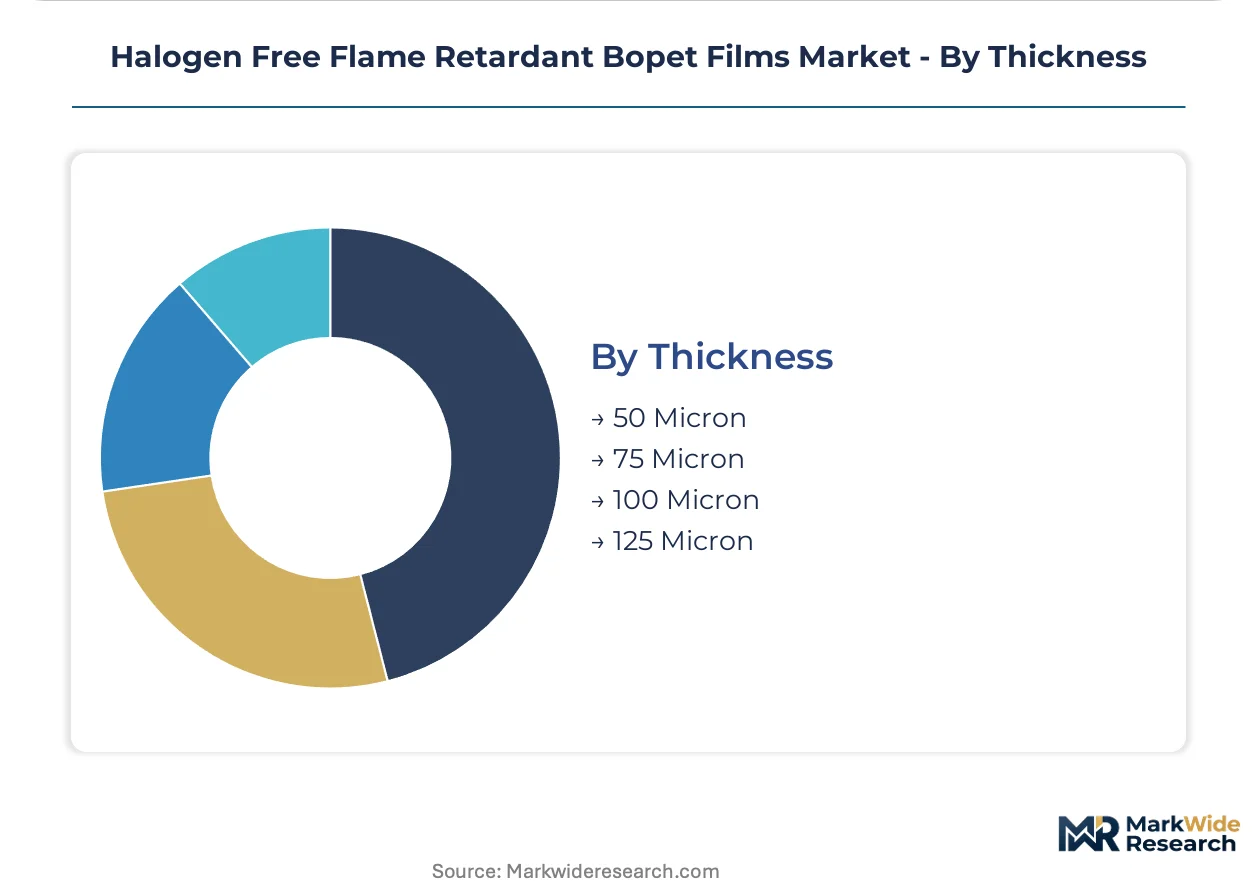
Thickness:
Film thickness directly correlates with performance requirements, influencing mechanical strength, flexibility, and dielectric properties across diverse applications.
- 50 Micron:Ultra-thin films below 50 microns are critical for flexible circuits, wearable electronics, and compact insulation layers where space is severely constrained. Demand from flexible display manufacturing in South Korea consistently drives innovation in this segment.
- 75 Micron:Films around 75 microns strike a balance between mechanical strength and flexibility, finding widespread use in general electrical insulation and some automotive components. This thickness is a standard for many industrial insulation requirements.
- 100 Micron:Thicker 100 micron films provide enhanced structural integrity and dielectric strength, suitable for more robust insulation in power electronics and industrial motor applications.
- 125 Micron:The 125 micron segment offers superior mechanical protection and dielectric properties, often specified for heavy-duty industrial insulation and structural components in demanding environments.
The 75 Micron segment maintains a substantial base, with 50 Micron films exhibiting the fastest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive electronics manufacturing infrastructure underwrites its significant role in the halogen-free flame retardant BOPET films market. This infrastructure supports massive production volumes for consumer electronics and electric vehicles. The country's strict material standards further solidify its market position.
China
Electronics manufacturing and electric vehicle production generate substantial demand for halogen-free BOPET films in China. The country's GB standards for electronic products and automotive parts mandate fire safety and material composition. The Yangtze River Delta region, a key electronics hub, concentrates extensive film usage for advanced components, particularly in flexible circuits.
South Korea
Advanced semiconductor and flexible display manufacturing drive significant consumption of thin-gauge flame retardant films in South Korea. National environmental policies reinforce the shift towards halogen-free materials in electronic components. The Seoul Capital Area, a global center for display technology, consistently innovates in ultra-thin film applications for wearable devices.
Germany
Advanced automotive electronics and electric vehicle battery packs create strong demand for high-performance films in Germany. The EU's RoHS and REACH directives strictly limit halogenated compounds, favoring compliant materials. Bavaria, a hub for automotive innovation, sees concentrated adoption of customized coated films for critical components in EV power modules.
United States
Electric vehicle production and industrial insulation applications fuel demand for these films across the United States. State-level environmental initiatives and evolving safety standards promote the use of non-halogenated alternatives. Michigan, a core automotive manufacturing state, is experiencing increased film integration into EV battery systems and power electronics.
Halogen Free Flame Retardant Bopet Films Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the halogen-free BOPET films market. The market exhibits a tiered structure, with a few large material science experts and integrated film producers defining the core supply landscape. Strategic archetypes include global chemical conglomerates focused on advanced polymer development and specialized film converters offering customized solutions. These players frequently engage in strategic partnerships and co-development initiatives to meet stringent OEM specifications.
Among the material science experts, Toray Industries, Inc. leverages its extensive research capabilities to offer customized solutions for demanding applications like electric vehicle battery packs. DuPont Teijin Films, a joint venture, occupies a strong market position through its extensive global distribution network, serving diverse electronics manufacturers across multiple regions. SKC Co., Ltd., a South Korea-based specialist, exemplifies focus on high-thickness films for industrial insulation, catering to niche segments requiring superior mechanical strength and thermal resistance in challenging environments.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| DuPont Teijin Films |
| Mitsubishi Polyester Film |
| SKC Co., Ltd. |
| Polyplex |
| Shanghai Huzheng Industrial Co., Ltd. |
| Mainyang Prochema Commercial Co., Ltd. |
| Teraoka Seisakusho Co., Ltd. |
| Uflex Limited |
Cost & Logistics Intelligence
The concentrated supply of specialized phosphorus-based flame retardant additives, largely from a few chemical manufacturers, directly influences margin pools across the BOPET film conversion and distribution tiers.
Pricing Analysis
Volume-discount tiering structures dominate pricing for halogen-free BOPET films, reflecting the scale of procurement by large electronics and automotive OEMs. Price differentiation stems from the film's certification level against EU RoHS and China's GB standards, alongside customization for specific applications like EV battery liners. Cost compression in standard-grade films is intensifying due to competition, while specialized high-performance films command a premium. Electronics manufacturers for consumer goods exhibit higher price sensitivity compared to automotive and aerospace buyers who prioritize performance and safety.
Supply Chain Analysis
Integrated film producers like Toray Industries and DuPont Teijin Films hold significant manufacturing capacity, shaping the core supply landscape for halogen-free BOPET films. Geographic supply concentrates in China, South Korea, and Germany, driven by electronics and automotive production hubs. The market relies on specialized phosphorus and nitrogen-based flame retardant additives, sourced from a concentrated base of chemical manufacturers. This creates single-source vulnerability for high-purity compounds. Distribution runs through direct supply partnerships with OEMs for advanced films, while standard products utilize broader industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat, underpinned by regulatory entrenchment from directives like EU RoHS and China's GB standards. These mandates create a non-negotiable demand for compliant halogen-free BOPET films.
For Market Incumbents: Entrench existing OEM partnerships by investing in co-development for next-generation EV battery insulation and flexible electronics. Expand specialized production capacity in key manufacturing hubs like the Yangtze River Delta to counter regional supply chain risks. Prioritize R&D in enhanced thermal conductivity to mitigate performance trade-offs, securing market share against emerging material alternatives. Strengthen certification investments to navigate complex international regulatory pathways.
For New Entrants and Emerging Players: Pursue niche opportunities in ultra-thin films below 50 microns for flexible and wearable electronics, particularly in advanced manufacturing hubs like South Korea. Target segments demanding enhanced thermal conductivity in power modules and 5G equipment. A go-to-market angle focused on rapid customization and specialized material science expertise can differentiate offerings. Focus on applications where performance, not just price, drives material selection.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-performance film manufacturing, driven by advanced material science and specialized equipment. This market offers strong long-term viability over the next 5-10 years, fueled by sustained regulatory pressure and electric vehicle expansion. Target acquisition archetypes include specialized film converters with proprietary additive integration technologies or deep OEM co-development partnerships. The signal to watch is increased R&D and commercialization of bio-based PET resins, indicating future sustainability differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Supports growing electronics and EV manufacturing demand in key regional hubs. |
| Green Manufacturing Transition | Aligns with OEM corporate ESG targets, enhancing market appeal and regulatory compliance. |
| Long-term Supply Agreement | Secures stable raw material access for specialized flame retardant additives, mitigating price volatility. |
| Joint Venture for R&D | Accelerates development of multifunctional films with enhanced thermal conductivity and dielectric strength. |
| Product Launch (Bio-based Films) | Addresses demand for sustainable materials, attracting OEMs with strong environmental commitments. |
Research Approach
Cross-validation between primary interviews and secondary research anchors the qualitative findings of this study. Conversations were conducted with R&D directors at film producers, procurement leads at electronics OEMs, and automotive component engineers. Secondary data sources included EU RoHS directives, China's GB standards, and specialized material science journals. A rigorous bottom-up and top-down triangulation approach ensured data consistency across all market segments.
The calibration approach for market sizing and forecasting integrates historical data with future projections across the analysis window. Segmentation dimensions modeled include Product Type, End-Use Industry, Application, Thickness, and regional regulatory compliance. Compound annual growth rates were derived from a multi-variant analysis considering technological adoption curves and market penetration rates. Electric vehicle production forecasts and electronics manufacturing output served as key industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in global industrial output or raw material price volatility would shift the trajectory. Forecasts reflect assumptions regarding sustained regulatory enforcement and technological advancements. Quarterly review of regulatory updates and raw material indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Street Lighting Market
Others
Powder Coating Equipment Market
Others
Folding Mobile Phone Market
Others
India Battery E-Commerce Market
Others
Military 4D Printing Market
Others
Flexographic Printing Plate Market
Others
Global Military Wearable Sensors Market
Others
Global Augmented Reality in Retail Market
Others
Global Digital Market
Others
Global Contactless Biometrics Technology Market
Others
Photo Booth/Kiosk Market
Others
Japan 3D Printing Construction Market
Others
Europe Flow Battery Market
Others
Cloud Gaming Baas Market
Others
India Data Center Physical Security Market
Others
Floor Cleaning and Mopping Machine Market