
 Global Contactless Biometrics Technology Market | 2026-2036
Global Contactless Biometrics Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contactless Biometrics Technology Market Intelligence
Platform licensing revenue from cloud-based solutions is reshaping the profitability models for biometric system providers. This shift moves value from one-time hardware sales to recurring software and service contracts. Thales Group leverages its diversified technology portfolio to serve government and enterprise clients. NEC Corporation specializes in high-accuracy facial recognition algorithms for large-scale public safety and border control projects. IDEMIA competes through its extensive research and development in iris, facial, and fingerprint recognition technologies for secure identification.
Contactless biometrics technology encompasses systems designed to capture and verify human identity without physical touch. These systems employ sensors to analyze unique physiological or behavioral traits, such as iris patterns at specific infrared wavelengths or facial geometry with sub-millimeter accuracy. The primary purpose is to enable secure, hygienic, and rapid authentication. Facial recognition leads in adoption for mobile authentication and access control applications. Iris scanning and palm vein authentication represent high-security niches within government agencies and financial institutions, often commanding higher margins.
Regulatory frameworks such as the GDPR in Europe and HIPAA in the United States significantly impact market access. These regulations mandate strict data privacy, consent, and security protocols, influencing system design and data storage policies. International standards like the ISO/IEC 24745 series provide guidelines for biometric information protection. The critical decision for system providers involves balancing algorithm performance and accuracy with evolving data protection obligations and ethical AI principles.
Market Dynamics
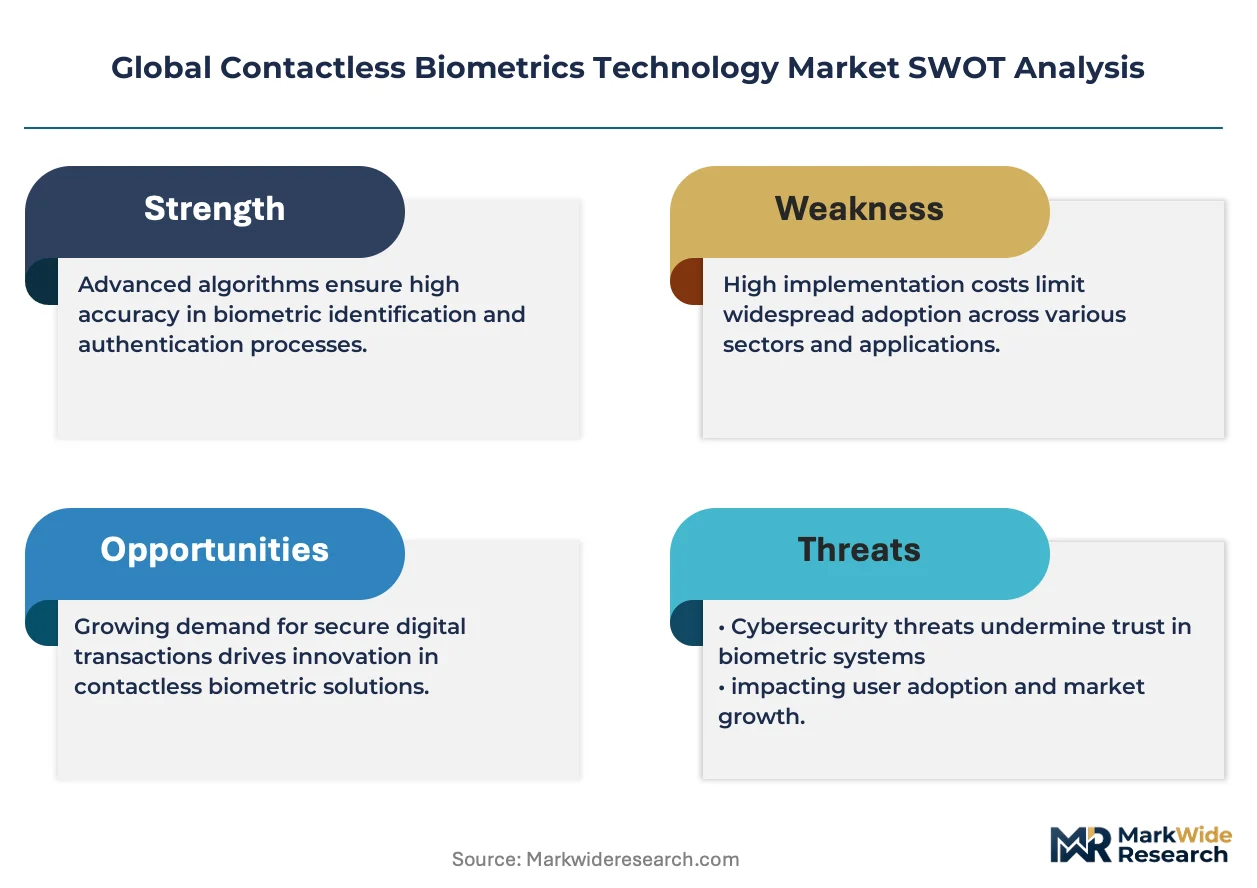
The central tension shaping the contactless biometrics market is the conflict between escalating demand for frictionless security in public and commercial spaces and the simultaneous rise of stringent data privacy regulations like GDPR. This dynamic forces providers to innovate on privacy-preserving architectures, such as on-device processing and federated learning, to meet security mandates without violating individual rights.
Growth Catalysts
- Government Mandates:National identity programs and border control modernization in countries like India and the United States require large-scale, high-speed biometric screening, creating sustained public sector demand for facial and iris recognition systems.
- Financial Services Integration:The need for secure and convenient mobile banking and payment authentication drives adoption of facial and fingerprint biometrics embedded within consumer smartphones, expanding the addressable market significantly. *Hygiene and Convenience: A heightened public awareness of hygiene has accelerated the replacement of touch-based systems like keypads and fingerprint scanners with contactless alternatives in corporate offices, hospitals, and transportation hubs.
Market Restraints
- Algorithm Bias and Accuracy:Performance variations of facial recognition algorithms across different demographic groups can lead to higher error rates, posing significant ethical and operational risks and limiting deployment in sensitive applications.
- Regulatory Compliance Overhead:Navigating complex and fragmented data protection laws, such as Europe's GDPR and the United States' HIPAA, increases system development costs and creates legal risks for data handling and storage.
- High Implementation Costs:The initial capital investment for high-accuracy biometric hardware, such as infrared iris scanners and 3D facial cameras, along with secure network infrastructure, remains a substantial barrier for smaller organizations.
Strategic Opportunities
- Healthcare Patient Identification:Deploying contactless biometrics in hospitals can improve patient safety by eliminating identification errors, streamlining administrative processes, and providing secure access to medical records, representing a large, underpenetrated vertical.
- Technology Convergence:Combining biometric data with blockchain technology offers a pathway to create decentralized, tamper-proof digital identities, providing users with greater control over their personal information.
- Automotive Personalization:Integrating facial or iris recognition into vehicles enables personalized driver profiles, automatic seat and mirror adjustments, and enhanced anti-theft security, opening a new consumer application frontier.
Industry Challenges
- Legacy System Integration:Integrating modern, API-driven biometric platforms with older, on-premise security and HR systems within large enterprises presents significant technical hurdles and prolongs implementation timelines.
- Specialized Talent Scarcity:A shortage of experts in AI ethics, data privacy law, and advanced algorithm development hinders the ability of vendors to build and maintain systems that are both effective and socially responsible.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contactless Biometrics Technology Market |
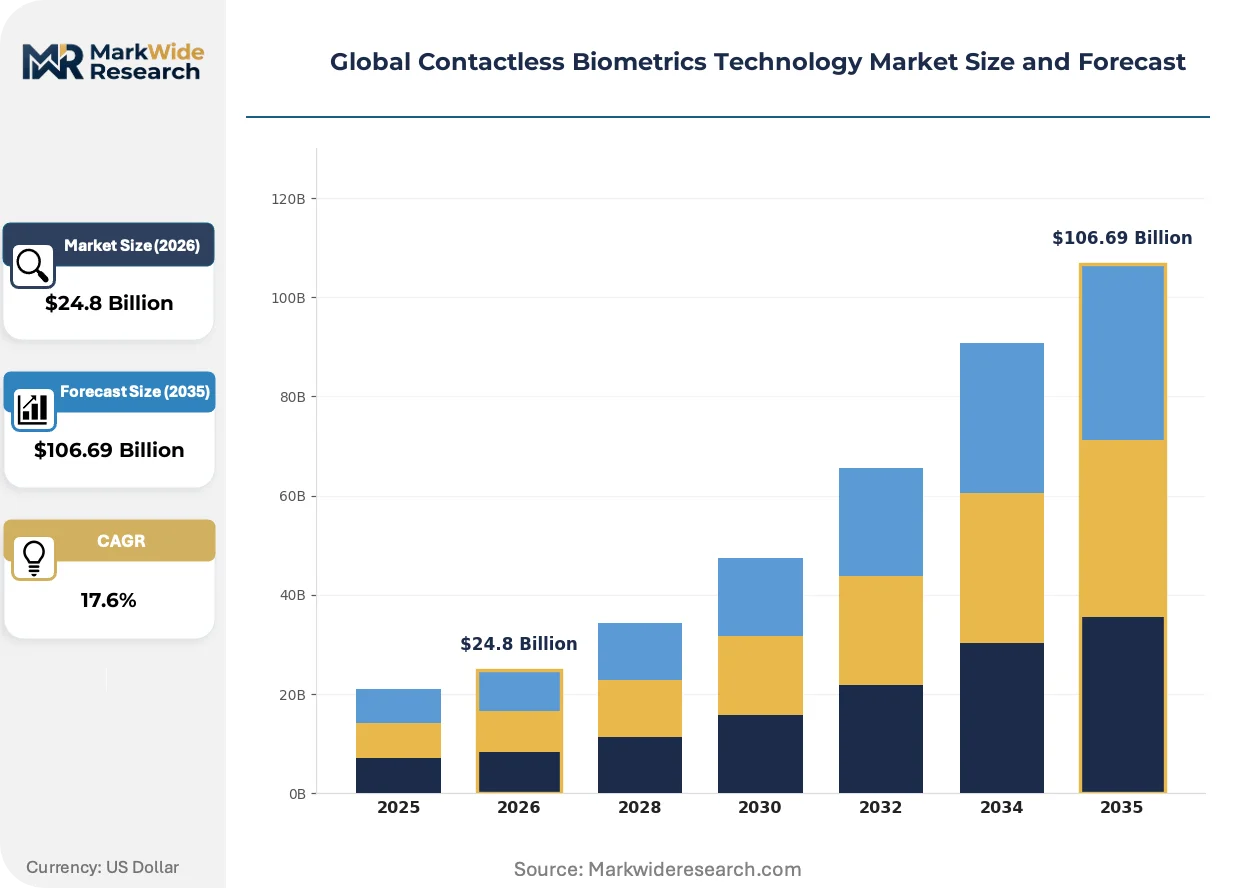
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $106.69 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Facial Recognition, Iris Scanning, Voice Identification, Palm Vein Authentication, Gesture Recognition, Behavioral Biometrics Application: Access Control, Border Security, Mobile Authentication, Payment Systems, Workforce Management, Event Management End User: Government Agencies, Financial Institutions, Telecommunications Operators, Cloud Service Providers, Online Retailers, Education Providers Deployment Mode: Cloud-Based, On-Premises, Hybrid Solutions, Edge Computing Platforms |
| Companies Covered | NEC Corporation, IDEMIA, Fujitsu Limited, HID Global Corporation, Thales Group, Fingerprint Cards AB, Aware Inc., M2SYS Technology, Gemalto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contactless Biometrics Technology Market Strategic Shifts & Innovations
The market's evolution is defined by the transition from hardware-centric sales to software-driven, recurring revenue models. This shift places a premium on algorithm performance, cloud-native architecture, and the ability to navigate an increasingly complex ethical and regulatory environment for identity verification technologies.
On-device biometrics, leveraging specialized neural processing units (NPUs) within smartphones and edge devices, perform authentication locally without sending raw data to the cloud. Consumer electronics and automotive manufacturers are rapidly adopting this for enhanced user privacy and instantaneous response times. This technology is digitizing identity verification at the network edge, reducing latency and mitigating the privacy risks associated with centralized data processing for every authentication request.
The European Union’s proposed AI Act introduces a risk-based framework that classifies most real-time biometric identification systems in public spaces as high-risk. This regulation mandates rigorous pre-market conformity assessments, human oversight, and strict transparency obligations. Vendors targeting government and public safety sectors in Europe are proactively redesigning system architectures to incorporate privacy-by-design principles and ensure compliance to avoid market access restrictions.
A clear behavioral change is visible as enterprise procurement moves from one-time capital expenditures on hardware to subscription-based Identity-as-a-Service (IDaaS) contracts. This model displaces the work of traditional system integrators with cloud-native platforms that offer scalable, pay-as-you-go user management and continuous updates. This trend is most advanced within the technology and financial services verticals, where agility and opex-based financial models are preferred.
Global Contactless Biometrics Technology Market Segmentation
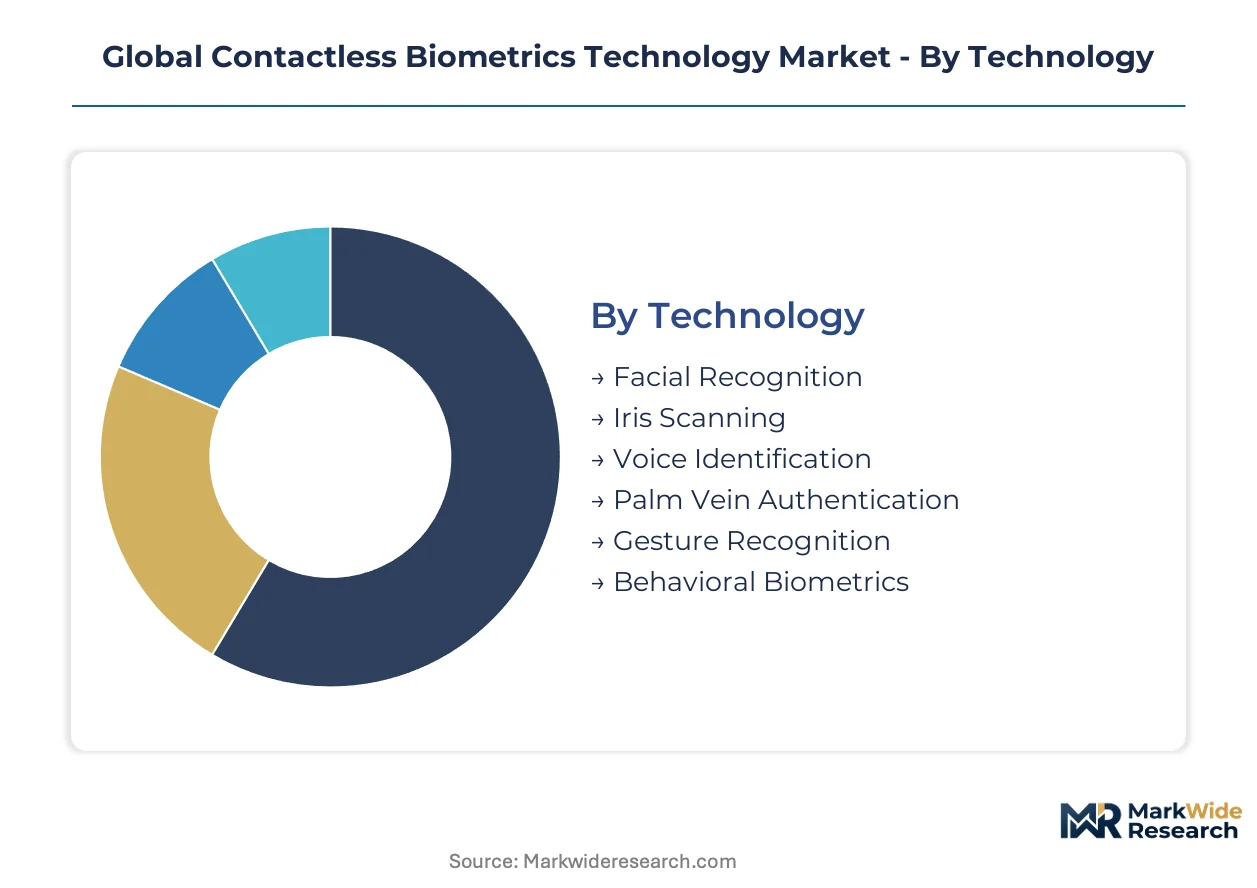
Understanding the distinct segments within the contactless biometrics market is essential for identifying strategic opportunities and allocating resources effectively. This detailed analysis reveals how diverse technologies, applications, end-users, and deployment models contribute to the overall market structure and growth trajectory. Each segment reflects unique demand drivers and operational characteristics.
Technology:
The technology segment reveals a spectrum ranging from mature, widely adopted solutions to emerging, specialized biometric modalities. Facial recognition technology leads in market penetration, while iris scanning offers high-security verification.
- Facial Recognition:This technology analyzes unique facial features and geometry for identification, often leveraging AI and machine learning algorithms. Demand is concentrating within mobile authentication and access control applications across consumer and enterprise sectors, driven by convenience and widespread smartphone integration.
- Iris Scanning:Utilizing infrared light to capture the complex and unique patterns of the human iris, this method offers extremely high accuracy and security. Government agencies and financial institutions are key consumers, requiring robust authentication for secure facilities and high-value transactions.
- Voice Identification:Analyzing unique vocal characteristics, including pitch, tone, and cadence, enables hands-free authentication. This technology finds applications in customer service centers and secure remote access.
- Palm Vein Authentication:This method maps the unique vein patterns beneath the skin of the palm, offering a highly secure and hygienic option. Healthcare and banking sectors utilize this for high-security access points.
- Gesture Recognition:Identifying individuals through unique hand movements or gestures, this technology is still in nascent stages. It holds potential for touchless interaction in public spaces and smart environments.
- Behavioral Biometrics:This segment encompasses analysis of unique patterns in typing, gait, or mouse movements. It primarily serves continuous authentication and fraud detection in online platforms.
Facial Recognition handles the majority of throughput; Iris Scanning is the fastest mover on share.
Application:
The application segment illustrates how contactless biometrics address specific functional needs across various sectors, from securing borders to streamlining daily transactions. Each application category presents distinct implementation challenges and adoption rates.
- Mobile Authentication:This application secures access to smartphones, mobile banking, and various digital services using embedded biometric sensors. Consumer convenience and the widespread use of personal devices drive significant adoption in this area.
- Border Security:Contactless biometrics enable rapid and accurate identification of individuals at national borders and immigration checkpoints. Government mandates for enhanced security and efficient passenger processing are critical drivers for this application.
- Access Control:Managing physical entry to buildings, restricted areas, and sensitive data centers without physical contact defines this application. Corporate offices and healthcare facilities increasingly deploy these systems for hygiene and enhanced security.
- Payment Systems:Integrating biometric verification into retail and online payment processes offers a secure and frictionless transaction experience. Financial institutions and e-commerce platforms are exploring broader deployment to reduce fraud.
- Workforce Management:Biometric solutions streamline time and attendance tracking, as well as internal access permissions for employees. Enterprises adopt these systems to improve operational efficiency and secure internal resources.
- Event Management:Contactless biometrics facilitate quick and secure attendee verification at conferences, concerts, and sports events. This application enhances security while reducing wait times for large gatherings.
Mobile Authentication holds the largest share of deployments; Border Security shows the steepest expansion trajectory.
End User:
The end-user segment highlights the diverse organizational types that leverage contactless biometrics, each with specific security requirements and regulatory environments. Government and financial sectors represent significant demand centers due to their stringent security needs.
- Government Agencies:These entities deploy contactless biometrics for national identity programs, law enforcement, and border control, requiring high accuracy and scalability. National security mandates and public safety initiatives drive substantial investment from these agencies.
- Financial Institutions:Banks and other financial service providers use biometrics for secure mobile banking, ATM authentication, and fraud prevention. The need for robust security in high-value transactions and compliance with financial regulations shapes their adoption.
- Telecommunications Operators:These companies utilize biometrics for customer verification during SIM card activation and secure access to online accounts. Preventing identity fraud and ensuring subscriber security are primary motivators.
- Cloud Service Providers:Biometric authentication secures access to cloud infrastructure and sensitive data stored remotely. These providers integrate biometrics to offer enhanced security layers for their enterprise clients.
- Online Retailers:E-commerce platforms employ biometrics for secure user logins and payment authorization, reducing cart abandonment and fraud. Enhancing customer trust and streamlining the purchasing process are key objectives.
- Education Providers:Schools and universities implement biometrics for secure campus access, attendance tracking, and exam proctoring. Improving student safety and administrative efficiency are primary benefits.
Government Agencies represent the largest spending segment; Cloud Service Providers are gaining share most quickly.
Deployment Mode:
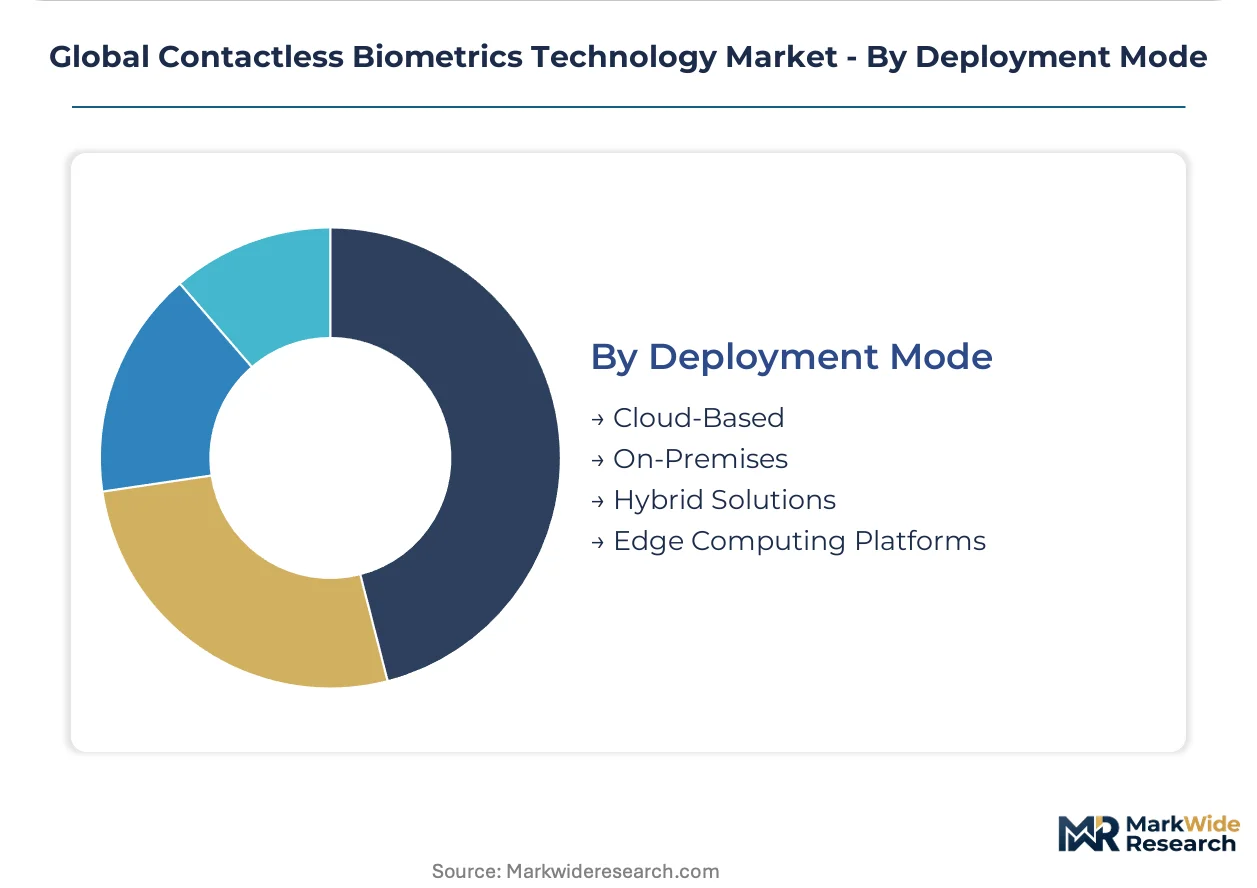
The deployment mode segment distinguishes how contactless biometric systems are architected and delivered, impacting scalability, cost, and data sovereignty. Cloud-based solutions are gaining prominence, while edge computing addresses privacy concerns.
- Cloud-Based:These solutions host biometric data and processing on remote servers, accessible via the internet, offering scalability and reduced infrastructure costs. Subscription-based Identity-as-a-Service (IDaaS) models are increasingly preferred by enterprises for agility.
- Edge Computing Platforms:Biometric authentication occurs directly on local devices or gateways, minimizing data transfer to central servers and enhancing privacy. Consumer electronics and automotive manufacturers adopt this for instantaneous response times and data protection.
- On-Premises:Systems are installed and managed directly within the client's physical infrastructure, providing maximum control over data. Organizations with strict data governance policies or legacy systems often prefer this deployment.
- Hybrid Solutions:This mode combines elements of both cloud-based and on-premises deployments, balancing scalability with localized control. Enterprises use hybrid models for sensitive data processing locally while leveraging cloud resources for less critical functions.
Cloud-Based deployments command the largest share of new installations; Edge Computing Platforms are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Where security mandates drive demand, contactless biometrics exhibit low price sensitivity, particularly in government and financial sectors. Conversely, consumer-facing applications often prioritize convenience and cost-effectiveness. This dynamic shapes regional investment priorities and technology adoption rates across diverse markets.
United States
Demand for contactless biometrics in the United States stems from national identity programs and border security modernization. HIPAA regulations mandate stringent data privacy for healthcare applications, influencing system design. Silicon Valley and Washington D.C. drive innovation and adoption for both commercial and federal deployments.
India
India's national identity programs, like Aadhaar, fuel massive demand for large-scale iris and facial recognition systems. The country's central bank, RBI, promotes secure digital payment authentication, integrating biometrics into financial services. Bangalore and Hyderabad are technology hubs developing scalable biometric solutions for public and private use.
Germany
Germany's focus on data protection drives innovation in privacy-preserving biometric architectures for access control. The EU's GDPR dictates strict consent and data handling protocols for all biometric deployments. Munich and Berlin host research centers advancing ethical AI principles in facial recognition technology.
United Arab Emirates
The United Arab Emirates prioritizes contactless biometrics for smart city initiatives and efficient border processing. MOHAP regulations influence healthcare identification systems, ensuring secure patient data. Dubai and Abu Dhabi lead in deploying advanced facial and iris scanning at airports and government facilities.
Japan
Japan's aging population and focus on convenience propel demand for contactless solutions in public transport and payments. METI guidelines encourage the development of secure and user-friendly biometric authentication methods. Tokyo and Osaka are centers for R&D in advanced facial recognition and palm vein technologies.
Global Contactless Biometrics Technology Market Key Industry Players
Capability concentration sits with one tier, focusing on advanced algorithm development and privacy-preserving architectures; scale advantage sits with another, leveraging extensive distribution networks for mass deployment. The market structure exhibits a tiered consolidation, with established technology conglomerates alongside specialized biometric solution providers. Key strategic archetypes include diversified technology providers and niche biometric innovators. Companies often pursue strategic partnerships and portfolio diversification to expand their market reach.
Within the diversified technology provider archetype, NEC Corporation and Thales Group represent established entities leveraging broad portfolios across various sectors, from public safety to enterprise solutions. IDEMIA exemplifies a specialized biometric innovator, focusing intensive research and development on core biometric modalities like iris, facial, and fingerprint recognition. These companies anchor the market through significant investments in high-accuracy solutions and global implementation capabilities, particularly in secure identification and authentication. Their competitive positioning often stems from deep expertise in government and large enterprise solutions, offering comprehensive platforms rather than single-point products. Fujitsu Limited also occupies a position among these established players, contributing to large-scale public infrastructure projects.
| Leading Market Players |
|---|
| NEC Corporation |
| IDEMIA |
| Fujitsu Limited |
| HID Global Corporation |
| Thales Group |
| Fingerprint Cards AB |
| Aware Inc. |
| M2SYS Technology |
| Gemalto |
| Others |
Cost & Logistics Intelligence
Specialized sensor manufacturing in East Asia dictates hardware costs, which in turn shifts margin pools towards recurring software licenses and integration services for biometric system providers.
Pricing Analysis
Recurring software and service contracts drive the lifetime value in contactless biometrics, reshaping profitability models. Subscription-based Identity-as-a-Service (IDaaS) models dominate new installations, often leveraging value-based pricing for specialized solutions. Algorithm accuracy and privacy-by-design compliance differentiate pricing for high-security applications like iris scanning. Hardware pricing faces pressure from commoditization, while government agencies exhibit low price sensitivity for advanced solutions.
Supply Chain Analysis
Contract manufacturing of specialized optical sensors and neural processing units in Taiwan and China forms a critical upstream concentration for hardware components. The supply chain also draws from secure element chips and advanced imaging components, alongside global software development for algorithms. Single-source vulnerability for high-accuracy iris and facial recognition sensors presents a structural risk. Distribution runs through direct sales channels for government and large enterprise clients, alongside OEM integration for consumer devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contactless biometrics market's trajectory is defined by a critical scarcity of expertise in AI ethics and data privacy law, particularly for system architects. This talent gap limits the development of compliant and socially responsible identification systems, creating a strategic bottleneck.
For Market Incumbents: Build a regulatory compliance moat by proactively integrating privacy-by-design principles into core system architectures. Invest in advanced R&D for federated learning and on-device processing to mitigate stringent data privacy regulations like the EU AI Act. Deepen integration capabilities with diverse enterprise legacy systems to maintain market share against agile software-focused entrants.
For New Entrants and Emerging Players: Healthcare patient identification and automotive personalization represent the most penetrable entry points for specialized biometrics. Target mid-sized hospital networks with outcome-based IDaaS offerings that streamline patient workflows and enhance data security. Focus on niche automotive manufacturers seeking integrated biometric solutions for advanced driver personalization and anti-theft systems.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized algorithm developers with robust intellectual property in on-device processing and behavioral biometrics for long-term viability. Target firms demonstrating strong compliance frameworks for GDPR and the EU AI Act. Widespread adoption of international biometric data protection standards, such as ISO/IEC 24745, will signal market maturation and reduced regulatory risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrates diverse biometric modalities into a unified security platform for enterprise clients. |
| Strategic Partnership | NEC Corporation partners with cloud providers to expand Identity-as-a-Service reach across new verticals. |
| Acquisition of Specialist Firm | Acquiring firms with expertise in federated learning enhances privacy-preserving capabilities for mobile authentication. |
| Product Launch | Introduces new iris scanning hardware for government border control applications, improving throughput. |
| Geographic Expansion | IDEMIA expands into new markets like the United States for national identity programs and public safety. |
Research Approach
Cross-validation between primary interviews and comprehensive secondary research anchors the qualitative findings. This study engaged CTOs, government procurement officers, financial institution security leads, and privacy compliance officers. Secondary data sources included regulatory body reports, technology patent databases, and corporate financial filings. Bottom-up and top-down triangulation ensured data integrity and market sizing accuracy.
Forecasts were calibrated across historical data and projected market drivers over the projection horizon. This analysis modeled segmentation dimensions including technology, application, end-user, deployment mode, and regional regulatory environment. Compound annual growth rates were derived from historical patterns and projected technological advancements. Key inputs included mobile authentication adoption rates and government security spending trends.
Practitioners should monitor rapid shifts in AI regulation, significant technological breakthroughs, or major geopolitical events for early signals of market revision. Forecasts reflect assumptions regarding regulatory stability and technology adoption. Quarterly review of new regulatory proposals and major technology patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Active Speaker Market
Others
Thermoformed Plastics Market
Others
Egg and Egg Products Market
Others
Mexico Retail Market
Others
Europe Postal Services Market
Others
Agitator Bead Mill Market
Others
Wearable AI Market
Others
ASEAN Smart Homes Market
Others
Global Cryogenic Tanks Market
Others
Japan Automotive LED Lighting Market
Others
Solar Lighting Tower Market
Others
Evidence Management Market
Others
Europe Street Lighting Market
Others
Global Animal Feed Protein Ingredients Market
Others
Global Video Processing Platform Market
Others
Internet Protocol Television (IPTV) Market