
 Flexographic Printing Plate Market | 2026-2036
Flexographic Printing Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Flexographic Printing Plate Market Intelligence
Asset-light leasing models for digital plate imaging equipment are rewriting competitive entry barriers for mid-sized converters. MacDermid Graphics Solutions leverages captive photopolymer chemistry to sustain margin control across plate formulations. Fujifilm anchors its position through integrated flat-top dot technology that reduces press setup waste. DuPont de Nemours competes by specializing in solvent-wash plate platforms for high-volume corrugated applications.
A flexographic printing plate is a raised-image relief matrix, typically manufactured from photopolymer elastomers or rubber compounds with thickness tolerances between 0.045 and 0.250 inches, designed to transfer ink from an anilox roller onto flexible substrates at speeds exceeding 500 feet per minute. Digital plates now dominate new equipment configurations because flat-top dot structures eliminate oxygen-inhibition artifacts and extend print gamut without additional screening steps. Photopolymer material formulations command the largest share of consumables spending, while water-based ink compatibility represents the fastest-growing technology dimension as converters retrofit presses for solvent-free operation. Liquid plate systems occupy a niche in prototype and short-run label environments where rapid changeover justifies higher unit chemistry costs.
EPA emissions guidelines and OSHA workplace exposure limits are restricting solvent-based plate processing chemistries in United States manufacturing facilities, redirecting capital toward thermal and water-wash alternatives. The EU REACH framework governs isocyanate and styrene content in photopolymer raw materials, compelling reformulation investments from European plate suppliers. Stakeholders must monitor how FDA food-contact notification requirements evolve for UV-cured ink systems, since plate surface energy properties directly influence migration test outcomes and brand owner qualification protocols.
Market Dynamics
Flat-top dot digital plate technology is compressing setup waste and extending color gamut without screening steps, while REACH and FDA food-contact rules are reformulating photopolymer chemistry specifications across manufacturing bases.
Growth Catalysts
- E-commerce corrugated demand in India:Box plants serving fulfillment centers are modernizing press fleets and consuming higher plate volumes per installation.
- Water-based ink compatibility mandates:EPA emissions guidelines and OSHA exposure limits are redirecting capital toward solvent-free press retrofits and compatible plate formulations.
- Shelf-ready flexible packaging formats:Southeast Asian converters are displacing rigid alternatives with flexible structures that require finer halftone reproduction.
Market Restraints
- Photopolymer raw material concentration:European suppliers face reformulation costs under REACH isocyanate and styrene content limits.
- Thermal and water-wash equipment capex:Solvent-restricted processors must absorb higher upfront imaging system costs.
- Digital plate imaging equipment leasing complexity:Asset-light models rewrite entry barriers but create long-term contractual lock-in for mid-sized converters.
Strategic Opportunities
- Short-run label prototype environments:Liquid plate systems command premium chemistry costs where rapid changeover justifies niche positioning.
- UV-cured ink food-contact qualification:FDA notification requirements for plate surface energy properties create service revenue around migration testing protocols.
- Integrated flat-top dot technology convergence:Combining digital imaging with optimized dot structures eliminates oxygen-inhibition artifacts for brand owner approval.
Industry Challenges
- Press fleet modernization skill gaps:Corrugated plants require technicians trained in digital plate mounting and automated register control.
- Multi-jurisdiction compliance timelines:Simultaneous REACH, FDA, and EPA adherence stretches qualification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexographic Printing Plate Market |
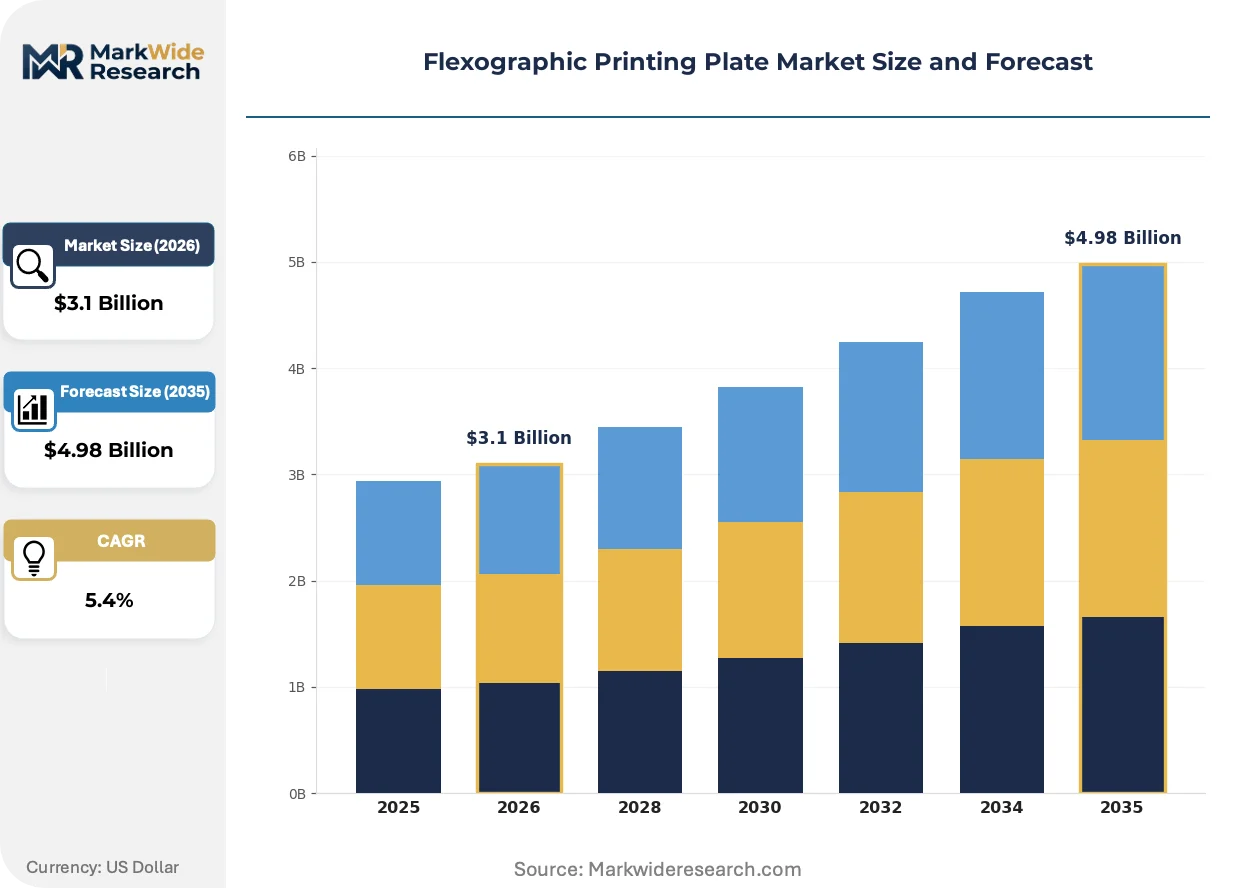
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Plates, Soft Plates, Liquid Plates, Digital Plates Material: Rubber, Photopolymer, Metal, Composite End User: Packaging Industry, Textile Industry, Label Printing, Corrugated Cardboard Technology: Water-Based Inks, UV-Curable Inks, Solvent-Based Inks, Eco-Friendly Solutions |
| Companies Covered | MacDermid Graphics Solutions, Toyobo, Toray Industries, Esko, Fujifilm, DuPont de Nemours, Asahi Kasei, Asahi Photoproducts, Kodak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexographic Printing Plate Market Strategic Shifts & Innovations
Equipment configuration and chemistry formulation are converging around waste reduction and regulatory pre-qualification, with digital workflows replacing analog platemaking steps.
Photopolymer elastomer formulations are migrating from solvent-wash processing toward thermal and water-wash alternatives. High-volume corrugated converters in the United States are accelerating this transition under EPA emissions guidelines. The structural consequence is chemistry supplier consolidation around aqueous and thermal platform compatibility.
REACH framework governance of isocyanate and styrene content is compelling European plate suppliers into reformulation investments. Industrial consequence includes raw material qualification delays and batch consistency verification costs. Flexible packaging segments serving food-contact applications are most affected, with brand owners demanding pre-certified plate documentation.
Asset-light leasing for digital plate imaging equipment is replacing capital purchase models among mid-sized converters. Equipment vendors are capturing recurring revenue through chemistry supply contracts and technical service retainers. This shift concentrates most visibly in India and Southeast Asia where converter balance sheets favor operational expenditure structures.
Flexographic Printing Plate Market Segmentation
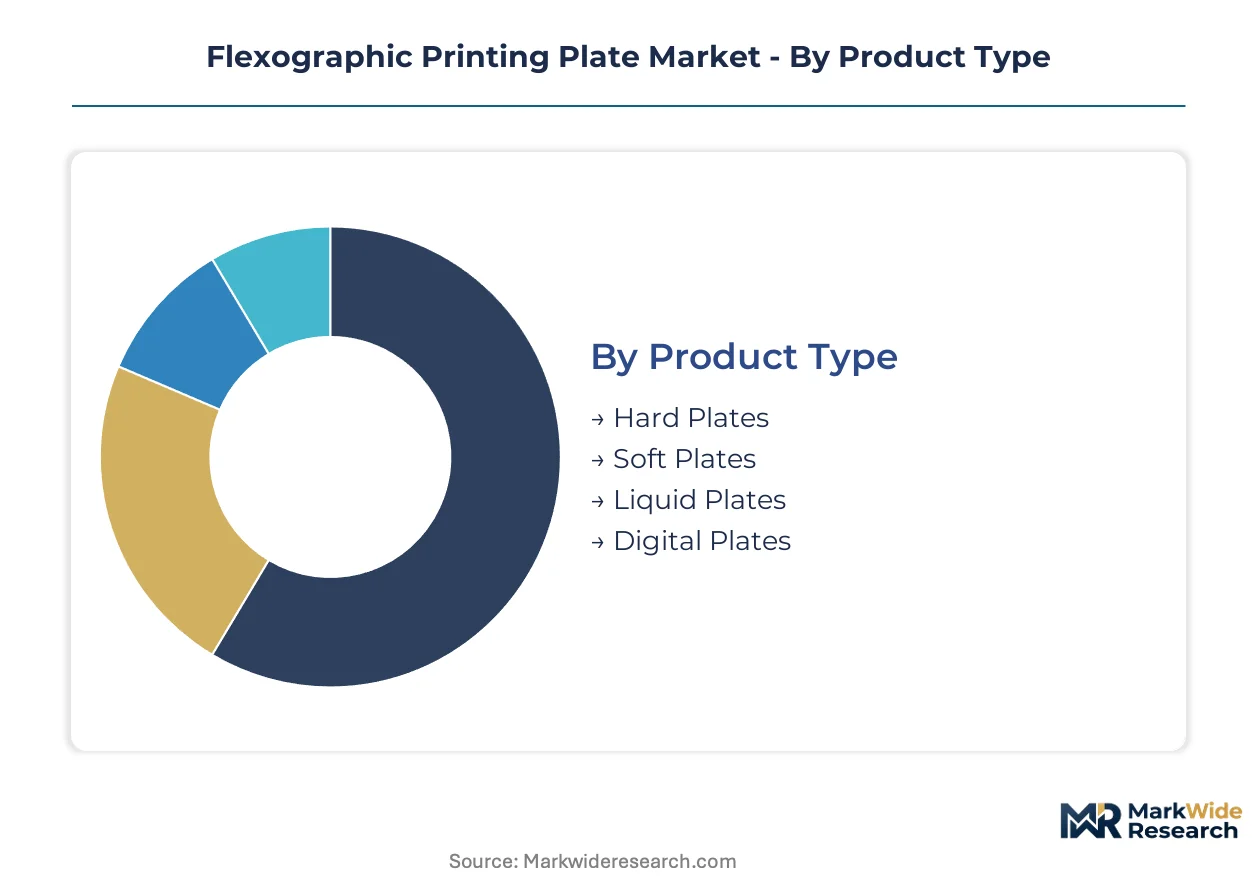
Segmentation in flexographic printing plates reveals how technical specifications align with press configurations and regulatory environments. Plate selection directly determines ink compatibility, substrate range, and compliance pathways for converters serving food-contact and industrial packaging.
Product Type:
Cycle times vary dramatically across plate formats, with digital workflows compressing prepress timelines while analog methods persist in legacy corrugated installations.
- Digital Plates:Flat-top dot structures eliminate oxygen-inhibition artifacts through LED-UV exposure systems. Indian e-commerce corrugated plants and Southeast Asian flexible packaging converters are prioritizing these formats to reduce press setup waste and extend color gamut without screening steps.
- Hard Plates:Dense photopolymer matrices with Shore A hardness exceeding 70 suit high-volume corrugated runs and abrasive substrates. Box plants serving fulfillment centers in India favor these for durability across long print campaigns, though thermal processing requirements add capex burden.
- Soft Plates:Lower-durometer elastomers conform to uneven substrates in textile and specialty label applications.
- Liquid Plates:Rapid-curing photopolymer systems dominate prototype and short-run label environments where changeover speed justifies premium chemistry costs.
Hard plates anchor the volume base while digital plates gain share at the steepest rate.
Material:
Cost tiers separate commodity elastomers from precision-engineered photopolymers with controlled molecular weight distributions.
- Photopolymer:Cross-linked elastomer formulations dominate consumables spending, with water-wash and thermal variants displacing solvent-processed alternatives under EPA emissions guidelines. REACH isocyanate and styrene content limits are forcing European reformulation investments.
- Rubber:Natural and synthetic compounds persist in textile printing and legacy press configurations. Indian corrugated plants modernizing fleets are phasing these out in favor of photopolymer durability.
- Metal:Nickel and copper sleeves serve rotary screen hybrid applications and specialty coating operations.
- Composite:Multi-layer constructions combining elastomeric faces with dimensionally stable substrates address high-register flexible packaging demands.
Photopolymer commands the revenue concentration while composite materials expand most quickly in premium flexible packaging.
End User:
Application requirements dictate plate thickness tolerances, mounting systems, and ink compatibility specifications.
- Packaging Industry:Flexible packaging converters in Southeast Asia require finest halftone reproduction for shelf-ready formats displacing rigid alternatives. Brand owners demand pre-certified plate documentation for food-contact migration compliance.
- Corrugated Cardboard:High-volume box production for e-commerce fulfillment centers in India consumes plates at elevated rates per installation. Fleet modernization programs favor digital imaging compatibility.
- Label Printing:Narrow-web operations prioritize rapid changeover and UV-curable ink adhesion.
- Textile Industry:Rotary screen and flexographic hybrid systems process pigment and reactive dyes on synthetic and natural fabrics.
Corrugated cardboard anchors the volume base while flexible packaging gains share at the steepest rate.
Technology:
Customer type separates solvent-free retrofits from legacy installations facing regulatory phase-out timelines.
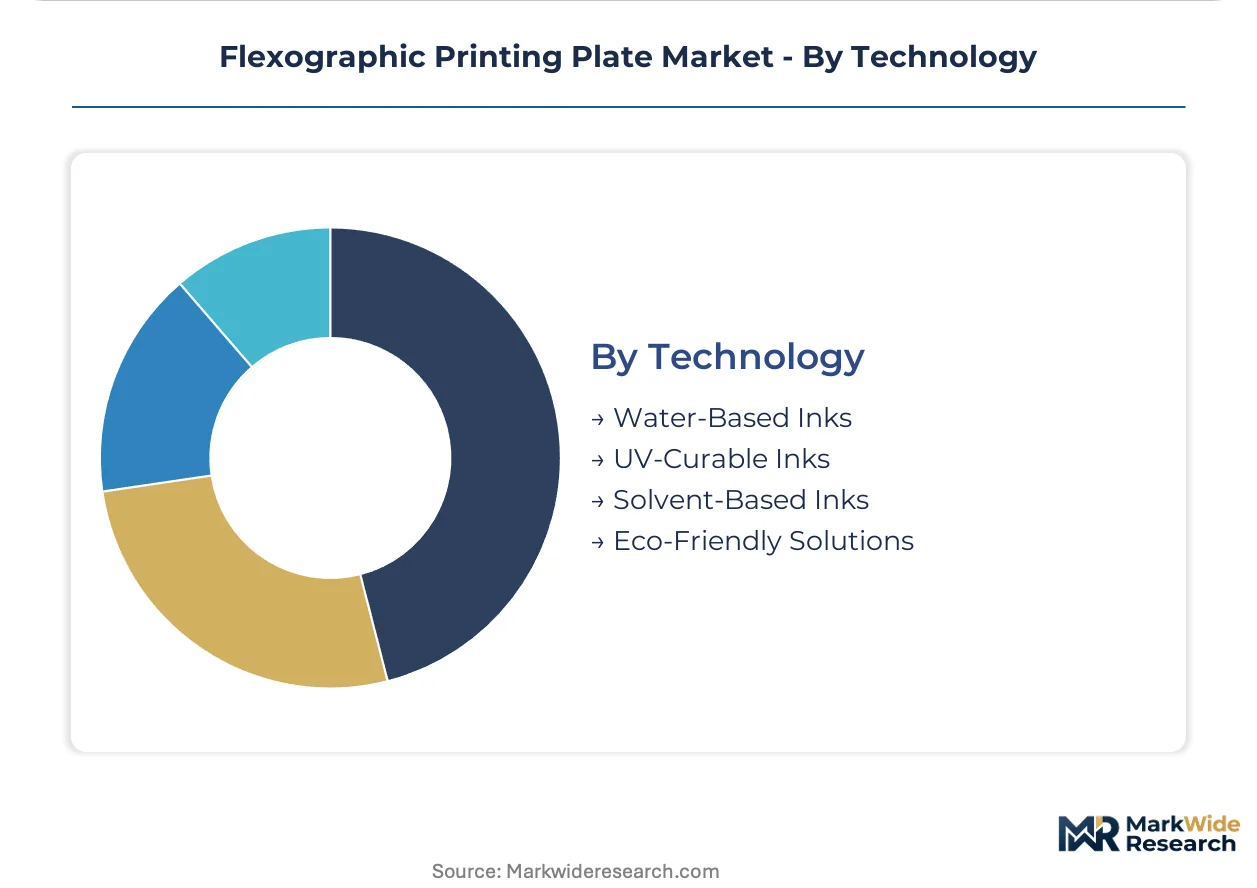
- Water-Based Inks:Compatibility represents the fastest-expanding technology dimension as EPA emissions guidelines and OSHA exposure limits redirect capital toward solvent-free press retrofits. Plate surface energy properties require specific photopolymer formulations.
- UV-Curable Inks:Instant-drying systems dominate label and flexible packaging segments. FDA food-contact notification requirements for plate surface energy properties create service revenue opportunities around migration testing protocols.
- Solvent-Based Inks:Declining share in regulated markets though persisting in industrial packaging applications with less stringent emissions oversight.
- Eco-Friendly Solutions:Bio-based and low-migration ink systems align with EU Green Deal objectives and brand owner sustainability commitments.
Water-based ink compatibility anchors the volume base while eco-friendly solutions gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for photopolymer raw materials concentrates manufacturing investment in chemical-producing economies, while converter demand clusters near packaging-intensive consumption centers. Trade flows show elastomer formulations moving from German and Japanese suppliers toward Indian and Southeast Asian plate fabricators.
United States
Corrugated box plants serving e-commerce fulfillment centers in Ohio and Pennsylvania are modernizing press fleets at accelerated rates. EPA emissions guidelines and OSHA workplace exposure limits are restricting solvent-based plate processing chemistries, redirecting capital toward thermal and water-wash imaging alternatives. The Chicago-Milwaukee corridor hosts concentrated converter operations where FDA food-contact notification requirements drive pre-certification documentation demand.
Germany
Flexible packaging converters in the Baden-Württemberg and Bavaria industrial belts require finest halftone reproduction for shelf-ready formats. ECHA REACH framework governance of isocyanate and styrene content in photopolymer raw materials is compelling reformulation investments from domestic plate suppliers. The Düsseldorf-Cologne chemical cluster anchors photopolymer elastomer production serving European converter demand.
India
Box plants in Maharashtra and Gujarat serving Amazon and Flipkart fulfillment centers are consuming plates at elevated volumes per installation. BIS standards and FSSAI food-contact regulations are tightening material specifications for corrugated applications. The Delhi-NCR industrial belt is witnessing rapid digital imaging equipment deployment as converters shift from rubber to photopolymer durability.
Japan
Specialty label and flexible packaging operations in the Kanto and Kansai regions maintain premium positioning through precision plate specifications. METI industrial standards and PMDA food-contact frameworks govern UV-cured ink system qualifications. The Nagoya-Chubu manufacturing corridor concentrates photopolymer research facilities serving Asian converter technical requirements.
Vietnam
Flexible packaging converters in Ho Chi Minh City and Binh Duong province are displacing rigid alternatives with shelf-ready structures requiring finer halftone reproduction. The country's national chemical regulator is aligning import standards with REACH-equivalent specifications for photopolymer raw materials. The northern Red River Delta industrial zone is attracting plate fabrication investment to serve ASEAN regional demand.
Flexographic Printing Plate Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in chemistry and imaging subsystems. The vendor base separates between consolidated multinational chemical conglomerates controlling photopolymer formulations and fragmented regional plate fabricators serving local converter networks. Three strategic archetypes dominate: captive chemistry suppliers leveraging backward integration into raw materials, equipment-integrated plate vendors bundling imaging systems with consumables contracts, and independent plate specialists competing on changeover speed and technical service density. Competitive moves concentrate on M&A to secure photopolymer formulation capabilities and strategic partnerships to embed plate supply within converter digital workflow contracts.
Among chemistry-integrated conglomerates, DuPont de Nemours and Fujifilm occupy positions where captive material science capabilities anchor margin control across plate formulations. MacDermid Graphics Solutions exemplifies the equipment-chemistry bundling archetype, with its organizational structure reflecting vertical integration into photopolymer production. Toray Industries and Asahi Kasei represent Japanese diversified material science groups where plate products sit within broader elastomer and film portfolios. These archetypes illustrate how competitive positioning depends on controlling either the imaging workflow interface or the underlying photopolymer chemistry specifications.
| Leading Market Players |
|---|
| MacDermid Graphics Solutions |
| Toyobo |
| Toray Industries |
| Esko |
| Fujifilm |
| DuPont de Nemours |
| Asahi Kasei |
| Asahi Photoproducts |
| Kodak |
| Others |
Cost & Logistics Intelligence
REACH isocyanate and styrene content restrictions determine both the three-tier pricing structure across premium, standard, and economy levels and the geographic reconfiguration of photopolymer raw material sourcing. European plate suppliers absorb reformulation costs that compress margins in standard tiers while premium certified grades command spreads justified by pre-certified documentation for food-contact applications.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments against chemistry supply guarantees. Price differentiation rests on certification grade—FDA food-contact notification tiers versus industrial packaging grades—and geographic delivery cost differentials between German-Japanese material sources and Indian-Southeast Asian fabrication points. Cost compression in standard photopolymer grades is intensifying because water-wash and thermal platform capex burdens concentrate procurement leverage among high-volume corrugated converters. Mid-sized label printers exhibit highest price sensitivity due to asset-light leasing exposure, while multinational flexible packaging groups secure least sensitivity through captive chemistry arrangements.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing arrangements between Japanese photopolymer elastomer producers and Indian plate fabricators. Geographic supply concentration centers on Germany, Japan, and the United States for controlled molecular weight distribution photopolymers, with India and Vietnam emerging as fabrication hubs. Raw material dependencies draw from isocyanate precursors, styrene-butadiene elastomers, and LED-UV initiator packages. Single-source vulnerability in specialized flat-top dot exposure equipment creates procurement risk for converters accelerating digital transitions. Distribution runs through regional converter networks anchored by technical service density rather than pure logistics optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among e-commerce fulfillment networks and multinational brand owners that demand pre-certified plate documentation, fragmenting pricing leverage across converter tiers.
For Market Incumbents: Build chemistry-captive moats through backward integration into photopolymer raw material production. DuPont and Fujifilm sustain margin control by anchoring formulations in proprietary elastomer science. Incumbents must defend against equipment-integrated bundling threats from MacDermid by embedding plate supply within digital workflow contracts that span imaging hardware, chemistry, and technical service retainers. Capacity addition in India addresses the steepest demand concentration while insulating against REACH-driven European supply disruption. For New Entrants and Emerging Players: Mid-market corrugated converters in Vietnam and Indonesia represent the most penetrable entry point where fleet modernization outpaces incumbent technical service density. Liquid plate systems for short-run label prototypes offer second white-space targeting where rapid changeover speed justifies premium chemistry positioning. A go-to-market angle emphasizing water-based ink compatibility certification captures EPA-mandated retrofit capital flows without requiring solvent-wash platform legacy infrastructure. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors chemistry-integrated conglomerates over independent plate fabricators. Long-term viability hinges on controlling photopolymer formulation capabilities rather than distribution scale alone. Acquisition target archetypes include regional plate specialists with dense converter relationships in India or Southeast Asia that lack captive material science. The signal to watch is FDA food-contact notification requirement evolution for UV-cured ink systems, which would reshape plate surface energy property valuations and trigger qualification resource reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photopolymer Chemistry | Captive isocyanate and styrene formulation control insulates margin against REACH reformulation cost shocks. |
| Water-Wash Platform Capacity Expansion | EPA emissions guideline compliance redirects solvent-restricted processor capital toward thermal alternatives. |
| Digital Workflow Partnership Embedding | Equipment-chemistry bundling locks mid-sized converters into recurring revenue structures across India. |
| FDA Food-Contact Certification Pre-Investment | Pre-certified plate documentation captures brand owner qualification protocols before competitor compliance. |
| Regional Fabrication Footprint in Vietnam | Binh Duong province proximity to ASEAN flexible packaging demand reduces logistics cost and tariff exposure. |
Research Approach
A standing panel of flexographic press fleet managers, photopolymer chemistry procurement leads, brand owner packaging specification directors, and digital imaging equipment vendors provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews with corrugated box plant engineers in Maharashtra and Gujarat, flexible packaging converters in Ho Chi Minh City, and technical service heads at European plate suppliers generated demand-side and supply-side perspectives. Secondary sources included EPA enforcement guidance documents, ECHA REACH substance restriction updates, FDA food-contact notification databases, and customs trade flow records for photopolymer elastomer imports. Bottom-up plate volume modeling triangulated against top-down packaging industry consumption estimates.
Scenario bracketing around regulatory enforcement intensity and e-commerce fulfillment center expansion pace framed the analytical approach across the projection horizon. Segmentation dimensions encompassed plate format type, material chemistry grade, end-use application, and ink compatibility technology. CAGRs derived from installed base turnover rates, press fleet modernization timelines, and consumables intensity per installation. Industry-specific forecast inputs included BIS standards evolution in India and FSSAI food-contact regulatory tightening for corrugated applications.
Macroeconomic conditions sit as an overlay; deviation in e-commerce fulfillment center construction pace, photopolymer raw material commodity volatility, or multi-jurisdiction regulatory synchronization would shift the trajectory. Forecasts reflect documented assumptions around EPA guideline enforcement consistency and REACH substance restriction implementation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Military and Aerospace Sensors Market
Others
Global Social Networking Market
Others
Conditional Access System (CAS) Market
Others
Middle East Smart Home Market
Others
Delumper Market
Others
Europe Street Lighting Market
Others
Fluid Dispensing Systems Market
Others
Global Pumpkin Candles Market
Others
Liposomes Market
Others
Fresh Pears Market
Others
United States Cigarette Market
Others
Photo Booth/Kiosk Market
Others
Global Optical Comparator Market
Others
Global Healthcare/Medical Simulation Market
Others
Global Active Speaker Market
Others
Buchner Funnels Market