
 Powder Coating Equipment Market | 2026-2036
Powder Coating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Coating Equipment Market Intelligence
Premium electrostatic spray systems and commodity manual units is decoupling on precision, throughput, and total cost of ownership. Nordson Corporation leverages its vertical integration into powder delivery and control systems to command the high-throughput automotive tier. Gema Switzerland GmbH differentiates through precision gun technology and recovery efficiency. WAGNER sustains broad geographic coverage across European job shops and Asian OEM lines.
Powder coating equipment encompasses electrostatic spray guns, curing ovens, recovery booths, and powder feeders designed to apply thermoset or thermoplastic powders to metal substrates at thicknesses typically ranging from 40 to 120 microns, followed by polymerization at 160 to 200 degrees Celsius to form durable, corrosion-resistant finishes. Electrostatic spray guns lead product type revenue due to replacement frequency and technology upgrade cycles among high-volume manufacturers. Automotive parts applications anchor demand volume, while aerospace components represent the fastest-growing application segment driven by coating weight reduction targets and chromate-free regulatory requirements. Job shops and OEMs split the end user base, with OEMs capturing larger per-facility equipment values and job shops driving unit volume through fragmented, price-sensitive procurement.
EPA emission standards and REACH chemical restrictions in the United States and Europe are systematically constraining liquid coating alternatives and redirecting capital toward powder systems. China's GB standards and MEE enforcement on industrial emissions are accelerating domestic equipment upgrades and import substitution. India's BIS certification requirements and PLI scheme incentives for manufacturing competitiveness are expanding the addressable base for mid-tier oven and gun suppliers. Stakeholders must monitor regulatory divergence between jurisdictions and align product certification roadmaps accordingly.
Market Dynamics
Automotive OEMs in Germany and the United States are consolidating coating line procurement around single-source automation vendors, compressing supplier margins while elevating technical certification barriers for mid-tier equipment providers.
Growth Catalysts
- REACH chemical restrictions:ECHA's tightening VOC emission limits are systematically disqualifying solvent-based liquid coating systems across European automotive supply chains.
- China's industrial clusters:Concentrated manufacturing zones around Shanghai and Guangzhou are driving replacement demand for high-throughput electrostatic spray systems.
- Chromate-free aerospace mandates:Boeing and Airbus supplier specifications are redirecting capital toward powder systems capable of meeting coating weight reduction targets.
Market Restraints
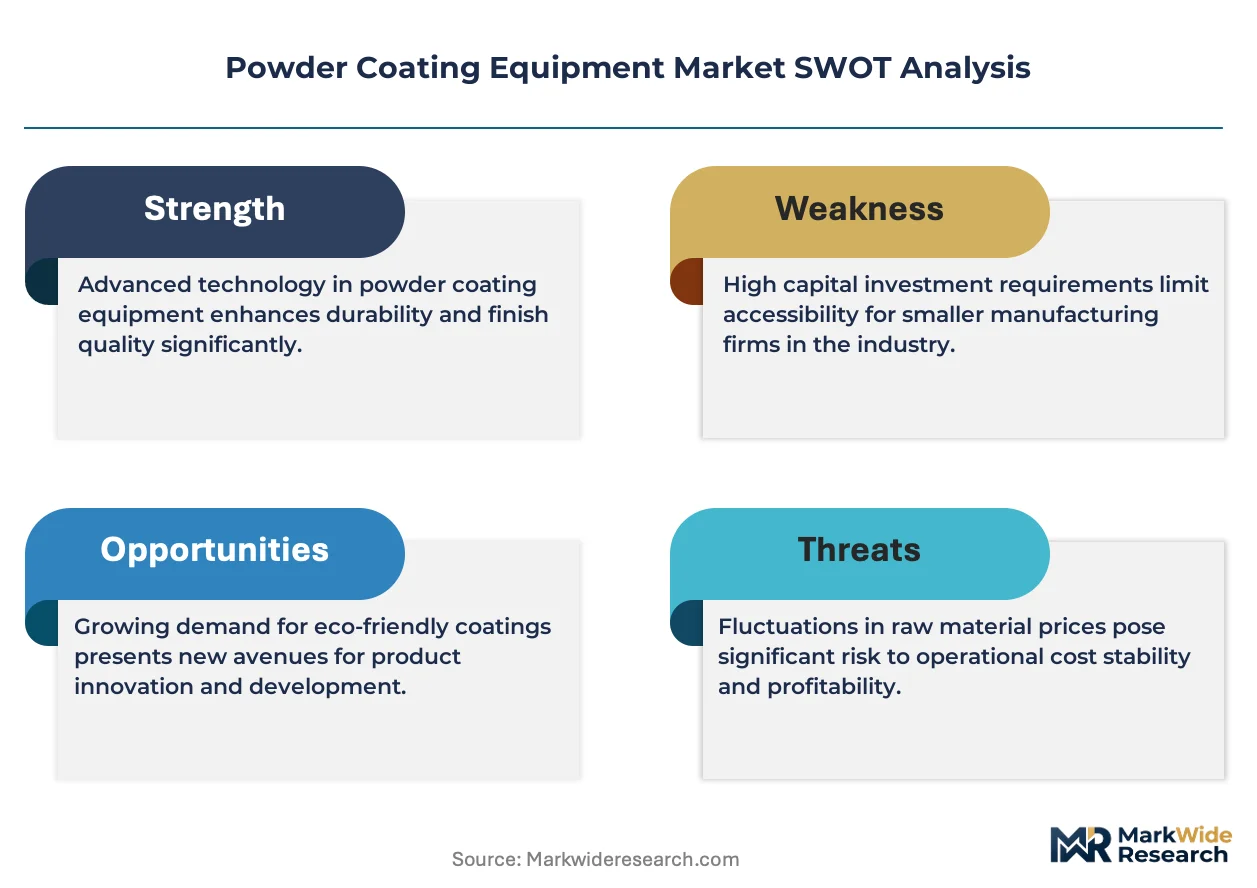
- Specialized powder resin supply:Concentration among three European chemical suppliers creates input cost volatility for equipment-dependent coating operations.
- Curing oven energy intensity:Natural gas price exposure in German and Italian manufacturing regions compresses operating margins for heat-dependent polymerization stages.
- Thin-film liquid coating substitution:Advanced waterborne systems are recapturing share in decorative appliance applications where powder thickness limits design flexibility.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for manufacturing competitiveness are expanding the addressable base for mid-tier oven and gun suppliers in Maharashtra and Tamil Nadu.
- Digital twin integration:Convergence of IoT sensors and predictive maintenance software is enabling outcome-based service contracts for high-value curing equipment.
- Job shop consolidation:Fragmented European metal finishers are creating demand for standardized, quick-changeover systems that reduce color-switching downtime.
Industry Challenges
- Electrostatic application expertise:Shortage of technicians trained in Faraday cage effect mitigation and gun-to-part distance optimization limits operational efficiency gains.
- Legacy oven retrofit compatibility:Integration complexity with existing convection and infrared curing infrastructure delays technology upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Coating Equipment Market |
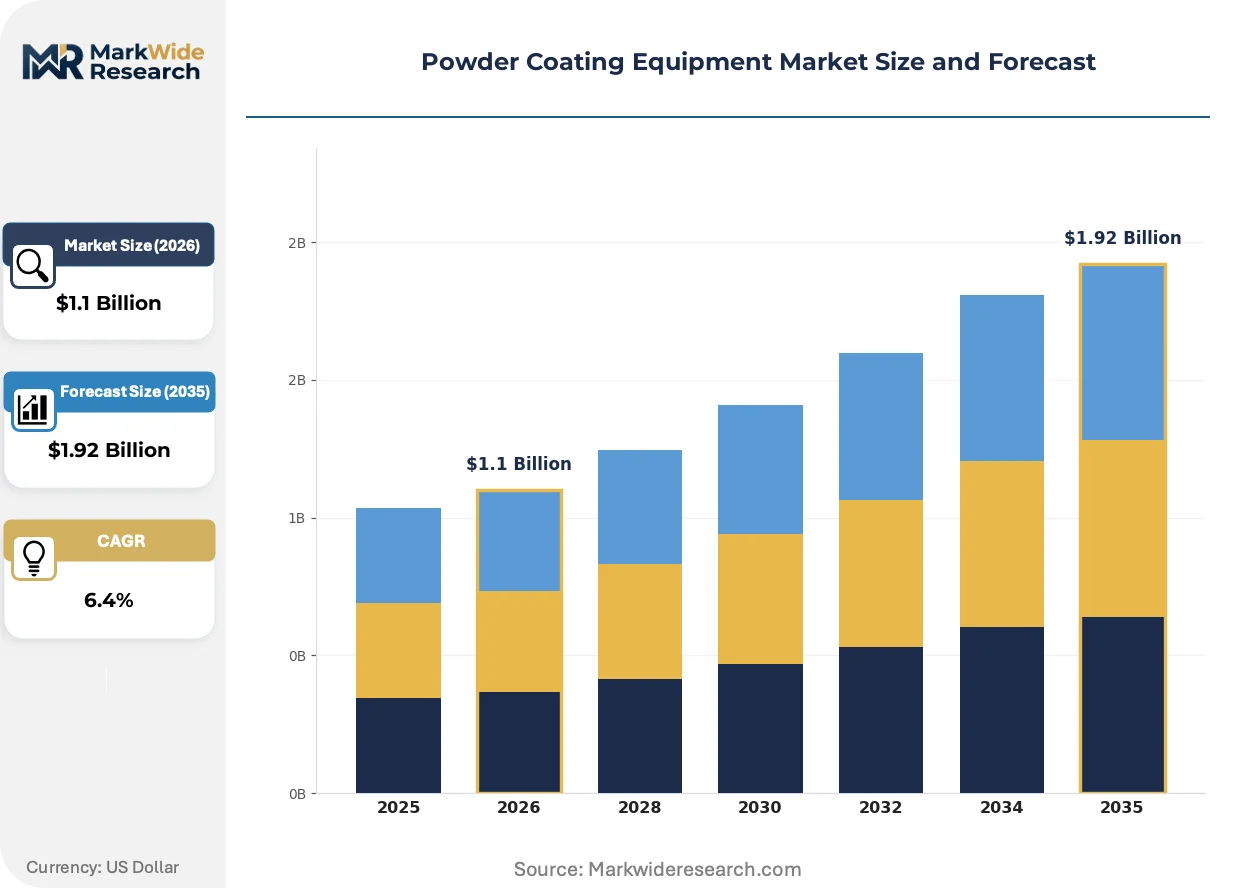
| Market Size in 2026 | $1.1 Billion |
| Market Size in 2035 | $1.92 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic Spray Guns, Ovens, Recovery Booths, Powder Feeders Application: Automotive Parts, Appliances, Furniture, Aerospace Components Technology: Electrostatic, Tribo, Hybrid, Manual End User: Manufacturers, Job Shops, OEMs, Aftermarket Providers |
| Companies Covered | Nordson Corporation, Gema Switzerland GmbH, WAGNER, Hangzhou Color Powder Coating Equipment Co., Ltd., Mitsuba Systems Pvt. Ltd., Eastwood Company, Oven Empire Manufacturing, Dürr, ANEST IWATA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Coating Equipment Market Strategic Shifts & Innovations
Real-time process control systems are compressing quality variance windows while enabling predictive maintenance models that unbundle traditional equipment-service relationships.
Advanced powder recovery systems with closed-loop sieving and color-change automation are integrating into high-mix production environments. Tier-one automotive suppliers in Stuttgart and Detroit are deploying these units to support just-in-sequence coating operations. The technology is integrating quality data streams directly into MES platforms, reducing first-pass defect rates and compressing rework labor costs.
EPA emission standards under the Clean Air Act are constraining liquid coating alternatives at metal fabrication facilities across Ohio and Michigan. The regulatory pressure is redirecting capital expenditure toward powder system conversions among mid-sized stampers and extruders. Job shops serving construction and agricultural equipment OEMs represent the most affected segment, with procurement teams prioritizing EPA-compliant system configurations.
Buyer concentration among automotive tier-one suppliers is compressing vendor negotiation cycles and elevating total cost of ownership analytics in equipment selection. European coating service providers are responding by unbundling after-sales service contracts from initial hardware purchases. German and Austrian job shops demonstrate the most pronounced shift, with procurement teams demanding performance-guaranteed maintenance agreements tied to uptime metrics.
Powder Coating Equipment Market Segmentation
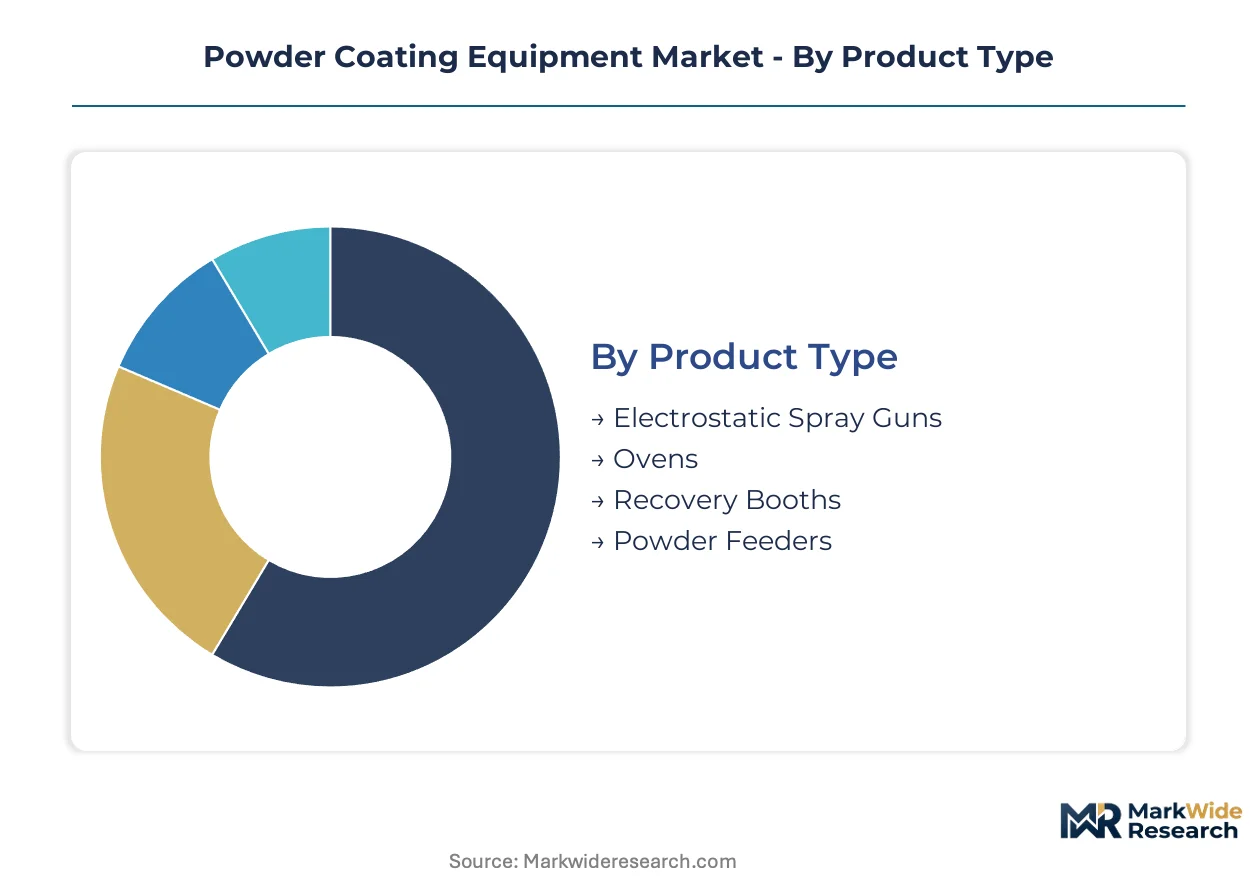
Powder coating equipment segmentation reveals divergent capital requirements across product categories, with curing infrastructure demanding the heaviest upfront outlays while application tools generate recurring replacement revenue. Application mix and technology choices further stratify procurement patterns between high-volume automotive lines and flexible job shop environments.
Product Type:
Capital intensity varies sharply across equipment categories, with curing ovens requiring substantial facility integration and electrostatic spray guns presenting lower barrier-to-entry replacement cycles.
- Electrostatic Spray Guns:Corona-charging or triboelectric systems apply powder particles through controlled electrostatic fields at 60-100 kV, with gun-to-part distance and Faraday cage management determining transfer efficiency. German and United States automotive parts manufacturers concentrate replacement demand here, driven by EPA emission compliance deadlines and color-change throughput requirements. Electrostatic spray guns absorb the bulk of installed capacity; recovery booths are expanding most quickly.
- Ovens:Convection, infrared, or hybrid curing systems polymerize thermoset powders at sustained temperatures, with natural gas or electric heating configurations determining operating cost profiles. Italian and German manufacturers face margin compression from energy price volatility, slowing upgrade cycles despite regulatory pressure.
- Recovery Booths:Cyclone and cartridge filtration systems capture overspray powder for reuse, with closed-loop sieving and color-change automation reducing material waste in high-mix environments.
- Powder Feeders:Fluidized bed or box-fed delivery systems maintain consistent powder flow to spray guns, with vibration control and moisture management determining coating uniformity.
Electrostatic spray guns absorb the bulk of installed capacity; recovery booths are expanding most quickly.
Application:
Application segmentation tracks divergent performance specifications, with aerospace weight reduction mandates and automotive corrosion resistance standards driving distinct equipment configurations.
- Automotive Parts:Chassis, wheel, and underhood components require 80-120 micron film builds with salt-spray corrosion resistance exceeding 1,000 hours. Stuttgart and Detroit tier-one suppliers anchor procurement volume, consolidating around single-source automation vendors.
- Aerospace Components:Boeing and Airbus supplier specifications demand chromate-free finishes below 50 microns to meet coating weight reduction targets, redirecting capital toward precision electrostatic systems capable of thin-film consistency.
- Appliances:Decorative refrigerator and washer panels prioritize color uniformity and scratch resistance, though advanced waterborne liquid coatings are recapturing share where design flexibility outweighs durability requirements.
- Furniture:Metal office and outdoor furniture applications emphasize UV resistance and edge coverage, with job shops in China's Guangzhou cluster driving fragmented, price-sensitive procurement.
Automotive parts anchor procurement volume; aerospace components are climbing the fastest.
Technology:
Technology selection hinges on substrate geometry complexity and powder resin chemistry, with Faraday cage penetration challenges favoring triboelectric approaches for recessed cavities.
- Electrostatic:Corona-charging dominates high-volume lines through superior transfer efficiency on flat-to-modest geometries, with voltage modulation and pattern air control enabling film build precision.
- Tribo:Friction-charging systems excel on complex recessed parts where corona guns suffer Faraday cage effects, penetrating deep cavities in automotive wheels and aerospace structural components.
- Hybrid:Combined corona-tribo configurations optimize coverage across varied part geometries within single coating cycles.
- Manual:Handheld gun systems serve low-volume job shops and touch-up operations, with limited automation integration compressing per-unit labor productivity.
Electrostatic systems command the largest installed base; tribo configurations are gaining share fastest in aerospace applications.
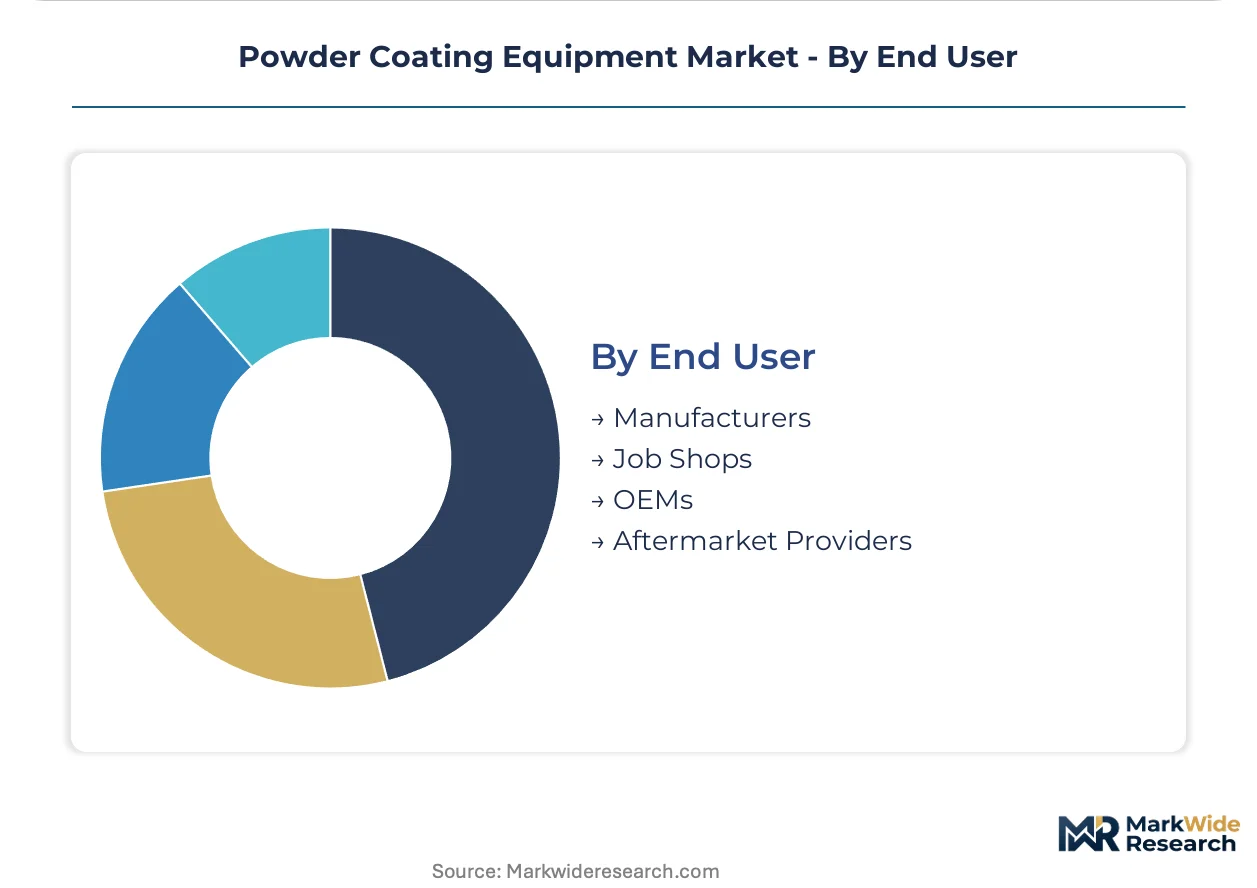
End User:
End user structure splits between capital-concentrated OEM lines and volume-fragmented job shops, with procurement sophistication and service contract expectations diverging accordingly.
- Manufacturers:In-house coating operations at metal stampers and extruders prioritize throughput consistency and regulatory compliance, with EPA Clean Air Act constraints redirecting capital from liquid conversions in Ohio and Michigan.
- Job Shops:Independent coating service providers across European and Asian markets drive unit volume through fragmented procurement, with German and Austrian operators demanding performance-guaranteed maintenance agreements tied to uptime metrics.
- OEMs:Original equipment manufacturers capture larger per-facility equipment values through integrated coating line procurement, compressing vendor negotiation cycles and elevating total cost of ownership analytics.
- Aftermarket Providers:Refinishing and repair operations require portable or compact systems with rapid color-change capability, serving construction and agricultural equipment segments.
OEMs concentrate the highest per-facility equipment values; job shops are expanding most quickly in India's Maharashtra and Tamil Nadu manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the powder coating equipment landscape through its dense automotive supplier ecosystem and MEE enforcement corridors. Germany's Stuttgart region and Detroit in the United States concentrate high-throughput line demand. Industrial clusters in Guangzhou, northern Italy, and western India are accelerating procurement cycles.
United States
Automotive tier-one suppliers in Detroit and Ohio are consolidating coating line procurement around automation vendors. EPA Clean Air Act emission standards are constraining liquid coating alternatives at metal fabrication facilities. Michigan and Ohio job shops serving construction equipment OEMs represent the most affected procurement segment.
Germany
Stuttgart-based automotive parts manufacturers are expanding automated coating lines for chassis and wheel components. REACH chemical restrictions from ECHA are systematically disqualifying solvent-based liquid systems across European supply chains. Bavarian and North Rhine-Westphalian industrial zones are driving replacement demand for precision electrostatic systems.
China
Shanghai and Guangzhou industrial clusters are driving replacement demand for high-throughput electrostatic spray systems. GB standards and MEE enforcement on industrial emissions are accelerating domestic equipment upgrades. Pearl River Delta metal finishers are prioritizing import substitution for mid-tier oven and gun suppliers.
India
Maharashtra and Tamil Nadu manufacturing corridors are expanding the addressable base for mid-tier equipment suppliers. BIS certification requirements and PLI scheme incentives for manufacturing competitiveness are redirecting capital toward powder system conversions. Pune-based automotive stampers are consolidating procurement around standardized quick-changeover configurations.
Italy
Northern Italian manufacturers face margin compression from natural gas price exposure in curing operations. CE marking and EU Green Deal compliance requirements are elevating technical certification barriers for equipment providers. Lombardy and Veneto job shops are demanding performance-guaranteed maintenance agreements tied to uptime metrics.
Powder Coating Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the powder coating equipment landscape. The market structure tilts toward consolidation at the high-throughput automotive tier while fragmenting across price-sensitive job shop segments. Three archetypes dominate: vertically integrated automation vendors, precision gun technology specialists, and broad-coverage regional fabricators. Competitive moves center on backward integration into powder delivery systems and geographic expansion through distributor networks.
Among Swiss and German precision specialists, Gema Switzerland GmbH and Dürr occupy positions emphasizing gun technology and system integration respectively. Nordson Corporation anchors the North American tier through its control over upstream powder delivery components. Chinese fabricators including Hangzhou Color Powder Coating Equipment Co., Ltd. exemplify the mid-tier oven and gun supplier archetype serving fragmented Asian demand. These three archetypes—precision European engineering, North American vertical integration, and Asian volume fabrication—structure competitive positioning across procurement segments.
| Leading Market Players |
|---|
| Nordson Corporation |
| Gema Switzerland GmbH |
| WAGNER |
| Hangzhou Color Powder Coating Equipment Co., Ltd. |
| Mitsuba Systems Pvt. Ltd. |
| Eastwood Company |
| Oven Empire Manufacturing |
| Dürr |
| ANEST IWATA Corporation |
| Others |
Cost & Logistics Intelligence
Tier-one automotive suppliers in Stuttgart and Detroit anchor procurement volume, compressing vendor negotiation cycles and elevating total cost of ownership analytics as the dominant pricing model across powder coating equipment categories.
Pricing Analysis
Value-based pricing anchored to throughput guarantees and uptime metrics dominates high-throughput automotive lines, while job shops negotiate per-unit transactional structures. Price differentiation hinges on CE marking certification tiers and after-sales service bundling, with German and Austrian operators demanding performance-guaranteed maintenance agreements. Cost compression in mid-tier oven and gun segments is intensifying because of import substitution pressures from Chinese fabricators. Job shops in China's Guangzhou cluster exhibit the highest price sensitivity, whereas aerospace tier-one suppliers demonstrate the lowest due to chromate-free regulatory compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with European chemical suppliers for specialized powder resins, creating input cost volatility for equipment-dependent coating operations. Manufacturing concentration centers on Germany, China, and the United States for precision electrostatic systems and curing infrastructure. Component dependencies include high-voltage power supplies, precision spray nozzles, and natural gas-fired heating elements. Tariff exposure on steel and aluminum inputs from German and Italian fabrication zones elevates landed cost uncertainty. Distribution runs through authorized distributor networks for European precision specialists and direct OEM relationships for North American vertical integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powder coating equipment represents a vertical-integration race, with competitive advantage accruing to players capturing upstream control over powder delivery systems and downstream service contract revenue streams.
For Market Incumbents: To counter margin compression from Chinese mid-tier fabricators, Nordson Corporation and Gema Switzerland GmbH should deepen backward integration into powder delivery components and predictive maintenance software stacks. CE marking and EPA certification investments will elevate technical barriers against price-competitive entrants. For New Entrants and Emerging Players: Enter via India's Maharashtra and Tamil Nadu manufacturing corridors, where PLI scheme incentives and BIS certification requirements have expanded the addressable base for standardized quick-changeover oven and gun configurations. Pune-based automotive stampers present the most penetrable segment for mid-tier suppliers offering performance-guaranteed uptime contracts. For Investors and Strategic Acquirers: The window for entry favors precision gun technology specialists with aerospace chromate-free certification and IoT-enabled predictive maintenance capabilities. Long-term viability rests on outcome-based service contract penetration rather than hardware margins alone. The signal to watch is consolidation velocity among European job shops demanding standardized color-change automation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Delivery Systems | Nordson Corporation's captive supply of control components locks in automotive tier-one procurement cycles. |
| Predictive Maintenance Software Development | Real-time IoT sensor integration enables outcome-based service contracts tied to curing oven uptime metrics. |
| Chromate-Free Aerospace Certification | Boeing and Airbus supplier specifications redirect capital toward precision electrostatic systems meeting coating weight targets. |
| Quick-Changeover System Standardization | Fragmented European metal finishers create demand for color-switching automation reducing production downtime. |
| Geographic Expansion via Distributor Networks | WAGNER sustains broad coverage across Asian OEM lines and European job shops through channel partnerships. |
Research Approach
SEC 10-K filings, ECHA REACH regulatory databases, and customs trade records formed the secondary backbone, supplemented by primary interviews with plant engineers at automotive tier-one suppliers, coating line procurement managers, aftermarket service heads, and technical R&D directors at powder resin manufacturers. Bottom-up equipment shipment data and top-down industrial capex forecasts were triangulated to validate market sizing across the analysis window.
Historical trendline analysis of electrostatic spray gun replacement cycles and curing oven upgrade patterns informed the projection framework. Segmentation dimensions modeled include product type, application vertical, technology configuration, and end-user procurement sophistication. CAGRs were derived from regression analysis of capital expenditure trajectories, with specific inputs from EPA Clean Air Act compliance deadlines and China's MEE enforcement corridors on industrial emissions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas price volatility in German and Italian manufacturing regions and potential thin-film liquid coating substitution in decorative appliance segments. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and automotive production stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
India Foundry Market
Others
Augmented Reality in Energy and Utilities Market
Others
South Korea Automotive LED Lighting Market
Others
5G Enabled Healthcare Services Market
Others
Military Image Intensifier Market
Others
Cloud-Based Streaming Services Market
Others
Vegan Confectionery Market
Others
Europe Video Encoder Market
Others
Belt Press Filter Market
Others
Surface Green Mining Market
Others
Gym Wipes Market
Others
Global Phablets and Superphones Market
Others
Cashew Kernel Market
Others
Boston Round Bottle Market
Others
Wearable AI Market
Others
Vacuum Evaporators Market