
 Floor Cleaning and Mopping Machine Market | 2026-2036
Floor Cleaning and Mopping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Cleaning and Mopping Machine Market Intelligence
ISO 9001 quality management certification is redrawing supplier eligibility for institutional procurement contracts. Tennant Company leverages its North American service network to sustain aftermarket revenue streams. Alfred Kärcher SE & Co. KG anchors European production scale with integrated component manufacturing. Nilfisk Group competes through robotic automation specialization in warehouse deployments.
Floor cleaning and mopping machines encompass powered and unpowered equipment designed for surface debris removal, utilizing brush mechanisms, sorbent materials, or pressurized steam operating at 120-180 degrees Fahrenheit for sanitization in commercial and industrial environments. Automatic scrubbers dominate capital expenditure flows among facility management firms due to labor substitution economics. Battery-powered technology captures the fastest upgrade cycle as lithium-ion chemistry extends runtime beyond eight hours for third-shift operations. Robotic systems concentrate margin pools in transport hubs where 24-hour operational windows justify premium automation spend.
OSHA workplace safety standards and EPA water discharge regulations shape equipment specifications for chemical recovery systems and noise thresholds in U.S. manufacturing units. CE marking under the EU Machinery Directive gates market access for European commercial spaces and hospitality venues. Stakeholders must monitor battery chemistry certification shifts and autonomous navigation liability frameworks as procurement criteria evolve beyond cleaning efficacy toward total cost of ownership verification.
Market Dynamics
Battery chemistry advancement is bifurcating procurement criteria between runtime-optimized lithium-ion fleets and legacy lead-acid replacement cycles, forcing facility managers to recalculate total cost of ownership around energy density rather than upfront capital expenditure.
Growth Catalysts
- OSHA workplace safety mandates:Stricter noise threshold enforcement in U.S. manufacturing plants accelerates demand for low-decibel scrubber models that protect worker hearing during extended cleaning shifts.
- Third-shift airport operations:Twenty-four-hour terminal maintenance windows in Dubai and Singapore justify premium automation spend on robotic systems that navigate passenger flows without operational disruption.
- Steam sanitization protocols:Pressurized systems operating at 120-180 degrees Fahrenheit penetrate healthcare and hospitality sectors where chemical-free disinfection meets infection control standards.
Market Restraints
- Lithium-ion raw material volatility:Cobalt and nickel price swings compress margin stability for battery-powered unit manufacturers dependent on cylindrical cell supply chains.
- German component concentration:Brush motor and squeegee assemblies cluster around Stuttgart industrial corridors, exposing procurement timelines to single-region logistics bottlenecks.
- Corded unit infrastructure lock-in:Existing electrical outlet density in aging U.S. school districts and municipal buildings delays battery conversion capex cycles beyond optimal replacement windows.
Strategic Opportunities
- India hospitality expansion:Luxury hotel construction in Mumbai and Bangalore creates first-mover advantage for automated cleaning fleet vendors establishing local service networks.
- EU Green Deal procurement incentives:Public sector tender scoring now weights energy recovery systems and water recycling capabilities, favoring equipment with closed-loop chemical recovery.
- Autonomous navigation convergence:LiDAR and computer vision integration enables robotic scrubbers to share facility maps with security and HVAC systems, unlocking building management system integration contracts.
Industry Challenges
- ISO 9001 certification timelines:Supplier qualification documentation for institutional procurement contracts extends sales cycles by six to twelve months as auditors verify quality management system compliance.
- Legacy fleet interoperability:Battery voltage mismatches between manufacturer-specific platforms prevent standardized charging infrastructure deployment across mixed-vendor cleaning operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Cleaning and Mopping Machine Market |
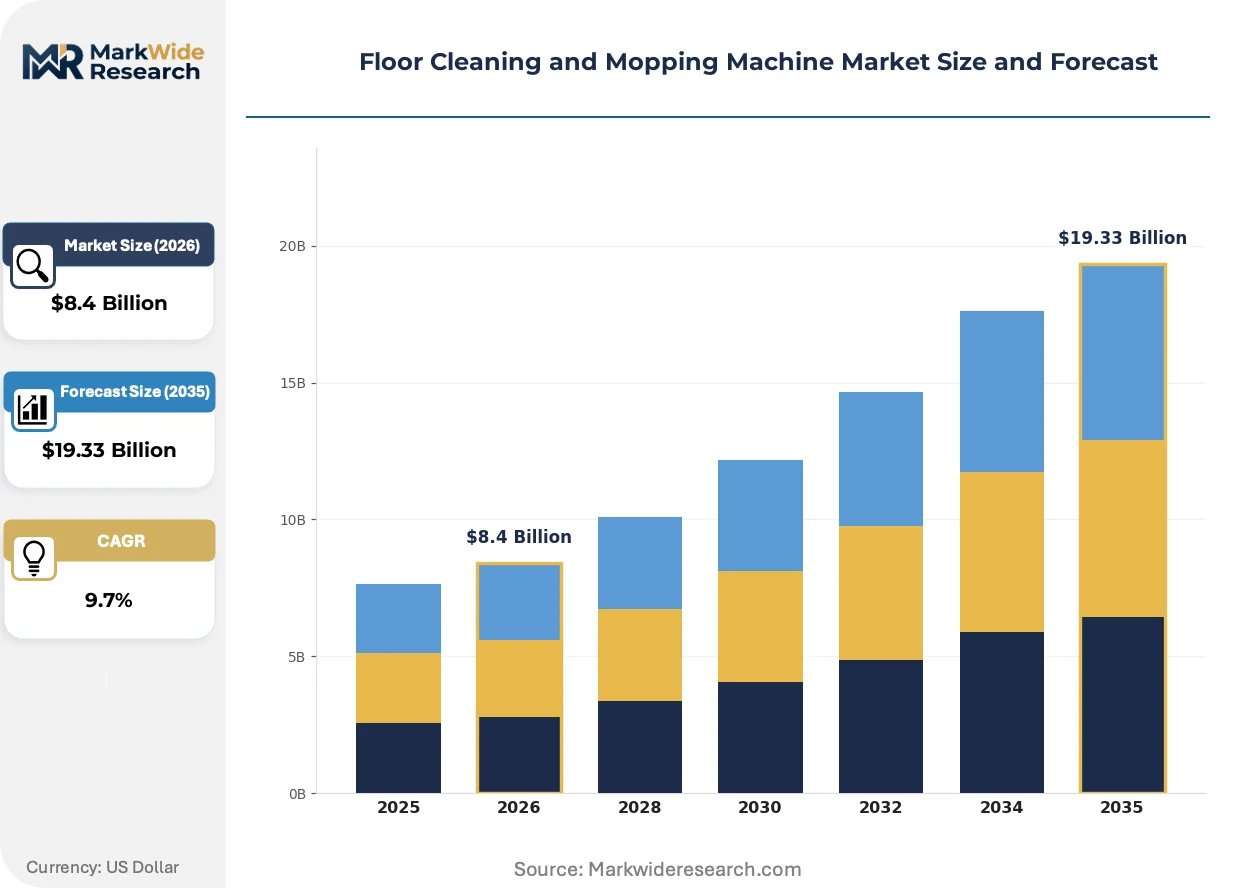
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Scrubbers, Wet Mops, Dry Mops, Steam Cleaners, Microfiber Machines Technology: Battery Powered, Corded Electric, Robotic, Manual, Ultrasonic Application: Commercial Spaces, Educational Facilities, Hospitality Venues, Transport Hubs, Manufacturing Units End User: Janitorial Services, Facility Management Firms, Warehousing, Public Venues, Government Buildings |
| Companies Covered | Nilfisk Group, Tennant Company, Alfred Kärcher SE & Co. KG, Hako GmbH, Comac, Taski, Factory Cat, Viper, Clarke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Cleaning and Mopping Machine Market Strategic Shifts & Innovations
Equipment functionality is splitting along operational intensity lines, with premium automation targeting continuous-use environments while simplified mechanics serve intermittent cleaning schedules. This divergence reshapes how manufacturers allocate R&D resources and field service capacity.
Lithium-ion battery chemistry is bifurcating the installed base between runtime-optimized fleets and legacy lead-acid replacement cycles. Airport terminal operators in Las Vegas and Dubai adopt eight-hour continuous-run configurations for overnight maintenance windows. The technology is bifurcating vendor revenue models toward battery-as-a-service subscriptions rather than transactional equipment sales.
CE marking under the EU Machinery Directive now mandates autonomous navigation safety certifications for robotic units deployed in commercial spaces. Manufacturers must document emergency stop protocols and collision avoidance validation to maintain European market access. Warehouse operators in Germany and the Netherlands restructure procurement teams to integrate compliance documentation into capital expenditure approvals.
Service contract unbundling disrupts traditional distributor relationships as large facility management firms bring preventive maintenance in-house. Third-party logistics providers in North America now offer certified technician training programs that bypass original equipment manufacturer service networks. Hospital systems in Texas and California pilot this model to reduce downtime penalties during critical infection control periods.
Floor Cleaning and Mopping Machine Market Segmentation
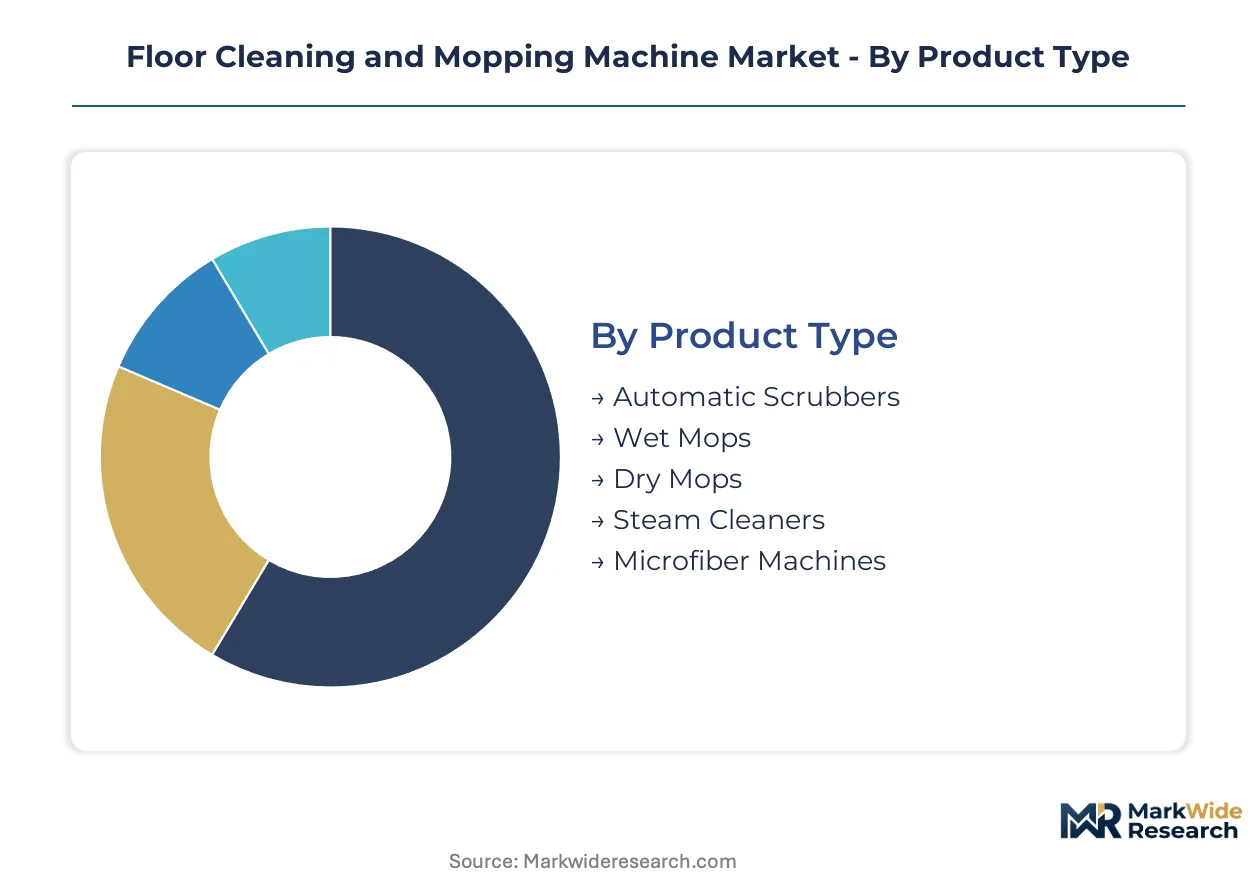
Floor cleaning equipment procurement splits along operational intensity and capital deployment timelines. Facility managers weight runtime economics against upfront investment differently across venue types. This segmentation captures where procurement criteria diverge and where standardization pressures converge.
Product Type:
Domestic demand clusters around automatic scrubbers in Germany and the United States, while steam cleaner exports concentrate in Italian and Chinese manufacturing corridors. Wet mop assemblies serve price-sensitive developing markets through Southeast Asian contract manufacturers.
- Automatic Scrubbers:Brush-and-squeegee systems with integrated solution tanks dominate capital expenditure flows among facility management firms. Third-shift airport terminals in Dubai and Singapore deploy these units for continuous runtime exceeding eight hours, driven by lithium-ion battery substitution economics that displace corded infrastructure.
- Steam Cleaners:Pressurized systems operating at 120-180 degrees Fahrenheit penetrate healthcare and hospitality sectors where chemical-free disinfection meets infection control standards. German hospitals and Las Vegas casino properties specify these units for sanitization protocols under stricter hygiene mandates.
- Wet Mops:Absorbent fiber assemblies with wringer mechanisms serve intermittent cleaning schedules in aging U.S. school districts where battery conversion capex cycles face budget constraints.
- Dry Mops:Electrostatic dust-retention systems target pre-cleaning workflows in electronics manufacturing cleanrooms across Japan and South Korea.
- Microfiber Machines:Low-moisture systems with reusable pad assemblies align with EU Green Deal procurement incentives for water recycling capabilities in Dutch and Danish public sector tenders.
Automatic scrubbers command the established base. The steepest expansion runs through steam cleaners.
Technology:
Cost tier stratification separates premium automation from mechanical alternatives, with battery chemistry advancement forcing recalculation of total cost of ownership around energy density metrics rather than upfront capital expenditure.
- Battery Powered:Lithium-ion configurations with cylindrical cell architectures capture the fastest upgrade cycle as runtime extends beyond eight hours. Airport terminal operators in Las Vegas and Dubai adopt these for overnight maintenance windows, though cobalt and nickel price swings compress margin stability for dependent manufacturers.
- Robotic:LiDAR-equipped units with autonomous navigation certifications concentrate margin pools in transport hubs where 24-hour operational windows justify premium automation spend. CE marking under the EU Machinery Directive now mandates emergency stop protocol documentation for European commercial space deployment.
- Corded Electric:AC-powered motors with tethered operation persist in aging U.S. municipal buildings where electrical outlet density delays conversion timelines.
- Manual:Unpowered push systems with mechanical brush drives serve intermittent schedules in Indian and Brazilian hospitality properties with limited capital equipment budgets.
- Ultrasonic:High-frequency vibration systems target precision cleaning in Swiss and German pharmaceutical manufacturing facilities where residue elimination requirements exceed mechanical abrasion capabilities.
Corded electric retains the installed base volume. Robotic systems are climbing the fastest on per-unit value expansion.
Application:
Volume concentration varies sharply by venue operational windows, with continuous-use environments justifying automation premiums while intermittent schedules favor simplified mechanics.
- Transport Hubs:Twenty-four-hour terminal maintenance operations in Singapore Changi and Dubai International justify robotic fleet deployment with passenger flow navigation capabilities. OSHA workplace safety mandates on noise thresholds accelerate demand for low-decibel scrubber models protecting worker hearing during extended shifts.
- Hospitality Venues:Luxury hotel properties in Las Vegas and Mumbai expand automated cleaning fleets to meet stricter hygiene protocols, with steam sanitization systems penetrating infection control workflows.
- Commercial Spaces:Office complexes and retail centers in German urban corridors specify energy recovery systems under EU Green Deal procurement scoring weights.
- Educational Facilities:K-12 districts and university campuses across Texas and California face infrastructure lock-in from aging electrical systems that delay battery conversion cycles.
- Manufacturing Units:U.S. industrial plants under EPA water discharge regulations specify chemical recovery systems for compliant effluent management.
Commercial spaces command the broadest installed base. Transport hubs are gaining share fastest on automation premium capture.
End User:
Customer type determines service contract structure, with large facility management firms unbundling preventive maintenance from original equipment manufacturer networks while smaller operators remain distributor-dependent.
- Facility Management Firms:Integrated service providers with multi-site contracts bring technician training in-house, bypassing OEM service networks through third-party logistics certification programs. Hospital systems in Texas and California pilot this model to reduce downtime penalties during critical infection control periods.
- Janitorial Services:Contract cleaning operators with thin margins favor wet mop and manual technology segments where capital deployment remains minimal and labor substitution economics prove unfavorable.
- Warehousing:Third-party logistics operators in the Netherlands and Germany restructure procurement teams to integrate CE marking compliance documentation into capital expenditure approvals for robotic units.
- Public Venues:Stadium and convention center operators in the United Kingdom and Australia specify runtime-optimized battery fleets for event-driven cleaning windows with compressed turnaround timelines.
- Government Buildings:Federal and municipal facilities face extended ISO 9001 certification timelines that extend sales cycles by six to twelve months as auditors verify quality management system compliance.
Janitorial services command the unit volume base. Facility management firms are expanding fastest on contract value consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal procurement incentives redirect institutional spending toward equipment with closed-loop chemical recovery and water recycling capabilities. Facility managers in Germany and the Netherlands restructure capital expenditure approvals to integrate compliance documentation. Battery chemistry certification shifts and autonomous navigation liability frameworks now shape vendor selection beyond cleaning efficacy metrics.
United States
Third-shift airport operations in Las Vegas and Dallas-Fort Worth justify premium automation spend on robotic systems with passenger flow navigation. OSHA workplace safety mandates enforce stricter noise thresholds in manufacturing plants, accelerating demand for low-decibel scrubber models. EPA water discharge regulations in Texas and California specify chemical recovery systems for compliant effluent management in industrial facilities.
Germany
CE marking under the EU Machinery Directive gates market access for commercial spaces and hospitality venues across Stuttgart and Hamburg industrial corridors. Brush motor and squeegee assembly manufacturing clusters around Baden-Württemberg expose procurement timelines to single-region logistics dependencies. Kärcher and Hako anchor European production scale with integrated component manufacturing and export capacity.
India
Luxury hotel construction in Mumbai and Bangalore creates first-mover advantage for automated cleaning fleet vendors establishing local service networks. BIS certification requirements for electrical equipment extend supplier qualification timelines in institutional procurement. Janitorial services in Maharashtra and Karnataka favor wet mop segments where capital deployment remains minimal and labor substitution economics prove unfavorable.
United Arab Emirates
Hospitality venues in Dubai expand automated cleaning fleets to meet stricter hygiene protocols under MOHAP infection control standards. Twenty-four-hour terminal maintenance windows at Dubai International justify eight-hour continuous-run battery configurations for overnight operations. Procurement teams prioritize runtime-optimized lithium-ion fleets over legacy lead-acid replacement cycles in new construction projects.
China
Dual carbon goals under MIIT guidance accelerate battery-powered technology displacement of corded units in airport terminals across Beijing and Shanghai. GB standards for electrical safety shape equipment specifications for chemical recovery systems in manufacturing zones. Contract manufacturers in Guangdong and Zhejiang concentrate wet mop assembly exports to price-sensitive developing markets in Southeast Asia.
Floor Cleaning and Mopping Machine Market Key Industry Players
Player mix skews toward integrated European manufacturers with captive component production and North American service network operators. Market structure concentrates around three to five dominant firms with established certification portfolios, while mid-tier specialists compete on regional price positioning. Strategic archetypes include full-line automation providers, battery-technology-integrated fabricators, and service-contract unbundlers. Competitive moves center on geographic expansion through distributor acquisition and vertical integration into brush motor and squeegee assembly production.
Among Germany-based integrated manufacturers, Alfred Kärcher SE & Co. KG and Hako GmbH occupy positions exemplifying the captive supply archetype with in-house component production. Tennant Company represents the North American service-network model, leveraging aftermarket revenue streams through certified technician coverage. Nilfisk Group sits within the robotic automation specialization tier, competing through LiDAR-equipped autonomous navigation systems for warehouse deployments.
| Leading Market Players |
|---|
| Nilfisk Group |
| Tennant Company |
| Alfred Kärcher SE & Co. KG |
| Hako GmbH |
| Comac |
| Taski |
| Factory Cat |
| Viper |
| Clarke |
| Others |
Cost & Logistics Intelligence
Lithium-ion battery chemistry substitution for legacy lead-acid systems simultaneously redraws supply geography toward East Asian cell manufacturers and compresses pricing economics around energy density metrics rather than upfront capital expenditure. Facility managers in Dubai and Singapore now calculate total cost of ownership across eight-hour runtime configurations, forcing vendors to unbundle battery-as-a-service subscriptions from transactional equipment sales.
Pricing Analysis
Certification level creates the primary spread between premium robotic units and economy-tier manual equipment, with CE marking under the EU Machinery Directive and ISO 9001 quality management tiers commanding substantial premiums. Three-tier pricing structure across premium automation, standard battery-powered, and economy corded segments reflects divergent compliance documentation burdens. Cost compression in the mid-tier battery segment intensifies because cobalt and nickel price volatility squeezes cylindrical cell supply chains. Janitorial services in India and Brazil exhibit highest price sensitivity, while facility management firms in Germany and the United States prioritize runtime economics over upfront capital deployment.
Supply Chain Analysis
China and South Korea anchor lithium-ion cylindrical cell production for battery-powered scrubber fleets, while Germany concentrates brush motor and squeegee assembly manufacturing around Stuttgart industrial corridors. Component sourcing draws from Japanese precision drive suppliers for robotic navigation systems and Italian pump manufacturers for pressurized steam configurations. Single-region logistics vulnerability in Baden-Württemberg exposes procurement timelines to localized disruption. Distribution runs through authorized dealer networks in North America and direct OEM service branches in European commercial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multi-site facility management firms that unbundle service contracts from original equipment manufacturer networks, fragmenting traditional distributor relationships. This consolidation among large-scale procurers reshapes vendor selection criteria toward total cost of ownership verification and aftermarket autonomy.
For Market Incumbents: Shield margin pools in transport hub automation by deepening captive supply of LiDAR navigation modules and collision avoidance firmware. Secure CE marking documentation advantages ahead of EU Machinery Directive enforcement timelines. Backward integration into brush motor production mitigates Stuttgart logistics bottlenecks that threaten delivery commitments to German hospital systems.
For New Entrants and Emerging Players: ISO 9001 certification fast-tracks unlock institutional procurement eligibility in Texas and California hospital systems where extended auditor timelines currently exclude uncertified vendors. Target wet mop and manual technology segments in Maharashtra and Karnataka hospitality properties where capital constraints favor minimal equipment deployment. Establish local service networks in Mumbai and Bangalore ahead of luxury hotel construction completion.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with North American service-network operators that have built certified technician coverage but lack robotic automation specialization. Five-to-ten-year viability hinges on lithium-ion chemistry certification shifts and autonomous navigation liability framework maturation. Watch battery-as-a-service subscription penetration rates as the inflection signal separating transactional equipment vendors from recurring revenue platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Subscription Launch | Transforms Tennant Company and Nilfisk Group revenue models from transactional sales to recurring runtime contracts. |
| CE Marking Fast-Track Investment | Accelerates European market access for robotic scrubbers ahead of EU Machinery Directive autonomous navigation mandates. |
| Backward Integration into Brush Motors | Reduces Kärcher and Hako exposure to Stuttgart logistics bottlenecks in squeegee assembly supply chains. |
| Local Service Network Establishment | Captures first-mover advantage in Mumbai and Bangalore luxury hotel construction before competitor distributor acquisition. |
| Third-Party Logistics Certification Program | Enables facility management firms in Texas and California to bypass OEM service networks during critical infection control periods. |
Research Approach
Initial hypotheses were tested against primary input from facility management procurement directors, OEM aftermarket service heads, airport maintenance operations managers, and janitorial services contract operators and refined through secondary validation. Trade data from customs filings, SEC equipment manufacturer disclosures, EU Machinery Directive regulatory databases, and airport authority procurement records anchored quantitative sizing. Bottom-up unit deployment estimates across Dubai, Singapore, and Las Vegas transport hubs were triangulated against top-down capital expenditure flows from institutional facility management firms.
Variance decomposition across product type, technology architecture, application venue, and end-user procurement structure shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level runtime economics and replacement cycle modeling. Battery chemistry substitution curves and autonomous navigation adoption thresholds in twenty-four-hour terminal operations served as industry-specific forecast inputs alongside OSHA noise threshold enforcement timelines.
Decision-makers should treat outputs as directional under assumptions of sustained lithium-ion cost curves and stable EU regulatory enforcement; material deviation in cobalt pricing or CE marking interpretation would warrant model refresh. Recalibration cycles align with material shifts in battery certification standards and autonomous navigation liability precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Agitation System Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Global Sportswear Market
Others
Connected TV Market
Others
Disposable Non Woven Sponge Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
LED Packaging Market
Others
Air Separation Plant Market
Others
Digital Bass Processor Market
Others
Security Bottles Market
Others
Europe Polycarbonate Sheets Market
Others
Global Optical Comparator Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Europe Medical Simulation Market
Others
8K Technology Market
Others
Global Computer Peripherals Market