
 Military 4D Printing Market | 2026-2036
Military 4D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Military 4D Printing Market Foresight
Shape-memory polymers are rebalancing cost-performance trade-offs in deployable military structures, replacing conventional rigid composites in applications requiring environmental adaptation. Stratasys Ltd leverages its fused deposition expertise to anchor defense prototyping contracts across NATO supply chains. EOS GmbH specializes in metal powder-bed systems that dominate airframe spare parts qualification programs. Nano Dimension Ltd competes in printed electronics integration for embedded sensing within 4D architectures.
Military 4D printing combines additive manufacturing with stimuli-responsive materials that autonomously change shape, property, or function when exposed to heat, light, moisture, or magnetic fields, typically operating across temperature ranges from -40°C to 150°C and achieving programmed morphing within seconds to minutes for field-adaptive equipment. Spare Parts Production leads application value pools due to supply chain redundancy imperatives, while Custom Tooling exhibits the fastest trajectory as forward-deployed units demand on-demand jigs and fixtures. Selective Laser Sintering occupies the premium technology tier for metal-responsive structures, whereas Fused Deposition Modeling sustains broader polymer adoption through lower capital barriers and field-portable system formats.
Defense procurement frameworks from the US Department of Defense, NATO Standardization Office, and ISO/ASTM additive manufacturing committees govern material qualification, cybersecurity protocols for digital part files, and interoperability standards across allied forces. These bodies mandate traceability systems and performance certification that filter vendor participation toward vertically integrated suppliers with in-house metallurgy and responsive materials laboratories. Stakeholders must monitor evolving export control classifications for programmable matter technologies and position supply chains before bilateral defense agreements lock in preferred supplier networks.
Market Dynamics
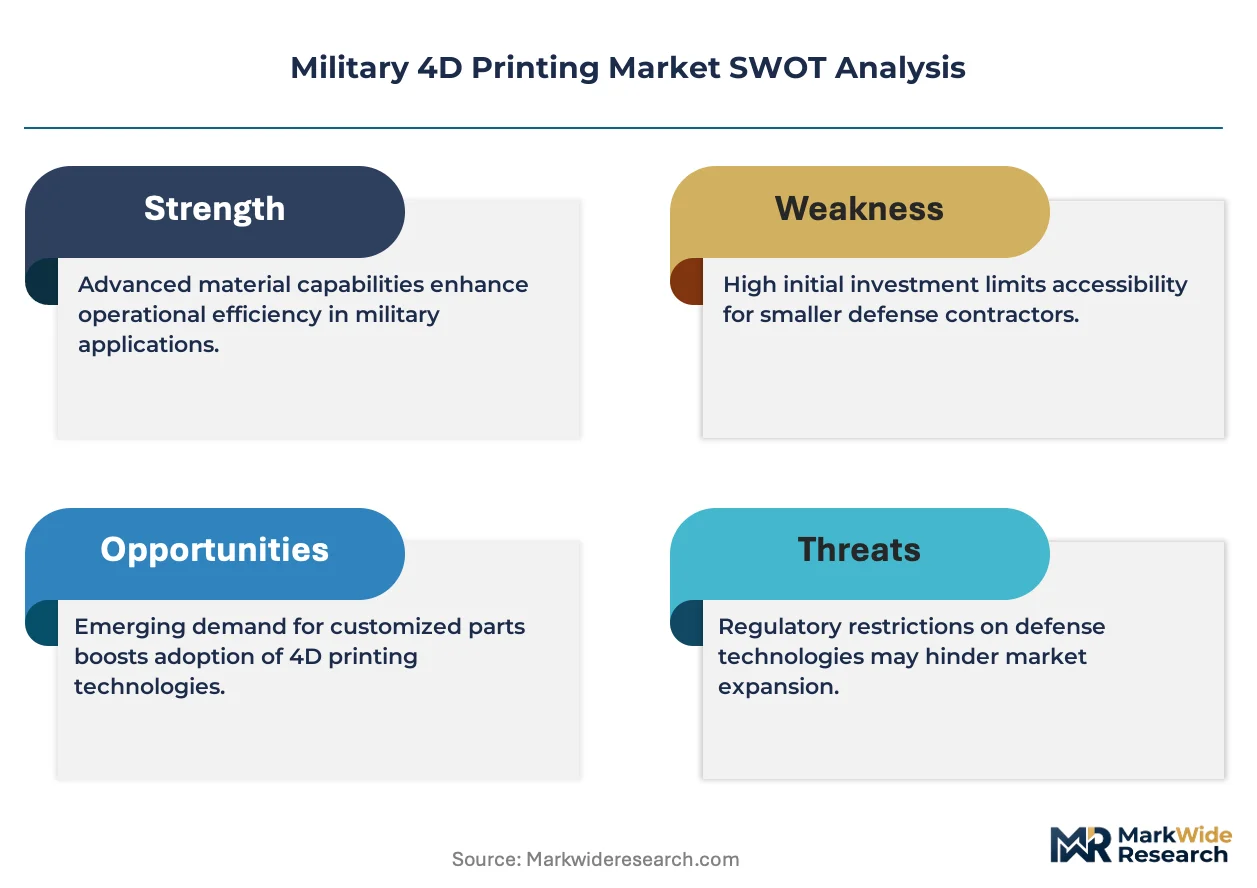
Programmable matter architectures are compressing development cycles for adaptive military platforms, forcing defense contractors to restructure R&D partnerships around stimuli-responsive materials rather than static composite supply chains.
Growth Catalysts
- DoD Additive Manufacturing Directives:Pentagon procurement mandates require qualified 3D-printed spares for critical systems, creating guaranteed demand pools for certified 4D material suppliers.
- Shape-memory polymers:These materials enable deployable structures that morph under thermal stimulus, eliminating mechanical actuators in satellite booms and temporary shelters.
- DARPA-funded smart materials programs:Accelerated funding cycles compress laboratory-to-field timelines for responsive hydrogels and magneto-active composites.
Market Restraints
- Specialized feedstock concentration:High-purity shape-memory polymer precursors depend on captive production at three German and Japanese chemical conglomerates.
- Material qualification timelines:MIL-STD-810 environmental testing and airworthiness certification extend development cycles beyond traditional procurement windows.
- Technical limitation in multi-field responsiveness:Current architectures respond to single stimuli; dual-trigger systems remain laboratory-bound with unreliable repeatability.
Strategic Opportunities
- Underpenetrated NATO allies:Poland, Romania, and Baltic states lack domestic 4D printing infrastructure, creating first-mover advantage for mobile field-deployable systems.
- Regulatory tailwind from EU Defense Fund:Joint procurement frameworks incentivize cross-border additive manufacturing networks for responsive spare parts.
- Convergence of printed electronics and 4D architectures:Embedded sensing layers enable real-time structural health monitoring in morphing airframes.
Industry Challenges
- Computational materials engineering talent gap:Finite element modeling for 4D shape-programming requires rare cross-training in polymer physics and topology optimization.
- Integration complexity with legacy logistics systems:Digital part file distribution conflicts with established NATO supply chain software and security protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military 4D Printing Market |
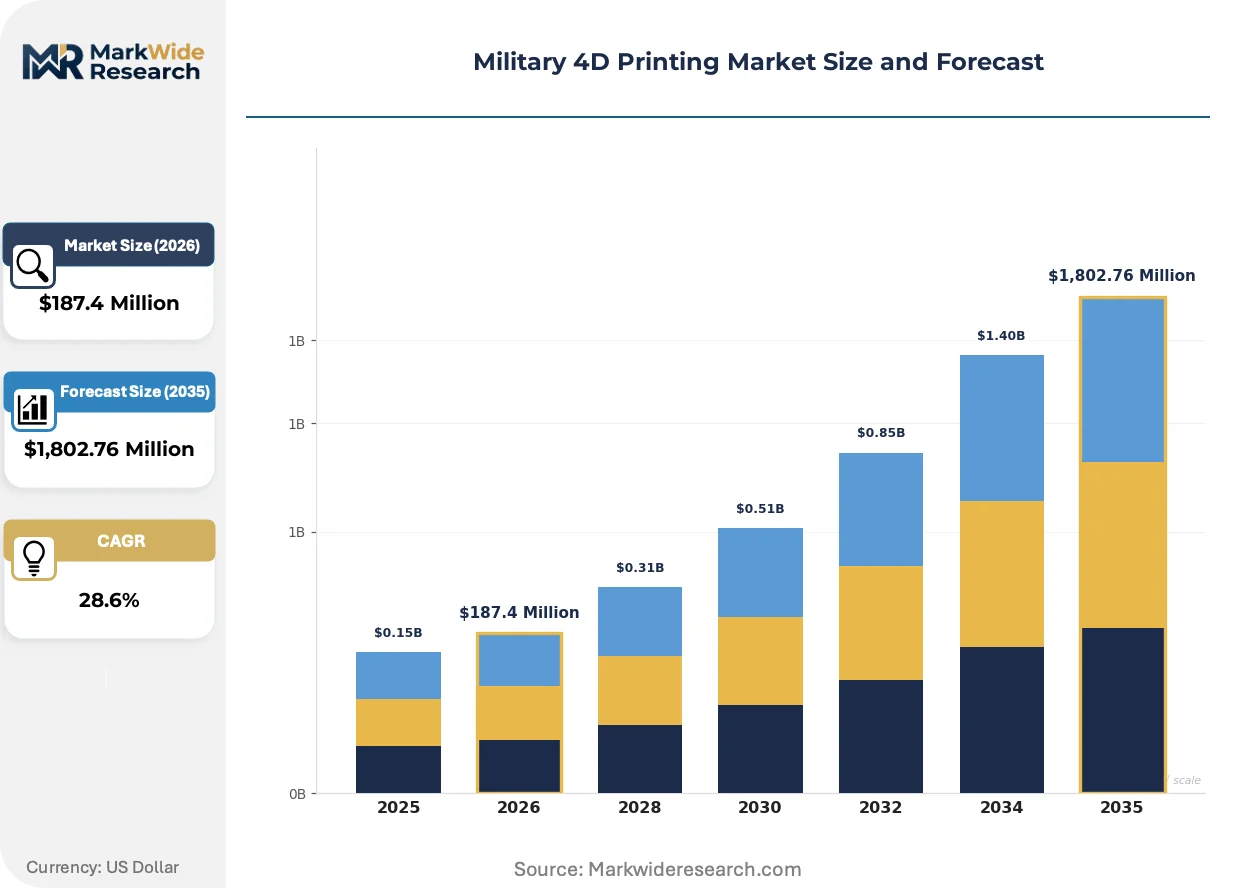
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing Application: Spare Parts Production, Prototyping, Equipment Repair, Custom Tooling End User: Defense Contractors, Military Organizations, Aerospace Manufacturers, Research Institutions Material Type: Metals, Polymers, Ceramics, Composites |
| Companies Covered | Engineering & Manufacturing Services Inc, Markforged Inc, Stratasys Ltd, Nano Dimension Ltd, EOS GmbH, 3D Systems Corporation, 3T Additive Manufacturing Ltd, ExOne Company, Norsk Titanium US Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military 4D Printing Market Shifts & Advancements
Responsive material systems are migrating from demonstration projects to qualified production lines, redefining how defense platforms adapt to operational environments without mechanical intervention.
Multi-material extrusion systems with embedded fiber reinforcement are overtaking single-polymer deposition for load-bearing deployable structures. Army Research Laboratory engineers are qualifying these systems for temporary bridge components that self-deploy upon heating. The technology is overtaking conventional inflatable architectures by eliminating pump requirements and reducing packed volume by half.
REACH authorization requirements for novel polymer chemistries are tightening precursor availability for European defense contractors. ECHA substance evaluation protocols now classify several shape-memory polymer building blocks as substances of very high concern. German and French suppliers are responding by reformulating feedstocks around bio-based alternatives ahead of 2027 authorization deadlines.
Forward-deployed units are consolidating fabrication requests through centralized digital part libraries rather than maintaining regional spare inventories. Marine expeditionary forces in the Pacific are piloting this model for adaptive camouflage netting and temporary shelter components. Australia and Japan are replicating the architecture for distributed island defense scenarios where resupply timelines stretch across weeks.
Military 4D Printing Market Segmentation
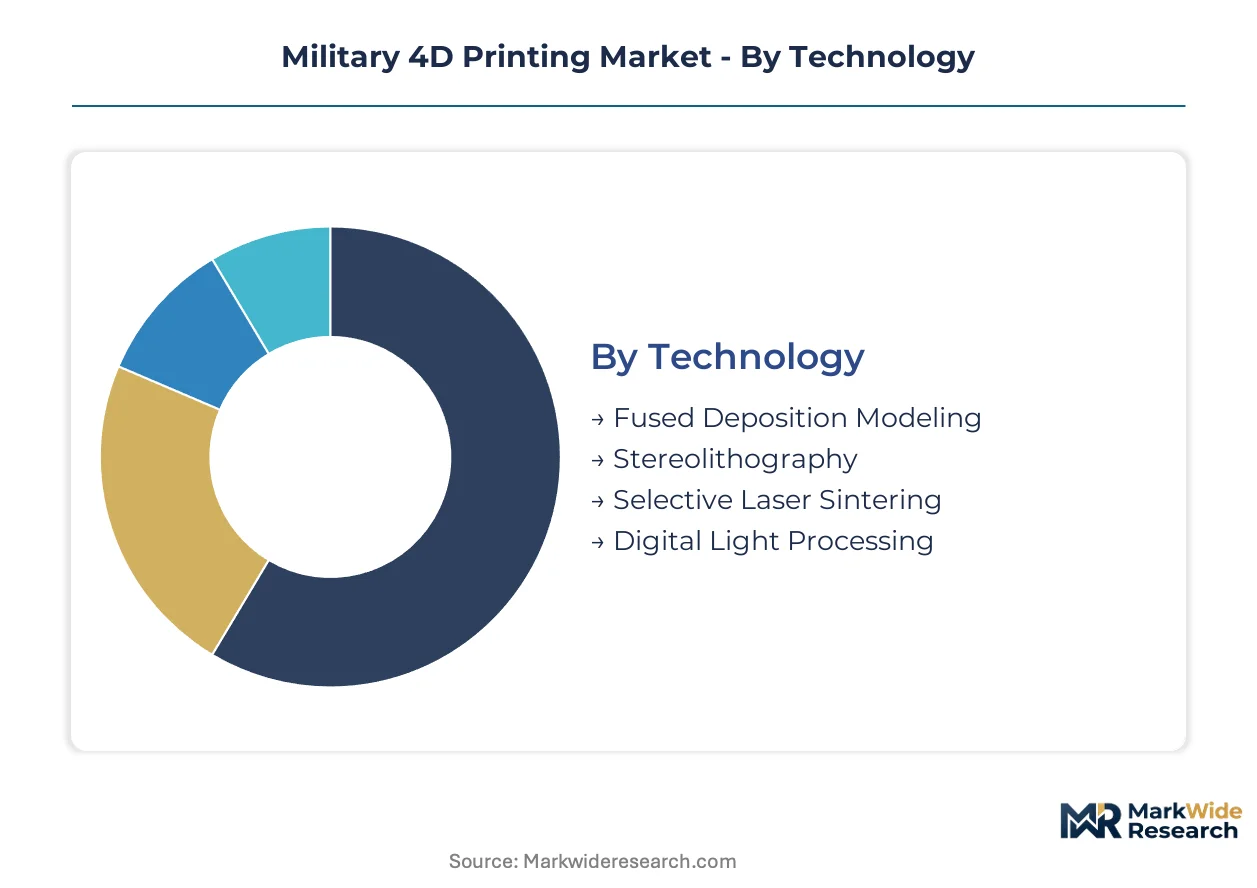
Defense procurement frameworks demand precise alignment between printing technology, material responsiveness, and operational theater requirements. Segmentation reveals where capital-intensive metal systems command premium contracts versus where polymer platforms enable distributed field deployment.
Technology:
Volume deployment clusters around lower-capital systems, while mission-critical metal responsiveness commands premium positioning.
- Selective Laser Sintering:Powder-bed fusion of nickel-titanium and aluminum alloys produces field-responsive structures with programmed phase transitions. United States Air Force airframe spare parts qualification programs concentrate demand here, constrained by inert gas supply chain vulnerabilities in Pacific theater operations.
- Fused Deposition Modeling:Continuous filament deposition of shape-memory polymers enables deployable shelter components and adaptive camouflage netting. United States Marine expeditionary forces in the Pacific drive procurement, prioritizing generator-compatible power requirements over precision tolerances.
- Stereolithography:Vat photopolymerization achieves finest feature resolution for micro-actuator housings in drone swarms.
- Digital Light Processing:Projected light curing accelerates batch production of temporary bridge connectors with sub-minute layer times.
Mature deployment sits with Fused Deposition Modeling. Newer deployment is concentrated in Selective Laser Sintering.
Application:
Operational tempo determines whether units prioritize immediate availability or precision engineering.
- Spare Parts Production:Qualified replacement components for ground vehicle powertrains and avionics cooling systems eliminate trans-oceanic resupply dependencies. United States Army tank-automotive commands anchor procurement, though MIL-STD-810 environmental certification extends lead times beyond tactical procurement windows.
- Custom Tooling:Forward-deployed fabrication of jigs, fixtures, and maintenance adapters responds to platform-specific damage patterns. Polish and Romanian land forces under NATO's enhanced forward presence drive fastest adoption, lacking legacy inventory depth.
- Prototyping:Rapid iteration of morphing wing sections and deployable antenna geometries compresses DARPA program development cycles.
- Equipment Repair:Battlefield restoration of cracked turbine blades and damaged sensor housings via responsive material overlays.
Established demand concentrates in Spare Parts Production. Steepest expansion trajectory belongs to Custom Tooling.
End User:
Budget authority and technical sophistication create tiered adoption patterns across institutional buyers.
- Military Organizations:Direct-operated fabrication cells in expeditionary logistics units prioritize field portability and energy independence over throughput. United States Marine Corps Systems Command and Japan Ground Self-Defense Force island defense units anchor procurement.
- Defense Contractors:Prime integrators embed 4D printing into platform design rather than aftermarket support, with Lockheed Martin and Northrop Grumman qualifying responsive materials for satellite bus structures.
- Aerospace Manufacturers:Boeing and Airbus Defense divisions apply self-healing composites to reduce depot maintenance cycles for military transport fleets.
- Research Institutions:Army Research Laboratory and Air Force Research Laboratory operate bridging facilities between laboratory demonstration and production qualification.
Institutional maturity rests with Defense Contractors. Emerging demand clusters in Military Organizations.
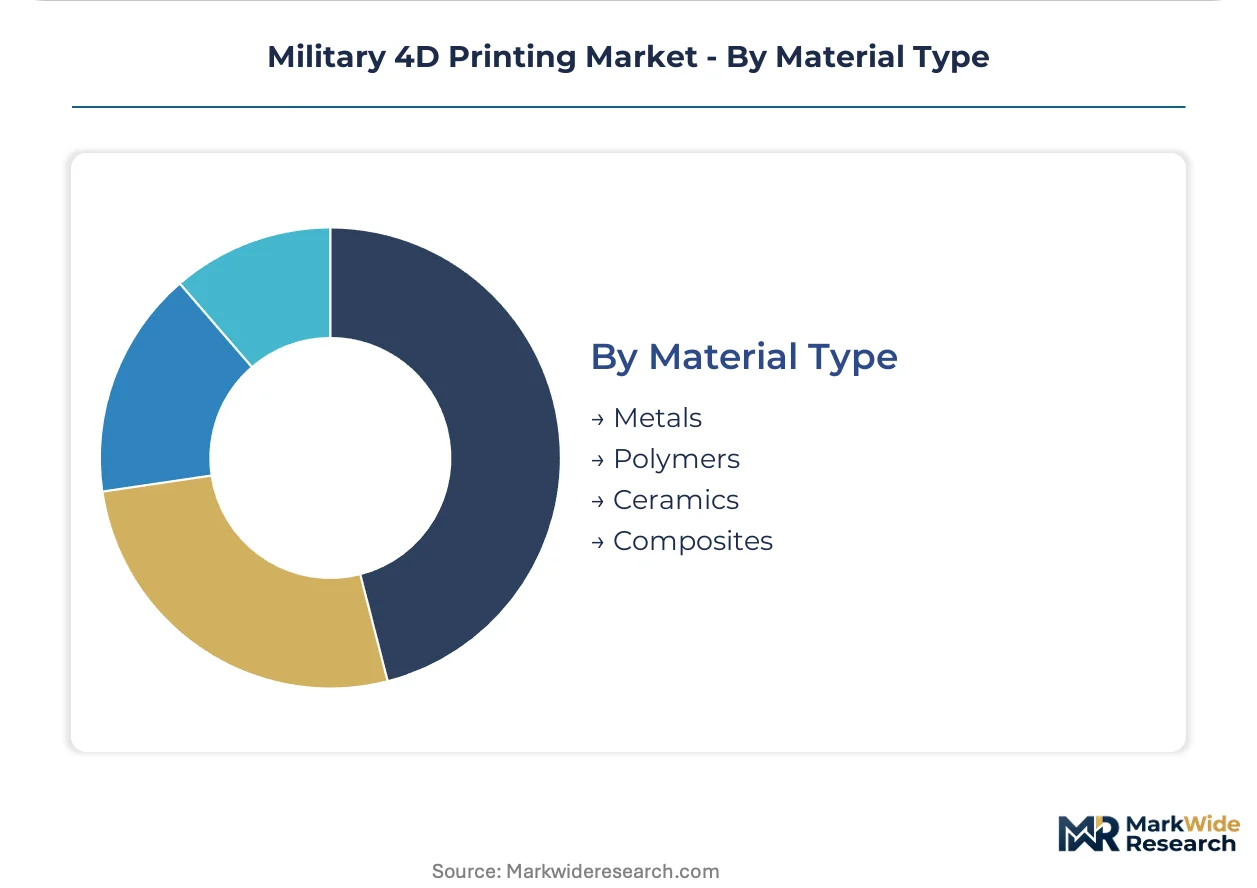
Material Type:
Stimuli-response mechanisms and load-bearing requirements dictate material selection hierarchies.
- Polymers:Shape-memory polyurethane and responsive hydrogel formulations enable thermal-triggered deployment at temperatures between 40°C and 80°C. Temporary shelter and satellite boom applications concentrate in United States and Australian defense programs.
- Metals:Nickel-titanium shape-memory alloys retain programmed configurations across -40°C to 150°C operational bands for airframe and powertrain components.
- Composites:Fiber-reinforced responsive matrices combine directional strength with morphing capability in load-bearing deployable structures.
- Ceramics:High-temperature responsive ceramics protect hypersonic vehicle leading edges with ablative self-adjustment.
Volume leadership belongs to Polymers. Technical frontier advancement concentrates in Metals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement concentrates in the United States, where Department of Defense additive manufacturing directives and DARPA-funded smart materials programs generate guaranteed demand pools for certified 4D material suppliers. Military organizations across NATO and Indo-Pacific allies are replicating this procurement architecture, though with varying degrees of domestic infrastructure depth.
United States
Air Force Research Laboratory and Army Research Laboratory operate bridging facilities between laboratory demonstration and production qualification for responsive materials. DoD additive manufacturing directives mandate qualified 3D-printed spares for critical systems, filtering vendor participation toward suppliers with in-house metallurgy capabilities. Huntsville, Alabama and Dayton, Ohio anchor concentrated defense contractor clusters where prime integrators embed 4D printing into satellite bus and morphing airframe designs.
Germany
EOS GmbH and chemical conglomerates in the Rhine-Ruhr region dominate high-purity shape-memory polymer precursor production for NATO supply chains. ECHA substance evaluation protocols now classify several polymer building blocks as substances of very high concern, forcing feedstock reformulation around bio-based alternatives. Bavarian industrial clusters around Munich specialize in powder-bed fusion systems for airframe spare parts qualification programs.
Japan
Japan Ground Self-Defense Force island defense units prioritize field-portable FDM systems for adaptive camouflage netting and temporary shelter components. METI standards govern material traceability systems that align with NATO interoperability requirements. Nagoya and Tokyo metropolitan areas concentrate aerospace manufacturer divisions applying self-healing composites to reduce depot maintenance cycles for military transport fleets.
Australia
Marine expeditionary forces in the Pacific are piloting centralized digital part libraries for distributed island defense scenarios where resupply timelines stretch across weeks. The country's defense procurement frameworks emphasize generator-compatible power requirements for forward-deployed fabrication cells. Melbourne and Sydney harbor emerging research partnerships between universities and defense contractors on responsive hydrogel applications.
Poland
Polish land forces under NATO's enhanced forward presence drive fastest adoption of custom tooling applications, lacking legacy inventory depth for conventional maintenance support. EU Defense Fund joint procurement frameworks incentivize cross-border additive manufacturing networks for responsive spare parts. Warsaw and Krakow industrial zones attract mobile field-deployable system providers seeking first-mover advantage in underpenetrated allied markets.
Military 4D Printing Market Competitive Landscape
Defense contracting partnerships dominate the current landscape, with prime integrators restructuring R&D relationships around stimuli-responsive materials rather than static composite supply chains. The vendor base separates into three tiers: vertically integrated material-printer combinations, specialized responsive feedstock suppliers, and field-portable system fabricators. Two strategic archetypes define positioning—those anchoring NATO supply chain qualification programs and those capturing expeditionary logistics unit procurement. Portfolio diversification into printed electronics integration and capacity expansion for high-purity polymer precursor production represent the dominant competitive moves.
Within the integrated material-printer tier, Stratasys Ltd and EOS GmbH exemplify divergent technology anchoring strategies, with the former representing fused deposition expertise for defense prototyping contracts and the latter specializing in metal powder-bed systems for airframe applications. Nano Dimension Ltd occupies a distinct position bridging printed electronics and 4D architectures for embedded sensing applications. These three companies illustrate how geographic origin and corporate structure align with divergent defense procurement channel strategies.
| Leading Market Players |
|---|
| Engineering & Manufacturing Services Inc |
| Markforged Inc |
| Stratasys Ltd |
| Nano Dimension Ltd |
| EOS GmbH |
| 3D Systems Corporation |
| 3T Additive Manufacturing Ltd |
| ExOne Company |
| Norsk Titanium US Inc |
| Others |
Supply & Pricing Matrix
Sovereign-backed defense research institutions and DARPA-funded laboratories anchor upstream control over shape-memory polymer precursor formulations, compressing margin capture for downstream printer OEMs while concentrating pricing power among three German and Japanese chemical conglomerates with captive high-purity feedstock production.
Pricing Analysis
Volume deployment through Fused Deposition Modeling systems competes on generator-compatible portability and lower capital barriers, while Selective Laser Sintering commands premium positioning for nickel-titanium airframe components with MIL-STD-810 certification. Three-tier pricing structure across qualified defense-grade, commercial-industrial, and research-laboratory levels separates certified NATO supply chain participants from uncertified entrants. Cost compression in polymer feedstock tiers is intensifying because REACH authorization deadlines are forcing reformulation investments. Forward-deployed military organizations exhibit highest price sensitivity due to expeditionary budget constraints, whereas prime defense contractors prioritize qualification reliability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with high-purity shape-memory polymer precursors concentrated in German and Japanese chemical conglomerates, with secondary concentration of nickel-titanium alloy powder production in United States and German industrial clusters. Raw material dependencies encompass responsive hydrogel monomers, magneto-active composite rare-earth elements, and inert gas supplies for powder-bed fusion systems. Regulatory restriction from ECHA substance evaluation protocols classifying polymer building blocks as substances of very high concern threatens precursor availability for European defense contractors. Distribution runs through qualified NATO supply chain networks with mandated traceability systems, filtering vendor participation toward vertically integrated suppliers with in-house metallurgy capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense contractors are restructuring procurement relationships around stimuli-responsive materials in a vertical-integration race, with prime integrators pursuing captive control over shape-memory polymer precursor production to secure supply chain redundancy against export control restrictions.
For Market Incumbents: Deploy qualification-first positioning by accelerating MIL-STD-810 and airworthiness certification for multi-material extrusion systems before bilateral defense agreements lock in preferred supplier networks. Lockheed Martin and Northrop Grumman are already embedding responsive materials into satellite bus structures, threatening aftermarket-focused suppliers with design-phase exclusion. Anchor NATO Standardization Office relationships to defend channel access against emerging field-portable system fabricators. For New Entrants and Emerging Players: Technology-first wedges in printed electronics integration for embedded sensing layers offer penetration paths outside established powder-bed fusion qualification programs. Polish and Romanian land forces under NATO's enhanced forward presence present the most penetrable demand pool, lacking legacy inventory depth for conventional maintenance support. Pursue mobile field-deployable system formats with generator-compatible power requirements to capture expeditionary logistics unit procurement before centralized digital part libraries consolidate fabrication requests. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated material-printer combinations in German and Japanese industrial clusters where ECHA authorization pressures are compressing valuations for specialty chemical feedstock producers. Five-to-ten year viability hinges on positioning before EU Defense Fund joint procurement frameworks incentivize cross-border additive manufacturing networks. Watch DARPA funding cycle acceleration as the inflection indicator for laboratory-to-field timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursor Production | EOS GmbH and Stratasys Ltd are securing captive supply of shape-memory polymer formulations against REACH authorization restrictions. |
| Qualification Investment for NATO Supply Chain Access | Defense contractors prioritize vendors with in-house metallurgy laboratories meeting ISO/ASTM additive manufacturing committee standards. |
| Platform Integration of Printed Electronics | Nano Dimension Ltd bridges 4D architectures with embedded sensing for real-time structural health monitoring in morphing airframes. |
| Joint Venture for Pacific Theater Inert Gas Supply | United States Air Force airframe programs require redundant noble gas sourcing to sustain powder-bed fusion operations. |
| Geographic Expansion into Baltic Defense Markets | Mobile field-deployable system providers are establishing presence in Warsaw and Krakow industrial zones ahead of EU Defense Fund disbursements. |
Research Methodology
Multi-period observation of DARPA funding allocations, DoD additive manufacturing directive implementation timelines, and NATO standardization protocol revisions anchored the trend analysis, supplemented by interviews with Army Research Laboratory program managers, EOS GmbH technical directors, Polish Ministry of National Defense procurement officers, and Air Force Research Laboratory materials engineers. Secondary validation drew from Department of Defense budget justification documents, ECHA substance evaluation protocols, METI standards publications, and EU Defense Fund programming guidelines. Bottom-up triangulation across technology-platform deployment counts and top-down reconciliation against defense procurement budget flows ensured cross-verification.
Segment-weighting across printing technology, material type, application, and end-user institutional tier informed the analytical framework across the projection horizon. Technology segmentation modeled Selective Laser Sintering, Fused Deposition Modeling, Stereolithography, and Digital Light Processing adoption curves. Material responsiveness temperature bands and stimuli-trigger reliability metrics served as industry-specific forecast inputs. CAGRs were derived from deployment trajectory slopes qualified against procurement cycle durations and certification timeline constraints.
Several conditions sit outside the modeled scope, including specific bilateral defense agreement negotiations, classified program budget allocations, and unforeseen export control reclassifications for programmable matter technologies. Forecasts reflect assumptions regarding DARPA funding continuity, REACH authorization timeline adherence, and NATO interoperability standard adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Cosmetovigilance Market
Others
North America Orange Market
Others
Paper Shredder Market
Others
Shear Testing Equipment Market
Others
Reusable Wine Bags Market
Others
Tunnel Lighting Market
Others
Digital Media Adaptor (DMA) Market
Others
Digital LUX Meter Market
Others
North America Healthcare Flexible Packaging Market
Others
Global Extruded Plastics Market
Others
Spain Automotive LED Lighting Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Lightweight Compact Wheel Loader Market
Others
Inflight Entertainment Solutions Market
Others
GCC Cigarette Market
Others
Mainframe Market