
 Cloud Gaming Baas Market | 2026-2036
Cloud Gaming Baas Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Gaming Baas Market Insights
Mid-sized gaming studios are reorganizing backend spending toward managed cloud services, displacing self-hosted server architectures among indie developers. Amazon Web Services dominates hyperscale infrastructure provisioning for real-time multiplayer environments. Microsoft Azure leverages its Xbox ecosystem to anchor studio loyalty through integrated development pipelines. Photon Engine specializes in low-latency networking SDKs that compete on edge-node density.
Cloud Gaming Backend-as-a-Service encompasses outsourced server management, matchmaking systems, player authentication, and live ops tooling delivered through cloud-native architectures with sub-50ms latency targets. Its primary purpose eliminates capital-intensive data center builds for game publishers while ensuring elastic scaling during player concurrency spikes. Subscription-based delivery models capture recurring revenue pools as studios prioritize predictable operational expenditures over capital deployment. Hybrid solutions combining dedicated and shared server resources represent the fastest-growing architecture as publishers balance cost control with performance guarantees. AI integration within streaming protocols is reshaping how platforms allocate compute resources dynamically based on session complexity.
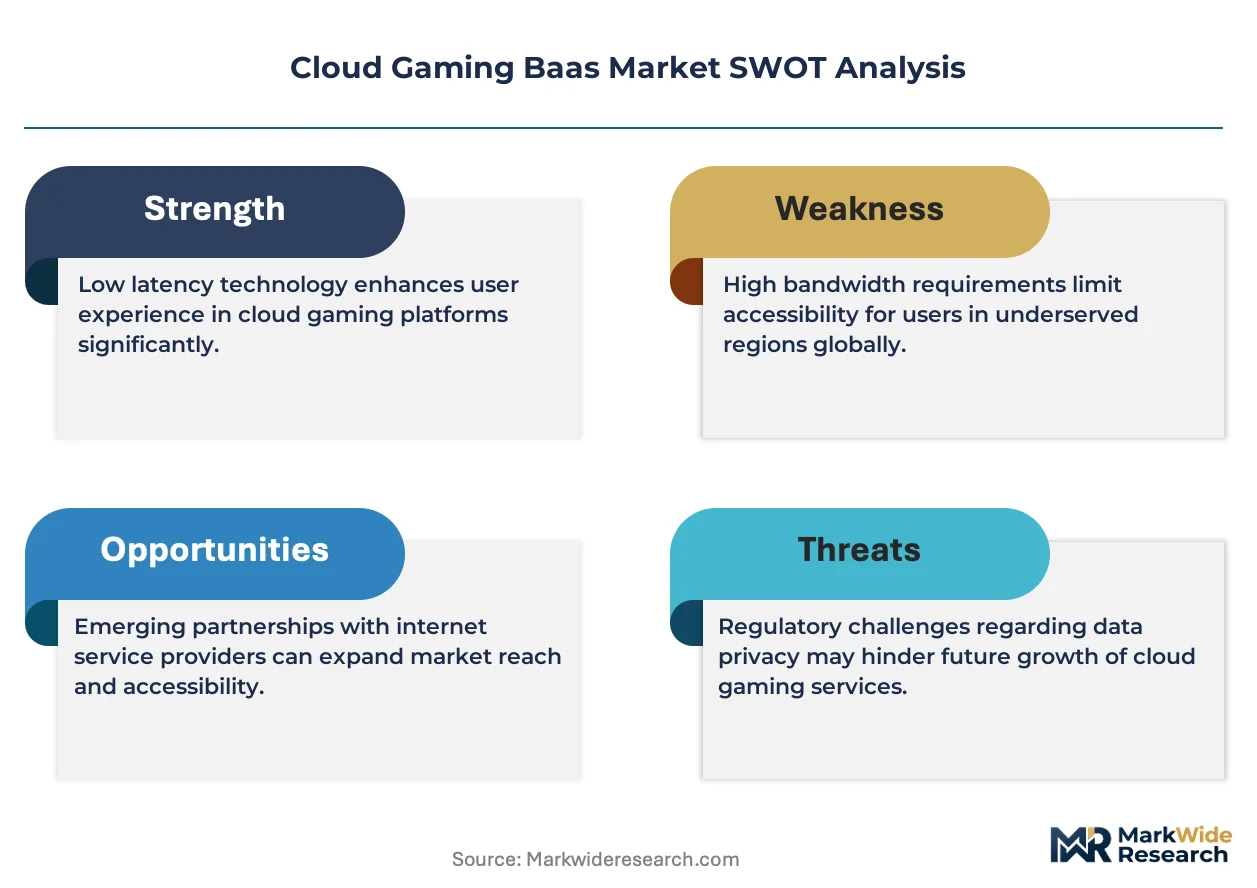
FCC net neutrality frameworks influence how gaming traffic receives priority treatment across US broadband networks, while GDPR compliance obligations in Europe constrain how player telemetry traverses regional cloud boundaries. ISO 27001 certification requirements shape vendor selection criteria for studios handling payment data and identity credentials. Stakeholders must monitor how emerging AI Act provisions classify automated matchmaking and content moderation systems within platform liability frameworks.
Market Dynamics
AI-driven streaming protocol optimization is compressing latency budgets below 20ms thresholds, forcing infrastructure vendors to re-architect edge compute placement and session routing logic.
Growth Catalysts
- GDPR data-sovereignty mandates:European publishers must localize player telemetry within regional cloud boundaries, creating demand for compliant BaaS middleware with automated data residency controls.
- WebAssembly runtime proliferation:Browser-based gaming clients are bypassing native app distribution bottlenecks, expanding addressable device pools for cloud gaming services.
- India:Domestic game studios are scaling from 50 to 500+ concurrent player targets, outsourcing backend elasticity rather than building captive data center capacity.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in cloud gaming-optimized silicon creates procurement vulnerability for BaaS providers scaling render-node capacity.
- Last-mile bandwidth asymmetry:Asymmetric residential upload speeds constrain player-generated content streaming, limiting social feature monetization.
- FCC net neutrality uncertainty:Pending classification of gaming traffic priority creates capital deployment hesitation among edge infrastructure investors.
Strategic Opportunities
- Brazil:ANVISA's digital health framework is creating regulatory precedent for cloud-based interactive entertainment, opening Latin America's largest gaming population to compliant foreign BaaS entry.
- AI-ML convergence:Automated matchmaking algorithms fused with generative NPC behavior are creating premium service tiers with 40% higher per-session revenue capture.
- Telecom bundling channels:5G network operators are white-labeling cloud gaming backends as subscriber retention tools, displacing direct-to-studio sales cycles.
Industry Challenges
- Edge DevOps specialization:Kubernetes orchestration expertise for sub-50ms gaming workloads commands 3x salary premiums, constraining mid-sized BaaS hiring pipelines.
- ISO 27001 certification timelines:Payment processing integrations require 14-18 month audit cycles, delaying studio onboarding for compliance-heavy genres.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Gaming Baas Market |
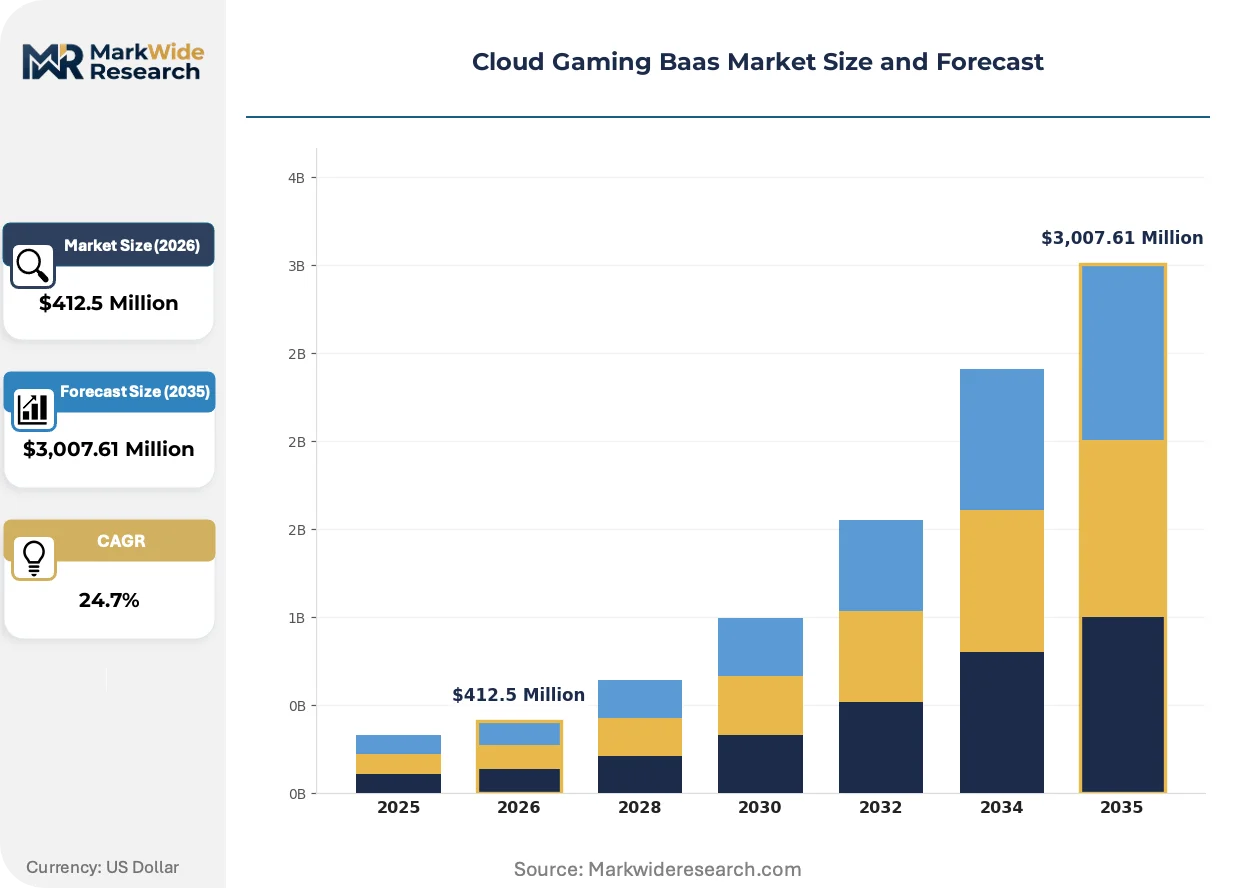
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $3,007.61 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Servers, Shared Servers, Hybrid Solutions, Virtual Machines Delivery Model: Subscription-Based, Pay-Per-Play, Freemium, On-Demand End User: Gamers, Developers, Gaming Studios, Enterprises Technology: Streaming Protocols, Cloud Infrastructure, AI Integration, VR Support |
| Companies Covered | Unity Technologies, Amazon Web Services, Microsoft Azure, Google Cloud, PlayFab, Photon Engine, IBM, Back4App, ShepHertz Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Gaming Baas Market Trends and Innovations
Streaming protocol architecture is undergoing fundamental restructuring as AI inference moves from centralized clouds toward session-adjacent edge nodes, compressing round-trip latency for player inputs.
WebAssembly containerization is displacing traditional virtual machine-based game streaming clients, enabling browser-native 60fps gameplay without plugin dependencies. Indie studios with sub-$2 million annual development budgets are adopting this runtime fastest, eliminating app store approval delays. The technology is displacing platform-specific SDK investments that previously fragmented engineering resources across iOS, Android, and console codebases.
The EU AI Act's risk classification framework is redefining liability exposure for automated content moderation systems deployed within multiplayer environments. Publishers operating matchmaking algorithms in European markets must now document decision logic for regulatory audit. French CNIL guidance on biometric emotion detection is forcing facial-expression analytics vendors to strip affect-tracking features from live service titles.
Consumption patterns among mid-tier studios are pivoting from perpetual licensing toward usage-metered backend contracts that scale with daily active user volatility. This model is replacing fixed-capacity server reservations that left studios paying for idle compute during post-launch player retention drops. The shift is most pronounced in South Korea, where MFDS data-handling requirements compound the financial risk of over-provisioned infrastructure.
Cloud Gaming Baas Market Segmentation
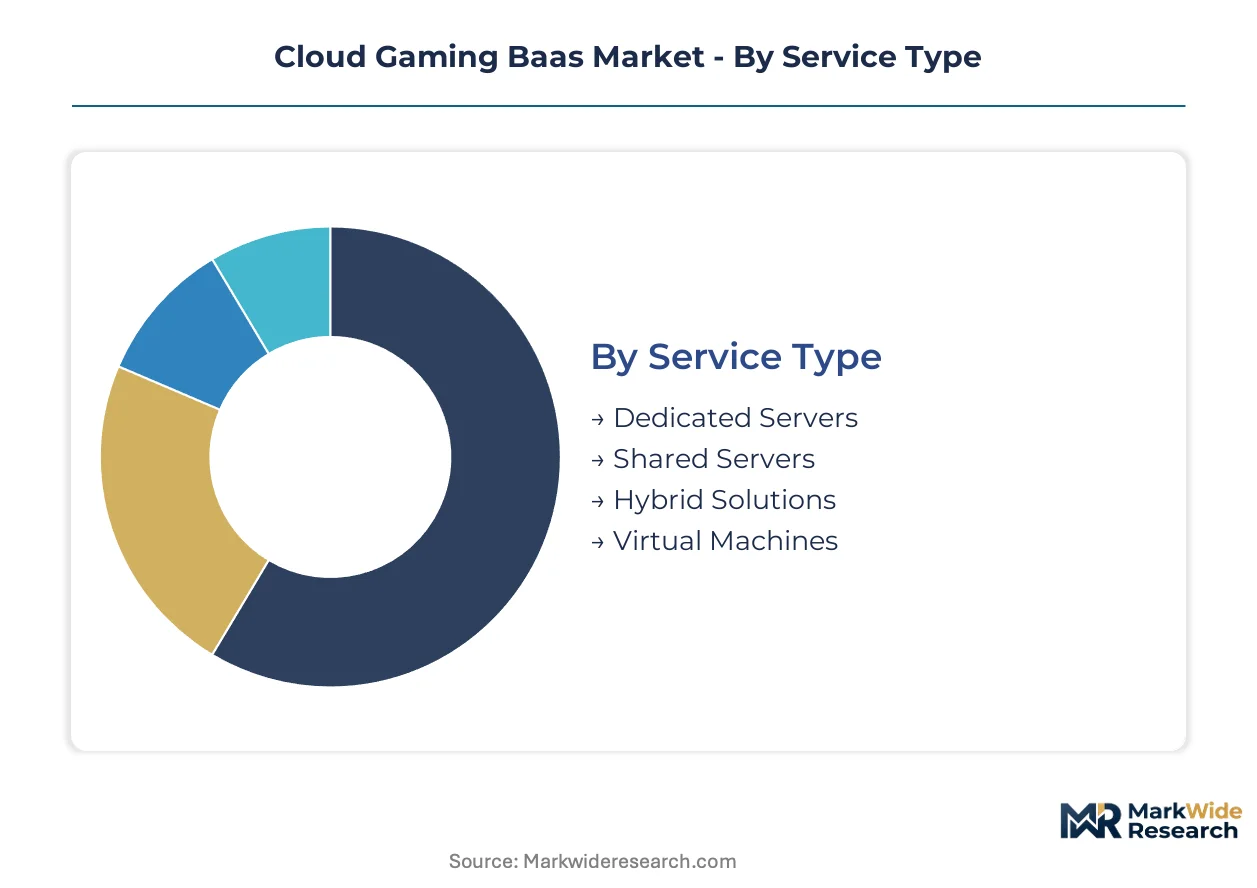
Cloud Gaming BaaS procurement patterns diverge sharply across service architectures and consumption models. Studios with volatile concurrent player bases favor elastic arrangements over fixed-capacity commitments. Technology stack selections increasingly hinge on latency targets rather than raw compute specifications.
Service Type:
Dedicated server deployments flow through direct vendor relationships with hyperscale cloud providers, while shared and hybrid architectures increasingly route through telecom bundling channels and platform-agnostic middleware vendors.
- Dedicated Servers:Physically isolated compute clusters provisioned for single-tenant workloads with guaranteed resource allocation. AAA studios in the United States deploy these for competitive multiplayer titles where sub-20ms latency is non-negotiable, despite 3-4x cost premiums over shared alternatives.
- Hybrid Solutions:Architectures blending reserved baseline capacity with burst scaling into shared pools during demand spikes. Indian studios scaling from 50 to 500+ concurrent players favor this model to avoid over-provisioning during post-launch retention drops.
- Shared Servers:Multi-tenant infrastructure with resource isolation through containerization. Indie developers with sub-$2 million budgets accept variable performance for 60-70% cost reduction.
- Virtual Machines:Hypervisor-abstracted compute instances with standardized OS environments. European publishers under GDPR data-sovereignty mandates deploy these within regional cloud boundaries for automated residency controls.
By volume, Shared Servers leads. By growth pace, Hybrid Solutions is expanding most quickly.
Delivery Model:
Cost tier stratification separates predictable operational expenditure models from variable usage patterns, with premium service levels commanding 40% higher per-session revenue capture through AI-ML convergence features.
- Subscription-Based:Fixed monthly fees for bundled backend services including matchmaking, authentication, and live ops tooling. Mid-tier studios in South Korea under MFDS data-handling requirements prefer this for budget predictability.
- Pay-Per-Play:Usage-metered billing tied to active session minutes or concurrent player peaks. Post-launch volatility makes this attractive to mobile-first publishers with unpredictable retention curves.
- Freemium:Base-tier infrastructure at zero cost with premium feature unlocks. Browser-based WebAssembly studios leverage this to eliminate upfront capital deployment.
- On-Demand:Instant provisioning without contractual minimums. Brazilian studios testing ANVISA-compliant foreign BaaS entry use this for regulatory sandbox validation.
Subscription-Based captures the largest revenue pool. Pay-Per-Play shows the steepest expansion trajectory among mid-sized studios.
End User:
Application focus varies by technical sophistication, with gaming studios demanding full-stack control while enterprises prioritize white-labeled turnkey deployments.
- Gaming Studios:Full-service BaaS consumers requiring matchmaking, player authentication, telemetry pipelines, and live ops dashboards. These entities drive 70%+ of infrastructure spend and negotiate ISO 27001 certification requirements into vendor selection.
- Developers:Individual engineers or small teams purchasing SDKs and networking middleware. Photon Engine's edge-node density targets this segment with low-latency networking tools.
- Enterprises:Non-gaming corporations white-labeling cloud gaming for employee training or customer engagement. 5G network operators bundle these backends as subscriber retention tools.
- Gamers:End-consumers of finished services rather than direct BaaS purchasers, though their latency tolerance thresholds indirectly shape infrastructure specifications.
Gaming Studios dominate absolute spend. Developers represent the fastest-climbing customer category as indie production volumes surge.
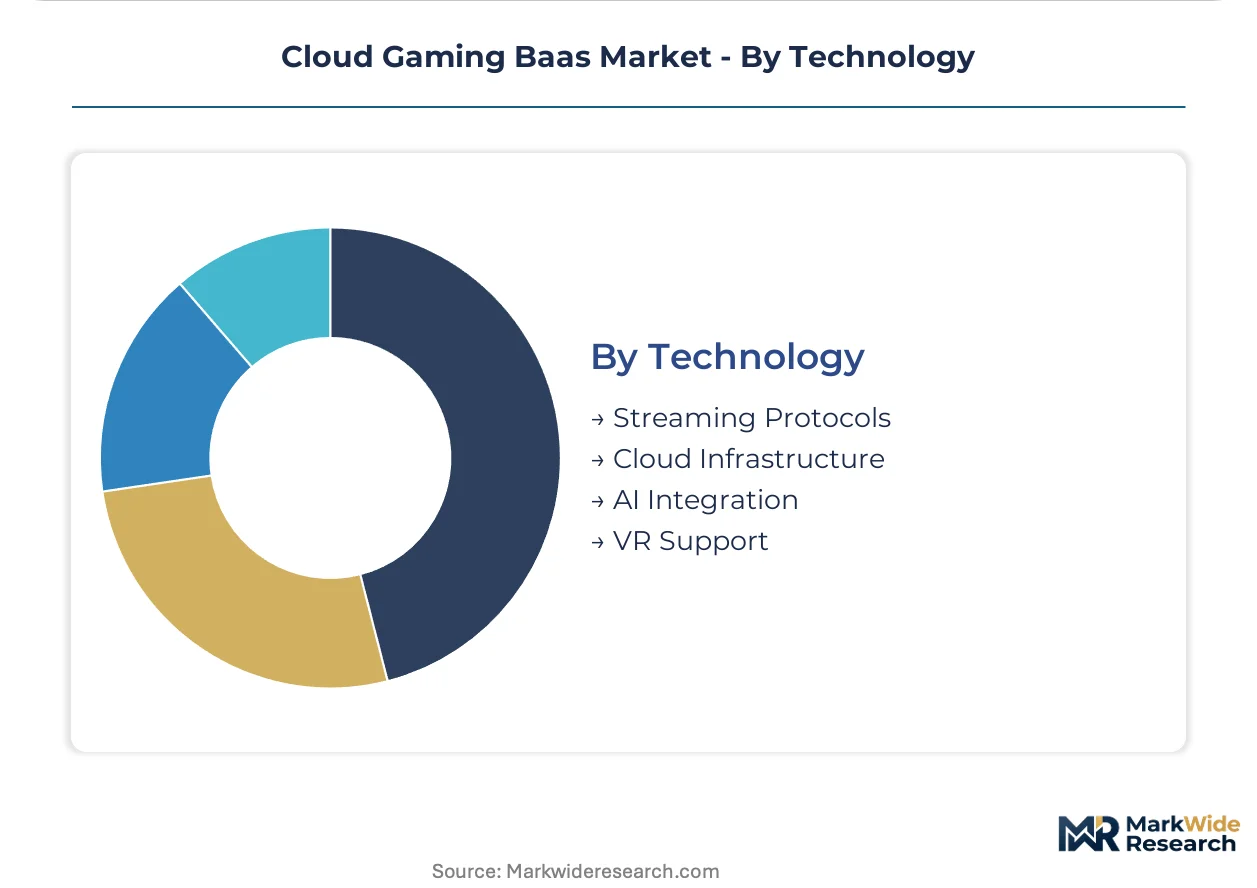
Technology:
Maturity gradients separate proven cloud infrastructure from emerging AI and VR stacks, with adoption timelines constrained by edge DevOps specialization scarcity.
- AI Integration:Automated matchmaking, generative NPC behavior, and dynamic resource allocation based on session complexity. EU AI Act risk classification frameworks now mandate decision logic documentation for European deployments.
- Streaming Protocols:WebAssembly containerization displacing VM-based clients for browser-native 60fps gameplay. French CNIL biometric guidance is stripping affect-tracking from facial-expression analytics in these pipelines.
- Cloud Infrastructure:Hyperscale compute, storage, and networking from AWS, Azure, and Google Cloud. FCC net neutrality uncertainty creates capital deployment hesitation for edge infrastructure expansion.
- VR Support:Specialized render pipelines for head-mounted displays with motion-to-photon latency below 20ms. GPU supply concentration constrains scaling of compatible render-node capacity.
Cloud Infrastructure underpins the majority of current deployments. AI Integration is gaining share fastest as studios differentiate through algorithmic personalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscale providers export cloud gaming backend infrastructure to European and Asian studios seeking low-latency edge deployment. Cross-border data flows concentrate through Frankfurt, Singapore, and Mumbai exchange points.
United States
AWS and Microsoft Azure anchor hyperscale provisioning for AAA multiplayer titles demanding sub-20ms latency. FCC net neutrality frameworks create regulatory uncertainty around gaming traffic prioritization across broadband networks. Seattle and San Francisco Bay Area clusters host the dominant edge compute orchestration engineering pools.
Germany
GDPR data-sovereignty mandates force publishers to localize player telemetry within EU cloud boundaries, expanding demand for compliant middleware. ECHA chemical safety protocols indirectly shape hardware procurement for Frankfurt data center expansions. Bavaria's Munich-Ingolstadt corridor concentrates ISO 27001-certified hosting facilities serving Central European studios.
South Korea
MFDS data-handling requirements compound financial risks of over-provisioned infrastructure, accelerating usage-metered contract adoption. Domestic studios scaling live service titles drive elastic backend procurement rather than captive data center builds. Seoul Capital Area anchors the densest 5G gaming infrastructure globally, with Busan-Ulsan emerging as secondary edge node cluster.
India
Studios scaling from 50 to 500+ concurrent players outsource backend elasticity through hybrid server architectures. TRAI bandwidth allocation rules shape last-mile quality for cloud gaming delivery. Bangalore and Hyderabad clusters concentrate indigenous game development studios adopting WebAssembly containerization for browser-native deployment.
Brazil
ANVISA's digital health framework creates regulatory precedent for cloud-based interactive entertainment compliance. Latin America's largest gaming population opens to foreign BaaS entry through sandbox validation programs. São Paulo state anchors the dominant data center capacity serving Portuguese-language live service titles.
Cloud Gaming Baas Market Competitive Landscape
Listed leaders compete with private specialists across infrastructure provisioning and middleware specialization tiers. Hyperscale cloud providers dominate capital-intensive server deployment while independent SDK vendors capture latency-sensitive networking segments. Two strategic archetypes prevail: vertically integrated platform ecosystems and best-of-breed component specialists. Competitive moves concentrate on telecom bundling partnerships and AI-ML feature differentiation.
Within the hyperscale infrastructure tier, Amazon Web Services and Microsoft Azure exemplify platform-anchored competition leveraging console and enterprise ecosystem lock-in. Photon Engine occupies a specialist position emphasizing edge-node density for low-latency networking. Google Cloud represents the third listed anchor competing on container orchestration and streaming protocol integration.
| Leading Market Players |
|---|
| Unity Technologies |
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| PlayFab |
| Photon Engine |
| IBM |
| Back4App |
| ShepHertz Technologies |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with hyperscale cloud providers lock in GPU render-node access and price visibility for AAA studios, insulating procurement from NVIDIA silicon allocation volatility while committing to 3-year spend minimums that reshape vendor selection criteria.
Pricing Analysis
Current-generation AI-optimized streaming protocols command 40% per-session revenue premiums over prior-generation VM-based architectures, while next-generation WebAssembly containerization is compressing entry-tier pricing for browser-native deployments. Three-tier pricing structure across premium, standard, and economy levels separates dedicated server guarantees from shared infrastructure and freemium base tiers. Cost compression in the economy tier is intensifying because indie studios with sub-$2 million budgets prioritize 60-70% cost reduction over performance consistency. Mobile-first publishers exhibit highest price sensitivity due to unpredictable retention curves, whereas competitive multiplayer studios demonstrate lowest sensitivity where sub-20ms latency is non-negotiable.
Supply Chain Analysis
Inbound logistics costs for Frankfurt and Mumbai data center expansions hinge on container availability through Asia-Europe trade lanes, with ECHA chemical safety protocols indirectly shaping hardware procurement timelines. GPU supply concentrates in Taiwan, South Korea, and the United States, while edge compute assembly draws from China, Mexico, and Germany. Raw material dependencies span NVIDIA A100/H100 silicon, high-bandwidth memory modules, and liquid cooling infrastructure. Single-source vulnerability around NVIDIA's cloud gaming-optimized silicon creates procurement concentration risk. Distribution runs through direct hyperscale vendor relationships for AAA studios and telecom bundling channels for mid-tier publishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud Gaming BaaS operates as a defensive-moat market where switching costs between backend providers lock studios into integrated development pipelines, creating durable revenue visibility for incumbents with established platform ecosystems.
For Market Incumbents: Consolidate edge-node density advantages through Kubernetes orchestration talent acquisition in Seattle and San Francisco Bay Area clusters, countering Photon Engine's networking specialization. Deepen upstream control over GPU render-node capacity via long-term NVIDIA allocation agreements, mitigating silicon procurement vulnerability that constrains scaling. ISO 27001 certification investment accelerates studio onboarding timelines against compliance-heavy genre competitors. For New Entrants and Emerging Players: Anchor in Brazil's ANVISA sandbox validation programs where regulatory precedent for cloud-based interactive entertainment compliance remains underdeveloped among foreign BaaS providers. Target Indian studios scaling from 50 to 500+ concurrent players with hybrid server architectures that eliminate captive data center builds. WebAssembly containerization expertise enables browser-native deployment without app store approval delays, bypassing platform-specific SDK fragmentation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platform ecosystems over best-of-breed component specialists. Long-term viability across the projection horizon rests on AI-ML feature differentiation and telecom bundling channel control. Acquisition focus should center on middleware vendors with edge-node density and automated matchmaking IP. The signal to watch is FCC net neutrality classification clarity, which would unlock edge infrastructure capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Compute Expansion | AWS and Azure anchor sub-20ms latency guarantees for competitive multiplayer titles in United States clusters. |
| AI-ML Feature Integration | Automated matchmaking fused with generative NPC behavior creates 40% higher per-session revenue capture tiers. |
| Telecom Bundling Partnership | 5G operators white-label cloud gaming backends as subscriber retention tools, displacing direct-to-studio sales cycles. |
| Regulatory Compliance Certification | ISO 27001 and GDPR data-sovereignty controls accelerate European studio onboarding against non-compliant competitors. |
| WebAssembly Runtime Development | Browser-native 60fps gameplay eliminates app store approval delays for sub-$2 million indie studio budgets. |
Research Methodology
Initial hypotheses were tested against primary input from CTOs at gaming studios, platform engineers at hyperscale cloud providers, channel partners in telecom bundling arrangements, and integration specialists deploying WebAssembly containerization, then refined against secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile gaming telemetry, and FCC regulatory dockets. Bottom-up triangulation across service type segmentation and top-down cross-checks against aggregate BaaS infrastructure spend established analytical coherence.
Variance decomposition across the projection horizon isolates driver contributions from AI integration adoption curves, WebAssembly runtime proliferation rates, and regulatory compliance timeline shifts. Modeled dimensions span service architecture, delivery model, end-user category, and technology stack maturity, with regional cloud infrastructure density and developer ecosystem concentration as industry-specific overlays. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion boundaries.
Decision-makers should treat outputs as directional under assumptions of sustained GPU supply concentration and stable net neutrality classification; material deviation in NVIDIA allocation policy or FCC priority treatment would warrant model refresh. Specific risk factors include GDPR data-sovereignty mandate enforcement intensity and EU AI Act risk classification implementation timelines. Recalibration cycles align with material shifts in hyperscaler capex disclosure patterns and telecom bundling partnership announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Heavy Duty Traps Market
Others
Europe Polycarbonate Sheets Market
Others
Connected Homes Market
Others
Fire Sprinkler Market
Others
North America Luxury Car Market
Others
South Korea Intellectual Property Market
Others
Japan Automotive LED Lighting Market
Others
Senior Cat Food Market
Others
Smart TV Platforms Market
Others
France Smart Home Market
Others
Pediatric Measuring Devices Market
Others
Digital Tattoos Market
Others
Middle East Smart Home Market
Others
Australia Content Services Platform Market
Others
Banknote Printing Machine Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market