
 India Data Center Physical Security Market | 2026-2036
India Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Physical Security Market Insights
ISO 27001 certification is bifurcating the vendor landscape into qualified integrators and peripheral suppliers. Honeywell International Inc. leverages its building automation heritage to bundle physical security with critical power management. Godrej Security Solutions anchors its position through deep domestic manufacturing and channel density across Tier-2 cities. Bosch Sicherheitssysteme GmbH differentiates via German-engineered video analytics calibrated for tropical operating conditions.
India data center physical security encompasses perimeter hardening, biometric access layers, video surveillance with thermal failover, and fire suppression systems engineered for uninterrupted IT load protection. Equipment must maintain mean time between failures exceeding 50,000 hours while operating at ambient temperatures up to 45°C without climate-controlled enclosures. Surveillance Systems currently commands the largest product type share as camera density per megawatt rises with insurer mandates. Video Analytics within the technology dimension represents the fastest-expanding margin pool, driven by AI-enabled anomaly detection that reduces guard staffing ratios. Cloud Service Providers among end users are pulling disproportionate service-type revenue into Monitoring contracts spanning multi-site estates.
BIS certification under the Compulsory Registration Scheme gates market access for electronic security hardware, while CEA electrical safety standards govern backup power integration with physical access systems. MeitY guidelines on data localization indirectly amplify physical security spending as domestic data center capacity expands. Stakeholders must weigh biometric data storage compliance against the operational efficiency of unified identity platforms.
Market Dynamics
Hyperscale cloud buildouts across Maharashtra, Karnataka, and Telangana are compressing procurement cycles for integrated physical security systems, forcing vendors to bundle perimeter, access, and surveillance layers into single-contract deployments.
Growth Catalysts
- Cloud Service Provider Expansion:Hyperscale facility clusters in Hyderabad, Mumbai, and Bengaluru are pulling multi-site monitoring contracts and unified identity platform deployments at scale.
- BIS Compulsory Registration Scheme:Certification mandates for electronic security hardware are filtering out unqualified suppliers and consolidating procurement toward certified integrators.
- Thermal Video Analytics:AI-enabled anomaly detection calibrated for tropical ambient conditions up to 45°C is reducing guard staffing ratios while maintaining insurer-mandated camera density per megawatt.
Market Restraints
- Import Dependency for Critical Sensors:Thermal imaging cores and high-precision biometric modules concentrate supply among German and Japanese component specialists, exposing integrators to currency volatility and extended lead times.
- CEA Electrical Safety Integration:Backup power systems must synchronize with physical access controls under Central Electricity Authority standards, adding engineering complexity and certification delays to deployment timelines.
- Skill Scarcity in Tropical Calibration:Video analytics tuning for high-humidity, high-dust environments requires specialized field engineers, constraining rollout velocity in Tier-2 facility locations.
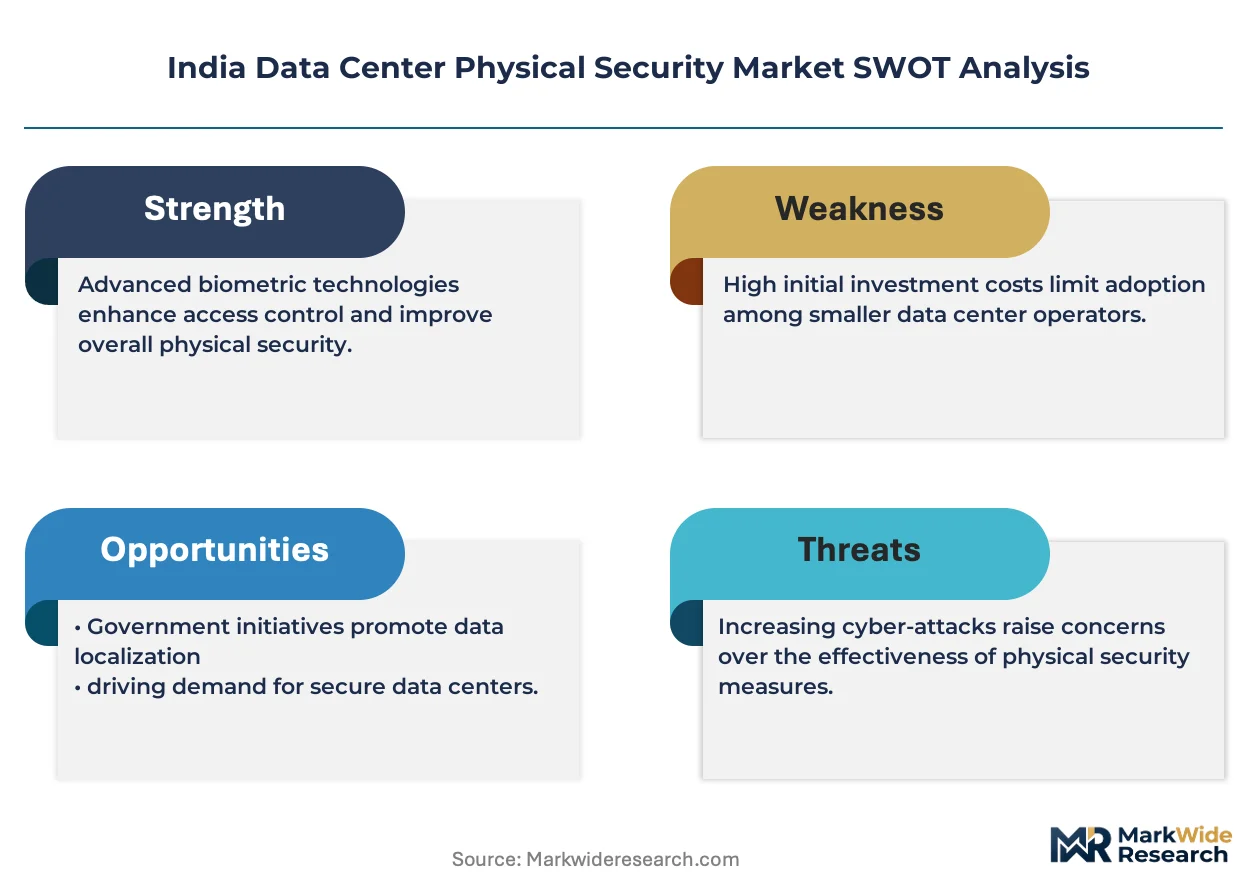
Strategic Opportunities
- Tier-2 City Data Center Clusters:Emerging facilities in Chennai, Pune, and Noida present underpenetrated demand for channel-dense integrators capable of rapid response outside metropolitan cores.
- MeitY Data Localization Tailwind:Domestic data center capacity expansion mandates are amplifying physical security spending as local storage requirements drive new construction.
- Convergence of Building Automation and Security:Integration of fire suppression, critical power management, and access control into unified command platforms creates service attach opportunities for systems integrators.
Industry Challenges
- Biometric Data Storage Compliance:Unified identity platforms face operational friction against evolving data protection requirements for fingerprint and iris template retention.
- ISO 27001 Certification Timeline:The bifurcation between qualified integrators and peripheral suppliers is compressing margins for vendors caught in extended audit and documentation cycles.
- Legacy Analog Surveillance Retrofit:Existing Tier-1 facilities require phased migration to IP-based thermal failover systems without disrupting uninterrupted IT load protection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Physical Security Market |
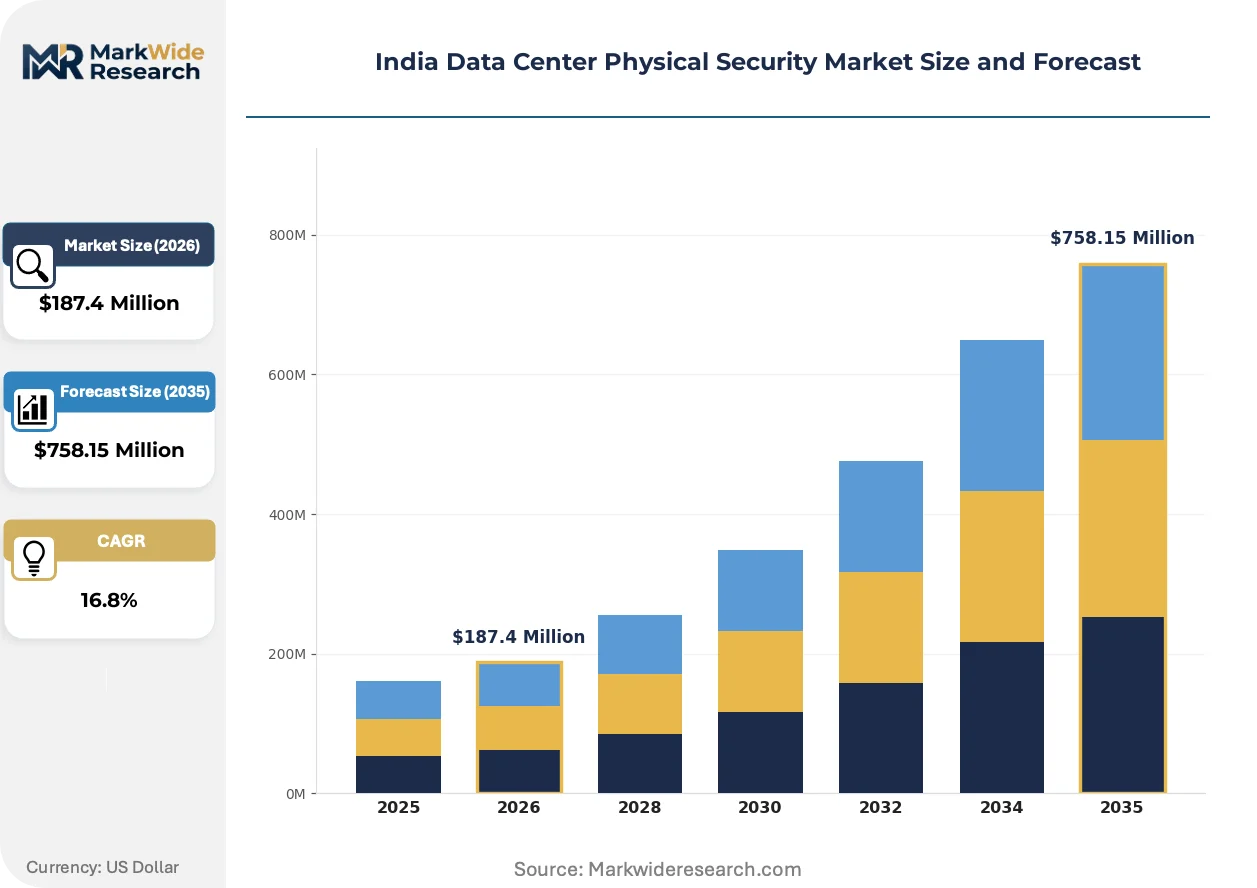
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control, Surveillance Systems, Fire Safety Equipment, Intrusion Detection Technology: Biometric Systems, RFID Solutions, Video Analytics, Motion Sensors End User: Telecommunications, Financial Institutions, Government Agencies, Cloud Service Providers Service Type: Consulting, Installation, Maintenance, Monitoring |
| Companies Covered | Axis Communications AB, CP Plus, Honeywell International Inc., Dahua Technology India, Hikvision India, Schneider Electric, Bosch Sicherheitssysteme GmbH, Godrej Security Solutions, Johnson Controls, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Physical Security Market Trends and Innovations
AI inference at the edge is restructuring how surveillance data gets processed, shifting computational load away from centralized servers toward camera-native analytics engines that operate independently during network interruptions.
Multi-spectral video analytics is supplanting conventional visible-spectrum monitoring in perimeter applications. The technology fuses thermal and optical feeds to eliminate false positives from wildlife and weather artifacts. Cloud service providers deploying hyperscale campuses are specifying these systems as baseline requirements. Guard staffing ratios compress by thirty to fifty percent where thermal-optical fusion achieves insurer-validated detection accuracy.
BIS certification under the Compulsory Registration Scheme is tightening market access gates for electronic security hardware. Non-certified equipment faces import prohibition and project disqualification regardless of technical specifications. Mid-tier integrators are responding by vertically integrating into domestic assembly or exclusive partnerships with certified component suppliers.
Cloud service providers are consolidating vendor relationships around multi-site estate monitoring contracts. Discrete product procurement is giving way to performance-based service agreements spanning five to seven year terms. This pattern concentrates most visibly in Maharashtra and Telangana where hyperscale clusters operate under unified security operations centers.
India Data Center Physical Security Market Segmentation
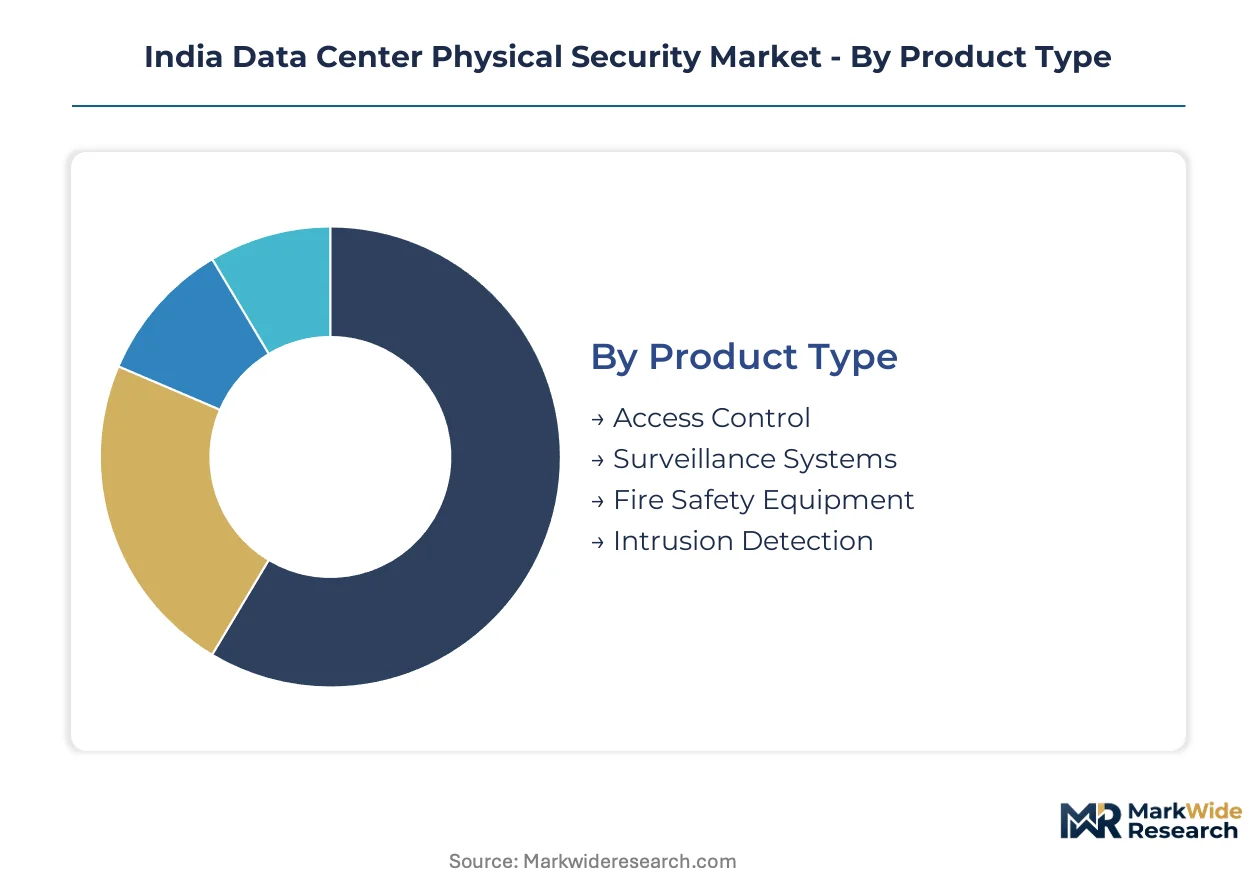
Segmentation in India's data center physical security market reveals how BIS certification tiers and tropical operating requirements reshape procurement patterns across equipment categories and service layers.
Product Type:
BIS Compulsory Registration Scheme gates market access differently across hardware categories, with thermal-rated equipment facing stricter ambient temperature validation protocols.
- Surveillance Systems:Camera density per megawatt has become the baseline procurement metric, with thermal failover specifications mandatory for insurer compliance in hyperscale facilities. Maharashtra and Telangana clusters are pulling multi-site deployments with unified video management platforms.
- Access Control:Biometric readers and card-based systems must maintain mean time between failures exceeding 50,000 hours while operating at 45°C without climate-controlled enclosures. Karnataka facilities are consolidating around unified identity platforms that integrate with critical power management.
- Fire Safety Equipment:Clean agent suppression systems engineered for uninterrupted IT load protection dominate Tier-1 deployments.
- Intrusion Detection:Perimeter hardening solutions with multi-spectral sensing are specified for hyperscale campus boundaries.
Surveillance Systems handles the majority of throughput; Video Analytics integration is expanding most quickly within this category.
Technology:
Cost tier differentiation separates premium AI-enabled analytics from standard sensor deployments, with tropical calibration capabilities commanding pricing premiums.
- Video Analytics:AI-enabled anomaly detection calibrated for high-humidity, high-dust environments reduces guard staffing ratios by thirty to fifty percent where insurer-validated accuracy is achieved. Cloud service providers in Hyderabad and Mumbai are specifying thermal-optical fusion as baseline for new hyperscale campuses.
- Biometric Systems:Fingerprint and iris recognition modules face operational friction against evolving data protection requirements for template retention, complicating unified identity platform deployments. Financial institutions in Bengaluru are driving demand for multi-factor authentication integration.
- RFID Solutions:Contactless access credentials remain standard for peripheral zone management in Tier-2 city facilities.
- Motion Sensors:PIR and microwave-based detection supplement perimeter layers in legacy facility retrofits.
Video Analytics is climbing the fastest on share; Biometric Systems carries the heaviest compliance overhead.
End User:
Customer type concentration maps directly to data center construction velocity, with cloud buildouts compressing procurement cycles toward bundled system deployments.
- Cloud Service Providers:Hyperscale operators are consolidating vendor relationships around five-to-seven-year performance-based service agreements spanning multi-site estates. Maharashtra, Karnataka, and Telangana facility clusters operate under unified security operations centers with centralized monitoring contracts.
- Telecommunications:Carrier-neutral facilities require discrete perimeter and access layers with interconnection security protocols. Mumbai and Chennai exchanges are retrofitting IP-based thermal failover without disrupting uninterrupted IT load protection.
- Financial Institutions:RBI data localization requirements amplify physical security spending for domestic storage mandates.
- Government Agencies:MeitY guidelines on data sovereignty drive procurement through certified integrators with ISO 27001 qualification.
Cloud Service Providers command the dominant share of new contract value; Financial Institutions are expanding fastest on regulatory tailwinds.
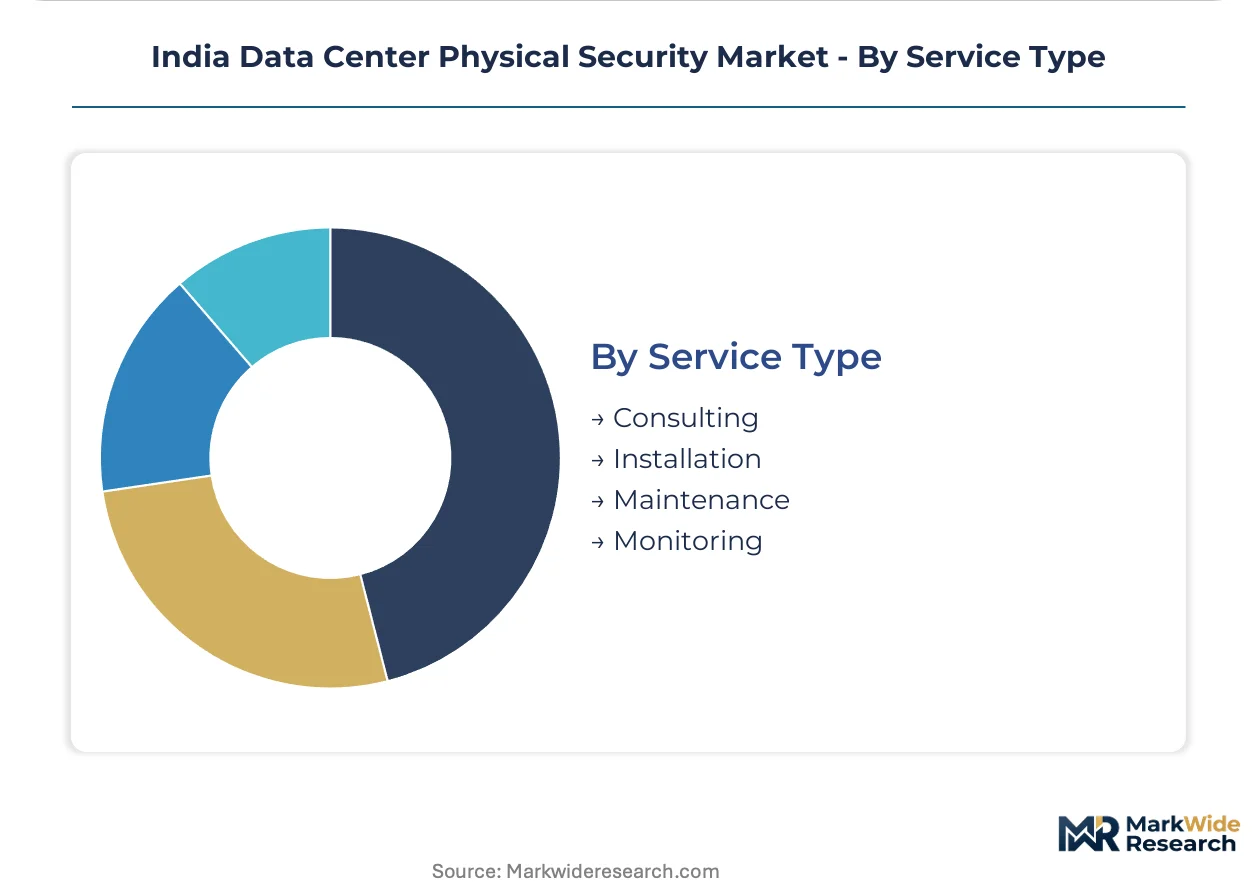
Service Type:
Margin structure inverts from product-heavy to service-heavy as contracts extend in duration, with monitoring services capturing recurring revenue pools.
- Monitoring:Multi-site estate contracts spanning five-to-seven-year terms are concentrating procurement toward qualified integrators with ISO 27001 certification. Cloud service providers in Hyderabad and Bengaluru are pulling disproportionate revenue into unified security operations center deployments.
- Maintenance:Tropical calibration requirements for video analytics create attach opportunities for specialized field engineering services. Tier-2 city clusters in Pune and Noida face skill scarcity constraints on rollout velocity.
- Installation:CEA electrical safety standards add engineering complexity to backup power synchronization with physical access systems.
- Consulting:Compliance navigation for BIS certification and biometric data storage requirements drives advisory demand.
Monitoring captures the largest recurring revenue pool; Maintenance is gaining share fastest on tropical calibration specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai-Chennai industrial corridor and the Dedicated Freight Corridor network underwrite Maharashtra's primacy in data center infrastructure buildout. Karnataka's Bangalore-Chennai expressway and submarine cable landings at Cochin and Chennai anchor its hyperscale cluster expansion. Telangana's Hyderabad Metro and Rajiv Gandhi International Airport logistics zone enable rapid facility deployment timelines.
Maharashtra
Mumbai's submarine cable density and Navi Mumbai land banking attract hyperscale cloud campuses requiring integrated perimeter hardening. BIS Compulsory Registration Scheme compliance gates equipment procurement for Thane and Panvel facility clusters. MMRDA infrastructure financing accelerates data center zone development along the Mumbai-Pune expressway corridor.
Karnataka
Bengaluru's startup ecosystem and Whitefield electronics manufacturing cluster drive demand for biometric access layers and thermal failover surveillance. MeitY data localization guidelines amplify physical security spending for domestic storage mandates. Hoskote and Devanahalli facility zones concentrate multi-site monitoring contract awards.
Telangana
Hyderabad's Genome Valley pharmaceutical corridor and Financial District fintech concentration require uninterrupted IT load protection with clean agent suppression. CEA electrical safety standards govern backup power synchronization with physical access systems in Gachibowli and Uppal clusters. TS-iPASS industrial clearance mechanisms compress deployment timelines for certified integrators.
Tamil Nadu
Chennai's submarine cable landing stations and Sriperumbudur automotive electronics corridor attract carrier-neutral facilities with interconnection security protocols. TANFAC industrial park incentives support Tier-2 city expansion beyond metropolitan cores. Coimbatore and Madurai emerging clusters face skill scarcity constraints on tropical calibration rollout velocity.
Delhi-NCR
Noida and Greater Noida's Yamuna Expressway industrial zones benefit from proximity to government data sovereignty requirements. RBI data localization mandates for financial institutions drive physical security procurement for domestic storage. Haryana's Manesar and Sohna facility corridors operate under unified security operations center specifications.
India Data Center Physical Security Market Competitive Landscape
Listed building automation conglomerates compete with private domestic specialists across certification depth and channel density. The vendor landscape bifurcates around ISO 27001 qualification tiers, with certified integrators consolidating procurement toward multi-site estate contracts. Three archetypes dominate: German-engineered precision specialists, Indian manufacturing anchors with Tier-2 city penetration, and building automation bundlers integrating critical power with access layers. Competitive moves concentrate on exclusive distribution partnerships with BIS-certified component suppliers and backward integration into domestic assembly capacity.
Among German-engineered precision specialists, Bosch Sicherheitssysteme GmbH exemplifies tropical-calibrated video analytics positioning. Honeywell International Inc. occupies the building automation convergence archetype, bundling physical security with critical power management. Godrej Security Solutions anchors the domestic manufacturing tier through deep channel density across Tier-2 cities. These three represent the certification-qualified integrator segment capturing disproportionate multi-site monitoring contract value.
| Leading Market Players |
|---|
| Axis Communications AB |
| CP Plus |
| Honeywell International Inc. |
| Dahua Technology India |
| Hikvision India |
| Schneider Electric |
| Bosch Sicherheitssysteme GmbH |
| Godrej Security Solutions |
| Johnson Controls |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for thermal imaging cores from German and Japanese component specialists concentrate pricing power among certified integrators with established supplier relationships, while BIS Compulsory Registration Scheme compliance gates create cost premiums for non-certified hardware alternatives. This inventory compression forces mid-tier vendors toward domestic assembly partnerships or exclusive distribution agreements with certified component suppliers, reshaping procurement economics across Maharashtra and Telangana hyperscale clusters.
Pricing Analysis
Volume-discount tiering structures stratify across certified-premium, standard-BIS-compliant, and economy-non-certified equipment levels, with cloud service providers extracting fifteen to twenty percent unit cost reductions on multi-site estate contracts exceeding five-year terms. Price differentiation centers on ISO 27001 certification depth and tropical calibration capabilities for 45°C ambient operation, with uncertified integrators facing margin compression from extended audit timelines. Pricing pressure intensifies in the standard tier as CEA electrical safety integration requirements add engineering overhead to backup power synchronization projects. Financial institutions in Bengaluru demonstrate lowest price sensitivity due to RBI data localization mandates, while Tier-2 city facilities in Pune and Noida prioritize economy-tier procurement despite higher failure rates.
Supply Chain Analysis
Inventory lead times stretching ninety to one hundred twenty days for thermal imaging cores and high-precision biometric modules expose integrators to currency volatility and project scheduling risk. Supply concentrates among German and Japanese component specialists for critical sensors, with domestic assembly capacity expanding for peripheral equipment categories. Raw material dependencies include germanium substrates for thermal optics, CMOS sensors for visible-spectrum cameras, and specialized alloys for biometric reader housings. Single-source vulnerability from concentrated thermal core manufacturing creates procurement risk for multi-site deployment timelines. Distribution runs through certified integrator channels with ISO 27001 qualification, consolidating procurement toward vendors with backward integration into domestic assembly or captive partnerships with BIS-certified component suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from tropical calibration maintenance and multi-site monitoring contracts is expanding faster than hardware procurement as cloud service providers consolidate around performance-based agreements spanning five-to-seven-year terms.
For Market Incumbents: Secure exclusive distribution partnerships with BIS-certified component suppliers to defend margin position against mid-tier integrators vertically integrating into domestic assembly. Invest in tropical calibration field engineering capacity to capture maintenance attach revenue from Tier-2 city cluster expansion. Certification depth under ISO 27001 and CEA electrical safety standards represents the primary defensive moat against price-competitive entrants. For New Entrants and Emerging Players: Anchor in Chennai and Noida carrier-neutral facilities where interconnection security protocols create white-space demand outside hyperscale vendor consolidation. Target Tier-2 city clusters in Coimbatore and Madurai facing skill scarcity constraints on tropical calibration rollout velocity. A go-to-market angle emphasizing rapid-response field engineering for high-humidity, high-dust environment tuning differentiates against metropolitan-focused incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from building automation conglomerates seeking to divest non-core physical security divisions amid convergence pressure from critical power management bundling. Long-term viability favors integrators with captive tropical calibration capabilities and ISO 27001-qualified multi-site monitoring infrastructure. The signal to watch is TS-iPASS industrial clearance acceleration in Telangana compressing deployment timelines for certified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | Backward integration into BIS-certified component supply reduces import dependency exposure for thermal imaging cores. |
| Tropical Calibration Service Expansion | Specialized field engineering for 45°C ambient operation captures recurring revenue from Tier-2 city clusters. |
| Multi-Site Monitoring Platform | Unified security operations center deployments consolidate cloud service provider contracts across Maharashtra and Telangana. |
| ISO 27001 Certification Investment | Audit qualification gates procurement toward certified integrators and filters peripheral suppliers from hyperscale tenders. |
| CEA Electrical Safety Integration | Backup power synchronization capabilities add engineering complexity premiums to access control deployment contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS registration databases, CEA electrical safety filings, and hyperscaler capex disclosures through structured interviews with data center facility managers, physical security procurement officers, certified systems integrators, and tropical calibration field engineers. Primary data collection combined facility deployment timelines, certification audit documentation, and component sourcing patterns with secondary validation from MeitY data localization guidelines, RBI storage mandate circulars, and TS-iPASS industrial clearance records. Bottom-up equipment shipment analysis triangulates against top-down construction pipeline tracking across Mumbai, Bengaluru, Hyderabad, Chennai, and Noida metropolitan zones.
Segmentation dimensions modeled span product type, technology tier, end-user vertical, and service layer across the projection horizon, with additional granularity on BIS certification status and tropical operating specification compliance. Analytical framework incorporates facility megawatt-scale camera density requirements, insurer-mandated thermal failover specifications, and guard staffing ratio compression targets from AI-enabled video analytics deployment. CAGRs derive from facility construction velocity in certified versus non-certified procurement corridors, with sensitivity analysis on import duty exposure and currency fluctuation impacts for thermal core components.
Material uncertainties — regulatory revision to biometric data storage requirements, BIS Compulsory Registration Scheme scope expansion, and CEA electrical safety standard updates — sit outside the modeled envelope and could accelerate or delay procurement cycles. Forecasts reflect assumptions on cloud service provider buildout continuity, TS-iPASS clearance velocity, and tropical calibration skill pipeline development. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Process Instrumentation Equipment Market
Others
Reef Aquarium Market
Others
Reusable Wine Bags Market
Others
Global Injectable Nanomedicine Market
Others
Fluid Bed Systems Market
Others
GCC Shisha Tobacco Market
Others
Cat Dry Food Market
Others
Bimodal Identity Management Solutions Market
Others
Global Transparent Plastics Market
Others
Human Enhancement Technology Market
Others
Global Human Augmentation Market
Others
Canada 3D Printing Construction Market
Others
Digital Signage Media Player Market
Others
Vegetable Carbon Market
Others
Global Telemetry Market
Others
Live IP Broadcast Equipment Market