
 Folding Mobile Phone Market | 2026-2036
Folding Mobile Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Folding Mobile Phone Market Insights
Enterprise buyers and tech enthusiasts is bifurcating the customer base away from early mainstream consumers. Samsung Electronics Co. Ltd. leverages its vertically integrated display division to control hinge and panel supply. Huawei Technologies Co. Ltd. competes through proprietary ultra-thin glass and satellite connectivity integration. Motorola Mobility LLC anchors its position in the compact flip form factor with aggressive carrier distribution in North America.
A folding mobile phone employs a flexible display substrate, typically polyimide-backed OLED with a multi-link hinge mechanism rated for hundreds of thousands of fold cycles, designed to combine smartphone portability with expanded tablet-class screen real estate. Flip phones dominate volume shipments due to lower entry pricing and pocket-friendly dimensions, while booklet phones capture premium margin pools through productivity-oriented screen expansion. OLED technology leads panel supply, though E-Ink variants are emerging for power-efficient secondary displays and outdoor readability.
The FCC governs electromagnetic emissions and SAR limits for devices sold in the United States, while the EU's RoHS and REACH directives restrict hazardous substances in flexible electronics and hinge assemblies. China's MIIT enforces network access licenses and domestic 5G band certification, shaping which models launch in mainland markets. Stakeholders must monitor how divergent e-waste and repairability mandates across these jurisdictions affect modular design investments and aftermarket service economics.
Market Dynamics
Display substrate innovation and hinge mechanism durability requirements are forcing manufacturers to deepen backward integration into polyimide supply and precision component fabrication. The tension between premium positioning and mass-market accessibility is compressing margin structures across all form factors.
Growth Catalysts
- Enterprise Mobility Mandates:Fortune 500 procurement departments are adding foldable devices to approved hardware catalogs, creating institutional pull for booklet-style phones with DeX-style desktop modes.
- REACH Substance Waivers:The EU's phased exemptions for flexible circuit substrates are enabling thinner, lighter hinge assemblies without immediate redesign cycles.
- Ultra-Thin Glass Diffusion:UTG cover layer adoption is expanding from flagship tier to upper-midrange flip phones, broadening addressable consumer segments.
Market Restraints
- Polyimide Concentration:Over 70% of high-temperature PI film supply originates from Japanese and South Korean chemical conglomerates, creating single-source vulnerability.
- FCC Certification Burden:SAR testing protocols for multi-position foldable antennas extend certification timelines by 4-6 months versus rigid smartphones.
- Mechanical Degradation Rates:Real-world fold cycle performance in dusty environments trails laboratory ratings by 30-40%, elevating warranty reserve requirements.
Strategic Opportunities
- India PLI Scheme:Domestic assembly incentives for display module integration are attracting contract manufacturers to establish foldable final assembly lines in Tamil Nadu and Uttar Pradesh.
- E-Ink Secondary Displays:Power-efficient always-on exterior screens are converging with notification management workflows, opening differentiation in business-oriented flip phones.
- Carrier Subsidy Restructuring:US operators are unbundling device financing from service contracts, enabling 24-month upgrade cycles that match foldable replacement cadences.
Industry Challenges
- Hinge Assembly Talent Scarcity:Precision mechanical engineering expertise for multi-link cam mechanisms concentrates in Suwon, Shenzhen, and Nagoya industrial clusters.
- microLED Transfer Yields:Mass transfer equipment for sub-50 micrometer chips remains bottlenecked at pilot-scale throughput, delaying cost parity timelines.
- RoHS Exemption Management:Rolling expiry dates for lead-containing solder in flexible PCB interconnects force continuous material qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Folding Mobile Phone Market |
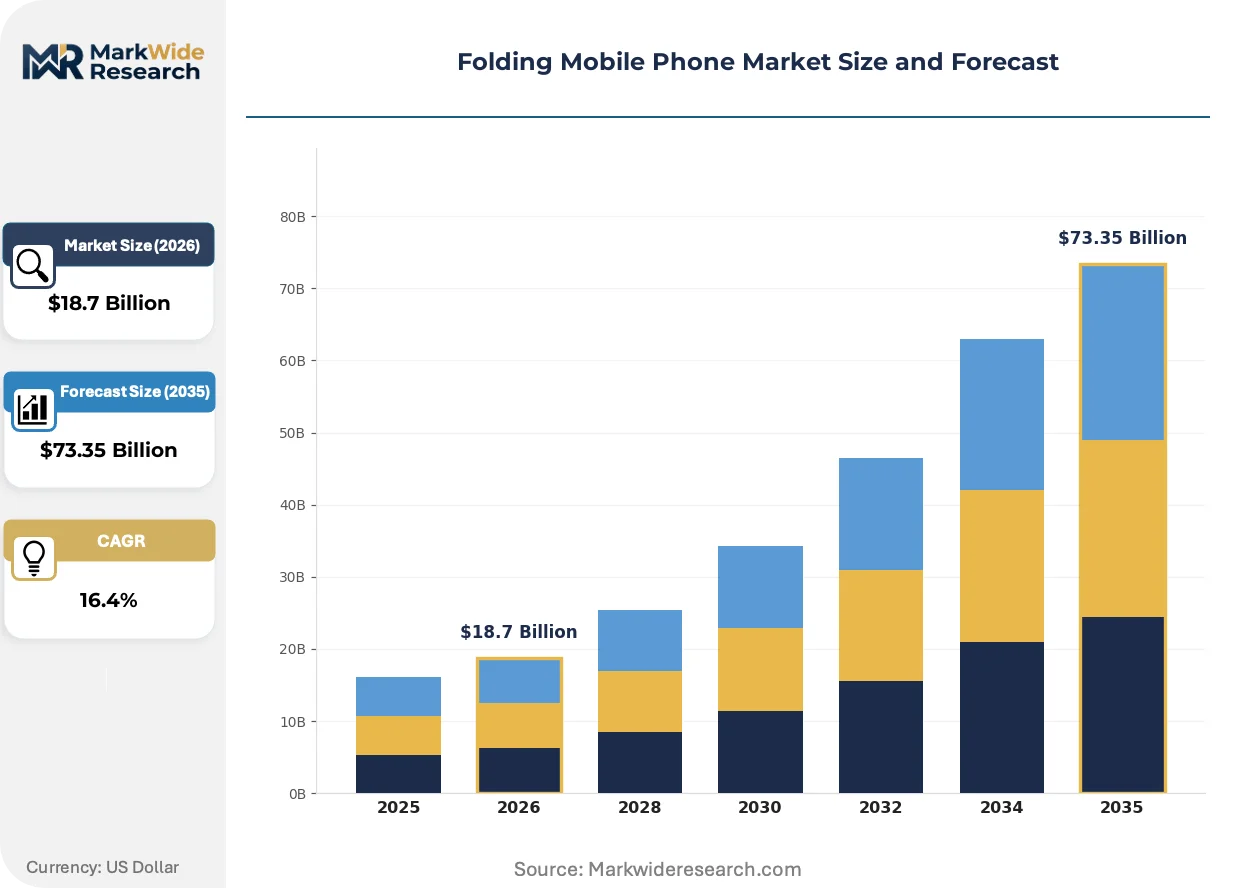
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flip Phones, Booklet Phones, Rollable Phones, Dual-Screen Phones Technology: OLED, LCD, E-Ink, MicroLED End User: Consumers, Business Professionals, Gamers, Tech Enthusiasts Distribution Channel: Online Retail, Electronics Stores, Carrier Stores, Third-Party Resellers |
| Companies Covered | Samsung Electronics Co. Ltd., Huawei Technologies Co. Ltd., Motorola Mobility LLC, Xiaomi Corp., Oppo Co. Ltd., vivo Communication Technology Co. Ltd., Honor Device Co. Ltd., Google LLC, OnePlus Technology (Shenzhen) Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Folding Mobile Phone Market Trends and Innovations
Materials science breakthroughs and procurement model evolution are restructuring competitive advantage away from brand marketing toward supply chain control and enterprise channel penetration.
Ultra-thin glass cover layers are displacing CPI (colorless polyimide) as the dominant foldable display surface material. Enterprise buyers with 36-month depreciation cycles are specifying UTG for scratch resistance and optical clarity. This displacement is compressing the addressable market for CPI specialists and rewarding glass-chemical vertical integration.
China's MIIT network access license requirements are tightening electromagnetic compatibility testing for satellite connectivity modules. Domestic manufacturers must pre-certify dual-mode 5G/satellite antenna configurations before mainland launch. Flagship booklet phones with emergency messaging capabilities face 90-day additional approval timelines versus standard SKUs.
Corporate procurement departments are consolidating mobility spend under device-as-a-service contracts that include damage protection and refresh guarantees. Telecom resellers are displacing retail channels for volumes above 500 units annually. This shift is most visible in US financial services and professional services verticals where IT departments prioritize standardized support over consumer feature differentiation.
Folding Mobile Phone Market Segmentation
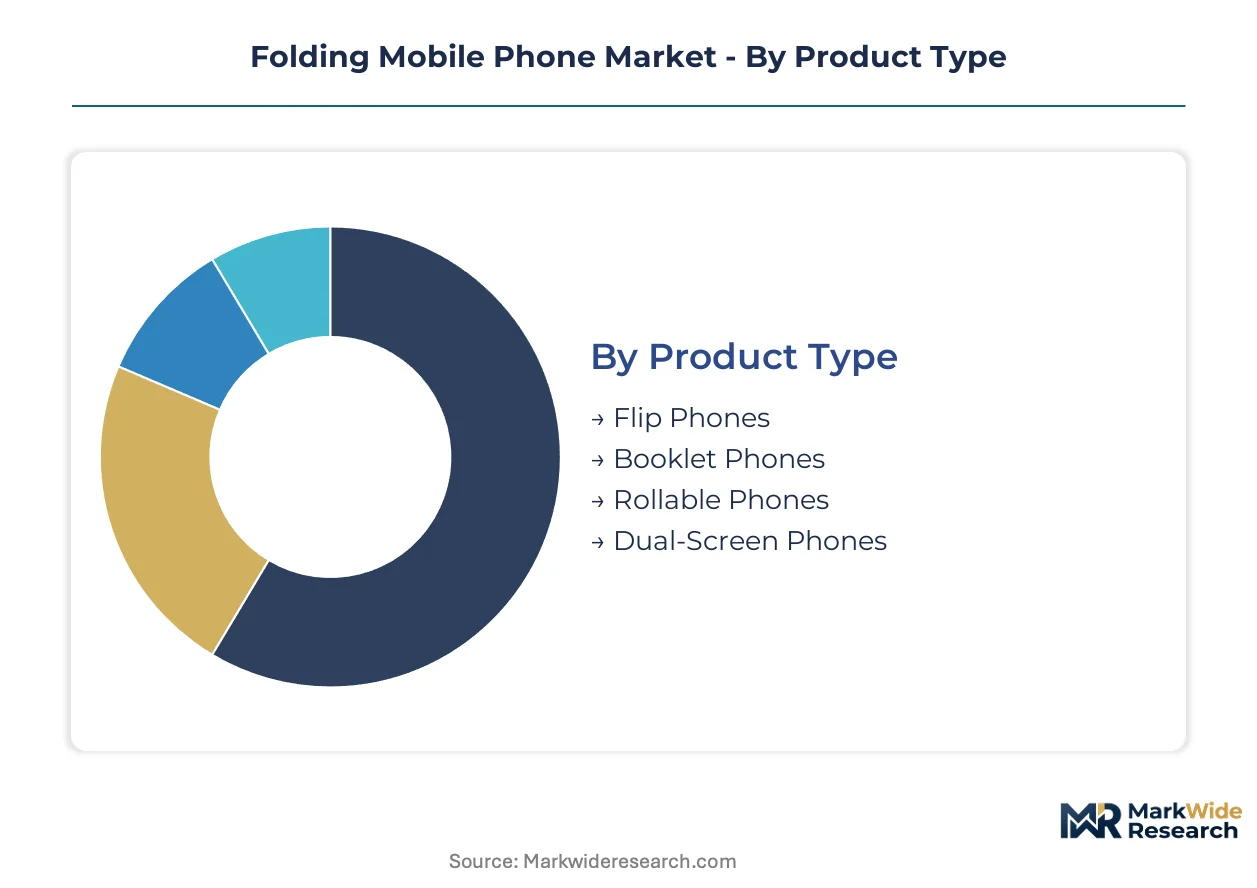
Segmentation in the folding mobile phone market determines which supply chain configurations and channel investments yield sustainable returns. Form factor and display technology choices dictate manufacturing complexity, while end-user profiles shape warranty terms and service attach rates.
Product Type:
Carrier stores and electronics retailers push flip phones through subsidized upgrade programs, while booklet phones flow through enterprise resellers and direct-to-business channels. Rollable and dual-screen variants remain concentrated in online retail and flagship brand stores due to limited inventory depth.
- Flip Phones:Clamshell designs with vertical folding displays utilize single-axis hinge mechanisms and smaller flexible panels. Demand clusters in North American carrier channels where pocketability drives consumer preference, though warranty claim rates for hinge debris ingress elevate service costs.
- Booklet Phones:Horizontal-folding tablet-class devices employ multi-link hinges and larger display substrates. Enterprise procurement in US financial services and South Korean conglomerates specifies these for DeX-style desktop productivity, creating institutional pull distinct from consumer markets.
- Rollable Phones:Motorized extending displays using scroll-type mechanisms remain pilot-scale with limited commercial availability.
- Dual-Screen Phones:Rigid displays paired with mechanical hinges bypass flexible substrate challenges but add thickness and weight penalties.
Flip phones dominate installed base. Booklet phones are where expansion concentrates.
Technology:
Cost tiers separate display technologies sharply. OLED commands premium positioning through carrier flagship programs. E-Ink and microLED occupy experimental niches with specialized distribution through direct manufacturer channels and industrial supply partners.
- OLED:Polyimide-backed organic emitters with thin-film encapsulation deliver color saturation and bend radius performance required for mainstream foldables. South Korean and Chinese panel fabs supply nearly all commercial volume, with UTG cover layers displacing CPI at upper price tiers.
- LCD:Rigid backlight architectures limit application to dual-screen hinge mechanisms rather than true flexible implementations.
- E-Ink:Bistable electrophoretic displays enable always-on exterior notification panels with near-zero standby power draw. Business-oriented flip phones from Chinese manufacturers integrate these for outdoor readability and battery extension.
- MicroLED:Inorganic emitter microchips promise brightness and lifetime advantages but remain constrained by mass transfer yield bottlenecks at sub-50 micrometer die sizes.
OLED captures current revenue concentration. E-Ink secondary displays are gaining share fastest in enterprise flip phone configurations.
End User:
Volume concentration sits with consumers, but margin extraction depends on business professionals and tech enthusiasts who accept premium pricing and service contracts. Gamers represent a nascent segment with specialized cooling and latency requirements.
- Consumers:Price-sensitive purchasers responding to carrier subsidy structures and trade-in programs. Replacement cycles align with 24-month financing terms, with flip phones preferred for pocketability and social photography use cases.
- Business Professionals:Corporate mobility spend owners specifying booklet phones with desktop mode compatibility and MDM enrollment. US and South Korean Fortune 500 procurement departments drive institutional adoption through device-as-a-service contracts.
- Gamers:Performance-focused users requiring thermal management and touch sampling rate optimization for expanded-screen mobile gaming.
- Tech Enthusiasts:Early adopters purchasing through direct channels and participating in beta software programs, accepting higher defect rates for feature access.
Consumers dominate installed base. Business professionals are where expansion concentrates.
Distribution Channel:
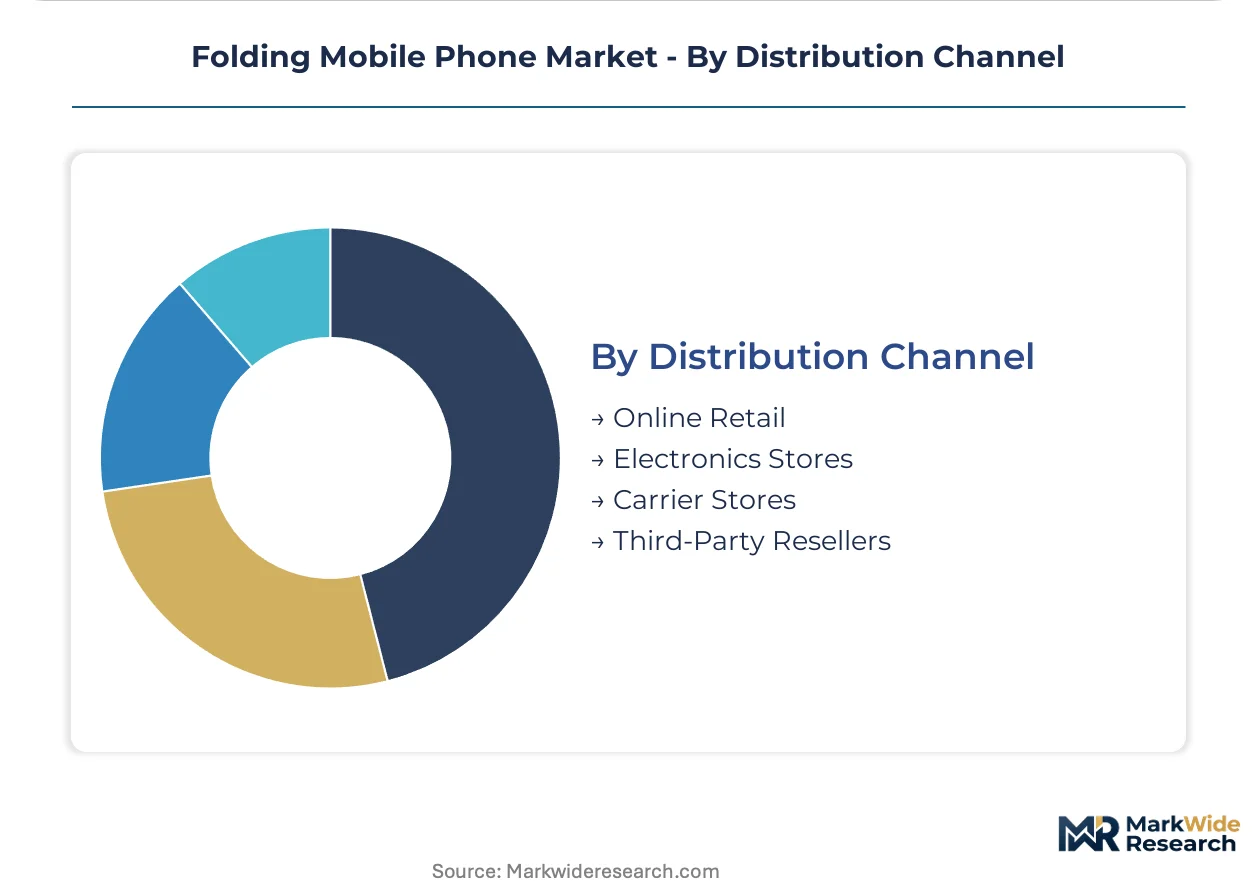
Geographic maturity determines channel mix. Developed markets concentrate carrier store and online retail volume. Emerging markets rely more heavily on electronics stores and third-party resellers with cash transaction preference.
- Online Retail:Direct manufacturer storefronts and marketplace platforms capture tech enthusiast and early adopter segments with full product range availability. Samsung and Huawei direct channels bypass retail margin extraction in domestic markets.
- Electronics Stores:Physical retail with assisted selling environment supports consumer education for first-time foldable purchasers. Chinese and Indian urban markets maintain high electronics store dependence.
- Carrier Stores:Subsidized device financing and network service bundling dominate North American and South Korean volume. FCC certification timelines and SAR testing protocols for foldable antennas extend carrier SKU approval cycles.
- Third-Party Resellers:Independent distributors and gray market channels serve price-sensitive segments and geographic markets with limited official distribution.
Carrier stores dominate installed base in subsidized markets. Online retail is where expansion concentrates as financing unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports display substrates and hinge mechanisms to assembly operations in Vietnam and India. Chinese manufacturers source UTG cover layers from German chemical specialists. The United States imports finished devices while domestic carriers shape certification requirements.
South Korea
Enterprise procurement from conglomerate headquarters drives booklet phone volumes in Seoul. The MFDS enforces electromagnetic compatibility standards for satellite connectivity modules. Suwon hosts precision hinge engineering clusters where multi-link cam mechanism expertise concentrates.
China
Domestic 5G band certification and MIIT network access licenses determine mainland launch timelines. The MIIT mandates pre-certification of dual-mode antenna configurations for emergency messaging capabilities. Shenzhen fabrication clusters handle flexible PCB interconnect assembly for export markets.
United States
Carrier subsidy restructuring and device-as-a-service contracts reshape procurement patterns for Fortune 500 mobility departments. The FCC governs SAR limits and extends certification timelines for multi-position foldable antennas. California enterprise IT departments specify DeX-compatible devices for hybrid workforce deployments.
Japan
High-temperature polyimide film supply from chemical conglomerates feeds substrate production across East Asia. METI coordinates industrial standards for flexible electronics manufacturing. Nagoya precision engineering clusters supply multi-link hinge components to Korean assembly operations.
India
PLI scheme incentives for display module integration attract contract manufacturers to Tamil Nadu and Uttar Pradesh. The BIS enforces conformity assessment procedures for imported electronic components. Electronics manufacturing clusters in Noida and Sri City scale final assembly capacity for domestic consumption and re-export.
Folding Mobile Phone Market Competitive Landscape
Player mix skews toward diversified electronics conglomerates with captive display divisions. Market structure concentrates around three Korean and Chinese manufacturers controlling hinge supply and panel fabrication. Strategic archetypes include vertically integrated conglomerates, specialist flip-phone vendors, and ecosystem-anchored software-hardware integrators. Dominant competitive moves encompass backward integration into polyimide supply and carrier-exclusive distribution partnerships.
Within the vertically integrated tier, Samsung Electronics Co. Ltd. and Huawei Technologies Co. Ltd. occupy positions defined by in-house control over critical substrate and hinge component supply. Motorola Mobility LLC anchors the compact flip form factor archetype through North American carrier channel relationships. These three entities exemplify how supply chain configuration and distribution architecture determine competitive positioning in premium and mid-tier segments respectively.
| Leading Market Players |
|---|
| Samsung Electronics Co. Ltd. |
| Huawei Technologies Co. Ltd. |
| Motorola Mobility LLC |
| Xiaomi Corp. |
| Oppo Co. Ltd. |
| vivo Communication Technology Co. Ltd. |
| Honor Device Co. Ltd. |
| Google LLC |
| OnePlus Technology (Shenzhen) Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for UTG cover layers and polyimide substrates lock Korean and Chinese manufacturers into price visibility while securing volume commitments from German chemical specialists and Japanese film suppliers. These arrangements insulate flagship tier pricing from spot-market volatility in display materials.
Pricing Analysis
Current-generation OLED booklet phones command substantial premiums over prior-generation CPI-based flip phones, while next-generation microLED prototypes remain priced at experimental tiers inaccessible to mainstream buyers. Three-tier pricing structure across premium UTG-flagship, standard CPI-upper-midrange, and economy hinge-repair-service tiers segments the market. Cost compression in the standard tier intensifies as Chinese panel fabs expand capacity. Consumers exhibit highest price sensitivity, while enterprise procurement departments accept premium positioning for DeX-compatibility and MDM enrollment.
Supply Chain Analysis
Container availability constraints on the Busan-to-Vietnam trade lane elevate inbound logistics costs for hinge mechanism assemblies destined for final integration. Manufacturing concentrates in South Korea, China, and Vietnam, with South Korean fabs supplying flexible OLED substrates and Chinese facilities handling PCB interconnect assembly. The supply chain rests on high-temperature polyimide from Japanese chemical conglomerates, UTG from German specialists, and precision cam components from Nagoya engineering clusters. Single-source vulnerability in polyimide film creates structural risk. Distribution runs through carrier stores in North America, direct manufacturer channels in China, and electronics retailers in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where damage protection contracts and device-as-a-service refresh guarantees expand faster than hardware shipments, particularly among Fortune 500 mobility departments.
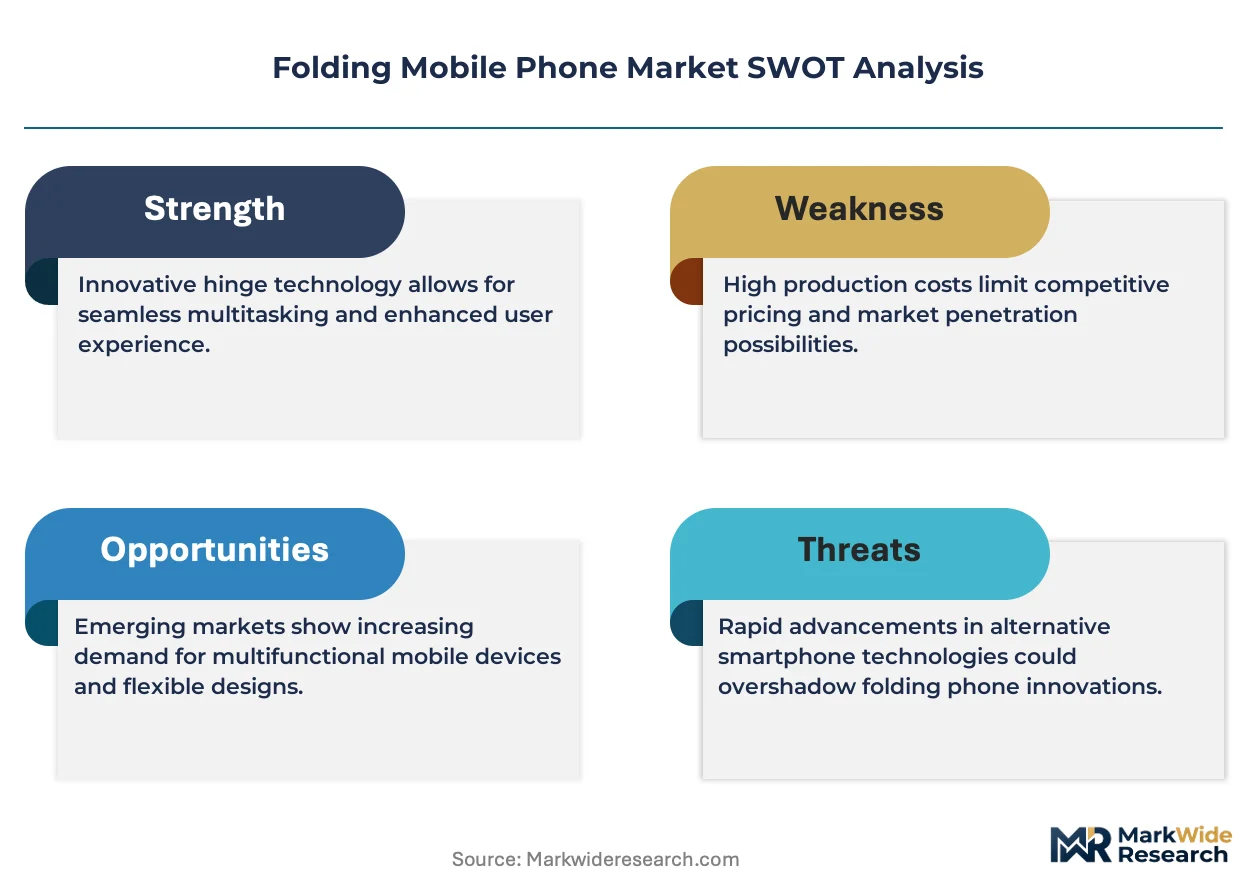
For Market Incumbents: Compound hinge mechanism durability advantages through captive UTG supply agreements while accelerating FCC pre-certification investments to compress carrier approval timelines. MicroLED transfer yield breakthroughs from specialist equipment vendors threaten OLED substrate incumbency. Backward integration into polyimide film production defends margin position against Japanese chemical supplier concentration. For New Entrants and Emerging Players: BIS fast-track conformity assessment for Tamil Nadu and Uttar Pradesh assembly operations enables cost-competitive positioning against established Korean and Chinese manufacturers. White-space concentrates in India PLI-subsidized production for domestic consumption and African markets with limited official distribution. Enterprise flip phones with E-Ink secondary displays offer the most penetrable segment. Carrier-exclusive distribution partnerships in North America provide viable go-to-market angles against Samsung and Motorola channel control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device-as-a-service providers with corporate damage protection attach rates exceeding consumer retail. Long-term viability favors manufacturers with in-house display divisions and enterprise channel relationships rather than assembly-only contract manufacturers. Acquisition targets include precision hinge engineering specialists in Suwon and Shenzhen industrial clusters. Monitor microLED mass transfer yield announcements as inflection indicators for next-generation display substrate displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyimide Supply | Samsung's captive film production reduces dependence on Japanese chemical conglomerates. |
| Enterprise Device-as-a-Service Launch | Telecom resellers displace retail channels for US financial services mobility contracts. |
| UTG Cover Layer Adoption Expansion | German chemical specialists broaden addressable market beyond flagship tier. |
| India PLI Assembly Investment | Tamil Nadu and Uttar Pradesh facilities capture domestic demand and re-export volumes. |
| E-Ink Secondary Display Integration | Chinese manufacturers differentiate business-oriented flip phones through power efficiency. |
Research Methodology
The analysis maps flip phone, booklet phone, and rollable form factor segments, each validated through procurement directors at Fortune 500 enterprises, carrier device financing executives, and precision hinge engineering specialists. Primary interviews with display substrate procurement leads, FCC certification consultants, and MIIT network access license advisors combined with secondary validation from SEC 10-K filings, MIIT network access license databases, and customs trade data. Bottom-up assembly cost modeling and top-down carrier shipment estimates triangulate market sizing.
Consistency checks validated volume and value outputs against carrier subsidy restructuring disclosures and enterprise mobility spend surveys across the analysis window. The analytical framework models form factor, display technology, end-user archetype, and distribution channel dimensions throughout the forecast period. CAGRs derive from hinge mechanism shipment trajectories and panel fab capacity expansion schedules. Forecast inputs include UTG adoption diffusion curves and PLI scheme incentive utilization rates.
Underlying assumptions cover sustained enterprise procurement momentum for DeX-compatible devices, with deviation risk concentrated in microLED transfer yield timelines and REACH substance waiver expiry dates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Green Technologies Market
Others
Aerospace Tester Market
Others
Palatants Market
Others
Nutricosmetics Market
Others
Digital Media Adaptor (DMA) Market
Others
China Smart Home Market
Others
Global Military Lighting Market
Others
South America Orange Market
Others
Wearable Translator Market
Others
Toy Packaging Market
Others
Reef Aquarium Market
Others
Smart Home As a Service Market
Others
Wearable AI Market
Others
Dry-Cleaning and Laundry Services Market
Others
Brazil Passenger Vehicles Lubricants Market
Others
Industrial PC Market