
 Europe Street Lighting Market | 2026-2036
Europe Street Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Street Lighting Market Foresight
Municipal procurement is bifurcating between legacy replacement cycles and connected infrastructure programs. Signify N.V. dominates European smart lighting deployments through its Interact platform. Eaton Corporation plc leverages its electrical distribution heritage to anchor retrofit projects across Nordic utility networks. Schreder SA competes on luminaire durability and dark-sky compliance for sensitive environmental zones.
Europe street lighting encompasses roadway, pathway, and public space illumination systems engineered to deliver specific luminous efficacy thresholds, color temperature consistency, and optical control for safety and energy optimization. LED modules now achieve system efficacies exceeding 150 lumens per watt while integrating thermal management for extended operating life in continental climates. Smart Lighting installations command premium positioning as cities deploy sensor-integrated poles for traffic monitoring and environmental sensing. Retrofit installations sustain the largest volume base as cash-constrained municipalities phase out mercury vapor and sodium vapor assets under Ecodesign mandates. Solar product types represent the fastest-growing niche in Southern European peripheries where grid extension costs exceed autonomous system economics.
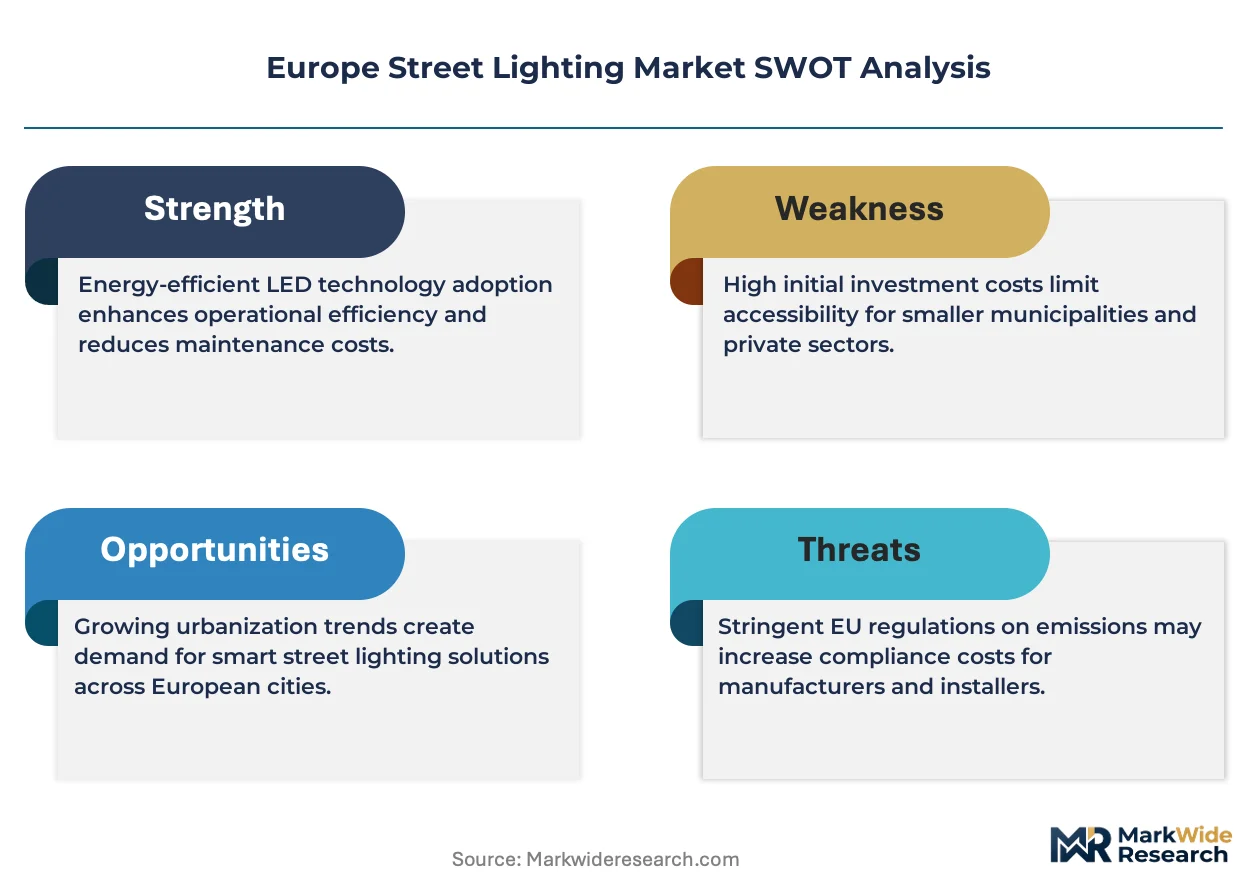
The EU Green Deal and Ecodesign Directive shape product eligibility by mandating minimum efficiency thresholds and mercury-free construction, while CE marking governs electromagnetic compatibility and safety access for intra-European trade. REACH compliance constrains substrate and coating chemistries, pushing manufacturers toward halogen-free driver electronics and recyclable aluminum housings. Stakeholders must monitor the F-Gas Regulation's indirect pressure on cooling-dependent legacy systems and position procurement frameworks around total cost of ownership rather than capital expenditure alone.
Market Dynamics
Municipal procurement across Western Europe is bifurcating between legacy replacement cycles and connected infrastructure programs, driven by Ecodesign mandates phasing out mercury-containing luminaires and tightening efficiency thresholds under the EU Green Deal.
Growth Catalysts
- Ecodesign Directive:Mandatory mercury-free construction and minimum efficacy thresholds force sodium vapor and mercury vapor replacements, accelerating LED retrofit volumes across French and German municipal networks.
- Smart pole convergence:Sensor-integrated lighting infrastructure enables traffic monitoring and environmental sensing, creating bundled procurement opportunities for urban digitalization budgets in Dutch and Belgian cities.
- Southern European solar autonomy:Grid extension costs exceeding autonomous system economics in Spanish and Italian peripheries drive fastest-growing niche demand for solar-powered street lighting.
Market Restraints
- Aluminum and driver electronics cost volatility:REACH compliance constraints on substrate chemistries push manufacturers toward halogen-free components, compressing margins on standardized luminaire portfolios.
- Smart lighting vendor concentration:Platform dependency on proprietary interoperability standards locks smaller municipalities into single-source ecosystems, limiting competitive pressure on pricing.
- Legacy asset stranded value:Functional high-pressure sodium installations with remaining operational life create political resistance to accelerated replacement timelines despite efficiency gaps.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian municipal budgets lag Western retrofit cycles, creating volume expansion potential as EU cohesion funds channel infrastructure investment eastward.
- Circular economy mandates:Ecodesign repairability requirements and recyclable aluminum housing specifications favor manufacturers with established take-back programs and modular luminaire architectures.
- Dark-sky compliance specialization:Optical control expertise for sensitive environmental zones in Alpine and Nordic regions commands premium positioning outside commodity LED competition.
Industry Challenges
- Electrical engineering skill scarcity:Smart lighting deployment requires power electronics and IoT integration capabilities that outpace vocational training pipeline output in aging municipal workforces.
- CE marking timeline compression:Electromagnetic compatibility and safety access testing for intra-European trade creates certification bottlenecks for product refresh cycles under tightening Ecodesign deadlines.
- Legacy control system integration:DALI and proprietary dimming protocols from 1990s installations conflict with wireless mesh architectures, forcing costly gateway infrastructure or full control replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Street Lighting Market |
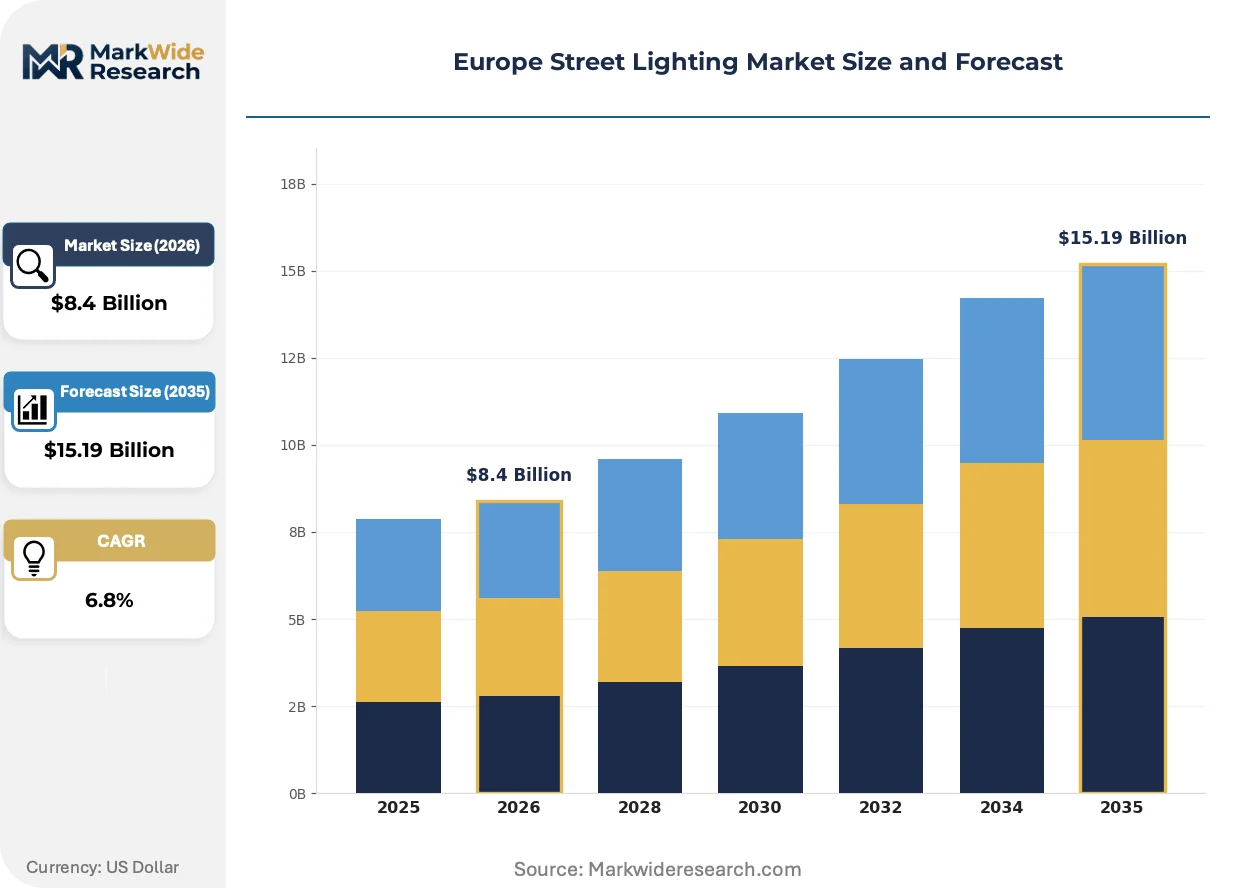
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
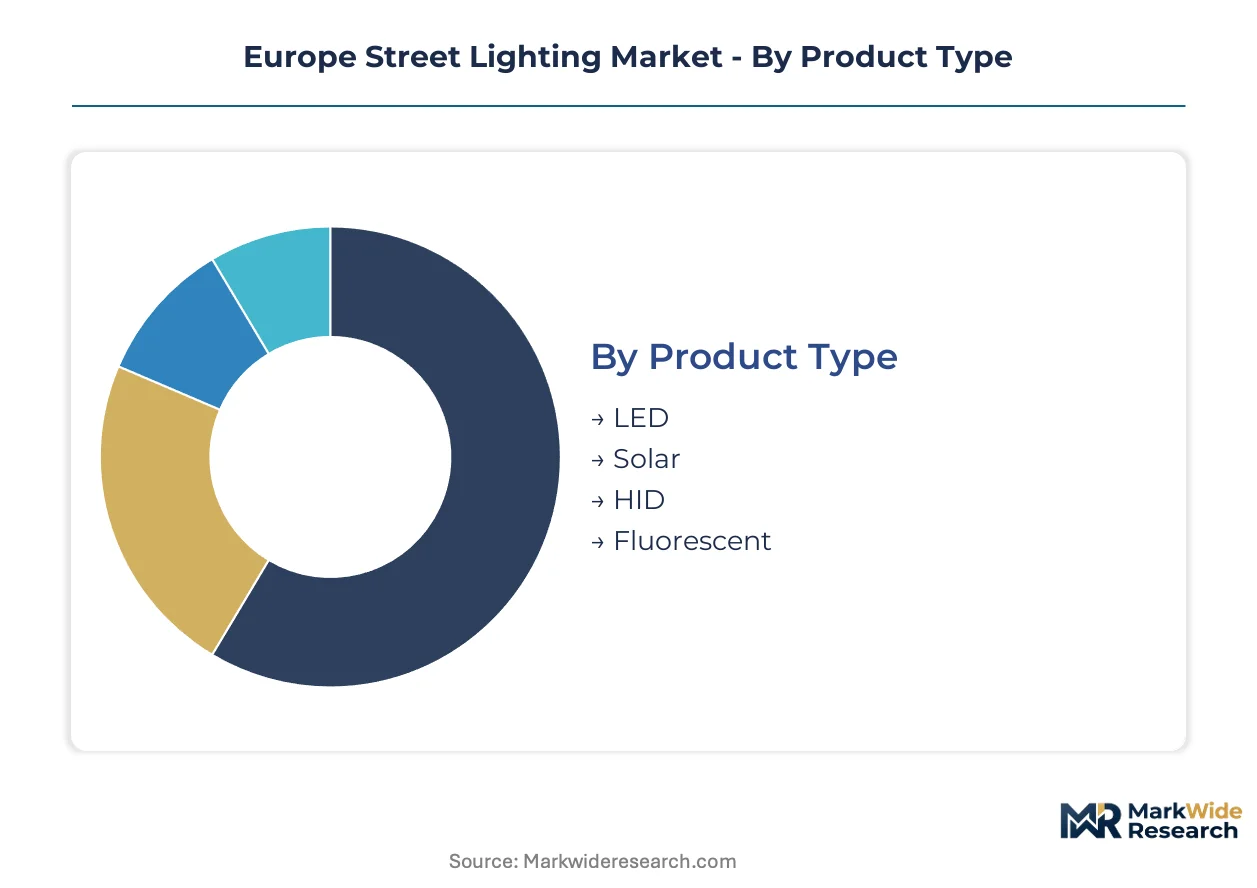
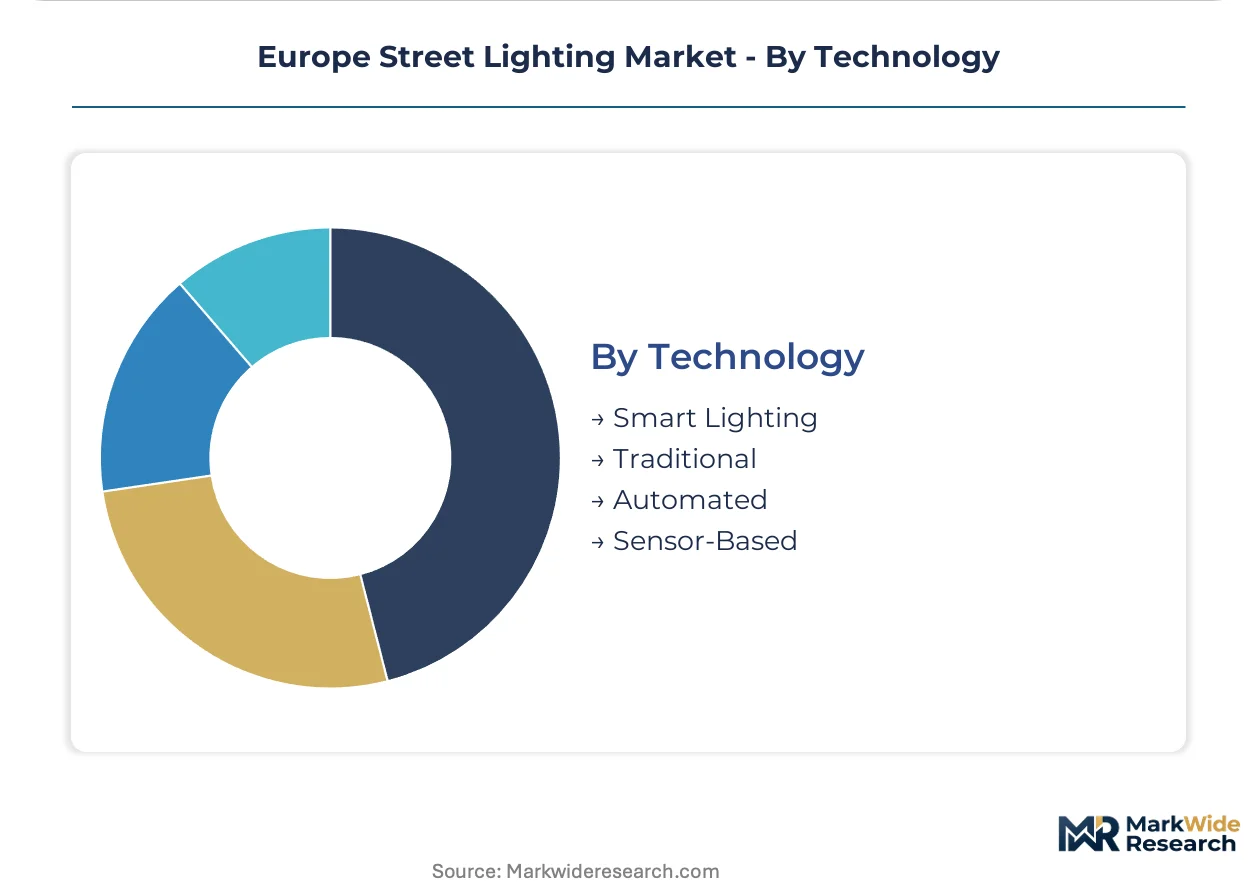
| Segmentation | Product Type: LED, Solar, HID, Fluorescent Installation Type: New, Retrofit, Replacement, Smart End User: Municipalities, Commercial, Residential, Industrial Technology: Smart Lighting, Traditional, Automated, Sensor-Based |
| Companies Covered | Eaton Corporation plc, Acuity Brands Inc., Signify N.V., Itron Inc., Cree Lighting, Zumtobel Group AG, OSRAM GmbH, Telensa Ltd., Schreder SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Street Lighting Market Shifts & Advancements
Connected infrastructure architectures are redefining competitive positioning in European street lighting, as luminaires evolve from passive illumination assets into sensor-hosting platforms for urban data networks.
Li-Fi optical wireless communication modules embedded in LED drivers are supplanting standalone fiber and 5G small-cell backhaul in dense urban corridors. Copenhagen and Barcelona pilot programs demonstrate gigabit-capable street-level connectivity without additional pole-mounted hardware. This convergence is compressing telecom infrastructure timelines and blurring procurement boundaries between lighting and communications departments.
The EU F-Gas Regulation indirectly pressures cooling-dependent legacy systems by accelerating phase-out of high-global-warming-potential refrigerants in associated power infrastructure. Municipal tenders increasingly specify passive thermal management for driver electronics to eliminate maintenance-intensive active cooling. Nordic utility networks lead specification shifts, with Stockholm and Oslo mandating fan-free luminaire designs for coastal climate exposure.
Total cost of ownership frameworks displace capital expenditure evaluation in French and German municipal procurement. Lifecycle contracting bundles luminaire supply, installation, energy management, and end-of-life recovery into single-source agreements spanning 15-20 year horizons. This restructuring concentrates vendor relationships around platform-integrated suppliers capable of underwriting performance guarantees across extended service windows.
Europe Street Lighting Market Segmentation
Street lighting procurement channels diverge sharply across segment boundaries. Municipal tendering favors established electrical distributors for bulk luminaire contracts, while smart infrastructure projects route through systems integrators bundling hardware with data platform subscriptions.
Product Type:
Channel mix splits between electrical wholesalers serving retrofit volumes and direct manufacturer relationships for smart pole deployments. LED and solar products increasingly bypass traditional distribution through energy service company financing arrangements.
- LED:System efficacies exceed 150 lumens per watt with passive thermal management for continental climate durability. French and German municipal networks concentrate demand as Ecodesign mandates force mercury-free replacements under EU Green Deal timelines.
- Solar:Autonomous photovoltaic-battery systems eliminate grid extension costs in Spanish and Italian peripheries where remote infrastructure economics favor off-grid deployment. Southern European regional governments channel cohesion funds toward solar street lighting fastest.
- HID:High-pressure sodium and metal halide installations persist in Eastern European municipalities with functional assets and constrained replacement budgets.
- Fluorescent:Linear tube luminaires remain in pathway and under-canopy applications where diffuse illumination requirements resist point-source LED retrofit.
By volume, LED leads. By growth pace, solar is climbing the fastest.
Installation Type:
Cost tier stratification separates capital-intensive smart infrastructure from maintenance-driven replacement cycles. Premium positioning attaches to integrated sensor platforms, while economy tiers cover standalone luminaire swaps.
- New:Greenfield urban expansion in Polish and Romanian growth corridors generates project-scale demand for complete lighting infrastructure bundled with civil works contracts.
- Retrofit:LED module insertion into existing pole infrastructure preserves civil asset value while achieving Ecodesign compliance. Nordic utility networks specify fan-free driver designs for coastal exposure under REACH-constrained material specifications.
- Replacement:Full luminaire swap programs dominate French departmental procurement through lifecycle contracting spanning 15-20 year service windows.
- Smart:Sensor-integrated pole deployments in Dutch and Belgian cities bundle traffic monitoring and environmental sensing capabilities into urban digitalization budgets.
By volume, retrofit leads. By margin capture, smart is expanding most quickly.
End User:
Customer type determines specification authority and financing mechanism. Municipal procurement drives standardization, while commercial end-users exercise flexibility on aesthetic and performance tiers.
- Municipalities:Public roadway and pathway illumination governed by EU Green Deal efficiency mandates and Ecodesign Directive mercury prohibitions. Total cost of ownership frameworks displace capital expenditure evaluation in German and French tendering.
- Commercial:Retail park and logistics facility lighting operates outside mandatory retrofit timelines, enabling phased LED conversion driven by energy cost reduction.
- Residential:Private estate and gated community installations concentrate in Southern European markets with homeowner association governance structures.
- Industrial:Heavy manufacturing and port facility lighting demands explosion-proof and vibration-resistant specifications outside standard municipal product ranges.
By volume, municipalities lead. By specification flexibility, commercial is gaining share fastest.
Technology:
Maturity gradient separates established illumination from emerging platform architectures. Traditional systems command immediate replacement volumes, while smart and automated segments capture forward-looking infrastructure investment.
- Smart Lighting:Wireless mesh-connected luminaires with centralized dimming control and asset monitoring. Copenhagen and Barcelona pilot Li-Fi optical wireless communication modules embedded in LED drivers for street-level gigabit connectivity.
- Traditional:Electromechanical control systems with fixed output levels and scheduled switching. Legacy DALI and proprietary dimming protocols from 1990s installations conflict with wireless mesh architectures, forcing gateway infrastructure or full control replacement.
- Automated:Daylight harvesting and motion-responsive output adjustment without network connectivity. Alpine municipalities specify automated systems for dark-sky compliance in sensitive environmental zones.
- Sensor-Based:Traffic flow and air quality monitoring hardware integrated into luminaire housings. Stockholm and Oslo mandate sensor-hosting platforms for urban data network convergence.
By volume, traditional leads. By infrastructure commitment, smart lighting is on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Western European manufacturing corridors where established electrical equipment producers anchor luminaire fabrication. German and Dutch industrial clusters dominate component sourcing for LED modules and driver electronics.
Germany
Municipal retrofit programs in North Rhine-Westphalia and Bavaria drive LED replacement volumes under Ecodesign Directive timelines. The Federal Environment Agency enforces mercury-free construction standards for public procurement. Berlin and Hamburg municipalities bundle smart pole deployments with urban data platform tenders.
France
Departmental lighting authorities in Île-de-France and Auvergne-Rhône-Alpes execute lifecycle contracting spanning 15-20 year service windows. ANSM oversees REACH compliance for substrate chemistries in luminaire housings. Lyon and Marseille pilot Li-Fi optical wireless modules embedded in LED drivers for street-level connectivity.
Netherlands
Smart infrastructure convergence concentrates in Randstad urban corridors where sensor-integrated poles serve traffic monitoring and environmental sensing. The Human Environment and Transport Inspectorate enforces CE marking for electromagnetic compatibility. Amsterdam and Rotterdam bundle lighting procurement with telecom infrastructure budgets.
Spain
Autonomous photovoltaic-battery systems eliminate grid extension costs in Andalusian and Valencian peripheries where remote infrastructure economics favor off-grid deployment. The Ministry for Ecological Transition channels EU cohesion funds toward solar street lighting. Barcelona pilots gigabit-capable Li-Fi connectivity without additional pole-mounted hardware.
Poland
Municipal budgets in Warsaw and Kraków lag Western retrofit cycles, creating volume expansion potential as EU cohesion funds channel infrastructure investment eastward. The Polish Committee for Standardization implements Ecodesign requirements through national technical regulations. Silesian industrial zones concentrate luminaire assembly operations for Eastern European distribution.
Europe Street Lighting Market Competitive Landscape
Concentration sits with diversified electrical equipment conglomerates and specialized lighting technology firms. Market structure tiers across platform-integrated suppliers capable of lifecycle contracting and component-focused manufacturers serving retrofit volumes. Strategic archetypes include smart infrastructure platform providers, luminaire durability specialists, and solar autonomy system integrators. Dominant competitive moves encompass vertical integration into driver electronics manufacturing and strategic partnerships with municipal energy service companies.
Among Netherlands-based platform providers, Signify N.V. exemplifies the connected infrastructure archetype through its Interact smart lighting deployments. Schreder SA, a Belgian specialist, occupies a position in optical control expertise for dark-sky compliance applications. Eaton Corporation plc, an Irish-American electrical equipment conglomerate, anchors retrofit project relationships across Nordic utility networks through its distribution heritage.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Acuity Brands Inc. |
| Signify N.V. |
| Itron Inc. |
| Cree Lighting |
| Zumtobel Group AG |
| OSRAM GmbH |
| Telensa Ltd. |
| Schreder SA |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for LED driver electronics concentrate pricing power among German and Dutch component suppliers, compressing margins for luminaire assemblers while REACH compliance costs elevate entry thresholds. Municipal buyers exploit this concentration through consolidated tendering, extracting volume discounts that offset supplier pricing leverage.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure across European street lighting procurement, separating premium smart pole platforms from standard LED retrofits and economy HID replacements. Certification grade and after-sales service bundling differentiate price levels, with CE-marked smart infrastructure commanding substantial premiums over commodity luminaires. Pricing pressure stems from aluminum and halogen-free driver cost volatility under REACH constraints, squeezing standardized product margins. Municipal procurement departments exhibit highest price sensitivity, while commercial end-users accept premium tiers for specification flexibility.
Supply Chain Analysis
Just-in-time inventory strategies dominate LED module procurement, though strategic stockpiling of aluminum substrates and driver electronics buffers against REACH-regulated material disruptions. Manufacturing concentrates in Germany, the Netherlands, and Belgium, drawing from Taiwanese semiconductor foundries and Chinese rare-earth phosphor suppliers. Single-source vulnerability in advanced driver ICs creates supply chain risk, as few European fabricators maintain captive production. Distribution runs through electrical wholesalers for retrofit volumes, while direct manufacturer relationships service smart infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European street lighting operates as a substitution defense market where solar-autonomous systems threaten incumbent grid-connected LED portfolios. Municipal procurement bifurcation between legacy replacement and connected infrastructure demands dual-track positioning.
For Market Incumbents: Secure lifecycle contracting relationships with French departmental authorities and German municipal utilities to lock out competitor platform integration. Deepen upstream control over driver electronics manufacturing to offset REACH-constrained material cost volatility. Counter solar-autonomous substitutes by bundling grid-connected smart poles with urban data platform subscriptions that off-grid systems cannot replicate.
For New Entrants and Emerging Players: Differentiate on dark-sky compliance specialization for Alpine and Nordic environmental zones where optical control expertise commands premium positioning outside commodity competition. Target Polish and Romanian municipal networks lagging Western retrofit cycles, leveraging EU cohesion fund accessibility as go-to-market entry point. Pursue energy service company financing partnerships to bypass established electrical distribution channels.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because lifecycle contracting concentration favors platform-integrated suppliers capable of underwriting performance guarantees across extended service windows. Acquisition targets include modular luminaire architects with established take-back programs and Li-Fi communication module developers. Watch for inflection when Ecodesign Directive enforcement timelines accelerate mercury-vapor phase-out beyond current municipal replacement pacing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Captive supply of REACH-compliant components insulates margin compression from substrate chemistry constraints. |
| Smart Pole Platform Integration | Sensor-hosting infrastructure bundles lighting with urban data budgets in Dutch and Belgian municipal tenders. |
| Lifecycle Contracting Expansion | Fifteen-to-twenty-year service agreements concentrate vendor relationships around performance-guarantee capabilities. |
| Solar-Autonomous System Development | Off-grid deployment addresses Spanish and Italian peripheries where grid extension economics favor photovoltaic-battery autonomy. |
| Circular Economy Certification | Ecodesign repairability requirements and aluminum take-back programs differentiate modular luminaire architectures. |
Research Methodology
Desk research of EU regulatory filings, municipal tender databases, and electrical equipment trade data preceded structured interviews with municipal procurement officers, smart lighting platform engineers, and energy service company financing directors. Secondary validation drew from Ecodesign Directive implementation reports, REACH compliance documentation, and national standardization committee technical regulations. Bottom-up luminaire shipment analysis triangulated against top-down municipal infrastructure spending estimates across the projection horizon.
Variance decomposition across product type, installation category, end-user segment, and technology maturity anchored the analytical framework. Modeled dimensions encompassed LED, solar, HID, and fluorescent product classifications intersecting with retrofit, replacement, new installation, and smart infrastructure deployment types. CAGRs derived from segment-level volume trajectories weighted by Ecodesign mandate acceleration curves and EU cohesion fund disbursement patterns. Driver electronics cost indices and aluminum price volatility surfaces informed margin sensitivity modeling throughout the forecast period.
Forecasts assume regulatory continuity in EU Ecodesign and REACH regimes; material policy shifts would require re-modeling. Specific risk factors include F-Gas Regulation expansion into cooling-dependent legacy systems and electromagnetic compatibility testing timeline compression under CE marking acceleration. Revision becomes warranted when smart lighting vendor concentration crosses monopoly thresholds or when solar-autonomous system cost parity accelerates beyond modeled adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Android STB and TV Market
Others
Binoculars and Mounting Solutions Market
Others
Industrial Gauges Market
Others
India Battery E-Commerce Market
Others
Africa Lime Market
Others
Digital Tattoos Market
Others
Global Hardware As a Service (Haas) Market
Others
North America Halal Food and Beverage Market
Others
Asia-Pacific Camping and Caravanning Market
Others
Global Mobile Video Optimization Market
Others
8K Technology Market
Others
Wearable Translator Market
Others
Post Consumer Recycled Bottles Market
Others
Bimodal Identity Management Solutions Market
Others
North America Thermoformed Plastics Market
Others
Edible Insects for Animal Feed Market