
 Global Military Wearable Sensors Market | 2026-2036
Global Military Wearable Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Wearable Sensors Market Foresight
The EU Green Deal's sustainable electronics mandates is shifting procurement criteria for military wearable sensors across European defense ministries. Honeywell International Inc. leverages its vertical integration in MEMS fabrication to dominate environmental sensor supply for NATO programs. Safran Electronics & Defense anchors its position through specialized R&D in fiber optic strain sensing for pilot and soldier suits. NXP Semiconductors competes by extending its secure element portfolio into encrypted biometric wearables for allied defense agencies.
Military wearable sensors are compact transducer assemblies, typically integrating MEMS accelerometers, galvanic skin response electrodes, and infrared thermopiles within textile-embedded or body-worn housings, designed to capture kinematic, physiological, and ambient data streams for real-time battlefield decision support. Physiological sensors lead current procurement volumes because combatant monitoring programs require continuous heart rate, hydration, and stress-level telemetry for mission planning and medical triage. Wireless sensor networks represent the fastest-growing technology segment as mesh-radio protocols replace tethered connections in contested electromagnetic environments. Motion sensors occupy mature margin pools due to established supply chains for IMU components originally developed for consumer electronics.
The U.S. FDA regulates physiological monitoring claims for devices crossing into medical-adjacent deployments, while the EU AI Act imposes risk-classification requirements on automated threat-detection algorithms embedded in wearable sensor suites. NATO's Standardization Office shapes interoperability demand by mandating common data formats for soldier-system telemetry across allied forces. Stakeholders must monitor how export control expansions under the U.S. Department of Commerce affect component sourcing for biometric sensor modules.
Market Dynamics
Defense procurement officers across NATO member states are consolidating vendor lists for soldier-system telemetry, compressing supplier margins while elevating technical qualification barriers for physiological monitoring hardware.
Growth Catalysts
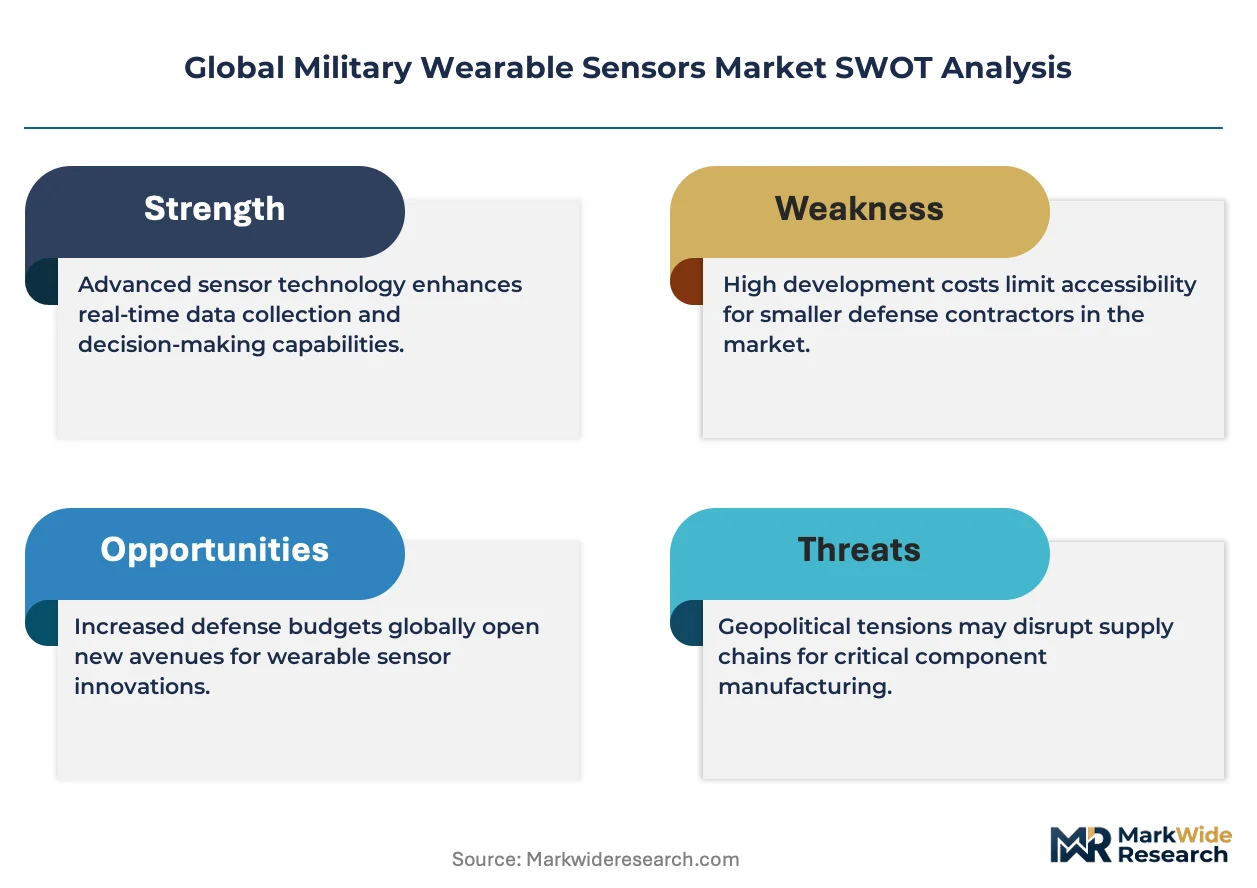
- EU AI Act risk-classification mandates:Automated threat-detection algorithms embedded in wearable sensor suites now face standardized compliance pathways, accelerating cleared product deployment across allied defense agencies.
- Mesh-radio protocol maturation:Wireless sensor networks replace tethered connections in contested electromagnetic environments, enabling real-time kinematic data streaming without vulnerable cable infrastructure.
- Army Futures Command modernization priorities:United States defense investment concentrates on biometric wearables for dismounted soldier programs, pulling component demand through secure supply chains.
Market Restraints
- Lead-free solder transition costs:EU Green Deal sustainable electronics mandates force retooling of MEMS fabrication lines, elevating unit economics for environmental sensor modules.
- Indium tin oxide supply concentration:Transparent conductive electrode materials for galvanic skin response sensors concentrate in East Asian refining capacity, exposing NATO manufacturers to export control volatility.
- FDA physiological monitoring claims:Devices crossing into medical-adjacent deployments face dual-use regulatory friction, extending certification timelines for combatant health telemetry systems.
Strategic Opportunities
- India defense indigenization:PLI scheme incentives for electronics manufacturing attract sensor module assembly investment, creating captive supply capacity for regional military procurement.
- Fiber optic strain sensing convergence:Integration of optical interferometry with textile-embedded housings enables electromagnetic-interference-immune pilot and soldier suit monitoring in high-RF environments.
- Secure element encryption tailwinds:NXP Semiconductors' extension of hardware security modules into biometric wearables opens encrypted data architecture standards for allied interoperability.
Industry Challenges
- ISO/IEC 27001 certification timelines:Information security management system audits for defense contractor status delay market entry for MEMS startups lacking established compliance infrastructure.
- Legacy system integration complexity:Proprietary data formats from existing soldier-system telemetry create friction for NATO Standardization Office common format adoption, fragmenting procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Wearable Sensors Market |
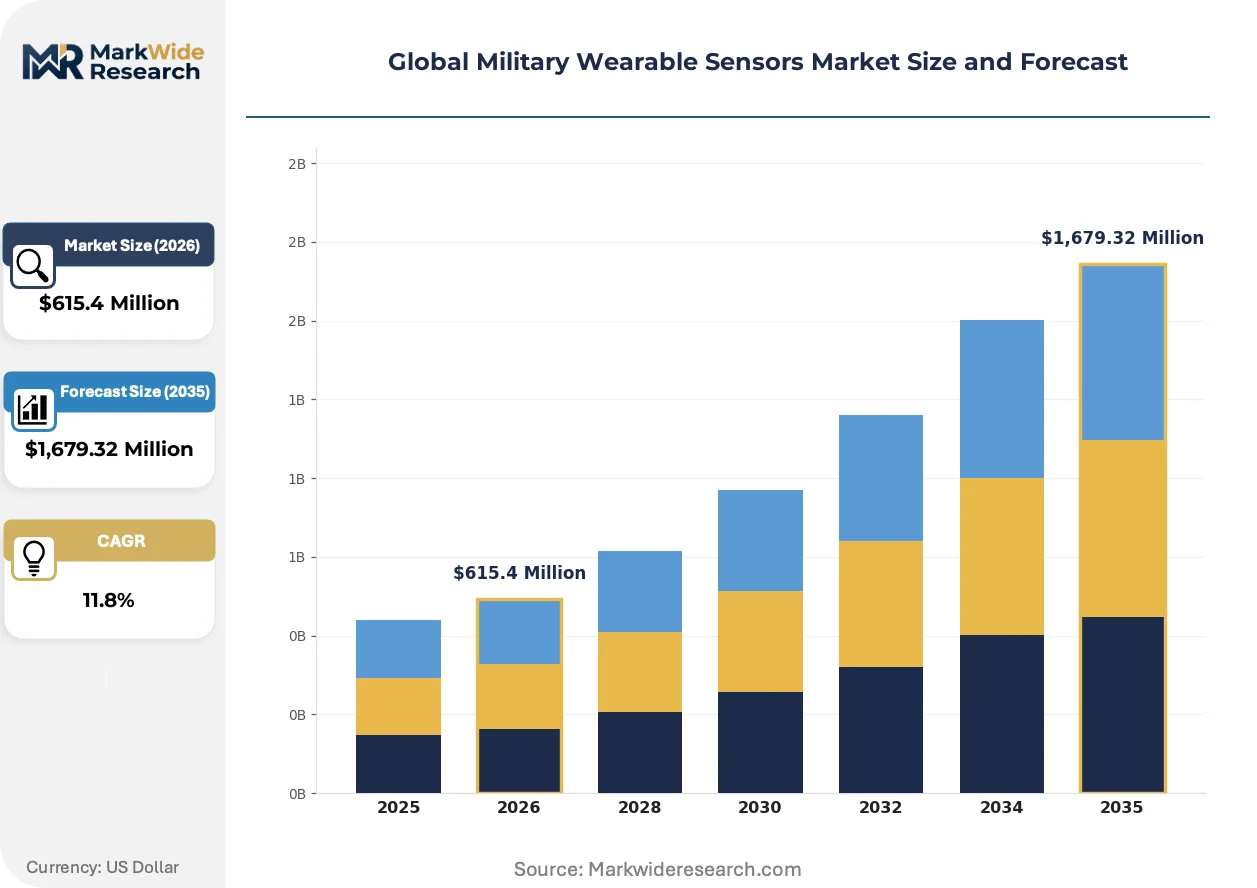
| Market Size in 2026 | $615.4 Million |
| Market Size in 2035 | $1,679.32 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motion Sensors, Environmental Sensors, Physiological Sensors, Location Sensors, Communication Sensors Technology: Wireless Sensor Networks, Biometric Sensors, RFID, GPS, Fiber Optic Sensors Application: Soldier Performance Monitoring, Situational Awareness, Equipment Tracking, Command & Control, Threat Detection End User: Defense Forces, Intelligence Agencies, Security Contractors, Peacekeeping Organizations |
| Companies Covered | Honeywell International Inc., Safran Electronics & Defense, BeBop Sensors, DuPont, Panasonic Corporation, NXP Semiconductors, Leidos, TT Electronics, Xsens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Wearable Sensors Market Shifts & Advancements
Battlefield electromagnetic contestedness is forcing hardware architects toward passive and fiber-optic sensing modalities, reducing active electronic signatures while maintaining physiological coverage.
Photonic strain sensing is absorbing the electromagnetic-vulnerability problem set for high-mobility warfighter monitoring. Special Operations Command units in the United States are field-testing interferometric fiber arrays woven into load-bearing equipment at squad-level scale. This modality is absorbing market share from conventional MEMS accelerometers in RF-denied operational envelopes where electronic emissions compromise mission security.
REACH substance restriction expansions are forcing reformulation of substrate adhesives and encapsulant chemistries for body-worn sensor housings. European defense ministries now require full material disclosure for soldier-system components, elevating compliant suppliers in competitive evaluations. Environmental sensor modules for NATO programs face the steepest compliance burden due to skin-contact proximity and extended wear durations.
Buyer consolidation around prime systems integrators is compressing component vendor access to end-user requirements. Dismounted soldier program offices in the United States and Germany now route wearable sensor specifications through Lockheed Martin and Rheinmetall platforms, marginalizing direct sales relationships. France maintains partial exception through Safran Electronics & Defense's embedded development contracts, preserving vertical channel access for specialized fiber optic sensing suppliers.
Global Military Wearable Sensors Market Segmentation
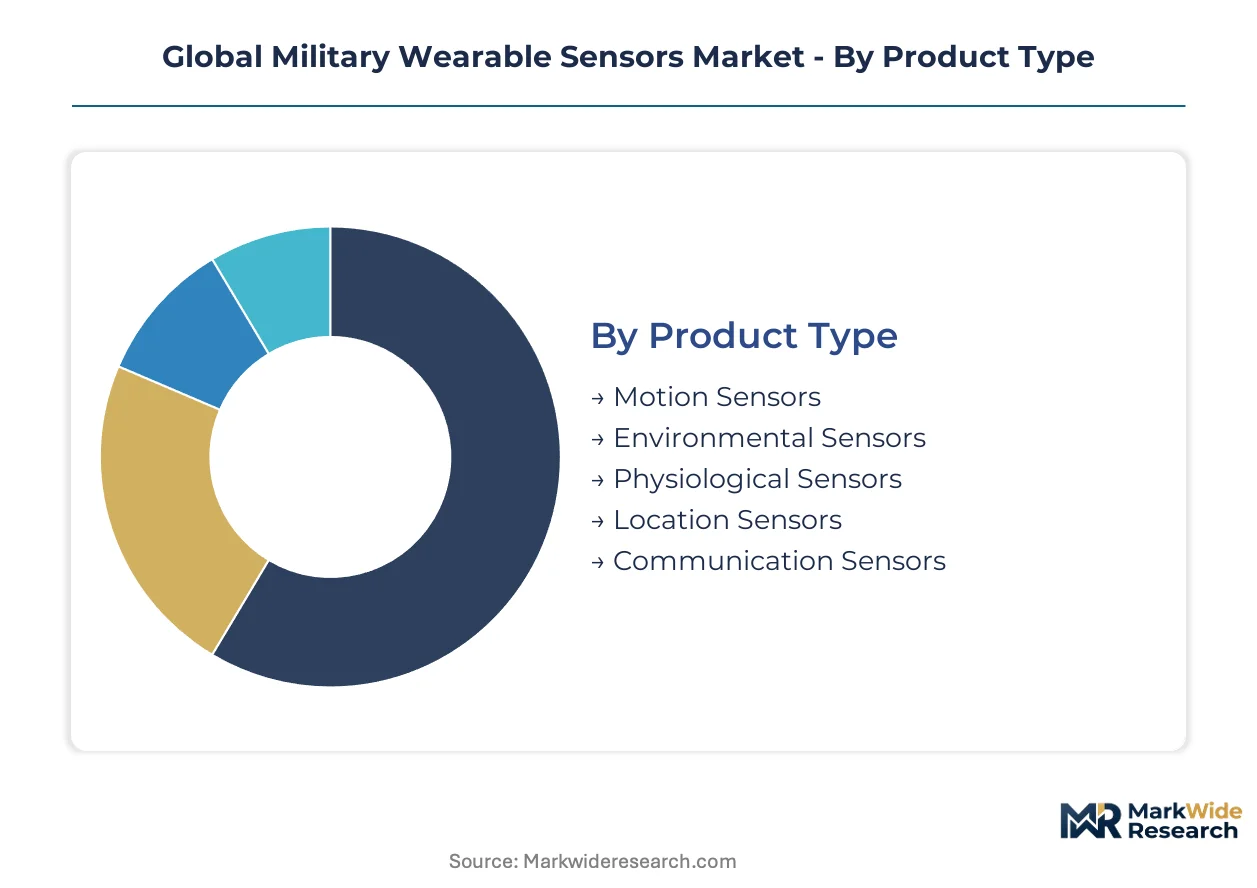
Military wearable sensors fragment across four structural dimensions that determine procurement pathways, integration complexity, and margin capture. Product type governs hardware specifications and textile-embedding requirements. Technology choice shapes electromagnetic signature and power budget. Application focus drives data architecture and interoperability mandates. End user classification determines security clearance levels and export control exposure.
Product Type:
Defense procurement officers distinguish sensor categories by data stream criticality and wear-location constraints.
- Physiological Sensors:Galvanic skin response electrodes, infrared thermopiles, and photoplethysmography modules capture heart rate, hydration status, and stress biomarkers. Combatant monitoring programs across NATO member states mandate continuous biometric telemetry for medical triage and mission planning, concentrating demand in dismounted soldier modernization budgets.
- Environmental Sensors:MEMS-based temperature, humidity, and chemical detection transducers monitor ambient conditions affecting operator performance. EU Green Deal sustainable electronics mandates are forcing lead-free solder transitions and recyclable substrate adoption, elevating unit economics for European defense ministry contracts.
- Motion Sensors:Inertial measurement units combining accelerometers and gyroscopes track kinematic data for load-bearing equipment analysis.
- Location Sensors:Dead-reckoning modules and magnetic compasses supplement GPS-denied positioning for dismounted operations.
- Communication Sensors:Mesh-radio transceivers and antenna-integrated housings enable squad-level data networking without vulnerable cable infrastructure.
Physiological sensors lead volumes today; environmental sensors are gaining share fastest.
Technology:
Platform architects select modalities based on contested electromagnetic environment exposure and signature management priorities.
- Wireless Sensor Networks:Mesh-radio protocols replace tethered connections in RF-contested theaters, enabling real-time kinematic streaming without cable vulnerability. Army Futures Command modernization priorities are pulling demand through secure supply chains for dismounted soldier programs.
- Fiber Optic Sensors:Interferometric strain arrays woven into textile-embedded housings eliminate electronic emissions entirely. Special Operations Command investment in electromagnetic-interference-immune pilot and soldier suit monitoring is accelerating field-testing at squad-level scale.
- Biometric Sensors:Fingerprint, iris, and gait recognition modules authenticate operator identity for command system access.
- RFID:Passive and active radio-frequency identification tags track equipment and ammunition inventory in logistics chains.
- GPS:Satellite navigation receivers with anti-jam processing provide position-fixing in contested signal environments.
Wireless sensor networks dominate current procurement volumes; fiber optic sensors are climbing the fastest.
Application:
Mission profile determines data fusion requirements and downstream system integration complexity.
- Soldier Performance Monitoring:Integrated physiological and kinematic telemetry supports fatigue management and medical evacuation triage. NATO Standardization Office common data format mandates are compressing vendor lists for soldier-system telemetry across allied forces.
- Situational Awareness:Multi-sensor fusion feeds command displays with real-time squad disposition and environmental status.
- Equipment Tracking:Asset location and condition monitoring reduces loss rates and maintenance backlogs in forward deployment.
- Command & Control:Biometric authentication and secure voice/data links enable distributed decision-making without fixed infrastructure.
- Threat Detection:Automated algorithmic processing of sensor streams for anomaly identification faces EU AI Act risk-classification compliance pathways.
Soldier performance monitoring anchors current demand; situational awareness applications are expanding most quickly.
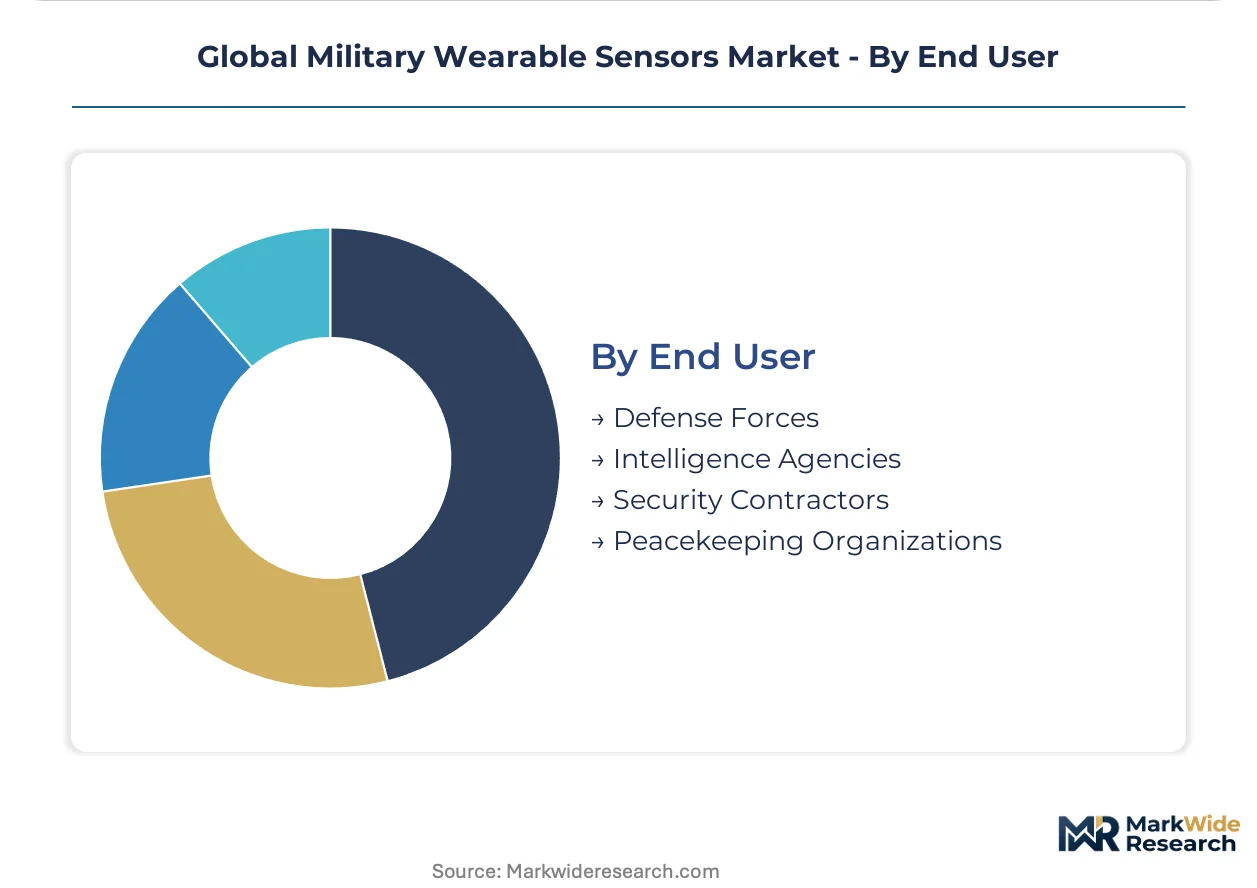
End User:
Security classification and operational authority segment buyers by contract vehicle access and technical qualification barriers.
- Defense Forces:National military services with formal soldier-system modernization programs and NATO interoperability requirements. Consolidation around Lockheed Martin and Rheinmetall platform specifications is marginalizing direct component vendor access in the United States and Germany.
- Intelligence Agencies:Clandestine service units with specialized electromagnetic-signature constraints and covert wearability demands.
- Security Contractors:Private military companies operating under government contract with limited system integration support.
- Peacekeeping Organizations:Multilateral forces with standardized equipment mandates and restricted national technology sourcing.
Defense forces command the largest procurement volumes; intelligence agencies are driving the steepest expansion trajectory for low-signature modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Military wearable sensor technology originated in United States defense research programs during the early 2000s, with subsequent scaling through NATO standardization initiatives that established common telemetry formats across allied forces.
United States
Army Futures Command modernization priorities and Special Operations Command biometric investment drive procurement volumes. FDA regulates physiological monitoring claims for medical-adjacent deployments, creating dual-use certification friction. Boston and Austin clusters host MEMS design firms supplying secure supply chains for dismounted soldier programs.
Germany
Rheinmetall platform specifications consolidate vendor access for soldier-system telemetry components. EU Green Deal sustainable electronics mandates force lead-free solder transitions in environmental sensor modules. Bavaria's precision manufacturing corridor hosts fabrication facilities serving NATO standardization requirements.
France
Safran Electronics & Defense embedded development contracts preserve vertical channel access for fiber optic sensing suppliers. REACH substance restriction expansions reformulate substrate adhesives for body-worn sensor housings. Paris-Saclay research cluster advances interferometric strain sensing for electromagnetic-interference-immune pilot suits.
United Kingdom
Defence Science and Technology Laboratory coordinates physiological monitoring trials for combatant health telemetry. NATO Standardization Office interoperability mandates shape common data format adoption across British Army modernization. South East England electronics corridor supplies secure element components for encrypted biometric architectures.
India
Defense indigenization under PLI scheme incentives attracts sensor module assembly investment for regional military procurement. BIS certification requirements elevate technical qualification barriers for foreign component vendors. Bengaluru and Hyderabad clusters develop captive supply capacity for soldier-system telemetry.
Global Military Wearable Sensors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the military wearable sensors landscape, with foundry-dependent MEMS fabricators facing margin pressure from vertically integrated defense primes. The vendor base concentrates around three strategic archetypes: aerospace conglomerates with captive sensor divisions, specialized MEMS foundries serving dual-use markets, and secure semiconductor suppliers extending hardware encryption portfolios. Dominant competitive moves include strategic partnerships with prime systems integrators and geographic expansion toward PLI scheme jurisdictions in South Asia.
Within the aerospace conglomerate tier, Honeywell International Inc. and Safran Electronics & Defense exemplify vertical integration strategies that capture environmental and fiber optic sensing contracts through platform-level relationships. NXP Semiconductors N.V. occupies a position bridging secure element expertise with biometric wearable applications. Among these, Honeywell International Inc. and Safran Electronics & Defense represent the capital-intensive archetype, while NXP Semiconductors N.V. anchors the semiconductor-specialist vector.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Safran Electronics & Defense |
| BeBop Sensors |
| DuPont |
| Panasonic Corporation |
| NXP Semiconductors |
| Leidos |
| TT Electronics |
| Xsens |
| Others |
Supply & Pricing Matrix
MEMS fabrication specialists concentrated in Bavaria's precision manufacturing corridor create labor-cost differentials that widen pricing-tier spreads between NATO-qualified environmental sensor modules and commercial-grade alternatives. EU Green Deal mandates for lead-free solder and recyclable substrates add compliance premiums that stack atop regional wage arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NATO-certified physiological monitoring systems from dual-use commercial variants and unqualified commodity sensors. Price differentiation hinges on ISO/IEC 27001 certification status and secure supply chain documentation. Pricing pressure stems from buyer consolidation around Lockheed Martin and Rheinmetall platform specifications, which compresses component vendor margins. Defense forces exhibit lowest price sensitivity due to mission-critical requirements, while security contractors face acute budget constraints.
Supply Chain Analysis
ITAR and NATO Standardization Office qualification gating restricts component sourcing to pre-approved fabrication facilities in the United States, Germany, and France. Raw material dependencies center on indium tin oxide for transparent conductive electrodes, gallium arsenide for RF transceivers, and specialized fiber optic filaments for interferometric arrays. Single-source vulnerability concentrates in East Asian indium refining capacity, exposing NATO manufacturers to export control volatility. Distribution runs through prime systems integrators rather than direct component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Military Wearable Sensors Market represents a late-cycle quality story as electromagnetic-contested battlefield requirements elevate premium specifications for passive and fiber-optic sensing modalities over conventional MEMS alternatives.
For Market Incumbents: Hedge against indium tin oxide supply concentration by securing alternative transparent conductor formulations or backward integration into gallium nitride electrode development. Accelerate ISO/IEC 27001 certification timelines to maintain prime integrator access as Rheinmetall and Lockheed Martin consolidate vendor lists. Fiber optic strain sensing R&D offers defensive moats against MEMS commoditization. For New Entrants and Emerging Players: EU AI Act risk-classification mandates in Europe open a window for algorithmic threat-detection specialists to enter cleared defense supply chains. Target intelligence agency procurement for low-signature biometric wearables, where electromagnetic-interference-immune modalities face less entrenched competition. Pursue embedded development contracts with Safran Electronics & Defense as a channel bypass around prime integrator gatekeeping. For Investors and Strategic Acquirers: Aerospace conglomerates with captive sensor divisions are the most active acquirer in this space, seeking MEMS design capabilities and secure element expertise. Five-to-ten-year viability favors asset-light designers with foundry partnerships over capital-heavy fabricators facing margin compression. Watch Special Operations Command field-testing outcomes for fiber optic strain arrays as an inflection indicator for modality substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Supply Chain Certification | ITAR and NATO Standardization Office compliance unlocks prime integrator procurement channels for component vendors. |
| Fiber Optic Sensing R&D Partnership | Interferometric strain array development captures electromagnetic-contested mission profiles from MEMS incumbents. |
| PLI Scheme Geographic Expansion | India defense indigenization incentives attract sensor module assembly investment for regional captive supply. |
| Hardware Security Module Integration | Encrypted biometric architectures align with Army Futures Command modernization priorities for dismounted soldier programs. |
| REACH-Compliant Material Reformulation | Substrate adhesive substitutions satisfy EU Green Deal mandates for European defense ministry contracts. |
Research Methodology
Multiple input streams — defense procurement officer interviews, prime systems integrator specification reviews, and regulatory filing analysis — were reconciled against customs data and NATO standardization documentation. Primary fieldwork captured perspectives from MEMS fabrication engineers, soldier-system program managers, biomedical telemetry specialists, and secure semiconductor procurement leads. Secondary validation drew from FDA 510(k) filings, EU AI Act implementation guidance, BIS export control updates, and Army Futures Command budget justifications. Bottom-up component demand modeling and top-down defense expenditure allocation were cross-referenced for triangulation.
Segment-level volume and value outputs across the projection horizon reflect reconciliation of product type, technology modality, application focus, and end-user security classification dimensions. CAGRs were derived from elasticity-adjusted procurement forecasts and platform-level content-per-soldier estimates. Industry-specific inputs included electromagnetic contestedness scenario planning and fiber optic sensor substitution curve modeling.
Revisions become necessary when NATO Standardization Office interoperability mandates shift, export control expansions alter component sourcing legality, or Special Operations Command field-testing outcomes accelerate modality transitions. A model refresh is warranted upon material change in Army Futures Command modernization budget allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bimodal Identity Management Solutions Market
Others
Agitator Bead Mill Market
Others
Vegetable Carbon Market
Others
North America Video Conferencing Hardware Market
Others
Cloud Digital Video Recorder Market
Others
Senior Cat Food Market
Others
Voice Controlled Devices Market
Others
Rugged Tablet Market
Others
Industrial Air Purifiers Market
Others
Cellular-Connected Laptops Market
Others
Global Molded Plastics Market
Others
Global Smart Devices Market
Others
Safety Instrumented System (SIS) Market
Others
Dry Washer Market
Others
Fluid Dispensing Systems Market
Others
Digital Mortgage Software Market