
 India Battery E-Commerce Market | 2026-2036
India Battery E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
India Battery E-Commerce Market Insights
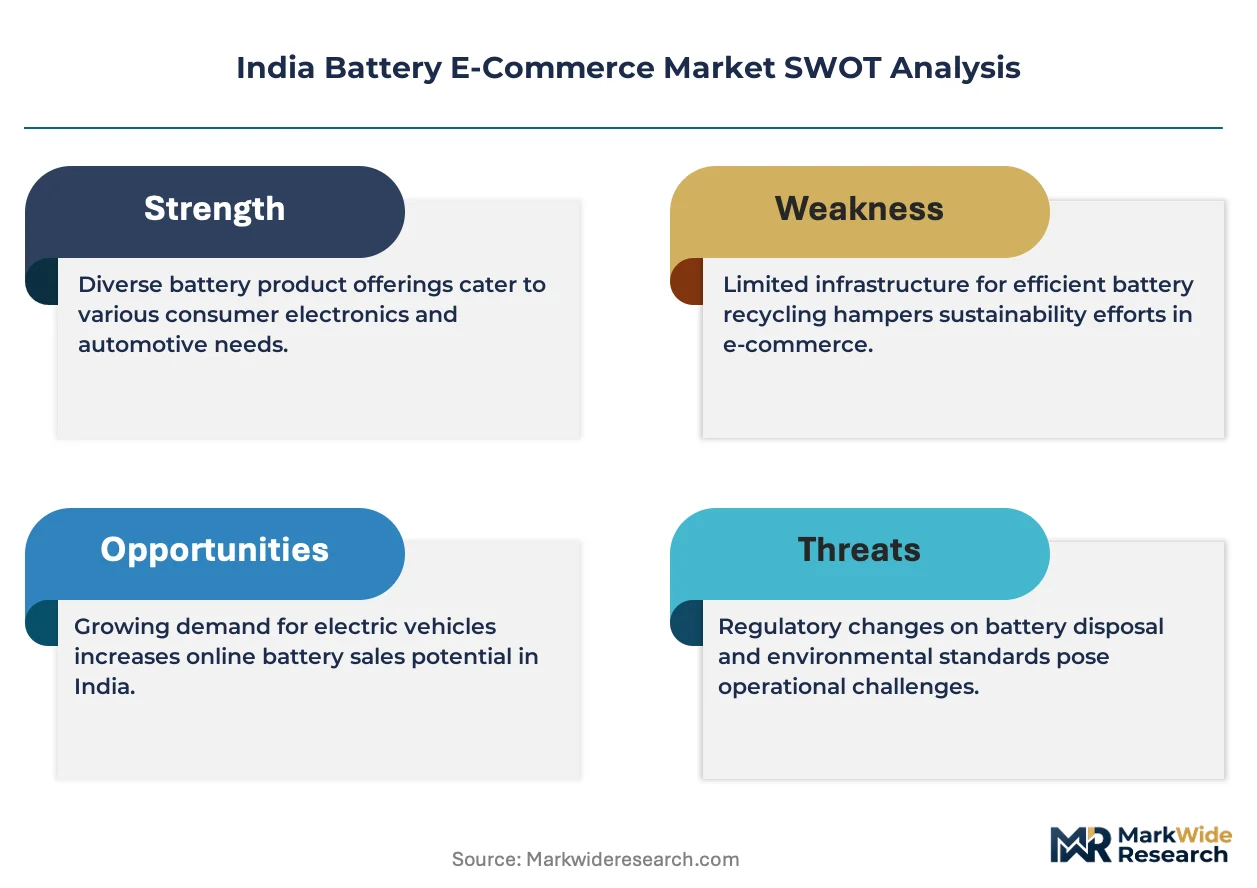
BIS certification for lithium-ion cells is collapsing the supplier base eligible for platform listing, forcing e-commerce aggregators to prune unqualified sellers. Exide Industries leverages its in-house testing infrastructure to maintain platform compliance without third-party delays. Luminous Power Technologies anchors its online presence through dedicated manufacturer-direct storefronts that bypass marketplace fees. Amazon India competes by controlling last-mile cold-chain logistics for temperature-sensitive battery chemistries.
India battery e-commerce denotes the digital sale and fulfillment of electrochemical energy storage devices, spanning lead-acid units with 12V nominal output and lithium-ion packs with 3.7V mean cell voltage, primarily serving mobility, backup, and portable power needs. The lithium-ion product type segment captures the fastest trajectory as EV penetration and inverter upgrades displace legacy lead-acid stock. Among end users, automotive applications dominate transaction value, while renewable energy buyers sustain higher per-order margins due to bulk storage configurations. Third-party sellers within distribution channels face margin compression as manufacturer websites capture direct relationships with institutional purchasers.
BIS mandates cell-level testing under IS 16046, while the CEA issues safety guidelines for grid-connected battery installations, and state EV policies in Maharashtra and Karnataka prescribe buyback and recycling obligations that reshape product lifecycle accountability. Compliance costs favor scaled players with captive certification labs, squeezing informal importers from platform algorithms. Stakeholders must monitor how DGFT import licensing for lithium cells intersects with platform listing requirements to determine viable sourcing models.
Market Dynamics
BIS certification mandates under IS 16046 are compressing the supplier base eligible for platform listing, forcing aggregators to prune unqualified sellers and redirect procurement toward scaled domestic manufacturers with captive testing infrastructure.
Growth Catalysts
- PLI scheme for advanced chemistry cells:The production-linked incentive framework redirects supplier investments toward lithium-ion chemistry, expanding domestic cell capacity and reducing import dependency for e-commerce fulfillment.
- Two-wheeler and three-wheeler fleet electrification:Commercial EV operators in Maharashtra, Karnataka, and Tamil Nadu are consolidating battery purchases through digital channels to secure volume pricing and streamlined logistics.
- State-level EV policies:Maharashtra and Karnataka prescribe buyback and recycling obligations that create lifecycle accountability, accelerating platform-based battery-as-a-service models.
Market Restraints
- Lithium cell import licensing:DGFT licensing requirements for lithium cells create sourcing friction that delays platform restocking cycles and inflates working capital needs.
- Temperature-sensitive logistics costs:Cold-chain fulfillment for advanced chemistries absorbs margin that third-party sellers cannot recover against manufacturer-direct pricing.
- Lead-acid displacement lag:Inverter and automotive replacement cycles in tier-2 and tier-3 cities sustain legacy chemistry demand that dilutes platform SKU rationalization efforts.
Strategic Opportunities
- Renewable energy storage bulk orders:Solar installers in Gujarat and Rajasthan are sourcing lithium battery banks through e-commerce to bypass distributor markups on containerized shipments.
- Manufacturer-direct storefronts:Bypassing marketplace fee structures allows domestic cell producers to capture institutional relationships and subscription-based replacement contracts.
- Metro logistics density expansion:Last-mile cold-chain networks in Bengaluru, Mumbai, and Chennai enable same-day delivery guarantees that differentiate platform value propositions.
Industry Challenges
- Cell-level testing capacity scarcity:BIS laboratory bottlenecks delay certification timelines for new suppliers, constraining platform assortment expansion and competitive pricing.
- Reverse logistics infrastructure gaps:State-mandated buyback obligations require e-commerce platforms to build collection networks that current courier partnerships cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Battery E-Commerce Market |
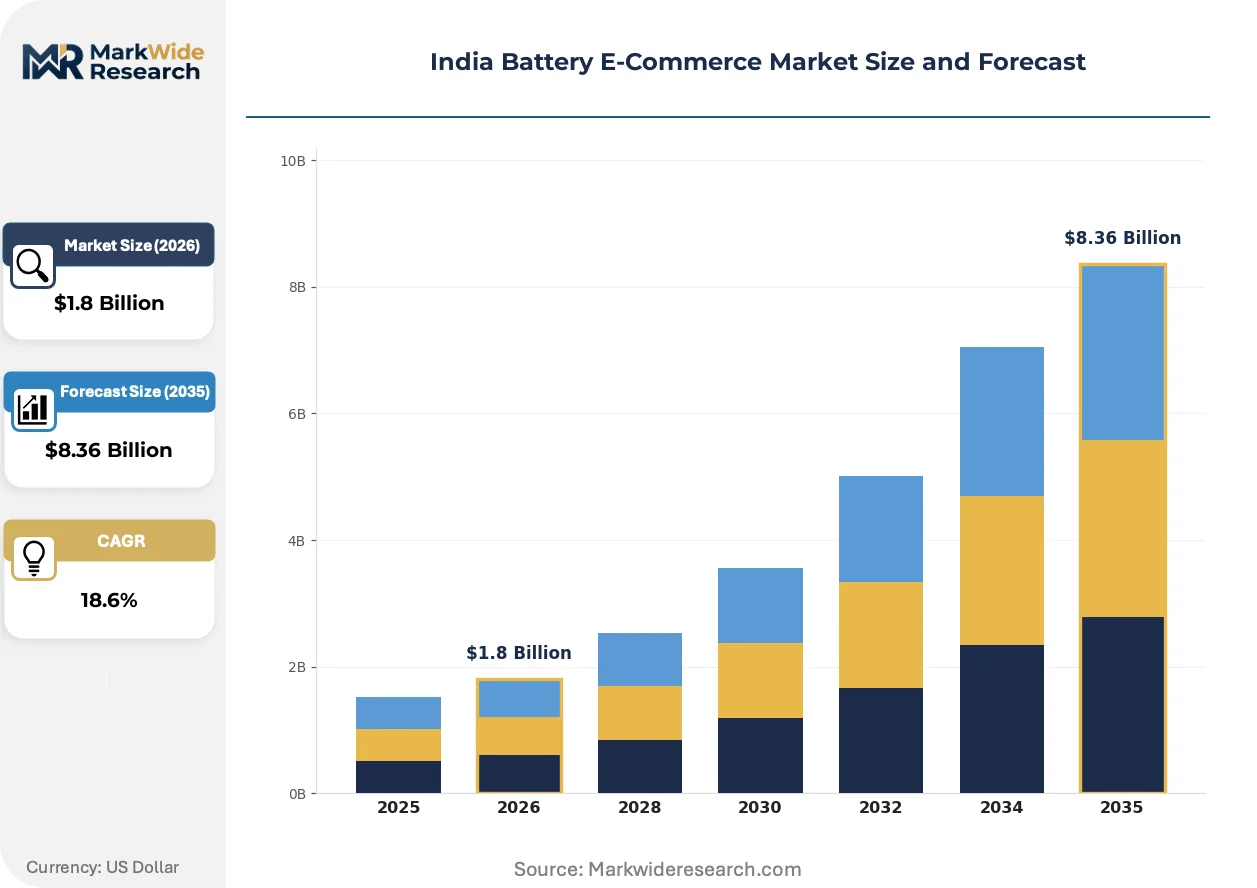
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Cadmium, Alkaline End User: Consumer Electronics, Automotive, Industrial, Renewable Energy Distribution Channel: Online Retailers, E-Commerce Platforms, Manufacturer Websites, Third-Party Sellers Battery Application: Backup Power, Electric Vehicles, Portable Devices, Energy Storage Systems |
| Companies Covered | Exide Industries Ltd, Luminous Power Technologies Pvt. Ltd, Panasonic Corporation, TATA AutoComp GY Batteries Pvt. Ltd, Okaya Power Pvt. Ltd, Amazon India, Flipkart, BatteryBhai, Amaron Batteries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Battery E-Commerce Market Trends and Innovations
Digital commerce architectures for electrochemical storage are pivoting from catalog aggregation toward integrated fulfillment systems that embed certification, temperature control, and lifecycle accountability into transaction infrastructure.
Solid-state electrolyte research is fragmenting the lithium-ion category into multiple chemistry variants with distinct thermal profiles and voltage characteristics. Two-wheeler OEMs are piloting silicon-anode cells for energy density gains that exceed conventional NMC configurations. This fragmentation is compressing platform standardization efforts and forcing SKU proliferation that strains warehouse slotting algorithms.
BIS mandates for cell-level testing under IS 16046 are reshaping supplier qualification workflows. The regulation disqualifies uncertified imports from platform algorithms, privileging domestic manufacturers with in-house compliance infrastructure. Maharashtra and Karnataka EV policies amplify this effect by layering state-level recycling obligations that only scaled producers can operationalize.
Fleet operators are consolidating procurement through direct manufacturer portals that disintermediate traditional distributor networks. Commercial two-wheeler and three-wheeler buyers in Tamil Nadu negotiate volume contracts through API-integrated ordering systems that bypass marketplace transaction fees. This channel migration is most visible in Bengaluru and Chennai, where metro logistics density supports just-in-time battery replacement cycles.
India Battery E-Commerce Market Segmentation
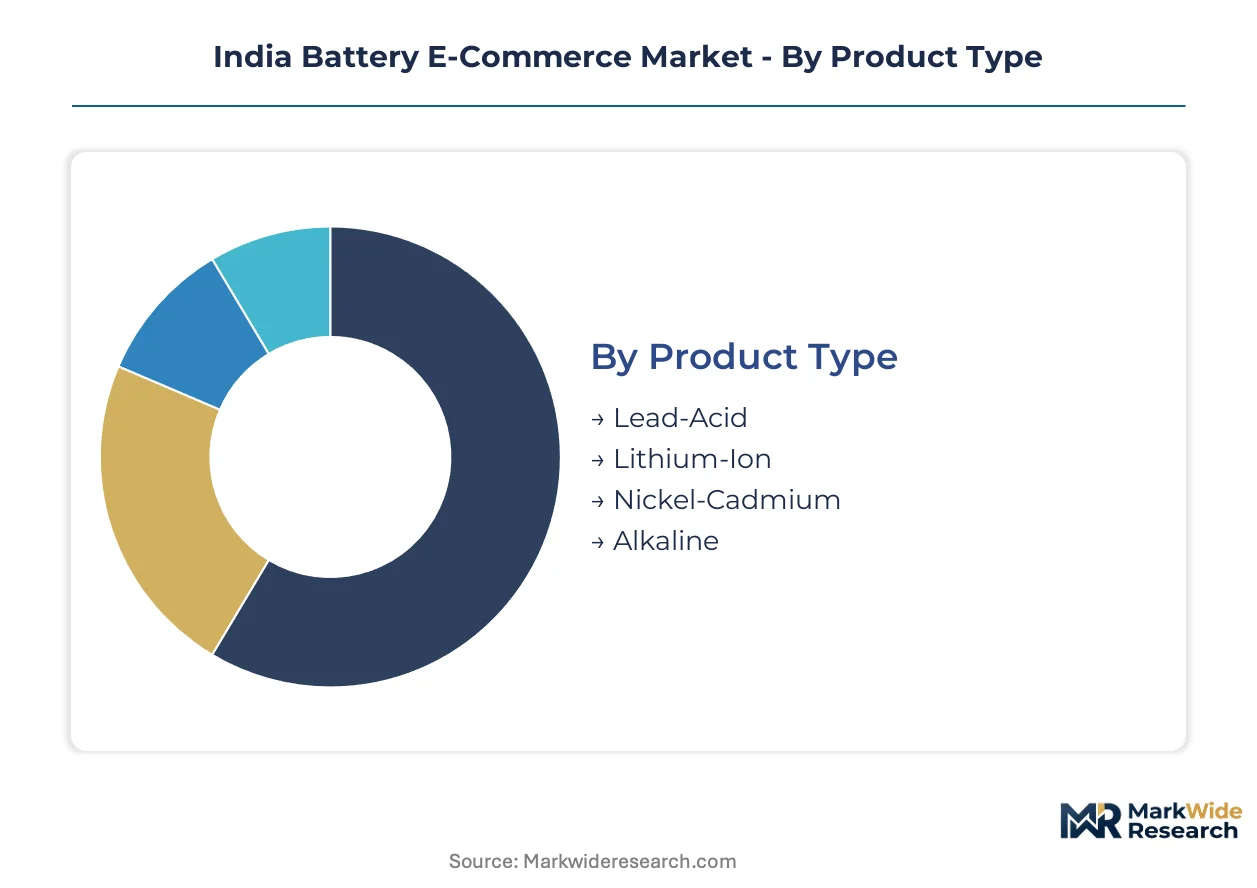
Segmentation in India's battery e-commerce market reveals how chemistry transitions and channel migration reshape procurement patterns. Each dimension exposes friction points between legacy infrastructure and emerging digital fulfillment models.
Product Type:
Substitution pressure from lithium-ion chemistry is collapsing lead-acid's historical dominance across mobility and backup applications, forcing platform algorithms to rebalance SKU exposure.
- Lead-Acid:Flooded and VRLA configurations with 12V nominal output serve inverter and automotive starter applications. Demand concentrates in tier-2 and tier-3 cities where replacement cycles and price sensitivity delay chemistry migration.
- Lithium-Ion:NMC and LFP cell packs with 3.7V mean cell voltage displace legacy stock in two-wheeler fleet operations. Maharashtra and Karnataka fleet operators consolidate procurement through digital channels to secure volume pricing and BIS-certified supply.
- Nickel-Cadmium:Rugged cylindrical cells tolerate temperature extremes in industrial backup configurations. Aviation and rail signaling applications in Tamil Nadu sustain niche demand despite environmental disposal constraints.
- Alkaline:Primary zinc-manganese dioxide cells power consumer electronics and medical devices. Portable device manufacturers in Bengaluru source bulk quantities through manufacturer-direct portals to bypass distributor markups.
Lead-Acid anchors the volume base while Lithium-Ion gains share at the steepest rate.
End User:
Cost tier stratification separates institutional purchasers negotiating API-integrated contracts from price-sensitive consumers browsing marketplace listings.
- Consumer Electronics:Smartphone, laptop, and wearable OEMs procure compact lithium polymer packs through dedicated procurement portals. Tamil Nadu electronics manufacturing clusters drive platform transaction density for standardized cell formats.
- Automotive:Two-wheeler and three-wheeler OEMs plus aftermarket replacement buyers dominate transaction value. Fleet operators in Maharashtra consolidate battery purchases through digital channels to streamline logistics and warranty tracking.
- Industrial:Forklift, telecom tower, and uninterrupted power supply operators source heavy-duty lead-acid and lithium configurations. Manufacturing corridors in Gujarat sustain bulk order flows with extended payment terms.
- Renewable Energy:Solar installers and microgrid developers procure containerized lithium battery banks. Rajasthan and Gujarat projects bypass traditional distributor networks to capture direct pricing on large-scale storage deployments.
Automotive commands transaction volume while Renewable Energy sustains the highest per-order margins through bulk storage configurations.
Distribution Channel:
Supply concentration among scaled domestic manufacturers with captive BIS testing infrastructure is squeezing third-party seller margins through algorithmic deprioritization.
- Online Retailers:Generalist e-commerce platforms aggregate catalog listings across chemistry types and applications. Cold-chain fulfillment capabilities for temperature-sensitive lithium cells differentiate operational sophistication.
- E-Commerce Platforms:Horizontal marketplaces with dedicated industrial procurement verticals serve institutional buyers. API integration enables fleet operators to embed battery procurement into existing fleet management workflows.
- Manufacturer Websites:Exide Industries and Luminous Power Technologies operate direct storefronts capturing institutional relationships. Subscription-based replacement contracts and warranty registration portals build recurring revenue streams.
- Third-Party Sellers:Independent distributors and import-dependent traders face margin compression from platform fee structures and BIS compliance costs. DGFT licensing friction for lithium cells constrains inventory depth and restocking velocity.
Manufacturer Websites capture the steepest expansion trajectory while Third-Party Sellers face structural displacement from compliance and logistics cost disadvantages.
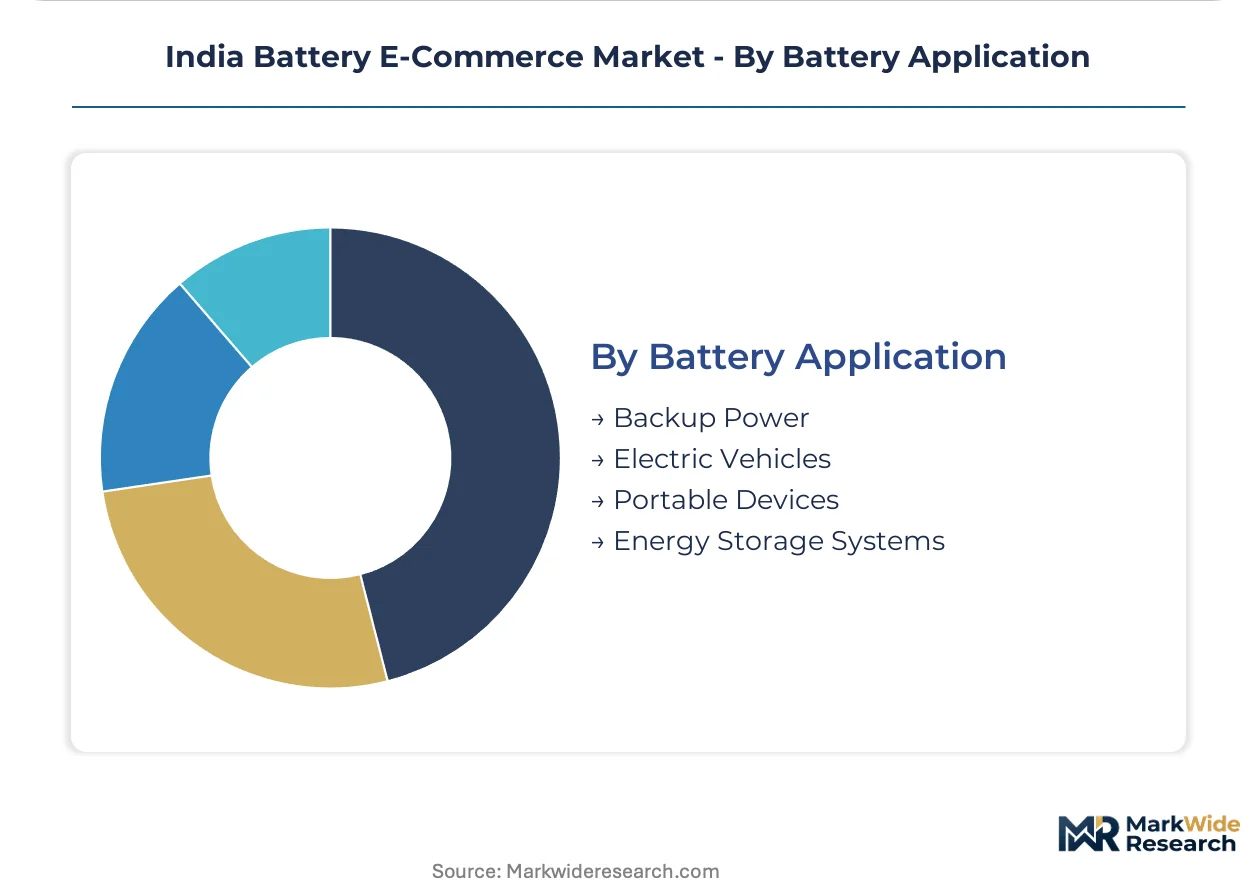
Battery Application:
Application maturity curves diverge sharply between saturated backup power replacement cycles and nascent electric vehicle fleet electrification driving platform innovation.
- Backup Power:Residential inverter and commercial UPS replacement sustains lead-acid demand in tier-2 and tier-3 cities. Maharashtra and Karnataka state policies mandating buyback obligations reshape product lifecycle accountability.
- Electric Vehicles:Two-wheeler and three-wheeler fleet operations consolidate procurement through digital channels. Bengaluru and Chennai metro logistics density enables same-day battery replacement guarantees.
- Portable Devices:Power banks, medical devices, and consumer electronics require compact lithium polymer configurations. Electronics manufacturing clusters in Tamil Nadu drive standardized cell format demand.
- Energy Storage Systems:Grid-connected and off-grid solar installations source containerized lithium battery banks. CEA safety guidelines for grid-connected installations impose technical qualification barriers that favor scaled suppliers.
Backup Power anchors current transaction volume while Electric Vehicles generates the steepest platform innovation investment in fulfillment infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The PLI scheme for advanced chemistry cells and state-level EV policies are redirecting supplier investments and procurement patterns across India's major industrial corridors.
Maharashtra
Two-wheeler fleet operators in Mumbai and Pune consolidate battery purchases through digital channels to secure volume pricing and streamlined logistics. The state's EV policy mandates buyback and recycling obligations that reshape product lifecycle accountability. Industrial clusters in Pune and Nashik host scaled manufacturers with captive BIS testing infrastructure.
Karnataka
Bengaluru's metro logistics density enables same-day delivery guarantees for temperature-sensitive lithium cell chemistries. State EV regulations prescribe extended producer responsibility frameworks that accelerate platform-based battery-as-a-service models. Electronics manufacturing corridors in Bengaluru and Mysuru drive standardized lithium polymer format demand.
Tamil Nadu
Three-wheeler commercial operators in Chennai negotiate API-integrated volume contracts through manufacturer-direct portals. The state's industrial policy incentivizes domestic cell assembly capacity that reduces import dependency for e-commerce fulfillment. Automotive and electronics manufacturing zones in Chennai and Coimbatore sustain bulk order flows.
Gujarat
Solar installers in Ahmedabad and Surat source containerized lithium battery banks through e-commerce to bypass distributor markups. State renewable energy policies support grid-connected storage deployments that favor scaled suppliers with CEA safety guideline compliance. Industrial corridors in Vadodara and Sanand host heavy-duty lead-acid and lithium configuration producers.
Rajasthan
Microgrid developers in Jaipur and Jodhpur procure large-scale storage through digital channels to capture direct pricing on containerized shipments. State solar park expansions create concentrated demand for grid-connected battery installations. Renewable energy project clusters in Bhadla and Phaseda sustain bulk procurement volumes with extended payment terms.
India Battery E-Commerce Market Competitive Landscape
Listed leaders compete with private specialists across certification infrastructure and cold-chain fulfillment capabilities. The supplier base compresses around scaled domestic manufacturers with captive BIS testing labs, squeezing import-dependent traders from platform algorithms. Three archetypes dominate: legacy battery manufacturers with in-house compliance infrastructure, horizontal e-commerce platforms with dedicated industrial procurement verticals, and pure-play digital natives specializing in last-mile logistics. Competitive moves concentrate on manufacturer-direct storefront expansion and metro cold-chain network densification.
Within the legacy manufacturer tier, Exide Industries Ltd and Luminous Power Technologies Pvt. Ltd exemplify scaled domestic producers with captive certification infrastructure that maintains platform compliance without third-party delays. Among horizontal platform operators, Amazon India occupies a position representing marketplace-based fulfillment with controlled last-mile cold-chain logistics for temperature-sensitive chemistries. These anchors illustrate how BIS mandates under IS 16046 privilege players with in-house testing capacity while DGFT licensing friction constrains import-dependent competitors.
| Leading Market Players |
|---|
| Exide Industries Ltd |
| Luminous Power Technologies Pvt. Ltd |
| Panasonic Corporation |
| TATA AutoComp GY Batteries Pvt. Ltd |
| Okaya Power Pvt. Ltd |
| Amazon India |
| Flipkart |
| BatteryBhai |
| Amaron Batteries |
| Others |
Pricing and Supply Chain Analysis
Ninety-day restocking cycles for lithium cells compress working capital buffers and tilt pricing power toward manufacturers with captive BIS testing infrastructure, while DGFT licensing friction inflates landed costs for import-dependent sellers. This dynamic concentrates procurement relationships around scaled domestic producers and forces platform algorithms to prioritize certified inventory over price-competitive alternatives.
Pricing Analysis
Certification level under IS 16046 creates the primary spread between qualified and unqualified supply, with BIS-compliant lithium-ion packs commanding premium positioning against uncertified imports. Three-tier pricing structure separates manufacturer-direct volume contracts, marketplace-listed branded inventory, and third-party seller offerings with limited warranty coverage. Cost compression in the third-party tier is intensifying because cold-chain fulfillment absorbs margins that sellers cannot recover against Exide Industries and Luminous Power Technologies captive production. Fleet operators in Maharashtra demonstrate lowest price sensitivity due to lifecycle cost optimization, while tier-3 inverter replacement buyers sustain highest elasticity.
Supply Chain Analysis
BIS laboratory bottlenecks in Mumbai and Bengaluru constrain certification throughput and delay supplier onboarding, creating qualification backlogs that reshape procurement calendars. Cell production draws from China, South Korea, and emerging domestic assembly capacity under the PLI scheme, with cathode active materials and electrolyte formulations resting on East Asian chemical processing. Single-source vulnerability concentrates in lithium carbonate and cobalt sulfate refining, where geographic concentration amplifies price volatility. Distribution runs through manufacturer-direct portals for institutional buyers and cold-chain-enabled platforms for temperature-sensitive chemistries, with third-party sellers facing algorithmic deprioritization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of in-house BIS testing infrastructure defines competitive viability, as laboratory capacity constraints disqualify uncertified suppliers from platform algorithms and compress the addressable vendor base to scaled domestic manufacturers.
For Market Incumbents: Compound certification advantages by expanding captive testing capacity in Maharashtra and Karnataka industrial corridors, capturing stranded demand from import-dependent competitors facing DGFT licensing delays. Deepen backward integration into cell assembly through PLI scheme incentives, securing supply certainty against raw material volatility. Lock fleet operators into subscription-based replacement contracts via API-integrated ordering systems that embed warranty tracking and state-mandated buyback compliance. For New Entrants and Emerging Players: BIS fast-track partnerships with accredited laboratories in Tamil Nadu and Gujarat offer qualification acceleration for lithium-ion pack assemblers targeting renewable energy storage white space. Solar installers in Rajasthan and microgrid developers present penetrable segments where distributor bypass appetite exceeds brand loyalty. Go-to-market positioning should emphasize containerized shipment logistics and extended payment terms that mirror project finance cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial divisions with dormant battery assembly lines and latent BIS infrastructure, offering qualified manufacturing capacity without greenfield certification timelines. Long-term viability hinges on chemistry transition exposure, with lithium-ion assembly capabilities preferred over lead-acid legacy positioning. Watch DGFT import licensing relaxation signals as inflection indicators for third-party seller margin recovery and platform assortment expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Logistics Partnership | Same-day delivery guarantees for lithium cells differentiate platform value in Bengaluru and Chennai. |
| Manufacturer-Direct Portal Launch | Bypassing marketplace fees allows Exide Industries to capture institutional fleet relationships. |
| BIS Certification Fast-Track Investment | In-house IS 16046 testing infrastructure eliminates third-party delays and sustains platform listing eligibility. |
| Renewable Energy Storage Vertical | Solar installers in Gujarat source containerized banks through digital channels to capture direct pricing. |
| Battery-as-a-Service Model | State-mandated buyback obligations in Maharashtra accelerate subscription-based replacement contract adoption. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with battery procurement managers at two-wheeler fleet operators, platform category heads at horizontal e-commerce marketplaces, and supply chain directors at domestic cell manufacturers; and secondary validation through BIS certification registries, DGFT import licensing disclosures, state EV policy documents from Maharashtra and Karnataka, and PLI scheme beneficiary announcements. Bottom-up triangulation cross-checked platform transaction volumes against manufacturer shipment data, while top-down modeling anchored total addressable market estimates to automotive and renewable energy deployment trajectories.
Across the projection horizon, the analytical framework modeled demand across chemistry type, end-use application, distribution channel, and regional logistics density. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation, incorporating PLI scheme capacity addition schedules, state EV policy implementation timelines, and cold-chain network expansion plans as battery-specific forecast inputs.
Underlying assumptions cover sustained PLI scheme disbursement continuity and state-level EV policy enforcement consistency, with deviation risk concentrated in DGFT licensing regime shifts and BIS laboratory capacity expansion delays. Practitioners should keep alternative scenarios live as regulatory implementation pace and raw material supply diversification efforts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Air Separation Unit Market
Others
Motor Grader Market
Others
Europe Military 4D Printing Market
Others
Caster Wheels Market
Others
Global Essential Oils and Plant Extracts for Livestock Market
Others
Dry-Cleaning and Laundry Services Market
Others
Finished Leather Market
Others
Hearables Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Vegetable Carbon Market
Others
Industrial Personal Computer Market
Others
Tote Bags Market
Others
Germany Smart Home Market
Others
TWS Micro-Battery Market
Others
High Voltage Measuring Equipment Market
Others
Ammeters Market